
 Global Ground and Precipitated Calcium Carbonate Market | 2026-2036
Global Ground and Precipitated Calcium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ground and Precipitated Calcium Carbonate Market Foresight
Talc and kaolin substitution by calcium carbonate in paper coating formulations is rebalancing product economics across filler markets. Imerys leverages integrated quarry-to-plant operations across Europe and North America to sustain cost leadership in ground calcium carbonate. Omya AG anchors its position through specialized slurry distribution networks serving paper mills. Minerals Technologies Inc. competes via precipitated calcium carbonate technology leadership in brightness and particle size control.
Ground and precipitated calcium carbonate encompasses calcium carbonate products derived from limestone grinding or carbonation of calcium hydroxide, with particle sizes ranging from sub-micron precipitated grades to coarse ground pebbles and functional specifications including brightness, oil absorption, and BET surface area. The material functions primarily as a functional filler, extender pigment, and rheology modifier across paper, plastics, paints, and construction applications. Paper applications dominate volume consumption due to coating and filling requirements, while plastics processing represents the fastest-growing segment as calcium carbonate masterbatch displaces virgin resin loadings. Coated calcium carbonate commands margin premiums in high-performance paint and adhesive formulations where surface treatment enables dispersion stability.
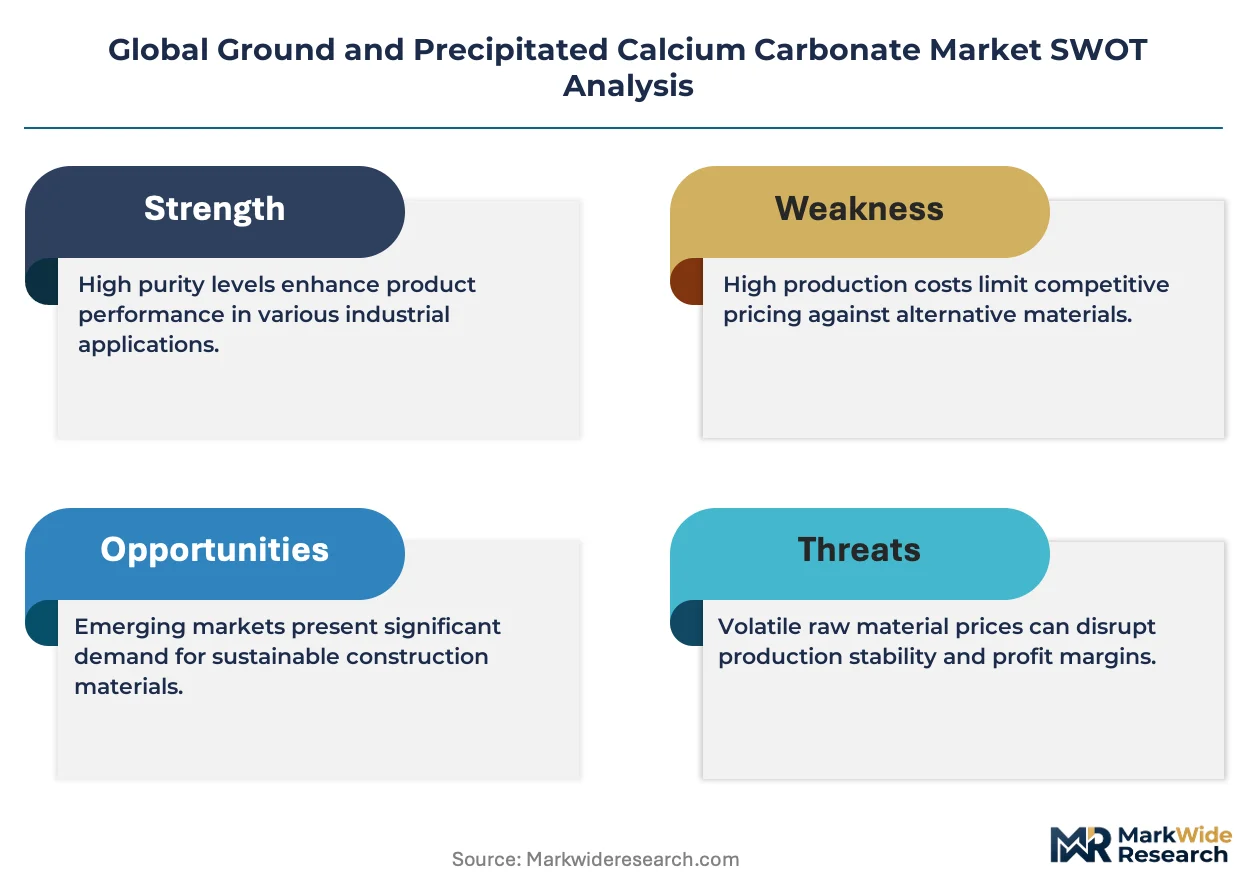
EPA mining waste regulations in the United States, REACH chemical registration requirements in Europe, and China's MEE emission standards for non-metallic mineral processing collectively elevate compliance costs and favor scaled producers with environmental control infrastructure. ISO 3262 and ASTM D1199 standards govern product specifications for brightness, particle distribution, and chemical purity, shaping qualification thresholds for supplier approval. Stakeholders must monitor tightening carbon border adjustments and regional mining permit restrictions that threaten raw material access for non-integrated processors.
Market Dynamics
Paper mill consolidation across Asia and Europe is compressing supplier margins while favoring slurry-delivery specialists with integrated logistics networks. This structural force concentrates procurement power among fewer buyers while rewarding producers with captive limestone reserves and carbonation technology.
Growth Catalysts
- EU Green Deal carbon border adjustments:Domestic European producers gain cost advantage over importers lacking verified emission profiles, accelerating capacity investments in France and Germany.
- Bioplastic compounding expansion:Calcium carbonate masterbatch loading in polylactic acid and starch-based resins reduces material costs while maintaining mechanical properties for packaging applications.
- China construction sector stabilization:Government infrastructure stimulus and PVC pipe demand recovery restore volume consumption for ground calcium carbonate in building materials.
Market Restraints
- Energy cost volatility:Natural gas and electricity price spikes in Germany and Italy directly impact precipitated calcium carbonate production economics where carbonation and drying are energy-intensive.
- Limestone reserve access concentration:High-calcium limestone deposits suitable for brightness-grade PCC concentrate in select regions of the United States, Vietnam, and Japan, creating raw material security risks for non-integrated processors.
- Titanium dioxide substitution ceiling:Opacity and weatherability limitations prevent calcium carbonate from displacing TiO2 in exterior architectural coatings regardless of cost differentials.
Strategic Opportunities
- India automotive plasticization:Underpenetrated calcium carbonate loading in polypropylene interior trim and bumper compounds offers white space as vehicle production scales under PLI scheme incentives.
- Food-grade PCC certification:EFSA and FDA food contact approvals for precipitated grades enable pharmaceutical excipient and chewing gum base applications commanding margin premiums.
- Carbon capture utilization integration:Waste CO2 from cement and power plants is integrating into carbonation circuits for synthetic PCC production, converting emission liabilities into feedstock assets.
Industry Challenges
- Particle size distribution control talent scarcity:Qualified process engineers capable of maintaining sub-micron PCC specifications with narrow polydispersity indices remain concentrated at established technology leaders.
- ISO 3262 and ASTM D1199 qualification timelines:Paper mill approval processes for new supplier qualification extend 18-24 months, freezing out emerging producers regardless of technical capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ground and Precipitated Calcium Carbonate Market |
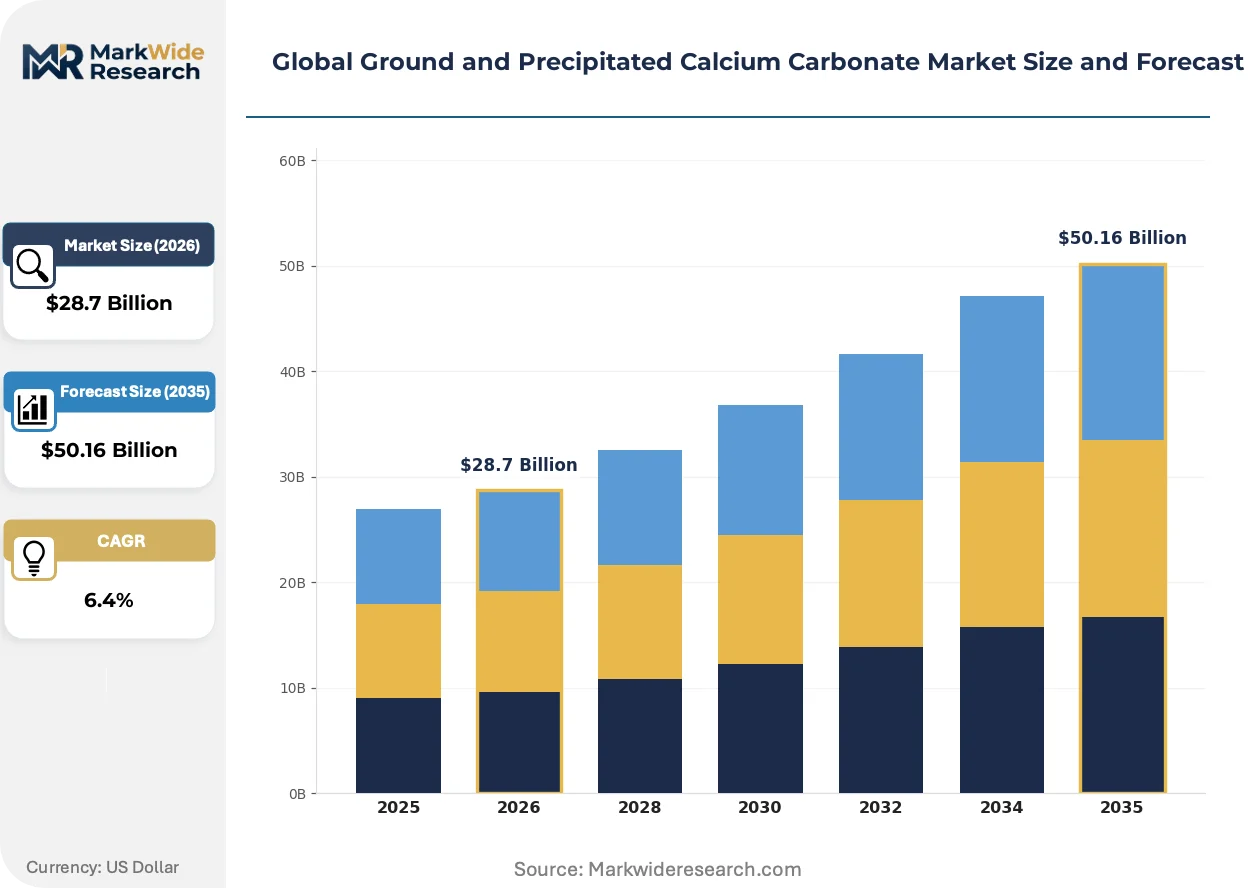
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Calcium Carbonate, Precipitated Calcium Carbonate, Coated Calcium Carbonate, Modified Calcium Carbonate Form: Powder, Granule, Slurry, Pebble Application: Paper, Plastics, Paints & Coatings, Adhesives & Sealants, Agriculture End User Industry: Paper Manufacturing, Plastics Processing, Paint Production, Chemical Processing, Construction Materials |
| Companies Covered | Imerys, Omya AG, Minerals Technologies Inc., Huber Engineered Materials, Carmeuse, Mississippi Lime Company, Gulshan Polyols Ltd., Schaefer Kalk GmbH & Co. KG, Nordkalk Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ground and Precipitated Calcium Carbonate Market Shifts & Advancements
Surface modification chemistry and digital process control are converging to produce functionalized grades with application-specific performance profiles. These advances are compressing the traditional gap between commodity fillers and specialty additives.
Nano-precipitated calcium carbonate with controlled aragonite morphology is integrating into tire tread compounds to reduce rolling resistance while maintaining wear properties. Bridgestone and Michelin compounders are adopting these grades at pilot scale. The technology is integrating silica-carbonate hybrid reinforcement systems that lower compound density and improve fuel efficiency metrics for electric vehicle range optimization.
REACH Annex XVII restrictions on microplastics are tightening labeling and disposal requirements for plastic fillers across EU member states. Compounders must now document calcium carbonate loading percentages and biodegradability assessments in technical files. The construction segment faces accelerated compliance costs as ECHA evaluates powder classification for respiratory hazard labeling.
Direct mill-supply contracts are displacing distributor intermediaries in European paper coating markets. Omya and Imerys field technical service teams co-located at major mill sites, replacing traditional stock-and-sell arrangements. This concentration is most visible in Finland and Sweden where Stora Enso and UPM have consolidated procurement through single-source slurry agreements with dedicated pipeline infrastructure.
Global Ground and Precipitated Calcium Carbonate Market Segmentation
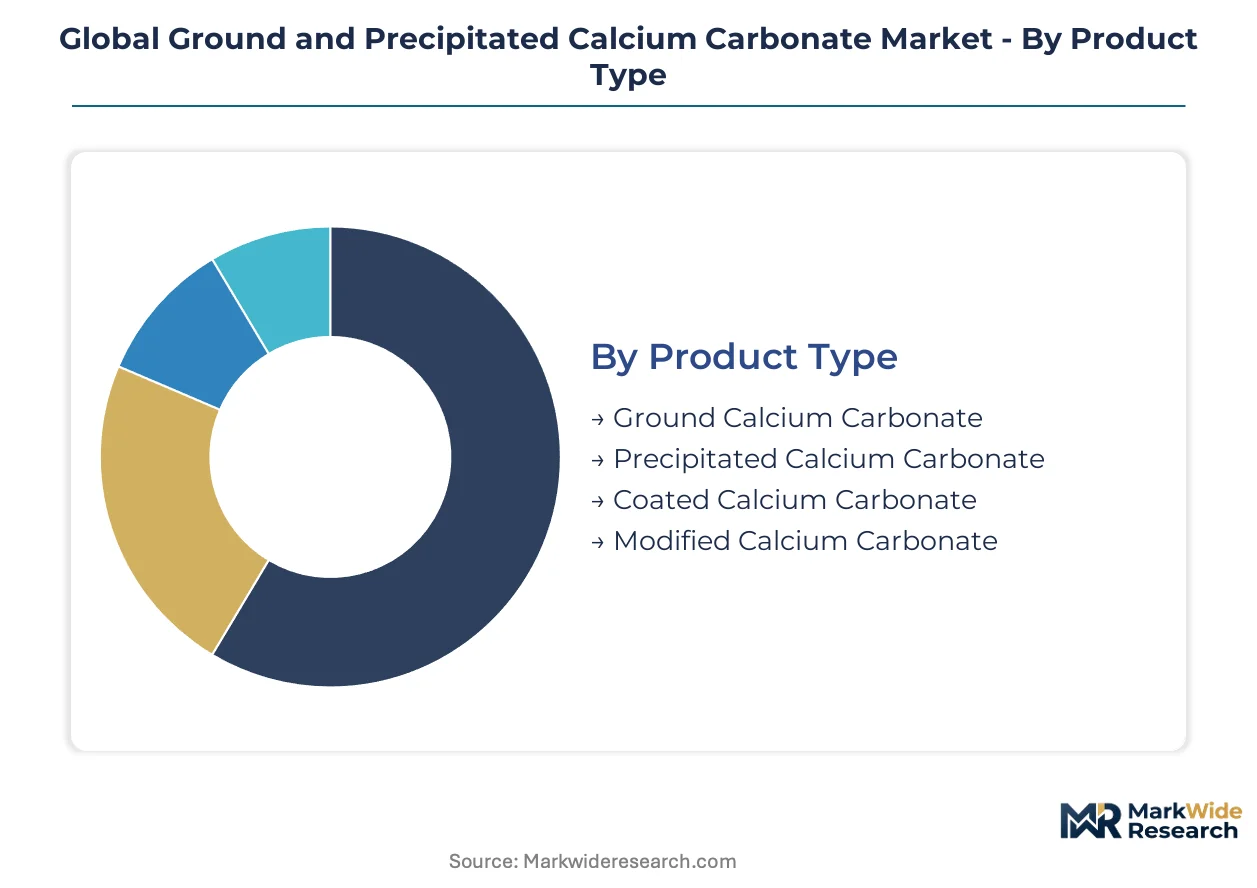
Calcium carbonate segmentation reflects divergent processing intensities and customer integration requirements. Ground products flow through commodity channels while precipitated and surface-modified grades demand technical sales support and application-specific qualification protocols.
Product Type:
Integration depth varies sharply across product types, with standalone ground grades contrasting against embedded precipitated variants requiring carbonation technology partnerships.
- Ground Calcium Carbonate:Mechanical grinding of limestone yields particles from 1 to 50 microns with brightness levels dictated by deposit purity. Demand concentrates in China's construction materials sector where PVC pipe and concrete admixture manufacturers prioritize cost over sub-micron specification control.
- Precipitated Calcium Carbonate:Carbonation of calcium hydroxide produces controlled aragonite or calcite morphologies with sub-micron particle sizes and narrow polydispersity. Paper coating mills in Finland and Japan specify these grades for gloss and printability performance where brightness thresholds exceed 95% ISO.
- Coated Calcium Carbonate:Surface treatment with stearic acid or silane coupling agents enables dispersion stability in hydrophobic polymer matrices. Masterbatch compounders leverage these grades for polypropylene loading without agglomeration.
- Modified Calcium Carbonate:Specialized surface chemistry and particle engineering target tire tread and bioplastic applications where silica-carbonate hybrid systems reduce rolling resistance.
Volume placements concentrate in Ground Calcium Carbonate; the faster expansion belongs to Precipitated Calcium Carbonate.
Form:
Physical form selection tracks customer processing infrastructure and logistics economics, with slurry systems rewarding producers with pipeline investments while powder serves dispersed regional markets.
- Powder:Dried and bagged material serves plastics compounding and construction applications where water content disrupts processing. Regional distributors stock powder grades for mid-sized paint manufacturers lacking slurry handling equipment.
- Granule:Compact, free-flowing particles reduce dust exposure and improve metering accuracy in automated feeding systems. Agricultural lime and animal feed supplement producers specify granule form for spreading equipment compatibility.
- Slurry:Aqueous suspensions at 70-78% solids eliminate drying energy costs and enable pipeline delivery to paper mills. Omya's dedicated slurry networks in Sweden and Germany demonstrate how form integration locks in long-term supply contracts.
- Pebble:Coarse, unground limestone serves glass manufacturing and steel flux applications where purity requirements exceed 97% calcium carbonate content with minimal magnesium or silica contamination.
Slurry deployments dominate paper sector procurement; powder retains widest geographic reach across fragmented end-use bases.
Application:
Application segmentation maps directly to customer scale and specification tolerance, with paper and plastics commanding dedicated technical service resources while agriculture tolerates broader quality bands.
- Paper:Coating and filling applications consume brightness-grade precipitated calcium carbonate for glossy magazine stocks and uncoated wood-free papers. Stora Enso and UPM mills in Finland specify slurry delivery with ISO 3262 brightness certification.
- Plastics:Calcium carbonate masterbatch loading in polypropylene and polyethylene reduces resin costs while maintaining tensile properties. India's automotive plasticization under PLI scheme incentives is expanding polypropylene interior trim applications.
- Paints & Coatings:Extender pigment applications displace titanium dioxide in interior architectural formulations where opacity requirements permit. Exterior coatings remain titanium dioxide-dependent due to weatherability limitations.
- Adhesives & Sealants:Rheology modification and cost reduction in construction adhesives leverage fine-ground grades with controlled particle size distribution.
- Agriculture:Soil pH amendment and animal feed calcium supplementation utilize lower-brightness ground limestone with minimal processing.
Paper maintains volume leadership; plastics processing is climbing the fastest as bioplastic compounding expands.
End User Industry:
End user concentration determines contract structure, with paper manufacturing consolidating procurement power while construction materials remain fragmented across regional suppliers.
- Paper Manufacturing:Integrated mills with on-site slurry storage and pipeline infrastructure demand 18-24 month qualification timelines under ISO 3262 and ASTM D1199 protocols. Direct mill-supply contracts displace distributor intermediaries in European markets.
- Plastics Processing:Masterbatch compounders and injection molders specify coated grades for dispersion stability in polyolefin matrices. China's packaging sector recovery is restoring volume consumption for filler-grade calcium carbonate.
- Paint Production:Waterborne and solvent-borne coating manufacturers balance cost reduction against gloss and scrub resistance performance. REACH Annex XVII microplastics restrictions are tightening documentation requirements for filler loading percentages.
- Chemical Processing:Precipitated calcium carbonate serves as a chemical intermediate and pH buffer in pharmaceutical and food-grade applications where EFSA and FDA approvals command margin premiums.
- Construction Materials:Concrete admixture, PVC pipe, and sealant manufacturers utilize ground calcium carbonate as a functional filler and cost extender. China's infrastructure stimulus is stabilizing demand after sector volatility.
Procurement volumes cluster in Paper Manufacturing; Construction Materials is gaining share fastest on China stimulus effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate precipitated calcium carbonate capacity near paper mill clusters. Vietnam's northern industrial corridors attract grinding operations serving export markets. Germany's Rhine-Ruhr chemical corridor anchors European carbonation technology.
China
Construction materials and plastics processing drive ground calcium carbonate consumption across Jiangsu and Shandong provinces. MEE emission standards for non-metallic mineral processing tighten particulate controls at limestone grinding facilities. The Pearl River Delta hosts masterbatch compounders expanding polypropylene loading for automotive interior applications.
United States
Paper coating mills in Wisconsin and Minnesota specify brightness-grade precipitated calcium carbonate for glossy publication stocks. EPA mining waste regulations elevate compliance costs for limestone quarry operations in the Midwest. High-calcium deposits in the Ohio River Valley concentrate PCC feedstock supply for regional carbonation plants.
Germany
Paper manufacturers in Bavaria and Baden-Württemberg procure slurry-delivery contracts with integrated pipeline infrastructure. EU Green Deal carbon border adjustments favor domestic producers with verified low-emission profiles over import competition. The Frankfurt-Rhine-Main chemical corridor hosts specialty carbonate surface modification facilities serving adhesive formulations.
India
Automotive plasticization under PLI scheme incentives expands calcium carbonate masterbatch loading in Gujarat and Maharashtra polypropylene compounds. BIS certification requirements for industrial minerals create qualification barriers for ungraded suppliers. The Delhi-Mumbai Industrial Corridor attracts grinding capacity serving construction materials demand from infrastructure stimulus projects.
Japan
Precipitated calcium carbonate for pharmaceutical excipients and food-grade applications commands premium pricing in Osaka and Tokyo processing hubs. METI circular economy guidelines encourage carbon capture integration into carbonation circuits. The Chubu region around Nagoya concentrates tire tread compound development incorporating nano-precipitated grades for rolling resistance reduction.
Global Ground and Precipitated Calcium Carbonate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated quarry-to-plant operators commanding paper sector procurement while toll processors serve regional construction markets. The vendor base concentrates around three strategic archetypes: captive limestone reserve holders with carbonation technology, slurry distribution specialists with mill-adjacent infrastructure, and surface modification compounders serving polymer masterbatch. M&A activity targets limestone reserve access in Vietnam and Turkey, while capacity investments cluster in France and Germany to exploit carbon border adjustment advantages.
Among European integrated producers, Imerys S.A. and Omya AG exemplify the quarry-to-slurry archetype with mill-proximate pipeline networks. Minerals Technologies Inc. occupies the technology-specialist position emphasizing precipitated grade brightness control. Schaefer Kalk GmbH & Co. KG represents mid-scale German fabricators with regional carbonation focus. These anchors illustrate how geographic integration depth and product specification intensity define competitive positioning across filler market tiers.
| Leading Market Players |
|---|
| Imerys |
| Omya AG |
| Minerals Technologies Inc. |
| Huber Engineered Materials |
| Carmeuse |
| Mississippi Lime Company |
| Gulshan Polyols Ltd. |
| Schaefer Kalk GmbH & Co. KG |
| Nordkalk Corporation |
| Others |
Supply & Pricing Matrix
Slurry-delivery infrastructure investments by European paper sector specialists simultaneously compress logistics costs and lock in procurement relationships. Carbon capture utilization integration at synthetic PCC plants converts emission liabilities into feedstock assets, reshaping cost economics for precipitated grades while favoring producers with cement and power plant partnerships.
Pricing Analysis
Volume placements in ground calcium carbonate generate thin margins while precipitated and surface-modified grades capture premium returns. Three-tier pricing structure across brightness-certified, technical-grade, and commodity ground tiers reflects ISO 3262 qualification intensity and particle size control precision. Pricing pressure stems from paper mill consolidation across Finland and Sweden concentrating buyer power through single-source slurry contracts. Construction materials processors in China's Jiangsu province exhibit highest price sensitivity, while pharmaceutical excipient buyers in Japan accept substantial premiums for EFSA and FDA food-grade PCC certification.
Supply Chain Analysis
EU Green Deal carbon border adjustments and China's MEE emission standards are reshaping sourcing patterns toward domestic producers with verified low-emission profiles. High-calcium limestone deposits concentrate in the United States Ohio River Valley, Vietnam's northern industrial corridors, and Japan's Chubu region, creating geographic supply concentration for PCC feedstock. Raw material security hinges on captive quarry access, carbonation technology licensing, and pipeline delivery infrastructure. Single-source vulnerability runs through slurry-distribution networks where Omya and Imerys have locked in mill-adjacent pipeline systems. Distribution runs through direct mill-supply contracts displacing distributor intermediaries in European paper coating markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcium carbonate sector is transitioning from commodity grinding toward functionalized precipitated grades with application-specific performance profiles. Nano-precipitated aragonite morphology control for tire tread compounds exemplifies how particle engineering is displacing legacy ground limestone in high-value segments.
For Market Incumbents: Cement cost leadership through captive limestone reserve expansion in Vietnam and Turkey, where M&A activity targets high-calcium deposit access. Deepen carbonation technology partnerships with cement and power plant operators to secure waste CO2 feedstock for synthetic PCC production. Defend against titanium dioxide substitution ceilings in exterior coatings by investing in silica-carbonate hybrid reinforcement systems for electric vehicle tire applications.
For New Entrants and Emerging Players: Enter via food-grade PCC certification pathways in India and Southeast Asia, where EFSA and FDA approvals remain underpenetrated for pharmaceutical excipient and chewing gum base applications. Target India's automotive plasticization wave under PLI scheme incentives, where calcium carbonate masterbatch loading in polypropylene interior trim offers white space. Pursue toll processing partnerships with regional construction materials distributors lacking carbonation technology.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale European carbonation specialists with ISO 3262 qualification timelines already completed and mill-proximate pipeline infrastructure. Long-term viability favors producers integrating carbon capture utilization into carbonation circuits, converting regulatory compliance costs into feedstock cost advantages. Watch for EU Green Deal carbon border adjustment enforcement intensity as the inflection signal determining import competitiveness versus domestic European capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Reserves | Captive quarry access in Vietnam and Turkey secures high-calcium feedstock for brightness-grade PCC production. |
| Carbon Capture Utilization Integration | Waste CO2 from cement plants converts emission liabilities into synthetic PCC feedstock assets under EU Green Deal compliance. |
| Food-Grade PCC Certification Investment | EFSA and FDA approvals enable pharmaceutical excipient applications commanding substantial margin premiums in Japan. |
| Slurry Pipeline Infrastructure Expansion | Mill-adjacent delivery systems lock in long-term supply contracts with Stora Enso and UPM in Finland and Sweden. |
| Silica-Carbonate Hybrid R&D Partnership | Bridgestone and Michelin tire compounders pilot nano-precipitated grades for electric vehicle rolling resistance reduction. |
Research Methodology
Independent corroboration across plant managers at integrated quarry-to-slurry operators, procurement leads at Nordic paper mills, distribution channel partners serving construction materials processors, and technical R&D directors specializing in surface modification chemistry underwrites the qualitative findings. Secondary validation draws from SEC 10-K filings of listed specialty minerals producers, Cefic sector reports on European chemical processing, customs and trade data on limestone and calcium carbonate flows, and EPA mining waste regulatory filings. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable-period anchoring to historical production and consumption patterns across the analysis window structures the forecast framework. Segmentation dimensions span product type tiers, end-use industry concentration, physical form requirements, and regional production hub integration depth. CAGRs derive from modeled supply-demand balances incorporating paper sector slurry contract volumes, plastics masterbatch loading intensity, and construction materials stimulus effects. Industry-specific inputs include ISO 3262 qualification timeline durations and REACH Annex XVII microplastics compliance cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under energy cost volatility in German and Italian carbonation plants, limestone reserve access restrictions in high-calcium deposit regions, and carbon border adjustment enforcement intensity divergences across EU member states. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Sodium Formate Market
Bulk Chemicals
2-Ethyl Hexanol Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
Phosphate Rock Market
Bulk Chemicals
North America Copper Sulphate Market
Bulk Chemicals
Green Petroleum Coke and Calcined Petroleum Coke Market
Bulk Chemicals
Coal Tar Pitch Market
Bulk Chemicals
North America Calcium Chloride Market
Bulk Chemicals
Global Naphthalene Derivatives Market
Bulk Chemicals
Commodity Plastics Market
Bulk Chemicals
Global Sodium Chlorate Market
Bulk Chemicals
Europe Methyl Acrylate Market
Bulk Chemicals
Ethylene and Propylene Market