
 Global Desalting and Buffer Exchange Market | 2026-2036
Global Desalting and Buffer Exchange Market Size, Share, and Industry Trends Forecast 2026-2036
Global Desalting and Buffer Exchange Market Foresight
Consumables and service contracts for membrane cartridges is rebalancing revenue models away from pure instrument sales. Thermo Fisher Scientific leverages its global distribution network to sustain recurring revenue from filtration consumables. Danaher Corporation anchors its position through Pall Corporation's integrated bioprocessing portfolios. Merck KGaA competes by extending its MilliporeSigma brand across chromatography and ultrafiltration workflows.
Desalting and buffer exchange encompasses separation processes that remove small-molecule salts and exchange aqueous buffers using molecular weight cutoffs typically ranging from 1 kDa to 1000 kDa in ultrafiltration membranes, with tangential flow configurations minimizing membrane fouling during high-concentration protein processing. The technique serves primarily to stabilize biologics between upstream expression and downstream purification stages. Ultrafiltration units dominate installed capacity due to their scalability from laboratory to production bioreactors, while diafiltration technology captures expanding share in continuous bioprocessing lines. Dialysis devices retain steady demand in academic settings where batch simplicity outweighs speed requirements.
The US FDA and the European Medicines Agency enforce process validation standards that mandate documented buffer exchange consistency for commercial biologics approval, directly shaping equipment qualification protocols and software documentation requirements. China's National Medical Products Administration aligns its biomanufacturing guidelines with international ICH Q5A through Q5D standards, opening market access for foreign suppliers meeting dual certification. Japan's Ministry of Health, Labour and Welfare through the Pharmaceuticals and Medical Devices Agency maintains distinct JIS standards for single-use filtration assemblies, creating regional specification layers that vendors must navigate. Stakeholders should monitor evolving regulatory convergence between FDA process analytical technology mandates and EMA's good manufacturing practice Annex 1 revisions for sterile filtration, as harmonization timelines will determine capital allocation priorities across R&D and compliance functions.
Market Dynamics
Continuous bioprocessing adoption is compressing batch cycle times and forcing membrane manufacturers to engineer higher-flux, lower-fouling ultrafiltration cassettes that sustain performance across extended operation windows without integrity failure.
Growth Catalysts
- FDA Process Analytical Technology Mandates:Real-time release testing requirements accelerate integrated buffer exchange platform deployment across commercial monoclonal antibody facilities in the United States.
- Single-Use Tangential Flow Systems:Biopharmaceutical contract manufacturers in Germany and Switzerland eliminate stainless-steel cleaning validation burdens through disposable flow paths.
- Cell and Gene Therapy Expansion:Viral vector production in the United Kingdom and Netherlands generates demand for gentle, high-recovery desalting protocols that preserve vector infectivity.
Market Restraints
- Membrane Polymer Cost Volatility:Polyethersulfone and regenerated cellulose feedstock prices fluctuate with petrochemical and forestry commodity cycles, squeezing consumables margin structures.
- European Supply Concentration:Specialized flat-sheet membrane production clusters in southern Germany create geographic single-point vulnerability for just-in-time bioprocessing supply chains.
- Protein Aggregation Risk:High-shear ultrafiltration configurations damage shear-sensitive fusion proteins, limiting application scope in emerging biologic modalities.
Strategic Opportunities
- India Biologics Manufacturing:CDSCO alignment with ICH Q5A-Q5D standards opens qualification pathways for foreign buffer exchange system suppliers serving emerging biosimilar production hubs.
- Continuous Capture-Chromatography Integration:Periodic counter-current chromatography systems paired with in-line diafiltration enable end-to-end continuous downstream processing with reduced tankage.
- Cloud-Based Process Analytics:Equipment vendors embedding AI-driven fouling prediction algorithms transform hardware sales into subscription-based performance contracts.
Industry Challenges
- Membrane Integrity Testing Expertise:Diffusion-based integrity test interpretation requires specialized training that outpaces workforce development in expanding biopharma clusters.
- Legacy Stainless-Steel Infrastructure:Brownfield facilities face structural constraints retrofitting skid-mounted single-use manifolds into existing cleanroom layouts without airflow requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Desalting and Buffer Exchange Market |
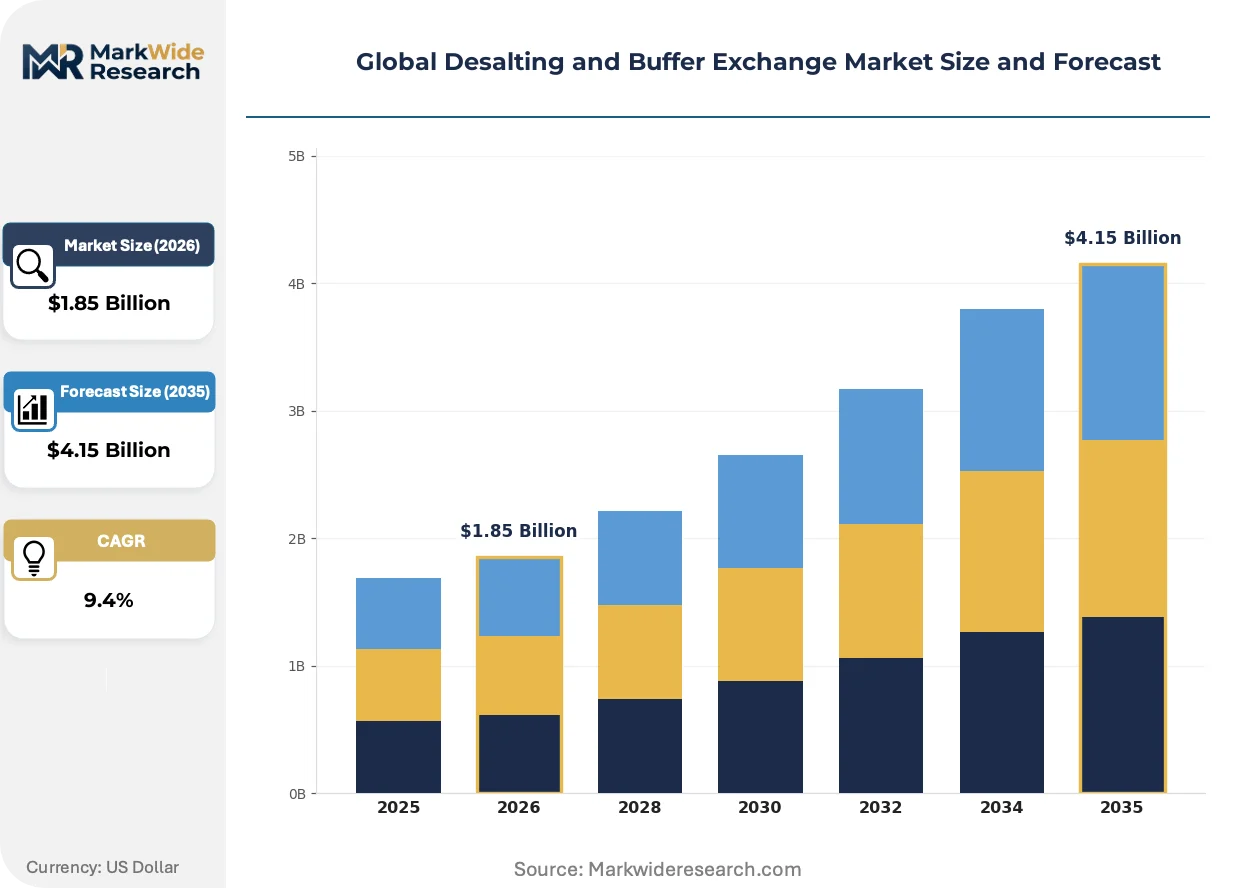
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dialysis Devices, Chromatography Columns, Ultrafiltration Units, Tangential Flow Filtration Systems Technology: Electrodialysis, Size Exclusion Chromatography, Ultrafiltration, Diafiltration Application: Protein Purification, Vaccine Production, Enzyme Isolation, Pharmaceutical Formulation End User: Biopharmaceutical Firms, Contract Research Organizations, Academic Laboratories, Specialty Drug Manufacturers |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Danaher Corporation, Sartorius AG, Agilent Technologies, Bio-Rad Laboratories, Cytiva, Pall Corporation, Repligen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Desalting and Buffer Exchange Market Shifts & Advancements
Membrane chemistry advances and regulatory data integrity requirements are converging to redefine equipment qualification protocols, while service contract structures displace capital purchase models across mid-scale biologics manufacturing.
Hydrophilic surface modification of polyethersulfone membranes is absorbing protein-binding sites that historically caused irreversible fouling during high-concentration immunoglobulin processing. Contract development and manufacturing organizations in Massachusetts and North Carolina are adopting these cassettes for 24-hour continuous campaigns. The technology is absorbing market share from regenerated cellulose alternatives by extending batch longevity and reducing buffer consumption per gram of purified protein.
EMA's Annex 1 revision for sterile manufacturing mandates enhanced contamination control strategy documentation for filtration steps, including buffer exchange operations. European biologics manufacturers must now implement automated electronic batch records with audit trails spanning membrane installation through integrity test completion. Small and mid-sized facilities in Denmark and Sweden are outsourcing validation protocol development to specialized compliance consultants rather than building in-house expertise.
Service-unbundling from hardware procurement is restructuring vendor-customer relationships as biopharmaceutical firms separate equipment capital budgets from operational expenditure accounts. Third-party filtration service providers in Singapore and South Korea now manage membrane inventory, installation, and post-use disposal for multi-product facilities. This model concentrates most visibly in emerging biosimilar manufacturing hubs where operational flexibility outweighs asset ownership preferences.
Global Desalting and Buffer Exchange Market Segmentation
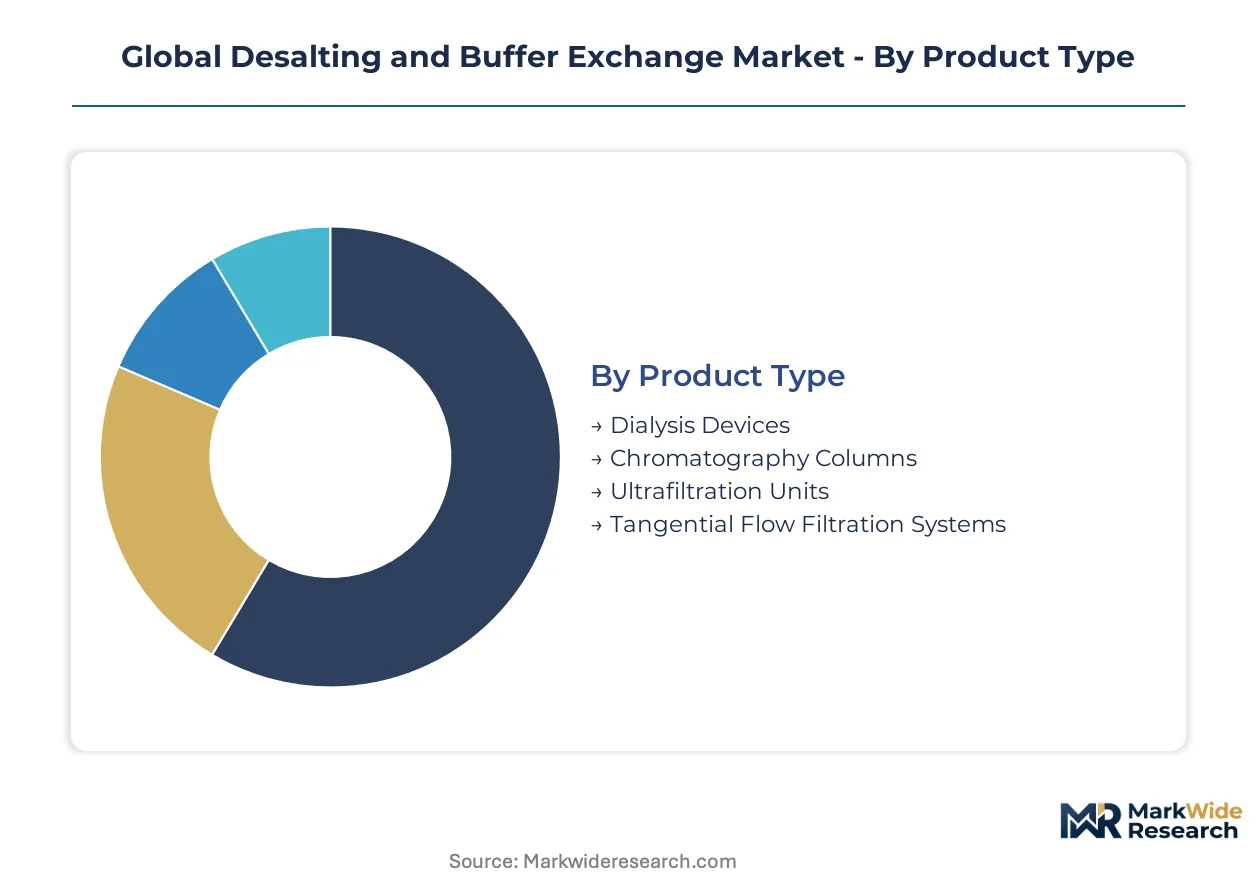
Segmentation in desalting and buffer exchange equipment tracks how purification workflows split across scale, automation, and regulatory intensity. Manufacturers configure product portfolios around whether customers operate under GMP-validated commercial production or exploratory research protocols.
Product Type:
Equipment selection hinges on throughput requirements and the balance between batch flexibility and continuous processing economics.
- Tangential Flow Filtration Systems:Recirculating flow paths sweep retained proteins across membrane surfaces, minimizing concentration polarization during high-viscosity monoclonal antibody concentration. Biopharmaceutical firms in Massachusetts and North Carolina deploy these for 24-hour perfusion campaigns where membrane longevity determines cost per batch.
- Ultrafiltration Units:Pressure-driven separation through molecular weight cutoff membranes ranging from 1 kDa to 1000 kDa dominates installed capacity across scales from laboratory to production bioreactors. Demand concentrates in Germany where Cytiva and Sartorius anchor specialized supply chains for European biologics manufacturing.
- Chromatography Columns:Resin-based separation enables high-resolution desalting with simultaneous impurity removal for final formulation polishing.
- Dialysis Devices:Passive diffusion across semipermeable membranes retains steady demand in academic settings where batch simplicity outweighs speed requirements.
Tangential flow filtration leads on scale; chromatography columns lead on momentum in continuous capture integration.
Technology:
Process architecture determines whether salt removal operates through size-based exclusion, charge differential, or pressure-driven concentration.
- Ultrafiltration:Cross-flow or dead-end configurations using polyethersulfone or regenerated cellulose membranes achieve 10-50x concentration factors for protein solutions. CDSCO alignment with ICH Q5A-Q5D standards in India opens qualification pathways for foreign system suppliers serving emerging biosimilar production hubs.
- Diafiltration:Continuous buffer exchange maintains constant volume while replacing solvent conditions, essential for formulation into final drug substance buffers. EMA's Annex 1 revision for sterile manufacturing mandates enhanced contamination control strategy documentation for these filtration steps.
- Size Exclusion Chromatography:Gel filtration separates molecules by hydrodynamic radius without binding interactions, preserving native protein structure.
- Electrodialysis:Ion-selective membranes driven by electric potential enable salt removal without pressure-induced protein denaturation.
Ultrafiltration commands the largest installed base; diafiltration is gaining share fastest in continuous bioprocessing lines.
Application:
Downstream processing stages impose distinct purity, recovery, and speed requirements that shape equipment specification.
- Protein Purification:Monoclonal antibody and recombinant protein production requires gentle buffer exchange to prevent aggregation during concentration. FDA process analytical technology mandates for real-time release testing accelerate integrated platform deployment across commercial facilities in the United States.
- Vaccine Production:Antigen purification and adjuvant formulation demand consistent ionic strength control for immunogenicity stability. Viral vector production in the United Kingdom and Netherlands generates specialized demand for gentle, high-recovery desalting protocols that preserve vector infectivity.
- Enzyme Isolation:Industrial biocatalyst recovery prioritizes throughput over resolution for bulk enzyme manufacturing.
- Pharmaceutical Formulation:Final drug substance preparation into administration-ready buffers requires validated consistency documentation.
Protein purification dominates revenue concentration; vaccine production shows the steepest expansion trajectory from cell and gene therapy growth.
End User:
Customer type determines whether procurement prioritizes capital efficiency, operational flexibility, or regulatory pedigree.
- Biopharmaceutical Firms:Integrated manufacturing organizations operate validated stainless-steel or single-use trains with dedicated process development groups. Contract manufacturers in Germany and Switzerland eliminate cleaning validation burdens through disposable tangential flow flow paths.
- Contract Research Organizations:Multi-client service providers demand rapid reconfiguration between projects with minimal cross-contamination risk. Third-party filtration service providers in Singapore and South Korea now manage membrane inventory, installation, and disposal for these multi-product facilities.
- Academic Laboratories:Research institutions prioritize capital cost minimization and operational simplicity over throughput optimization.
- Specialty Drug Manufacturers:Niche pharmaceutical producers focus on orphan disease and personalized medicine batches with unique formulation requirements.
Biopharmaceutical firms anchor volume demand; contract research organizations are expanding most quickly through service-unbundling trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturers are relocating buffer exchange capacity to jurisdictions with streamlined regulatory pathways and lower qualification costs. The FDA's process analytical technology mandates in the United States create compliance premiums that contract manufacturers in Germany and Switzerland increasingly undercut through single-use disposable workflows.
United States
Massachusetts and North Carolina biologics clusters drive tangential flow filtration deployment for 24-hour perfusion campaigns. FDA process analytical technology guidelines for real-time release testing accelerate integrated platform adoption across commercial monoclonal antibody facilities. Greater Boston contract manufacturers are retrofitting stainless-steel infrastructure with skid-mounted single-use manifolds to eliminate cleaning validation burdens.
Germany
Cytiva and Sartorius anchor specialized supply chains for European biologics manufacturing from southern German membrane production clusters. EMA Annex 1 revisions for sterile manufacturing mandate enhanced contamination control documentation for filtration steps. Bavarian contract development organizations are outsourcing validation protocol development to specialized compliance consultants rather than building in-house expertise.
Switzerland
Basel-region biopharmaceutical headquarters generate concentrated demand for high-recovery desalting protocols in continuous bioprocessing lines. Swissmedic maintains alignment with EMA good manufacturing practice standards while offering streamlined qualification pathways for novel modalities. Zurich-area service providers now manage membrane inventory, installation, and post-use disposal for multi-product facilities under operational expenditure contracts.
India
CDSCO alignment with ICH Q5A through Q5D standards opens qualification pathways for foreign buffer exchange system suppliers serving emerging biosimilar production hubs. Karnataka and Telangana biologics parks are attracting contract manufacturing investment from European and American filtration vendors. Hyderabad-based facilities are adopting cloud-based process analytics with AI-driven fouling prediction algorithms to bypass capital-intensive hardware procurement.
United Kingdom
Viral vector production in Oxford and Cambridge generates specialized demand for gentle desalting protocols that preserve vector infectivity in cell and gene therapy applications. The Medicines and Healthcare products Regulatory Agency enforces process validation standards consistent with EMA guidelines for commercial biologics approval. London-area contract research organizations are expanding most quickly through service-unbundling trends that separate equipment capital budgets from operational expenditure accounts.
Global Desalting and Buffer Exchange Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated life science conglomerates commanding premium positions in validated GMP environments while regional fabricators capture price-sensitive academic and emerging market demand. The vendor base organizes around three strategic archetypes: diversified analytical instrumentation houses with filtration portfolios, pure-play bioprocessing specialists focused on single-use technologies, and diversified conglomerates with life science divisions. M&A activity concentrates on membrane chemistry capabilities and software-enabled process analytics, while geographic expansion targets Indian and South Korean biosimilar manufacturing clusters.
Among diversified analytical instrumentation houses, Thermo Fisher Scientific leverages global distribution networks to sustain recurring revenue from filtration consumables. Merck KGaA competes by extending its MilliporeSigma brand across chromatography and ultrafiltration workflows. Danaher Corporation anchors its position through Pall Corporation's integrated bioprocessing portfolios. These three entities exemplify the tier of players combining hardware scale with consumables attachment to transform capital sales into operational expenditure relationships.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Danaher Corporation |
| Sartorius AG |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Cytiva |
| Pall Corporation |
| Repligen Corporation |
| Others |
Supply & Pricing Matrix
GMP-validated versus research-grade equipment bifurcation creates distinct commercial ecosystems where FDA-compliant membrane cassettes command substantial premiums over academic-use alternatives, and this tier divergence manifests in both procurement budgets and supplier qualification burdens. Polyethersulfone membrane manufacturers in southern Germany concentrate premium-tier production while commodity-grade assemblies source from broader Asian fabrication networks, embedding certification tier directly into geographic supply chain configuration.
Pricing Analysis
Distributor margins for filtration consumables typically absorb 15-25 percent of end-user price across European and North American channels, compressing to 8-12 percent for direct OEM relationships with large biopharmaceutical manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated single-use cassettes from stainless-steel reusable systems and basic laboratory dialysis units. Price differentiation hinges on FDA 21 CFR Part 11 compliance documentation and ISO 13485 certification status. Cost compression in standard-tier ultrafiltration skids is intensifying because contract manufacturers in India and South Korea negotiate volume-based procurement frameworks. Academic laboratories exhibit highest price sensitivity, while commercial biologics manufacturers prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Membrane cartridge refurbishment and end-of-life disposal flows are increasingly managed by third-party service providers in Singapore and South Korea under operational expenditure contracts, reversing traditional capital-asset ownership models. Polyethersulfone resin supply concentrates in Germany, Japan, and the United States, while regenerated cellulose membrane feedstock draws from Austrian and Canadian forestry processing clusters. Raw material dependencies span petrochemical derivatives, specialty polymer additives, and precision-milled hardware housings. Single-source vulnerability in southern German flat-sheet membrane production creates geographic concentration risk for just-in-time bioprocessing supply chains. Distribution runs through authorized distributor networks for validated GMP equipment and direct e-commerce channels for research-grade consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Desalting and Buffer Exchange Market functions as a stable compounder anchored by biopharmaceutical manufacturing expansion that mandates recurring consumables procurement regardless of macroeconomic cycles.
For Market Incumbents: To counter emerging single-use system specialists from Asia-Pacific, deepen backward integration into proprietary membrane polymer formulations and expand captive service capabilities in India and South Korea. Secure exclusive supply agreements with top-20 global biopharmaceutical contract manufacturers to lock in recurring revenue streams and raise competitive switching costs. For New Entrants and Emerging Players: Begin with cloud-based process analytics subscriptions targeting mid-scale biosimilar manufacturers in India seeking to bypass capital-intensive hardware procurement. White-space concentration sits in AI-driven fouling prediction algorithms and membrane inventory management services for multi-product facilities. Pursue regulatory qualification partnerships with established European vendors to accelerate CDSCO and FDA pathway access. For Investors and Strategic Acquirers: Consolidation pressure builds where membrane chemistry IP and software-enabled process analytics capabilities remain fragmented across sub-scale specialists. The market supports long-term compounding through consumables attachment and service contract expansion rather than cyclical equipment replacement. Target acquisition archetypes include regional filtration service providers with established biopharmaceutical relationships and membrane surface modification technology holders. Monitor EMA-FDA regulatory harmonization timelines for sterile filtration as early inflection signal for capital allocation toward integrated platform vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Chemistry Patent Acquisition | Proprietary polyethersulfone surface modifications extend batch longevity for Cytiva and Sartorius customers. |
| Continuous Bioprocessing Partnership | Integration with periodic counter-current chromatography systems enables end-to-end downstream automation. |
| Regulatory Qualification Outsourcing | Specialized compliance consultants in Denmark and Sweden capture EMA Annex 1 validation demand. |
| Cloud-Based Analytics Subscription | AI-driven fouling prediction transforms Thermo Fisher hardware sales into recurring performance contracts. |
| India Biosimilar Hub Expansion | CDSCO ICH alignment opens qualification pathways for foreign buffer exchange system suppliers. |
Research Methodology
Direct dialogue with bioprocess engineers, regulatory affairs directors at filtration equipment vendors, contract manufacturing organization procurement leads, and academic laboratory managers grounded qualitative insights, validated against FDA 510(k) filings, EMA good manufacturing practice guidance documents, CDSCO regulatory circulars, and SEC 10-K disclosures from publicly traded life science conglomerates. Bottom-up and top-down triangulation cross-checked membrane shipment volumes against bioreactor capacity expansion data.
Bottom-up modeling segmented addressable demand across tangential flow filtration systems, ultrafiltration units, chromatography columns, and dialysis devices, further disaggregated by technology type, application stage, and end-user archetype across the projection horizon. Top-down validation anchored total market size against biopharmaceutical capital expenditure surveys and consumables procurement patterns. CAGRs derived from regression analysis of historical membrane cartridge pricing trajectories correlated with biologics approval volumes and contract manufacturing capacity utilization.
Several conditions sit outside the modeled scope, including potential breakthroughs in non-membrane desalting technologies, abrupt shifts in FDA process analytical technology enforcement intensity, and geopolitical disruptions to German membrane polymer supply chains. Forecasts reflect documented assumptions regarding regulatory convergence timelines and biopharmaceutical outsourcing trends. Practitioners should monitor EMA Annex 1 implementation progress and CDSCO inspection capacity expansion for early signals of qualification pathway acceleration or delay.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Silicates Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
Chlorine Trifluoride Market
Industrial Chemicals
Lithium Hexafluorophosphate Market
Industrial Chemicals
Dipropylene Glycol (DPG) Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Honing Oil Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
North America Molecular Sieve Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market