
 Global Ethiprole Market | 2026-2036
Global Ethiprole Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ethiprole Market Intelligence
Expanded production capacity in China is rewriting the supply dynamics for ethiprole. Bayer CropScience AG leverages its extensive R&D to develop specialized formulations for key international markets. Jiangsu Tuoqiu Agrochemical Ltd specializes in technical grade manufacturing, supplying active ingredients to global formulators. Syngenta competes through its broad portfolio and established distribution channels in major agricultural economies.
Ethiprole is a non-systemic phenylpyrazole insecticide that functions by disrupting the central nervous system of target insects. Its chemical structure allows it to effectively block GABA-gated chloride channels, leading to rapid pest mortality. Formulated Products, such as Emulsifiable Concentrates, hold a significant share due to their ease of application for end users like agricultural farms. Within applications, its use on cereal crops and cotton is driven by its efficacy against specific, economically damaging pests.
Regulatory frameworks from bodies like the US Environmental Protection Agency (EPA), the European Chemicals Agency (ECHA), and India's Central Insecticides Board govern market access. These agencies define Maximum Residue Levels (MRLs) on food crops and approve specific uses, directly impacting which formulations can be sold. Manufacturers must continuously adapt product development and registration strategies to navigate evolving environmental and health standards across key agricultural regions.
Market Dynamics
Regulatory divergence between major agricultural blocs is the central force shaping the ethiprole market. Differing standards for Maximum Residue Levels and environmental safety, particularly between the EU, the US, and China, create a fragmented compliance landscape for manufacturers.
Growth Catalysts
- Intensified Crop Production:Heightened demand for cereal crops to meet food security objectives in nations like China and India sustains the need for effective pest control agents against economically damaging insects.
- Specialty Formulations:The development of advanced formulations, such as Emulsifiable Concentrates (ECs) with improved bioavailability and reduced environmental runoff, meets stricter regulatory criteria and expands use cases.
- New Market Registrations:Securing regulatory approval for ethiprole on new crops or in previously untapped agricultural economies, like for rice in Vietnam, opens significant volume opportunities for formulators.
Market Restraints
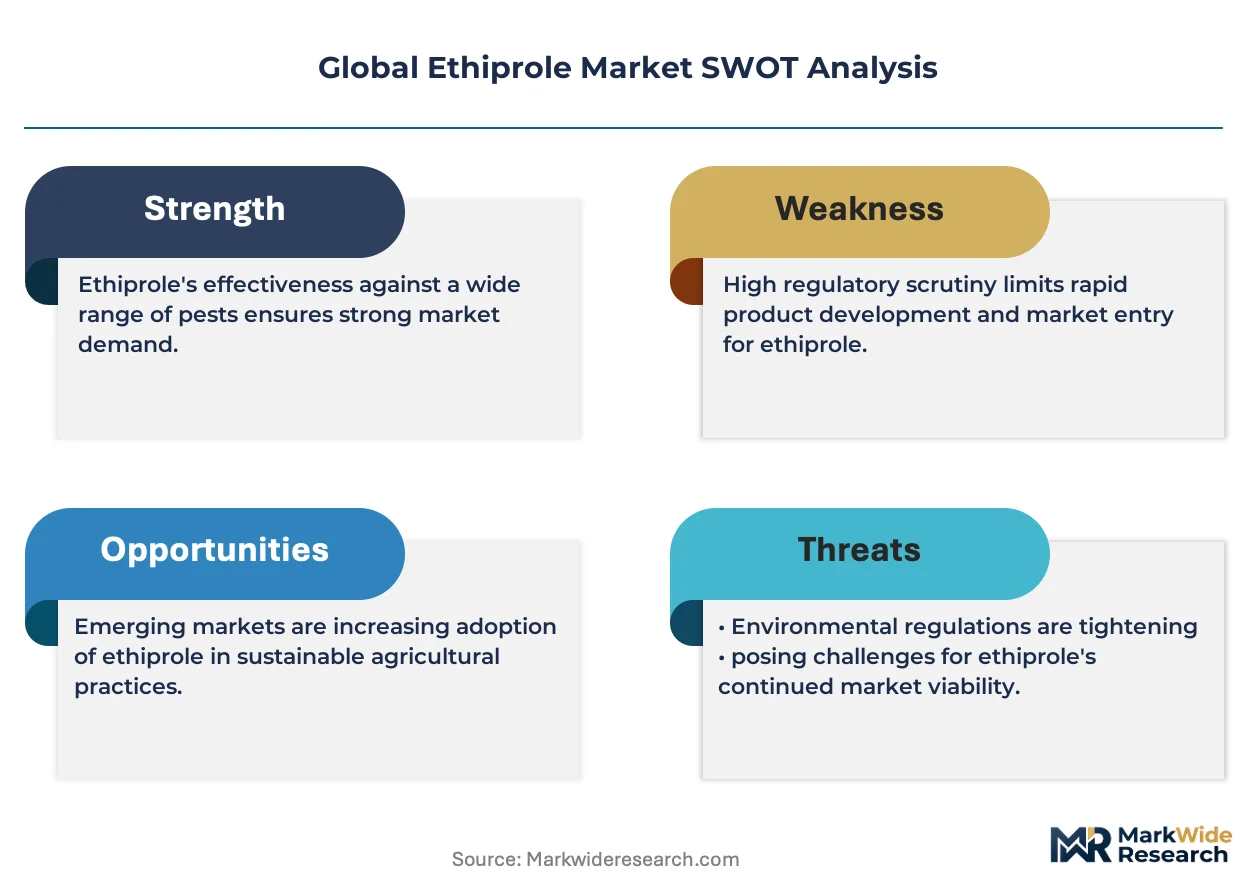
- Strict Regulatory Scrutiny:Stringent environmental and health standards, exemplified by the European Chemicals Agency (ECHA) assessments, can delay or block market access and increase compliance costs significantly.
- Insect Resistance:The potential for target pests to develop resistance to phenylpyrazole insecticides necessitates careful stewardship and rotation programs, limiting continuous or widespread application.
- Substitution by IPM:The adoption of Integrated Pest Management (IPM) programs, which prioritize biological and cultural controls, can reduce the overall chemical insecticide volume used by large agricultural enterprises.
Strategic Opportunities
- Combination Products:Developing synergistic formulations that combine ethiprole with other active ingredients can help manage insect resistance, broaden the spectrum of controlled pests, and create new intellectual property.
- Non-Agricultural Applications:There is an opportunity to expand formulations for the professional pest management sector, targeting applications like structural termite control or public health vector control.
- Emerging Economies:Targeting agricultural sectors in fast-growing economies in Africa and Southeast Asia, where pest pressure on staple crops is high and modern insecticide adoption is increasing, offers new growth frontiers.
Industry Challenges
- Data Generation Costs:The high expense and long timelines required to conduct the toxicological and ecotoxicological studies mandated by bodies like the US EPA create a significant barrier to entry and new product registration.
- Generic Competition:The expiration of primary patents allows for the entry of technical grade manufacturers, particularly from India and China, which intensifies price competition for active ingredients.
- End-User Education:Ensuring the proper and safe application of ethiprole to minimize off-target effects and manage resistance requires extensive and ongoing training for farmers and applicators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ethiprole Market |
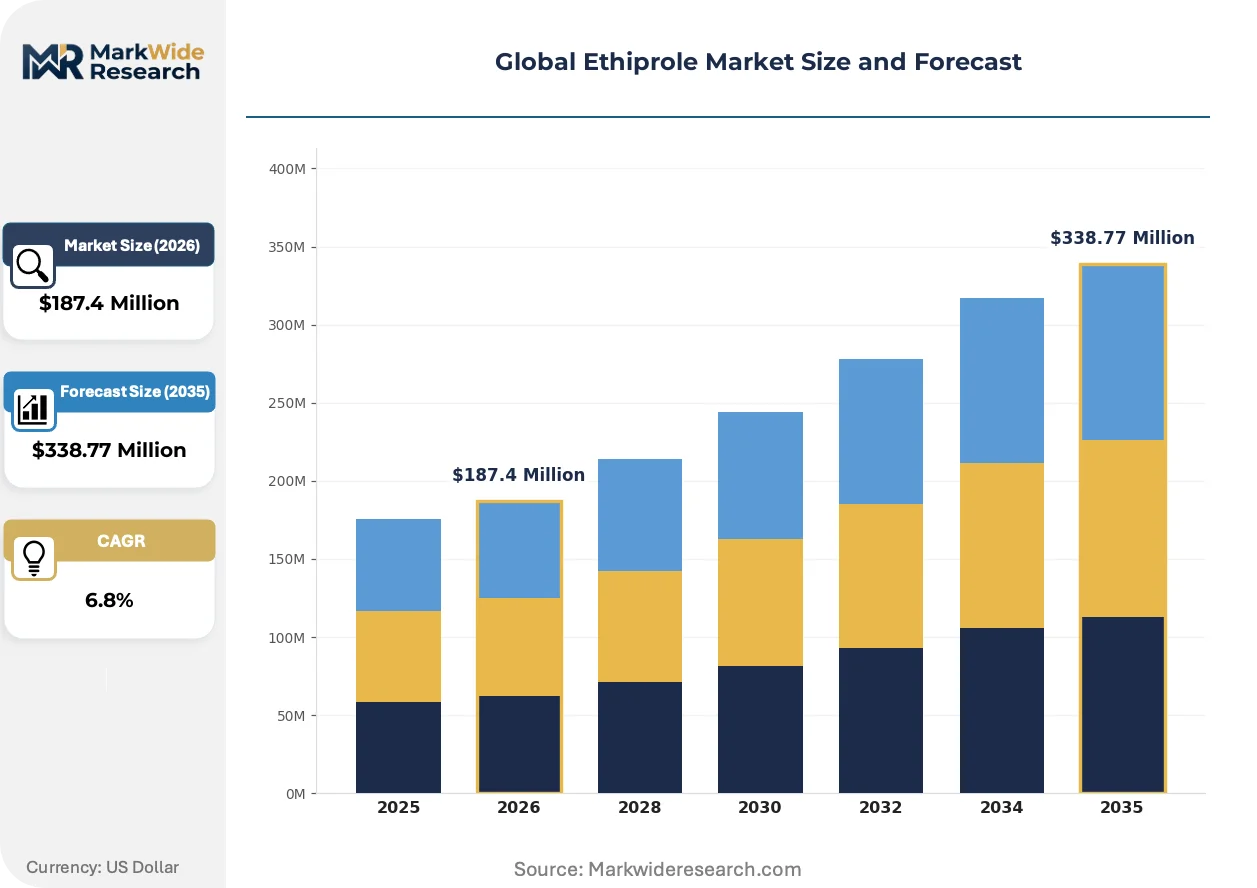
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Technical Concentrate, Formulated Products, Emulsifiable Concentrate, Water Dispersible Granule Application: Cereal Crops, Cotton, Vegetables, Oilseeds, Legumes End User: Agricultural Farms, Crop Consultants, Agrochemical Distributors, Contract Sprayers Packaging Type: Plastic Bottles, Metal Drums, Pouches, Fiber Drums, Sachets |
| Companies Covered | Bayer CropScience AG, Rayfull Holding Co., Ltd., Jiangsu Tuoqiu Agrochemical Ltd, Syngenta, BASF, Sumitomo Chemical, UPL Limited, Nufarm, Adama Agricultural Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ethiprole Market Strategic Shifts & Innovations
Innovation in the ethiprole market is being driven by the dual pressures of precision agriculture and sustainability mandates. This dynamic is reshaping product development toward more targeted, efficient, and environmentally conscious pest control solutions that align with evolving regulatory frameworks.
Precision application technology, including sensor-equipped drones and GPS-guided sprayers, enables the targeted delivery of ethiprole formulations. Large agricultural enterprises in Brazil and the United States are adopting these systems to optimize chemical use and reduce input costs. This technology is digitizing pest management by generating field-level data maps that inform application timing and volume, thereby minimizing environmental impact.
The European Union's Green Deal and its associated Farm to Fork strategy are compelling a shift in formulation chemistry. These policies, which aim to reduce overall chemical pesticide usage, push manufacturers to invest in lower-dose, higher-efficacy products or combinations that demonstrate a superior environmental profile under ECHA review. The cereal and specialty fruit sectors are most affected, actively seeking compliant solutions.
A behavioral shift is occurring where large agricultural cooperatives are prioritizing suppliers who offer integrated pest management support over simple product transactions. This change disrupts traditional sales channels, favoring manufacturers capable of providing technical assistance, resistance monitoring, and stewardship training. This trend is most visible in mature agricultural economies like Australia and Canada, where farm consolidation drives demand for holistic solutions.
Global Ethiprole Market Segmentation
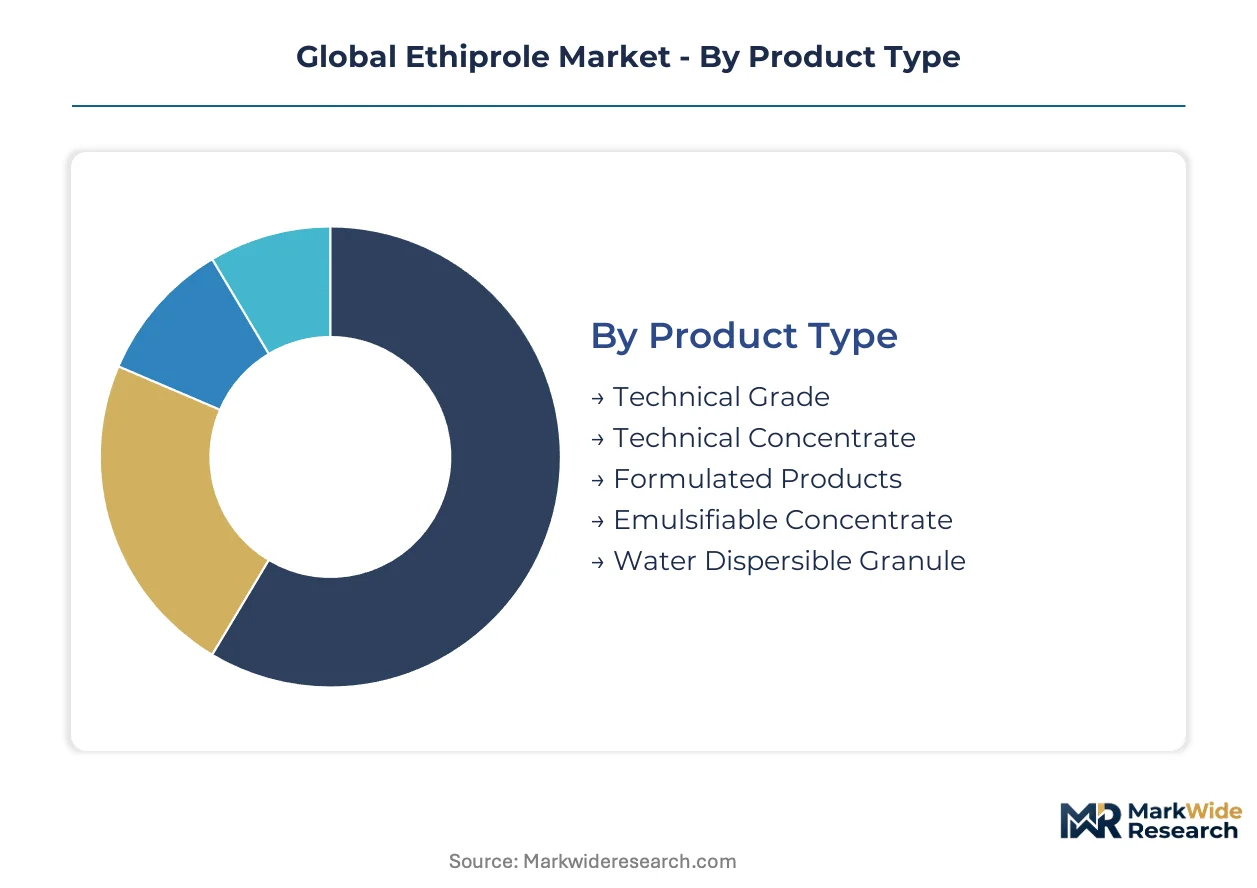
Understanding the ethiprole market segmentation provides clarity on demand drivers and supply dynamics across its diverse applications. This granular view helps manufacturers tailor product development, marketing strategies, and distribution channels to specific end-user needs and regulatory environments.
Product Type:
The use-case spectrum for ethiprole product types ranges from basic active ingredients to ready-to-apply solutions, each serving distinct stages of the supply chain.
- Technical Grade:This segment represents the pure active ingredient, typically 95% or higher purity, used by formulators to create end-use products. Jiangsu Tuoqiu Agrochemical Ltd specializes in this manufacturing, supplying global formulators with the base chemical.
- Technical Concentrate:A higher concentration of the active ingredient, often mixed with basic solvents, intended for further dilution or formulation by specialized companies. This product type offers flexibility for regional formulators adapting to local market requirements.
- Formulated Products:These are finished ethiprole products ready for application, containing active ingredients, solvents, and adjuvants for optimal performance. These products hold a significant share due to their ease of application for end users like agricultural farms.
- Emulsifiable Concentrate:A specific type of formulated product where ethiprole is dissolved in a solvent and emulsifiers, forming a stable emulsion when mixed with water. This formulation offers improved bioavailability and reduced environmental runoff, meeting stricter regulatory criteria in regions like the European Union.
- Water Dispersible Granule:A dry, granular formulation that disperses in water to form a suspension, offering advantages in handling, storage, and reduced dust exposure for applicators.
The dominant share belongs to Formulated Products, while Emulsifiable Concentrate is closing the gap fastest.
Application:
Demand for ethiprole is primarily shaped by its efficacy against key pests in specific agricultural applications, influencing crop protection strategies globally.
- Cereal Crops:Ethiprole is highly effective against economically damaging pests in staple cereal crops such as rice, wheat, and maize. Heightened demand for cereal crops to meet food security objectives in nations like China and India sustains the need for effective pest control agents.
- Cotton:This insecticide provides crucial protection for cotton crops against specific sucking and chewing pests, safeguarding yields in major cotton-producing regions. Its efficacy on cotton is a significant driver for its adoption in countries like India and the United States.
- Vegetables:Ethiprole is used in vegetable cultivation to control a range of insect pests, ensuring crop health and marketability for growers.
- Oilseeds:Application on oilseed crops helps manage pest infestations that can severely impact yield and oil quality, supporting agricultural productivity.
- Legumes:Ethiprole protects legume crops from various insect threats, contributing to food production and soil health in many agricultural systems.
These applications collectively define the primary demand channels for ethiprole, with specific crop needs influencing formulation development.
End User:
The diverse end-user landscape dictates varied purchasing patterns and technical support requirements for ethiprole products.
- Agricultural Farms:These direct consumers apply ethiprole to protect their crops, driven by the need for effective pest control to maximize yields and profitability. Large agricultural enterprises in Brazil and the United States are adopting precision application technology to optimize chemical use.
- Crop Consultants:These advisors recommend ethiprole formulations to farmers based on pest pressure, crop type, and local regulations. Their influence is critical in promoting integrated pest management practices.
- Agrochemical Distributors:These entities form the backbone of the supply chain, purchasing ethiprole from manufacturers and supplying it to farms, retailers, and other end-users. Syngenta leverages established distribution channels in major agricultural economies.
- Contract Sprayers:Professional applicators who offer pest control services to multiple farms, requiring bulk quantities and efficient formulations for their operations.
Each end-user group requires tailored product support and distribution strategies from manufacturers.
Packaging Type:
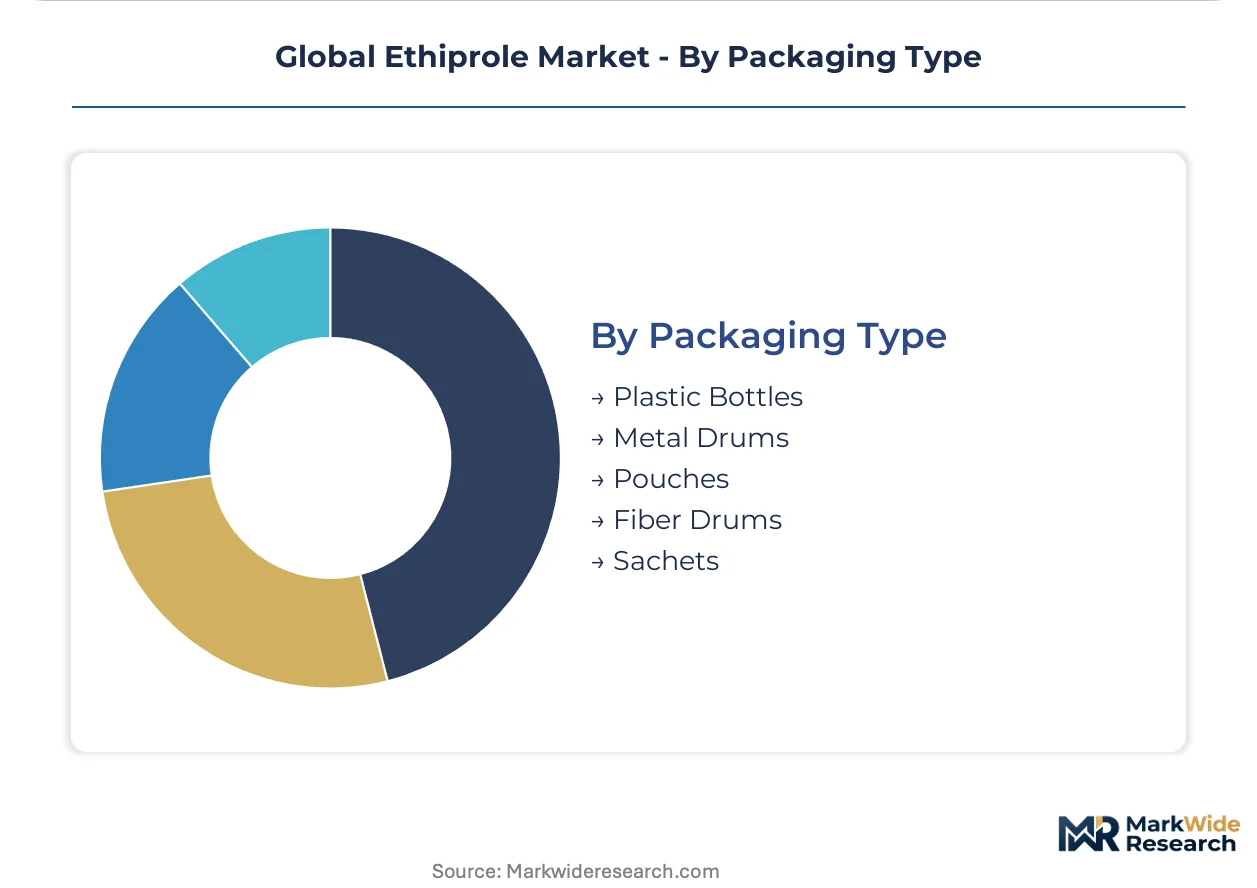
The choice of packaging for ethiprole products is influenced by volume requirements, safety regulations, and convenience for different end-user segments.
- Plastic Bottles:Commonly used for smaller to medium volumes of liquid ethiprole formulations, offering ease of handling and precise dosing for individual farmers. These are prevalent in markets where smaller landholdings dominate.
- Metal Drums:Employed for larger bulk quantities of liquid or granular ethiprole, suitable for large-scale agricultural operations and industrial formulators. These are often seen in major agricultural economies like China and the United States.
- Pouches:Flexible packaging solutions for smaller quantities, often used for granular or soluble powder formulations, providing convenience and reduced waste.
- Fiber Drums:Typically used for bulk packaging of dry formulations like water dispersible granules, offering a cost-effective and environmentally conscious option.
- Sachets:Single-use or small-dose packaging, ideal for small farms or specific applications, minimizing waste and ensuring accurate application rates.
The selection of packaging directly impacts product stability, logistics, and end-user convenience across diverse agricultural settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global ethiprole market exhibits distinct regional dynamics, with supply-side concentration heavily influencing market accessibility and product flow. China's expanded production capacity for ethiprole is reshaping global supply dynamics. This concentration influences market access and pricing across key agricultural regions. Manufacturers must adapt to evolving trade policies and local demand patterns.
China
Demand for ethiprole in China is primarily driven by its extensive cereal crops sector and significant agricultural scale. The Ministry of Ecology and Environment (MEE) defines stringent environmental standards for agrochemical production and use. Jiangsu province, home to manufacturers like Jiangsu Tuoqiu Agrochemical Ltd, is a hub for technical grade ethiprole manufacturing.
India
India's demand for ethiprole stems from heightened food security objectives and the need to protect major crops like cereals and cotton. The Central Insecticides Board governs market access and defines specific uses for pest control agents. Gujarat and Maharashtra represent key agricultural and agrochemical manufacturing regions, driving adoption of effective insecticides.
United States
In the United States, ethiprole demand is influenced by large agricultural enterprises adopting precision application technology for crops like cotton. The US Environmental Protection Agency (EPA) establishes Maximum Residue Levels (MRLs) and approves specific product formulations. Major agricultural states like California and those in the Midwest are key end-user markets for advanced pest control solutions.
France
France, within the European Union, sees demand for ethiprole shaped by the EU Green Deal and its Farm to Fork strategy, which prioritize lower-dose, higher-efficacy products. The European Chemicals Agency (ECHA) conducts rigorous environmental assessments, impacting formulation development. Agricultural regions such as Nouvelle-Aquitaine are actively seeking compliant and sustainable pest control options.
Brazil
Brazil's large agricultural enterprises are rapidly adopting precision application technology to optimize chemical use for staple crops. The Agência Nacional de Vigilância Sanitária (ANVISA) regulates pesticide registration and use, influencing market entry for new formulations. Mato Grosso, a major agricultural state, is a significant market for advanced insecticides and precision farming equipment.
Global Ethiprole Market Key Industry Players
Large multinational agrochemical companies and specialized technical grade manufacturers split the market for ethiprole. The market structure is moderately concentrated, with a few major players dominating the formulated products segment. Strategic archetypes include global innovators focused on R&D and regional specialists emphasizing cost-effective technical grade supply. Capacity expansion and the development of specialized formulations are dominant competitive moves.
Within the large multinational tier, Bayer CropScience AG and Syngenta represent established players with broad portfolios and extensive distribution channels. Jiangsu Tuoqiu Agrochemical Ltd, a Chinese company, exemplifies the specialized technical grade manufacturers, supplying active ingredients to global formulators. These companies navigate a complex regulatory environment and varying regional demands, influencing their product development and market strategies.
| Leading Market Players |
|---|
| Bayer CropScience AG |
| Rayfull Holding Co., Ltd. |
| Jiangsu Tuoqiu Agrochemical Ltd |
| Syngenta |
| BASF |
| Sumitomo Chemical |
| UPL Limited |
| Nufarm |
| Adama Agricultural Solutions |
| Others |
Cost & Logistics Intelligence
Regulatory divergence between major agricultural blocs creates a compliance chokepoint that determines both pricing tier spreads for ethiprole formulations and the geographic shape of its supply chain.
Pricing Analysis
The European Chemicals Agency (ECHA) dictates the pricing tier structure, especially for advanced, lower-dose formulations required in the EU. Per-unit transactional pricing dominates for formulated products sold to end-users. Price differentiation stems from brand premium for established players like Bayer CropScience AG, certification levels for specific regional approvals, and volume scale for large agricultural enterprises. Pricing pressure stems from generic competition, particularly from technical grade manufacturers in India and China. Agricultural farms often exhibit the most price sensitivity, while large enterprises prioritize efficacy and compliance.
Supply Chain Analysis
The upstream supply of technical grade ethiprole active ingredients primarily originates from concentrated manufacturing hubs in China. Geographic supply concentration exists in China and India for technical grade material, which feeds global formulators. Raw material dependencies include chemical intermediates required for phenylpyrazole synthesis. Single-source vulnerability from this concentration represents a structural supply chain risk. Distribution runs through agrochemical distributors who procure from manufacturers and supply to agricultural farms and contract sprayers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethiprole market presents a fragmentation opportunity, driven by demand-side shifts towards precision agriculture and integrated pest management, creating distinct niches for specialized solutions.
For Market Incumbents: Insulate core market share by investing heavily in R&D for advanced, lower-dose formulations that meet evolving environmental standards like the EU Green Deal. Consolidate distribution channels in mature agricultural economies to counter generic competition from technical grade manufacturers. Maintain strong relationships with large agricultural cooperatives by offering integrated pest management support. Expand production capacity in strategic regions like China to secure supply.
For New Entrants and Emerging Players: Pursue market entry into emerging economies, particularly in Africa and Southeast Asia, where pest pressure is high and modern insecticide adoption is increasing. Target non-agricultural applications, such as structural termite control or public health vector control, with specialized formulations. Focus on securing new market registrations for ethiprole on specific crops like rice in Vietnam. Partner with regional distributors to leverage existing local networks.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized formulators with strong regulatory compliance capabilities. Long-term viability is strong for entities that can adapt to evolving environmental and health standards. Target technical grade manufacturers with expanded capacity in key regions like China or formulators with unique intellectual property in combination products. Watch for shifts in major regulatory frameworks, such as ECHA assessments, as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Secures stable supply of active ingredients for global formulators and mitigates regional supply chain risks. |
| R&D in Combination Products | Manages insect resistance and broadens pest control spectrum, creating new intellectual property for formulators. |
| Targeted New Market Registrations | Unlocks significant volume opportunities in high-growth agricultural economies like Vietnam for specific crops. |
| Integrated Pest Management (IPM) Support | Aligns with sustainability mandates and strengthens relationships with large agricultural cooperatives in mature markets. |
| Non-Agricultural Market Diversification | Expands revenue streams into professional pest management and public health sectors beyond crop protection. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, company annual reports, and agricultural trade statistics. This involved in-depth interviews with agrochemical R&D directors, farm managers, regulatory affairs specialists, and key distributors. Bottom-up data aggregation and top-down market sizing provided robust triangulation. Data from the US EPA, ECHA, and India's Central Insecticides Board informed market parameters.
Forecast inputs being considered include historical sales data, evolving regulatory landscapes, and agricultural commodity price trends across the analysis window. The quantitative model integrates segmentation by product type, application, end user, and packaging type. Compound Annual Growth Rates were derived from an analysis of historical market expansion and projected growth catalysts. Crop production forecasts and pest resistance development rates served as critical industry-specific variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational agrochemical companies or new technical grade entrants would shift outcomes. Assumptions account for current regulatory frameworks and expected pest control challenges. Cross-checking against agricultural output statistics and global pesticide usage reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Rust Preventive Oil Market
Industrial Chemicals
Proline Market
Industrial Chemicals
Industrial Cyclohexylamine Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Global N-Methyl-2-Pyrrolidone (NMP) Market
Industrial Chemicals
North America Biocides Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Oilfield Scale Inhibitors Market
Industrial Chemicals
Chlorine Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Naphthenic Acid Market
Industrial Chemicals
Sulfur Recovery Technology Market
Industrial Chemicals
Honing Oil Market
Industrial Chemicals
Hazardous Chemicals Packaging Market
Industrial Chemicals
Indonesia Construction Chemicals Market
Industrial Chemicals
Industrial Phenol Market