
 Global Electronic Grade Sulfuric Acid Market | 2026-2036
Global Electronic Grade Sulfuric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Grade Sulfuric Acid Market Foresight
Multi-source procurement among semiconductor chemical buyers is pivoting toward qualified dual-vendor arrangements for sulfuric acid supply security. BASF SE leverages its integrated sulfur-to-acid production network across European and Asian sites to serve foundry customers with consistent lot-to-lot purity. Kanto Chemical Co., Inc. anchors its position through captive distillation capabilities and direct pipeline connections to Japanese semiconductor fabrication plants. INEOS Group Holdings S.A. competes on merchant sulfur access and bulk logistics scale, particularly for European electronics manufacturing customers.
Electronic grade sulfuric acid denotes sulfuric acid purified to parts-per-billion metal impurity levels, typically manufactured through multi-stage distillation, membrane filtration, or vapor-phase oxidation to achieve the sub-100 ppt specifications demanded by sub-7 nanometer semiconductor etching processes. Its primary commercial purpose centers on silicon wafer surface preparation, photoresist stripping, and controlled oxide removal in cleanroom environments. Concentrated sulfuric acid and fuming sulfuric acid variants occupy the largest volume positions in current semiconductor fabrication plant consumption, while ultra-purity grades within the purity grade taxonomy command the strongest margin pools as process node geometries shrink. Semiconductor etching applications lead absolute demand within the application dimension, though photovoltaic cell production represents a structurally faster-growing outlet as solar cell manufacturers adopt semiconductor-grade wet chemistry for passivation layer processing.
EPA regulations in the United States and REACH frameworks in Europe impose stringent reporting and purity documentation requirements on electronic chemical suppliers, effectively raising barriers to qualification for new market entrants. China's NMPA and GB standards for electronic chemicals add parallel certification layers for suppliers targeting domestic semiconductor fabrication capacity expansion. Japan's METI coordinates national purity standards through JIS frameworks that align with SEMI guidelines for global equipment and materials compatibility. Stakeholders must monitor how divergent regional purity specifications and carbon border adjustments reshape qualification timelines and regional sourcing economics for new fabrication plant projects.
Market Dynamics
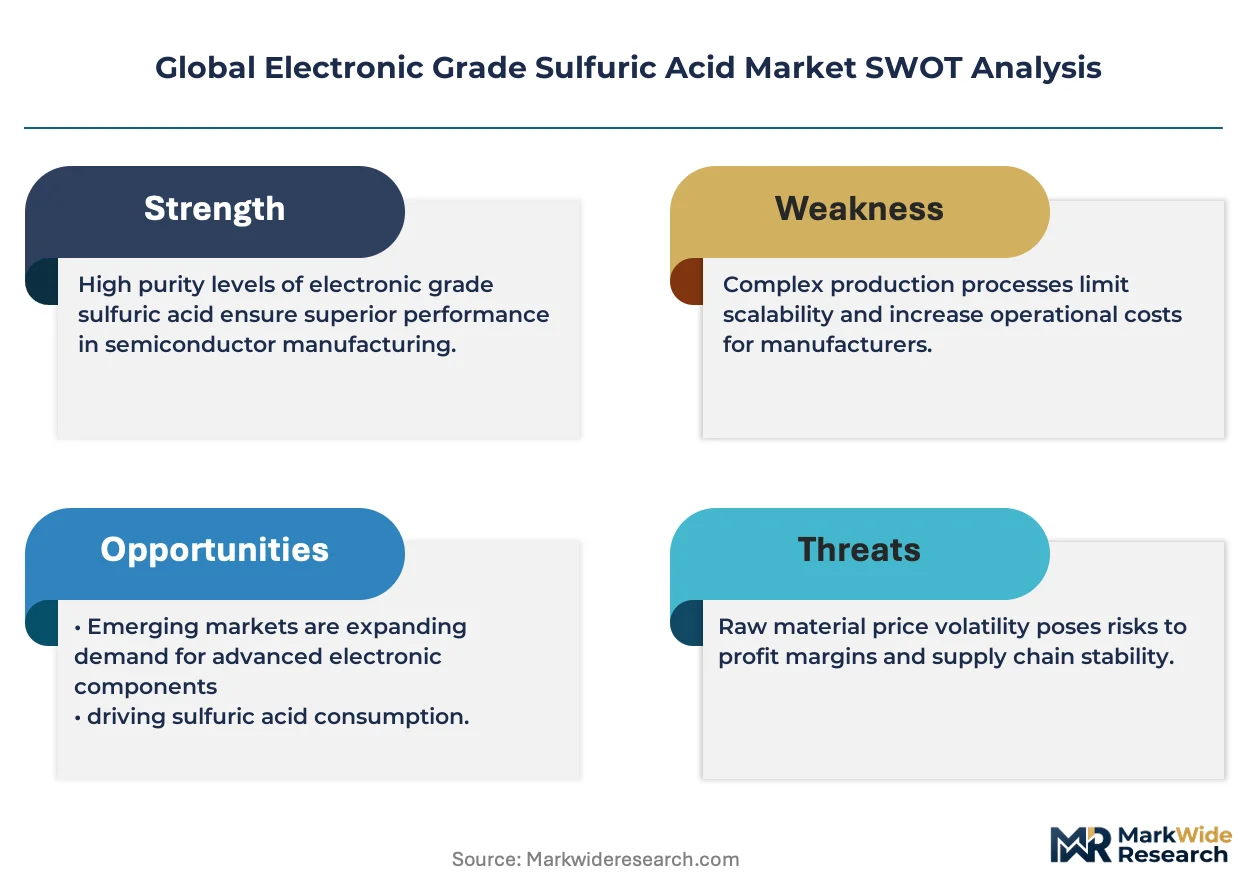
Sub-7 nanometer semiconductor etching specifications are compressing impurity tolerances from parts-per-billion to parts-per-trillion thresholds, forcing sulfuric acid producers to retool distillation trains and membrane filtration arrays ahead of foundry qualification cycles.
Growth Catalysts
- Taiwanese foundry expansion:TSMC and UMC are commissioning new fabrication plants in Tainan and Taichung that require ultra-purity sulfuric acid volumes exceeding existing local supply contracts.
- REACH impurity thresholds:The EU Green Deal's tightening emissions protocols for electronic chemical production are accelerating qualification of closed-loop sulfuric acid regeneration systems at European semiconductor manufacturing sites.
- Photovoltaic passivation adoption:Solar cell manufacturers in South Korea are importing semiconductor-grade wet chemistry for PERC and TOPCon cell fabrication, creating a structurally faster-growing outlet than traditional electronics.
Market Restraints
- Merchant sulfur price volatility:Sulfuric acid producers lack captive sulfur access, exposing margin structures to fluctuations in oil refining byproduct availability and phosphate fertilizer industry offtake patterns.
- Kanto Chemical pipeline dominance:Direct pipeline connections between Japanese distillers and domestic fabrication plants create supply security advantages that foreign entrants cannot replicate without decade-long infrastructure commitments.
- Fluorine-based dry etching substitution:Plasma etching technologies using CF4 and SF6 chemistries are displacing wet sulfuric acid processes in certain oxide removal steps at advanced nodes below 3 nanometers.
Strategic Opportunities
- Indian semiconductor manufacturing:The country's PLI scheme for electronic components is attracting foundry investments in Gujarat and Karnataka where no qualified local sulfuric acid suppliers currently exist.
- Closed-loop regeneration systems:On-site acid recovery and redistillation units at fabrication plants reduce virgin acid consumption and align with EPA hazardous waste reduction mandates in the United States.
- SEMI guideline convergence:Global standardization of purity documentation through SEMI C3 and C28 frameworks is reducing multi-regional qualification costs for suppliers with existing JIS or GB certifications.
Industry Challenges
- Cleanroom chemist scarcity:Semiconductor fabrication plants report acute shortages of process engineers capable of validating lot-to-lot purity consistency for sub-100 ppt sulfuric acid specifications.
- Dual-vendor qualification timelines:Foundry customers demand 18-24 month parallel testing periods before approving secondary sulfuric acid sources, compressing supplier revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Grade Sulfuric Acid Market |
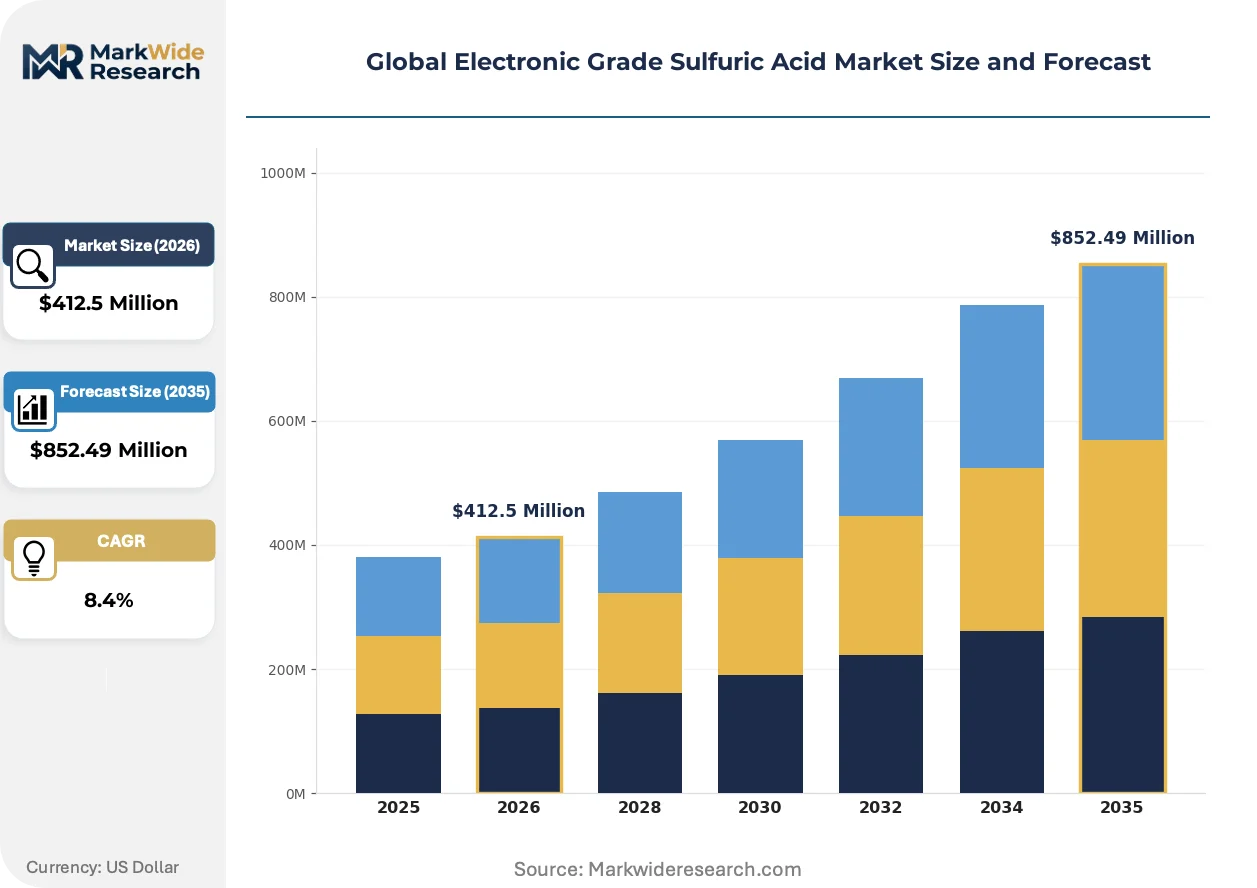
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuming Sulfuric Acid, Oleum, Concentrated Sulfuric Acid, Diluted Sulfuric Acid Purity Grade: Ultra-Pure, High-Purity, Electronic Grade, Semiconductor Grade Application: Semiconductor Etching, Circuit Board Manufacturing, Photovoltaic Cell Production, Chemical Synthesis End User Industry: Semiconductor Fabrication Plants, Electronics Manufacturing, Solar Panel Producers, Specialty Chemical Manufacturers |
| Companies Covered | BASF SE, INEOS Group Holdings S.A., KMG Chemicals, Chemtrade Logistics, Kanto Chemical Co., Inc., Linde plc, PVS Chemicals, Honeywell International Inc., Asia Union Electronic Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Grade Sulfuric Acid Market Shifts & Advancements
Vapor-phase oxidation and point-of-use purification systems are displacing centralized bulk supply models, while regulatory documentation requirements and procurement consolidation are reshaping competitive positioning across the value chain.
Membrane contactor technology for final metal ion removal is modularizing sulfuric acid purification architectures. Foundry customers in South Korea are piloting skid-mounted units adjacent to etch baths rather than accepting tanker deliveries from off-site distillers. This distributed approach is compressing logistics costs and reducing contamination risk during transport.
EPA hazardous waste manifesting requirements under RCRA are tightening chain-of-custody documentation for spent sulfuric acid streams. Semiconductor fabrication plants in the United States must now report metal impurity accumulation rates to regional offices, increasing administrative burden but creating audit-ready data trails for ESG disclosures. Arizona and Texas fabrication clusters are responding by investing in on-site regeneration capacity.
Consolidated procurement desks at major foundry operators are unbundling sulfuric acid supply from bundled chemical management contracts. Direct negotiations between plant-level technical staff and distiller technical service teams are replacing distributor intermediaries in Taiwan and Japan. This disintermediation is most visible at TSMC's southern Taiwan science park facilities where pipeline-connected suppliers now handle volume scheduling without third-party logistics involvement.
Global Electronic Grade Sulfuric Acid Market Segmentation
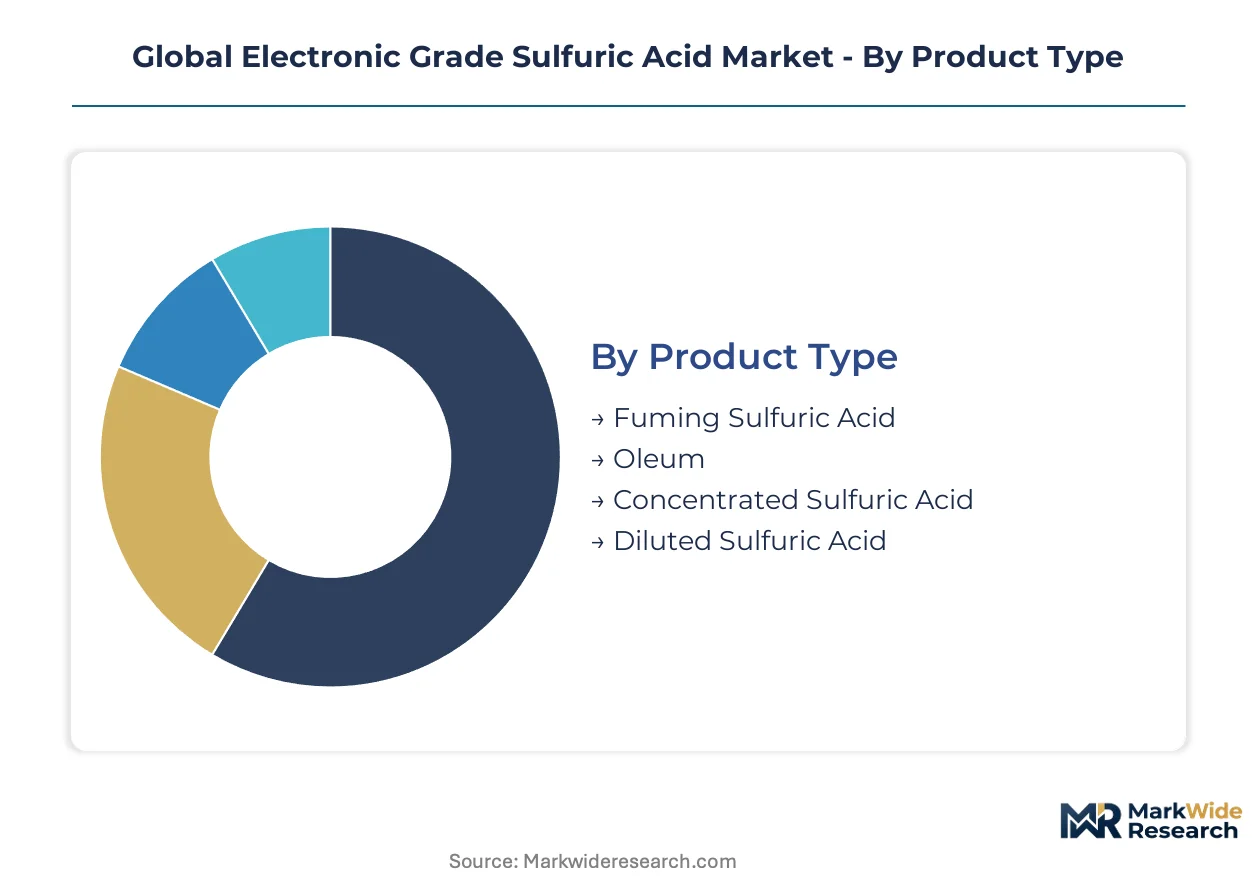
Segmentation in electronic grade sulfuric acid tracks how purity thresholds, application specificity, and supply chain integration depth fragment procurement patterns across semiconductor fabrication ecosystems. Each dimension carries distinct qualification timelines and margin structures that reshape vendor-customer relationships.
Product Type:
Integration depth varies sharply: concentrated and fuming grades flow through centralized bulk systems, while diluted variants increasingly deploy at point-of-use via modular skids adjacent to etch baths.
- Fuming Sulfuric Acid:Contains dissolved sulfur trioxide at 20-65% concentration, demanding specialized corrosion-resistant handling infrastructure. TSMC's Tainan facilities anchor regional demand as sub-7 nanometer node etching specifications tighten impurity tolerances. The compound's aggressive reactivity limits transport radius and favors pipeline-connected supply.
- Concentrated Sulfuric Acid:Represents the workhorse specification at 93-98% purity, manufactured through multi-stage distillation to achieve parts-per-billion metal content. Arizona and Texas fabrication clusters in the United States consume bulk volumes for photoresist stripping and wafer surface preparation, though on-site regeneration systems are compressing virgin acid offtake.
- Oleum:Sulfur trioxide solutions in sulfuric acid base, deployed where sulfonation chemistry or extreme dehydration drives process requirements.
- Diluted Sulfuric Acid:Pre-blended or point-of-use diluted specifications, gaining traction as foundries reduce hazardous chemical inventory on-site.
Volume placements concentrate in Concentrated Sulfuric Acid; the steepest expansion trajectory belongs to Diluted Sulfuric Acid as distributed purification architectures displace centralized bulk models.
Purity Grade:
Cost tier stratification separates qualification-intensive ultra-purity specifications from standard electronic grades, with margin pools inversely correlated to volume throughput.
- Ultra-Pure:Sub-100 parts-per-trillion metal specifications achieved through vapor-phase oxidation and membrane contactor final polishing. South Korean foundries at Samsung and SK Hynix drive qualification urgency as 3 nanometer node production ramps, where single-particle contamination risks wafer loss economics.
- Semiconductor Grade:Parts-per-billion thresholds sufficient for mature node fabrication above 28 nanometers, where price sensitivity outweighs incremental purity premiums. Taiwanese packaging and testing houses consume steady volumes, though this segment faces margin compression from regenerative acid systems.
- High-Purity:Intermediate specification bracket serving display panel manufacturing and legacy semiconductor processes.
- Electronic Grade:Baseline purity tier for circuit board manufacturing and general electronics cleaning applications.
Revenue concentration sits with Ultra-Pure grades; Semiconductor Grade captures the widest volume base.
Application:
Customer type fragmentation splits between captive semiconductor fabrication demand and emerging photovoltaic adoption, each with divergent purity documentation and procurement cadence requirements.
- Semiconductor Etching:Dominates absolute consumption through silicon wafer surface preparation, controlled oxide removal, and photoresist stripping in cleanroom environments. Japanese fabrication plants connected via direct pipeline to Kanto Chemical and Stella Chemifa facilities operate on just-in-time delivery schedules that foreign entrants cannot replicate.
- Photovoltaic Cell Production:PERC and TOPCon cell fabrication in South Korea is importing semiconductor-grade wet chemistry for passivation layer processing, creating demand growth structurally faster than traditional electronics applications despite smaller absolute volumes.
- Circuit Board Manufacturing:Printed circuit board etching and surface finishing, where purity requirements moderate relative to wafer fabrication.
- Chemical Synthesis:Specialty chemical manufacturing requiring electronic-grade feedstock for catalyst and reagent production.
Demand scale favors Semiconductor Etching; Photovoltaic Cell Production is gaining share fastest as solar cell efficiency roadmaps converge with semiconductor process chemistry.
End User Industry:
Supply concentration maps to geographic clustering of fabrication capacity, with procurement consolidation at major foundry operators reshaping vendor access patterns.
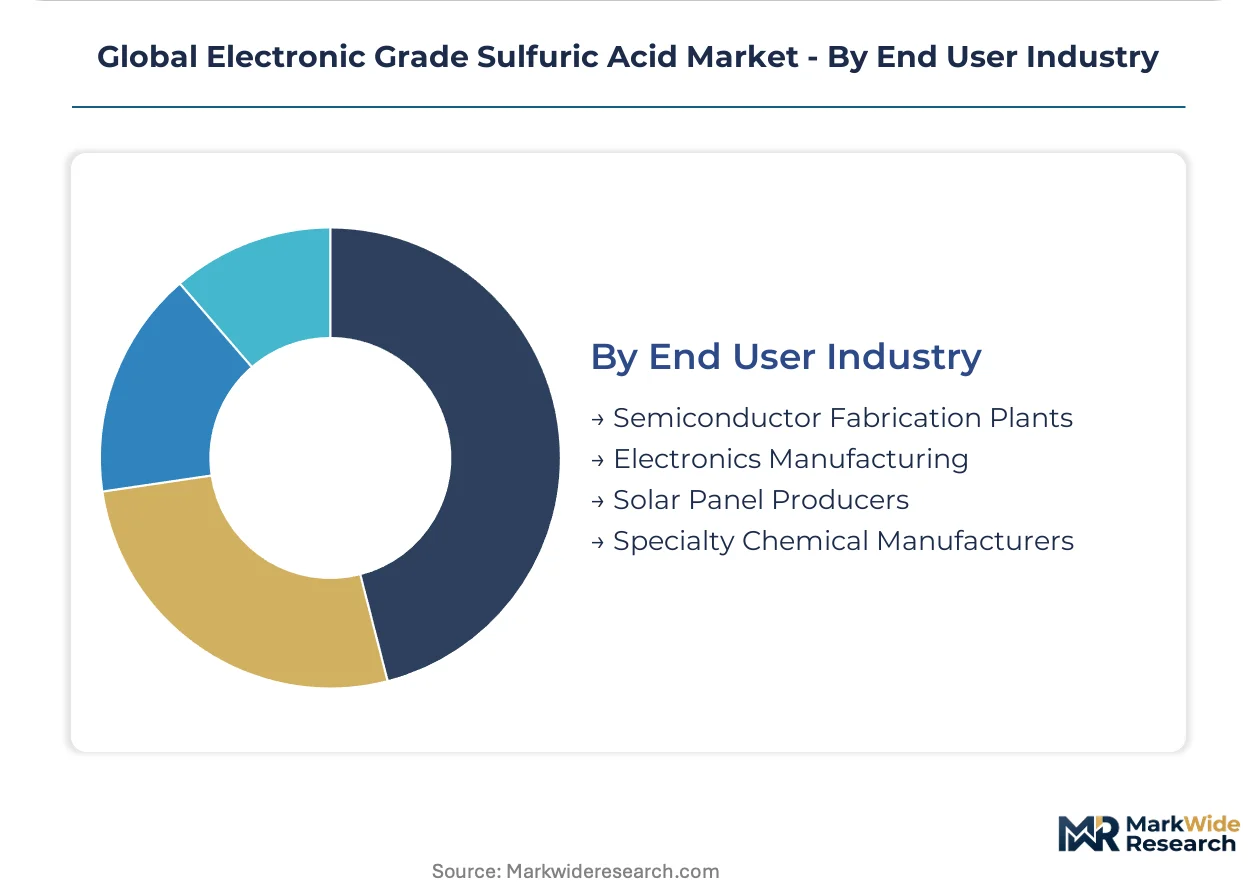
- Semiconductor Fabrication Plants:Foundry and IDM facilities command the tightest purity specifications and longest qualification timelines, with 18-24 month parallel testing periods for secondary sulfuric acid sources. TSMC, Samsung, and Intel procurement desks are disintermediating distributor relationships in favor of direct technical service negotiations with distiller field teams.
- Solar Panel Producers:Emerging demand segment with accelerating purity requirements as cell efficiency targets tighten, though qualification frameworks remain less stringent than semiconductor counterparts.
- Electronics Manufacturing:Assembly and component production facilities consuming electronic-grade acids for cleaning and surface treatment.
- Specialty Chemical Manufacturers:Downstream chemical synthesis operations requiring high-purity sulfuric acid as process input.
Procurement volume centers on Semiconductor Fabrication Plants; Solar Panel Producers show the most rapid demand acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sulfur deposits in volcanic zones and petroleum refining centers anchor electronic grade sulfuric acid production networks. Foundry demand concentrates where semiconductor fabrication clusters intersect with merchant sulfur supply corridors.
United States
TSMC's Arizona fabrication complex and Intel's expansion in Ohio drive ultra-purity acid demand. EPA hazardous waste manifesting under RCRA tightens documentation for spent acid streams. Texas and Arizona fabrication clusters invest in on-site regeneration capacity to reduce virgin acid offtake.
Taiwan
TSMC and UMC commission new fabrication plants in Tainan and Taichung requiring sulfuric acid volumes beyond existing supply contracts. The island's environmental regulator encloses emissions protocols for electronic chemical production. Southern Taiwan science park facilities now schedule pipeline-connected volumes without third-party logistics.
South Korea
Samsung and SK Hynix ramp 3 nanometer node production with sub-100 ppt purity specifications. MFDS aligns national standards with SEMI guidelines for materials compatibility. The Busan-Ulsan corridor hosts foundry pilot programs for skid-mounted point-of-use purification systems.
Japan
METI coordinates JIS purity standards that govern domestic qualification frameworks. Direct pipeline connections between distillers and fabrication plants create supply security advantages in the Kanto region. Kanto Chemical anchors procurement relationships through captive distillation capabilities.
Germany
REACH frameworks and the EU Green Deal accelerate closed-loop regeneration system adoption at European semiconductor sites. BASF leverages integrated sulfur-to-acid production networks across European sites. Saxony-Anhalt and Bavaria host specialty chemical manufacturing requiring high-purity feedstock.
Global Electronic Grade Sulfuric Acid Market Competitive Landscape
Global majors compete with regional champions across purification technology and supply chain integration depth. The vendor base stratifies into three tiers: integrated chemical conglomerates with captive sulfur access, regional specialists with direct foundry pipeline connections, and merchant suppliers competing on logistics scale. Strategic archetypes include backward-integrated producers controlling feedstock, distillation-focused specialists, and logistics-optimized bulk handlers. Capacity expansion and qualification partnerships dominate competitive moves as foundries demand dual-vendor security.
Among integrated chemical conglomerates, BASF SE exemplifies the backward-integrated archetype through sulfur-to-acid production networks. Kanto Chemical Co., Inc. occupies a position as the regional specialist archetype with direct pipeline infrastructure. INEOS Group Holdings S.A. represents the logistics-scale competitor serving merchant demand across European electronics manufacturing.
| Leading Market Players |
|---|
| BASF SE |
| INEOS Group Holdings S.A. |
| KMG Chemicals |
| Chemtrade Logistics |
| Kanto Chemical Co., Inc. |
| Linde plc |
| PVS Chemicals |
| Honeywell International Inc. |
| Asia Union Electronic Chemical Corporation |
| Others |
Supply & Pricing Matrix
Vapor-phase oxidation and point-of-use purification systems are compressing logistics costs while redrawing where value capture concentrates along the sulfuric acid value chain. This technology transition simultaneously elevates capital intensity for producers and fragments procurement power as foundries gain optionality between centralized bulk supply and distributed on-site generation.
Pricing Analysis
Technical service bundling formerly justified premium positioning for ultra-purity grades, though foundry procurement desks in Taiwan and South Korea are now unbundling acid supply from bundled chemical management contracts. Three-tier pricing structure across ultra-purity, semiconductor-grade, and high-purity specifications tracks qualification intensity and impurity thresholds. Price differentiation hinges on sub-100 ppt certification status and direct pipeline connectivity to fabrication plants. Cost compression in semiconductor-grade tiers is intensifying because regenerative acid systems at Arizona and Texas facilities reduce virgin acid offtake. Photovoltaic cell manufacturers in South Korea exhibit highest price sensitivity as they import semiconductor-grade chemistry for passivation processing without captive volume commitments.
Supply Chain Analysis
Cleanroom chemist scarcity in Taiwan, South Korea, and Japan constrains qualification throughput and extends vendor onboarding timelines. Production gravity centers on East Asian manufacturing clusters where foundry capacity additions outpace other regions. Feedstock supply draws from merchant sulfur streams tied to oil refining byproduct availability and phosphate fertilizer industry offtake patterns. Single-source vulnerability persists where Kanto Chemical's direct pipeline connections to Japanese fabrication plants create supply security advantages foreign entrants cannot replicate without decade-long infrastructure commitments. Distribution runs through direct technical service negotiations between plant-level staff and distiller field teams, displacing distributor intermediaries in Taiwan and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electronic grade sulfuric acid market is becoming a vertical-integration race as producers pursue captive sulfur access to insulate margin structures from merchant feedstock volatility.
For Market Incumbents: Anticipate displacement pressure from fluorine-based dry etching substitution at sub-3 nanometer nodes by accelerating closed-loop regeneration system partnerships with Arizona and Texas fabrication clusters. Deepen backward integration into sulfur-to-acid production networks to match BASF's integrated model across European and Asian sites. Defend qualification relationships through 18-24 month parallel testing investments that compress entrant revenue recognition windows. For New Entrants and Emerging Players: Solar panel producers in India present the most penetrable buyer archetype as the country's PLI scheme for electronic components attracts foundry investments in Gujarat and Karnataka where no qualified local sulfuric acid suppliers currently exist. Target photovoltaic passivation adoption in South Korea where semiconductor-grade wet chemistry demand is structurally faster-growing than traditional electronics. Pursue SEMI C3 and C28 certification pathways to reduce multi-regional qualification costs for suppliers with existing JIS or GB certifications. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of regional specialists with direct foundry pipeline infrastructure and captive distillation capabilities. Long-term viability over the projection horizon favors producers with backward-integrated sulfur access and modular point-of-use purification technology portfolios. Watch for inflection in Indian semiconductor manufacturing commitments as signal for geographic supply rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Feedstock | Captive sulfur access insulates margin structures from oil refining byproduct availability swings. |
| Closed-Loop Regeneration System Deployment | On-site acid recovery at Arizona and Texas fabrication plants aligns with EPA hazardous waste reduction mandates. |
| SEMI C3 and C28 Certification Investment | Global standardization reduces multi-regional qualification costs for suppliers with existing JIS or GB certifications. |
| Direct Pipeline Infrastructure Expansion | Pipeline-connected supply to TSMC's southern Taiwan science park facilities eliminates third-party logistics involvement. |
| Point-of-Use Purification Skid Deployment | Modular units adjacent to etch baths at Samsung and SK Hynix compress contamination risk during transport. |
Research Methodology
Independent corroboration across primary interviews with plant managers at semiconductor fabrication facilities, procurement leads at downstream foundry operators, distribution channel partners in East Asian chemical logistics networks, and technical R&D directors at sulfuric acid distillers underwrites the qualitative findings. Secondary validation drew from customs and trade data, SEMI industry reports, SEC 10-K filings of integrated chemical conglomerates, and EPA hazardous waste manifesting records under RCRA. Bottom-up demand modeling across purity grades and applications triangulated against top-down market sizing from production capacity disclosures.
Rate-of-change decomposition across the analysis window disaggregated volume growth into node shrinkage effects, foundry capacity addition, and substitution dynamics between wet and dry etching chemistries. Segmentation dimensions modeled include purity grade tier, application specificity across semiconductor etching and photovoltaic passivation, end-use industry concentration, and regional production hub clustering. CAGRs were derived from weighted capacity expansion schedules and qualification timeline assumptions. Industry-specific forecast inputs incorporated REACH and EU Green Deal emissions protocol tightening, China's NMPA certification layers for domestic fabrication capacity, and Japan's METI-coordinated JIS purity standards.
Revisions become necessary when sub-3 nanometer node production ramps accelerate fluorine-based dry etching substitution, merchant sulfur price volatility disrupts feedstock economics, or Indian and Southeast Asian fabrication investments materially alter geographic demand distribution. Material deviation in these triggers warrants pause and re-evaluation of vendor positioning and capacity commitment assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Pelletized Activated Carbon Market
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Froth Flotation Chemicals Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
Paraffin Inhibitors Market
Industrial Chemicals
Foam Market
Industrial Chemicals
Potassium Acetate Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
Global Ethylene Carbonate Market
Industrial Chemicals
Chlorine Market
Industrial Chemicals
Metalworking Treating Fluid Market