
 Oman Sodium Hydroxide Market | 2026-2036
Oman Sodium Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Sodium Hydroxide Market Intelligence
Maintenance contracts for membrane cell electrolysis systems is repositioning how buyers procure sodium hydroxide in Oman, shifting capital expenditure into operational partnerships. Oman Chlorine S.A.O.G anchors domestic supply through its integrated chlor-alkali complex near Sohar. BASF SE leverages its technical service network to secure long-term offtake agreements with water treatment operators. EQUATE Petrochemical Company competes on feedstock integration across Kuwait and Oman operations.
Sodium hydroxide, commonly called caustic soda, is an inorganic compound with the formula NaOH, typically produced via membrane electrolysis of brine at concentrations of 50% solution or 98-99% solid form; it serves as a fundamental reagent for pH adjustment, saponification, and chemical synthesis across industrial processes. Liquid caustic soda dominates volume offtake from Sohar's alumina refineries and petrochemical plants due to bulk handling efficiency. Industrial grade material captures the largest purity segment, though pharmaceutical grade commands premium pricing for specialized applications in regional healthcare manufacturing.
Oman's Ministry of Commerce, Industry and Investment Promotion and the country's national standards body enforce chemical safety and handling protocols that shape product labeling, storage infrastructure, and import documentation requirements for caustic soda traders. The Sultanate's alignment with Gulf Cooperation Council technical regulations further harmonizes cross-border shipment standards across the Arabian Peninsula. Stakeholders must monitor how Oman's industrial diversification strategy and downstream chemical park investments alter procurement patterns and local production economics.
Market Dynamics
Membrane cell electrolysis retrofits at Sohar's chlor-alkali facilities are compressing legacy mercury-cell capacity while tightening chlorine-hydrogen balancing requirements across Oman's chemical parks. This technology transition is redrawing supply contracts and forcing buyers into longer-term offtake negotiations.
Growth Catalysts
- Desalination capacity expansion:Water treatment operators across Muscat Governorate are scaling caustic soda procurement for pH correction in reverse osmosis pre-treatment systems.
- REACH-equivalent alignment:Oman's national standards body is harmonizing chemical safety documentation with Gulf Cooperation Council technical regulations, streamlining cross-border shipments from Sohar Industrial Port.
- Alumina refining integration:Bayer process refineries at Sohar are captive-consuming liquid caustic soda for bauxite digestion, anchoring regional demand.
Market Restraints
- Brine supply concentration:Feedstock sourcing depends on limited seawater intake infrastructure controlled by coastal desalination utilities.
- Energy cost volatility:Electrolysis operations face exposure to natural gas pricing fluctuations under Oman's domestic tariff framework.
- Chlorine absorption bottlenecks:Co-product chlorine offtake from membrane cells requires matched demand from polyvinyl chloride or water treatment sectors.
Strategic Opportunities
- Dhofar industrial corridor:Greenfield chemical park investments near Salalah Port offer untapped offtake potential for specialty caustic grades.
- Pharmaceutical grade certification:Healthcare manufacturing clusters in Muscat are creating pull for higher-purity material meeting Ministry of Health standards.
- Renewable-powered electrolysis:Solar-hydrogen integration projects at Duqm are enabling carbon-intensity differentiation for export-oriented production.
Industry Challenges
- Membrane cell technician scarcity:Specialized maintenance skills for zero-gap electrolyzer technology remain concentrated among Sohar-based engineering contractors.
- Legacy storage infrastructure:Existing carbon steel tanks require lining upgrades to handle membrane-grade caustic concentration specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Sodium Hydroxide Market |
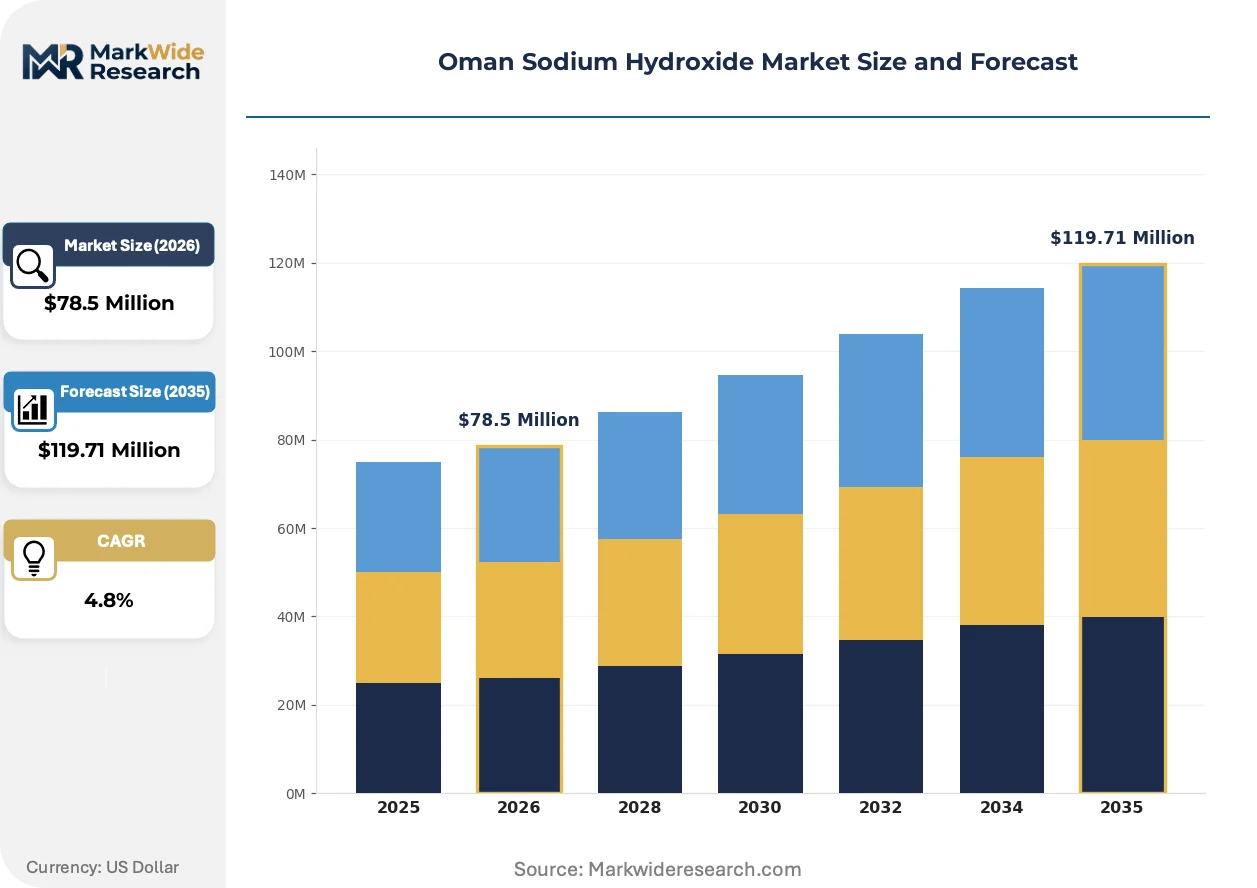
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $119.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Flakes, Granules End Use Industry: Pulp & Paper, Textiles, Chemical Manufacturing, Water Treatment Distribution Channel: Direct Sales, Online, Distributors, Retail Purity Grade: Industrial Grade, Food Grade, Pharmaceutical Grade, Others |
| Companies Covered | Al Karam Group, BASF SE, EQUATE Petrochemical Company, Aditya Birla Chemicals, Olin Corporation, Oman Chlorine S.A.O.G, Occidental Petroleum Corporation, INEOS Group AG, The Dow Chemical Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Sodium Hydroxide Market Strategic Shifts & Innovations
Electrolyzer technology maturation and buyer-side contracting sophistication are converging to reshape how caustic soda flows through Oman's industrial corridors. Three developments warrant particular attention.
Zero-gap membrane cell designs are consolidating operational control across Sohar's chlor-alkali complex. Sohar Industrial Port's petrochemical cluster is adopting these systems for their reduced energy intensity per ton of chlorine equivalent. This consolidation is compressing the margin structure for smaller mercury-cell operators still serving niche industrial accounts.
Oman's Ministry of Commerce, Industry and Investment Promotion is enforcing tightened chemical handling standards under its national industrial safety framework. The regulations mandate upgraded secondary containment and automated leak detection for caustic soda storage above threshold volumes. Water treatment facilities across Muscat Governorate are responding by consolidating procurement through certified logistics providers rather than direct mill sourcing.
Long-term offtake agreements with embedded technical service clauses are displacing spot market purchases among alumina refiners. Sohar's Bayer process operators are locking in five-year supply contracts that bundle membrane cell maintenance expertise with volume commitments. This pattern is most visible across the Sohar Industrial Port chemical park, where feedstock integration economics favor relational contracting over transactional buying.
Oman Sodium Hydroxide Market Segmentation
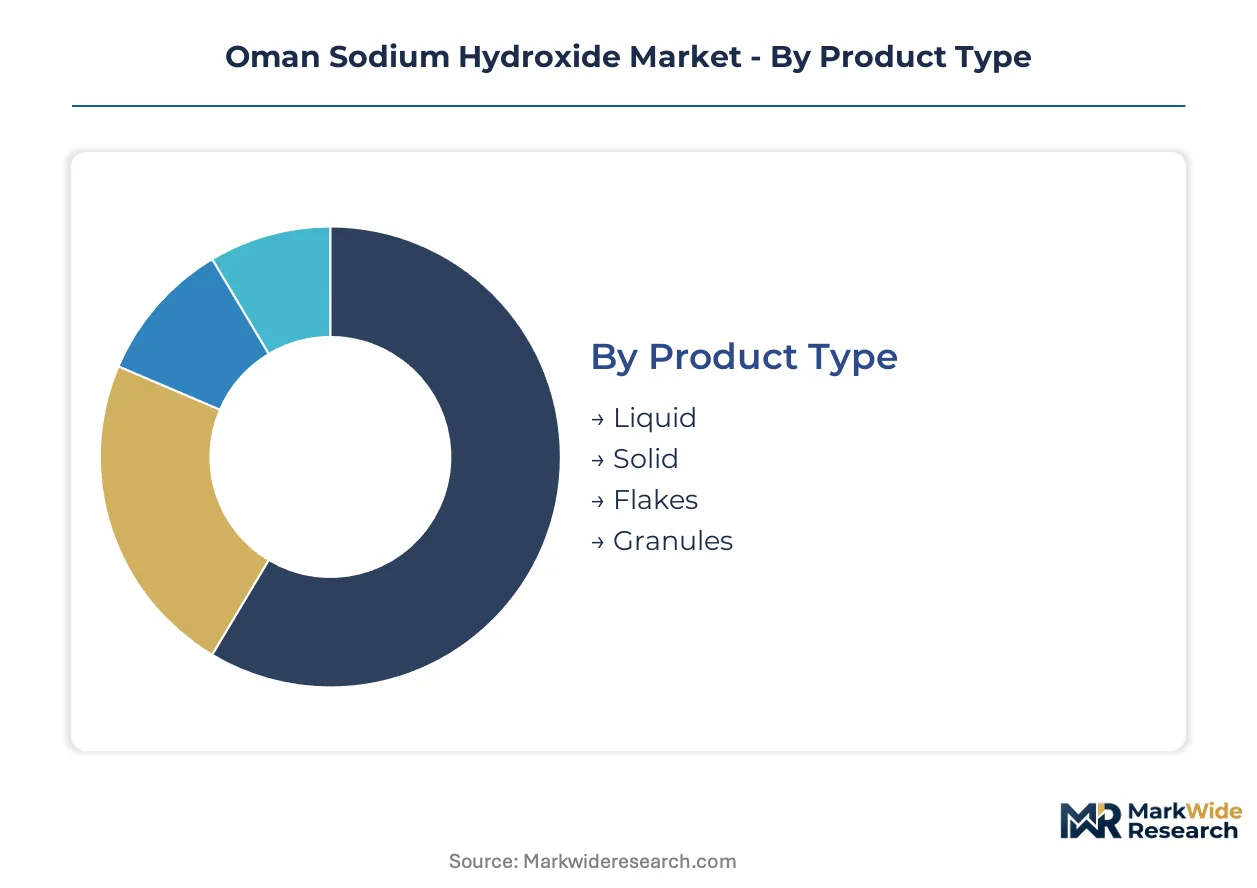
Oman's sodium hydroxide procurement patterns fragment across product forms, purity specifications, and channel structures that reflect the Sultanate's industrial concentration around Sohar and Muscat. Understanding these segment boundaries clarifies where membrane cell producers can capture premium positioning versus commodity volume plays.
Product Type:
Supply concentration at Sohar's chlor-alkali complex heavily favors liquid caustic soda, shaping how buyers across Oman's industrial corridor access material.
- Liquid:Aqueous solution at 50% concentration dominates bulk offtake from Sohar Industrial Port's alumina refineries and petrochemical plants. Membrane cell producers at Sohar pump directly into dedicated pipeline infrastructure serving the Bayer process operators, eliminating packaging and handling costs for high-volume consumers.
- Solid:Cast blocks or anhydrous pellets at 98-99% purity serve remote construction sites and smaller chemical processors lacking liquid storage infrastructure. Dhofar-based contractors source solid forms for concrete admixture applications where transportation economics override handling convenience.
- Flakes:Thin, brittle sheets at 98% purity balance solubility speed with storage stability for textile processors in Muscat's industrial zones. Regional soap manufacturers prefer flakes for controlled dissolution rates in batch saponification.
- Granules:Spherical particles minimize dust generation during pneumatic conveying systems used by water treatment facilities across Muscat Governorate. Desalination operators specify granules for automated dosing equipment requiring consistent flow characteristics.
Today's leader: Liquid. Tomorrow's challenger: Granules.
End Use Industry:
Cost tier differentiation separates captive consumption at integrated industrial sites from spot-market purchasing among fragmented downstream processors.
- Pulp & Paper:Kraft process pulping consumes caustic soda for lignin extraction and fiber bleaching sequences. Oman's limited domestic paper production relies on imported pulp, constraining segment scale despite technical specifications matching Gulf Cooperation Council standards.
- Textiles:Mercerization and scouring operations in Muscat's garment manufacturing clusters drive demand for consistent purity grades. Dye house operators prioritize pH stability over volume discounts, creating margin opportunities for certified suppliers.
- Chemical Manufacturing:Sohar Industrial Port's petrochemical complex represents the highest-volume consumption tier, with chlor-alkali derivatives feeding polyvinyl chloride and epichlorohydrin production. EQUATE Petrochemical's integrated operations across Kuwait and Oman demonstrate how feedstock control shapes procurement economics.
- Water Treatment:Reverse osmosis pre-treatment and wastewater neutralization anchor municipal demand across Muscat and Sohar. The Ministry of Regional Municipalities and Water Resources mandates pH correction protocols that standardize procurement specifications for desalination operators.
Chemical Manufacturing commands volume leadership. Water Treatment offers the steepest expansion trajectory as desalination capacity multiplies.
Distribution Channel:
Customer type and procurement sophistication determine whether buyers transact through relational contracts or arm's-length market mechanisms.
- Direct Sales:Long-term offtake agreements with embedded technical service clauses dominate Sohar's alumina and petrochemical sectors. Oman Chlorine S.A.O.G leverages pipeline connectivity to lock in five-year supply contracts bypassing intermediaries entirely.
- Distributors:Certified logistics providers consolidate procurement for water treatment facilities responding to tightened secondary containment regulations. These intermediaries absorb compliance documentation burdens under Oman's national industrial safety framework.
- Online:Digital procurement platforms serve small-scale textile processors and construction contractors requiring rapid spot purchases. Limited traction reflects the hazardous material shipping constraints that complicate e-commerce fulfillment for caustic soda.
- Retail:Hardware and chemical supply stores stock diluted household and laboratory grades for educational institutions and maintenance contractors. Margins compress at this tier due to packaging and last-mile delivery costs.
Direct Sales structure the high-volume core. Distributors are gaining share fastest as regulatory compliance costs favor outsourced logistics expertise.
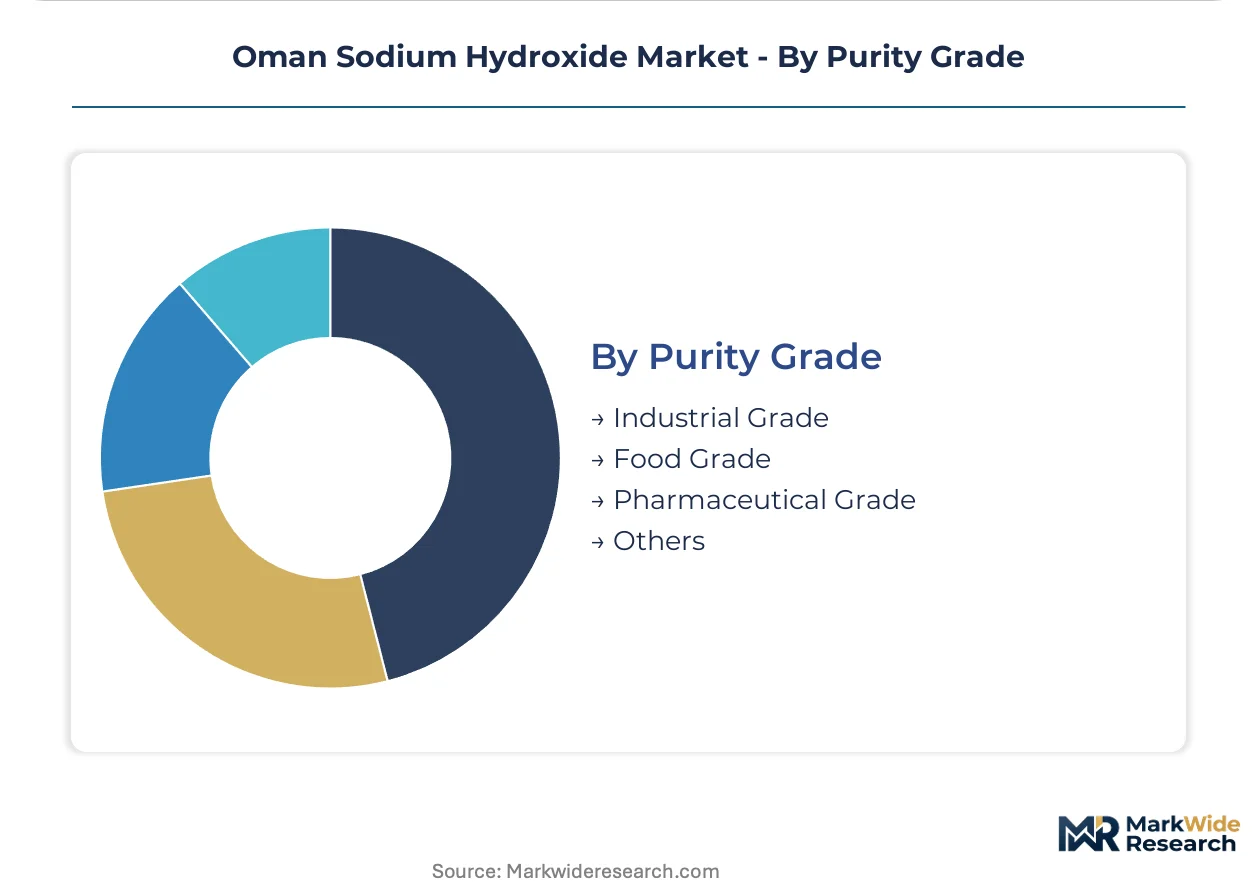
Purity Grade:
Application maturity and certification requirements stratify pricing power across industrial, food, and pharmaceutical specifications.
- Industrial Grade:96-99% purity material satisfies alumina refining, petrochemical synthesis, and wastewater treatment without premium certification overhead. Sohar's membrane cell output concentrates at this specification, matching Gulf Cooperation Council technical regulations for cross-border shipment.
- Pharmaceutical Grade:Ultra-high purity meeting Ministry of Health standards commands substantial premiums for intravenous solution manufacturing and active pharmaceutical ingredient synthesis. Muscat's healthcare manufacturing clusters are pulling capacity toward this segment as domestic pharmaceutical production expands.
- Food Grade:Certified material for olive processing, cocoa treatment, and food equipment cleaning adheres to standards enforced by Oman's Ministry of Commerce, Industry and Investment Promotion. Limited domestic food processing scale constrains segment development relative to pharmaceutical applications.
- Others:Reagent grades for laboratory and analytical applications serve educational institutions and quality control laboratories. Niche volume reflects Oman's research infrastructure rather than production economics.
Industrial Grade anchors current supply. Pharmaceutical Grade represents the priority expansion target for margin-focused producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting caustic soda procurement toward jurisdictions with streamlined chemical handling protocols. Oman's alignment with Gulf Cooperation Council technical regulations creates a compliance-cost advantage versus markets with fragmented national standards.
Muscat Governorate
Desalination capacity expansion drives caustic soda procurement for reverse osmosis pre-treatment pH correction. The Ministry of Regional Municipalities and Water Resources mandates standardized neutralization protocols across municipal water operators. Water treatment facilities in the capital corridor are consolidating procurement through certified logistics providers to meet tightened secondary containment requirements.
Sohar Industrial Port Cluster
Bayer process alumina refineries and petrochemical complexes anchor the Sultanate's highest-volume consumption tier for liquid caustic soda. The Ministry of Commerce, Industry and Investment Promotion enforces national industrial safety framework standards for chemical storage infrastructure. Pipeline-connected chlor-alkali facilities pump directly into alumina digestion units, eliminating packaging costs for captive consumers.
Dhofar Governorate
Greenfield chemical park investments near Salalah Port are creating untapped offtake potential for specialty caustic grades. The central government's industrial diversification strategy channels investment toward southern corridor development. Construction contractors source solid caustic forms for concrete admixture applications where transportation economics override liquid handling infrastructure.
Duqm Special Economic Zone
Solar-hydrogen integration projects are enabling carbon-intensity differentiation for export-oriented electrolysis operations. The zone's renewable energy incentives attract producers seeking to decarbonize chlor-alkali output. Industrial planners are positioning membrane cell capacity to serve both domestic demand and re-export markets across the Arabian Peninsula.
Oman Sodium Hydroxide Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated chlor-alkali producers commanding pipeline-connected volumes while distributors capture regulatory-compliance-driven consolidation. The market structure concentrates around Sohar's membrane cell complex for bulk supply, fragmenting into certified logistics intermediaries for smaller water treatment accounts. Three archetypes dominate: captive-integrated petrochemical operators, national chlor-alkali champions with pipeline infrastructure, and global chemical majors leveraging technical service networks. Capacity expansion and long-term offtake contracting represent the dominant competitive moves, with buyers locking in five-year supply agreements bundling maintenance expertise.
Among global chemical majors, BASF SE anchors technical service capabilities for water treatment operators seeking bundled compliance support. EQUATE Petrochemical Company occupies a position exemplifying feedstock integration economics across Kuwait and Oman operations. Oman Chlorine S.A.O.G represents the national champion archetype with pipeline-connected dominance at Sohar Industrial Port.
| Leading Market Players |
|---|
| Al Karam Group |
| BASF SE |
| EQUATE Petrochemical Company |
| Aditya Birla Chemicals |
| Olin Corporation |
| Oman Chlorine S.A.O.G |
| Occidental Petroleum Corporation |
| INEOS Group AG |
| The Dow Chemical Company |
| Others |
Cost & Logistics Intelligence
Alumina refineries and petrochemical complexes at Sohar Industrial Port concentrate procurement volume, anchoring contract-based long-term offtake as the dominant pricing model across Oman's sodium hydroxide market. This buyer concentration compresses spot-market liquidity and transfers pricing power toward membrane cell producers with pipeline-connected infrastructure.
Pricing Analysis
Capacity additions in Sohar are reshaping price floors as zero-gap membrane cell retrofits displace legacy mercury-cell output. Three-tier pricing structure across pharmaceutical, industrial, and technical grades captures differentiation driven by Ministry of Health certification requirements and volume scale. Cost compression in industrial-grade material is intensifying because feedstock integration economics favor captive chlor-alkali consumption. Water treatment operators across Muscat Governorate demonstrate highest price sensitivity due to standardized procurement mandates, while pharmaceutical manufacturers accept premium positioning for certified purity.
Supply Chain Analysis
Regional distribution centers at Sohar Industrial Port and Muscat logistics hubs anchor hub-and-spoke patterns for liquid caustic soda delivery. Supply concentration centers on Oman, with secondary sourcing from Kuwait and Saudi Arabia through Gulf Cooperation Council harmonized shipment protocols. Brine feedstock, natural gas for electrolysis, and specialized membrane cell components constitute critical input dependencies. Single-source vulnerability runs through Sohar's pipeline-connected chlor-alkali complex, which feeds directly into alumina digestion units. Distribution runs through certified logistics providers consolidating compliance documentation for downstream water treatment and chemical manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's sodium hydroxide market represents a late-cycle quality story as pharmaceutical grade certification requirements displace commodity industrial specifications across Muscat's healthcare manufacturing expansion.
For Market Incumbents: Cement pipeline-connected supply relationships through embedded technical service clauses that bundle membrane cell maintenance expertise with volume commitments. Expand backward integration into brine intake infrastructure controlled by coastal desalination utilities to defend against feedstock concentration risk. Priority investment targets automated leak detection and secondary containment upgrades mandated under the national industrial safety framework. For New Entrants and Emerging Players: The price-point gap between pharmaceutical grade premiums and industrial grade commoditization creates entry space for mid-tier certified suppliers. Target Dhofar Governorate's greenfield chemical park investments near Salalah Port, where specialty caustic grades face limited incumbent penetration. Lead with certified logistics partnerships absorbing compliance burdens for water treatment facilities consolidating procurement under tightened handling standards. For Investors and Strategic Acquirers: Regional petrochemical conglomerates seeking feedstock integration represent the most active acquirer in this space. Five-to-ten year viability hinges on membrane cell technology maturation and renewable-powered electrolysis economics at Duqm. Target acquisition archetype: chlor-alkali operators with pipeline infrastructure and captive industrial offtake agreements. Monitor solar-hydrogen project announcements at Duqm Special Economic Zone as inflection indicator for carbon-intensity differentiation strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Cell Capacity Expansion | Zero-gap electrolyzer retrofits at Sohar compress legacy mercury-cell margins and tighten chlorine-hydrogen balancing. |
| Backward Integration into Brine Supply | Seawater intake infrastructure control insulates producers from coastal desalination utility concentration risk. |
| Pharmaceutical Grade Certification Investment | Ministry of Health compliance opens premium positioning as Muscat healthcare manufacturing clusters expand. |
| Long-term Supply Agreement Structuring | Five-year offtake contracts with embedded maintenance clauses displace spot purchasing among alumina refiners. |
| Renewable-Powered Electrolysis Development | Solar-hydrogen integration at Duqm enables carbon-intensity differentiation for export-oriented chlor-alkali output. |
Research Approach
Bottom-up water treatment and alumina refining modeling reconciled against top-down chlor-alkali capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Sohar's membrane cell facilities, procurement leads at downstream petrochemical complexes, distribution channel partners, and technical R&D directors at certified logistics providers combined with secondary validation. Secondary sources include customs and trade data, Gulf Petrochemicals and Chemicals Association reports, SEC 10-K filings from listed chemical majors, and Ministry of Commerce regulatory documentation.
Input-output matrices map electrolysis capacity, brine feedstock availability, and end-use consumption patterns across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use industry, product form, and regional production hub. CAGRs derive from elasticity-adjusted demand projections and supply-side capacity buildout schedules. Forecast inputs incorporate natural gas tariff frameworks under Oman's domestic energy policy and desalination capacity expansion timelines mandated by the Ministry of Regional Municipalities and Water Resources.
Caveats apply where membrane cell technician scarcity, chlorine absorption bottlenecks, or energy cost volatility could materially shift the outlook. Forecasts reflect documented assumptions about technology transition timelines and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Potassium Chlorate Market
Bulk Chemicals
Methyl Methacrylate (MMA) Market
Bulk Chemicals
Sodium Ferrocyanide Market
Bulk Chemicals
Isobutyraldehyde Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
Tallow Market
Bulk Chemicals
Pyridine Market
Bulk Chemicals
China Starch and Starch Derivatives Market
Bulk Chemicals
Global Benzaldehyde Market
Bulk Chemicals
Acetochlor Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Pivaloyl Chloride Market
Bulk Chemicals
Thiodiglycol Market
Bulk Chemicals
Zinc L-Pidolate Market
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market
Bulk Chemicals
Global Capric Acid Market