
 Batch Reactors Market | 2026-2036
Batch Reactors Market Size, Share, and Industry Trends Forecast 2026-2036
Batch Reactors Market Insights
ASME-grade pressure vessel certification is unwinding competitive dynamics across the batch reactors landscape. Pfaudler leverages its glass-lined technology leadership to anchor premium positioning in corrosive process environments. De Dietrich Process Systems sustains European manufacturing scale through specialized alloy fabrication capabilities. Zibo Taiji Glass Lined Equipment dominates cost-competitive supply chains serving Asia-Pacific project developers.
Batch reactors are enclosed vessels designed for discrete chemical processing cycles, typically rated for pressures from full vacuum to 6,000 psi and temperatures spanning cryogenic to 500°C, with agitation systems ensuring homogeneous reaction conditions for pharmaceutical active ingredient synthesis and specialty polymer production. Industrial reactors command the largest installed base due to sustained capital replacement cycles in bulk chemical manufacturing, while laboratory reactors represent the fastest-growing segment as contract research organizations scale automated parallel experimentation platforms. Stainless steel technology retains margin concentration in high-purity pharmaceutical applications where surface finish specifications exceed Ra 0.4 micrometers.
ASME Boiler and Pressure Vessel Code compliance shapes North American market access requirements, while REACH and the EU Pressure Equipment Directive govern European material traceability and hazard classification protocols. India's CEA electrical safety mandates and China's GB 150 pressure vessel standards create divergent certification burdens for multinational suppliers. Stakeholders must monitor evolving hydrogen economy process specifications that will redefine reactor alloy selection criteria and thermal management architectures.
Market Dynamics
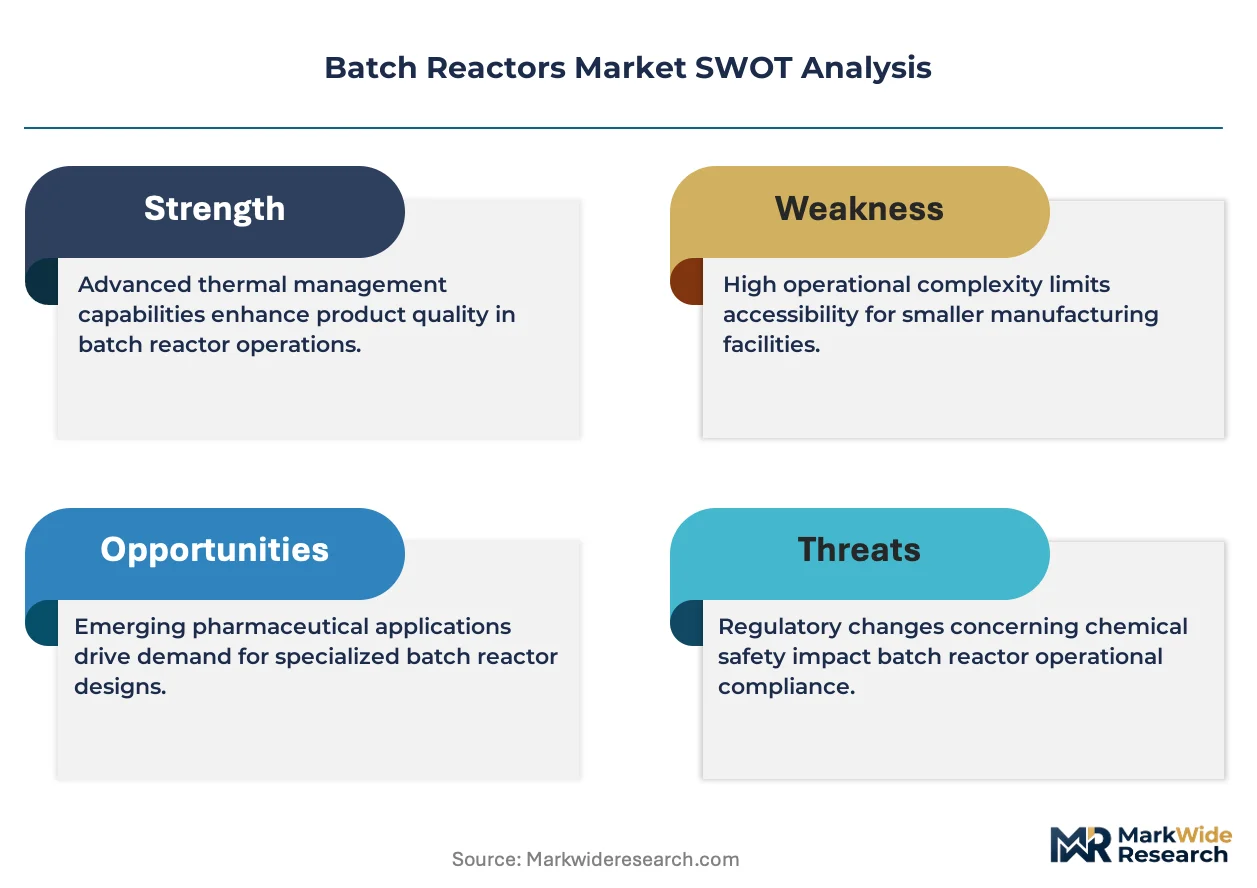
ASME-grade certification requirements are compressing supplier margins while India's PLI scheme for specialty chemicals redirects procurement toward domestic glass-lined equipment fabricators.
Growth Catalysts
- India's PLI Scheme:Domestic production incentives for specialty chemicals manufacturers are accelerating batch reactor procurement from Gujarat-based fabricators.
- Process Safety Standards:Tightening specifications under India's national chemical regulator are forcing equipment upgrades across corrosive process environments.
- Automated Parallel Experimentation:Contract research organizations are scaling laboratory reactor platforms to compress pharmaceutical development timelines.
Market Restraints
- Alloy Cost Volatility:Nickel and molybdenum price swings destabilize fabrication economics for high-performance stainless steel vessels.
- Certification Fragmentation:Divergent ASME, GB 150, and EU Pressure Equipment Directive requirements extend compliance timelines for multinational suppliers.
- Modular Continuous Processing:Plug-flow reactor systems threaten batch reactor share in bulk chemical manufacturing volume applications.
Strategic Opportunities
- Hydrogen Economy Specifications:Evolving process requirements for green hydrogen production will redefine thermal management architectures and alloy selection criteria.
- CEA Electrical Safety Mandates:India's tightening electrical integration standards create retrofit demand for automated control system upgrades.
- Digital Twin Integration:Convergence of process simulation software with physical reactor assets enables predictive maintenance revenue streams.
Industry Challenges
- ASME Inspector Scarcity:Limited certified welding inspectors extend lead times for pressure vessel qualification.
- Legacy Control System Migration:Pharmaceutical manufacturers face integration complexity when retrofitting automated batch control onto existing vessel infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Batch Reactors Market |
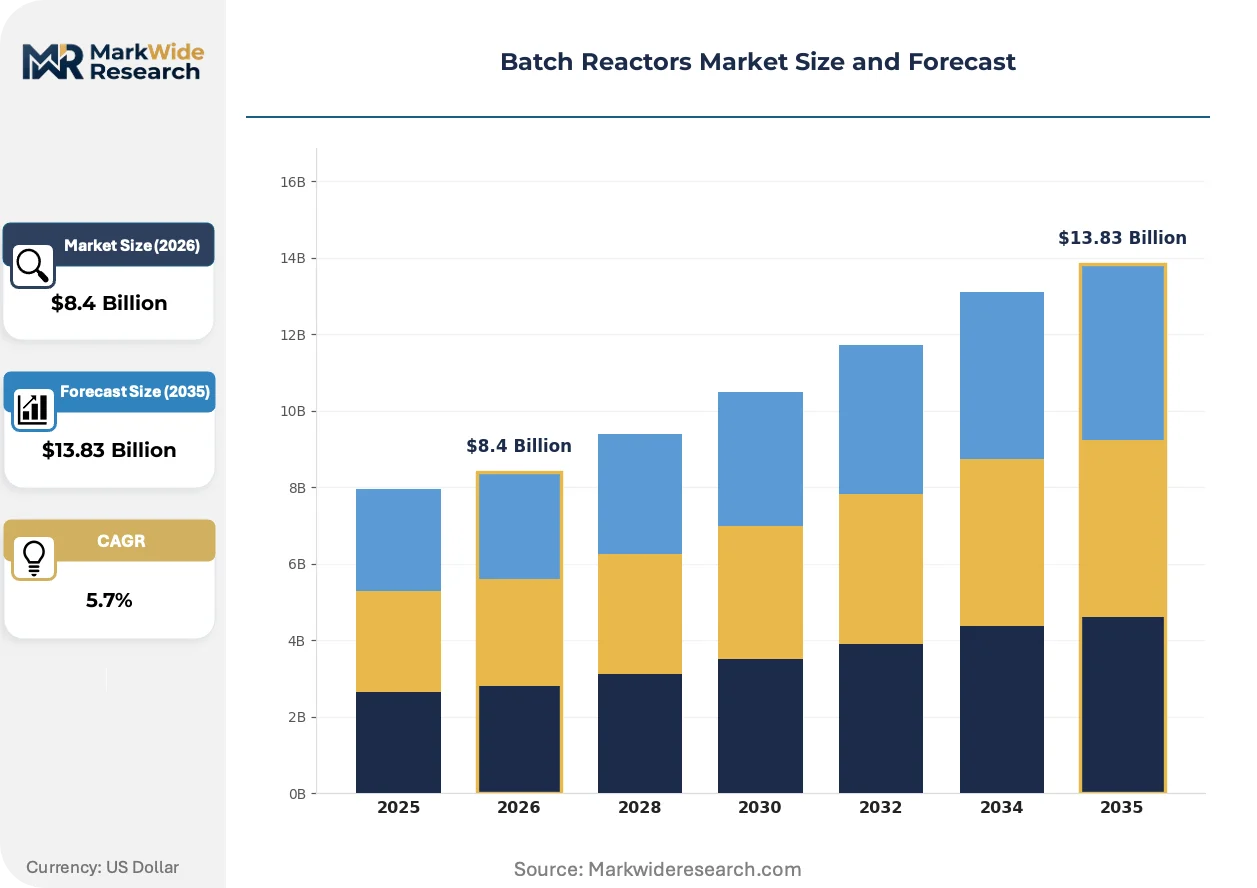
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Reactors, Laboratory Reactors, Industrial Reactors, Specialty Reactors Technology: Glass-Lined, Stainless Steel, Mixers, Heat Exchangers End User: Chemicals, Pharmaceuticals, Food Processing, Environmental Application: Synthesis, Fermentation, Polymerization, Drug Development |
| Companies Covered | Pfaudler, De Dietrich Process Systems, Zibo Taiji Glass Lined Equipment, Dharma Engineering, Sigma Scientific Glass Pvt. Ltd., McGean-Rohco Inc., Bepex International LLC, Buchiglas, Pratik Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Batch Reactors Market Trends and Innovations
Equipment form factors and process intelligence architectures are undergoing simultaneous transformation as pharmaceutical developers demand faster experimentation cycles and chemical manufacturers pursue autonomous batch operations.
Single-use bioreactor technology is miniaturizing upstream pharmaceutical processing. Contract development organizations are adopting disposable vessel systems at pilot-scale to eliminate cross-contamination risk between active pharmaceutical ingredient campaigns. This shift is miniaturizing the addressable market for traditional stainless steel fabrication in clinical-phase production.
REACH substance authorization protocols are tightening material traceability requirements for European chemical manufacturing. Suppliers must now document full alloy provenance and hazard classification across multi-tier supply chains. Specialty polymer producers in Germany and the Netherlands are responding by consolidating procurement with vertically integrated vessel fabricators possessing in-house metallurgical testing capabilities.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-scale specialty chemical producers. Leasing arrangements with embedded maintenance and certification compliance are capturing share in India and Southeast Asia where balance sheet constraints limit upfront capex deployment. This restructuring is most visible among agrochemical formulators seeking operational flexibility during seasonal demand fluctuations.
Batch Reactors Market Segmentation
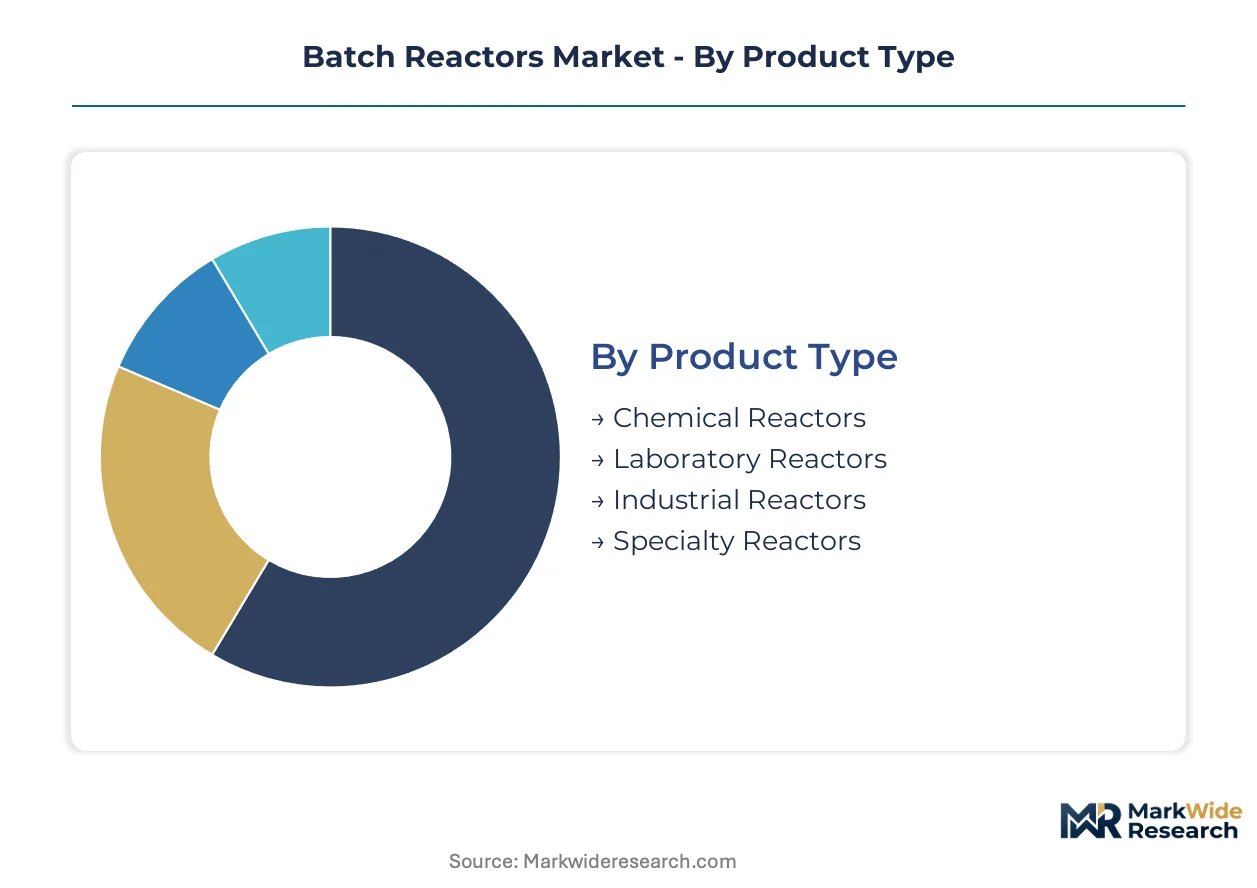
Batch reactor segmentation reflects divergent certification burdens and process safety standards across end-use industries. Equipment specifications vary sharply between pharmaceutical synthesis requiring surface finishes below Ra 0.4 micrometers and bulk chemical processing tolerating coarser tolerances.
Product Type:
ASME Boiler and Pressure Vessel Code compliance creates tiered market access, with industrial-scale vessels facing stricter inspector qualification requirements than laboratory equivalents.
- Industrial Reactors:These vessels handle discrete chemical cycles at pressures reaching 6,000 psi and temperatures to 500°C. Demand concentrates in Gujarat's chemical corridor where India's national chemical regulator is tightening equipment specifications for corrosive process environments. Established volume favors this segment; emerging adoption favors laboratory reactors.
- Laboratory Reactors:Automated parallel experimentation platforms enable contract research organizations to compress pharmaceutical development timelines. Procurement is accelerating from Mumbai and Hyderabad-based CROs scaling high-throughput screening infrastructure. Stainless steel fabrication dominates where surface finish specifications exceed pharmaceutical purity thresholds.
- Chemical Reactors:Standard vessels serve commodity chemical manufacturing with full vacuum to moderate pressure ratings.
- Specialty Reactors:Custom configurations address proprietary process chemistries in agrochemical and fine chemical production.
Capital replacement cycles sustain industrial reactor volumes; laboratory automation drives steepest expansion trajectory.
Technology:
Material selection hinges on corrosion resistance requirements and alloy cost volatility, with nickel and molybdenum price swings destabilizing fabrication economics.
- Glass-Lined:Acid-resistant enamel coatings protect against aggressive chemistries in pharmaceutical active ingredient synthesis. Procurement concentrates among specialty chemicals manufacturers in Gujarat responding to India's PLI scheme production incentives. Cost-competitive supply chains from Zibo serve Asia-Pacific project developers with shorter lead times than European fabricators.
- Stainless Steel:High-purity surface finishes below Ra 0.4 micrometers command margin concentration in injectable drug manufacturing. Demand clusters around parenteral formulation facilities in Germany and the Netherlands where REACH substance authorization protocols tighten material traceability.
- Mixers:Agitation systems ensure homogeneous reaction conditions across viscosity ranges from aqueous solutions to high-solids polymer slurries.
- Heat Exchangers:Thermal management architectures integrate with reactor vessels for exothermic process control and temperature-sensitive synthesis.
Glass-lined technology anchors corrosive process applications; stainless steel dominates high-purity pharmaceutical specifications.
End User:
Customer procurement patterns diverge between capital-constrained mid-scale producers and balance-sheet-flexible multinational manufacturers.
- Chemicals:Specialty and bulk chemical manufacturers drive sustained replacement demand for pressure-rated vessels. Equipment-as-a-service contracting is displacing traditional capital purchases among Indian and Southeast Asian agrochemical formulators seeking operational flexibility during seasonal demand fluctuations.
- Pharmaceuticals:Active ingredient synthesis and drug product manufacturing require validated cleaning protocols and automated batch control systems. Single-use bioreactor technology is miniaturizing the addressable market for traditional stainless steel at clinical-phase production scales.
- Food Processing:Sanitary design specifications govern vessel construction for fermentation and enzyme catalysis applications.
- Environmental:Wastewater treatment and remediation processes utilize batch configurations for controlled oxidation and precipitation reactions.
Chemical sector procurement sustains equipment volumes; pharmaceutical automation commands premium pricing tiers.
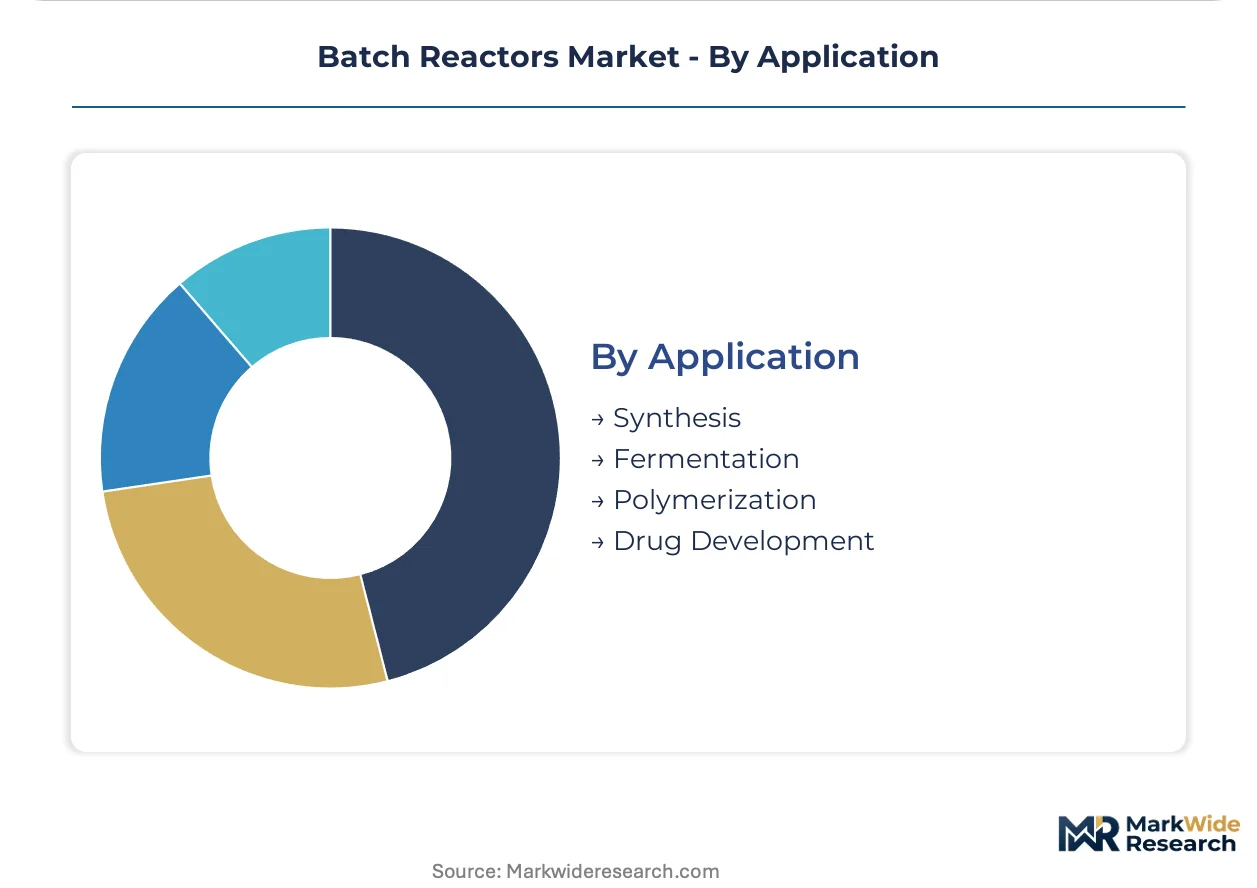
Application:
Process intensity and batch cycle duration determine thermal management requirements and agitation system specifications.
- Synthesis:Multi-step organic reactions demand precise temperature control and inert atmosphere capabilities for moisture-sensitive intermediates. Contract development organizations in Hyderabad and Bangalore are scaling automated platforms to accelerate route scouting for complex molecules.
- Polymerization:Exothermic chain-growth reactions require heat removal systems capable of managing viscous, high-solids slurries. Specialty polymer producers in Germany are consolidating procurement with vertically integrated fabricators possessing in-house metallurgical testing capabilities under REACH protocols.
- Fermentation:Bioprocess applications integrate sterile design with automated pH and dissolved oxygen control for cell culture and microbial production.
- Drug Development:Pilot-scale campaigns bridge laboratory chemistry to commercial manufacturing with flexible equipment configurations supporting rapid product changeover.
Synthesis applications dominate installed capacity; drug development automation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass-lined equipment fabrication clusters in Germany, China, and India, with each concentration serving distinct certification regimes and end-use specifications. Regulatory divergence across ASME, GB 150, and India's CEA mandates creates localized supply advantages.
United States
Pharmaceutical active ingredient manufacturers in New Jersey and Massachusetts drive demand for ASME-certified stainless steel vessels with surface finishes below Ra 0.4 micrometers. FDA validation requirements for injectable drug manufacturing tighten equipment qualification protocols. The Delaware Valley chemical corridor sustains replacement cycles for pressure-rated vessels in specialty polymer production.
Germany
Specialty polymer producers in North Rhine-Westphalia consolidate procurement with fabricators possessing in-house metallurgical testing capabilities. REACH substance authorization protocols mandate full alloy provenance documentation across multi-tier supply chains. The Leverkusen-Düsseldorf industrial cluster anchors European demand for high-purity pharmaceutical reactor systems.
China
Cost-competitive glass-lined equipment from Shandong Province serves Asia-Pacific project developers with shorter lead times than European alternatives. GB 150 pressure vessel standards create divergent certification burdens for multinational suppliers seeking market access. The Yangtze River Delta chemical corridor scales automated batch control integration for agrochemical formulation.
India
Specialty chemicals manufacturers in Gujarat accelerate batch reactor procurement under the PLI scheme's domestic production incentives. CEA electrical safety mandates and tightening process standards under the national chemical regulator force equipment upgrades across corrosive process environments. The Ankleshwar-Vapi industrial belt concentrates glass-lined reactor demand from agrochemical and fine chemical producers.
Japan
Contract research organizations in the Kanto region scale automated parallel experimentation platforms to compress pharmaceutical development timelines. METI industrial standards govern thermal management architectures for temperature-sensitive synthesis. The Osaka-Kobe manufacturing corridor sustains demand for precision alloy fabrication in electronic materials processing.
Batch Reactors Market Competitive Landscape
Concentration sits with heritage European fabricators and cost-optimized Asian manufacturers, creating a bifurcated structure around certification grade and lead time performance. The market stratifies across three tiers: ASME-certified premium specialists serving pharmaceutical validation requirements, mid-scale regional fabricators capturing PLI-driven Indian procurement, and volume-oriented Chinese suppliers dominating Asia-Pacific project economics. Strategic moves center on backward integration into alloy supply and geographic licensing arrangements to bypass certification fragmentation.
Among heritage European specialists, Pfaudler and De Dietrich Process Systems exemplify the premium-tier archetype anchored in corrosive process technology leadership. Zibo Taiji Glass Lined Equipment occupies a position within the cost-optimized tier serving Asia-Pacific developers with compressed delivery schedules. These three fabricators represent divergent competitive vectors: certification-intensive pharmaceutical positioning versus scale-driven project supply.
| Leading Market Players |
|---|
| Pfaudler |
| De Dietrich Process Systems |
| Zibo Taiji Glass Lined Equipment |
| Dharma Engineering |
| Sigma Scientific Glass Pvt. Ltd. |
| McGean-Rohco Inc. |
| Bepex International LLC |
| Buchiglas |
| Pratik Engineering |
| Others |
Pricing and Supply Chain Analysis
ASME Boiler and Pressure Vessel Code compliance gates both supplier qualification and price differentiation simultaneously, compressing margins for uncertified fabricators while concentrating premium pricing power among accredited specialists serving pharmaceutical validation requirements.
Pricing Analysis
ASME Boiler and Pressure Vessel Code dictates the pricing tier structure across three distinct certification grades. Premium-mid-economy pricing differentiation separates ASME-certified pharmaceutical specialists from regional fabricators serving commodity chemical applications, with surface finish specifications below Ra 0.4 micrometers commanding substantial brand premiums. Cost compression in standard-grade industrial vessels is intensifying because nickel and molybdenum price volatility destabilizes alloy-intensive fabrication economics. Mid-scale specialty chemical producers in India exhibit highest price sensitivity due to balance sheet constraints, while injectable drug manufacturers in Germany demonstrate lowest sensitivity given FDA validation imperatives.
Supply Chain Analysis
ASME inspector scarcity creates a chokepoint that extends lead times for pressure vessel qualification and concentrates fabrication capacity among heritage European specialists. Manufacturing gravity centers on Germany, China, and India, with each hub serving distinct certification regimes and end-use specifications. Raw material supply draws from specialty steel mills in Europe, nickel alloy producers in Asia, and glass enamel formulators in Shandong Province. Single-source vulnerability sits with certified welding inspector pools, where limited qualification throughput constrains capacity expansion. Distribution runs through direct OEM relationships for pharmaceutical applications and equipment-as-a-service leasing arrangements for capital-constrained chemical producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification regimes and divergent national process safety standards creates niche entry points for specialized fabricators. Contract research organizations scaling automated experimentation platforms represent the most dynamic demand-side shift, fragmenting procurement patterns between laboratory and industrial scale.
For Market Incumbents: Secure ASME inspector training pipelines to defend qualification capacity against lead time extension. Capture backward integration into specialty alloy supply to buffer nickel and molybdenum price volatility threatening fabrication margins. Anchor pharmaceutical positioning through surface finish capabilities exceeding Ra 0.4 micrometers as single-use bioreactor substitution threatens clinical-phase stainless steel demand.
For New Entrants and Emerging Players: Lead with digital twin integration capabilities targeting mid-scale Indian chemical producers under CEA electrical safety mandates. Target Gujarat's specialty chemicals corridor where PLI scheme incentives accelerate domestic procurement from cost-competitive fabricators. Pursue equipment-as-a-service contracting models that bypass balance sheet constraints among agrochemical formulators facing seasonal demand fluctuations.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized process equipment divisions possessing captive metallurgical testing capabilities. Long-term viability hinges on hydrogen economy specification readiness as thermal management architectures undergo fundamental redesign. Watch for green hydrogen project announcements as the critical inflection signal for alloy selection criteria shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive nickel and molybdenum sourcing buffers Pfaudler and De Dietrich against raw material price volatility. |
| ASME Certification Expansion | Additional accredited welding inspectors compress lead times for pharmaceutical vessel qualification in New Jersey. |
| Digital Twin Platform Launch | Convergence with process simulation software enables predictive maintenance revenue from Mumbai-based CROs. |
| Joint Venture in Gujarat Corridor | Local fabrication partnerships capture PLI-driven procurement from Ankleshwar-Vapi agrochemical producers. |
| Hydrogen-Ready Alloy Development | High-pressure thermal management architectures position fabricators for green hydrogen project specifications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, procurement leads at downstream chemical manufacturers, aftermarket service heads, and regulatory compliance officers; and secondary validation through customs and trade data, SEC filings from listed equipment fabricators, ASME certification registries, and national chemical production statistics. Bottom-up vessel shipment data triangulated against top-down specialty chemicals and pharmaceutical capital expenditure disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning vessel scale tier, material technology type, surface finish specification grade, end-use industry vertical, and regional regulatory cluster. CAGRs derived from regression analysis against historical capital replacement cycles and announced capacity expansion timelines. Forecast inputs incorporated PLI scheme disbursement schedules, REACH substance authorization phase-in timelines, and hydrogen economy infrastructure deployment announcements.
Forecasts assume regulatory continuity in ASME, REACH, and India's CEA regimes; material policy shifts would require re-modeling certification burden trajectories and equipment upgrade cycles. Practitioners should keep alternative scenarios live as hydrogen economy process specifications and single-use bioreactor substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Aerosol Refrigerants Market
Industrial Chemicals
Europe Biocides Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Global Industrial Oils Market
Industrial Chemicals
Naphthenic Acid Market
Industrial Chemicals
Global Neopentyl Glycol Market
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
Global Silicone Fluid Market
Industrial Chemicals
Hazardous Chemicals Packaging Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Non-PVC Waterstop Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Draft Tube Baffle (DTB) Crystallizers Market
Industrial Chemicals
India Precipitated Silica Market