
 Europe Surface Treatment Chemicals Market | 2026-2036
Europe Surface Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Surface Treatment Chemicals Market Foresight
Maintenance contracts for chemical bath monitoring and replenishment is rebalancing how surface treatment value gets captured across Europe. Henkel AG & Company KGaA leverages its adhesive heritage to bundle pretreatment chemistry with process control services. Socomore anchors French aerospace demand through specialized chromate-free conversion coatings for Airbus-tier suppliers. Chemetall dominates automotive pretreatment lines through OEM-qualified phosphate systems.
Europe surface treatment chemicals encompass formulated blends of phosphates, chromates, organic polymers, and nitrocarbon compounds designed to modify metal substrates for corrosion resistance, paint adhesion, or electrical insulation, typically applied via immersion spray or electrolytic processes at controlled pH and temperature parameters. These formulations serve primarily to extend component lifespan in harsh operating environments while enabling subsequent manufacturing steps. Organic coatings and phosphate systems lead product-type revenue due to their entrenched role in automotive body-in-white lines, while chemical conversion technology commands expanding share as REACH-driven hexavalent chromium substitution accelerates specification changes. Aerospace application demand concentrates in premium anodizing grades, whereas metal fabrication channels absorb volume-driven powder coating pretreatments.
EU REACH restrictions on hexavalent chromium and ECHA authorization requirements are forcing reformulation investments across chromate-dependent product lines, while CE marking and MDR standards extend compliance burdens to medical device metal finishing. Germany's KBA and France's ANSM enforce sector-specific chemical safety protocols that fragment product registration requirements. Buyers must track pending F-Gas Regulation amendments and evolving CSRD disclosure rules to anticipate supply chain qualification costs.
Market Dynamics
EU REACH restrictions on hexavalent chromium are forcing immediate reformulation across chromate-dependent product lines, while maintenance contracts for chemical bath monitoring are rebalancing how surface treatment value gets captured across the region.
Growth Catalysts
- REACH-driven substitution mandates:ECHA authorization requirements accelerate specification changes toward chromate-free conversion coatings in aerospace and automotive pretreatment lines.
- Powder coating technology migration:Metal fabricators redirect procurement budgets toward phosphate and anodizing systems that eliminate hazardous primers.
- Automotive OEM expansion:Germany and France anchor demand as phosphate coating lines scale to meet stricter corrosion resistance standards.
Market Restraints
- Raw material volatility:Phosphate rock and specialty polymer feedstock costs fluctuate with energy pricing, squeezing formulation margins.
- Supply concentration risk:Pretreatment chemical production clusters in Germany's industrial corridor, creating single-point vulnerability for pan-European buyers.
- Technical substitution limits:Hexavalent chromium retains performance advantages in certain aerospace anodizing grades where chromate-free alternatives fail qualification.
Strategic Opportunities
- Spanish and Italian metal fabrication:Underpenetrated pretreatment service markets in Southern Europe offer expansion paths for process control bundling.
- CSRD disclosure alignment:Chemical suppliers can capture premium positioning by embedding carbon footprint tracking into maintenance contracts.
- Digital bath monitoring convergence:IoT sensor integration with automated replenishment systems creates new recurring revenue streams.
Industry Challenges
- Formulation chemist scarcity:REACH-compliant chromate substitution requires rare expertise in phosphate-organic hybrid chemistry.
- OEM qualification timelines:Airbus-tier and automotive body-in-white approvals demand 18-36 month validation cycles.
- Legacy line retrofit costs:Immersion tank conversion for new chemistries requires substantial capital outlay at fabricator facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Surface Treatment Chemicals Market |
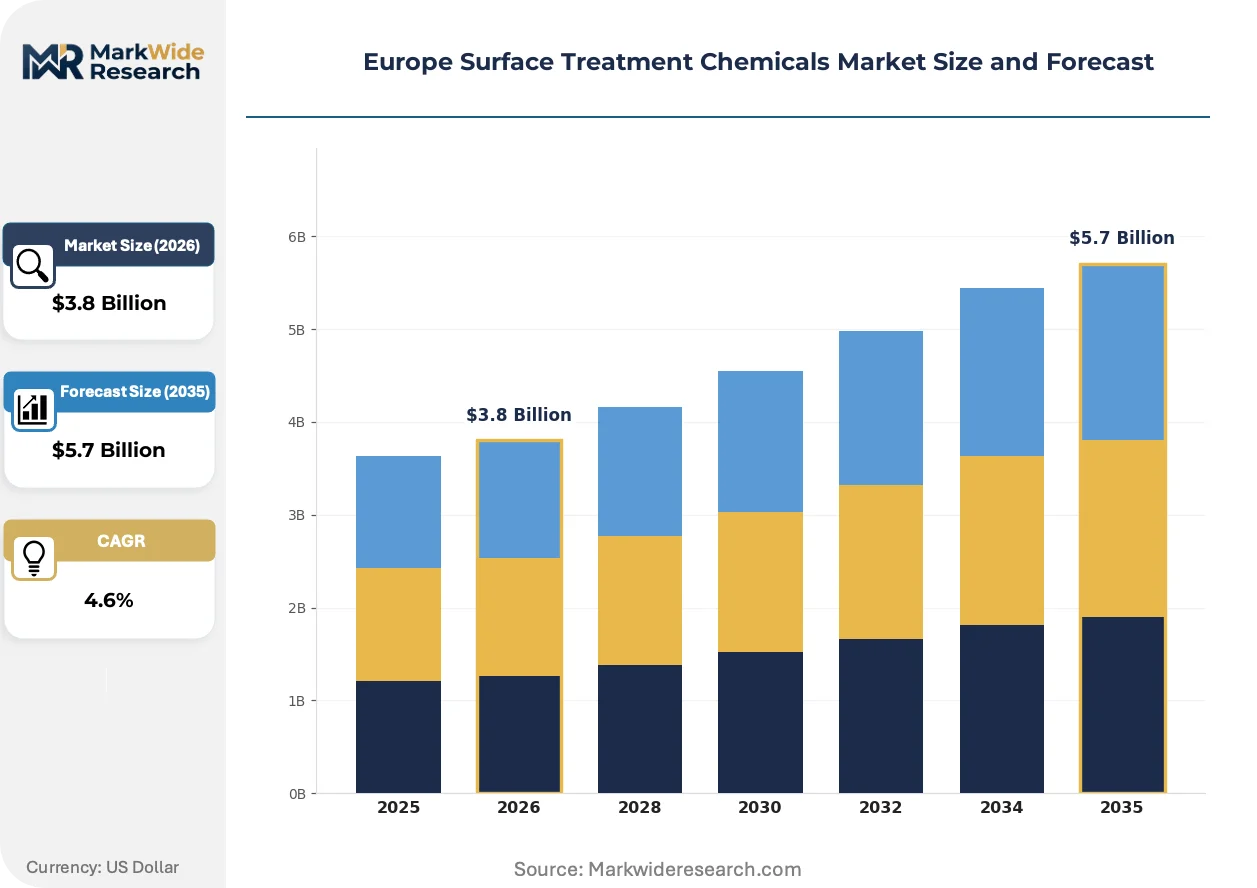
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphates, Chromates, Nitrocarbons, Organic Coatings Application: Aerospace, Automotive, Electronics, Metal Fabrication End User: Manufacturers, Distributors, Contractors, OEMs Technology: Electroplating, Anodizing, Powder Coating, Chemical Conversion |
| Companies Covered | Socomore, Nihon Parkerizing Co Ltd, Henkel AG & Company KGaA, Fokker Technik, Quaker Chemical Corporation, Chemetall, Oerlikon Group, The Surface Company, Solvay SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Surface Treatment Chemicals Market Shifts & Advancements
Surface treatment chemistry is pivoting from commodity formulation supply toward integrated process service models, with digital monitoring and regulatory compliance bundling now defining competitive differentiation.
Chromate-free conversion coatings are expanding into aerospace tier-one supply chains as Airbus mandates REACH-compliant alternatives across its European supplier base. Anodizing shops in Toulouse and Hamburg accelerate adoption despite higher unit chemistry costs. The technology is expanding into premium market segments previously locked by performance specifications.
ECHA's evolving authorization list for hexavalent chromium compounds forces continuous reformulation investment across pretreatment portfolios. Automotive OEMs face 2024-2025 sunset dates for legacy chromate systems in multiple coating applications. French aerospace suppliers and German automotive pretreatment lines absorb the heaviest compliance burdens.
Service contract unbundling now separates chemical supply from bath analysis and replenishment scheduling. Tier-one automotive buyers in Stuttgart and Wolfsburg prefer fixed-cost-per-part arrangements over traditional volume purchasing. This shift concentrates most visibly in Germany's automotive corridor where process control expertise commands pricing power.
Europe Surface Treatment Chemicals Market Segmentation
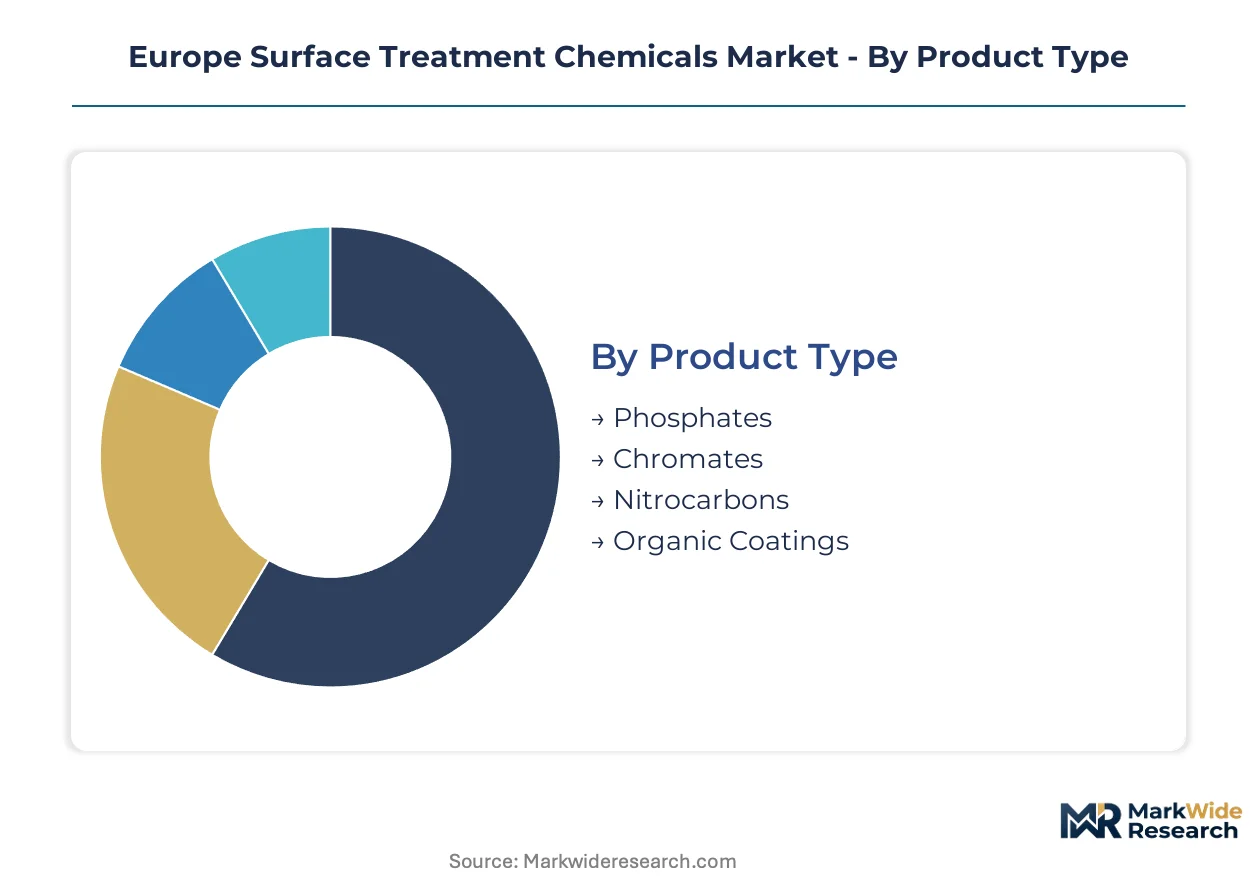
Segmentation in Europe surface treatment chemicals reveals how supply-side concentration and regulatory fragmentation create divergent growth trajectories across product lines and customer channels. Understanding these divisions exposes where procurement budgets are shifting and which technologies are capturing maintenance contract value.
Product Type:
Supply concentration in phosphate and chromate production clusters around Germany's industrial corridor, with formulation expertise concentrating in legacy chemical manufacturing hubs.
- Phosphates:Zinc and iron phosphate formulations dominate automotive body-in-white pretreatment lines through immersion and spray application. Demand concentrates in Stuttgart and Wolfsburg automotive clusters where OEM-qualified systems command premium positioning. REACH-driven hexavalent chromium substitution accelerates phosphate specification in corrosion-resistant coating sequences.
- Chromates:Hexavalent and trivalent chromate conversion coatings retain entrenched positions in aerospace anodizing despite ECHA authorization pressures. Toulouse and Hamburg aerospace suppliers absorb the heaviest compliance burdens as Airbus mandates REACH-compliant alternatives across tier-one supply chains.
- Nitrocarbons:Salt bath nitrocarburizing compounds serve wear-resistant applications in metal fabrication channels.
- Organic Coatings:Polymer-based sealants and primers integrate with phosphate systems for paint adhesion enhancement.
Today's leader: Phosphates. Tomorrow's challenger: Chromates as reformulation investments accelerate.
Application:
End-use demand fragments across corrosion resistance specifications, with aerospace and automotive absorbing premium chemistry while metal fabrication drives volume.
- Aerospace:Premium anodizing grades and chromate-free conversion coatings serve Airbus-tier suppliers in Toulouse and Hamburg. ECHA sunset dates for hexavalent chromium force continuous reformulation investment despite technical substitution limits in certain qualification-critical applications.
- Automotive:Phosphate coating lines scale across Germany and France to meet stricter corrosion resistance standards. OEM expansion in Frankfurt and Hamburg industrial corridors redirects procurement budgets toward chemical conversion processes that eliminate hazardous primers.
- Electronics:Precision cleaning and conversion coatings serve printed circuit board and connector manufacturing.
- Metal Fabrication:Powder coating pretreatments absorb volume-driven demand in underpenetrated Southern European service markets.
Aerospace commands premium pricing. Metal fabrication offers the steepest expansion trajectory through Southern European penetration.
End User:
Customer type determines contract structure, with OEMs and manufacturers shifting from volume purchasing toward fixed-cost-per-part arrangements.
- Manufacturers:In-house surface treatment operations in metal fabrication and automotive component production absorb phosphate and anodizing chemistry through direct procurement. Process control expertise commands pricing power as maintenance contracts unbundle chemical supply from bath analysis.
- OEMs:Automotive and aerospace original equipment manufacturers in Stuttgart and Wolfsburg prefer integrated service bundling. Fixed-cost-per-part arrangements concentrate value capture with suppliers offering digital monitoring and regulatory compliance alignment.
- Distributors:Regional chemical distributors serve fragmented metal fabricator demand across Southern Europe.
- Contractors:Job shop pretreatment service providers absorb volume in Spanish and Italian expansion markets.
OEMs set contract terms. Manufacturers represent the fastest-growing channel as in-house process control investments accelerate.
Technology:
Process technology selection determines chemistry specification, with powder coating migration and anodizing premiumization redirecting formulation demand.
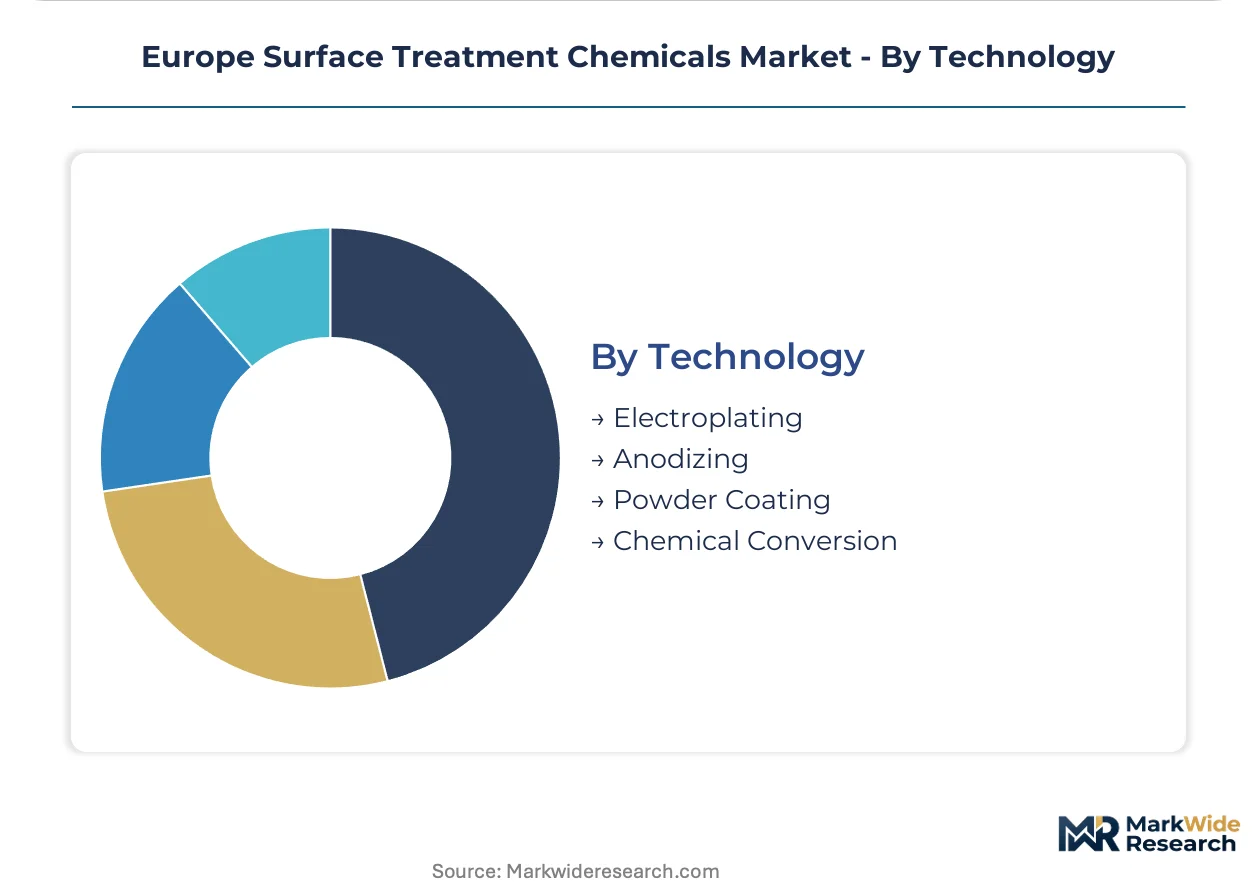
- Chemical Conversion:Chromate-free and phosphate conversion coatings displace hazardous primers as REACH mandates accelerate. ECHA authorization requirements force specification changes in aerospace and automotive pretreatment lines, with reformulation investments heaviest in French aerospace and German automotive channels.
- Anodizing:Sulfuric and chromic acid anodizing serves electrical insulation and corrosion resistance in premium aerospace applications. Hamburg and Toulouse shops accelerate chromate-free adoption despite higher unit chemistry costs.
- Electroplating:Zinc, nickel, and chromium deposition processes retain entrenched positions in functional coating applications.
- Powder Coating:Thermoset powder pretreatment chemistry expands as metal fabricators eliminate solvent-based primer systems.
Chemical conversion leads specification change. Powder coating gains share fastest through Southern European metal fabrication adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs heavier pretreatment chemical volumes than France, though French aerospace demand commands steeper per-unit pricing for chromate-free conversion coatings. Industrial clustering around automotive and aerospace manufacturing corridors concentrates procurement budgets in specific metropolitan zones.
Germany
Automotive OEMs in Stuttgart and Wolfsburg scale phosphate coating lines to meet stricter corrosion resistance standards. KBA enforces sector-specific chemical safety protocols that fragment product registration requirements across pretreatment portfolios. Frankfurt and Hamburg industrial corridors anchor demand as aerospace suppliers and metal fabricators cluster around qualified process control service providers.
France
Airbus-tier suppliers in Toulouse accelerate adoption of REACH-compliant chromate-free alternatives despite higher unit chemistry costs. ANSM monitors medical device metal finishing compliance under extended CE marking and MDR standards. The Toulouse aerospace cluster absorbs the heaviest ECHA-driven reformulation investment as sunset dates for hexavalent chromium approach.
Italy
Metal fabrication channels in Northern Italy drive volume-driven powder coating pretreatment demand. ECHA authorization requirements force specification changes in automotive component finishing. Milan-Turin industrial zones represent underpenetrated service markets for process control bundling expansion.
Spain
Job shop pretreatment service providers absorb volume in underpenetrated Southern European expansion markets. EU F-Gas Regulation amendments pressure refrigerant-dependent coating line operators to anticipate supply chain qualification costs. Barcelona and Valencia metal fabricators redirect procurement budgets toward phosphate systems that eliminate hazardous primers.
United Kingdom
Aerospace precision finishing in Midlands manufacturing zones sustains demand for premium anodizing grades. ECHA REACH restrictions on hexavalent chromium force immediate reformulation across chromate-dependent product lines imported from continental suppliers. Birmingham aerospace subcontractors face compressed qualification timelines for alternative conversion coatings.
Europe Surface Treatment Chemicals Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise concentrating in legacy chemical manufacturing hubs while service bundling captures value downstream. The market exhibits moderate consolidation around qualified phosphate and chromate-free conversion coating systems. Three archetypes dominate: integrated process service providers, specialty chemical formulators, and diversified materials conglomerates. Capacity expansion and strategic partnerships represent the dominant competitive moves as players position for REACH-driven specification changes.
Within the integrated process service tier, Henkel AG & Company KGaA and Chemetall exemplify suppliers bundling pretreatment chemistry with bath monitoring and replenishment scheduling. Socomore occupies a specialist position serving French aerospace demand through chromate-free conversion coating expertise. These three companies anchor the competitive structure as maintenance contracts unbundle chemical supply from process control services.
| Leading Market Players |
|---|
| Socomore |
| Nihon Parkerizing Co Ltd |
| Henkel AG & Company KGaA |
| Fokker Technik |
| Quaker Chemical Corporation |
| Chemetall |
| Oerlikon Group |
| The Surface Company |
| Solvay SA |
| Others |
Supply & Pricing Matrix
EU REACH sunset dates for hexavalent chromium gate qualified supply access and premium-tier pricing power across European pretreatment chemical markets. Formulators demonstrating ECHA-compliant chromate-free conversion coating qualifications capture pricing premiums from Airbus-tier and automotive OEM buyers, while uncertified suppliers face exclusion from specification-critical procurement channels.
Pricing Analysis
Capacity additions in Germany's industrial corridor are reshaping price floors for phosphate and organic coating formulations as Chemetall and Henkel scale OEM-qualified production. Three-tier pricing structure across REACH-certified premium, standard industrial, and economy-grade tiers reflects certification investment recovery and technical qualification depth. Price differentiation hinges on ECHA authorization status and automotive OEM body-in-white approval tier. Cost compression in economy-grade powder coating pretreatments is intensifying because Spanish and Italian metal fabricators prioritize per-unit chemistry costs over process control bundling. Job shop contractors in Southern Europe exhibit highest price sensitivity, while Stuttgart and Wolfsburg automotive OEMs absorb premium positioning for fixed-cost-per-part service contracts.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Airbus-tier suppliers and German automotive clusters, while regional distributors serve fragmented metal fabricator procurement across Southern Europe. Supply concentration rests in Germany, France, and Belgium where legacy chemical manufacturing infrastructure anchors phosphate and chromate-free conversion coating production. Raw material feeds draw from phosphate rock deposits, specialty polymer feedstocks, and nitrocarbon salt bath compounds. Single-source vulnerability concentrates around German industrial corridor production clusters, where qualified formulation expertise limits rapid supply substitution. Distribution runs through Chemetall and Henkel direct sales organizations for tier-one automotive and aerospace accounts, with regional chemical distributors penetrating Italian and Spanish job shop markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European surface treatment chemicals offer margin expansion through REACH-driven premium-tier substitution and process control service bundling that captures recurring revenue from bath monitoring contracts.
For Market Incumbents: Anchor market position through backward integration into phosphate rock processing and chromate-free conversion coating R&D to defend against specialty chemical entrants exploiting formulation expertise gaps. Deepen vertical integration by acquiring IoT sensor technology for digital bath monitoring platforms, creating captive demand for integrated service contracts. ECHA authorization timeline compression threatens incumbents lacking qualified alternative portfolios. For New Entrants and Emerging Players: The mid-tier price gap between premium REACH-certified systems and economy-grade powder coating pretreatments creates entry space for hybrid phosphate-organic formulations targeting Italian and Spanish metal fabrication job shops. Focus white-space capture on underpenetrated Southern European service markets where process control bundling remains nascent. Pursue contractor channel partnerships rather than direct OEM qualification to bypass 18-36 month automotive body-in-white validation cycles. For Investors and Strategic Acquirers: Roll-up economics work for regional pretreatment service providers because ECHA compliance costs are forcing consolidation among sub-scale formulators lacking reformulation investment capacity. Target acquisition archetypes include Italian and Spanish job shop networks with established automotive tier-two relationships and unbundled chemical supply contracts. Watch for inflection when Airbus mandates chromate-free conversion coatings across Hamburg supply chains, accelerating specification change velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Feedstocks | Captive supply of phosphate rock reduces raw material volatility exposure for German formulators. |
| Chromate-Free Conversion Coating R&D Scale-Up | ECHA authorization timelines force accelerated qualification investment for aerospace pretreatment lines. |
| Digital Bath Monitoring Platform Deployment | IoT sensor integration creates recurring revenue streams from Stuttgart and Wolfsburg automotive OEMs. |
| Southern European Service Network Expansion | Underpenetrated Italian and Spanish job shop markets offer process control bundling growth vectors. |
| REACH Compliance Certification Investment | ECHA-qualified status gates premium-tier pricing access from Airbus-tier suppliers in Toulouse. |
Research Methodology
Multiple input streams — executive interviews with pretreatment chemical plant managers, procurement leads at German automotive OEMs, technical R&D directors at aerospace suppliers, and distribution channel partners across Southern Europe — were reconciled against customs and trade data, Cefic industry reports, SEC 10-K filings, and ECHA authorization databases. Bottom-up volume modeling across phosphate, chromate, nitrocarbon, and organic coating product lines was triangulated with top-down market sizing derived from automotive production forecasts and aerospace build rates.
Data-stream reconciliation applied analytical frameworks across product type, application end-use, technology process, and regional production hub segmentation dimensions throughout the forecast period. CAGRs were derived from weighted average growth contributions across these segments, incorporating ECHA regulatory phase-out schedules, automotive corrosion resistance specification evolution, and powder coating technology migration rates as industry-specific forecast inputs.
Caveats apply where ECHA authorization timeline delays, raw material energy cost spikes, or automotive OEM qualification cycle extensions could materially shift the outlook. Forecasts reflect base-case assumptions regarding REACH compliance enforcement consistency and chromate-free conversion coating technical substitution feasibility. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market
Industrial Chemicals
Organophosphate Insecticides Market
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
Northern Europe Calcium Sulphate Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Lime Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
Global Desalting and Buffer Exchange Market
Industrial Chemicals
Global Electronic Grade Sulfuric Acid Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Foam Market
Industrial Chemicals
Ethyl Acrylate Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Carbon Molecular Sieves Market