
 Global Baghouse Filters Market | 2026-2036
Global Baghouse Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Baghouse Filters Market Analysis
Modular filter-bag and cage bundling is hardening as the dominant procurement pattern, forcing suppliers to bundle installation services with media replacement contracts. Donaldson Company leverages its vertical integration into pleated media manufacturing to lock in OEM channel control. Camfil AB anchors its position through R&D intensity in high-temperature aramid blends for cement kilns. CECO Environmental Corp. competes by specializing in turnkey retrofit systems for aging coal-fired power infrastructure.
Baghouse filters are enclosed dust-collection systems using fabric filter bags supported by metal cages to capture particulate matter from industrial gas streams, operating across temperature ranges from ambient to 260°C depending on media selection. Pulse jet filters dominate installed capacity due to their continuous-cleaning capability and compatibility with high dust-loading environments, while reverse air configurations retain share in large-flow cement and power applications where low pressure-drop operation preserves energy efficiency. Fiberglass and Nomex materials command premium positioning in thermal-intensive segments, whereas polyester occupies cost-sensitive standard-duty roles across food and metal processing.
EPA Maximum Achievable Control Technology standards and China's MEE emission limits are tightening particulate thresholds, directly expanding replacement demand for high-efficiency filter media. REACH compliance in Europe and India's CEA stack-emission notifications are converging on comparable PM limits, compressing the effective product-design window for suppliers. Stakeholders must monitor regulatory divergence between developed and emerging economies to calibrate regional product portfolios and certification investments.
Market Dynamics
Modular filter-bag and cage bundling hardens procurement patterns across cement and power sectors, forcing suppliers to integrate installation services with multi-year media replacement contracts or lose channel access entirely.
Growth Catalysts
- EPA Maximum Achievable Control Technology standards:Tightening PM thresholds in US coal-fired power and cement force accelerated filter media replacement cycles. Plants retrofit aging pulse-jet systems with high-efficiency PTFE membranes to maintain compliance.
- China MEE emission limits:Provincial enforcement of stack-emission rules drives cement kiln upgrades. Domestic producers expand baghouse capacity to capture dust from clinker cooling and grinding operations.
- PTFE membrane nanofiber composites:Extended filter lifecycles reduce total cost of ownership for thermal-intensive applications. Cement manufacturers in India and the United States adopt these materials for high-temperature kiln exhaust streams.
Market Restraints
- Aramid fiber supply concentration:Dependence on limited specialty chemical producers for high-temperature filter media creates input cost volatility. Cement and steel sectors face margin compression when aramid prices spike.
- Reverse air system technical limitations:Large-flow configurations require substantial footprint and cannot match pulse-jet cleaning efficiency. Power utilities hesitate to retrofit existing reverse air installations despite energy advantages.
- REACH compliance friction:European chemical registration requirements delay new filter media introductions. Suppliers must reformulate coatings and binders to meet substance restriction timelines.
Strategic Opportunities
- India CEA stack-emission notifications:Tightening PM limits for thermal power plants create retrofit demand for high-efficiency baghouse systems. Domestic cement capacity additions compound filter procurement volumes.
- Predictive maintenance convergence with IoT sensors:Pressure-drop monitoring and bag-life analytics enable condition-based replacement scheduling. Cement producers reduce unplanned downtime through integrated digital platforms.
- Metal processing expansion in Southeast Asia:Steel and aluminum smelter investments in Vietnam and Indonesia drive demand for standard-duty polyester filters. Regional distributors capture aftermarket replacement contracts.
Industry Challenges
- High-temperature filtration engineering talent scarcity:Specialized knowledge in aramid blend specification and cage design for cement kilns concentrates at a handful of technical consultancies. Equipment suppliers struggle to staff field engineering teams.
- Legacy DCS integration complexity:Modern pulse-jet controllers require communication protocols incompatible with aging plant distributed control systems. Power utilities face capex decisions on full automation upgrades versus standalone filter controls.
- Multi-jurisdiction certification timelines:Simultaneous EPA, MEE, and REACH compliance testing stretches R&D resources. Filter media innovators delay product launches to accumulate certification documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Baghouse Filters Market |
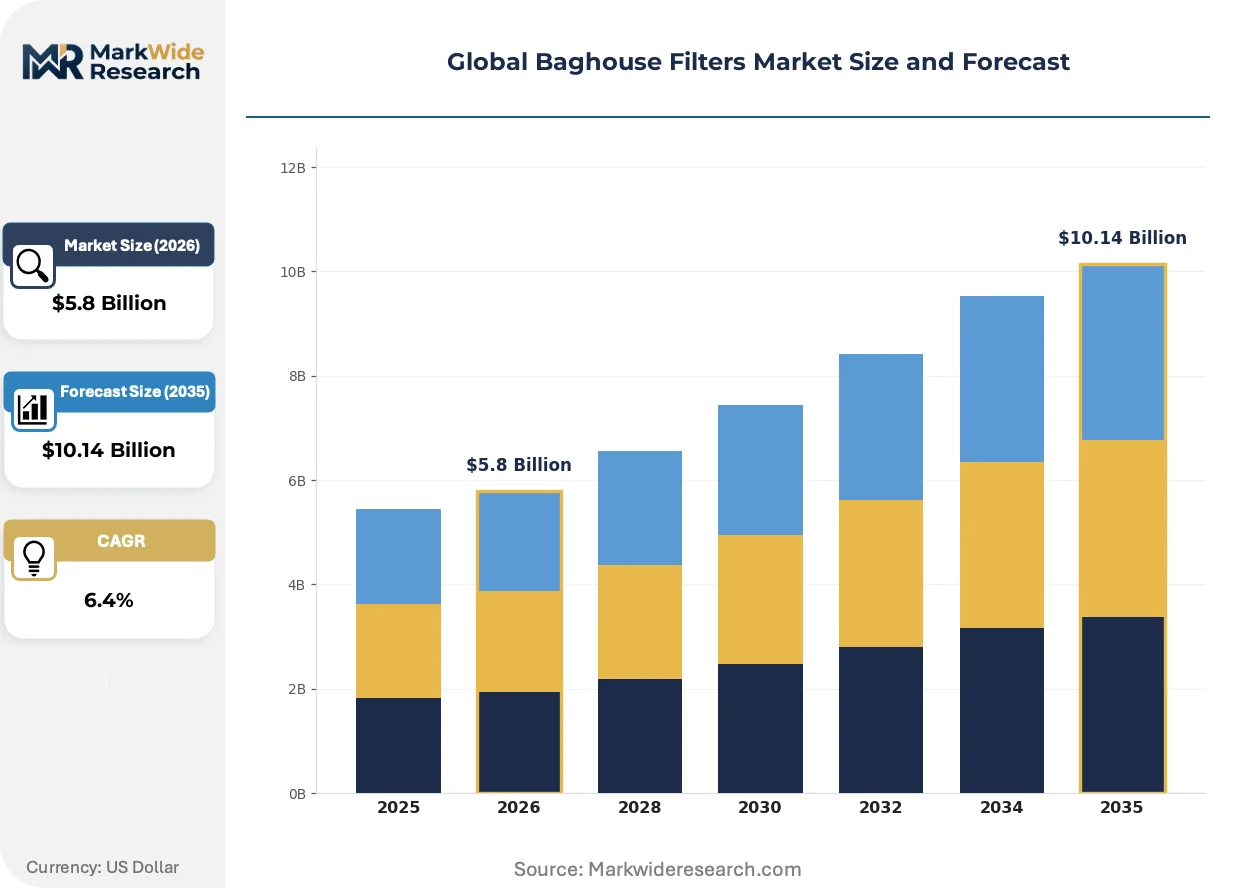
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulse Jet Filters, Reverse Air Filters, Shake Filters, Bag Filter Housings Application: Cement Manufacturing, Chemical Processing, Food Production, Metal Industries Material: Polyester, Fiberglass, Nomex, P84 End User: Power Plants, Pharmaceutical Companies, Oil Refineries, Mining Operations |
| Companies Covered | Donaldson Company, Inc., Camfil AB, CECO Environmental Corp., AGET Manufacturing Co., Aircon Corp., Airex Industries Inc., Amerair Industries LLC, Baghouse America Inc., FLSmidth and Co. AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Baghouse Filters Market Emerging Trajectories
Active materials science breakthroughs and regulatory threshold compression reshape competitive positioning across baghouse filter supply chains. Technology convergence and procurement model evolution accelerate simultaneously.
Nanofiber-coated PTFE membranes is electrifying high-temperature filtration performance in cement kiln applications. Leading cement producers in China and the United States specify these composites for clinker cooler exhaust streams. The technology compresses replacement intervals from eighteen months to thirty-six months while maintaining sub-10 mg/Nm³ emission levels.
China's MEE is tightening provincial enforcement of GB 4915 cement industry emission standards. Stack PM limits now match or exceed EPA MACT stringency in key industrial zones. Domestic filter suppliers accelerate PTFE membrane localization to capture retrofit demand from state-owned cement groups.
Buyers now unbundle filter media procurement from original equipment manufacturer lock-in. Cement and power operators source replacement bags directly from specialty media producers, bypassing traditional system integrators. This channel disintermediation concentrates in the United States and India where aftermarket transparency platforms mature fastest.
Global Baghouse Filters Market Segmentation
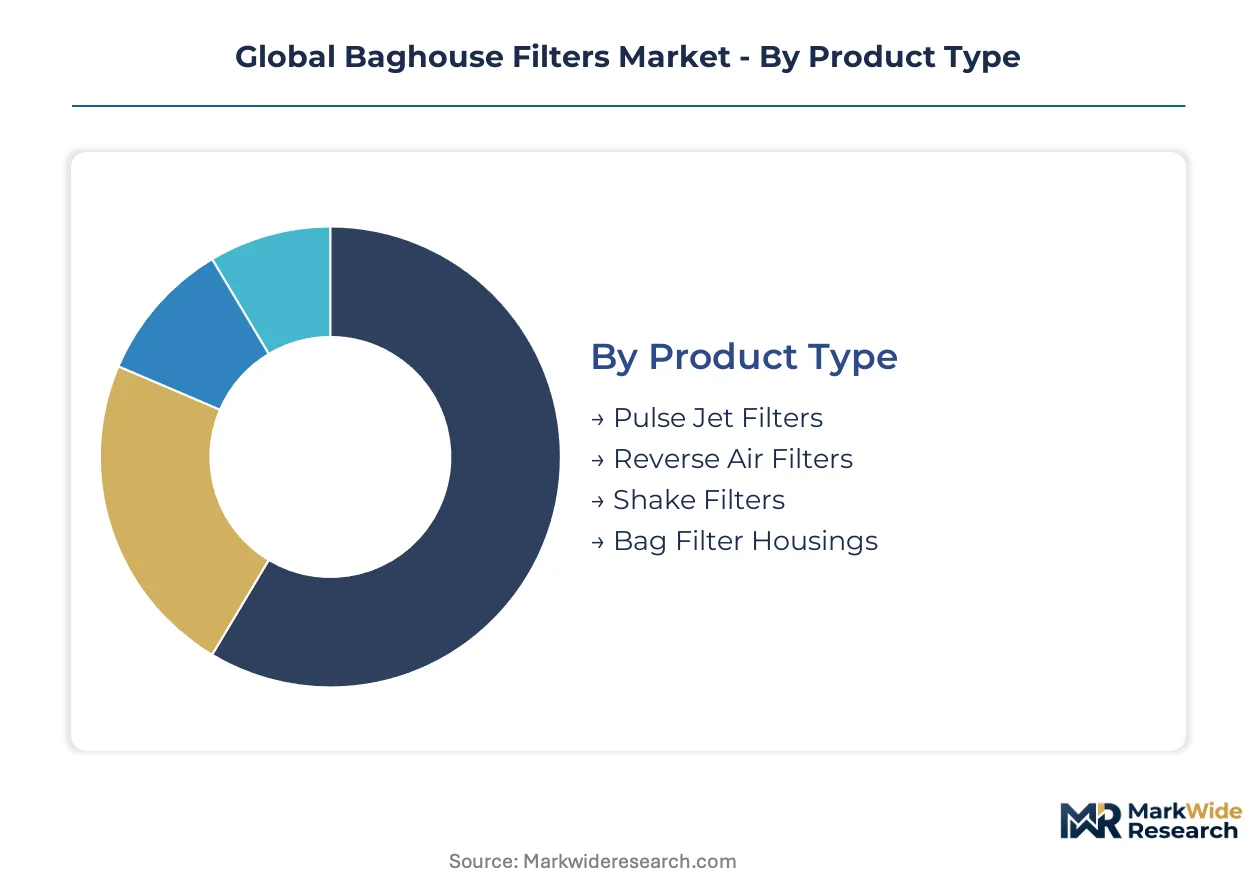
Baghouse filter procurement patterns diverge sharply across operating temperatures, dust loading, and regulatory exposure. Segmentation reveals where technology premiums concentrate versus where commoditization pressures dominate.
Product Type:
Pulse jet configurations command volume leadership through continuous-cleaning architecture, while reverse air retains premium positioning in energy-sensitive large-flow installations.
- Pulse Jet Filters:Compressed-air pulse cleaning enables uninterrupted operation in high dust-loading environments. Cement manufacturers in China and India specify these for clinker grinding and kiln exhaust streams where EPA MACT and MEE emission thresholds apply.
- Reverse Air Filters:Low pressure-drop operation preserves fan energy consumption in large-volume gas streams. Coal-fired power utilities in the United States retain these for boiler flue gas treatment despite footprint penalties and slower cleaning cycles.
- Shake Filters:Mechanical shaker cleaning suits intermittent-duty applications with moderate dust concentrations. Food processing facilities in Europe deploy these for grain handling where batch operations align with shutdown cleaning intervals.
- Bag Filter Housings:Structural enclosures accommodate filter bag and cage arrays across temperature and pressure specifications. Mining operations in Australia prioritize corrosion-resistant carbon steel housings for abrasive ore processing environments.
Today's leader: Pulse Jet Filters. Tomorrow's challenger: Reverse Air Filters.
Application:
Thermal intensity and particulate abrasiveness determine material specification and replacement frequency across end-use sectors.
- Cement Manufacturing:Kiln exhaust streams at 200-260°C demand aramid and fiberglass media with PTFE membrane finishes. Chinese state-owned cement groups drive retrofit demand as MEE enforces GB 4915 stack emission standards.
- Chemical Processing:Aggressive gas chemistries require corrosion-resistant media coatings and specialized cage alloys. Specialty chemical producers in Germany navigate REACH substance restrictions while maintaining filtration performance.
- Food Production:Hygienic design standards and moisture-resistant polyester media dominate grain and sugar processing. Indian food manufacturers expand baghouse capacity under FSSAI particulate control notifications.
- Metal Industries:High-temperature ferrous and non-ferrous smelting exhausts push fiberglass and P84 specifications. Steel producers in Vietnam and Indonesia source standard-duty filters for sinter plant and electric arc furnace applications.
Cement Manufacturing captures the steepest expansion trajectory. Chemical Processing presents the highest margin preservation challenge.
Material:
Cost-performance tradeoffs stratify across temperature tolerance, chemical resistance, and mechanical durability requirements.
- Polyester:Cost-optimized standard-duty media for ambient-temperature applications below 130°C. Metal fabrication and woodworking facilities in Brazil specify these for dry dust collection where operating economics dominate procurement.
- Fiberglass:Woven glass fiber construction withstands continuous exposure to 260°C in cement kiln and boiler exhaust streams. PTFE membrane lamination extends service life in thermal power plants facing CEA emission compliance deadlines.
- Nomex:Meta-aramid chemistry delivers thermal stability and flame resistance in asphalt production and metal foundries. Supply concentration among specialty chemical producers creates input cost volatility for filter manufacturers.
- P84:Polyimide fiber excels in high-temperature chemical environments with superior acid resistance. Waste-to-energy facilities in Japan specify these for flue gas treatment where chlorine and sulfur compounds degrade standard media.
Polyester dominates unit volume. Fiberglass commands revenue per square meter.
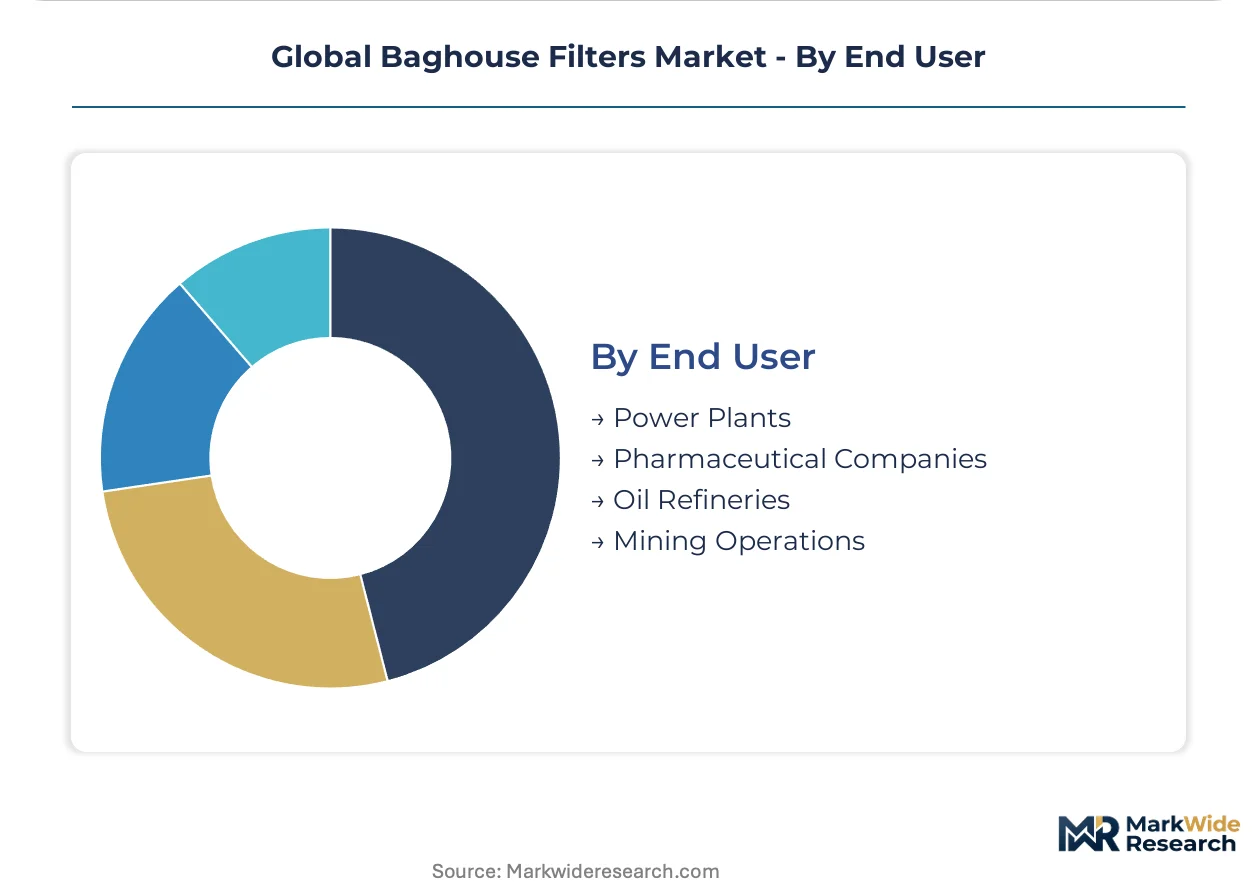
End User:
Regulatory enforcement intensity and asset replacement cycles concentrate demand in emission-intensive infrastructure sectors.
- Power Plants:Coal and biomass combustion drives demand for high-temperature pulse-jet systems with advanced media. United States utilities accelerate retrofit schedules under EPA MACT compliance timelines.
- Pharmaceutical Companies:Containment and cross-contamination prevention require validated filtration systems with integrity testing protocols. FDA inspection emphasis on airborne particulate control elevates specification rigor.
- Oil Refineries:Fluid catalytic cracking and coking operations generate abrasive catalyst fines at elevated temperatures. Saudi Aramco and ADNOC facilities in the Middle East specify heavy-duty fiberglass media for FCCU exhaust treatment.
- Mining Operations:Crushing, grinding, and material handling generate high dust loads in abrasive mineral processing. Chilean copper concentrators and Australian iron ore ports deploy large-format baghouse systems with rapid bag changeout designs.
Power Plants anchor current procurement volumes. Pharmaceutical Companies offer the most defensible pricing architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The baghouse filter industry traces its industrial-scale origins to early twentieth-century American cement and steel operations, where fabric-based dust collection first addressed particulate emissions from high-temperature process streams. This engineering heritage established technical foundations that now propagate through regulatory-driven retrofit cycles across multiple industrial economies.
United States
Coal-fired power utilities and cement manufacturers drive replacement demand as EPA Maximum Achievable Control Technology deadlines compress filter media procurement timelines. The IRA's clean energy provisions accelerate biomass co-firing retrofits requiring high-temperature pulse-jet system upgrades. Texas and Ohio industrial corridors concentrate aging infrastructure requiring simultaneous compliance and efficiency improvements.
China
State-owned cement groups expand clinker capacity while provincial MEE enforcement tightens GB 4915 stack emission thresholds. Domestic filter suppliers localize PTFE membrane production to capture retrofit demand from Shanxi and Hebei industrial clusters. Yangtze River Delta manufacturing hubs integrate baghouse systems into new greenfield steel and chemical complexes.
India
Thermal power producers face CEA stack-emission notification deadlines while cement capacity additions in Rajasthan and Gujarat compound filter procurement volumes. Domestic manufacturers expand polyester and fiberglass media production to serve cost-sensitive standard-duty applications. Maharashtra industrial zones concentrate pharmaceutical and food processing demand for validated containment systems.
Germany
Chemical processors and waste-to-energy facilities navigate REACH substance restrictions while maintaining filtration performance in aggressive gas chemistries. ECHA registration timelines delay new media introductions, favoring established suppliers with compliant formulations. Ruhr industrial heritage sites drive turnkey retrofit demand for aging coal-to-biomass conversion projects.
Saudi Arabia
Aramco and ADNOC downstream expansion generates demand for heavy-duty fiberglass media in fluid catalytic cracking and coking operations. SAMR technical regulations converge on international emission standards for refinery and petrochemical complexes. Jubail and Yanbu industrial cities anchor large-format baghouse deployments for abrasive catalyst fines treatment.
Global Baghouse Filters Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology intensity and service bundling dimensions, with PTFE membrane specialists commanding pricing power over standard polyester fabricators. The vendor base stratifies into three tiers: integrated system providers with captive media manufacturing, pure-play filter media specialists, and regional installation contractors. Consolidation pressure concentrates among mid-scale European and North American fabricators facing Chinese cost competition. Dominant competitive moves include backward integration into pleated media production and multi-year replacement contract bundling.
Within the integrated-system-provider tier, Donaldson Company, Inc. and Camfil AB exemplify archetypes combining manufacturing scale with channel control, while CECO Environmental Corp. occupies a position specializing in turnkey retrofit engineering. Donaldson's Minneapolis-based structure represents North American vertical integration models, Camfil's Swedish corporate form anchors European R&D-intensive positioning, and CECO's incorporated US structure exemplifies project-execution specialists serving regulated infrastructure sectors. These three entities collectively illustrate how geographic origin and corporate architecture map to distinct competitive vectors without prescribing specific strategic actions or market shares.
| Leading Market Players |
|---|
| Donaldson Company, Inc. |
| Camfil AB |
| CECO Environmental Corp. |
| AGET Manufacturing Co. |
| Aircon Corp. |
| Airex Industries Inc. |
| Amerair Industries LLC |
| Baghouse America Inc. |
| FLSmidth and Co. AS |
| Others |
Supply Flow & Price Mechanics
State-owned cement groups in China and utility procurement consortia in the United States anchor demand concentration, locking in project-based long-term contracting with multi-year media replacement bundles as the dominant pricing architecture.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates PTFE membrane composites from fiberglass blends and polyester fabrics. Price differentiation hinges on temperature tolerance certification and installation service bundling. Cost compression in standard-duty polyester is intensifying because Chinese manufacturers expand fiberglass media capacity. Cement manufacturers in India exhibit highest price sensitivity, while pharmaceutical containment buyers accept substantial premiums for validated systems.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's localization requirements for MEE compliance equipment are reshaping sourcing patterns toward in-country media production. Manufacturing concentrates in China, the United States, and Germany for high-temperature aramid blends. Raw material supply draws from specialty chemical producers for PTFE resins, glass fiber rovings, and meta-aramid polymers. Single-source vulnerability in aramid fiber supply creates exposure to input cost spikes. Distribution runs through OEM system integrators and direct aftermarket channels to end-user maintenance teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where regulatory enforcement lag between China's MEE deadlines and India's CEA timelines creates eighteen-to-twenty-four month demand phasing windows for suppliers with cross-border manufacturing footprints.
For Market Incumbents: Anticipate channel disintermediation pressure from direct media sourcing platforms by cement and power operators in the United States and India. Lock in backward integration into pleated media manufacturing to preserve OEM channel control. Deepen captive supply of PTFE membrane substrates to defend margin position against emerging Chinese membrane localizers. For New Entrants and Emerging Players: IoT-enabled predictive maintenance platforms offer the most penetrable wedge for aftermarket service contracts in cement and power sectors. Target India's CEA compliance retrofit cycle for pulse-jet system upgrades where domestic installation capacity lags demand. Pursue white-label sensor integration partnerships with established filter media producers to bypass direct channel conflict. For Investors and Strategic Acquirers: Industrial conglomerates with captive cement or power assets are the most active acquirer in this space, seeking vertical control over maintenance spend. Filter media specialists with REACH-compliant formulations and MEE certification documentation represent priority acquisition archetypes. Watch for aramid fiber price inflection as the signal for margin compression timing across high-temperature filtration tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captive PTFE substrate production locks in supply security for cement kiln retrofit demand in China and the United States. |
| Long-term Replacement Contract Bundling | Multi-year media supply agreements with installation services cement channel access against direct sourcing platforms. |
| Predictive Maintenance Platform Development | Pressure-drop analytics integration with IoT sensors reduces unplanned downtime for cement producers facing MEE enforcement. |
| Regional Certification Investment | Simultaneous EPA, MEE, and REACH compliance documentation accelerates product launch timelines across jurisdiction clusters. |
| Joint Venture with Domestic Filter Suppliers | Localization partnerships in India and China capture retrofit demand under domestic-content procurement rules. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged plant engineers at cement and power facilities, procurement leads at state-owned industrial groups, aftermarket service heads at OEM distributors, and technical R&D directors at filter media manufacturers. Secondary validation drew from EPA enforcement databases, MEE stack-emission compliance records, customs trade data for filter media imports, and SEC filings of listed filtration equipment suppliers. Bottom-up volume builds across temperature tiers and application segments were triangulated against top-down industry spend estimates.
Historical reference periods anchored the projection horizon to capture full regulatory compliance cycle impacts across the analysis window. The analytical framework modeled segmentation across product type, material specification, end-use sector, and regional regulatory cluster. CAGRs were derived from regression-based demand elasticity coefficients applied to capacity addition pipelines. Forecast inputs incorporated clinker capacity expansion schedules, CEA notification compliance deadlines, and biomass co-firing retrofit timelines.
The model holds under stable regulatory enforcement intensity and continuous aramid fiber supply availability; deviation in trade policy restrictions or abrupt MEE enforcement acceleration would shift replacement cycle phasing. Forecasts reflect documented assumptions regarding technology adoption curves and procurement pattern evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Nonwoven Air Conditioning Filter Market
Filters
Furnace Filters Market
Filters
Filter Media Market
Filters
US Baghouse Filters Market
Filters
Global Liquid Filtration Market
Filters
Aerospace Filter Market
Filters
ePTFE Filter Film Market
Filters
Fiberglass Filters Market
Filters
Activated Carbon Market
Filters
Activated Carbon Filter Market
Filters
Fabric Filters Market
Filters
Nonwoven Filter Media Market
Filters
United States Activated Carbon Market
Filters
Global Filter Press Market
Filters
Ceramic Filters Market
Filters
Industrial Filtration Market