
 Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market | 2026-2036
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market Insights
China's chemical manufacturing corridor is reshaping HFO precursor supply chains for rigid polyurethane foam applications. Honeywell leverages its fluorine chemistry heritage to sustain patent-protected HFO-1233zd production at scale. Arkema anchors European supply through specialized polymer-grade blowing agent formulations.
Hydrofluoroolefin blowing agent systems for rigid PU foam comprise low-global-warming-potential fluorinated compounds, typically with GWP values below 15, that generate cellular structures through exothermic reaction with isocyanate in polyurethane formulations. These systems replace hydrofluorocarbon blowing agents in applications demanding thermal resistance below 0.02 W/m·K, primarily serving cold chain infrastructure and building energy efficiency mandates. HFO-1233zd formulations command premium positioning due to superior insulation performance in thick-pour refrigeration panels, while HFO-1234ze variants dominate spray foam building envelope applications where flammability constraints relax. Water blowing technology retains cost leadership in appliance manufacturing, though physical HFO blowing achieves tighter cell structures for aerospace-grade thermal barriers.
EPA Significant New Alternatives Policy program and EU F-Gas Regulation jointly determine which HFO chemistries gain commercial traction across North American and European rigid foam markets. China's GB standards and dual carbon goals from MEE are now filtering HFO adoption thresholds for construction material suppliers operating in East Asian supply chains. Stakeholders must track evolving country-specific GWP ceilings and flammability reclassifications that could abruptly invalidate installed formulation investments.
Market Dynamics
The EU F-Gas Regulation phase-down schedule is compressing formulation cycles for rigid PU foam producers, forcing simultaneous retooling across appliance and construction supply chains. This regulatory compression is redrawing competitive boundaries between HFC incumbents and HFO entrants.
Growth Catalysts
- EU F-Gas Regulation:The staged GWP reduction mandates are eliminating HFC-245fa and HFC-365mfc from refrigeration panels, pulling HFO-1233zd into cold chain infrastructure specifications.
- Building envelope retrofits:Germany's federal energy efficiency ordinances for existing commercial stock are specifying sub-0.02 W/m·K thermal barriers, expanding spray foam contractor demand for HFO-1234ze formulations.
- Aerospace thermal barriers:Satellite and launch vehicle manufacturers are qualifying HFO-blown syntactic foams for cryogenic fuel tank insulation, opening premium formulation tiers.
Market Restraints
- Fluorinated precursor supply concentration:Chlorotrifluoroethylene feedstock production clusters in China's Jiangsu and Shandong provinces, exposing formulators to single-source geographic risk.
- Water-blown cost advantage:Appliance manufacturers retain HFC-to-water conversion pathways at 40-60% lower blowing agent cost, limiting HFO penetration in price-sensitive refrigerator segments.
- Flammability reclassification delays:EU CLP regulation uncertainty around HFO-1234ze flammability thresholds is freezing insurance underwriting for spray foam contractors.
Strategic Opportunities
- India's cold chain expansion:The government's Pradhan Mantri Kisan Sampada Yojana cold storage subsidies are creating first-mover openings for low-GWP foam systems in perishable logistics.
- Formic acid-HFO hybrid systems:Combining chemical and physical blowing in single formulations is enabling density tuning for medical shipping containers, a specification-heavy segment.
- Direct-to-contractor distribution:Bypassing traditional chemical distributor markups through certified installer networks is capturing margin in commercial roofing retrofits.
Industry Challenges
- Fluorine chemistry talent scarcity:Formulation chemists with HFC-to-HFO transition experience are concentrated at legacy producers, constraining independent compounders.
- Dual certification timelines:Simultaneous UL 94 flammability and ISO 4892 weathering approvals for new HFO blends are extending product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market |
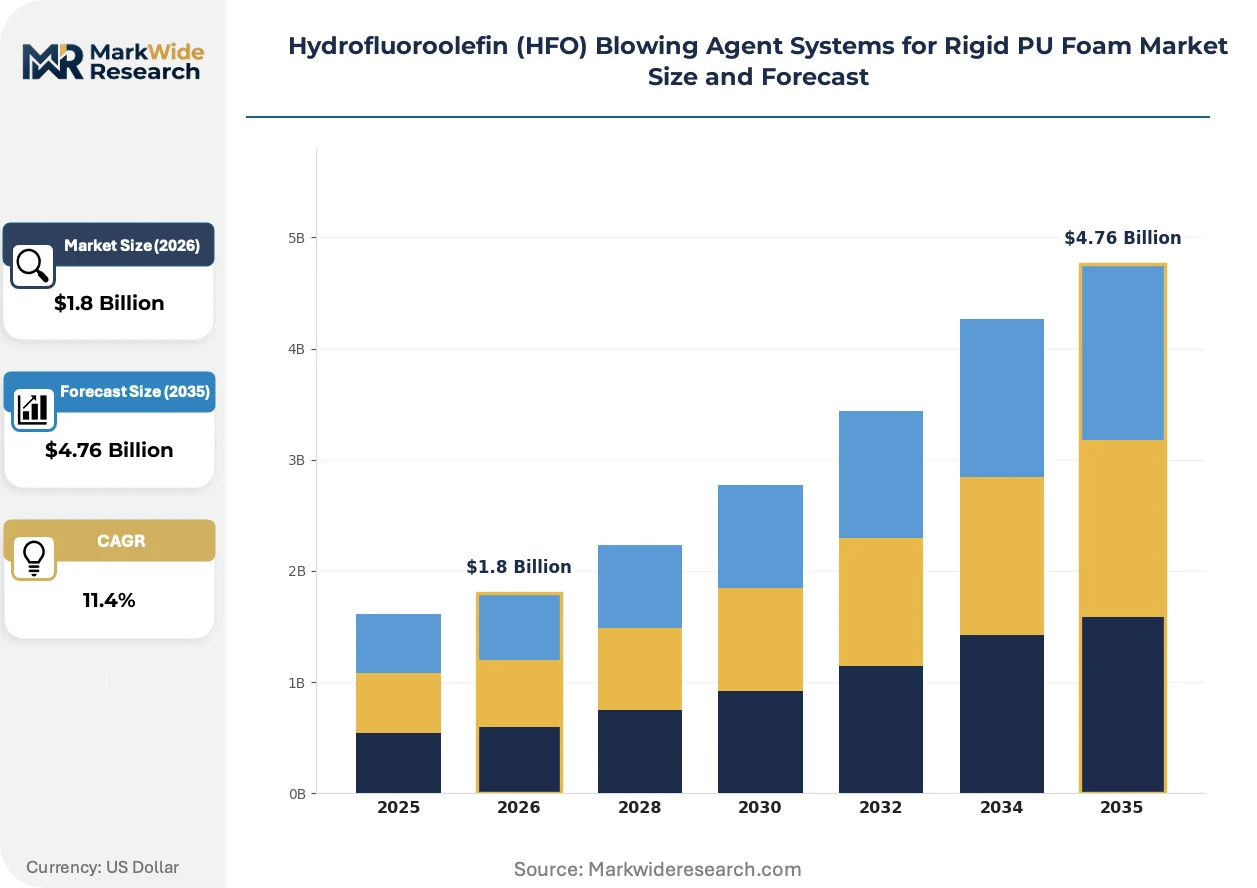
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HFO-1234ze, HFO-1234yf, HFO-1233zd, HFO Blends, HFO-1234ze(E), HFO-1234yf(E) Technology: Water Blowing, Physical Blowing, Chemical Blowing, Co-Blowing, Cyclopentane Blowing, Hydrocarbon Blowing End User: Thermal Insulation Manufacturers, Refrigeration Equipment Producers, Automotive Component Makers, Construction Material Suppliers, Appliance Manufacturers Application: Cold Storage Insulation, Building Envelope, Refrigeration Panels, HVAC Systems, Automotive Thermal Barrier, Packaging Solutions |
| Companies Covered | Honeywell, Arkema, Chemours, DuPont, BASF, Covestro, Dow, Huntsman, Linde, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market Trends and Innovations
Formulation science is converging with supply chain traceability requirements, creating new specification tiers that reward documented carbon footprint rather than standalone thermal performance. This shift is elevating process transparency to a competitive differentiator.
Hybrid HFO-formic acid blowing systems are rendering obsolete single-mechanism physical blowing in thick-pour refrigeration panels. Cold storage OEMs in Germany and the Netherlands are qualifying these dual-action formulations for -40°C operating environments. The technology is compressing cell size distribution variance, tightening lambda values below 0.019 W/m·K in production-scale pours.
REACH authorization timelines for legacy fluorinated intermediates are accelerating HFO precursor investments by European chemical suppliers. The regulatory friction is forcing appliance manufacturers to dual-source HFC and HFO formulations through the transition window. Spray foam contractors in France face compressed retraining schedules as certifying bodies update application standards ahead of 2027 GWP ceilings.
Specification-driven procurement is consolidating buyer power among national construction material distributors. Regional roofing contractors are losing direct supplier relationships as certified HFO applicator networks centralize purchasing through approved channels. The channel compression is most visible in Benelux markets, where building envelope performance guarantees now require documented blowing agent GWP certification.
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market Segmentation
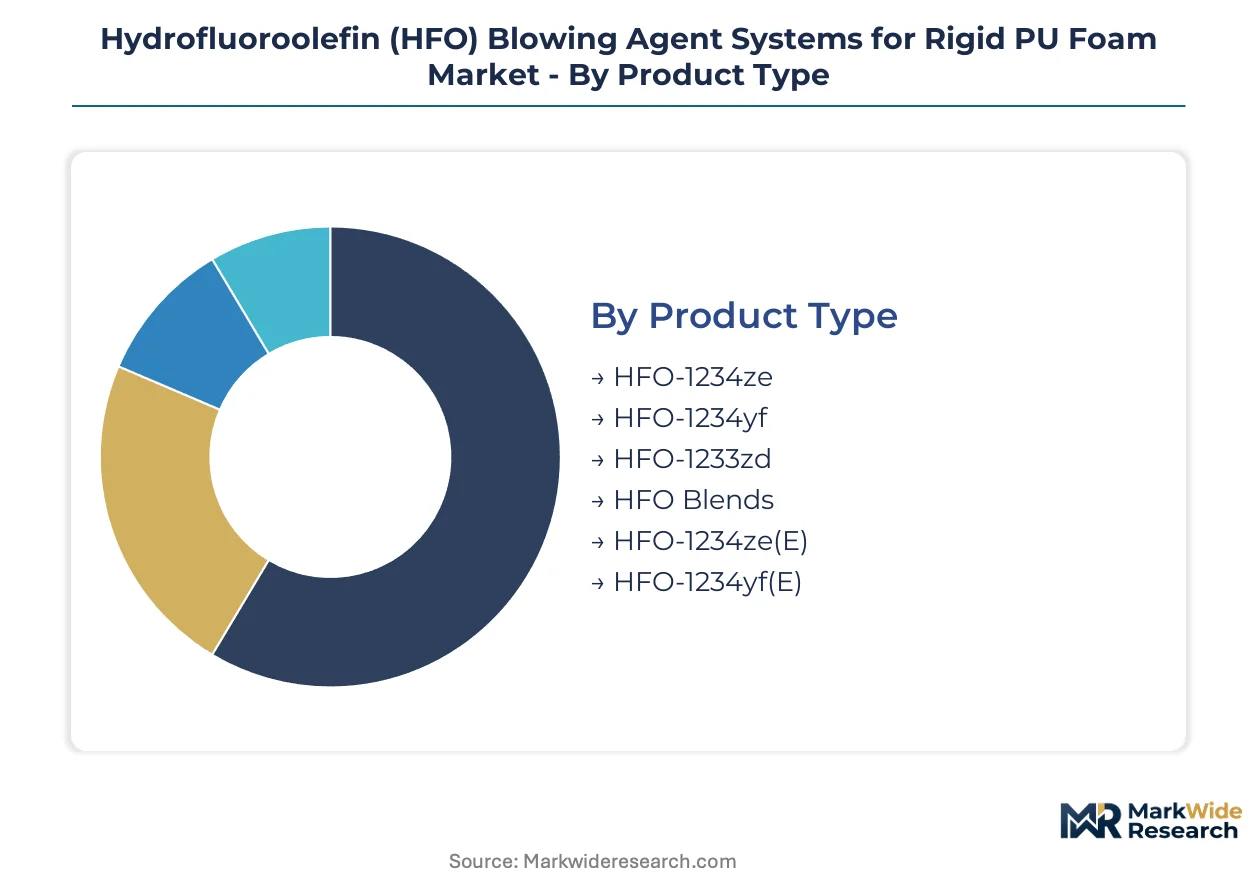
HFO blowing agent selection determines thermal performance thresholds, regulatory compliance windows, and formulation cost structures across rigid polyurethane applications. Segmentation reveals where technical specifications diverge from procurement economics.
Product Type:
Mature chemistries dominate installed capacity while next-generation isomers capture specification upgrades in premium thermal barriers.
- HFO-1234ze:This trans-isomer formulation achieves sub-15 GWP ratings with lambda values approaching 0.019 W/m·K in spray foam applications. Construction material suppliers in Germany specify HFO-1234ze for commercial roofing retrofits facing 2027 EU F-Gas Regulation deadlines.
- HFO-1233zd:Honeywell's patent-protected production delivers superior cell structure stability in thick-pour refrigeration panels operating below -40°C. Cold storage OEMs in the Netherlands and Germany qualify this chemistry for industrial freezer specifications demanding sub-0.02 W/m·K thermal resistance.
- HFO-1234yf:Mobile thermal barrier applications favor this lower-boiling-point variant for automotive component integration.
- HFO Blends:Custom formulations balance flammability ratings with GWP targets across hybrid blowing systems.
- HFO-1234ze(E):The E-isomer variant addresses specific viscosity requirements in continuous panel production lines.
- HFO-1234yf(E):Stereoisomer-pure grades serve aerospace-grade syntactic foam specifications.
HFO-1234ze retains volume leadership; HFO-1233zd holds the steepest expansion curve.
Technology:
Cost tiers separate legacy water-based systems from premium physical blowing achieving aerospace thermal performance.
- Physical Blowing:HFO-based physical blowing generates uniform microcell structures through controlled vapor pressure release during polyurethane polymerization. Refrigeration equipment producers specify physical blowing for thick-pour panels where lambda consistency across production batches determines warranty coverage.
- Co-Blowing:Hybrid HFO-formic acid systems combine chemical and physical mechanisms for density-tuned medical shipping containers. Cold storage OEMs in Germany and the Netherlands qualify these dual-action formulations for -40°C operating environments with compressed cell size variance.
- Water Blowing:Appliance manufacturers retain this pathway at 40-60% lower blowing agent cost, constraining HFO penetration in price-sensitive refrigerator segments.
- Chemical Blowing:Formic acid derivatives generate CO₂ expansion independent of external blowing agents.
- Cyclopentane Blowing:Hydrocarbon alternative serves markets with relaxed flammability constraints.
- Hydrocarbon Blowing:Isobutane and n-pentane variants compete on raw material cost in emerging market construction.
Water blowing commands the lowest cost position; co-blowing systems gain share fastest in specification-heavy cold chain segments.
End User:
Customer type determines whether procurement prioritizes GWP certification documentation or unit economics.
- Refrigeration Equipment Producers:Cold chain infrastructure manufacturers face the strictest EU F-Gas Regulation phase-down schedules, eliminating HFC-245fa and HFC-365mfc from panel specifications. German appliance manufacturers and construction material suppliers dual-source HFC and HFO formulations through the regulatory transition window.
- Construction Material Suppliers:Building envelope retrofits in Germany's federal energy efficiency ordinances specify sub-0.02 W/m·K thermal barriers. Spray foam contractors face compressed retraining schedules as French certifying bodies update application standards ahead of 2027 GWP ceilings.
- Thermal Insulation Manufacturers:Panel producers balance lambda performance with REACH authorization timelines for fluorinated intermediates.
- Automotive Component Makers:OEM thermal barrier specifications integrate HFO-blown foams into electric vehicle battery enclosures.
- Appliance Manufacturers:Mass-market refrigerator producers retain water-blown conversion pathways for cost-sensitive segments.
Refrigeration equipment producers drive premium formulation demand; construction material suppliers represent the steepest volume expansion trajectory.
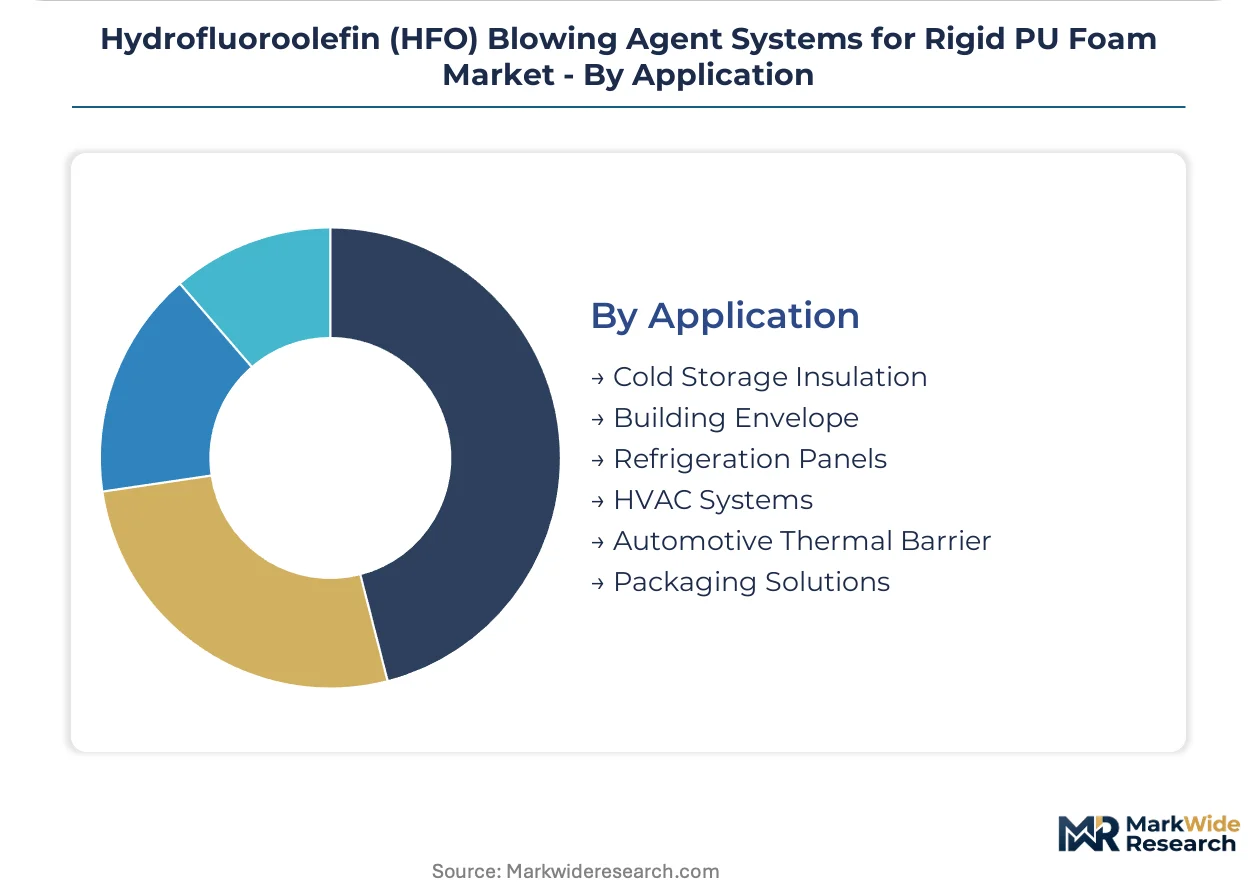
Application:
Application scope separates thick-pour industrial specifications from spray-applied building envelope retrofits.
- Cold Storage Insulation:Industrial freezer and refrigerated warehouse specifications demand HFO-1233zd for lambda stability across -40°C to ambient temperature cycling. India's Pradhan Mantri Kisan Sampada Yojana cold storage subsidies create first-mover openings for low-GWP foam systems in perishable logistics infrastructure.
- Building Envelope:Commercial roofing and wall assembly retrofits specify HFO-1234ze where spray foam contractors require updated insurance underwriting. EU CLP regulation uncertainty around HFO-1234ze flammability thresholds has frozen coverage approvals in France and Belgium.
- Refrigeration Panels:Continuous and discontinuous panel production lines specify blowing agents by pour thickness and demold time requirements.
- HVAC Systems:Duct insulation and equipment casings balance thermal performance with acoustic dampening specifications.
- Automotive Thermal Barrier:Electric vehicle battery pack enclosures and climate control systems integrate lightweight HFO-blown cores.
- Packaging Solutions:Medical shipping containers and temperature-controlled logistics boxes demand density-tuned hybrid formulations.
Cold storage insulation retains specification leadership; building envelope applications climb fastest as EU energy efficiency mandates accelerate retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes HFO blowing agents predominantly for thick-pour refrigeration panels, while China directs the chemistry toward precursor manufacturing rather than end-use foam production. This consumption-mix differential separates specification-driven European demand from supply-chain-oriented Asian investment.
United States
Refrigeration equipment producers in the Midwest and Southeast are converting HFC-245fa lines ahead of EPA SNAP enforcement timelines. The Significant New Alternatives Policy program is disqualifying high-GWP blowing agents from cold chain infrastructure specifications. Appliance manufacturing clusters in Ohio and Tennessee face compressed retooling schedules as 2027 compliance deadlines approach.
Germany
Cold storage OEMs in Bavaria and North Rhine-Westphalia specify HFO-1233zd for industrial freezer panels operating below minus 40 degrees Celsius. The federal energy efficiency ordinances mandate sub-0.02 W/m·K thermal barriers for commercial building retrofits. Spray foam contractors in the Ruhr region face retraining mandates as certifying bodies update application standards.
China
Chemical manufacturers in Jiangsu and Shandong provinces dominate chlorotrifluoroethylene feedstock production for HFO precursors. The Ministry of Ecology and Environment dual carbon goals are filtering adoption thresholds for construction material suppliers. MEE GB standards are gradually tightening GWP ceilings for rigid foam applications in East Asian supply chains.
Netherlands
Panel producers in Rotterdam and Eindhoven industrial corridors qualify hybrid HFO-formic acid formulations for continuous production lines. REACH authorization timelines for legacy fluorinated intermediates are accelerating dual-sourcing strategies. Cold storage infrastructure investment in the Port of Rotterdam complex is pulling premium blowing agent specifications.
India
The Pradhan Mantri Kisan Sampada Yojana cold storage subsidies are creating first-mover demand for low-GWP foam systems in perishable logistics. Bureau of Indian Standards is developing GWP labeling requirements for construction insulation materials. Perishable logistics clusters in Maharashtra and Gujarat are specifying imported HFO formulations for temperature-controlled warehouses.
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market Competitive Landscape
Capability concentration sits with fluorine chemistry heritage players; scale advantage sits with diversified polyurethane system houses. The market structure splits between patent-protected HFO producers and formulation-integrated foam suppliers. Three archetypes dominate: legacy fluorochemical specialists, diversified chemical conglomerates, and regional system compounders. Competitive moves center on backward integration into precursor supply and technology licensing agreements.
Within the fluorochemical specialist tier, Honeywell and Arkema occupy positions anchored by patent-protected production assets and regional formulation expertise respectively. Chemours represents the diversified chemical conglomerate archetype with integrated fluorine chemistry capabilities. These three companies exemplify the capability-scale tension: specialists control molecule-level intellectual property while diversified players leverage polyurethane system integration.
| Leading Market Players |
|---|
| Honeywell |
| Arkema |
| Chemours |
| DuPont |
| BASF |
| Covestro |
| Dow |
| Huntsman |
| Linde |
| Others |
Pricing and Supply Chain Analysis
Jiangsu province's chlorotrifluoroethylene production clusters determine downstream formulation economics across rigid PU foam supply chains. Capacity concentration in China's chemical manufacturing corridor translates directly to pricing power for HFO precursor suppliers serving European and North American formulators. EU F-Gas Regulation compliance deadlines are compressing procurement timelines and amplifying spot-price volatility for refrigeration equipment producers.
Pricing Analysis
Geographic price spreads between Chinese precursor exports and European formulated products reflect tariff exposure and REACH authorization costs. Three-tier pricing structure across premium, standard, and economy levels separates patent-protected HFO-1233zd from licensed generic formulations and water-blown alternatives. Cost compression in appliance-grade segments is intensifying because appliance manufacturers retain HFC-to-water conversion pathways. Mass-market refrigerator producers exhibit highest price sensitivity; aerospace thermal barrier specifications demonstrate lowest elasticity.
Supply Chain Analysis
Upstream feedstock production of chlorotrifluoroethylene concentrates in China's Jiangsu and Shandong provinces, with secondary capacity in Japan and limited Western hemisphere assets. Formulated blowing agents draw from fluorinated intermediates, isocyanate feedstocks, and specialty surfactant packages. Single-source geographic vulnerability in Chinese precursor manufacturing exposes formulators to supply disruption from environmental enforcement actions or export license restrictions. Distribution runs through certified applicator networks and national construction material distributors rather than traditional chemical merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a platform-economics inflection where formulation certification interoperability determines competitive access. The shift from HFC to HFO chemistry is creating ecosystem lock-in effects around patent-protected molecule supply and certified installer networks.
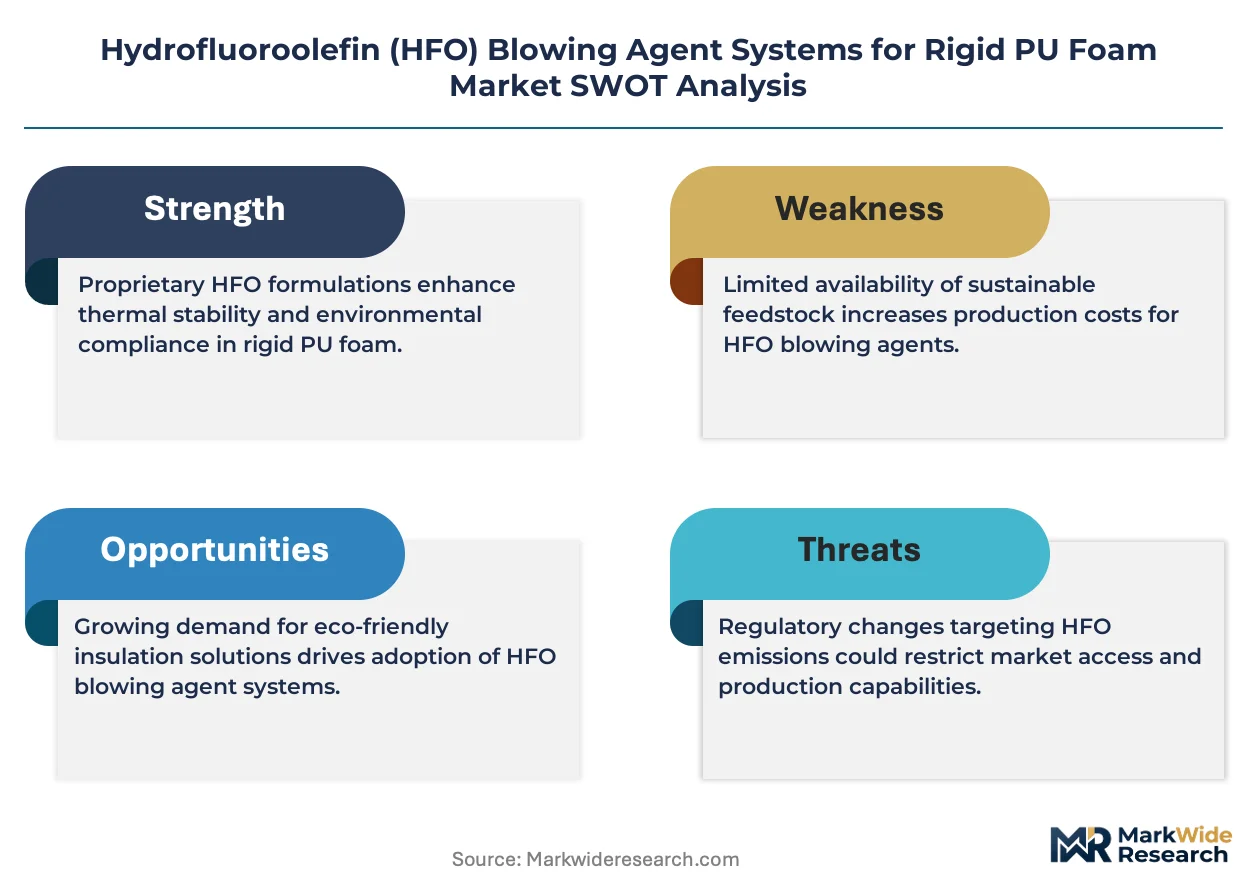
For Market Incumbents: Insulate patent-protected production positions through backward integration into precursor supply and exclusive licensing arrangements with polyurethane system houses. Water-blown technology substitution in appliance segments threatens volume retention; counter through premium positioning in cold chain infrastructure where lambda performance commands specification adherence. Capacity expansion in European compounding facilities reinforces proximity to German and Dutch OEM qualification programs.
For New Entrants and Emerging Players: Establish a beachhead in India's cold chain expansion under Pradhan Mantri Kisan Sampada Yojana subsidies, where imported formulation demand outpaces domestic supply capability. Hybrid HFO-formic acid co-blowing systems for medical shipping containers represent the most penetrable specification-heavy segment. Pursue direct-to-contractor distribution partnerships in Benelux commercial roofing retrofits to bypass entrenched distributor markups.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EU F-Gas and Kigali Amendment phase-down schedules create irreversible demand substitution. Target acquisition candidates with fluorine chemistry talent concentration and dual-certification capabilities for UL 94 and ISO 4892 standards. Monitor India's Bureau of Indian Standards GWP labeling rulemaking as the inflection signal for emerging market premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captures margin compression from Chinese chlorotrifluoroethylene concentration for European formulators. |
| Certified Installer Network Expansion | Locks in specification-driven procurement through Benelux and German commercial roofing channels. |
| Hybrid Co-Blowing Formulation Development | Addresses -40°C cold storage OEM requirements in Netherlands and German industrial corridors. |
| India Market Entry Partnership | Positions for Pradhan Mantri Kisan Sampada Yojana cold storage subsidy deployment in Maharashtra. |
| REACH Authorization Timeline Acceleration | Preempts competitor access to legacy fluorinated intermediate substitution pathways. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, EPA SNAP program filings, EU ECHA registration databases, and SEC chemical company disclosures. Primary interviews engaged formulation chemists at polyurethane system houses, procurement directors at refrigeration equipment OEMs, spray foam contractor certification bodies, and fluorochemical plant operations managers. Secondary validation drew from Cefic sector reports, customs export statistics, and patent filing analysis. Bottom-up volume modeling triangulated against top-down regulatory phase-down schedule impacts.
Forecast inputs include HFC quota allocation trajectories, EU F-Gas Regulation GWP ceiling schedules, and cold chain infrastructure investment pipelines across the projection horizon. Segmentation dimensions modeled comprise blowing agent chemistry tier, technology mechanism, end-user industry vertical, application thermal performance specification, and regional regulatory cluster. CAGRs derived from elasticity-adjusted substitution curves linking HFC phase-down mandates to HFO uptake rates. Industry-specific inputs include REACH authorization timelines for legacy intermediates and Bureau of Indian Standards labeling rulemaking progress.
Stress conditions across chlorotrifluoroethylene export restriction scenarios, EU CLP flammability reclassification outcomes, and water-blown technology performance advancement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions around regulatory enforcement consistency and OEM qualification cycle stability. Cross-checking against ECHA registration database updates and Indian cold storage subsidy disbursement rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Fatty Amines Market
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
Froth Flotation Chemicals Market
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market
Industrial Chemicals
Heat Shrink Tubes Market
Industrial Chemicals
Fluidized Bed Reactors Market
Industrial Chemicals
Well Stimulation Materials Sales Market
Industrial Chemicals
Dewatering Aids Market
Industrial Chemicals
Diesel Exhaust Fluid Market
Industrial Chemicals
Fabric Starch Market