
 Global Microencapsulated Pesticides Market | 2026-2036
Global Microencapsulated Pesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microencapsulated Pesticides Market Foresight
ISO 17025 accreditation for analytical testing of encapsulated active ingredients is redrawing competitive boundaries in crop protection chemistry. BASF SE leverages its polymer science division to sustain formulation leadership across multiple active ingredient classes. Syngenta Group anchors its position through integrated seed-to-spray platforms that bundle microencapsulated products with trait technologies. FMC Corporation differentiates via specialized coacervation expertise targeting high-value horticulture markets.
Microencapsulated pesticides incorporate active ingredients within protective shells of synthetic polymers, natural gums, or lipid matrices, typically ranging from 1 to 1000 micrometers in diameter, enabling timed release and reduced phytotoxicity. These formulations serve commercial agriculture by improving application safety windows, minimizing non-target exposure, and extending efficacy duration against pest pressure. Insecticides command the largest current volume share, reflecting entrenched demand for controlled-release pyrethroids and neonicotinoids in row-crop systems. Polymer coating technology is expanding fastest, as aqueous-based shell formation methods displace solvent-dependent processes under tightening volatile organic compound rules. Commercial farmers represent the dominant end-user channel, though agricultural cooperatives are gaining procurement leverage through collective volume commitments.
The EPA regulates microencapsulated pesticides under FIFRA with enhanced data requirements for particle size distribution and release kinetics, while the EU REACH framework governs polymer constituent safety and environmental fate assessments. Brazil's ANVISA and China's MEE impose additional residue and ecotoxicology standards that filter market entrants by registration capacity. India's CDSCO and Central Insecticides Board are tightening import clearance protocols for novel encapsulation chemistries. Stakeholders must monitor evolving equivalence determinations across jurisdictions, as divergent shell-material approvals threaten portfolio fragmentation and duplicative testing burdens.
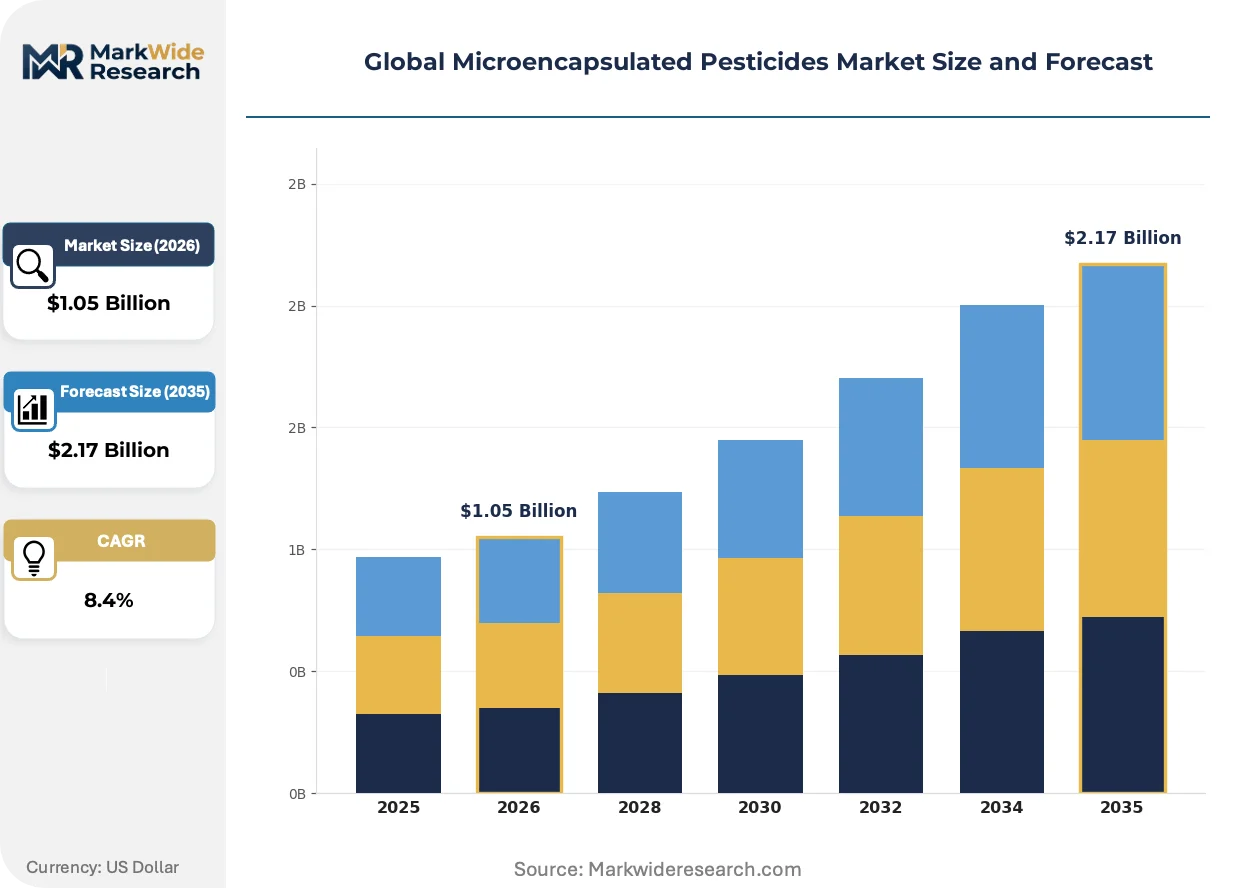
Market Dynamics
Polymer coating technology is displacing solvent-based encapsulation methods as tightening volatile organic compound regulations force reformulation investments across crop protection chemistry.
Growth Catalysts
- EPA FIFRA Registration Pathways:Controlled-release data requirements now explicitly recognize microencapsulation benefits, accelerating product approvals for environmental fate claims.
- Brazilian Soybean Belt Resistance Protocols:Precision delivery systems align with integrated pest management mandates favoring timed-release insecticides over calendar spraying.
- Aqueous Polymer Science Advances:Shell formation methods eliminate solvent handling costs while improving batch consistency for commercial scale-up.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic polymer shell materials expose formulators to propylene and ethylene derivative price swings.
- Registration Capacity Concentration:Brazil's ANVISA and China's MEE equivalence determinations filter entrants lacking multi-jurisdiction testing infrastructure.
- Release Kinetics Variability:Field temperature and moisture fluctuations degrade shell integrity predictability versus laboratory conditions.
Strategic Opportunities
- India's CDSCO Import Clearance Tightening:Novel encapsulation chemistry approvals favor early movers establishing local analytical partnerships.
- Horticulture Precision Application:High-value permanent crops demand residue-minimizing formulations with extended re-entry intervals.
- EU REACH Polymer Constituent Safety:Shell material registration creates first-mover advantage for biodegradable gum and lipid matrix alternatives.
Industry Challenges
- ISO 17025 Analytical Talent Scarcity:Encapsulated active ingredient testing requires specialized chromatography and particle characterization expertise concentrated in contract laboratories.
- Multi-Jurisdiction Equivalence Burden:Divergent shell-material approvals between EPA, ECHA, and ANVISA threaten portfolio fragmentation and duplicated ecotoxicology studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microencapsulated Pesticides Market |
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Herbicides, Fungicides, Rodenticides, Nematicides Crop Type: Cereals & Grains, Fruits & Vegetables, Oilseeds & Pulses, Plantation Crops, Horticulture Formulation Technology: Polymer Coating, Liposome Encapsulation, Spray Drying, Coacervation, Fluidized Bed End User: Commercial Farmers, Agricultural Cooperatives, Landscape Contractors, Greenhouse Operators |
| Companies Covered | BASF SE, Syngenta Group, FMC Corporation, Bayer AG, ADAMA Agricultural Solutions Ltd., Yara International, Sumitomo Chemical Co., Ltd., GAT Microencapsulation, Nufarm Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microencapsulated Pesticides Market Shifts & Advancements
Formulation chemistry is pivoting toward bio-based shell materials as regulatory pressure on synthetic polymers intensifies across major agricultural economies.
Aqueous-based polymer coating methods are displacing solvent-dependent processes under tightening EPA volatile organic compound rules and EU F-Gas Regulation phase-down schedules. Commercial row-crop operators in the US Corn Belt and Brazilian Cerrado are adopting these formulations at accelerating rates to maintain application windows during regulatory transition periods. This technology shift is compressing capital recovery timelines for legacy solvent infrastructure while opening contract manufacturing slots for aqueous specialists.
EU REACH framework amendments now mandate polymer constituent safety assessments and environmental fate documentation for encapsulated active ingredients entering European markets. The industrial consequence forces reformulation investments or market withdrawal for shell chemistries lacking biodegradation data. Horticulture and high-value vegetable segments face the steepest compliance costs, driving consolidation toward integrated seed-to-spray platforms with captive analytical capabilities.
Collective procurement through agricultural cooperatives is fragmenting traditional distributor channels as volume commitments concentrate buying power. Brazil's soybean cooperatives and US Midwest grain marketing alliances now negotiate direct formulation supply agreements, disintermediating regional crop protection distributors. This pattern is most visible in maturing no-till systems where precision agriculture bundles favor single-source supplier relationships over multi-brand portfolios.
Global Microencapsulated Pesticides Market Segmentation
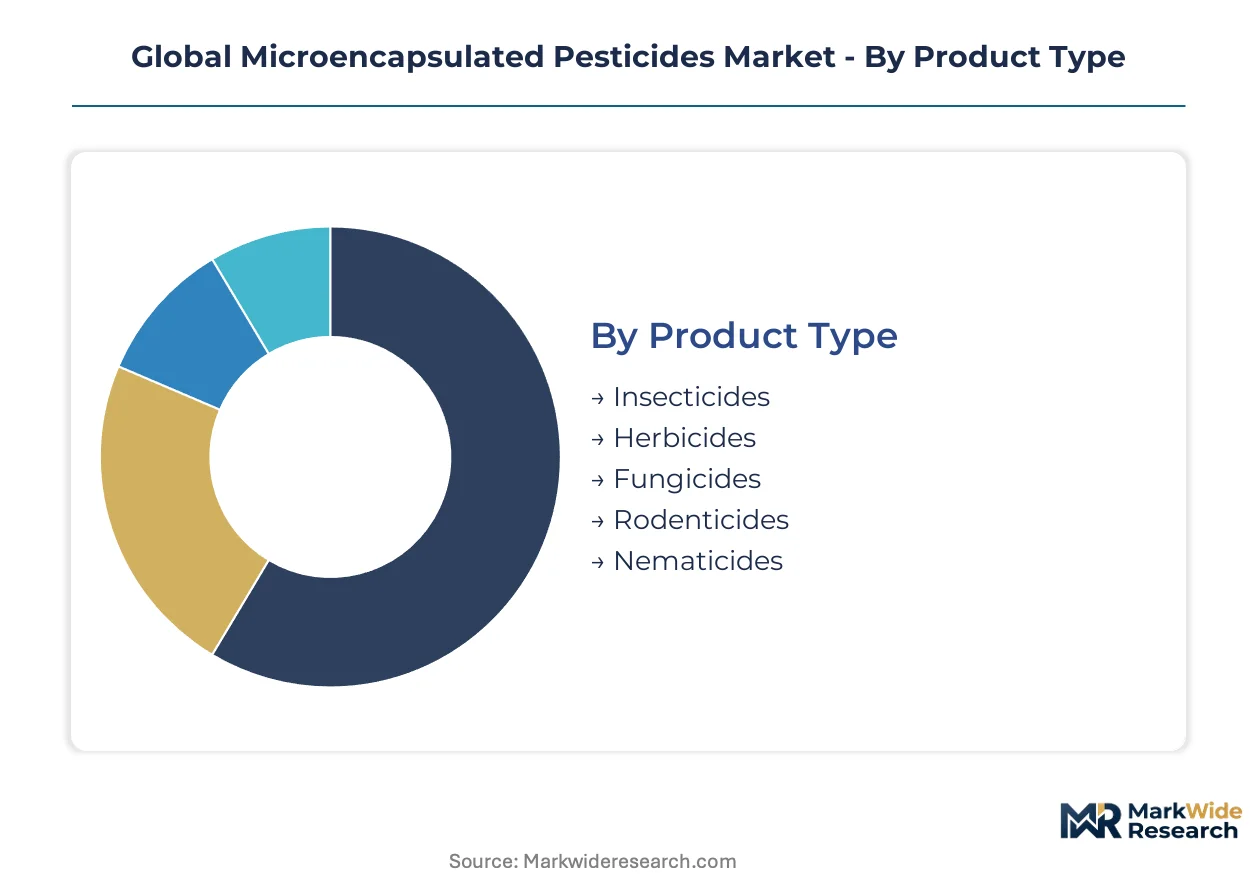
Segmentation in microencapsulated pesticides reveals how formulation chemistry, crop economics, and regulatory pressure intersect to determine commercial viability. Distinct technology and end-user channels command divergent margin profiles and registration investment thresholds.
Product Type:
EPA FIFRA registration pathways differentiate environmental fate claims across active ingredient classes, concentrating development resources where timed-release data accelerates approval timelines.
- Insecticides:Controlled-release pyrethroids and neonicotinoids dominate current volume, with Brazil's soybean belt driving demand for resistance management protocols that favor precision delivery over calendar spraying. EPA recognition of microencapsulation benefits in reducing runoff claims has shortened registration cycles for this class.
- Herbicides:Encapsulated glyphosate and auxinic formulations extend application windows in no-till systems, though petrochemical feedstock volatility in synthetic polymer shells compresses margin predictability for formulators. The US Corn Belt and Brazilian Cerrado represent concentrated demand centers.
- Fungicides:Lipid-matrix encapsulation of triazoles and strobilurins targets high-value horticulture segments requiring extended re-entry intervals.
- Rodenticides:Anticoagulant encapsulation reduces non-target exposure, aligning with EU REACH environmental fate mandates.
- Nematicides:Polymer-coated abamectin and fluopyram address soil-dwelling pest pressure in vegetable production systems.
Established volume favors insecticides; emerging adoption favors herbicides as no-till acreage expands.
Crop Type:
Application economics vary sharply by crop value per hectare, with permanent crops justifying premium formulation costs that row-crop operators resist.
- Fruits & Vegetables:Residue-minimizing microencapsulated formulations command premium positioning in EU and US markets where MRL compliance determines market access. EU REACH polymer constituent safety assessments favor biodegradable shell alternatives in this high-scrutiny segment.
- Cereals & Grains:Wheat, corn, and rice systems prioritize cost efficiency, with aqueous polymer coating methods displacing solvent-based processes under tightening VOC rules. Volume concentration in US Midwest and Black Sea corridor drives procurement scale.
- Oilseeds & Pulses:Soybean and canola applications in Brazil and Argentina align with cooperative procurement consolidation.
- Plantation Crops:Coffee and cocoa operations in Colombia and Indonesia adopt extended-release insecticides for labor scheduling flexibility.
- Horticulture:Ornamental and nursery sectors demand phytotoxicity-reducing formulations with precise release kinetics.
Permanent crop premiums sustain horticulture margins; row-crop scale drives cereals and oilseeds volume leadership.
Formulation Technology:
Capital recovery timelines for manufacturing infrastructure diverge dramatically between aqueous and solvent-dependent process platforms.
- Polymer Coating:Aqueous-based shell formation eliminates solvent handling costs while improving batch consistency, with commercial scale-up accelerating across US and EU contract manufacturing networks. EPA VOC rule tightening and EU F-Gas Regulation phase-down schedules compress legacy infrastructure viability.
- Coacervation:Specialized aqueous phase separation targets high-value horticulture markets where particle size uniformity commands price premiums. FMC Corporation's captive expertise in this method illustrates technology-specific competitive moats.
- Liposome Encapsulation:Phospholipid bilayer systems offer biodegradation pathways aligned with EU REACH shell-material registration requirements.
- Spray Drying:Cost-efficient solid matrix formation serves mass-market row-crop applications with lower performance specifications.
- Fluidized Bed:Continuous processing technology enables high-throughput operations for large-volume insecticide and herbicide production.
Process investment favors polymer coating; specialized performance favors coacervation in premium crop segments.
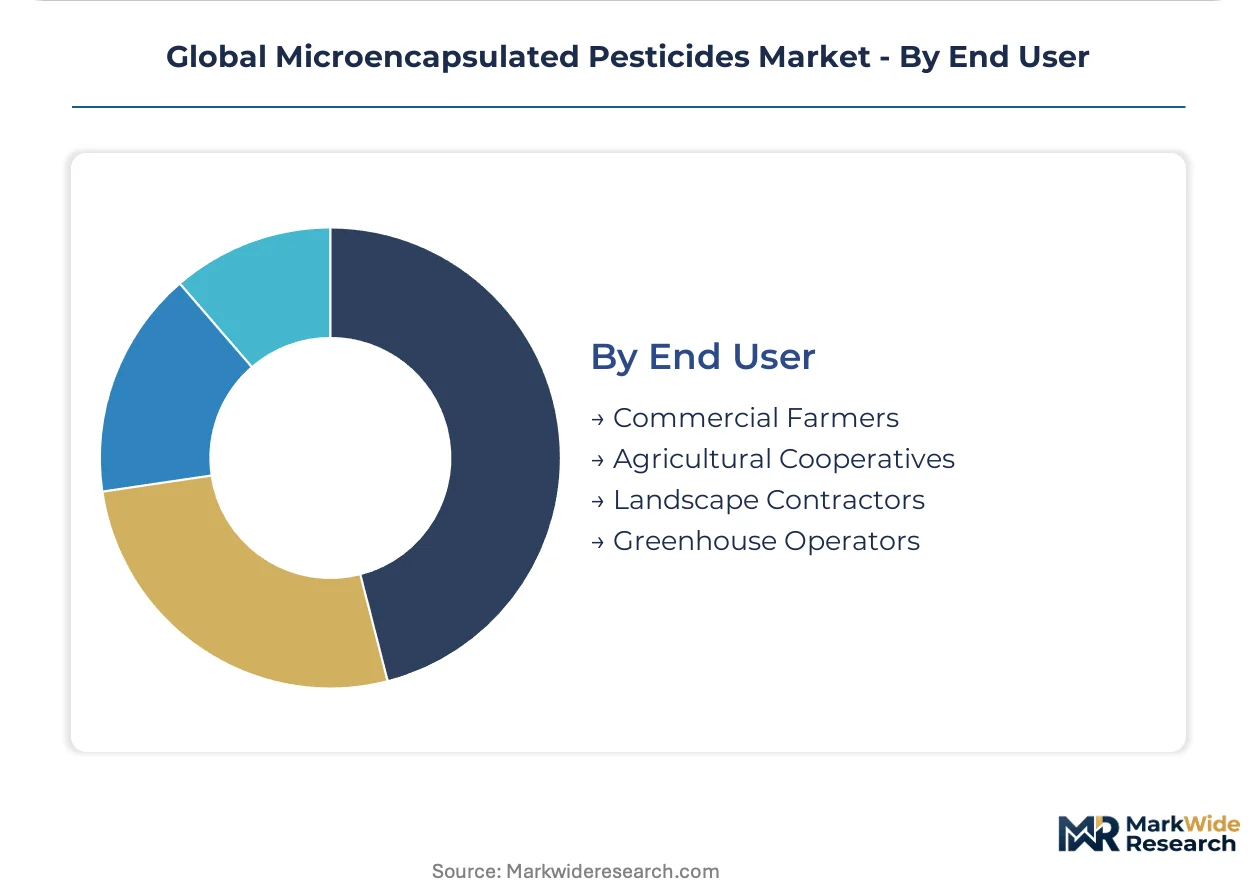
End User:
Procurement channel structure determines pricing power distribution between formulators and their customers.
- Commercial Farmers:Individual operators in US Corn Belt and Brazilian Cerrado maintain application flexibility preferences, though collective bargaining through grain marketing alliances is fragmenting traditional distributor relationships. Direct supply agreements now bypass regional crop protection distributors in maturing no-till systems.
- Agricultural Cooperatives:Brazil's soybean cooperatives and US Midwest grain alliances concentrate volume commitments, disintermediating multi-brand portfolios in favor of single-source precision agriculture bundles. This channel is expanding fastest as procurement leverage shifts downstream.
- Landscape Contractors:Turf and ornamental applications require extended residual activity with minimal re-entry restrictions.
- Greenhouse Operators:Controlled-environment agriculture demands precise release kinetics for integrated pest management compliance.
Direct farm procurement favors commercial farmers; collective leverage favors agricultural cooperatives as the expanding channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA FIFRA registration pathways for controlled-release data requirements and EU REACH polymer constituent safety assessments are redirecting commercial investment toward jurisdictions with harmonized encapsulation standards. Brazil's ANVISA equivalence determinations and China's MEE residue protocols filter market entry by registration capacity.
United States
Commercial row-crop operators in the Corn Belt adopt aqueous polymer coating formulations to maintain application windows during EPA volatile organic compound rule transitions. The EPA's explicit recognition of microencapsulation benefits in environmental fate claims accelerates product approvals for runoff reduction. St. Louis and Research Triangle Park host concentrated formulation R&D clusters where polymer science divisions advance shell formation methods.
Brazil
Soybean belt cooperatives drive precision delivery system demand through integrated pest management mandates favoring timed-release insecticides over calendar spraying. ANVISA equivalence determinations for novel encapsulation chemistries filter entrants lacking multi-jurisdiction testing infrastructure. The Cerrado region concentrates direct supply agreements between agricultural cooperatives and formulators, disintermediating traditional distributor channels.
Germany
EU REACH framework amendments mandate polymer constituent safety assessments and environmental fate documentation for shell materials entering European markets. ECHA biodegradation data requirements force reformulation investments or market withdrawal for synthetic polymer chemistries. Ludwigshafen and Leverkusen anchor industrial clusters where polymer science expertise sustains formulation leadership across active ingredient classes.
China
MEE residue standards and ecotoxicology requirements for novel encapsulation chemistries filter market entrants by analytical testing capacity. The country's national environmental regulator imposes additional shell-material approval protocols that threaten portfolio fragmentation. Yangtze River Delta manufacturing hubs scale aqueous-based coating methods as solvent-dependent processes face phase-down schedules.
India
CDSCO and Central Insecticides Board tightening of import clearance protocols for novel encapsulation chemistries favors early movers establishing local analytical partnerships. BIS standards for encapsulated active ingredient testing concentrate contract laboratory capacity in Mumbai and Hyderabad. Maharashtra and Gujarat agricultural belts drive cooperative procurement consolidation for precision agriculture bundles.
Global Microencapsulated Pesticides Market Competitive Landscape
Listed leaders compete with private specialists across polymer science capabilities and multi-jurisdiction registration infrastructure. The vendor base concentrates around integrated agrochemical conglomerates with captive formulation divisions and specialized contract manufacturers with coacervation expertise. Three archetypes dominate: diversified chemical majors with polymer science divisions, crop protection specialists with seed-to-spray integration, and niche encapsulation technology providers. Competitive moves center on aqueous process capacity expansion and analytical testing partnerships for ISO 17025 accreditation.
Within the diversified chemical major tier, BASF SE and Bayer AG occupy positions anchored by polymer science divisions that sustain formulation leadership across multiple active ingredient classes. Syngenta Group exemplifies the seed-to-spray integration archetype through bundled microencapsulated products with trait technologies. FMC Corporation represents the specialized expertise vector with coacervation capabilities targeting high-value horticulture segments. GAT Microencapsulation sits within the niche technology provider tier focused on encapsulation process licensing.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta Group |
| FMC Corporation |
| Bayer AG |
| ADAMA Agricultural Solutions Ltd. |
| Yara International |
| Sumitomo Chemical Co., Ltd. |
| GAT Microencapsulation |
| Nufarm Limited |
| Others |
Supply & Pricing Matrix
Contract manufacturing scale in aqueous polymer coating compresses unit economics for solvent-dependent legacy infrastructure, concentrating price-setting power with aqueous specialists while establishing cost floors for reformulation investments. Brazil's ANVISA registration capacity requirements and EU REACH shell-material compliance costs propagate through tiered pricing structures that separate multinational formulators from regional blenders lacking multi-jurisdiction testing infrastructure.
Pricing Analysis
Certification level (ISO 17025-accredited analytical testing) creates the primary spread between premium and standard tiers, with EPA FIFRA environmental fate data packages commanding price premiums over baseline encapsulated formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by polymer shell complexity and release kinetics documentation. Cost compression in economy-tier pyrethroid formulations is intensifying because petrochemical feedstock volatility in propylene derivatives squeezes margin buffers for synthetic polymer shells. Agricultural cooperatives in Brazil's soybean belt exhibit highest price sensitivity through collective volume negotiations, while high-value horticulture operators in EU markets demonstrate lowest sensitivity due to residue-minimizing formulation premiums.
Supply Chain Analysis
China and India anchor active ingredient manufacturing for encapsulated formulations, with Germany and the United States concentrating polymer science R&D and advanced shell formation technology. Synthetic polymer shell production draws from ethylene and propylene derivative feedstocks, while natural gum alternatives rest on acacia and alginate harvesting networks in East Africa and Southeast Asia. Single-source vulnerability in ISO 17025-accredited contract testing laboratories threatens registration timelines for novel encapsulation chemistries. Distribution runs through agricultural cooperatives and direct supply agreements that disintermediate traditional regional crop protection distributors in maturing no-till systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulated pesticide adoption sits in early-cycle expansion as aqueous polymer coating technology displaces solvent-based methods under tightening EPA volatile organic compound rules and EU F-Gas Regulation phase-down schedules.
For Market Incumbents: Secure aqueous process capacity through contract manufacturing partnerships or backward integration into aqueous polymer coating infrastructure before legacy solvent infrastructure obsolescence accelerates. Defend registration portfolios against emerging contract research organizations by embedding ISO 17025 analytical capabilities within captive testing divisions. Channel control through direct supply agreements with Brazil's soybean cooperatives and US Midwest grain alliances locks out multi-brand distributors. For New Entrants and Emerging Players: Differentiate on biodegradable shell material expertise targeting EU REACH polymer constituent safety mandates that force reformulation investments for synthetic polymer incumbents. White-space concentration in India's CDSCO import clearance tightening favors early movers establishing Mumbai or Hyderabad analytical partnerships. Target high-value horticulture segments in EU and US markets where residue-minimizing formulations command premium positioning and cooperative procurement consolidation has not yet penetrated. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aqueous polymer coating specialists with ISO 17025 accreditation and established multi-jurisdiction registration infrastructure over solvent-dependent legacy assets. Long-term viability across the analysis window hinges on shell-material biodegradation pathways and analytical testing capacity concentration. The signal to watch is ANVISA equivalence determination timelines for novel encapsulation chemistries, which filter market entrants and concentrate competitive moats around registration capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Polymer Coating Capacity Expansion | EPA VOC rule tightening and EU F-Gas phase-down compress legacy solvent infrastructure viability windows. |
| ISO 17025 Analytical Partnership Development | CDSCO import clearance tightening in India and ANVISA equivalence determinations in Brazil demand accredited testing capacity. |
| Biodegradable Shell Material R&D Investment | EU REACH polymer constituent safety assessments favor gum and lipid matrix alternatives with biodegradation data packages. |
| Direct Supply Agreement with Agricultural Cooperatives | Brazil's soybean cooperatives and US Midwest grain alliances concentrate procurement leverage and disintermediate distributors. |
| Multi-Jurisdiction Registration Infrastructure Buildout | Divergent EPA, ECHA, and ANVISA shell-material approvals threaten portfolio fragmentation without harmonized testing capacity. |
Research Methodology
Desk research of EPA FIFRA registration databases, EU ECHA polymer constituent safety filings, and ANVISA equivalence determination precedents preceded structured interviews with formulation R&D directors, agricultural cooperative procurement managers, contract manufacturing executives, and ISO 17025 laboratory accreditation specialists. Primary fieldwork combined with secondary validation against customs trade data, SEC 10-K agrochemical segment disclosures, and national agricultural ministry pesticide usage surveys. Bottom-up segment sizing triangulated against top-down macroeconomic agricultural input expenditure models.
Variance decomposition across product type, crop application, formulation technology, and end-user channel dimensions informed the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical adoption curves against regulatory inflection points and technology substitution rates. Industry-specific forecast inputs incorporated petrochemical feedstock price elasticity for synthetic polymer shells and cooperative procurement consolidation velocity in Brazil and the US Midwest.
Forecasts assume regulatory continuity in EPA FIFRA controlled-release data requirements, EU REACH polymer constituent safety mandates, and ANVISA equivalence determination protocols; material policy shifts in shell-material approval standards or residue testing protocols would require re-modeling. Recalibration cycles align with material shifts in aqueous coating technology adoption rates and cooperative procurement channel penetration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Cobalt Acetate Solution Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
Global Aerosol Propellant Market
Industrial Chemicals
Dynamite Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Industrial Phenol Market
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
Babassu Oil Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Nitrous Oxide Market
Industrial Chemicals
Adblue Market
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
Calciner Market
Industrial Chemicals
E-Fluids Market