
 Anhydrous Ammonia Storage Tank Market | 2026-2036
Anhydrous Ammonia Storage Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Anhydrous Ammonia Storage Tank Market Insights
Modular tank skids bundled with vapor recovery and safety instrumentation are restructuring buyer procurement patterns across the anhydrous ammonia value chain. Linde Engineering leverages its cryogenic equipment heritage to anchor large-scale turnkey storage complexes for chemical producers. Assmann Corporation specializes in rotationally molded polyethylene mini tanks that dominate agricultural co-op distribution networks. McDermott sustains engineering-procurement-construction capabilities for the most demanding above-ground bullet tank installations.
Anhydrous ammonia storage tanks are pressure vessels engineered to contain NH3 at ambient temperature or refrigerated conditions, typically constructed from carbon steel with post-weld heat treatment to resist stress corrosion cracking in wet ammonia service. Their primary purpose is to provide safe containment for this toxic, flammable compound during distribution between production facilities, wholesale terminals, and agricultural or industrial end users. Horizontal tanks occupy the largest installed base due to their stability and ease of transport by rail and truck, while vertical tanks command premium positioning where footprint constraints dominate site planning. Underground installations represent the fastest-growing configuration as population encroachment on legacy chemical facilities drives secondary containment and risk-mitigation investments.
EPA Risk Management Plan requirements and OSHA Process Safety Management standards govern ammonia quantities above threshold levels, mandating hazard assessments, emergency response integration, and mechanical integrity programs that directly shape tank specification and replacement cycles. ASME Boiler and Pressure Vessel Code Section VIII Division 1 provides the foundational fabrication standard, with state-level amendments in Texas, Louisiana, and Iowa adding jurisdiction-specific inspection intervals. Stakeholders must monitor evolving hydrogen-ammonia co-storage specifications as power-to-ammonia projects begin blending energy transition requirements with traditional agricultural demand.
Market Dynamics
Power-to-ammonia projects are electrifying storage tank specifications as hydrogen-ammonia co-storage requirements reshape fabrication standards and safety instrumentation across the value chain.
Growth Catalysts
- US Gulf Coast export terminal expansion:Petrochemical clustering around Houston and Corpus Christi concentrates procurement activity for large-scale refrigerated storage complexes serving agricultural and industrial off-takers.
- EPA Risk Management Plan amendments:Tightened leak detection and emergency response integration mandates accelerate replacement cycles for aging above-ground installations.
- Carbon steel post-weld heat treatment:Advances in stress corrosion cracking resistance extend tank service life in wet ammonia service, reducing total cost of ownership for fertilizer distributors.
Market Restraints
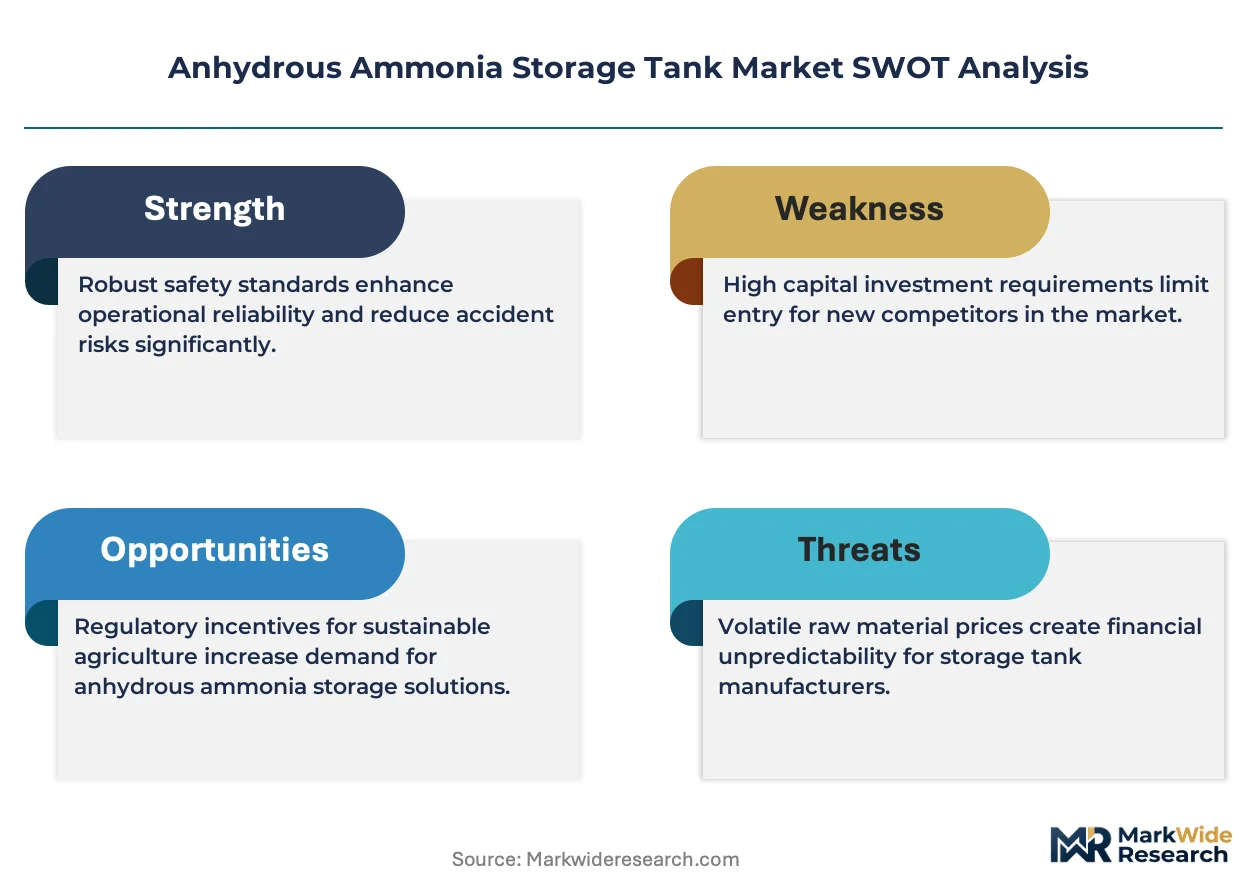
- Specialized carbon steel alloy costs:Volatility in nickel and molybdenum pricing compresses margins for fabricators serving mid-scale agricultural co-ops.
- ASME-certified welder concentration:Shortage of qualified pressure vessel welders in the Midwest agricultural belt extends lead times for horizontal tank deliveries.
- Underground installation complexity:Secondary containment and groundwater monitoring requirements in Iowa and Illinois add 15-25% to installed costs versus above-ground equivalents.
Strategic Opportunities
- Brazilian fertilizer import infrastructure:Port terminal modernization at Santos and Paranaguá creates demand for refrigerated ammonia storage to support corn and soybean belt expansion.
- OSHA Process Safety Management integration services:Bundled mechanical integrity programs and hazard assessment consulting offer recurring revenue streams beyond equipment sales.
- Modular skid packaging with vapor recovery:Pre-assembled tank-instrumentation bundles reduce field construction duration for greenfield chemical facilities.
Industry Challenges
- ASME Section VIII Division 1 state amendments:Jurisdiction-specific inspection intervals in Texas, Louisiana, and Iowa complicate fleet standardization for multi-state operators.
- Legacy tank retrofit compatibility:Integrating modern leak detection and emergency shutdown systems with 1970s-era installations strains electrical and control engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anhydrous Ammonia Storage Tank Market |
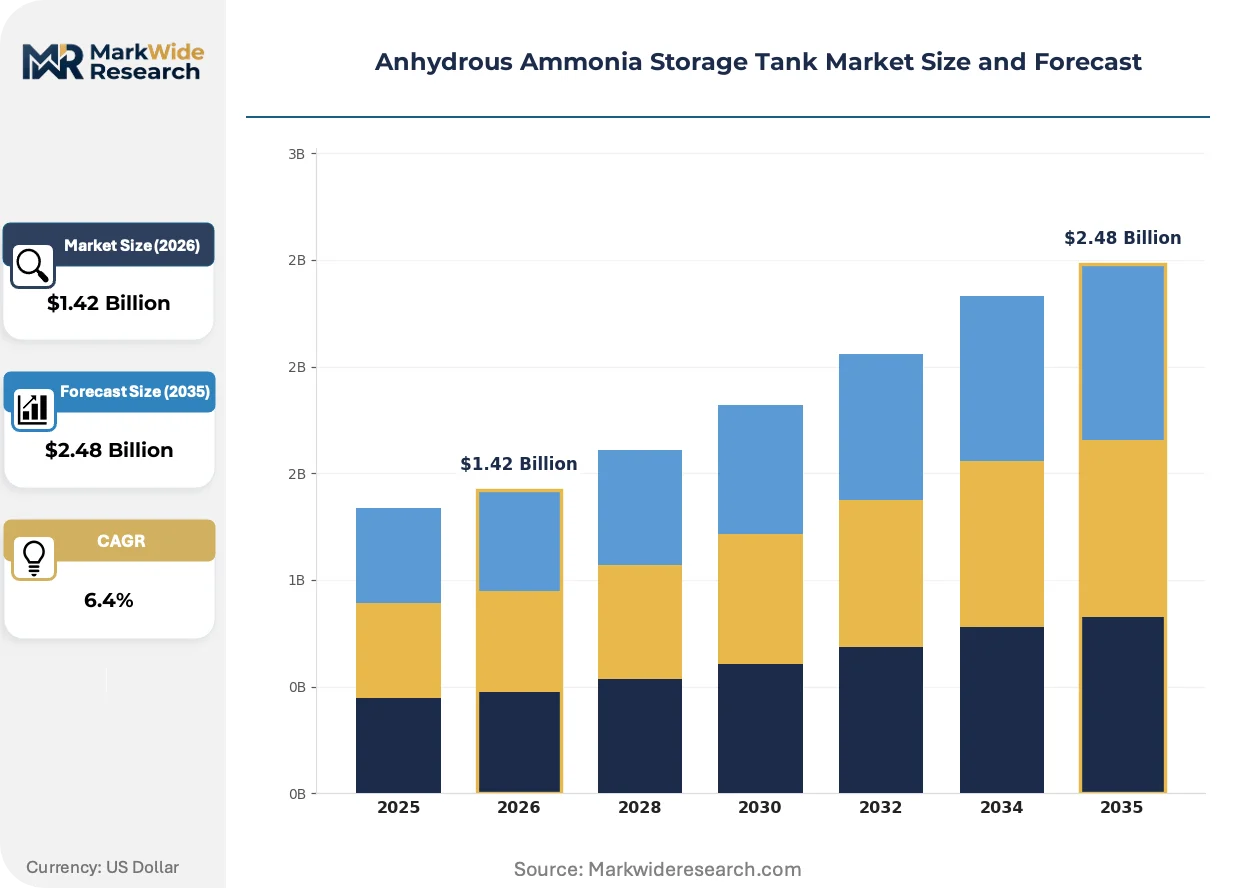
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Tanks, Vertical Tanks, Mini Tanks, Custom Tanks End User: Agriculture, Chemical Industry, Food Processing, Pharmaceuticals Installation Type: Above Ground, Underground, Mobile, Stationary Capacity: Small Scale, Medium Scale, Large Scale, Custom Size |
| Companies Covered | Highberg Solutions, Linde Engineering, Assmann Corporation, Geldof, McDermott, Balmoral Tanks Ltd., Chart Industries, thyssenkrupp Uhde GmbH, Meridian Manufacturing Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anhydrous Ammonia Storage Tank Market Trends and Innovations
Digital instrumentation and modular construction methods are compressing project timelines while ammonia's emerging role as a hydrogen carrier is forcing storage technology convergence.
Advanced fiber-optic leak detection systems are electrifying safety architecture for refrigerated ammonia terminals. Fertilizer distributors with coastal export exposure are retrofitting existing spheres with distributed temperature sensing. This technology is electrifying the risk profile of aging infrastructure by enabling predictive maintenance before catastrophic release.
EPA's forthcoming updates to Risk Management Plan requirements for toxic substances will mandate enhanced consequence analysis and community notification protocols. Chemical facilities above threshold quantities must integrate real-time meteorological data into emergency response planning. Agricultural terminals in Nebraska and Kansas are pre-emptively upgrading secondary containment to exceed baseline federal standards.
Turnkey procurement bundling is consolidating vendor relationships as buyers shift from component purchasing to integrated storage complex contracts. EPC contractors are absorbing more pre-commissioning and operator training scope previously handled separately. This pattern is most pronounced among nitrogen fertilizer producers expanding capacity along the US Gulf Coast corridor.
Anhydrous Ammonia Storage Tank Market Segmentation
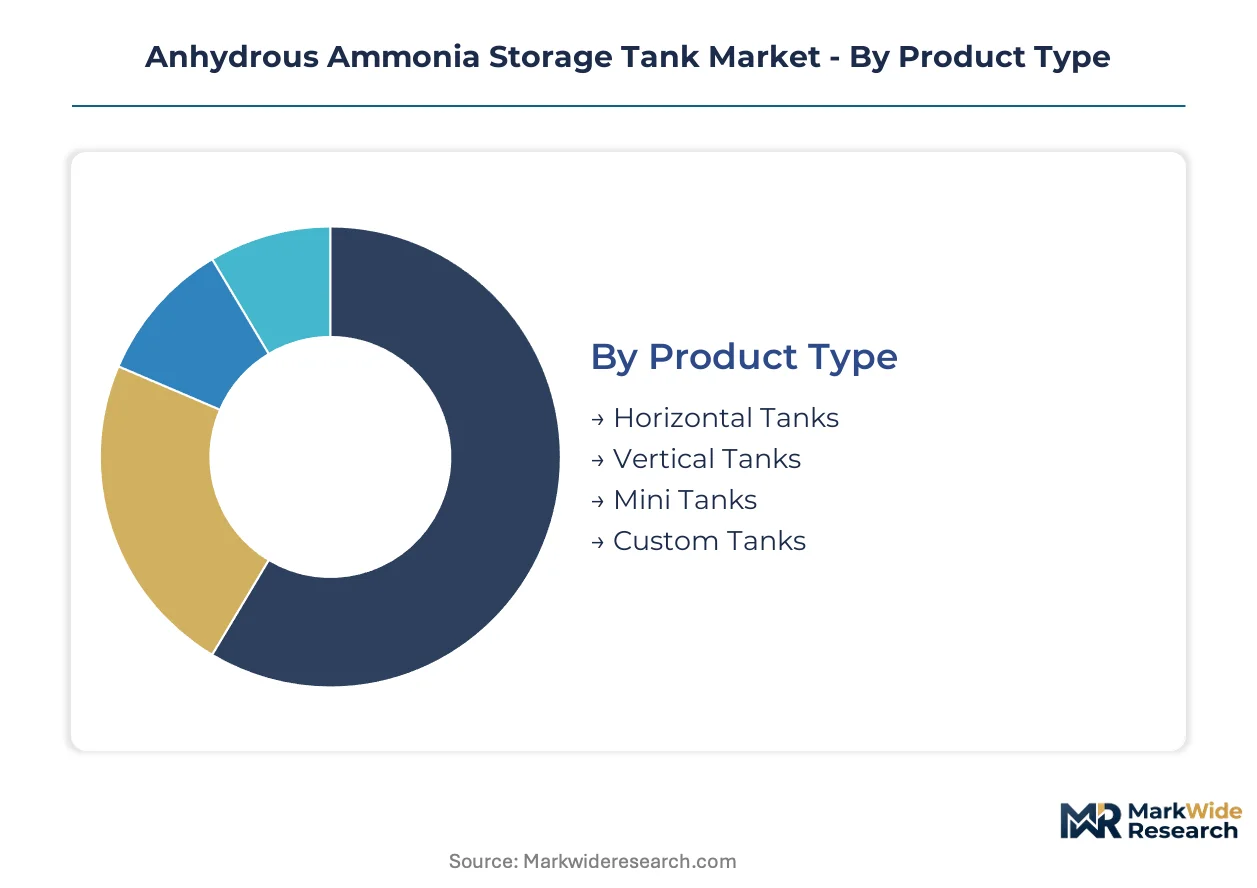
Segmentation in anhydrous ammonia storage reveals how tank specifications diverge across pressure vessel classes, installation constraints, and end-use toxicity exposure levels. Procurement patterns vary sharply between agricultural co-ops seeking transportable horizontal units and petrochemical terminals requiring refrigerated spherical storage.
Product Type:
Upgrade and replacement cycles diverge significantly by tank orientation and fabrication complexity, with older horizontal fleets driving near-term demand while vertical installations capture greenfield chemical terminal expansions.
- Horizontal Tanks:Cylindrical pressure vessels mounted on saddles dominate rail and truck transport applications due to structural stability during movement. Demand concentrates across Iowa, Illinois, and Nebraska agricultural co-ops where EPA Risk Management Plan amendments accelerate replacement of 1980s-era carbon steel shells lacking post-weld heat treatment.
- Vertical Tanks:Upright cylindrical or spherical configurations minimize footprint at congested Gulf Coast petrochemical complexes. Procurement clusters around Houston and Corpus Christi export terminals where ammonia refrigeration systems require elevated liquid head pressure.
- Mini Tanks:Rotationally molded polyethylene units below 1,000-gallon capacity serve distributor last-mile delivery networks.
- Custom Tanks:Engineered-to-order vessels accommodate unique site constraints at legacy chemical facilities undergoing leak detection retrofits.
Volume placements concentrate in Horizontal Tanks; the faster expansion belongs to Vertical Tanks.
End User:
Cost tier stratification separates commodity agricultural procurement from premium industrial applications demanding specialized metallurgy and instrumentation.
- Agriculture:Nitrogen fertilizer distributors represent the foundational demand layer, with tank specifications governed by seasonal application windows and co-op capital constraints. Corn and wheat belt operations in Kansas and Oklahoma prioritize horizontal tank mobility for field-side nurse tank deployment.
- Chemical Industry:Petrochemical producers and ammonia export terminal operators drive specifications for refrigerated storage complexes with vapor recovery integration. Gulf Coast clustering creates concentrated procurement for ASME Section VIII Division 1 certified spheres with distributed temperature sensing.
- Food Processing:Cold storage refrigeration systems using ammonia as working fluid require compact horizontal vessels with enhanced leak detection.
- Pharmaceuticals:High-purity ammonia for synthesis demands specialized surface finish and cleaning protocols.
Revenue concentration sits with Agriculture; margin expansion favors Chemical Industry.
Installation Type:
Application context determines whether mobility, risk mitigation, or capital efficiency dominates specification trade-offs.
- Above Ground:Conventional bullet tanks and spheres on concrete foundations remain the default for greenfield terminals with adequate setback distances. Texas and Louisiana facilities favor this configuration for simplified OSHA Process Safety Management inspection access.
- Underground:Buried horizontal tanks with secondary containment address population encroachment on legacy facilities. Iowa and Illinois groundwater monitoring requirements add complexity but reduce community risk exposure.
- Mobile:Skid-mounted horizontal tanks with integrated vapor recovery enable rapid deployment at seasonal fertilizer distribution points.
- Stationary:Fixed refrigerated storage spheres anchor export terminal infrastructure with multi-decade service horizons.
Installed base dominance belongs to Above Ground; Underground configurations are climbing the fastest.
Capacity:
Customer type and volume scale create distinct procurement channels from agricultural retail to integrated chemical manufacturing.
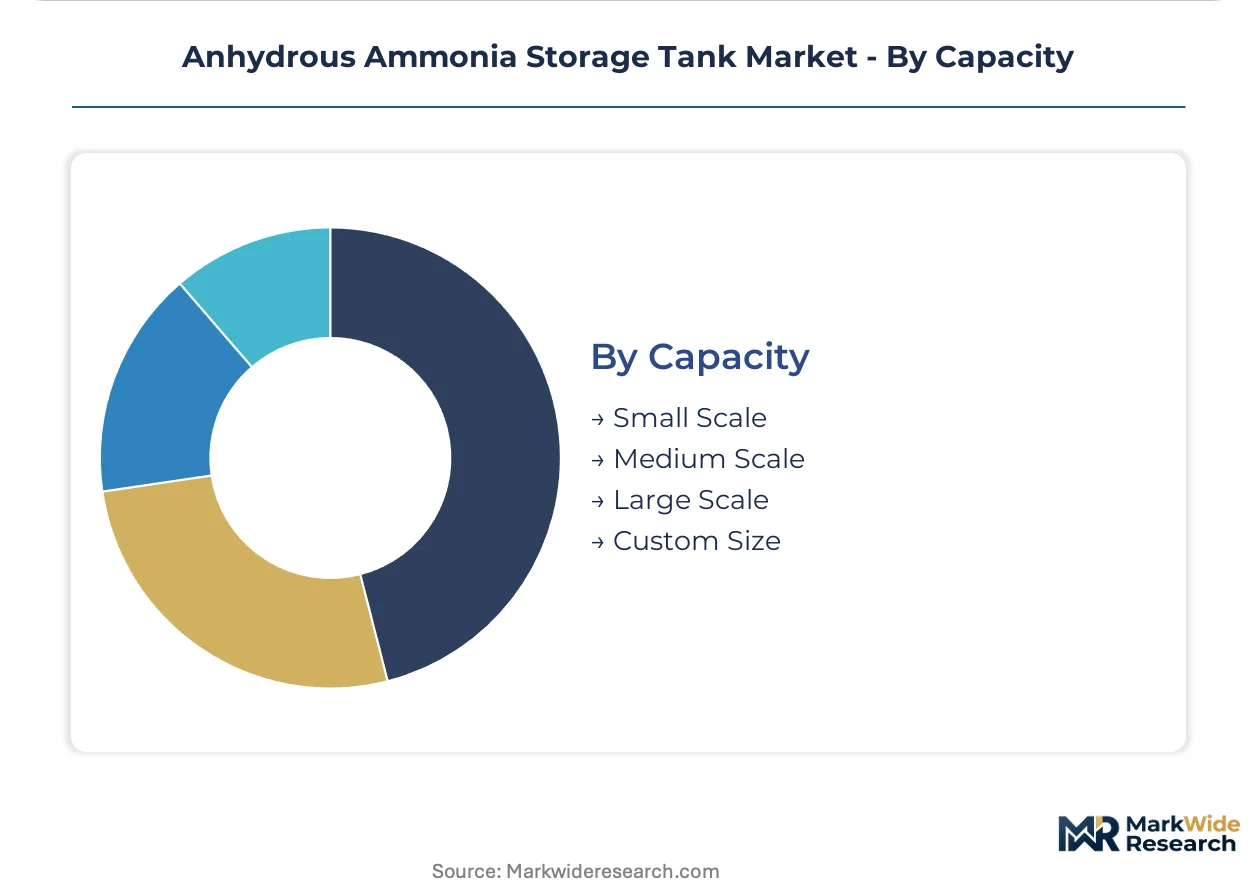
- Small Scale:Tanks below 5,000-gallon capacity serve farm-level nurse tank applications and food processing refrigeration circuits. Regional fabricators compete on delivery speed to agricultural co-ops with seasonal procurement windows.
- Large Scale:Refrigerated spherical tanks exceeding 50,000-ton capacity anchor Gulf Coast export terminals. Turnkey EPC contracts bundle these with vapor recovery and safety instrumentation for ammonia trading hub development.
- Medium Scale:Horizontal bullets in the 5,000-30,000-gallon range dominate wholesale fertilizer terminal operations.
- Custom Size:Non-standard dimensions accommodate site-specific constraints at retrofit projects.
Unit volume concentrates in Small Scale; project value aggregation favors Large Scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates ammonia consumption through corn belt agriculture, while production concentrates along the Gulf Coast petrochemical corridor. This geographic split between demand centers and supply infrastructure shapes storage tank procurement patterns across distinct regional markets.
United States
Iowa and Illinois agricultural co-ops drive horizontal tank replacement cycles as EPA Risk Management Plan amendments mandate enhanced leak detection. OSHA Process Safety Management standards govern above-ground installations in Nebraska and Kansas. The Houston Ship Channel anchors Gulf Coast export terminal development where refrigerated spherical storage complexes serve ammonia trading hub expansion.
Brazil
Corn and soybean belt expansion in Mato Grosso and Goiás generates port terminal demand at Santos and Paranaguá. ANVISA and environmental licensing requirements govern chemical storage facility permitting. The country's fertilizer import dependency creates concentrated procurement for refrigerated ammonia infrastructure serving agricultural frontier development.
Germany
Chemical producers in Ludwigshafen and Leverkusen operate legacy ammonia storage requiring mechanical integrity program upgrades under REACH and Seveso III directives. The country's hydrogen-ammonia import strategy for energy transition reshapes terminal specifications at Wilhelmshaven and Hamburg. Industrial clusters along the Rhine corridor drive demand for ASME-equivalent pressure vessel replacements.
India
Urea fertilizer subsidies sustain ammonia storage demand across Gujarat and Maharashtra industrial corridors. The Petroleum and Explosives Safety Organisation mandates pressure vessel inspection protocols for fertilizer manufacturing complexes. Dahej and Hazira petrochemical zones concentrate procurement for large-capacity refrigerated terminals serving domestic nitrogen production.
Saudi Arabia
Jubail Industrial City hosts integrated ammonia export infrastructure with storage specifications governed by SASO and Royal Commission for Jubail and Yanbu standards. The kingdom's blue ammonia export ambitions drive spherical tank investments at Ras Al-Khair. SABIC-affiliated complexes anchor procurement for cryogenic storage systems serving Asian fertilizer markets.
Anhydrous Ammonia Storage Tank Market Competitive Landscape
The competitive structure tilts toward engineering-procurement-construction integrators capable of delivering turnkey refrigerated complexes. Tier-one contractors dominate Gulf Coast export terminal awards through bundled safety instrumentation and pre-commissioning services. Three archetypes define positioning: cryogenic equipment specialists leveraging liquefied gas heritage, regional fabricators serving agricultural distribution networks, and EPC contractors absorbing full project risk. Consolidation pressure intensifies as ammonia-hydrogen co-storage specifications favor integrated technology providers over component suppliers.
Among European-headquartered engineering groups, Linde Engineering and thyssenkrupp Uhde GmbH occupy positions anchored by cryogenic process technology heritage. McDermott represents the EPC-contractor archetype with project execution capabilities for demanding above-ground installations. These three exemplify how fabrication scale and process integration depth determine competitive positioning as power-to-ammonia projects reshape procurement criteria.
| Leading Market Players |
|---|
| Highberg Solutions |
| Linde Engineering |
| Assmann Corporation |
| Geldof |
| McDermott |
| Balmoral Tanks Ltd. |
| Chart Industries |
| thyssenkrupp Uhde GmbH |
| Meridian Manufacturing Inc |
| Others |
Pricing and Supply Chain Analysis
Post-weld heat treatment advances in carbon steel fabrication are compressing cost economics for wet ammonia service while concentrating procurement leverage among ASME-certified fabricators with in-house thermal processing capabilities. This metallurgical transition simultaneously extends tank service life and raises barriers for regional competitors lacking capital-intensive heat treatment infrastructure.
Pricing Analysis
Margin tightening in mid-scale horizontal tank procurement reflects nickel and molybdenum alloy volatility pressuring fabricators serving Iowa and Illinois agricultural co-ops. Three-tier pricing structure across premium, standard, and economy levels separates ASME Section VIII Division 1 certified spheres with distributed sensing from baseline carbon steel bullets and rotationally molded polyethylene mini tanks. Cost compression accelerates in standard-tier horizontal vessels as qualified welder scarcity extends delivery timelines and forces expediting premiums. Agricultural distributors exhibit highest price sensitivity due to seasonal capital constraints, while Gulf Coast petrochemical terminals prioritize vapor recovery integration over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from nitrogen fertilizer producers are fragmenting fabrication contracts between US Gulf Coast specialists and European cryogenic equipment heritage firms. Supply concentration centers on Texas, Louisiana, and Iowa for pressure vessel fabrication, with specialty alloy feedstock drawing from German and Japanese metallurgical suppliers. Nickel-molybdenum steel plate dependency creates tariff exposure as trade policy shifts affect specialty alloy pricing. Distribution runs through EPC contractors bundling tank-instrumentation packages for greenfield export terminals, compressing direct procurement channels for component suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASME-certified welder scarcity across the Midwest agricultural belt props pricing power for fabricators with captive training pipelines, creating a supply-constrained market structure favoring incumbents with workforce development infrastructure.
For Market Incumbents: Lock in long-term offtake agreements with Iowa and Illinois co-ops before EPA Risk Management Plan amendments accelerate replacement demand. Defensive consolidation should prioritize acquiring regional fabricators with established welder apprenticeship programs to neutralize workforce scarcity threats. Vertical integration into post-weld heat treatment services captures margin currently leaking to third-party thermal processors. For New Entrants and Emerging Players: Brazilian fertilizer import infrastructure at Santos and Paranaguá represents an underserved buyer archetype with limited domestic fabrication capacity and urgent port modernization timelines. White-space opportunity concentrates in modular skid packaging with pre-integrated vapor recovery and safety instrumentation, reducing field construction duration for greenfield terminals. Go-to-market positioning should emphasize rapid deployment capabilities versus incumbent engineering-procurement-construction timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by cryogenic equipment specialists seeking ammonia-hydrogen co-storage capabilities. Long-term viability favors fabricators with demonstrated hydrogen compatibility testing and power-to-ammonia project references. Acquisition target archetype: mid-scale horizontal tank specialists with EPA Risk Management Plan compliance consulting capabilities. The signal to watch is hydrogen-ammonia blending ratio specifications in emerging energy transition storage standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Captive nickel-molybdenum steel sourcing insulates margins from commodity volatility and tariff exposure. |
| Hydrogen-Ammonia Co-Storage Certification | ASME-equivalent testing for hydrogen compatibility opens power-to-ammonia project procurement channels. |
| Modular Skid Packaging with Vapor Recovery | Pre-assembled tank-instrumentation bundles compress field construction duration for Gulf Coast terminals. |
| ASME-Certified Welder Apprenticeship Programs | Captive workforce development neutralizes Midwest fabrication bottleneck and accelerates delivery timelines. |
| OSHA Process Safety Management Integration Services | Recurring mechanical integrity program revenue extends customer lifetime value beyond equipment sales. |
Research Methodology
Independent corroboration across plant managers at nitrogen fertilizer facilities, procurement leads at agricultural co-ops, EPC contractors, and aftermarket service heads underwrites the qualitative findings in this analysis. Primary interviews with pressure vessel welders and technical R&D directors at cryogenic equipment specialists were cross-referenced against customs and trade data, American Chemistry Council reports, SEC 10-K filings from disclosed chemical producers, and state-level EPA Risk Management Plan enforcement records. Bottom-up tank unit economics were triangulated against top-down ammonia consumption forecasts.
Comparable-period anchoring linked the projection horizon to historical replacement cycles observed through EPA enforcement data and OSHA Process Safety Management inspection intervals. The analytical framework modeled segmentation across tank orientation, installation type, capacity tier, and end-use toxicity exposure level throughout the forecast period. CAGRs were derived from installed base aging analysis and regulatory amendment implementation timelines. Industry-specific forecast inputs included hydrogen-ammonia co-storage specification evolution and Brazilian port terminal modernization schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hydrogen carrier adoption rates and power-to-ammonia project financing availability. Deviation in ASME Section VIII Division 1 state amendment harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Ionophores Market
Industrial Chemicals
Swimming Pool Salt Chlorinator Market
Industrial Chemicals
Ferric Chloride As Etchant Market
Industrial Chemicals
2-Ethoxy Propene Market
Industrial Chemicals
Global Ethylene Carbonate Market
Industrial Chemicals
2,3-Butanediol Market
Industrial Chemicals
Pelletized Activated Carbon Market
Industrial Chemicals
Diesel Exhaust Fluid Market
Industrial Chemicals
Multi Component Injection Moulding Technology Market
Industrial Chemicals
Mass Finishing Consumables Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Global CMP Slurry Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Knitting Oils Market