
 Permeate Market | 2026-2036
Permeate Market Size, Share, and Industry Trends Forecast 2026-2036
Permeate Market Analysis
Asset-light toll processing and third-party membrane filtration leasing is narrowing the capital barrier for mid-sized dairy cooperatives seeking permeate capacity. Glanbia Ingredients leverages its integrated whey processing network across Ireland and the United States to sustain volume leadership in whey permeate powders. Arla Foods Ingredients anchors its competitive position through backward integration into Scandinavian milk supply pools, while Lactalis Ingredients dominates southern European permeate distribution through its captive dairy collection infrastructure.
Permeate denotes the liquid fraction remaining after ultrafiltration removes proteins and fats from milk or whey, typically containing 75-85 percent lactose along with minerals and non-protein nitrogen compounds; manufacturers spray-dry this stream into hygroscopic powders for use as economical bulking agents, flavor carriers, and browning agents in processed foods. Milk permeate occupies the largest volume share among product types due to its seamless substitution for skim milk powder in cost-sensitive bakery and confectionery applications, whereas whey permeate registers the fastest expansion as sports nutrition and infant formula manufacturers seek standardized lactose sources. Within applications, dairy products command the deepest margin pool because permeate's mineral profile enhances texture in processed cheese spreads and fermented beverages.
The United States Food and Drug Administration maintains permeate within its Standard of Identity regulations for dairy products, while the European Food Safety Authority evaluates novel permeate applications under expanded use petitions; these frameworks determine labeling permissibility and directly shape which product categories manufacturers can target. China's National Medical Products Administration and its national food safety standards impose residual protein thresholds that influence export-oriented processing configurations. Stakeholders must monitor evolving mineral content specifications across jurisdictions to preempt reformulation costs and secure multi-regional market access.
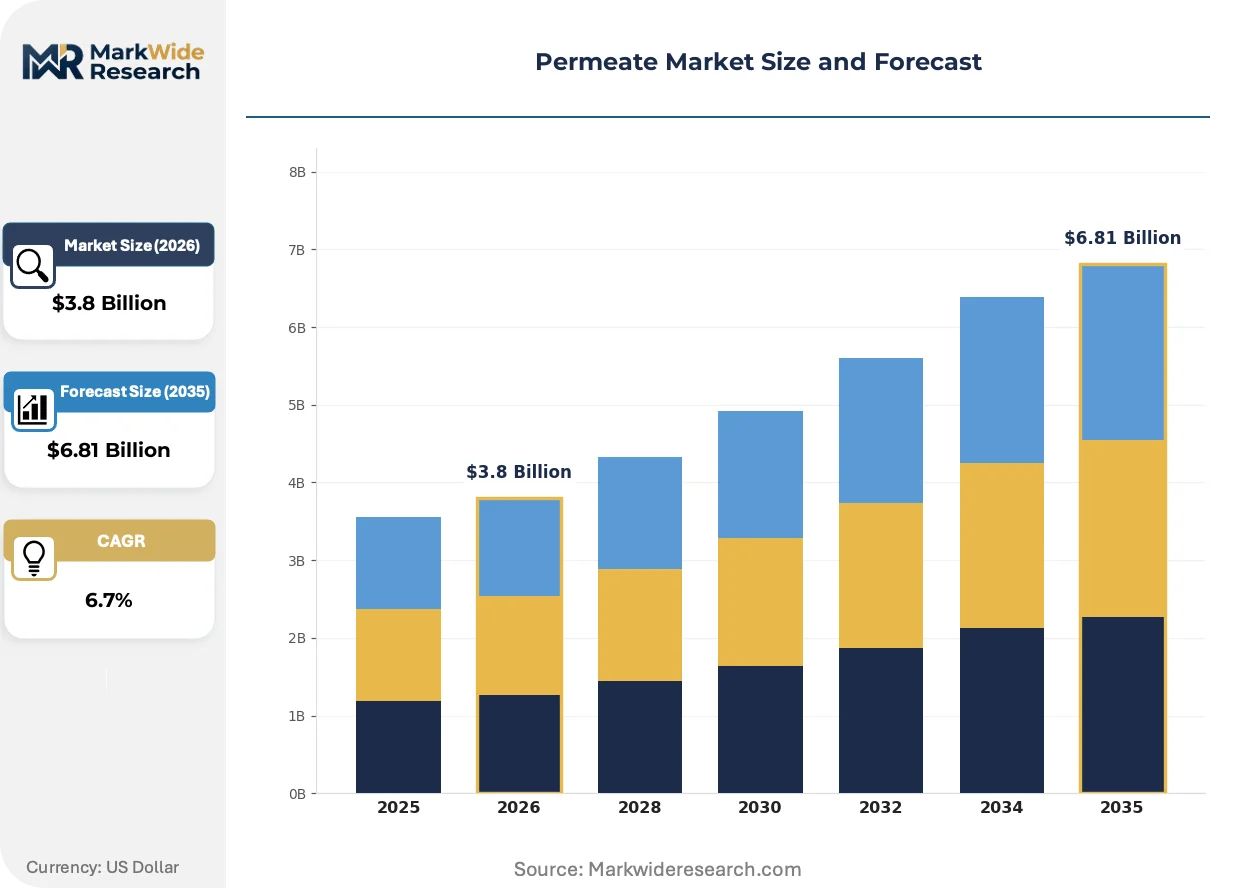
Market Dynamics
The European Union's F-Gas Regulation is compressing capital deployment timelines for membrane filtration retrofits, forcing dairy processors to front-load energy-efficient equipment upgrades ahead of 2030 phase-down targets.
Growth Catalysts
- Decarbonization mandates:The EU Green Deal and national carbon border adjustments incentivize permeate adoption as a lower-carbon bulking agent versus spray-dried alternatives requiring intensive thermal processing.
- Dairy reformulation wave:Processed cheese and fermented beverage manufacturers substitute permeate solids for skim milk powder to reduce raw material costs without altering mineral-driven texture profiles.
- Membrane technology maturation:Spiral-wound ultrafiltration modules with improved lactose transmission rates now achieve 85 percent permeate recovery, expanding viable feedstock economics for mid-scale processors.
Market Restraints
- Input cost volatility:Natural gas price swings directly destabilize spray-drying economics, compressing margins for permeate powder producers without long-term fuel hedging.
- Supply concentration risk:Scandinavian milk supply pools dominate high-quality milk permeate feedstock, creating geographic vulnerability for buyers dependent on Arla Foods Ingredients' backward-integrated network.
- Residual protein thresholds:China's NMPA national food safety standards impose strict compositional limits that disqualify suboptimal ultrafiltration configurations from export eligibility.
Strategic Opportunities
- Underpenetrated bakery segment:Artisan and industrial bakeries in Germany remain below 30 percent permeate penetration for browning and Maillard reaction applications, presenting volume expansion potential.
- Regulatory tailwind:The EU's Corporate Sustainability Reporting Directive creates disclosure pressure that favors permeate's favorable lifecycle carbon footprint versus conventional dairy ingredients.
- Technology convergence:Integration of inline near-infrared sensors with automated membrane cleaning protocols reduces protein leakage and improves permeate standardization for infant formula manufacturers.
Industry Challenges
- Membrane operator skill scarcity:Qualified technicians for transmembrane pressure optimization and fouling mitigation remain concentrated in Ireland and Denmark, constraining facility expansion in peripheral markets.
- Capex intensity for food-grade drying:Hygienic spray-dryer installations with CIP capabilities require substantial upfront investment, limiting toll processing options for smaller dairy cooperatives.
- Multi-jurisdictional labeling complexity:Divergent FDA Standard of Identity and EFSA expanded use petition timelines create reformulation lag, delaying product launches across Atlantic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Permeate Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Permeate, Milk Permeate, Casein Permeate, Vegetable Permeate Application: Dairy Products, Bakery Products, Nutraceuticals, Animal Feed Form: Powder, Liquid, Concentrate, Granulate End User: Food & Beverage Industry, Pharmaceutical Industry, Animal Nutrition, Cosmetics |
| Companies Covered | Idaho Milk Products, Hoogwegt Group, Agropur Ingredients, Glanbia Ingredients, Proliant Dairy Ingredients, Arla Foods Ingredients, Arion Dairy Products, Volac Feeds Limited, Lactalis Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Permeate Market Emerging Trajectories
Electrodialysis demineralization and ceramic membrane cascades are redefining permeate quality tiers, enabling precision mineral profiles that unlock premium application segments previously reserved for pharmaceutical-grade lactose.
Electrodialysis demineralization technology is collapsing the traditional quality gap between food-grade and pharmaceutical-grade permeate streams. Infant formula manufacturers in the Netherlands and Germany now specify ED-treated permeate for mineral-standardized lactose sources. This capability compression eliminates the historical 40-60 percent price premium for pharma-grade material, redistributing margin across the value chain.
The EU F-Gas Regulation's hydrofluorocarbon phase-down timeline is accelerating membrane system replacement cycles among large-scale dairy cooperatives. Processors face stranded asset risk on refrigeration-dependent drying infrastructure, redirecting capital toward ambient-temperature membrane concentration. German equipment fabricators report order backlogs stretching 18-24 months for integrated membrane-RO systems compliant with 2027 benchmarks.
Sports nutrition brands are consolidating supplier relationships around certified permeate streams with documented mineral consistency and residual protein specifications. Bulk ingredient distributors now bundle third-party laboratory certification with volume contracts, displacing spot-market purchasing for whey permeate. This preference shift concentrates procurement leverage among toll processors with captive analytical capabilities, most visible in the United States whey processing corridor.
Permeate Market Segmentation
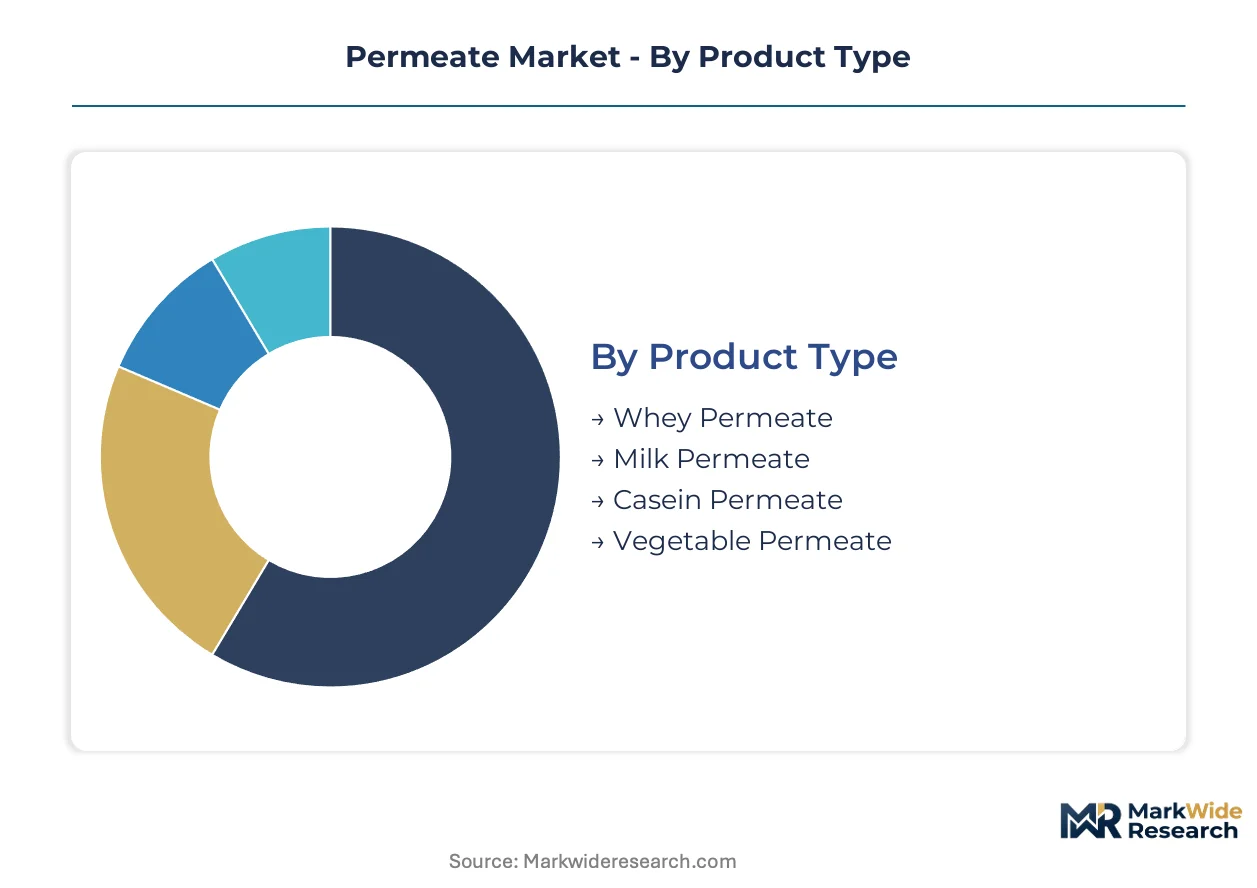
Permeate segmentation reveals divergent margin structures across feedstock origins and downstream specifications. Powder form factors and dairy applications command premium positioning, while liquid concentrates and animal feed channels absorb volume at compressed economics. Understanding these tiered value pools shapes capital allocation for membrane filtration investments.
Product Type:
Inventory velocity varies sharply by lactose purity and mineral standardization requirements. Whey permeate cycles fastest through sports nutrition procurement pipelines, while vegetable permeate sits longest in specification validation queues.
- Milk Permeate:Contains 75-85 percent lactose with native mineral profiles intact, spray-dried into hygroscopic powders for cost-sensitive bakery and confectionery substitution. German dairy cooperatives anchor procurement volumes for processed cheese reformulation where mineral-driven texture enhancement justifies specification premiums.
- Whey Permeate:Derived from cheese whey ultrafiltration with standardized protein residuals below 2 percent, positioned for infant formula and sports nutrition lactose sourcing. Netherlands and German manufacturers specify electrodialysis-dematerialized grades, collapsing historical quality premiums through technology maturation.
- Casein Permeate:Byproduct of micellar casein isolation with distinct mineral ratios suited for specialized animal nutrition formulations.
- Vegetable Permeate:Emerging category from plant protein extraction, awaiting EFSA novel food determinations for broad food-grade permissibility.
Milk permeate dominates installed base. Whey permeate is where expansion concentrates.
Application:
Margin capture stratifies by formulation complexity and regulatory scrutiny intensity. Dairy applications sustain deepest value pools through mineral functionality premiums, while animal feed channels compete on delivered cost per lactose unit.
- Dairy Products:Processed cheese spreads and fermented beverages leverage permeate's calcium-magnesium profile for texture stabilization without skim milk powder cost structures. Arla Foods Ingredients' backward-integrated Scandinavian supply anchors European procurement for this specification-critical segment.
- Bakery Products:Maillard reaction acceleration and browning control in industrial cracker and biscuit production, with German artisan bakeries below 30 percent penetration presenting volume expansion headroom.
- Nutraceuticals:Mineral-standardized lactose for prebiotic formulations and excipient applications, constrained by pharmaceutical-grade certification requirements.
- Animal Feed:Calorie-dense carbohydrate source for ruminant and swine nutrition, competing with dextrose and molasses on metabolizable energy pricing.
Dairy products command specification premiums. Bakery products are gaining share fastest.
Form:
Conversion economics and logistics density determine form selection across customer scale tiers. Powder commands shelf stability premiums, while liquid and concentrate forms reduce energy intensity in regional distribution.
- Powder:Hygroscopic spray-dried product with 24-month stability, dominating export-qualified shipments and long-haul distribution. Hygienic dryer capital requirements concentrate production among toll processors with CIP-capable installations.
- Liquid:Unconcentrated permeate stream for regional dairy processor integration, eliminating spray-drying energy costs but constraining radius to chilled distribution networks.
- Concentrate:Reverse osmosis reduced water content for intermediate logistics efficiency, common in intra-European bulk movement.
- Granulate:Agglomerated low-dust format for automated handling in large-scale bakery and feed milling operations.
Powder dominates installed base. Liquid is where expansion concentrates.
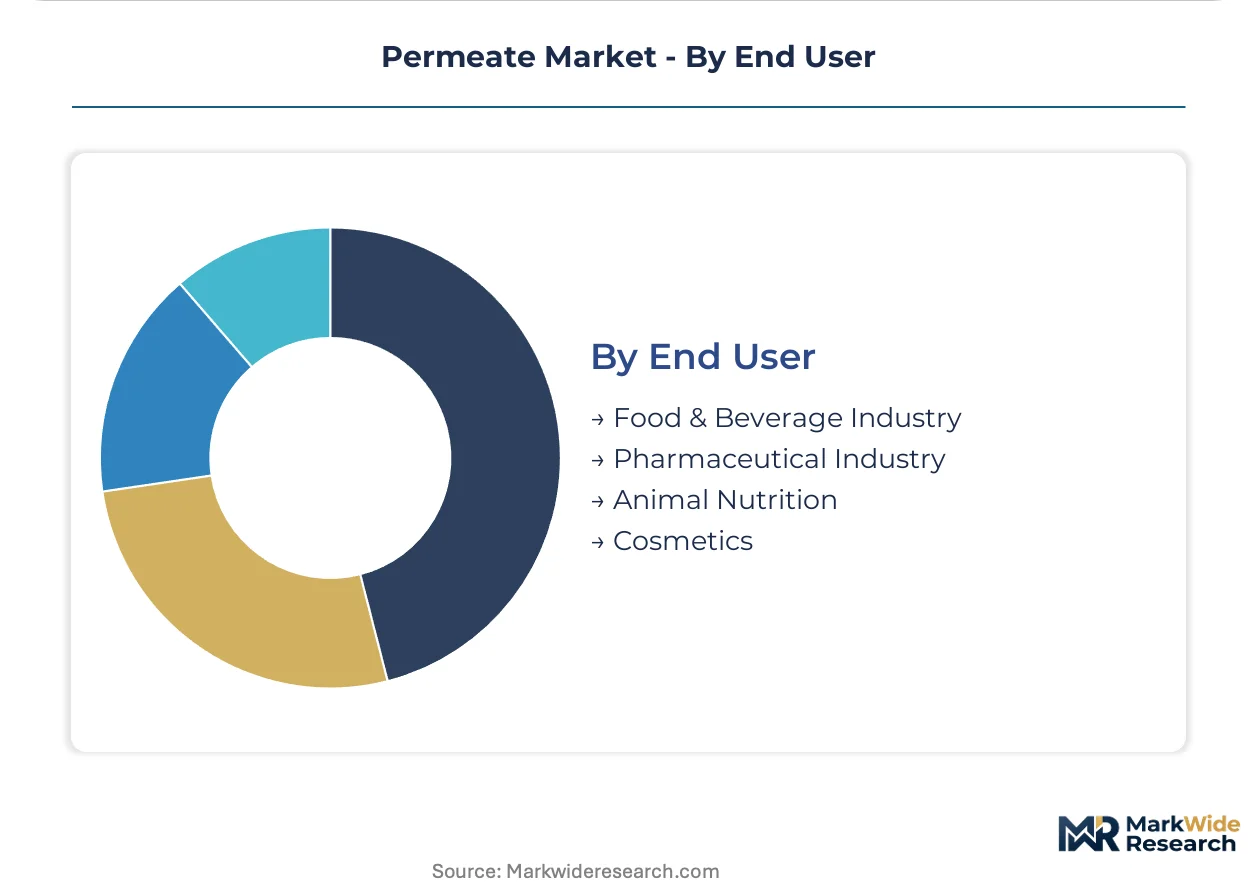
End User:
Procurement sophistication varies by sector quality assurance maturity. Pharmaceutical and infant formula channels impose certificate-of-analysis requirements that filter supplier bases, while animal nutrition prioritizes volume consistency.
- Food & Beverage Industry:Largest volume sink spanning processed cheese, bakery, and beverage applications, with reformulation waves driving substitution economics.
- Pharmaceutical Industry:Excipient-grade lactose for tablet binding and inhaler formulations, requiring residual protein thresholds below 0.1 percent and documented mineral consistency.
- Animal Nutrition:Ruminant feed energy supplementation, with procurement consolidated among compound feed manufacturers.
- Cosmetics:Humectant and bulking agent applications in personal care, marginal volume relative to food-grade channels.
Food and beverage dominates installed base. Pharmaceutical is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Scandinavian milk supply pools while German dairy cooperatives extract volume discounts through backward-integrated procurement networks. This asymmetry redistributes margin toward feedstock-controlling geographies and compresses returns for toll-dependent processors.
Germany
Large-scale dairy cooperatives in Bavaria and Lower Saxony anchor European permeate procurement volumes for processed cheese reformulation. The EU F-Gas Regulation accelerates membrane filtration retrofits ahead of 2030 phase-down targets. Ingredient processors in the Münsterland cluster invest in electrodialysis-equipped facilities to serve infant formula manufacturers.
United States
Sports nutrition brands in the Mountain West and Midwest consolidate supplier relationships around certified whey permeate streams. FDA Standard of Identity regulations determine labeling permissibility for dairy product reformulation. The Wisconsin-Idaho whey processing corridor hosts toll processors with captive analytical capabilities.
Netherlands
Infant formula manufacturers specify electrodialysis-dematerialized permeate grades for mineral-standardized lactose sourcing. The EU Green Deal incentivizes adoption as lower-carbon bulking agents versus thermally intensive alternatives. Rotterdam-area ingredient distributors bundle third-party laboratory certification with volume contracts.
China
Export-oriented processors configure ultrafiltration systems to meet NMPA residual protein thresholds for food safety compliance. National dual carbon goals pressure domestic dairy ingredient producers toward energy-efficient membrane concentration. Yangtze River Delta dairy hubs import specification-critical permeate for bakery and confectionery applications.
Ireland
Integrated whey processing networks sustain volume leadership in whey permeate powders for international markets. Qualified technicians for transmembrane pressure optimization remain concentrated in the Cork-Dublin corridor, constraining facility expansion elsewhere. Irish processors leverage EU Corporate Sustainability Reporting Directive disclosure pressure to position permeate's favorable lifecycle carbon footprint.
Permeate Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in membrane module fabrication and analytical certification. The vendor base stratifies across three tiers: backward-integrated dairy cooperatives with captive feedstock, toll processors with hygienic spray-dryer assets, and ingredient distributors bundling third-party laboratory validation. Two dominant competitive moves are reshaping positioning: M&A activity consolidates regional membrane filtration capacity, and strategic partnerships between equipment fabricators and dairy cooperatives reduce capital barriers for mid-scale processors.
Within the backward-integrated tier, Glanbia Ingredients and Arla Foods Ingredients exemplify contrasting geographic anchoring strategies. Glanbia leverages its network across Ireland and the United States to sustain volume leadership in whey permeate powders. Arla occupies a position anchored in Scandinavian milk supply pools for specification-critical dairy applications. Lactalis Ingredients represents the southern European vector, dominating distribution through captive dairy collection infrastructure. These three archetypes illustrate how feedstock control, processing asset location, and regional regulatory alignment determine competitive positioning.
| Leading Market Players |
|---|
| Idaho Milk Products |
| Hoogwegt Group |
| Agropur Ingredients |
| Glanbia Ingredients |
| Proliant Dairy Ingredients |
| Arla Foods Ingredients |
| Arion Dairy Products |
| Volac Feeds Limited |
| Lactalis Ingredients |
| Others |
Supply Flow & Price Mechanics
Bavarian dairy cooperatives in southern Germany concentrate membrane filtration capacity for electrodialysis-dematerialized grades, translating captive milk supply into specification premiums for infant formula manufacturers while compressing margins for toll-dependent processors in peripheral markets.
Pricing Analysis
Configured-to-order pricing for electrodialysis-dematerialized permeate commands a 15-25 percent premium over standard spray-dried powders, with differentiation driven by residual protein certification and mineral standardization protocols. Three-tier pricing structure across premium, standard, and economy levels stratifies by lactose purity and end-use regulatory scrutiny, with pharmaceutical-grade specifications absorbing the deepest margin pools. Pricing pressure stems from natural gas cost volatility destabilizing spray-drying economics, forcing producers without long-term fuel hedging into cost compression. Animal feed buyers exhibit highest price sensitivity, competing on delivered cost per lactose unit against dextrose and molasses substitutes, while infant formula manufacturers prioritize specification consistency over unit economics.
Supply Chain Analysis
Scandinavian milk supply pools in Denmark and Sweden anchor high-quality milk permeate feedstock, while the United States whey processing corridor and Netherlands infant formula hubs concentrate whey permeate conversion. Raw material dependencies center on fluid milk collection networks, cheese whey availability from cheddar and mozzarella production, and ceramic membrane modules for ultrafiltration cascades. Single-source vulnerability concentrates in Arla Foods Ingredients' backward-integrated Scandinavian network, creating geographic exposure for specification-critical dairy applications. Distribution runs through Rotterdam-area ingredient distributors bundling third-party laboratory certification with volume contracts, displacing spot-market purchasing for certified permeate streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among sports nutrition brands and infant formula manufacturers consolidating supplier relationships around certified permeate streams, fragmenting procurement leverage away from spot-market dependent toll processors.
For Market Incumbents: Pre-empt membrane operator skill scarcity by securing qualified technicians for transmembrane pressure optimization through training partnerships with Danish technical institutes or acquisition of Ireland-based specialist teams. Defend margin position against electrodialysis technology maturation collapsing quality premiums by investing in inline near-infrared sensor integration for automated membrane cleaning protocols that reduce protein leakage and improve standardization. For New Entrants and Emerging Players: Build out toll processing capacity in Germany's Münsterland cluster to serve underpenetrated artisan bakeries below 30 percent permeate adoption for browning and Maillard reaction applications. Target the bakery segment through volume-based pricing contracts with industrial cracker and biscuit manufacturers seeking cost-effective skim milk powder substitutes, leveraging asset-light membrane filtration leasing to narrow capital barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from dairy cooperatives seeking to monetize captive membrane filtration assets without full vertical integration into ingredient distribution. Long-term viability hinges on positioning within EU Green Deal carbon disclosure frameworks, with electrodialysis-equipped facilities commanding valuation premiums. Monitor EU F-Gas Regulation compliance timelines as an inflection indicator for stranded asset risk on refrigeration-dependent drying infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Milk Supply Pools | Arla Foods Ingredients anchors competitive positioning through Scandinavian feedstock control. |
| Electrodialysis Technology Deployment | Netherlands infant formula manufacturers specify ED-treated grades for mineral-standardized lactose sourcing. |
| Membrane Filtration Retrofit Programs | German dairy cooperatives front-load energy-efficient upgrades ahead of EU F-Gas phase-down targets. |
| Third-Party Laboratory Certification Bundling | Rotterdam-area distributors displace spot-market purchasing with documented mineral consistency guarantees. |
| Toll Processing Capacity Expansion | Asset-light leasing narrows capital barriers for mid-sized cooperatives seeking permeate powder output. |
Methodological Framework
Initial hypotheses were tested against primary input from membrane filtration plant managers, dairy cooperative procurement leads, infant formula manufacturer technical directors, and sports nutrition brand supply chain heads, and refined through secondary validation against EU F-Gas Regulation implementation documents, EFSA expanded use petition filings, FDA Standard of Identity regulations, and trade data from customs records. Bottom-up volume modeling from installed membrane capacity and top-down demand estimation from end-use sector consumption patterns were triangulated to constrain forecast ranges.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by feedstock origin, lactose purity grade, mineral standardization level, and end-use regulatory scrutiny intensity. CAGRs were derived from regression analysis of historical capacity expansion rates against projected reformulation adoption curves, with cross-validation against energy cost sensitivity scenarios and carbon border adjustment implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by backward-integrated dairy cooperatives or electrodialysis technology licensors would shift outcomes beyond modeled ranges. Cross-checking against EFSA novel food determination timelines and NMPA residual protein threshold revisions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Dipropylene Glycol (DPG) Market
Industrial Chemicals
Cobalt Acetate Solution Market
Industrial Chemicals
Paraffin Inhibitors Market
Industrial Chemicals
Drum Melters Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
South Africa Lime Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Multi Component Injection Moulding Technology Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Global Isocyanate Market
Industrial Chemicals
Global Itaconic Acid Market
Industrial Chemicals
Global Acid Proof Lining Market