
 Lignin Products Market | 2026-2036
Lignin Products Market Size, Share, and Industry Trends Forecast 2026-2036
Lignin Products Market Intelligence
Specialized biochemical engineering talent is redrawing competitive boundaries in lignin valorization. Borregaard leverages its century-long pulping heritage to dominate high-purity lignin output from its Sarpsborg complex. Stora Enso sustains an integrated biorefinery model that converts softwood Kraft streams into dispersant-grade material. Ingevity differentiates through sulfur-free lignin fractions tailored to carbon fiber precursor applications.
Lignin constitutes a complex phenolic polymer comprising p-coumaryl, coniferyl, and sinapyl alcohol units, typically recovered as a byproduct from chemical pulping or extracted via organosolv fractionation; its aromatic backbone and reactive functional groups position it as a renewable substitute for petroleum-derived phenols and polyols. Kraft lignin anchors the product mix through established recovery infrastructure at sulfate mills, while lignosulfonates retain volume leadership in concrete admixture and dust suppression applications where dispersant performance commands stable margins. Organosolv lignin represents the fastest-growing product category, as its low sulfur and high purity unlock bioplastics and carbon fiber precursor markets that demand consistent macromolecular architecture.
EPA bio-based product labeling requirements under the Federal BioPreferred Program shape procurement specifications for U.S. government contracts, while REACH registration obligations in Europe enforce compositional transparency for lignin derivatives sold into adhesive and coating formulations. The EU Green Deal's industrial emissions benchmarks further tighten process energy standards for Kraft lignin recovery operations. Stakeholders must monitor evolving carbon border adjustment mechanisms and decide whether to invest in sulfur-free extraction capacity or optimize incumbent sulfite process economics.
Market Dynamics
Bioplastics manufacturers are accelerating lignin adoption as petroleum-derived phenol substitutes, while REACH registration obligations in Europe enforce compositional transparency that favors suppliers with integrated pulp-to-chemical operations.
Growth Catalysts
- EU Green Deal industrial emissions benchmarks:Kraft lignin recovery operations face tightening process energy standards, advantaging mills with captive renewable power.
- Carbon fiber precursor demand:Sulfur-free lignin fractions unlock aerospace and automotive lightweighting applications requiring consistent macromolecular architecture.
- Rhineland chemical cluster concentration:Germany's integrated pulp-to-specialty chemical operations anchor supply security for adhesive and coating formulators.
Market Restraints
- Softwood Kraft feedstock dependency:Pulp mill capacity constraints in Nordic regions limit high-purity lignin expansion regardless of downstream demand.
- Organosolv capex intensity:Greenfield sulfur-free extraction facilities require capital deployment that sulfite process incumbents resist.
- Petroleum phenol price volatility:Crude oil fluctuations compress lignin substitution economics in polyol applications during low crude cycles.
Strategic Opportunities
- Concrete admixture grade arbitrage:Lignosulfonate producers can capture margin expansion in dust suppression applications where dispersant performance commands stable pricing.
- EPA Federal BioPreferred Program procurement specifications:U.S. government contract eligibility creates preferential offtake channels for bio-based adhesive suppliers.
- Carbon fiber precursor certification pipelines:Automotive OEMs are qualifying sulfur-free lignin fractions for composite structural components under NHTSA crashworthiness protocols.
Industry Challenges
- Biochemical engineering talent scarcity:Lignin valorization requires specialized expertise in phenolic polymer modification that pulp mill workforces lack.
- REACH registration timelines:Compositional disclosure obligations for lignin derivatives extend commercialization cycles for adhesive and coating formulations.
- Carbon border adjustment uncertainty:Stakeholders face investment paralysis deciding between sulfur-free extraction capacity and incumbent sulfite process optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lignin Products Market |
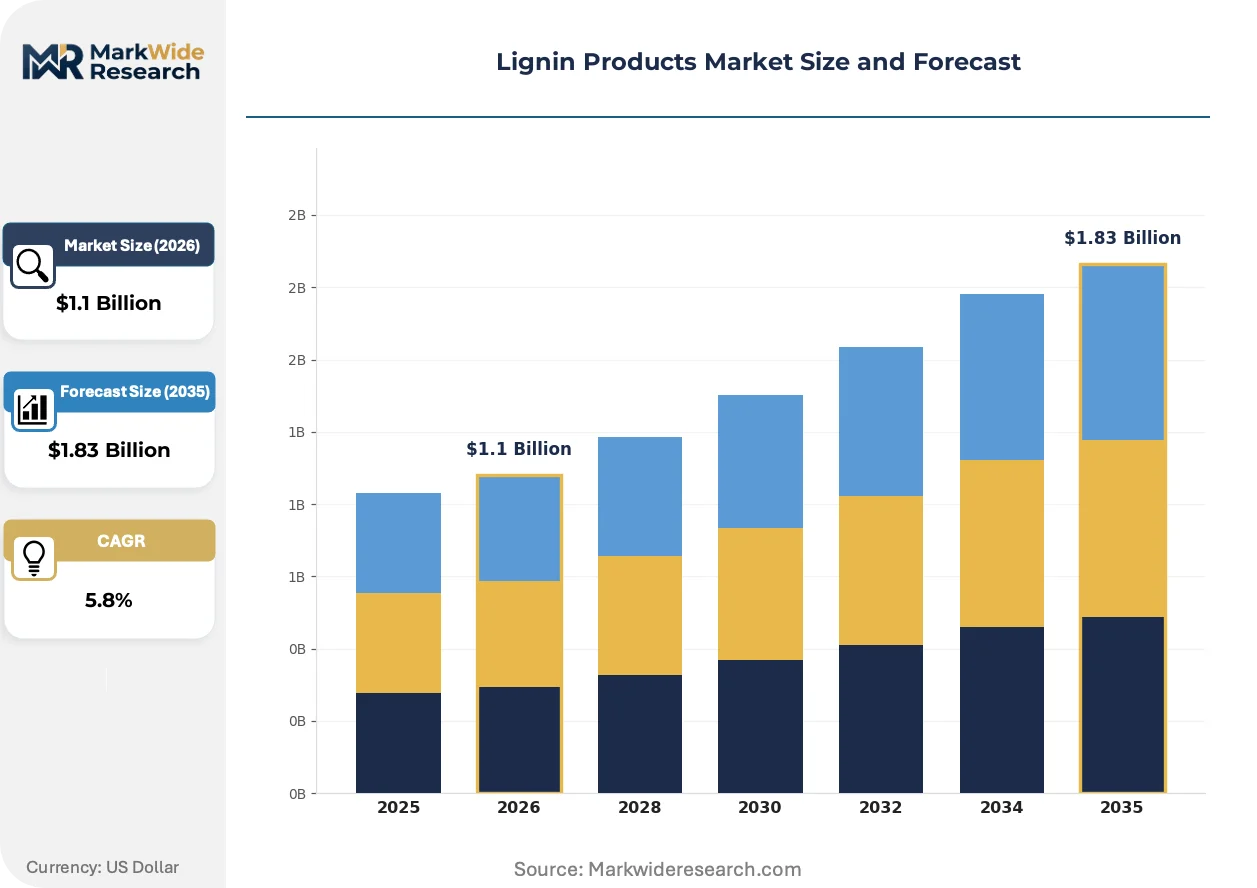
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $1.83 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
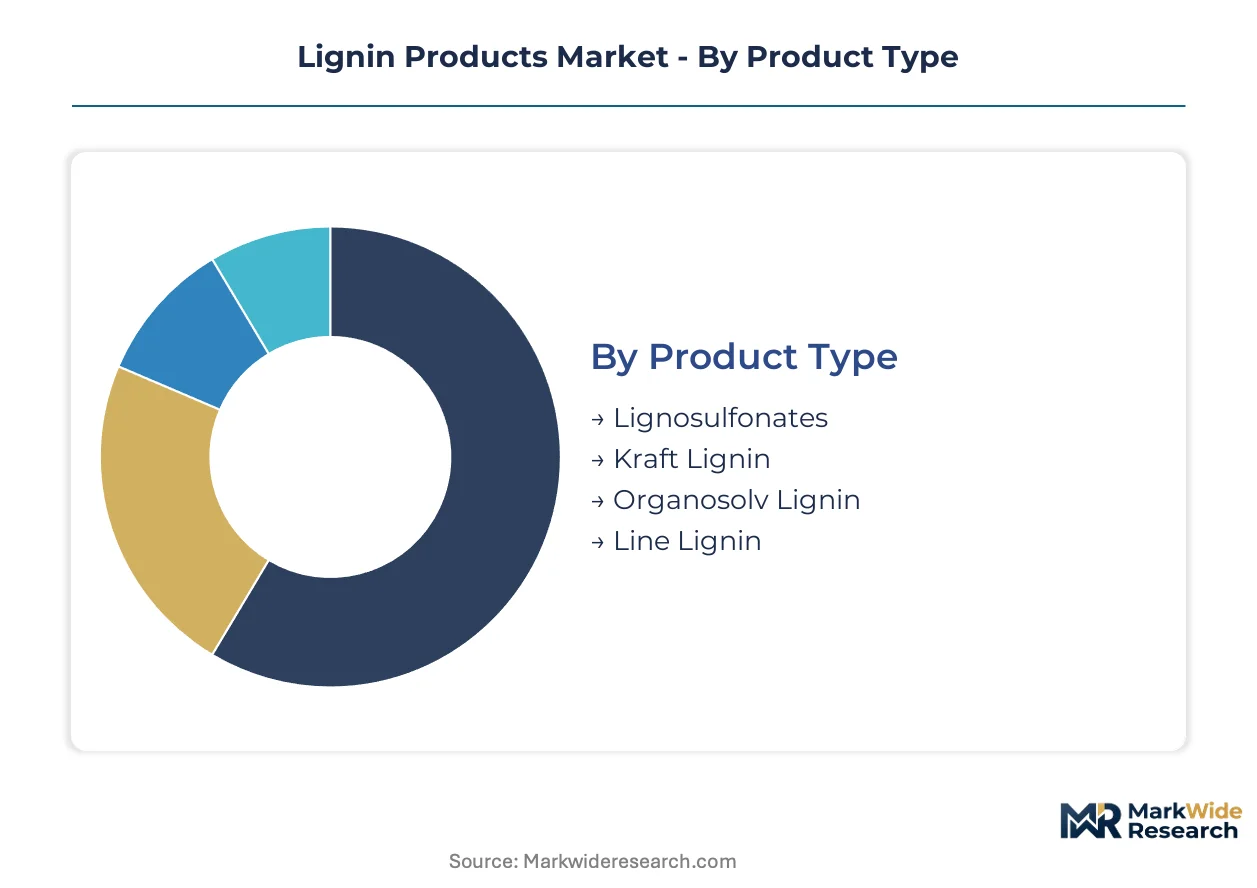
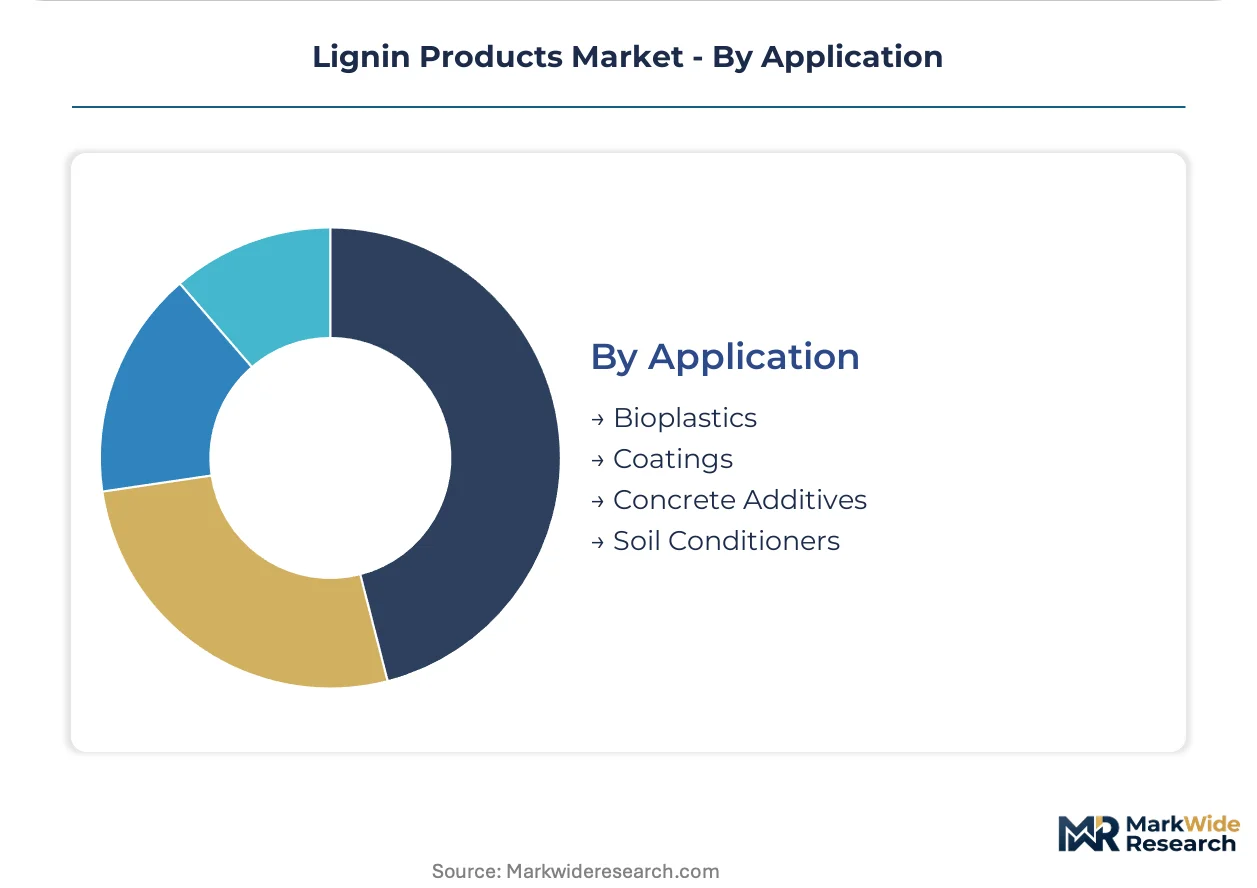
| Segmentation | Product Type: Lignosulfonates, Kraft Lignin, Organosolv Lignin, Line Lignin End Use Industry: Animal Feed, Pulp & Paper, Adhesives, Carbon Fiber Form: Powder, Liquid, Granular, Fibrous Application: Bioplastics, Coatings, Concrete Additives, Soil Conditioners |
| Companies Covered | Borregaard, Stora Enso, Domtar Corporation, Ingevity, UPM Biochemicals, Sappi Limited, Suzano, Rayonier Advanced Materials, Nippon Paper Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lignin Products Market Strategic Shifts & Innovations
Organosolv fractionation technology is splitting the competitive landscape between commodity lignosulfonate producers and high-purity specialty suppliers, with carbon fiber and bioplastics applications driving the divergence.
Organosolv lignin is bifurcating the product architecture of this market. The technology extracts low-sulfur, high-purity fractions suitable for carbon fiber precursor and bioplastics applications. Automotive and aerospace material buyers are accelerating qualification timelines for these grades. The structural consequence is compressing margins for commodity Kraft lignin while creating premium pricing tiers for consistent macromolecular architecture.
REACH registration obligations under ECHA enforcement are tightening compositional transparency requirements for lignin derivatives sold into European adhesive and coating markets. Manufacturers must disclose phenolic unit distributions and sulfur content specifications to maintain market access. German and French formulators are consolidating supplier relationships toward integrated pulp-to-chemical operations with captive analytical capabilities.
Specification-driven procurement is displacing spot-market purchasing for dispersant-grade material. Concrete admixture producers are locking multi-year offtake agreements with Nordic mills to secure lignosulfonate supply against pulp capacity volatility. This pattern is most visible in the Benelux construction chemicals sector, where dust suppression and water-reducer applications face seasonal demand spikes that spot markets cannot reliably serve.
Lignin Products Market Segmentation
Lignin product specifications diverge sharply across end-use requirements, with sulfur content and macromolecular purity determining market access. Regulatory thresholds under EPA and ECHA frameworks enforce compositional disclosure that fragments supply into distinct qualification tiers.
Product Type:
EPA bio-based labeling and ECHA REACH registration obligations create divergent compliance burdens across extraction chemistries.
- Lignosulfonates:Sulfonated derivatives from sulfite pulping carry high sulfur loads suited to concrete dispersants and dust suppression. Demand concentrates in German and Benelux construction chemicals where seasonal infrastructure spending requires reliable dispersant supply.
- Kraft Lignin:Recovered from black liquor via acid precipitation, this sulfate-derived material anchors volume production through established pulp mill infrastructure. Nordic integrated operations supply adhesive and coating formulators facing EU Green Deal emissions benchmarks.
- Organosolv Lignin:Low-sulfur, high-purity fractions from organic solvent extraction unlock carbon fiber precursor and bioplastics applications requiring consistent phenolic architecture.
- Line Lignin:Emerging classification for hydrolysis-derived material with intermediate purity profiles serving specialty polyol markets.
Established volume favors Kraft Lignin; emerging adoption favors Organosolv Lignin.
End Use Industry:
Application-specific performance thresholds sort lignin grades into distinct margin tiers.
- Animal Feed:Lignosulfonate binders pelletize feed rations under FDA and EFSA safety protocols. Demand clusters in US Midwest and Brazilian agribelt operations where pellet durability commands premium pricing.
- Pulp & Paper:Internal recycling of black liquor lignin for energy recovery dominates captive consumption. Nordic mills optimize this loop under tightening EU industrial emissions standards.
- Adhesives:Phenolic substitution in wood panel binders requires low-ash Kraft grades with controlled molecular weight distribution.
- Carbon Fiber:Aerospace and automotive OEMs under NHTSA and EASA protocols are qualifying sulfur-free lignin fractions for composite structural components.
Feed and pulp applications capture incumbent volume; carbon fiber qualification opens the steepest expansion trajectory.
Form:
Logistics economics and handling requirements shape procurement specifications across construction and agricultural channels.
- Powder:Standardized flow properties enable precise dosing in concrete batching and adhesive compounding. Dust control regulations favor dust-suppressed grades for US OSHA compliance.
- Liquid:Pumpable lignosulfonate concentrates reduce handling costs in ready-mix concrete operations. French and German admixture producers prefer liquid delivery for automated dosing systems.
- Granular:Low-dust handling suits animal feed pelleting and soil conditioner spreading equipment.
- Fibrous:Retained structural integrity benefits composite reinforcement and specialty filtration media.
Powder and liquid forms dominate commodity throughput; fibrous grades command specialty premiums.
Application:
Substitution economics against petroleum-derived alternatives determine addressable market depth.
- Bioplastics:Organosolv lignin replaces bisphenol-A and petroleum polyols in thermoset and thermoplastic formulations. German and Dutch compounders lead qualification under EU Single-Use Plastics Directive pressure.
- Coatings:UV-stable lignin derivatives serve protective and decorative finishes with bio-based content claims. ECHA disclosure requirements favor suppliers with integrated analytical capabilities.
- Concrete Additives:Lignosulfonate water reducers and retarders maintain volume leadership through proven performance in high-slump mixes.
- Soil Conditioners:Humic acid mimics from lignin support moisture retention and nutrient chelation in arid agriculture.
Concrete additives retain volume dominance; bioplastics substitution is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing for sulfur-free lignin concentrates in Germany's Rhineland chemical cluster contrasts sharply with commoditized lignosulfonate rates in Nordic bulk markets. This asymmetry reflects divergent regulatory stringency and end-use qualification thresholds across European and North American demand centers.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria are qualifying organosolv lignin for carbon fiber composite structural components. REACH registration obligations under ECHA enforcement mandate compositional transparency for adhesive and coating formulators. The Rhineland chemical cluster around Leverkusen and Düsseldorf anchors integrated pulp-to-specialty chemical operations with captive analytical capabilities.
United States
Concrete admixture producers in the Midwest and Southeast are locking multi-year offtake agreements for lignosulfonate supply against pulp capacity volatility. EPA bio-based product labeling requirements under the Federal BioPreferred Program shape procurement specifications for government contracts. Dust suppression applications in Texas and California oilfield operations command seasonal demand spikes.
Sweden
Nordic integrated mills optimize black liquor lignin recycling loops under tightening EU industrial emissions standards. Stora Enso's biorefinery operations in Värmland and Gävleborg convert softwood Kraft streams into dispersant-grade material. The Stockholm-Uppsala corridor concentrates biochemical engineering talent for phenolic polymer modification.
Brazil
Eucalyptus pulp producers in São Paulo and Minas Gerais are expanding lignosulfonate output for animal feed pellet binders serving agribelt operations. ANVISA safety protocols govern feed additive applications. The Santos port complex handles bulk export logistics for dust suppression and concrete admixture shipments to African and Middle Eastern markets.
Japan
Nippon Paper Industries and regional chemical formulators in the Kanto and Kansai regions are developing lignin-derived polyol substitutes for polyurethane applications. METI industrial standards and JIS certification requirements enforce consistent macromolecular architecture for automotive and electronics coatings. The Chubu region around Nagoya hosts composite material qualification laboratories.
Lignin Products Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes in this bifurcated market. Sulfite process incumbents dominate commodity lignosulfonate volume through established pulp mill infrastructure, while organosolv specialists capture premium tiers for carbon fiber and bioplastics applications. Two strategic archetypes define competitive positioning: integrated forest products conglomerates with captive feedstock security, and independent biochemical refiners with sulfur-free extraction capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as players navigate carbon border adjustment uncertainty.
Among Nordic integrated operators, Borregaard exemplifies the heritage-driven technology archetype through its century-long pulping operations. Stora Enso occupies a position bridging commodity and specialty tiers via its biorefinery model. Ingevity represents the independent biochemical specialist archetype with sulfur-free fractionation capabilities. These three anchors illustrate the market's structural divergence between volume-scale Kraft producers and purity-focused organosolv suppliers.
| Leading Market Players |
|---|
| Borregaard |
| Stora Enso |
| Domtar Corporation |
| Ingevity |
| UPM Biochemicals |
| Sappi Limited |
| Suzano |
| Rayonier Advanced Materials |
| Nippon Paper Industries |
| Others |
Cost & Logistics Intelligence
Scale economies at Nordic sulfate mills anchor price floors for commodity Kraft lignin while enabling premium capture for sulfur-free organosolv fractions. Capacity utilization across Germany's Rhineland cluster and Brazil's São Paulo agribelt directly shapes margin distribution between dispersant-grade bulk and carbon fiber precursor specialty tiers.
Pricing Analysis
Configured-to-order pricing for sulfur-free organosolv lignin commands spreads against standard Kraft lignin based on certification grade and customization level. Contract-based long-term offtake structures dominate concrete admixture procurement, while spot-market softness reflects petroleum phenol price volatility compressing substitution economics. Automotive OEMs exhibit least price sensitivity for aerospace-qualified carbon fiber precursor grades; construction chemical formulators in Benelux show highest sensitivity to lignosulfonate delivered cost.
Supply Chain Analysis
Container availability constraints on Baltic-Atlantic trade lanes elevate inbound logistics costs for Nordic mill exports to North American bioplastics compounders. Supply concentrates in Norway, Sweden, and Germany for high-purity fractions, with Brazil anchoring lignosulfonate volume for animal feed and dust suppression. Raw material dependency on softwood Kraft black liquor and sulfite pulping streams creates single-source vulnerability during pulp mill maintenance cycles. Distribution runs through integrated pulp-to-chemical operations with captive analytical capabilities serving REACH-compliant European formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. REACH registration timelines and ECHA compositional disclosure requirements create switching costs that lock adhesive and coating formulators into validated supplier relationships.
For Market Incumbents: Fortify captive feedstock security through backward integration into Nordic pulp mill capacity or long-term black liquor offtake agreements. Invest in sulfur-free extraction certification to defend margin position against organosolv specialists targeting carbon fiber precursor markets. Prioritize analytical capability expansion to accelerate REACH registration timelines for new lignin derivative formulations.
For New Entrants and Emerging Players: Technical service gaps in phenolic polymer modification for small-to-mid-size bioplastics compounders present white-space opportunity. Target German and Dutch thermoset formulators under EU Single-Use Plastics Directive pressure with organosolv lignin sampling programs. Pursue toll-manufacturing partnerships with Brazilian eucalyptus pulp producers to bypass greenfield capex barriers.
For Investors and Strategic Acquirers: Independent biochemical refiners with proven sulfur-free fractionation and automotive qualification pipelines represent the priority acquisition archetype. Long-term viability hinges on carbon border adjustment mechanism resolution favoring low-sulfur extraction economics. Monitor NHTSA crashworthiness certification timelines for lignin-based composite structural components as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Feedstock | Captive softwood Kraft supply secures margin stability against Nordic capacity constraints. |
| Sulfur-Free Extraction Capacity Buildout | Organosolv technology unlocks carbon fiber precursor markets under EASA qualification protocols. |
| Long-Term Supply Agreement with Automotive OEMs | Multi-year offtake contracts reduce qualification cycle risk for bioplastics substitution programs. |
| REACH Registration Acceleration Program | ECHA compliance investment compresses commercialization timelines for adhesive formulators. |
| Joint Venture with Brazilian Pulp Producers | Eucalyptus lignosulfonate access targets African and Middle Eastern dust suppression demand. |
Research Approach
A spread of perspectives from biorefinery operations managers, downstream adhesive formulators, carbon fiber procurement leads, and ECHA regulatory consultants converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from customs trade data, SEC pulp and paper sector filings, EU ETS emissions registries, and REACH registration databases. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates across the analysis window.
Segmentation dimensions modeled include extraction chemistry tier, sulfur content specification, end-use industry application, and regional regulatory cluster. CAGRs were derived through cross-referencing historical pulp mill output trends with downstream qualification pipeline visibility. Forecast inputs incorporated EU Green Deal industrial emissions benchmark trajectories and EPA Federal BioPreferred Program procurement specification evolution throughout the projection horizon.
Forecasts assume regulatory continuity in REACH enforcement and EPA bio-based labeling regimes; material policy shifts would require re-modeling. Commodity price volatility in petroleum phenol markets and carbon border adjustment mechanism finalization present specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
PEG and PPG Esters Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
Erucic Acid Market
Specialty Chemicals
Sodium Ascorbyl Phosphate (SAP) Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
Global Specialty Fuel Additives Market
Specialty Chemicals
Aerosol Cans Market
Specialty Chemicals
L-Ergothioneine Market
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
Barium Sulfate Market
Specialty Chemicals
Arginine Market
Specialty Chemicals
Alkoxide Market
Specialty Chemicals
Betulinic Acid Market