
 PEG and PPG Esters Market | 2026-2036
PEG and PPG Esters Market Size, Share, and Industry Trends Forecast 2026-2036
PEG and PPG Esters Market Outlook
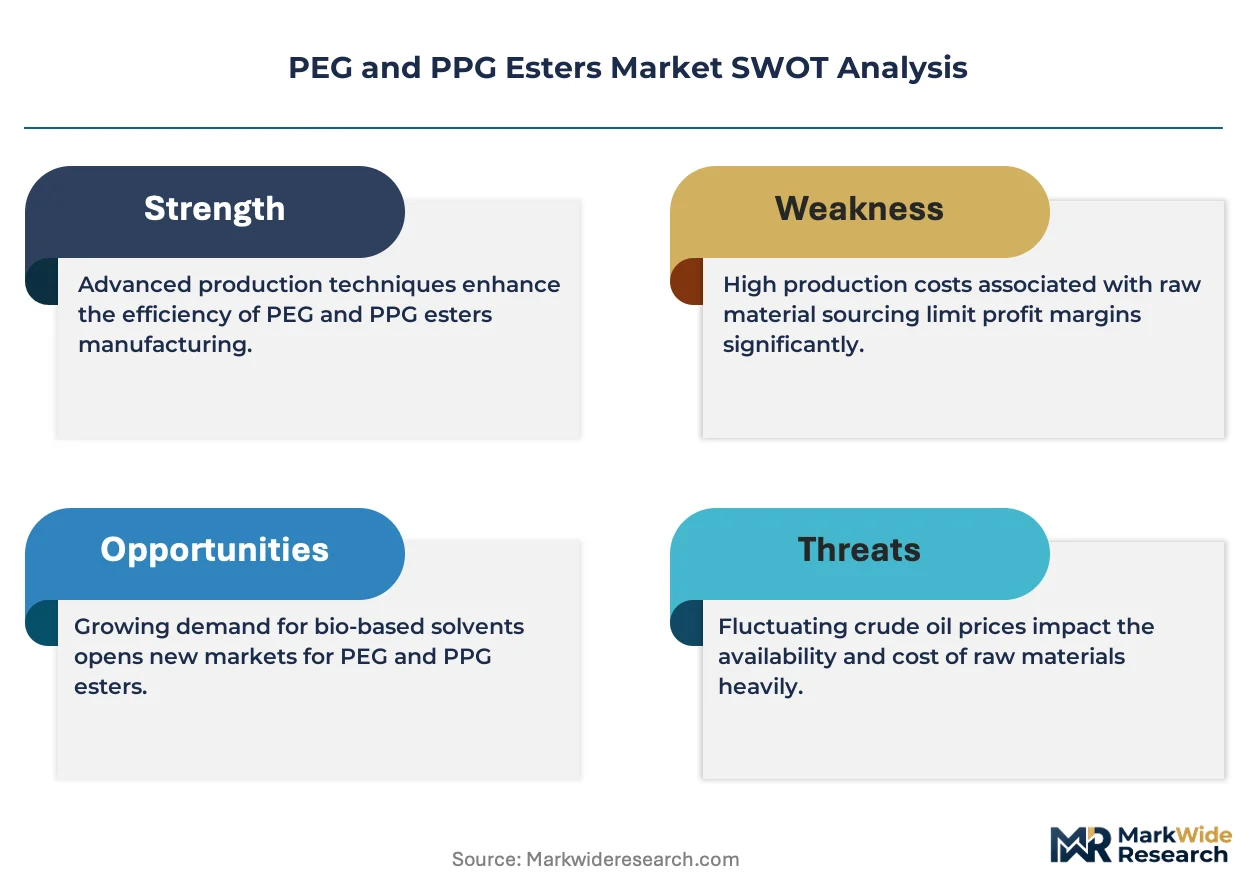
Petrochemical-derived alkyl phenol ethoxylates is rebalancing toward PEG esters across surfactant value chains as formulators seek lower aquatic toxicity profiles. BASF leverages its integrated ethylene oxide pipeline to secure cost-advantaged PEG ester supply for European personal care customers. Venus Ethoxyethers anchors its position through specialized ethoxylation capacity serving Indian pharmaceutical and cosmetic producers. Zschimmer & Schwarz differentiates via technical-grade ester portfolios targeting industrial metalworking and textile processing segments.
PEG and PPG esters comprise fatty acid esters of polyethylene glycol and propylene glycol, typically synthesized through base-catalyzed esterification of ethoxylated alcohols with C12-C18 fatty acids, yielding products with HLB values spanning 4 to 16 for emulsion stabilization. Their primary commercial purpose centers on surfactant functionality across personal care, pharmaceutical, and food processing applications where controlled hydrophilic-lipophilic balance governs performance. Polyethylene glycol esters occupy the dominant revenue position due to entrenched use in cosmetic emulsifiers, while propylene glycol esters are gaining fastest in food-grade surfactant applications driven by clean-label formulation trends. The liquid form commands the largest volume share given processing convenience, though powder esters capture premium positioning in pharmaceutical solid-dosage applications.
REACH registration requirements and the EU F-Gas Regulation are tightening chemical manufacturing standards and pushing ester producers toward carbon footprint disclosure across European supply chains. FDA food additive regulations and EPA aquatic toxicity guidelines in the United States shape product approval pathways and environmental fate testing for surfactant chemistries entering consumer markets. China's SAMR national standards and GB compliance frameworks govern import quality thresholds for esters used in domestic cosmetic and food processing industries. Stakeholders must monitor evolving bio-based content mandates and carbon border adjustment mechanisms to align product portfolios with shifting compliance boundaries.
Market Dynamics
REACH registration deadlines and the EU F-Gas Regulation are compressing formulation timelines for surfactant producers, forcing simultaneous carbon footprint disclosure and feedstock requalification across European supply chains.
Growth Catalysts
- EU Green Deal bio-based mandates:Procurement teams at cosmetic formulators redirect sourcing toward plant-derived fatty acid feedstocks to meet Scope 3 reduction targets.
- India personal care manufacturing expansion:Domestic production capacity for shampoos and skin care products drives localized ester consumption as brands onshore formulation operations.
- Aquatic toxicity profile advantages:PEG esters displace alkyl phenol ethoxylates in dishwashing and laundry applications where EPA guidelines restrict legacy surfactant chemistries.
Market Restraints
- Ethylene oxide feedstock volatility:Crude oil price swings and refinery operating rates transmit directly into PEG ester production economics.
- Specialized ethoxylation capacity concentration:Limited merchant producers in Western Europe create supply bottlenecks during maintenance turnarounds.
- Propylene glycol ester performance ceiling:Narrower HLB range restricts substitution into high-performance cosmetic emulsifier formulations.
Strategic Opportunities
- China pharmaceutical solid-dosage growth:Powder ester demand for tablet lubricants expands as domestic generic drug production scales.
- Clean-label food emulsifier convergence:Propylene glycol esters capture share from synthetic alternatives in bakery and dairy processing.
- Carbon border adjustment mechanism preparation:Early adopters of mass-balance certified bio-based content secure preferential access to EU personal care supply chains.
Industry Challenges
- Ethoxylation process safety expertise:Tight labor markets for chemical engineers familiar with high-pressure alkoxylation reactor operations constrain capacity expansion timelines.
- REACH data gap closure:Extended substance evaluation periods for novel bio-based fatty acid sources delay product registration and commercial launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PEG and PPG Esters Market |
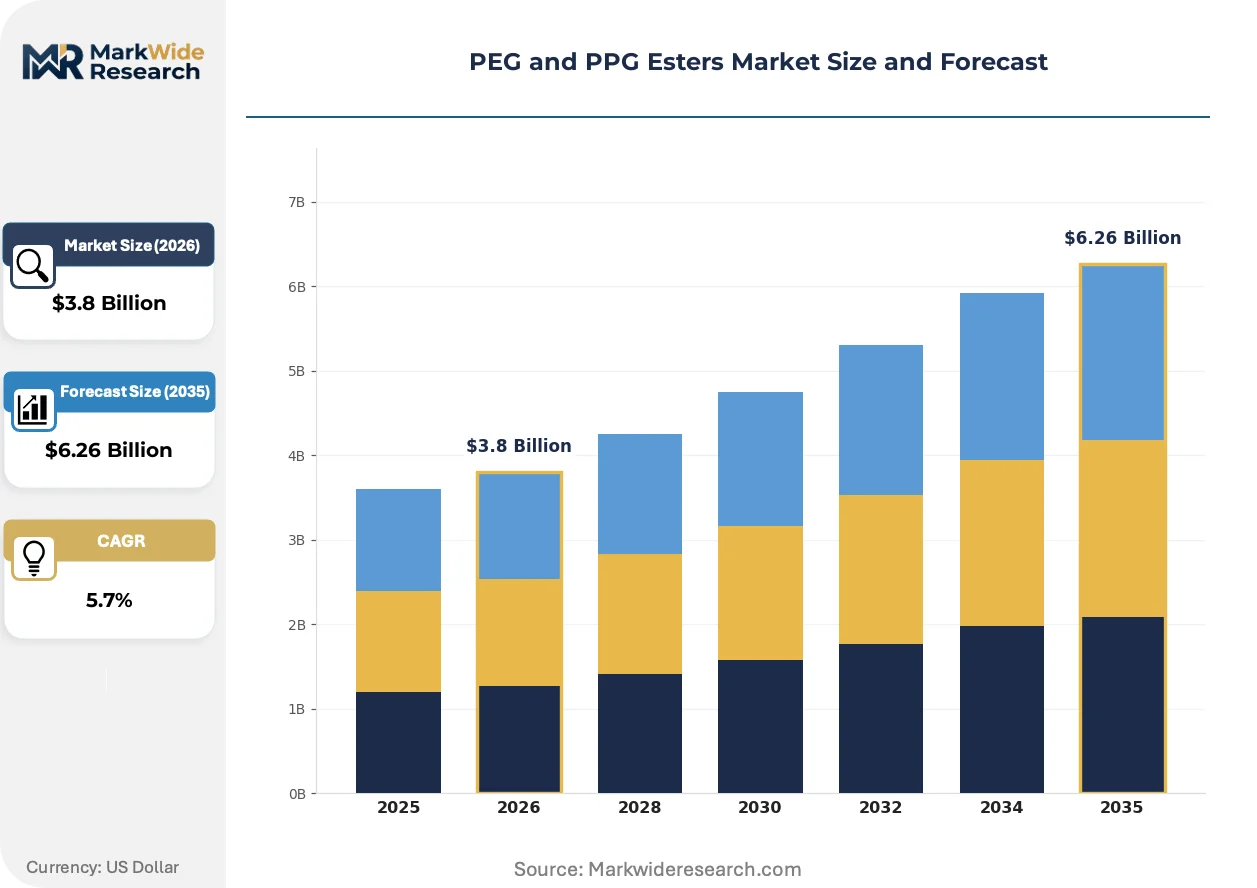
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Glycol Esters, Propylene Glycol Esters, Mixed Esters, Glycerin Esters End User: Cosmetics, Pharmaceuticals, Food Additives, Industrial Applications Form: Liquid, Solid, Powder, Gel Application: Emulsifiers, Surfactants, Solubilizers, Absorbents |
| Companies Covered | Venus Ethoxyethers, Fine Organics, BASF, Pacific Texchem Private, Hangzhou GengYang Chemical Materials, Ivanhoe Industries, Zschimmer & Schwarz, Symrise, American eChem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PEG and PPG Esters Market Strategic Shifts
Formulation science is pivoting toward milder surfactant systems that reconcile performance benchmarks with tightening aquatic toxicity standards. Three developments dominate this transition.
Enzymatic esterification routes are absorbing capital allocation from traditional base-catalyzed processes. Specialty chemical producers pilot lipase-mediated synthesis to achieve lower reaction temperatures and reduced byproduct formation. Cosmetic formulators in Germany and France prioritize these enzymatic grades for premium skin care lines, compressing acceptance timelines for novel manufacturing methods.
REACH authorization list expansion is restricting ethoxylated alcohol precursors derived from specific petrochemical streams. ECHA evaluations of endocrine-disrupting potential force reformulation cycles across industrial cleaning and textile processing segments. German metalworking fluid compounders accelerate qualification of alternative PEG ester grades to maintain machinery warranty compliance.
Direct procurement from specialty ester producers is displacing distributor-mediated purchasing in mid-sized personal care brands. Technical service requirements for HLB matching and emulsion stability testing drive relationship consolidation with manufacturers possessing in-house application laboratories. This pattern concentrates most visibly among South Korean and Japanese cosmetic OEMs building regional formulation centers.
PEG and PPG Esters Market Segmentation
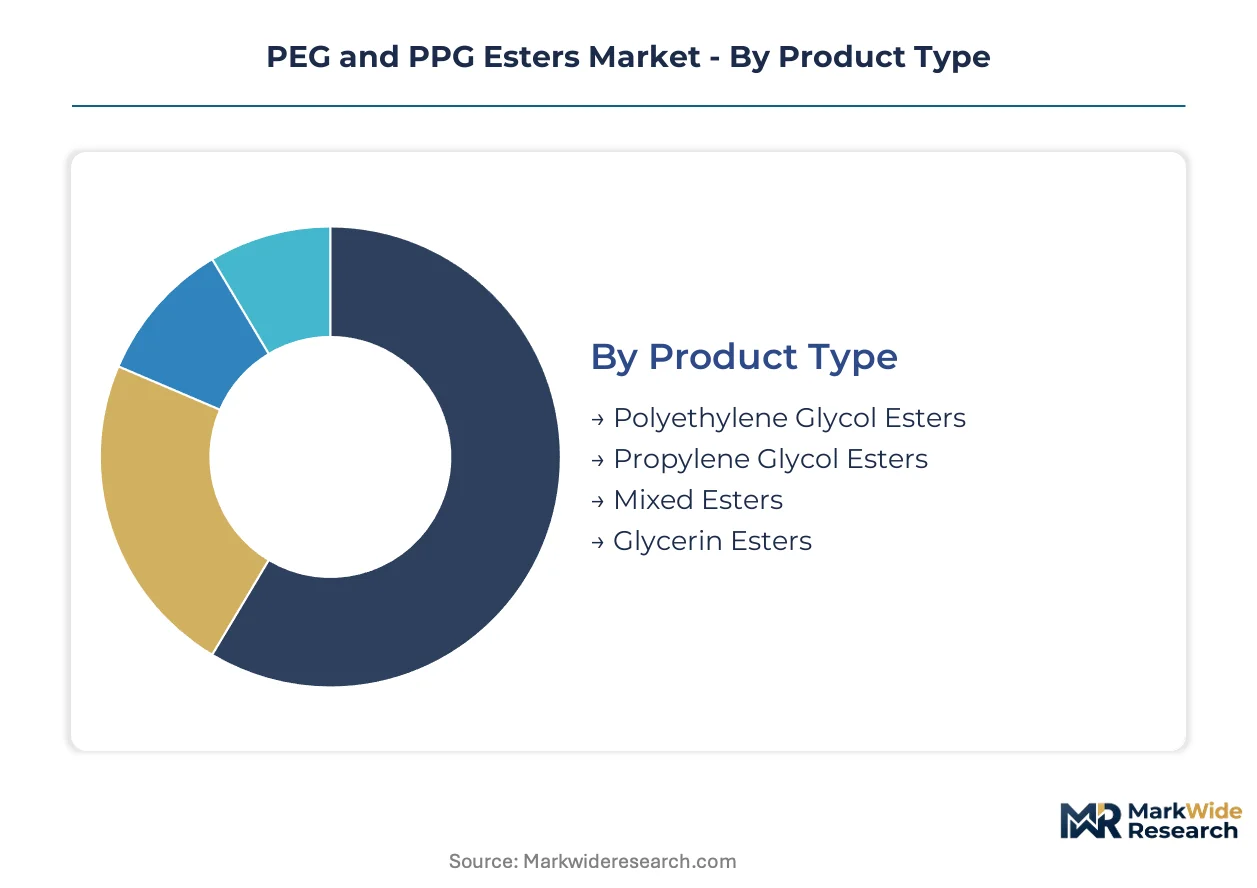
PEG and PPG ester segmentation reveals divergent margin profiles across product chemistries and end-use specifications. Formulators prioritize HLB-matched grades for emulsion stability, while regulatory compliance drives feedstock differentiation across pharmaceutical and food-grade tiers.
Product Type:
Volume concentration favors established ethoxylated platforms, yet premium positioning accrues to specialized ester architectures serving pharmaceutical and clean-label food markets.
- Polyethylene Glycol Esters:Synthesized through base-catalyzed esterification of ethoxylated alcohols with C12-C18 fatty acids, delivering HLB values from 4 to 16 for broad emulsion stabilization. Cosmetic formulators in Germany and France anchor demand for these grades as REACH restrictions on alkyl phenol ethoxylates intensify reformulation cycles.
- Propylene Glycol Esters:Derived from propylene glycol condensation with fatty acids, exhibiting narrower HLB ranges yet superior thermal stability in food processing. Clean-label bakery and dairy applications in North America absorb volume gains as brands displace synthetic alternatives.
- Mixed Esters:Hybrid architectures combining polyethylene and propylene glycol backbones for tailored surfactant performance.
- Glycerin Esters:Bio-based alternatives leveraging glycerol feedstocks for natural-positioned personal care formulations.
Today's leader: Polyethylene Glycol Esters. Tomorrow's challenger: Propylene Glycol Esters.
End User:
Customer concentration spans personal care compounders seeking milder surfactant systems and pharmaceutical manufacturers demanding excipient-grade consistency.
- Cosmetics:Skin care and hair care formulators specify low-aquatic-toxicity emulsifiers for rinse-off products facing EPA discharge guidelines. South Korean and Japanese OEMs consolidate direct procurement relationships with ester producers possessing in-house application laboratories.
- Pharmaceuticals:Tablet lubricants and solubilizers for oral solid dosage forms require powder-grade esters with tight particle size distribution. China's expanding generic drug production drives localized demand for pharmaceutical-grade PEG esters.
- Food Additives:Bakery emulsifiers and dairy stabilizers favor propylene glycol esters for clean-label positioning.
- Industrial Applications:Metalworking fluids and textile processing chemicals specify technical-grade esters for lubricity and antistatic performance.
Cosmetics commands current volume primacy. Pharmaceuticals posts the steepest expansion trajectory as solid-dosage manufacturing scales in Asia.
Form:
Processing economics favor liquid handling infrastructure, though solid and powder formats capture specification premiums in pharmaceutical and food-grade supply chains.
- Liquid:Dominant volume position due to pumping and blending convenience in continuous manufacturing environments. Bulk cosmetic and industrial compounders specify liquid esters for streamlined formulation workflows.
- Solid:Flake and pastille formats serving food processing and pharmaceutical applications where metering precision and storage stability outweigh handling complexity.
- Powder:Micronized grades for tablet lubrication and dry-mix food applications command specification premiums.
- Gel:Thickened ester preparations for specialized topical pharmaceutical and cosmetic delivery systems.
Liquid maintains processing dominance. Powder gains share fastest as pharmaceutical solid-dosage production concentrates in China and India.
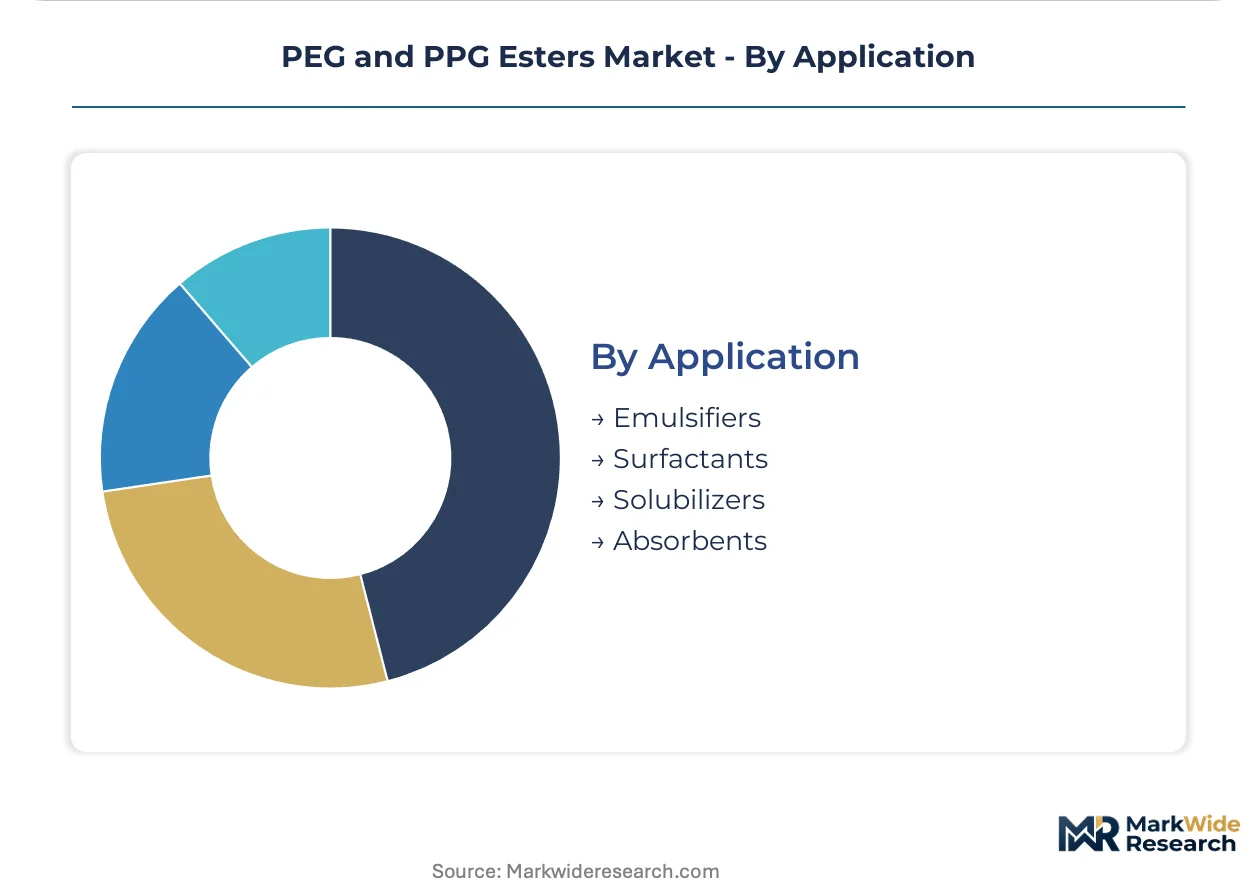
Application:
Functional performance requirements stratify demand across emulsion stabilization, surface activity, and solubilization roles.
- Emulsifiers:HLB-optimized esters stabilizing oil-in-water and water-in-oil systems for skin care creams and food spreads. Cosmetic formulators specify these grades for sensory profile control.
- Surfactants:Surface-active esters reducing interfacial tension in cleansing formulations and industrial cleaners. EPA aquatic toxicity guidelines accelerate displacement of legacy alkyl phenol ethoxylates.
- Solubilizers:Hydrotrope functionality for incorporating lipophilic actives into aqueous matrices.
- Absorbents:Specialized ester applications in pharmaceutical and personal care delivery systems.
Emulsifiers anchor revenue concentration. Surfactants climb fastest as regulatory pressure reshapes cleaning product formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Antwerp-Rotterdam chemical corridor anchors European PEG and PPG ester production, with integrated ethoxylation clusters serving cosmetic and pharmaceutical formulators. Procurement patterns diverge sharply across regulatory jurisdictions, with REACH compliance timelines and bio-based mandates reshaping supply chain configurations.
Germany
Cosmetic formulators in Hamburg and Düsseldorf drive demand for low-aquatic-toxicity emulsifiers as brands reformulate away from alkyl phenol ethoxylates. ECHA substance evaluations under REACH compress product registration timelines for novel bio-based fatty acid sources. The Rhine-Ruhr industrial belt hosts specialized ethoxylation capacity serving metalworking fluid compounders accelerating alternative PEG ester qualification.
China
Domestic pharmaceutical solid-dosage manufacturing expansion in Jiangsu and Zhejiang provinces absorbs powder-grade esters for tablet lubrication applications. SAMR national standards and GB compliance frameworks govern import quality thresholds for cosmetic and food processing grades. The Yangtze River Delta concentration of personal care OEMs drives localized ester consumption as brands onshore formulation operations from Southeast Asia.
India
Personal care manufacturing clusters in Maharashtra and Gujarat drive volume gains for liquid emulsifiers serving shampoo and skin care production. FSSAI food additive regulations shape approval pathways for propylene glycol esters entering bakery and dairy processing. Venus Ethoxyethers anchors specialized ethoxylation capacity in Mumbai-Pune corridor serving domestic pharmaceutical and cosmetic producers.
United States
EPA aquatic toxicity guidelines accelerate displacement of legacy surfactant chemistries in dishwashing and laundry applications, favoring PEG ester alternatives. FDA food additive regulations govern excipient-grade consistency requirements for pharmaceutical applications. The Gulf Coast petrochemical corridor provides integrated ethylene oxide feedstock for cost-advantaged PEG ester production serving North American personal care customers.
France
Premium skin care formulators in Paris region prioritize enzymatic esterification grades for milder surfactant systems in clean beauty positioning. EU Green Deal bio-based procurement mandates redirect sourcing toward plant-derived fatty acid feedstocks for Scope 3 reduction compliance. The Lyon chemical cluster hosts application laboratories supporting direct procurement relationships with mid-sized cosmetic brands consolidating supplier relationships.
PEG and PPG Esters Market Competitive Environment
Global majors compete with regional champions across feedstock integration and specialized ethoxylation capabilities. The vendor base stratifies into three tiers: integrated petrochemical producers with captive ethylene oxide supply, merchant specialty ester houses with application laboratory infrastructure, and regional distributors serving fragmented local formulators. Dominant competitive moves include backward integration into fatty acid feedstocks and geographic expansion of ethoxylation capacity to serve pharmaceutical solid-dosage growth in Asia.
Among integrated chemical producers, BASF represents the archetype of cost-advantaged supply through ethylene oxide pipeline control. Venus Ethoxyethers and Zschimmer & Schwarz exemplify specialized positioning: the former anchors Indian pharmaceutical and cosmetic demand through dedicated ethoxylation assets, while the latter occupies technical-grade portfolios targeting industrial metalworking and textile processing segments where machinery warranty compliance drives specification stickiness.
| Leading Market Players |
|---|
| Venus Ethoxyethers |
| Fine Organics |
| BASF |
| Pacific Texchem Private |
| Hangzhou GengYang Chemical Materials |
| Ivanhoe Industries |
| Zschimmer & Schwarz |
| Symrise |
| American eChem |
| Others |
Value Chain & Pricing Dynamics
Enzymatic esterification pilot programs across German and French cosmetic compounders are simultaneously compressing production cost curves and concentrating supply relationships with specialty houses possessing lipase-mediated synthesis capabilities. This manufacturing transition rewards early adopters with premium positioning while marginalizing traditional base-catalyzed producers unable to fund qualification timelines.
Pricing Analysis
Ethylene oxide feedstock volatility transmits directly into PEG ester contract structures, with crude oil price swings forcing quarterly renegotiation clauses across European supply chains. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels reflects certification burden differentials rather than manufacturing cost alone. Pricing pressure stems from REACH data gap closure delays extending registration timelines for novel bio-based fatty acid sources. Mid-sized personal care brands exhibit highest price sensitivity as direct procurement consolidation eliminates distributor margin buffers.
Supply Chain Analysis
REACH registration and EU F-Gas Regulation compliance certification gates access to European cosmetic and pharmaceutical formulators, filtering supply relationships toward producers with dedicated regulatory affairs infrastructure. Manufacturing concentrates in Germany, China, and India, with the Antwerp-Rotterdam corridor anchoring ethoxylation capacity and the Yangtze River Delta absorbing fastest volume gains. Feedstock draws from C12-C18 fatty acid streams and ethoxylated alcohol precursors, both exposed to petrochemical price cycles. Single-source vulnerability concentrates in specialized high-pressure alkoxylation reactor operations where qualified chemical engineer scarcity constrains capacity expansion. Distribution runs through direct technical service relationships displacing traditional distributor networks among South Korean and Japanese cosmetic OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-constrained European supply chains and cost-advantaged Asian manufacturing expansion, with carbon border adjustment mechanisms threatening to erode that differential over the projection horizon.
For Market Incumbents: Extend application laboratory capabilities into China and India to capture pharmaceutical solid-dosage growth localized in Jiangsu and Zhejiang provinces. Deepen upstream control over bio-based fatty acid feedstocks before EU Green Deal Scope 3 mandates harden procurement specifications. Defensive positioning requires simultaneous carbon footprint disclosure infrastructure and enzymatic esterification capacity investment to maintain premium tier access.
For New Entrants and Emerging Players: Mid-sized South Korean cosmetic OEMs building regional formulation centers represent an underserved buyer archetype seeking technical service partnerships for HLB matching and emulsion stability testing. White-space targets include powder-grade ester production for China's expanding generic drug tablet lubricant market and clean-label propylene glycol esters for North American bakery applications. Go-to-market positioning should emphasize mass-balance certified bio-based content to secure preferential EU personal care supply chain access.
For Investors and Strategic Acquirers: Valuations sit cheapest among merchant specialty ester houses with stranded base-catalyzed capacity lacking enzymatic qualification pathways. Long-term viability over the next decade hinges on backward integration into fatty acid feedstocks and geographic expansion of ethoxylation assets to serve Asian pharmaceutical growth. The inflection signal to monitor is carbon border adjustment mechanism implementation timing and stringency.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Esterification Capacity Investment | Lipase-mediated synthesis secures premium positioning with German and French cosmetic formulators prioritizing milder surfactant systems. |
| Backward Integration into Bio-Based Fatty Acids | Plant-derived feedstock control satisfies EU Green Deal Scope 3 reduction targets before carbon border adjustments harden. |
| Application Laboratory Expansion in Asia | Technical service proximity to Jiangsu and Zhejiang pharmaceutical clusters captures powder-grade ester demand from solid-dosage manufacturing growth. |
| REACH Data Gap Closure Acceleration | Novel bio-based fatty acid source registration speed determines commercial launch timelines against compressed ECHA evaluation periods. |
| Direct Procurement Relationship Consolidation | Technical partnership depth with South Korean and Japanese cosmetic OEMs displaces distributor-mediated purchasing in mid-sized brand segments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with cosmetic formulators, pharmaceutical excipient procurement managers, ethoxylation plant engineers, and specialty chemical distribution channel partners against secondary validation from REACH registration databases, ECHA substance evaluation records, SAMR national standards filings, and customs trade flow data. Bottom-up segment sizing triangulated against top-down ethylene oxide derivative consumption models.
Historical reference periods anchored demand modeling across the projection horizon, with segmentation dimensions spanning product chemistry type, end-use industry vertical, physical form factor, and regional regulatory compliance tier. CAGRs derived from ethoxylation capacity utilization trends, fatty acid feedstock price elasticity estimates, and substitution rate assumptions for alkyl phenol ethoxylate displacement under EPA aquatic toxicity guidelines.
Underlying measurement precision varies by segment; pharmaceutical-grade and food-grade tiers carry tighter precision than technical-grade industrial applications given more standardized specification requirements. Forecasts reflect documented assumptions on enzymatic process adoption curves and carbon border adjustment implementation timing. A model refresh is warranted upon material change in REACH authorization list expansion pace or EU Green Deal bio-based mandate enforcement stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Undecylenic Acid Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Perms and Relaxants Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
Monoaluminum Phosphate Market
Specialty Chemicals
Sodium Hyaluronate Market
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
Phenyl Trimethicone Market
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Medical Propellants Market