
 Dispersant Polymer Market | 2026-2036
Dispersant Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Dispersant Polymer Market Outlook
Market Dynamics
Specialty chemical distribution networks serving coatings formulators is reconfiguring around consolidated distributor partnerships and direct technical service models. BASF SE leverages its backward integration into acrylic monomer supply to secure cost positions across European and Asian dispersant grades. Dow anchors its competitiveness through proprietary polyurethane dispersant architectures developed for high-performance industrial coatings. Evonik Industries AG differentiates via tailored silicone-polymer hybrid dispersants targeting electronics-grade applications with stringent purity requirements.
Product Landscape
Dispersant polymers are macromolecular additives engineered with controlled molecular weights and anchor-solvent chain architectures to stabilize particulate phases in liquid media, typically functioning at active loadings of 0.5-5.0 weight percent depending on pigment surface area and polarity. Acrylic dispersants dominate volume consumption in architectural paints due to mature supply chains and cost-efficient radical polymerization processes, while polyurethane variants command premium positioning in automotive OEM clearcoats where gloss retention and scratch resistance specifications are critical. Cellulose-based alternatives occupy niche positions in food-contact inks and biodegradable coating systems where renewable feedstock credentials determine procurement decisions.
Regulatory Environment
EPA oversight under TSCA and the Clean Air Act shapes permissible solvent content and chemical substance notifications for dispersant polymers manufactured or imported into the United States, while REACH registration requirements and the EU Green Deal's decarbonization mandates enforce cradle-to-grave accountability for European suppliers. China's MEE administers discharge permits and chemical environmental risk assessments that increasingly influence dispersant plant siting decisions along the Yangtze River Economic Belt. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as fluorinated dispersant chemistries face intensifying regulatory scrutiny across multiple jurisdictions.
Market Dynamics
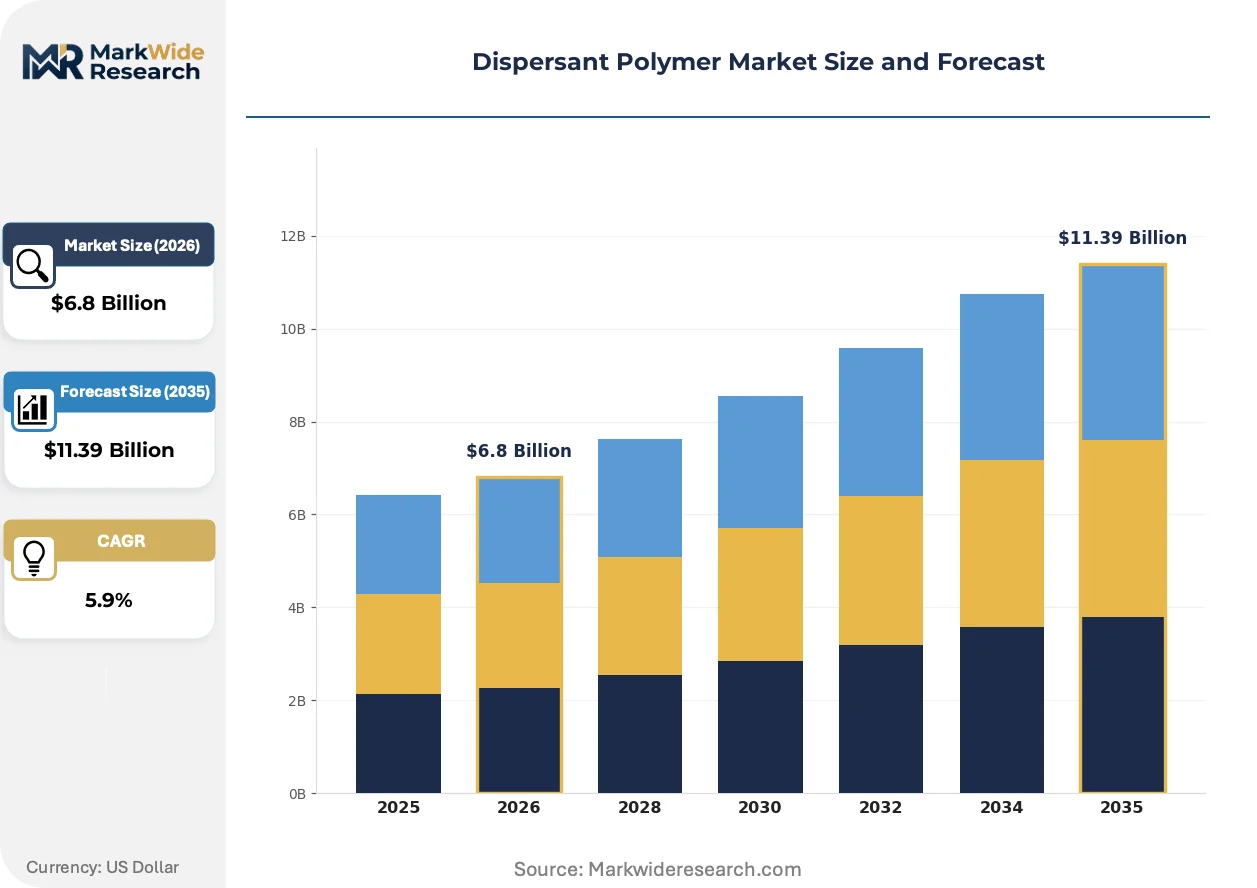
Waterborne coating mandates across automotive OEM and refinish segments are compressing solvent-based dispersant demand while accelerating acrylic and polyurethane polymer reformulation cycles. Formulators now face simultaneous pressure to reduce volatile organic compound emissions and maintain pigment stabilization performance in high-solids systems.
Growth Catalysts
- EPA Clean Air Act Amendments:Tightening volatile organic compound thresholds for industrial coatings in the United States are forcing solvent-to-waterborne conversions that expand dispersant polymer loadings in reformulated systems.
- Automotive refinish waterborne transition:Collision repair shops across Germany and the United States are adopting waterborne basecoat technologies that require specialized polyurethane dispersants for metallic flake orientation control.
- China infrastructure spending:Provincial governments along the Yangtze River Economic Belt are expanding transportation and municipal construction, driving architectural paint consumption that absorbs acrylic dispersant volumes.
Market Restraints
- Acrylic acid supply concentration:Backward-integrated producers in Germany and China control monomer supply, exposing non-integrated dispersant manufacturers to feedstock price volatility and allocation risk.
- REACH registration cost burden:European small and mid-scale dispersant formulators face escalating data requirements and substance evaluation fees that compress margins on specialty grades.
- Silica nanoparticle substitution:High-performance coatings in Japan and South Korea are testing surface-modified fumed silica as partial replacements for polymeric dispersants in scratch-resistant clearcoats.
Strategic Opportunities
- Battery electrode slurries:Lithium-ion cell manufacturers in South Korea and Japan are qualifying dispersant polymers for cathode active material stabilization, opening non-coating applications with purity specifications exceeding paint grades.
- EU Green Deal carbon border adjustments:Cradle-to-grave carbon accounting requirements will favor European dispersant producers with renewable feedstock certificates and bio-based acrylic acid supply chains.
- Direct technical service models:Distributor consolidation is creating openings for dispersant suppliers to embed formulation chemists at major coatings manufacturers, capturing specification authority.
Industry Challenges
- Colloidal stability modeling expertise:Formulators lack personnel trained in Hansen solubility parameter mapping and anchor-group optimization for novel pigment surface chemistries.
- Multi-jurisdictional substance notifications:TSCA pre-manufacture notices, REACH dossier updates, and China's MEE new chemical registration create parallel compliance timelines that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispersant Polymer Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Ethylene-Vinyl Acetate, Cellulose Application: Paints, Coatings, Inks, Adhesives End User: Construction, Automotive, Electronics, Consumer Goods Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | BASF SE, Dow, Evonik Industries AG, Nouryon, The Lubrizol Corporation, Ashland Global Holdings Inc., Solvay SA, LANXESS AG, Nippon Shokubai Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispersant Polymer Market Strategic Shifts
Reactive dispersant architectures that polymerize into the coating film during cure are eliminating migratory additives while maintaining grind viscosity control. This shift is compressing the distinction between dispersant and binder chemistries.
Polymerizable dispersants incorporating methacrylate-functional anchor groups are collapsing the traditional separation between pigment stabilization and film formation in radiation-curable coatings. Wood furniture manufacturers in Italy and Germany are adopting these systems to eliminate surface defects from incompatible additive migration. The technology is collapsing quality control costs by reducing batch-to-batch variation in high-throughput flatline finishing operations.
REACH restriction proposals targeting microplastic release are forcing dispersant suppliers to demonstrate biodegradation pathways or polymer molecular weight thresholds below environmental persistence limits. The European Chemicals Agency's ongoing evaluation of polymer registration requirements is redirecting R&D spending toward oligomeric dispersants with defined degradation profiles. Waterborne industrial maintenance coatings in Northern Europe are first to face reformulation pressure as environmental release modeling tightens.
Specification authority is migrating from procurement departments to coatings formulators embedded at automotive OEM technical centers. Tier-1 paint suppliers in Stuttgart, Detroit, and Shanghai now demand dispersant samples with full toxicological dossiers and application-specific performance data before trial approvals. This behavioral shift is compressing supplier qualification cycles and favoring partners with analytical service laboratories co-located near customer R&D facilities.
Dispersant Polymer Market Segmentation
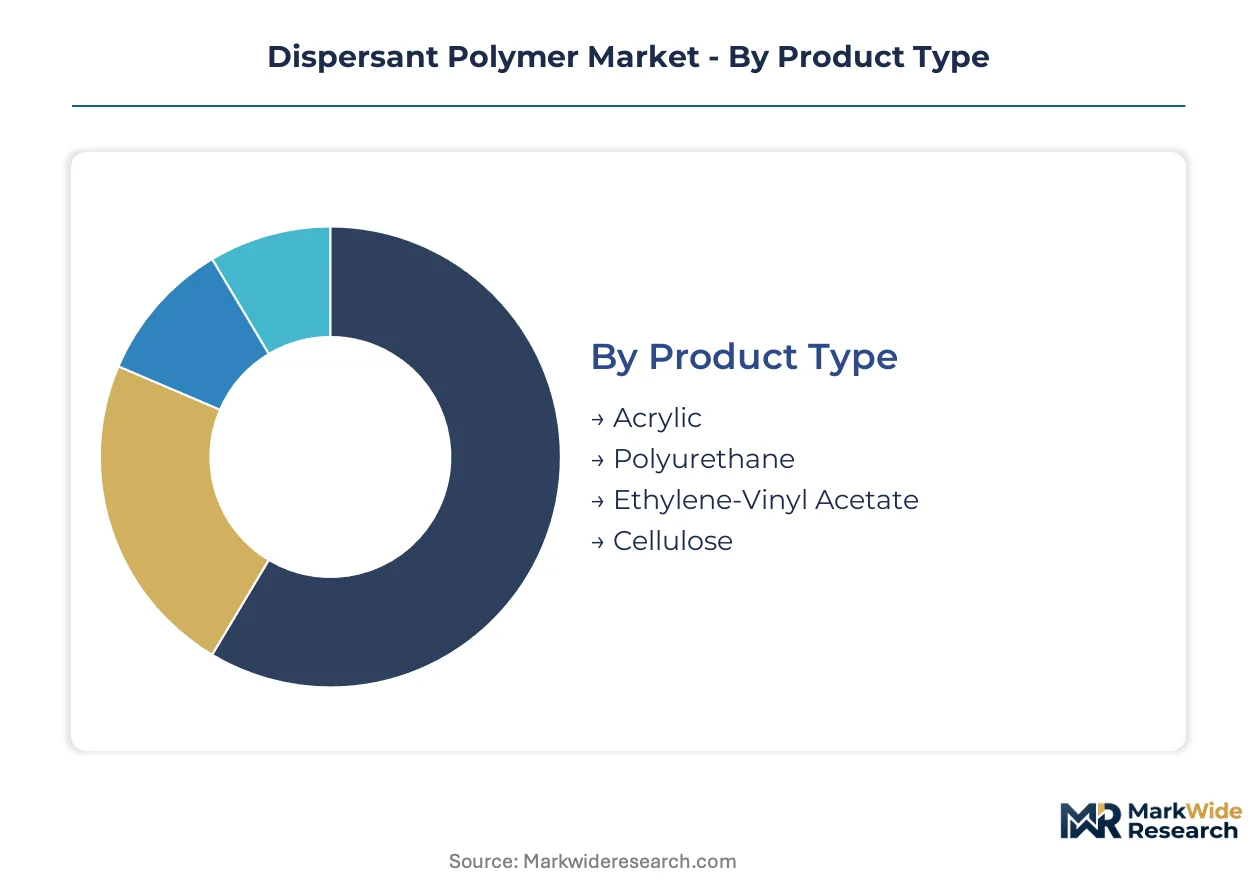
Dispersant polymer procurement cycles vary dramatically by end-use, with automotive OEM qualification timelines stretching across multiple years while construction coatings demand turns over seasonally. Understanding these velocity differentials helps suppliers calibrate inventory positions and technical service investments.
Product Type:
Reformulation cycles determine competitive exposure, with some chemistries facing near-annual specification reviews while others lock in for half-decade automotive contracts.
- Acrylic:Radical polymerization yields cost-efficient dispersants with tunable acid numbers for architectural pigment wetting. Construction coatings in China absorb the dominant volume as provincial infrastructure programs expand waterborne paint capacity along the Yangtze River.
- Polyurethane:Blocked isocyanate architectures deliver steric stabilization in high-solids automotive clearcoats where metallic flake orientation demands precise viscosity control. German collision repair chains are converting to waterborne basecoats that specify these grades for gloss retention.
- Ethylene-Vinyl Acetate:Copolymer dispersants serve packaging ink applications requiring low-temperature flexibility and adhesion to polyolefin substrates.
- Cellulose:Renewable feedstock credentials position these dispersants in food-contact inks and biodegradable coating systems subject to EU Green Deal procurement preferences.
Acrylic anchors the volume base while polyurethane gains share at the steepest rate.
Application:
Performance specifications stratify sharply, with industrial maintenance coatings demanding salt-spray resistance that decorative paints never require.
- Paints:Architectural formulations consume dispersant volumes at 0.5-3.0 weight percent loadings depending on titanium dioxide surface area. China's MEE discharge permit tightening is accelerating waterborne conversions in provincial manufacturing zones.
- Coatings:Industrial OEM and refinish segments specify polyurethane dispersants for corrosion protection and weathering resistance. EPA Clean Air Act amendments are compressing solventborne system viability in United States manufacturing.
- Inks:Gravure and flexographic applications require dispersants with rapid solvent release and low foam generation for high-speed printing lines.
- Adhesives:Structural bonding formulations utilize dispersants to stabilize filler phases in epoxy and polyurethane systems for automotive assembly.
Paints dominate current offtake while coatings expand most quickly on regulatory displacement of solventborne alternatives.
End User:
Customer concentration patterns diverge, with electronics-grade specifications consolidating around a handful of South Korean and Japanese battery manufacturers while construction remains fragmented across thousands of regional paint contractors.
- Construction:Municipal infrastructure and residential finishing in China drive acrylic dispersant consumption through domestic paint production networks. Provincial transportation spending along the Yangtze River Economic Belt sustains volume offtake.
- Automotive:OEM clearcoat and refinish basecoat specifications demand polyurethane dispersants with batch-to-batch consistency certified for metallic flake control. German and United States collision repair adoption of waterborne systems is accelerating qualification activity.
- Electronics:Lithium-ion electrode slurry stabilization is emerging as a non-coating application with purity specifications exceeding traditional paint grades. South Korean cell manufacturers are qualifying dispersant polymers for cathode active material processing.
- Consumer Goods:Packaging and furniture coatings utilize dispersants in wood finishing and decorative applications with moderate performance requirements.
Construction maintains the installed base while electronics climbs the fastest on battery supply chain expansion.
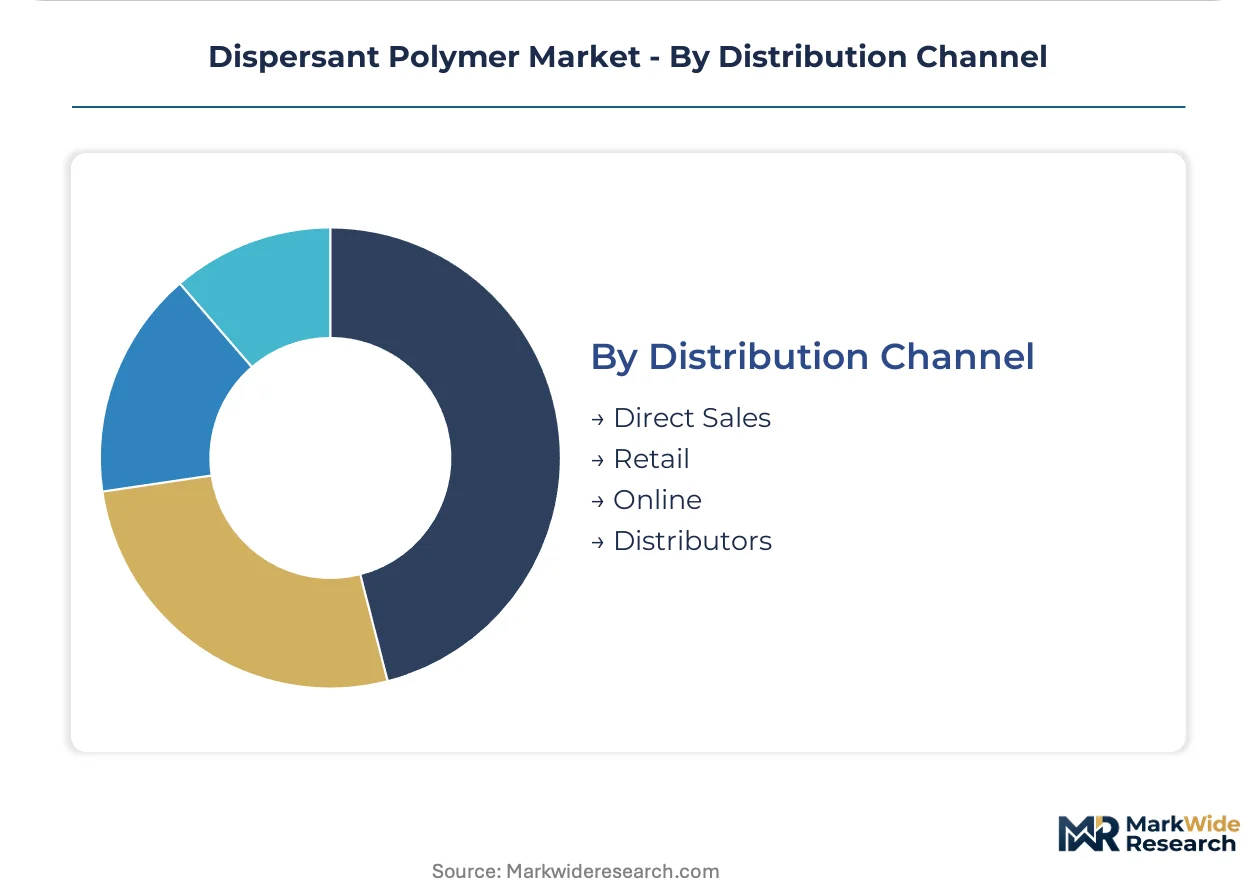
Distribution Channel:
Channel economics reflect technical complexity, with direct sales capturing specification-intensive automotive accounts while distributors serve fragmented construction contractors.
- Direct Sales:Technical service teams embed formulation chemists at major coatings manufacturers to capture specification authority. BASF SE and Dow maintain direct relationships with automotive OEM technical centers in Stuttgart and Detroit.
- Distributors:Consolidated specialty chemical distributors serve mid-scale architectural paint formulators with inventory pooling and local technical support.
- Retail:Small-volume sales to independent contractors and maintenance shops move through paint store networks with limited technical consultation.
- Online:Digital procurement platforms are capturing standard-grade acrylic dispersant orders from price-sensitive formulators in China.
Direct sales commands the margin pool while online channels show the steepest expansion trajectory on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure anchors European dispersant polymer distribution, while Shanghai's Yangshan deep-water port underwrites Asia-Pacific supply chain throughput for coating raw materials.
United States
Automotive refinish shops in Michigan and Ohio are converting to waterborne basecoat systems that require specialized polyurethane dispersants. EPA Clean Air Act amendments tighten volatile organic compound thresholds for industrial coatings manufactured in the Midwest and Southeast. Houston's petrochemical corridor hosts acrylic acid production that feeds dispersant polymer synthesis for architectural paint formulators.
Germany
Collision repair chains in Bavaria and Baden-Württemberg specify polyurethane dispersants for metallic flake orientation in waterborne refinish coatings. REACH registration requirements enforce cradle-to-grave accountability for dispersant formulations manufactured along the Rhine chemical belt. Ludwigshafen's integrated chemical parks concentrate backward-integrated producers with captive acrylic monomer supply.
China
Provincial infrastructure spending in Jiangsu and Zhejiang provinces drives architectural paint consumption absorbing acrylic dispersant volumes. MEE discharge permits and environmental risk assessments influence plant siting decisions along the Yangtze River Economic Belt. Shanghai's coatings manufacturing clusters are expanding waterborne production capacity to serve domestic construction markets.
Japan
Lithium-ion battery manufacturers in Kansai and Kyushu are qualifying dispersant polymers for cathode active material stabilization with purity specifications exceeding traditional paint grades. METI industrial policy supports advanced materials development for electronics applications. Osaka's chemical industry corridor hosts specialty dispersant producers serving electronics-grade specifications.
South Korea
Battery electrode slurry stabilization is emerging as a non-coating application with cell manufacturers in Gyeonggi and Chungcheong provinces testing dispersant performance. MFDS chemical safety assessments govern substances used in electronics manufacturing. Ulsan's petrochemical complex supplies monomer feedstocks for dispersant polymer production serving regional coating and battery industries.
Dispersant Polymer Market Competitive Environment
On the supply side, the industry is consolidating around integrated chemical conglomerates with backward integration into acrylic monomer supply and specialized performance additive divisions. Three strategic archetypes dominate: petrochemical majors with captive raw material positions, specialty chemical houses with tailored silicone-polymer hybrid architectures, and diversified materials companies with multi-sector dispersant portfolios. Capacity expansion and direct technical service embedding represent the dominant competitive moves, as suppliers position formulation chemists at major coatings manufacturers to capture specification authority.
Within the integrated chemical conglomerate tier, BASF SE anchors the European supply position through its Ludwigshafen production network, while Dow exemplifies the North American specialty architecture approach with proprietary polyurethane dispersant development. Evonik Industries AG occupies the tailored hybrid specialist position, representing the German specialty chemical model for electronics-grade purity requirements. These three companies collectively illustrate the competitive spectrum from commodity-scale acrylic production to premium-tier customized formulations.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Evonik Industries AG |
| Nouryon |
| The Lubrizol Corporation |
| Ashland Global Holdings Inc. |
| Solvay SA |
| LANXESS AG |
| Nippon Shokubai Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
The Port of Rotterdam's chemical handling infrastructure channels acrylic acid feedstock from Ludwigshafen and Antwerp production clusters toward dispersant polymer manufacturers, with freight cost differentials between barge and rail modes directly amplifying pricing power for backward-integrated producers while compressing margins at non-integrated formulators serving price-sensitive architectural paint buyers in provincial China.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by molecular weight precision and REACH dossier completeness, with polyurethane grades for automotive OEM clearcoats commanding substantial premiums over commodity acrylics for construction coatings. Price differentiation hinges on certification tier and volume scale, with annual offtake commitments above 500 metric tons unlocking standard-tier discounts. Cost compression in economy-grade acrylic dispersants is intensifying because Chinese domestic producers are expanding radical polymerization capacity along the Yangtze River. Construction coatings formulators in Jiangsu province exhibit highest price sensitivity, while automotive OEM technical centers in Stuttgart and Detroit prioritize batch consistency over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with integrated chemical conglomerates BASF SE, Dow, and Evonik Industries AG, which retain in-house production of dispersant polymer grades across European and North American facilities. Geographic supply concentration centers on Germany, China, and the United States, with acrylic acid monomer production anchoring in Ludwigshafen, Nanjing, and Houston petrochemical corridors. Raw material dependencies draw from propylene oxidation feedstocks, isocyanate precursors for polyurethane architectures, and silicone intermediates for hybrid grades. Single-source vulnerability runs through concentrated acrylic acid supply controlled by backward-integrated majors. Distribution runs through consolidated specialty chemical distributors serving mid-scale formulators alongside direct technical service teams embedded at automotive OEM accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dispersant polymer demand sits in early-cycle expansion as waterborne coating mandates across automotive refinish and industrial maintenance segments displace solvent-based systems, with battery electrode slurry applications in South Korean cell manufacturing opening non-coating penetration vectors.
For Market Incumbents: Insulate specification authority at automotive OEM technical centers by embedding formulation chemists with full toxicological dossiers and application-specific performance databases. Deepen backward integration into bio-based acrylic acid supply chains to capture EU Green Deal carbon border adjustment preferences. Defend against silica nanoparticle substitution threats in Japanese scratch-resistant clearcoats by accelerating reactive dispersant architectures that polymerize into cured films. For New Entrants and Emerging Players: Establish a beachhead in lithium-ion electrode slurry stabilization for South Korean and Japanese battery manufacturers, where purity specifications exceed traditional paint grades and incumbent chemical majors lack dedicated electronics-grade service infrastructure. Target cellulose-based dispersants for EU Green Deal procurement preferences in food-contact inks and biodegradable coating systems. Pursue qualification partnerships with tier-1 paint suppliers in Shanghai coatings manufacturing clusters seeking alternative acrylic dispersant sources. For Investors and Strategic Acquirers: Regional specialists with captive silicone-polymer hybrid capabilities and established electronics-grade purity protocols represent priority acquisition archetypes, as battery supply chain expansion outpaces major chemical conglomerate R&D cycle times. Long-term viability favors producers with demonstrated biodegradation pathway documentation for REACH microplastic restriction compliance. Watch South Korean cathode active material qualification timelines as inflection indicators for non-coating application scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Acrylic Acid | Captures EU Green Deal carbon border adjustment advantages for European dispersant producers. |
| Direct Technical Service Embedding | BASF SE and Dow position formulation chemists at Stuttgart and Detroit automotive OEM centers to lock specifications. |
| Electronics-Grade Purity Certification | Opens lithium-ion battery electrode slurry applications with MFDS compliance in South Korean cell manufacturing. |
| Reactive Dispersant Architecture Development | Eliminates migratory additive defects for Italian and German wood furniture radiation-curable coating adoption. |
| REACH Biodegradation Pathway Documentation | Defends European market access as ECHA evaluates polymer registration requirements for microplastic release restrictions. |
Study Parameters
Operator-level perspectives from coatings formulators, automotive OEM procurement specialists, battery cell manufacturing engineers, and specialty chemical distribution managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with technical R&D directors at major dispersant producers and procurement leads at tier-1 paint suppliers. Secondary validation drew from ECHA REACH dossier databases, EPA TSCA pre-manufacture notice filings, China MEE discharge permit records, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up segment sizing across product type, application, and end-use dimensions was triangulated against top-down trade flow analysis.
Scenario-bracketing framed demand projections across the analysis window, with base, upside, and downside cases reflecting varying paces of waterborne coating mandate enforcement and battery electrode slurry qualification timelines. Segmentation dimensions modeled include dispersant chemistry type, coating application category, end-use industry vertical, and regional production hub clustering. CAGRs were derived from fitted growth curves against historical adoption patterns in comparable specialty chemical additive markets. Industry-specific forecast inputs incorporated automotive refinish shop conversion rates to waterborne basecoat systems and provincial infrastructure spending trajectories along China's Yangtze River Economic Belt.
Stress conditions across acrylic acid feedstock price volatility, REACH registration fee escalation, and silica nanoparticle substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and battery supply chain expansion cadence. Quarterly review of South Korean cathode active material qualification approvals and China MEE discharge permit issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
Global Amino Resin Market
Polymers & Resins
Global Polyethylene Market
Polymers & Resins
Medical Polymers Market
Polymers & Resins
Polyvinyl Alcohol (PVA) Market
Polymers & Resins
Europe Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
Global Chromatography Resin Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
Middle East LLDPE Market