
 Aerosol Cans Market | 2026-2036
Aerosol Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Aerosol Cans Market Analysis
European aluminum rolling capacity is realigning around thinner-walled, high-recyclability can stock. Ball Corporation leverages backward integration into aluminum slug production to secure raw material flows. Crown Holdings anchors its position through dedicated aerosol lines across multiple continents. Trivium Packaging differentiates via printed steel and aluminum hybrid designs for premium personal care clients.
An aerosol can is a pressurized metal, plastic, or composite container designed to dispense a product through a valve system using liquefied or compressed gas propellant, typically constructed from aluminum alloy 3104 or tinplate steel with internal epoxy phenolic coatings to prevent chemical interaction. These containers serve the primary commercial purpose of delivering controlled, continuous spray patterns for products ranging from cosmetics to industrial coatings. Aluminum dominates material selection due to its infinite recyclability and compatibility with high-speed necking and shaping equipment. Personal care applications command the largest volume share, while industrial paints and automotive cleaners generate higher per-unit margins through specialized corrosion-resistant lining requirements.
REACH in Europe and EPA regulations in the United States govern volatile organic compound limits and propellant chemistries, directly constraining formulation choices and can interior coating specifications. FDA oversight applies to food-contact aerosol applications, requiring migration testing for coating systems used in cooking spray and whipped cream dispensers. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple jurisdictions, as these programs will determine who bears end-of-life collection and recycling infrastructure costs.
Market Dynamics
REACH restrictions on volatile organic compounds are compressing formulation choices across European filling operations and forcing accelerated adoption of compressed gas propellant systems.
Growth Catalysts
- Dry shampoo portfolio expansion:Personal care brands are adding aerosol formats to hair care lines, creating dedicated production lines at contract fillers in Germany and the United States.
- REACH VOC limits:European restrictions on volatile organic compounds are pulling converters toward low-pressure propellant chemistries and water-based product formulations.
- Aluminum 3104 alloy availability:Backward integration into aluminum slug production is securing raw material flows for high-recyclability can stock.
Market Restraints
- Propellant cost volatility:Liquefied petroleum gas and dimethyl ether prices fluctuate with petrochemical feedstock markets, squeezing converter margins on fixed-price contracts.
- Coating formulation concentration:Epoxy phenolic interior lining systems rely on a narrow supplier base in Belgium and the Netherlands, creating single-source vulnerability.
- Steel substitution threat:Plastic and bag-on-valve alternatives are capturing share in food-contact and pharmaceutical applications where migration testing requirements are less stringent.
Strategic Opportunities
- India personal care penetration:Aerosol adoption in deodorants and hair sprays remains below European levels, offering volume expansion for converters establishing local filling partnerships.
- EU Green Deal packaging mandates:Extended producer responsibility frameworks will reward aluminum recyclability credentials with reduced compliance fees.
- Compressed gas and mechanical pump convergence:Hybrid dispensing systems combining nitrogen propellant with precision valves are opening premium positioning in sun care and facial mists.
Industry Challenges
- Coating technician scarcity:Formulation chemists with expertise in epoxy phenolic migration testing for food-contact applications command premium wages and limited availability.
- Multi-jurisdiction certification timelines:FDA food-contact notification parallel with EU migration testing creates six-to-twelve month product launch delays for cooking spray formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerosol Cans Market |
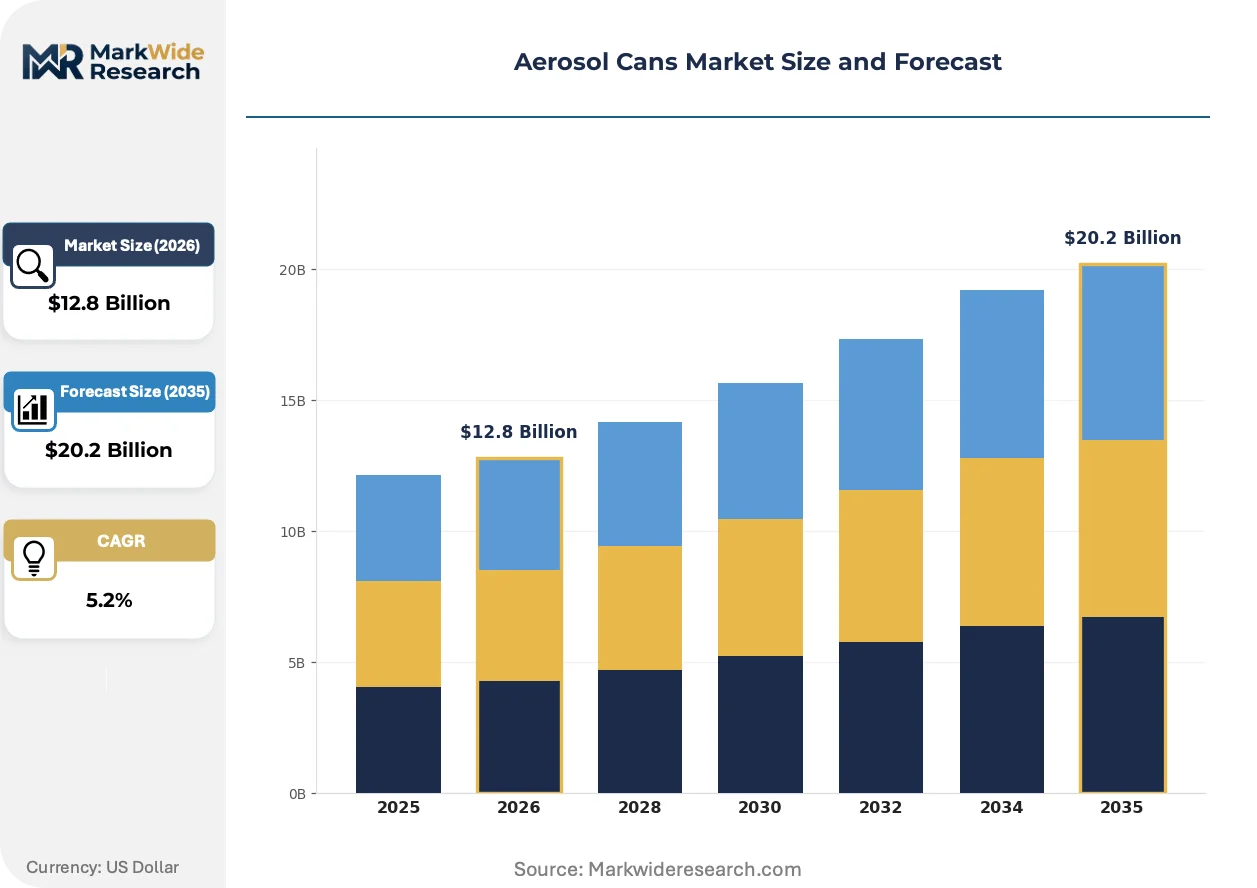
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.2 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Care, Household, Industrial, Automotive Material: Aluminum, Steel, Plastic, Composite Application: Paints, Cleaners, Insecticides, Food Products End User: Manufacturers, Retailers, Consumers, Distributors |
| Companies Covered | Ball Corporation, Crown Holdings, Trivium Packaging, CCL Industries, Sonoco Products Company, Ardagh Group, Mauser Packaging Solutions, Toyo Seikan Group Holdings, Nampak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerosol Cans Market Emerging Trajectories
Active modifications to propellant chemistry, valve precision engineering, and coating barrier properties are reshaping competitive capabilities across personal care and food-contact segments.
Bag-on-valve technology is modularizing aerosol architecture by separating product from propellant through a laminated film pouch welded to a standard valve cup. Premium skincare and pharmaceutical brands are adopting this format for preservative-free formulations and 360-degree dispensing. The technology is modularizing production lines, allowing contract fillers to switch between conventional and barrier formats without dedicated equipment.
EPA Significant New Alternatives Policy reviews are constraining hydrofluorocarbon propellant use in industrial aerosols, pushing formulators toward hydrocarbon and compressed gas alternatives. The industrial coatings segment faces reformulation costs for corrosion-resistant products. California Air Resources Board districts are enforcing stricter limits than federal standards, creating a bifurcated compliance environment.
Direct-to-retailer procurement contracts are compressing traditional distributor roles in personal care aerosol supply chains. Major European retailers are negotiating directly with Hamburg and Berlin filling operations for private-label dry shampoo and sun care lines. Germany hosts the most visible concentration of this channel disintermediation, with discounters and drugstore chains consolidating volume through dedicated supply agreements.
Aerosol Cans Market Segmentation
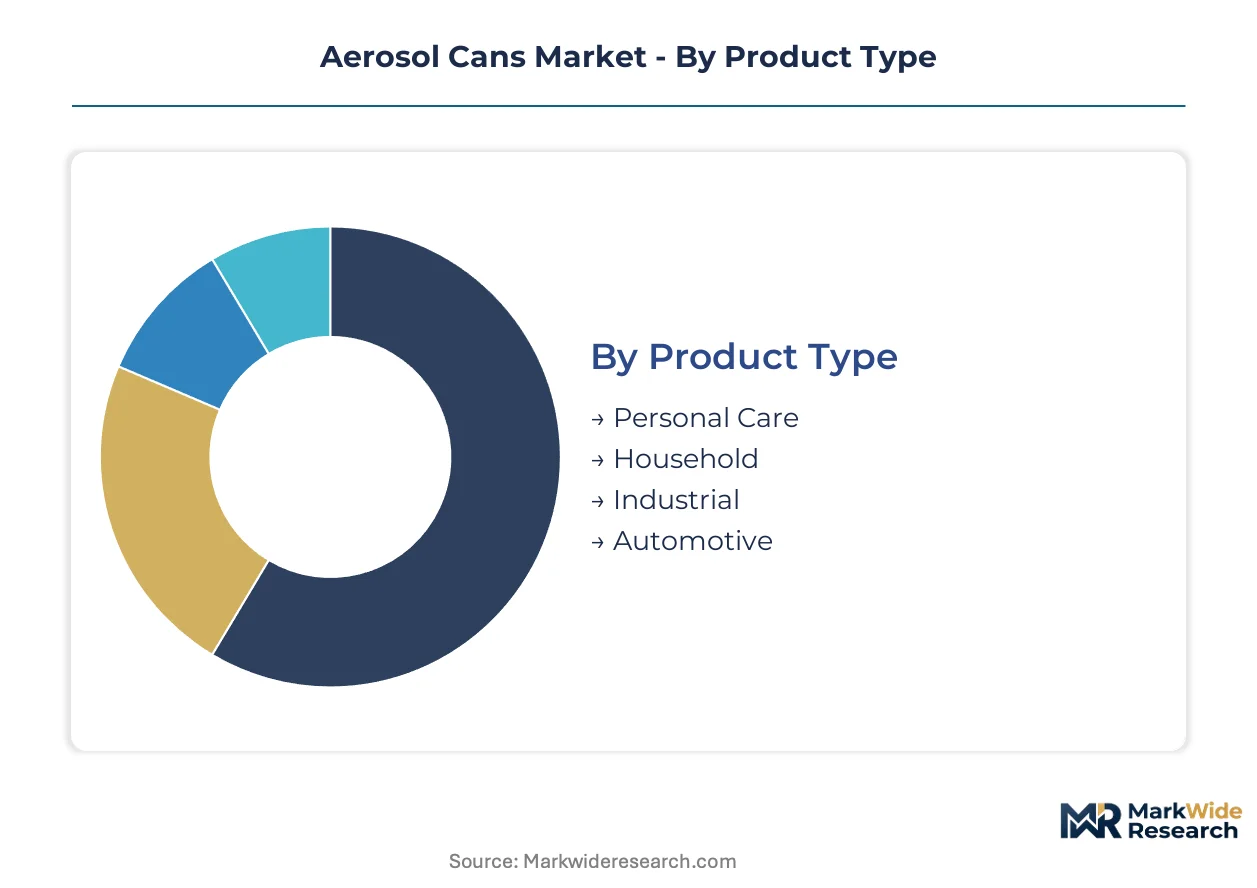
Aerosol can specifications diverge sharply across end-use requirements, with coating chemistry, pressure ratings, and recyclability credentials driving converter selection. Material and product type choices determine filling line configurations and regulatory compliance pathways.
Product Type:
Standardization dominates high-volume segments while customization concentrates in industrial niches requiring corrosion-resistant linings.
- Personal Care:Deodorants, hair sprays, and dry shampoos utilize aluminum alloy 3104 with epoxy phenolic interior coatings. Demand clusters in Germany at Hamburg and Berlin filling operations serving European private-label retailers.
- Household:Air fresheners and surface cleaners run on thinner-walled aluminum stock with reduced propellant loads. REACH VOC restrictions are compressing formulation choices and accelerating compressed gas adoption.
- Industrial:High-pressure steel cans with specialized barrier coatings serve paints and coatings. EPA Significant New Alternatives Policy reviews constrain hydrofluorocarbon propellant options.
- Automotive:Brake cleaners and lubricants require chemical-resistant linings and higher pressure tolerances. Per-unit margins exceed personal care formats through specialized specification requirements.
Most installed capacity flows through Personal Care. Expansion is steepest in Household as retailers consolidate private-label volume through direct procurement.
Material:
Cost tiers separate premium recyclability credentials from commodity alternatives with shorter regulatory compliance horizons.
- Aluminum:Infinite recyclability and compatibility with high-speed necking equipment make this the dominant choice. Backward integration into slug production secures raw material flows for major converters.
- Steel:Tinplate construction with epoxy phenolic coatings serves industrial applications requiring higher pressure ratings. Belgium and Netherlands suppliers dominate interior lining formulation supply.
- Plastic:PET and PP alternatives capture food-contact applications where migration testing requirements are less stringent than metal formats.
- Composite:Hybrid aluminum-plastic laminates serve premium skincare positioning with enhanced barrier properties and tactile differentiation.
Aluminum commands the largest production footprint. Composite formats are gaining share fastest in premium personal care lines.
Application:
Volume concentration sits with high-frequency consumer products while margin concentration favors specialized industrial formulations.
- Paints:Architectural and automotive coatings demand corrosion-resistant interior linings and hydrocarbon propellant systems. California Air Resources Board districts enforce stricter VOC limits than federal EPA standards.
- Cleaners:Degreasers and disinfectants utilize standard aluminum construction with water-based formulation shifts under REACH compliance pressure.
- Insecticides:Household and agricultural pest control products require specialized valve precision for controlled spray patterns.
- Food Products:Cooking sprays and whipped cream dispensers trigger FDA food-contact notification requirements alongside EU migration testing protocols.
Paints absorb the most specialized coating capacity. Food Products face the steepest certification timeline constraints.
End User:
Procurement patterns diverge between direct-to-retailer consolidation and traditional distributor networks.
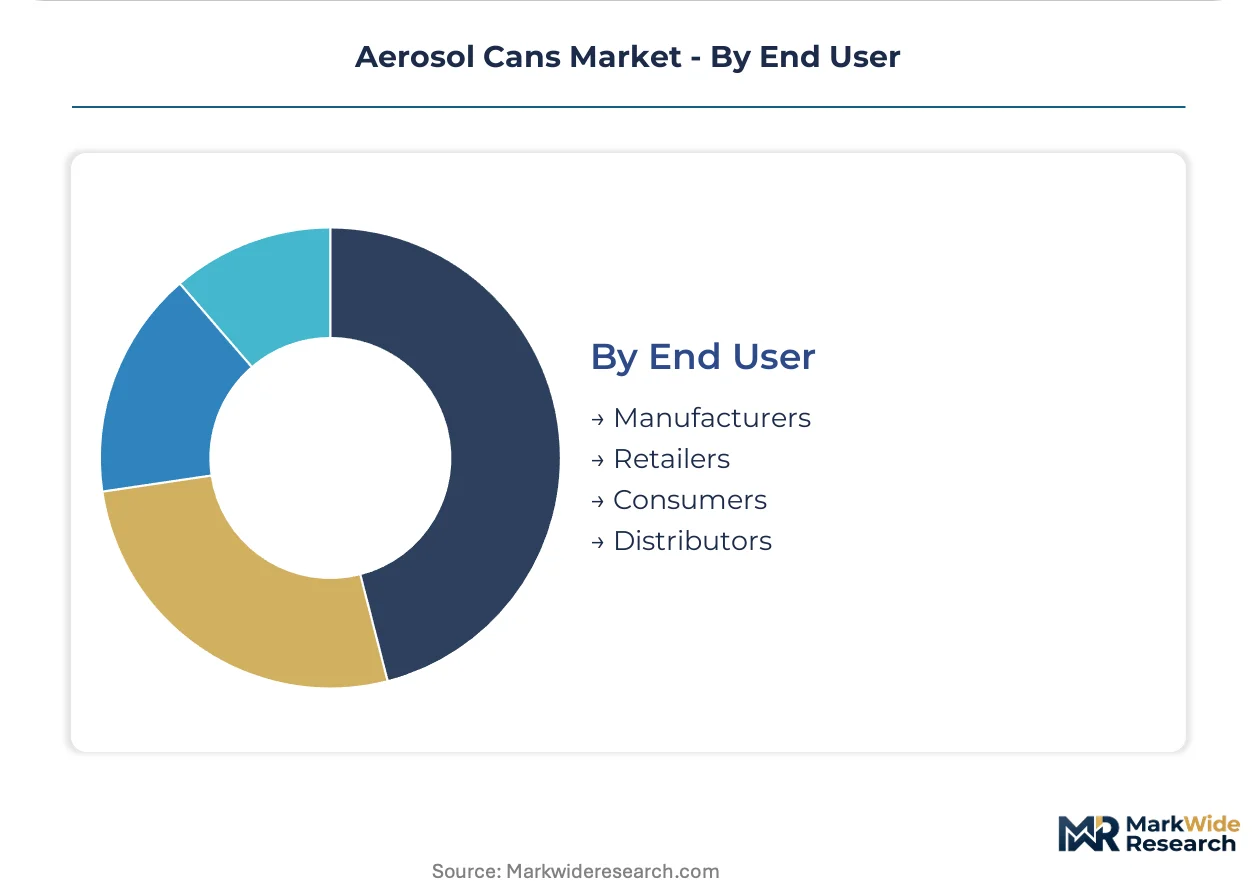
- Manufacturers:Brand owners specify can geometry, coating systems, and valve configurations for dedicated filling lines.
- Retailers:European discounters and drugstore chains negotiate directly with Hamburg and Berlin contract fillers for private-label dry shampoo and sun care lines.
- Consumers:End demand concentrates through e-commerce channels for specialty automotive and industrial aerosol products.
- Distributors:Traditional wholesale roles compress as direct procurement contracts disintermediate regional stockholding.
Retailers are consolidating the fastest volume growth. Distributors face margin compression from channel disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as converters migrate toward jurisdictions with lower compliance costs for volatile organic compound limits. REACH enforcement in Europe compresses margins for legacy propellant systems while compressed gas alternatives gain cost advantages in regulated markets.
Germany
Dry shampoo and sun care demand from private-label retailers drives volume concentration. ECHA REACH restrictions on VOCs force Hamburg and Berlin filling operations toward low-pressure propellant chemistries. The Hamburg-Berlin corridor hosts dedicated contract filling lines for European personal care and household brands.
United States
EPA Significant New Alternatives Policy reviews constrain hydrofluorocarbon propellant options in industrial coatings. California Air Resources Board districts enforce stricter VOC limits than federal standards, creating bifurcated compliance costs. Midwest filling operations serve automotive and industrial aerosol demand with hydrocarbon propellant systems.
India
Deodorant and hair spray penetration remains below European benchmarks, offering volume expansion for converters establishing local partnerships. BIS standards govern container pressure ratings and coating migration limits. Maharashtra and Gujarat host emerging filling capacity for domestic personal care brands.
China
Domestic personal care brands expand aerosol portfolios for tier-one city consumers. MEE enforcement of dual carbon goals pressures converters toward aluminum recyclability credentials. Yangtze River Delta rolling mills supply thinner-walled can stock for high-speed necking equipment.
Brazil
Household insecticide and air freshener demand concentrates in São Paulo and Rio de Janeiro metropolitan markets. ANVISA regulates food-contact coating migration for cooking spray formats. Southeast filling operations serve Latin American export demand through Mercosur trade preferences.
Aerosol Cans Market Vendor Landscape
North American producers anchor one tier through backward integration into aluminum slug production; European specialists hold differentiated positions in printed steel and hybrid designs. The market structure consolidates around three global converters with multi-continent filling line partnerships. Strategic archetypes separate scale-driven aluminum rollers, coating-technology specialists, and hybrid-material innovators. Competitive moves center on captive raw material supply and direct-to-retailer procurement contracts.
Within the integrated aluminum tier, Ball Corporation exemplifies upstream control over slug production. Crown Holdings occupies a position across dedicated aerosol lines on multiple continents. Trivium Packaging represents the hybrid-design archetype through printed steel-aluminum combinations for premium personal care positioning.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| Trivium Packaging |
| CCL Industries |
| Sonoco Products Company |
| Ardagh Group |
| Mauser Packaging Solutions |
| Toyo Seikan Group Holdings |
| Nampak |
| Others |
Supply Flow & Price Mechanics
European private-label retailers negotiating direct procurement contracts with Hamburg and Berlin contract fillers operate on a volume-tiered pricing model that compresses distributor margins and rewards dedicated production lines. This buyer concentration shifts pricing power toward converters with captive aluminum slug supply and multi-format filling flexibility.
Pricing Analysis
Distributor margins in personal care aerosols have compressed from fifteen to eight points as European discounters and drugstore chains negotiate direct-to-filler agreements. Three-tier pricing structure across premium hybrid-composite, standard aluminum, and economy steel formats differentiates converters by recyclability credentials and coating complexity. Pricing pressure stems from REACH compliance costs for epoxy phenolic lining reformulation. Private-label retailers exhibit highest price sensitivity; premium skincare brands tolerate markup for bag-on-valve barrier technology.
Supply Chain Analysis
End-of-life aluminum collection and remelting flows in Germany feed closed-loop slug production for Ball Corporation's European rolling operations. Raw material supply draws from Norwegian primary aluminum and Spanish recycled feedstock, with epoxy phenolic coating chemicals sourced from Belgium and Netherlands specialty chemical producers. Single-source vulnerability concentrates in interior lining formulation supply. Distribution runs through dedicated filling corridors in Hamburg-Berlin for European personal care and São Paulo for Latin American household demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
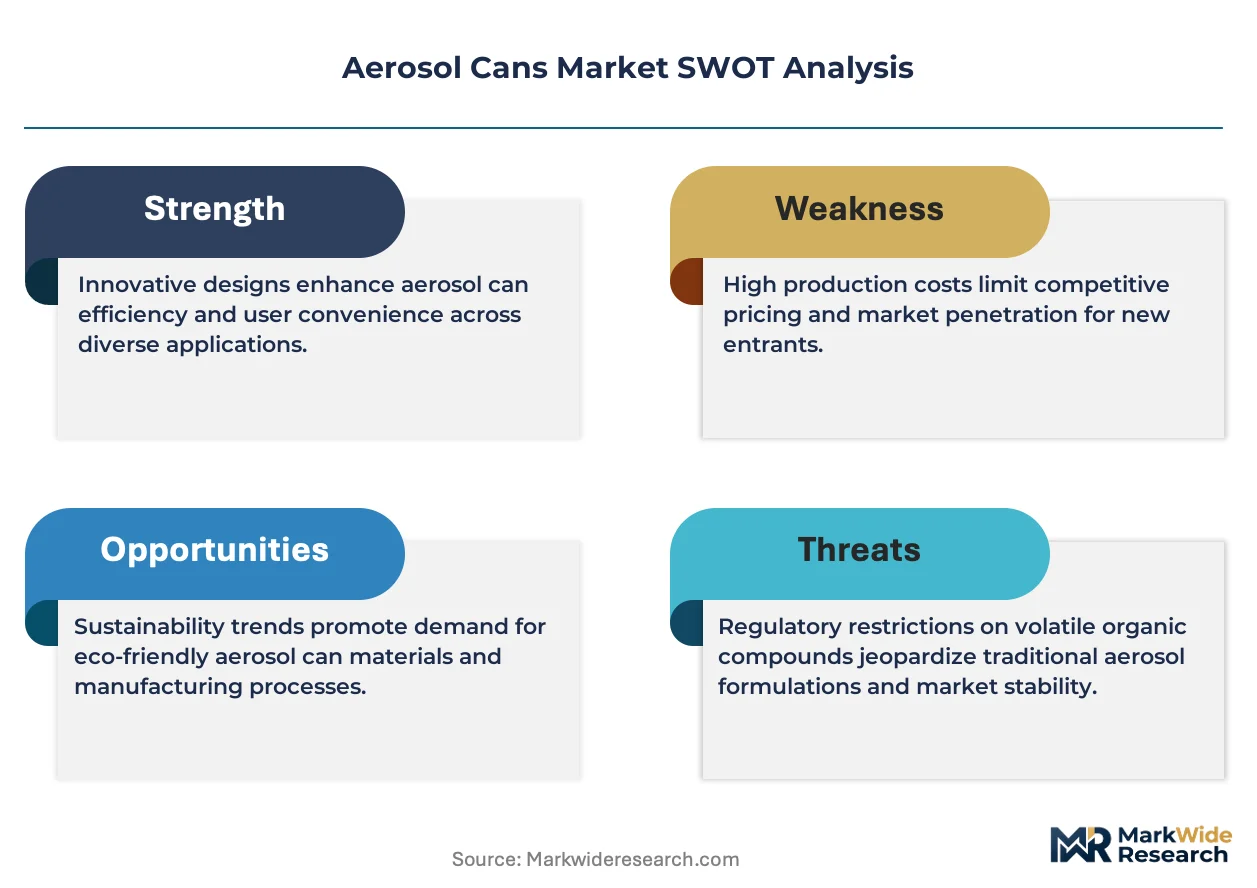
Margin expansion in aerosol packaging hinges on aluminum recyclability premiums and compressed gas propellant adoption reducing REACH compliance burdens. Converters capturing backward integration into slug production secure cost-down advantages unavailable to merchant-market buyers.
For Market Incumbents: Acquire epoxy phenolic coating formulation capabilities to reduce Netherlands-Belgium supplier concentration risk. Expand dedicated aerosol lines in Maharashtra and Gujarat to preempt local Indian converters. Bag-on-valve technology from pharmaceutical skincare entrants threatens premium personal care positioning; defend through hybrid aluminum-plastic laminate patents. For New Entrants and Emerging Players: E-commerce direct-to-consumer channels for specialty automotive and industrial aerosol products bypass compressed distributor networks. Target India's deodorant and hair spray segments where aerosol penetration trails European benchmarks by fifteen points. Partner with Yangtze River Delta rolling mills for thinner-walled aluminum stock supply. For Investors and Strategic Acquirers: Private equity firms with packaging platform experience are the most active acquirer in this space, rolling up mid-cap European converters with REACH-compliant coating expertise. Five-to-ten year viability favors aluminum recyclability credentials under EU Green Deal extended producer responsibility frameworks. Monitor California Air Resources Board district enforcement actions as signal for hydrocarbon propellant cost compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Slug Production | Ball Corporation's captive Norwegian and Spanish feedstock supply locks in raw material cost advantages against merchant-market competitors. |
| Compressed Gas Propellant Transition | REACH VOC limits force Hamburg and Berlin fillers toward nitrogen-based systems with lower regulatory compliance burdens. |
| Bag-on-Valve Technology Licensing | Premium skincare brands in Germany adopt laminated film pouch separation for preservative-free formulation positioning. |
| Direct-to-Retailer Procurement Contracts | European discounters bypass traditional distributors for private-label dry shampoo volume consolidation. |
| Hybrid Material Design Patent Portfolio | Trivium Packaging's printed steel-aluminum combinations defend premium personal care positioning against commodity converters. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with aerosol plant managers, coating formulation chemists, procurement leads at personal care brand owners, and contract filler operations directors with secondary validation. Secondary sources included ECHA REACH substance restriction databases, EU packaging extended producer responsibility framework documents, aluminum trade association recycling statistics, and SEC filings from publicly traded packaging converters. Bottom-up filling line capacity estimates triangulated against top-down personal care shipment data.
Historical reference periods anchored the projection horizon to pre-pandemic baseline volumes and post-REACH implementation cost structures. Segmentation dimensions modeled include material type, product category, propellant chemistry, pressure rating tier, and regional regulatory cluster. CAGRs derived from converter capacity expansion announcements and brand owner portfolio shift intentions. Forecast inputs incorporated aluminum LME price volatility assumptions and epoxy phenolic coating supplier concentration risk.
The model assumes a particular technology adoption path; alternative pathways for water-based compressed gas propellants would alter the outlook if REACH restrictions accelerate beyond current ECHA timelines. Forecasts reflect assumptions about private-label retailer direct procurement momentum and EU Green Deal packaging mandate enforcement intensity. Practitioners should monitor California Air Resources Board district rulemaking and Indian BIS aerosol container standard revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Carbocernaite Market
Specialty Chemicals
Tubatoxin Market
Specialty Chemicals
Alkoxide Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Mequinol Market
Specialty Chemicals
Global Optical Brighteners Market
Specialty Chemicals
Lignin Products Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Asia-Pacific UV Stabilizers Market
Specialty Chemicals
Dimethyl Succinyl Succinate Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Specialty Chemicals Market
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
Sugarcane Wax Market