
 Global Specialty Fuel Additives Market | 2026-2036
Global Specialty Fuel Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Fuel Additives Market Intelligence
Specialty chemical producers in North America and Europe are expanding production capacity for high-performance deposit control additives to meet new engine specifications. The Lubrizol Corporation leverages its extensive R&D infrastructure to develop formulations for next-generation fuels. Afton Chemical specializes in performance additives for gasoline and diesel engines. Infineum International Limited competes on a global scale through its joint venture structure and secure supply chain.
Specialty fuel additives are complex chemical compounds blended into fuels like gasoline, diesel, and jet fuel to optimize performance. Formulations containing polyisobutylene amines (PIBA) or polyetheramines (PEA) are engineered to improve combustion, reduce deposits, and enhance engine longevity. Deposit control additives and detergents constitute the largest product segments, valued for their direct impact on fuel economy. Additives for aviation fuels represent the fastest-growing application, driven by strict aerospace performance and safety mandates.
Regulatory frameworks from the US EPA, the EU's ECHA under the REACH directive, and China's MEE dictate permissible chemical compositions and emission levels. These rules directly shape product development, forcing manufacturers to innovate with lower-sulfur and bio-compatible additive packages. Ultimately, stakeholder success will depend on navigating the divergent timelines of vehicle electrification and the persistent need for cleaner internal combustion engine performance.
Market Dynamics
A persistent need for cleaner internal combustion engine performance, driven by stringent emissions regulations, defines the market's trajectory. This contrasts with the long-term shift to electrification, creating a dual focus on optimizing both legacy and next-generation fuel systems.
Growth Catalysts
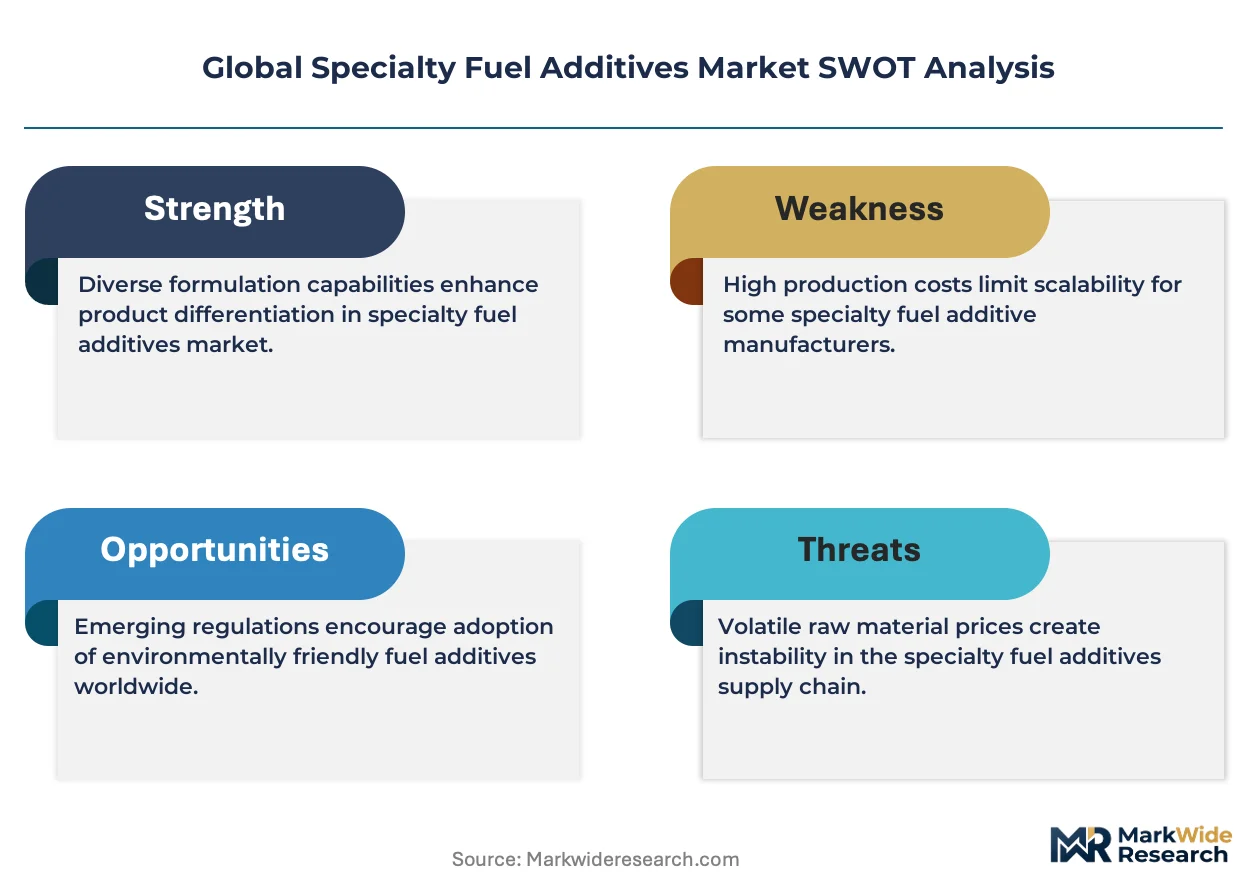
- Emission Control Mandates:Regulations from the EU's FuelEU Maritime initiative to China's MEE standards compel operators to use advanced additive packages for compliance.
- Engine Technology Evolution:Gasoline direct injection (GDI) engines require sophisticated deposit control additives like polyetheramines (PEA) to prevent performance degradation.
- Aerospace Safety Protocols:The aviation industry's strict safety protocols mandate the use of specialized additives for thermal stability and lubricity in jet fuel.
Market Restraints
- Feedstock Price Volatility:Production costs are exposed to price fluctuations in petrochemical precursors like polyisobutylene, creating margin pressure for additive manufacturers.
- Vehicle Electrification:The long-term adoption of battery electric vehicles systematically reduces the addressable market for additives in the passenger car segment.
- Complex Certification Cycles:Additive formulations face lengthy and expensive testing cycles to prove compatibility with biofuels and new engine hardware.
Strategic Opportunities
- Concentrated Marine Demand:Stricter maritime emission rules create demand for additive packages in bunkering hubs like Singapore and Rotterdam.
- Biofuel Blend Stabilizers:Growing biofuel blend mandates require new additives to ensure fuel stability, prevent corrosion, and maintain engine performance.
- Hydrogen Combustion Aids:Research into hydrogen for internal combustion engines opens a frontier for additives that manage challenges like pre-ignition.
Industry Challenges
- Navigating Divergent Regulations:Formulating a single global product is difficult due to conflicting chemical registration requirements between the EU's REACH, the US EPA, and China's MEE.
- Securing Key Intermediates:The supply of high-purity precursors like polyetheramines is concentrated among a few large chemical producers, creating supply chain vulnerability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Fuel Additives Market |
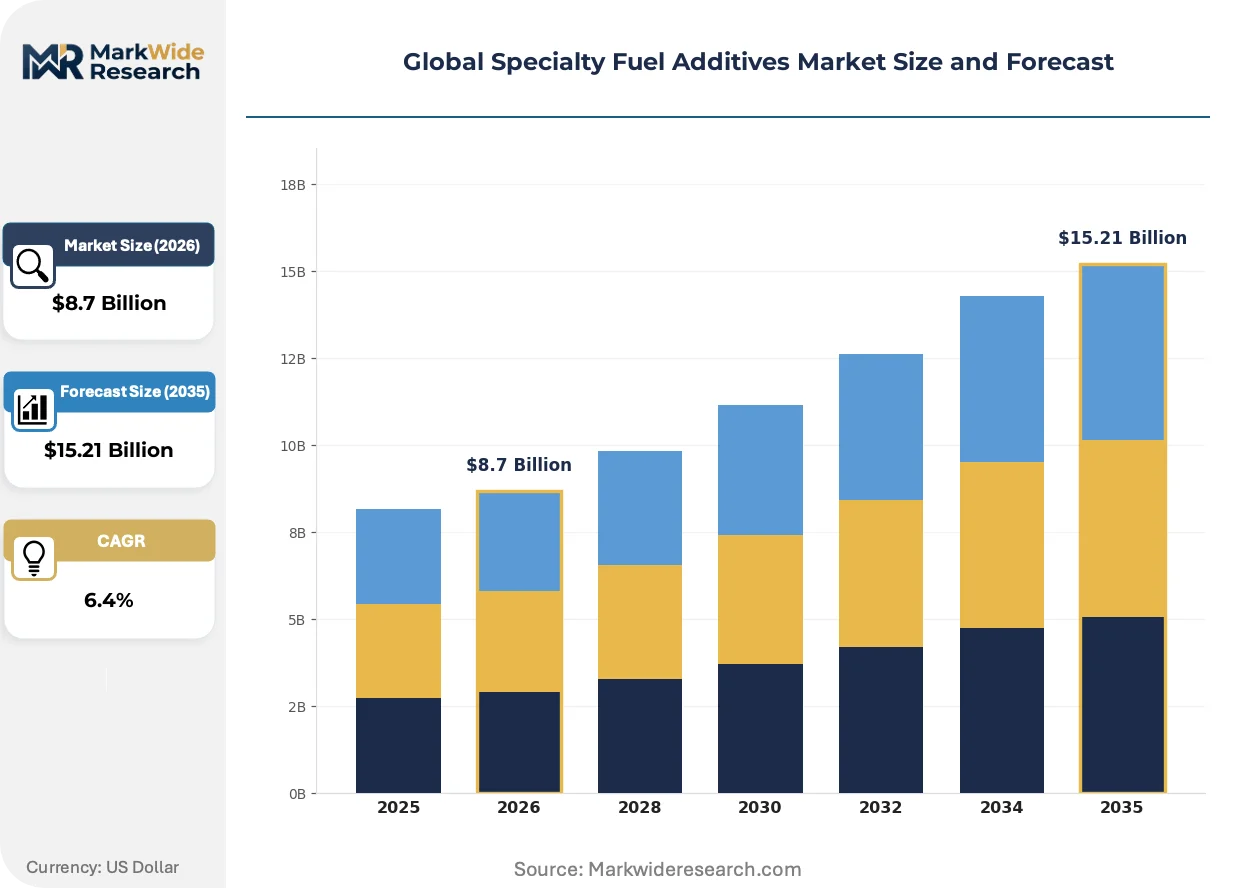
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detergents, Anti-Knock Agents, Corrosion Inhibitors, Deposits Control Additives, Lubricity Improvers Application: Gasoline Engines, Diesel Engines, Marine Engines, Aviation Fuels, Industrial Engines End User Industry: Oil Refineries, Fuel Blenders, Petrochemical Plants, Marine Operators, Aviation Companies Distribution Channel: Direct Sales, Distributors, Online Retailers, Bulk Suppliers, Specialty Chemical Suppliers |
| Companies Covered | The Lubrizol Corporation, Afton Chemical, Innospec, Chevron Corporation, Evonik Industries AG, BASF SE, Dorf Ketal Chemicals, Infineum International Limited, Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Fuel Additives Market Strategic Shifts & Innovations
Innovation in specialty fuel additives is bifurcating between highly specialized formulations for new applications and multifunctional packages for legacy systems. This reflects a dual strategy of supporting both emerging fuel technologies and the vast existing internal combustion engine fleet.
Digital formulation platforms using machine learning accelerate the discovery of new additive molecules. Major chemical producers are adopting these tools to drastically shorten traditional R&D timelines. This computational approach is decentralizing innovation from purely physical testing to a model-driven process, enabling rapid screening against performance and regulatory constraints.
China’s “dual carbon” policy, enforced through the Ministry of Ecology and Environment (MEE), establishes stringent new requirements for fuel quality. This compels suppliers to reformulate products for the Chinese market, emphasizing lower sulfur and ash content. The heavy-duty diesel segment is most impacted, requiring additives that support compliance with China VI emission standards.
End-users are increasingly purchasing fully-formulated additive packages rather than individual components for in-house blending. This model favors large, integrated suppliers who can offer warrantied performance and a simplified path to regulatory compliance. The shift is most pronounced in Europe’s commercial fleet market, driven by complex engine technologies and a focus on total cost of ownership.
Global Specialty Fuel Additives Market Segmentation
Understanding the market through segmentation reveals distinct demand drivers and regulatory influences across various product types, applications, and end-user industries. Each segment presents unique challenges and opportunities for specialty fuel additive manufacturers, necessitating tailored product development and market strategies.
Product Type:
Certain product types face rigorous certification burdens, particularly those intended for highly regulated applications like aviation and marine, shaping their market entry and adoption timelines.
- Deposits Control Additives:These formulations prevent harmful carbon buildup on engine components, improving fuel efficiency and maintaining performance over time. Demand concentrates in gasoline direct injection (GDI) engines due to their specific susceptibility to deposit formation.
- Detergents:Detergents chemically clean fuel system components, ensuring optimal fuel atomization and combustion efficiency in internal combustion engines. Europe's commercial fleet market drives demand for these fully-formulated additive packages.
- Anti-Knock Agents:These compounds increase fuel octane ratings, preventing premature ignition in high-compression engines, critical for high-performance vehicles.
- Corrosion Inhibitors:Formulations protect fuel system metals from degradation, particularly important with increasing biofuel blends that can accelerate corrosion.
- Lubricity Improvers:These additives enhance the lubricating properties of low-sulfur fuels, protecting fuel pumps and injectors from wear in diesel engines.
Deposits Control Additives sits at the top of the volume ranking, with Lubricity Improvers climbing the fastest.
Application:
Application segments differentiate by their unique performance requirements and operational environments, dictating specific additive chemistries.
- Aviation Fuels:Specialized additives ensure thermal stability, anti-icing properties, and lubricity in jet fuels, meeting stringent aerospace performance and safety mandates. Strict safety protocols from regulators like the FAA drive innovation in this segment.
- Marine Engines:Additive packages for marine fuels address challenges like sulfur content, deposit control, and fuel stability, driven by regulations such as the EU's FuelEU Maritime initiative. Demand concentrates in major bunkering hubs like Singapore and Rotterdam.
- Gasoline Engines:Additives optimize combustion, reduce emissions, and prevent deposit formation in gasoline-powered vehicles, supporting compliance with US EPA standards.
- Diesel Engines:Formulations improve cold flow properties, enhance lubricity, and control deposits in diesel engines, especially in heavy-duty commercial vehicles.
- Industrial Engines:This segment requires additives to maintain performance and extend the lifespan of large, stationary engines used in power generation and manufacturing.
The aviation sector mandates highly specialized formulations, while marine engines represent a substantial and expanding volume base.
End User Industry:
End-user industries are distinguished by their procurement scale and technical integration capabilities, influencing additive package customization.
- Oil Refineries:These facilities integrate additives directly into fuel streams during the refining process, requiring bulk supply and technical support for large-scale blending operations. Compliance with national fuel quality standards, such as China's MEE requirements, is paramount.
- Fuel Blenders:Companies that blend various fuel components and additives to meet specific market specifications demand flexible additive solutions and technical expertise. They often purchase fully-formulated additive packages for simplified compliance and performance.
- Petrochemical Plants:These industrial facilities use specialty fuel additives in specific processes or for internal combustion equipment, often requiring tailored solutions.
- Marine Operators:Shipping companies and vessel owners procure additive solutions to ensure compliance with maritime emission regulations and optimize engine performance.
- Aviation Companies:Airlines and aircraft operators require highly certified additives for jet fuel, prioritizing safety, performance, and regulatory adherence from bodies like the FAA.
Oil Refineries and Fuel Blenders represent the largest procurement volumes, with Marine Operators showing significant growth.
Distribution Channel:
Distribution channels vary significantly in their direct engagement with end-users and the complexity of logistics required for specialty chemical delivery.
- Direct Sales:Manufacturers engage directly with large industrial clients and integrated fuel companies, providing technical support, customized solutions, and bulk delivery. This channel is critical for complex, high-volume additive sales.
- Distributors:These intermediaries manage logistics and sales to smaller fuel blenders, regional operators, and specialized industrial clients, offering a broader portfolio of products. Distributors often navigate local regulatory requirements for chemical registration.
- Online Retailers:A nascent channel for smaller volume purchases or niche additive products, offering convenience for specific end-users.
- Bulk Suppliers:Specializing in large-volume deliveries of base additives or common formulations to major industrial users and refineries.
- Specialty Chemical Suppliers:These providers focus on highly technical or customized additive solutions, often for specific performance challenges or emerging fuel types.
Direct sales channels dominate for large-volume customers, while distributors serve fragmented markets efficiently.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Varying regulatory stringencies across global markets influence the production and demand for specialty fuel additives. Manufacturers often assess regional compliance costs when establishing new capacities or optimizing supply chains. This dynamic shapes investment flows and product development priorities for diverse end-use applications.
United States
Demand for specialty fuel additives in the United States stems from strict US EPA emission standards for vehicles and industrial engines. The US EPA mandates specific additive packages to ensure compliance, particularly for gasoline and diesel fuels. Major chemical producers in states like Texas and Louisiana develop advanced formulations for the North American market.
Germany
European demand for specialty fuel additives is significantly influenced by Germany's robust automotive sector and stringent EU environmental regulations. ECHA under the REACH directive dictates permissible chemical compositions, driving innovation in bio-compatible solutions. Chemical manufacturing hubs like Ludwigshafen and Leverkusen specialize in high-performance additive development.
China
China's "dual carbon" policy and MEE regulations create substantial demand for cleaner fuel additive packages. The China VI emission standards particularly impact the heavy-duty diesel segment, necessitating advanced deposit control. Industrial zones in the Yangtze River Delta focus on producing and blending additives for the vast domestic market.
Singapore
Maritime demand for specialty fuel additives concentrates heavily in Singapore, a critical global bunkering hub. The EU's FuelEU Maritime initiative and IMO 2020 regulations compel marine operators to use compliant fuel solutions. Port facilities in Singapore integrate advanced additive blending services to meet international shipping requirements.
Netherlands
The Netherlands, home to the Port of Rotterdam, serves as another pivotal hub for marine fuel additive consumption in Europe. Strict environmental mandates from the EU drive the need for low-sulfur and deposit-controlling additives. Chemical companies in the Rotterdam-Moerdijk industrial complex develop and supply specialized marine fuel treatments.
Global Specialty Fuel Additives Market Key Industry Players
Established producers occupy the standard tier, focusing on high-volume, well-understood additive chemistries, while emerging entrants pursue niche applications in biofuel stabilization and hydrogen combustion. The market structure exhibits a tiered consolidation, with a few global giants dominating core segments and numerous specialized firms serving specific performance needs. Strategic archetypes include integrated chemical conglomerates, specialized additive formulators, and oil majors with in-house capabilities. Key competitive moves include strategic partnerships for R&D and targeted capacity expansions to meet regional demand.
Within the specialized additive formulator archetype, The Lubrizol Corporation represents extensive R&D capabilities for next-generation fuel formulations, particularly for complex combustion systems. Afton Chemical exemplifies a focus on high-performance additives for both gasoline and diesel engines, serving a broad global client base with tailored solutions. Infineum International Limited, through its joint venture structure, anchors a secure global supply chain for complex additive packages, ensuring reliable delivery to major bunkering hubs. These companies leverage their deep technical expertise and strategic market reach to address evolving regulatory and engine technology requirements across diverse applications worldwide.
| Leading Market Players |
|---|
| The Lubrizol Corporation |
| Afton Chemical |
| Innospec |
| Chevron Corporation |
| Evonik Industries AG |
| BASF SE |
| Dorf Ketal Chemicals |
| Infineum International Limited |
| Clariant |
| Others |
Cost & Logistics Intelligence
Polyisobutylene, a key petrochemical precursor, influences the cost structure for specialty fuel additive manufacturers. These raw material costs then propagate through the pricing tiers for fully-formulated additive packages sold to refineries and blenders.
Pricing Analysis
Distributor margins often reflect the complexity of logistics and technical support for specialty chemical delivery. The dominant pricing model is contract-based long-term offtake, particularly for large refinery volumes. Price differentiation stems from specific certification levels and procurement volume scale. Pricing softness stems from intense competition among integrated chemical conglomerates; marine operators and aviation companies exhibit lower price sensitivity than smaller fuel blenders due to compliance and safety mandates.
Supply Chain Analysis
Many large fuel blenders and refineries mandate dual-sourcing for critical additive components, ensuring supply reliability. Supply concentration for key intermediates like polyetheramines is primarily in Germany and China. The supply chain draws from petrochemical precursors such as polyisobutylene and various amines. Single-source vulnerability for high-purity precursors presents a structural risk, while distribution runs through direct sales channels for major industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialty fuel additives market represents a late-cycle quality story, driven by a persistent demand shift toward premium specifications for cleaner internal combustion engine performance. This focus on high-performance formulations aligns with evolving regulatory landscapes and engine technology.
For Market Incumbents:
Cement existing market share by expanding production capacity for high-performance deposit control additives in North America and Europe. Incumbents must also deepen R&D investment into bio-compatible additive packages to counter the long-term threat of vehicle electrification. Investing in rigorous certification processes for new biofuel blends will reinforce market leadership. Securing key intermediate supply chains through strategic partnerships further mitigates supply chain vulnerability.
For New Entrants and Emerging Players:
Digital formulation platforms offer a technology-first wedge into specialized segments like biofuel blend stabilizers and hydrogen combustion aids. New entrants should target the aviation fuels application, given its stringent performance mandates and rapid growth. A focused go-to-market angle involves providing highly specialized technical support for complex next-generation fuel systems. This strategy leverages innovation against the established market positions of incumbents.
For Investors and Strategic Acquirers:
Roll-up economics work for specialized additive formulators because of fragmented niche expertise and complex certification requirements. The market exhibits long-term viability, driven by the persistent need for cleaner internal combustion engine performance and biofuel mandates. Acquisition targets should include mid-cap specialists with proprietary formulations for emerging fuel types. The signal to watch is the acceleration of regulatory harmonization across major economic blocs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding production for high-performance deposit control additives addresses demand from North American engine specifications. |
| Joint Venture | Forming joint ventures secures critical intermediate supply chains from concentrated chemical producers. |
| R&D Investment | Targeted R&D into bio-compatible additive packages meets evolving EU environmental regulations. |
| Product Launch | Introducing new biofuel blend stabilizers supports growing biofuel mandates for marine operators. |
| Geographic Expansion | Entering China's heavy-duty diesel segment aligns with the stringent China VI emission standards. |
Research Approach
Bottom-up marine engine modeling reconciled against top-down specialty chemical producer tracking forms the analytical core of this study. This approach combines insights from primary interviews with R&D directors, procurement leads, refinery managers, and marine fleet operators. Secondary validation draws upon US EPA filings, EU ECHA reports, China MEE regulations, and relevant industry association reports. This triangulation ensures a robust and comprehensive market perspective.
An input-output matrix frames the analytical framework, modeling market dynamics across the analysis window. Segmentation dimensions include product type, application, end-user industry, distribution channel, and regional regulatory cluster. Compound annual growth rates are derived from a weighted average of segment-specific growth trajectories. Key industry-specific forecast inputs include projected global fuel consumption trends and anticipated emission standard updates.
The model holds under stable petrochemical feedstock prices and consistent regulatory enforcement; deviation in geopolitical conflicts or rapid electrification acceleration would shift the outlook. Forecasts reflect assumptions regarding technological advancements and evolving regulatory landscapes. Deviation in feedstock price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Polycarboxylate Ethers (Pces) Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Disodium Adenosine Triphosphate Market
Specialty Chemicals
Phenyl Trimethicone Market
Specialty Chemicals
Brominated Flame Retardants Market
Specialty Chemicals
Alkoxide Market
Specialty Chemicals
Superoxide Dismutase Market
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
Glucosinolates Market
Specialty Chemicals
Europe Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Chemicals
Myrcene Market