
 Sugarcane Wax Market | 2026-2036
Sugarcane Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Sugarcane Wax Market Analysis
Supercritical CO2 extraction is reconfiguring how sugarcane wax gets refined from filter-cake residue, replacing solvent-based methods with cleaner yield profiles. Deurex AG leverages its German engineering base to supply high-purity grades for pharmaceutical coatings. Godavari Biorefineries anchors South Asian supply through integrated sugar-to-wax processing at its Maharashtra facilities. BASF SE extends its position via backward integration into bio-based additives that incorporate sugarcane wax derivatives.
Sugarcane wax is a hard, crystalline lipid extracted from sugarcane filter cake, composed primarily of long-chain alcohols, esters, and hydrocarbons with melting points between 78°C and 82°C, serving as a functional substitute for carnauba and synthetic waxes in surface protection and barrier applications. Natural wax commands the dominant share due to clean-label pull from cosmetic and food packaging buyers, while coating wax represents the fastest-expanding product type as industrial formulators seek plant-based alternatives to petroleum-derived slip agents. In application terms, cosmetics absorbs the highest-margin volumes, whereas food packaging generates the largest tonnage throughput across distribution networks.
EMA standards for pharmaceutical-grade excipients and REACH registration requirements for chemical imports into Europe jointly elevate compliance costs for non-European suppliers. EPA guidelines under the Toxic Substances Control Act govern wax classifications in US industrial coatings, shaping how producers label and ship cross-border. FDA food-contact regulations determine which purification grades qualify for direct food packaging applications. Stakeholders must track evolving bio-based content thresholds in EU Green Deal procurement rules and assess whether captive sugarcane sourcing or third-party filter-cake purchasing offers more resilient margin structures.
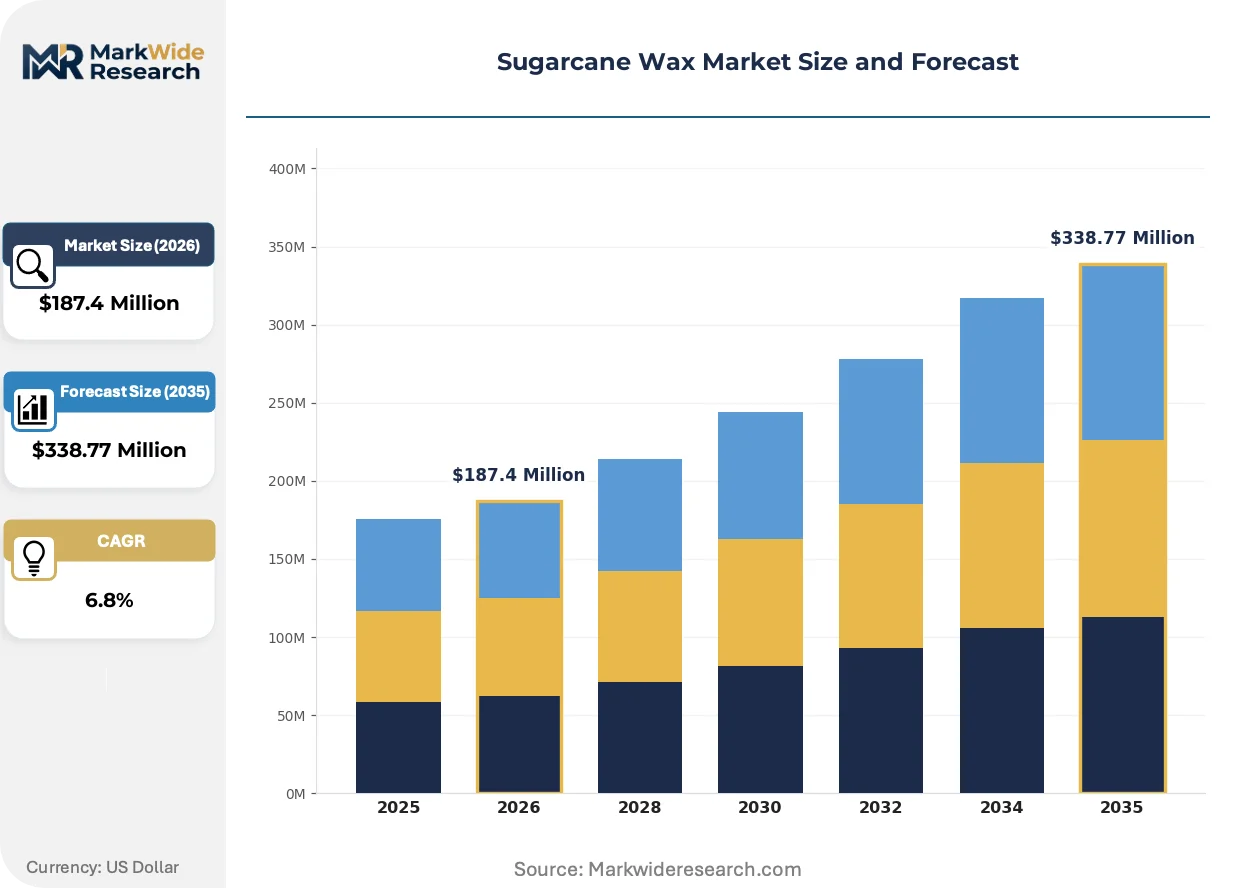
Market Dynamics
Supercritical CO2 extraction is consolidating control over sugarcane wax purification, compressing the competitive set around producers who can achieve pharmaceutical-grade purity without solvent residues. This technology shift is redistributing margin from traditional solvent-based refiners to integrated biorefinery operators.
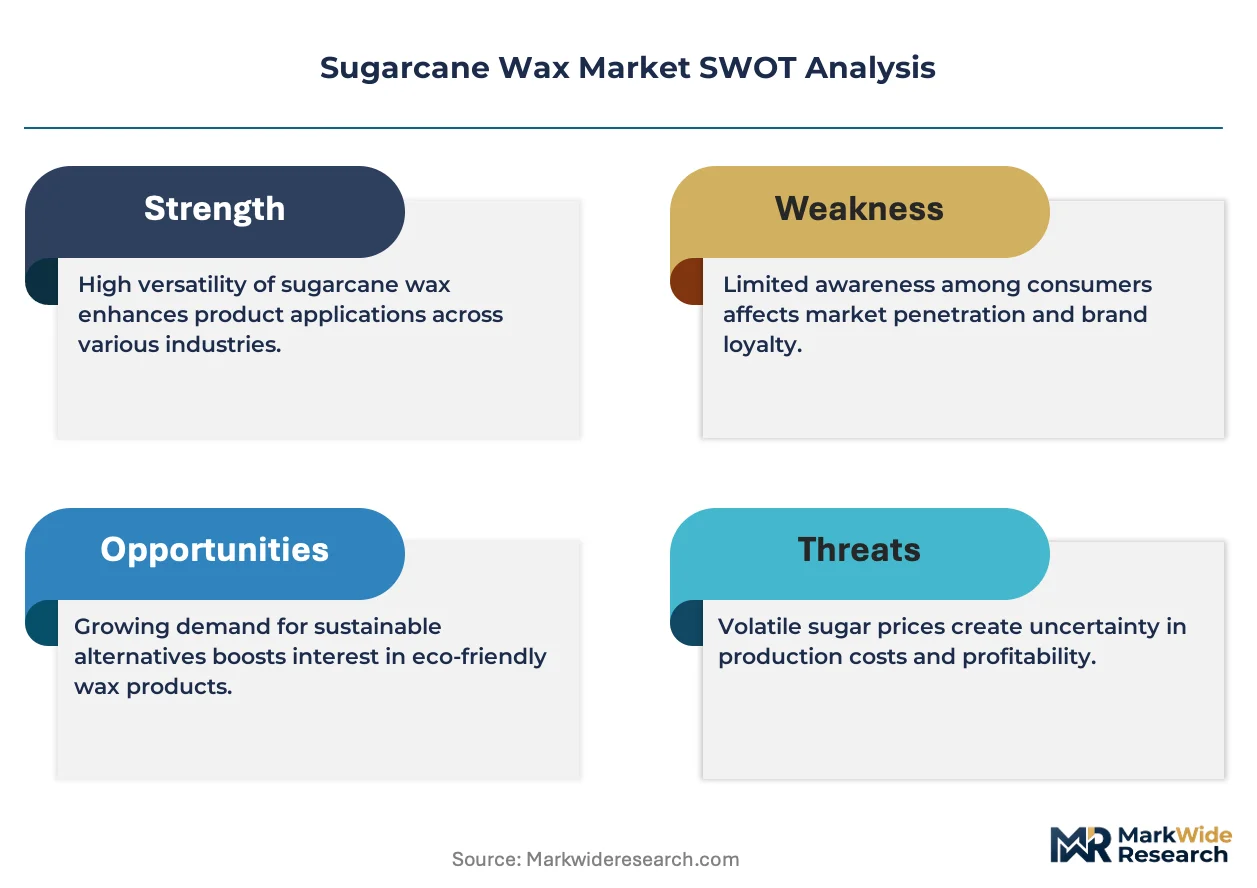
Growth Catalysts
- REACH compliance thresholds:European ECHA mandates for chemical purity in personal care formulations are filtering out low-grade imports and redirecting volume toward certified refiners.
- Cosmetics sector pull:Clean-label beauty brands are specifying plant-derived waxes for lipstick and cream formulations, creating dedicated supply contracts.
- Brazilian upstream concentration:Sao Paulo state's integrated sugar-to-wax processing clusters capture economies of scale in filter-cake collection and initial refining stages.
Market Restraints
- Filter-cake supply volatility:Raw material availability fluctuates with Brazilian sugarcane harvest cycles and ethanol pricing arbitrage decisions.
- Carnauba substitution threat:Amazon-sourced palm wax offers comparable hardness properties at lower certification burden for non-pharmaceutical applications.
- Supercritical equipment capex:High-pressure CO2 extraction systems require substantial capital deployment, freezing out mid-scale processors.
Strategic Opportunities
- Indian pharmaceutical excipient demand:CDSCO registration pathways for natural waxes in tablet coatings remain underdeveloped relative to synthetic alternatives.
- EU Green Deal bio-content mandates:Procurement rules for sustainable packaging are creating preferential sourcing windows for certified plant-derived inputs.
- Food packaging barrier films:Edible and biodegradable coating applications for fresh produce represent an emerging high-volume outlet.
Industry Challenges
- Pharmaceutical-grade certification timelines:EMA excipient qualification processes extend 18-24 months, delaying revenue recognition for new entrants.
- Skilled extraction technicians:Supercritical CO2 operation requires specialized training unavailable in traditional sugar processing labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugarcane Wax Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Wax, Synthetic Wax, Blended Wax, Coating Wax Application: Cosmetics, Food Packaging, Candles, Coatings End User: Food Industry, Personal Care, Pharmaceutical, Automotive Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Deurex AG, Cerax, BASF SE, Godavari Biorefineries, Huzhou Shengtao Biotech LLC, Cargill, Origen Chemicals, Evonik Industries AG, Kraton Performance Polymers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugarcane Wax Market Emerging Trajectories
Extraction technology and regulatory compliance frameworks are converging to reshape competitive positioning in sugarcane wax supply. Producers must now integrate purification capabilities with traceability systems to maintain access to premium segments.
Supercritical CO2 extraction systems are replacing hexane-based solvent methods in commercial-scale sugarcane wax refining. Pharmaceutical coating manufacturers are prioritizing solvent-free grades for tablet film applications. This shift is rendering obsolete the cost advantage previously held by conventional solvent refiners who cannot meet residual solvent limits.
REACH registration requirements for chemical substances imported into Europe are tightening purity documentation standards. Wax suppliers must now submit comprehensive toxicological dossiers to ECHA for market access. Personal care formulators are responding by consolidating supplier bases around pre-registered European refiners with established compliance infrastructure.
Long-term supply agreements are displacing spot-market purchasing in cosmetic and pharmaceutical procurement. Brand owners are locking in multi-year contracts with certified refiners to secure traceability for clean-label claims. This pattern is most pronounced in German and French personal care markets where retailer sustainability scorecards penalize supply chain opacity.
Sugarcane Wax Market Segmentation
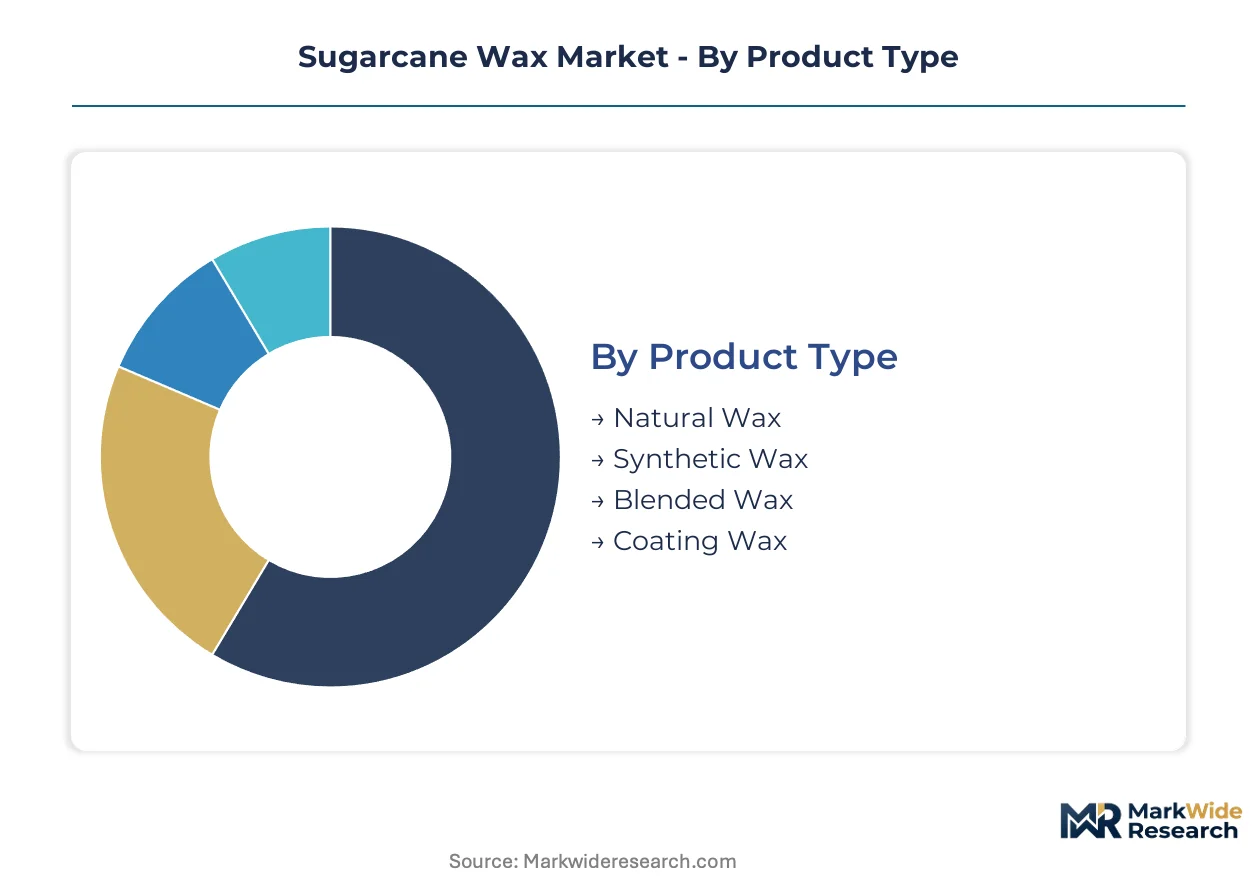
Sugarcane wax procurement cycles vary dramatically across end-use sectors, with food packaging buyers turning inventory monthly while pharmaceutical qualification extends across years. Understanding these velocity differentials helps suppliers align purification investments with contract structures.
Product Type:
Natural wax commands the longest production cycles due to harvest-dependent raw material flows, while synthetic and blended alternatives offer shorter, more predictable lead times.
- Natural Wax:Extracted directly from sugarcane filter cake through supercritical CO2 or solvent methods, this grade contains long-chain alcohols and esters with melting points between 78°C and 82°C. Clean-label cosmetics manufacturers in Germany and France specify this grade for lipstick and cream formulations, though ECHA REACH registration requirements extend procurement timelines. Natural wax anchors the volume base while coating wax gains share at the steepest rate.
- Coating Wax:Engineered specifically for surface protection applications, this segment delivers controlled slip and barrier properties for food packaging films. Industrial formulators seeking petroleum alternatives drive specification shifts in EU Green Deal procurement windows.
- Synthetic Wax:Petroleum-derived substitutes formulated to match sugarcane wax hardness properties, serving price-sensitive candle and coating applications where bio-content certification is not required.
- Blended Wax:Hybrid formulations combining natural and synthetic fractions to optimize cost-performance ratios for mid-tier personal care and automotive applications.
Natural wax captures the highest absolute tonnage while coating wax climbs the fastest as packaging sustainability mandates tighten across European markets.
Application:
Margin structures diverge sharply across applications, with cosmetics commanding premium pricing for pharmaceutical-grade purity and food packaging operating on volume-scaled economics.
- Cosmetics:Lipstick, cream, and balm formulations require high-purity grades with complete solvent residue elimination. EMA excipient standards and retailer sustainability scorecards in France and Germany consolidate demand around certified European refiners.
- Food Packaging:Edible coatings and barrier films for fresh produce represent the largest throughput channel, with FDA food-contact regulations determining qualification pathways for direct packaging applications.
- Candles:Fragrance retention and burn characteristics position sugarcane wax as a carnauba alternative, though Amazon-sourced palm wax competes on certification simplicity.
- Coatings:Industrial surface protection and slip agents for automotive and furniture applications, where EPA TSCA classifications under US guidelines shape cross-border shipment labeling.
Food packaging generates the highest tonnage flows while cosmetics delivers the steepest margin expansion.
End User:
Regulatory complexity scales with end-user sophistication, from FSSAI food safety compliance for Indian food processors to CDSCO pharmaceutical registration for tablet coating applications.
- Food Industry:Fresh produce packaging and edible coating applications across Brazilian, Indian, and European supply chains, with bio-based content thresholds in EU procurement rules driving specification shifts.
- Personal Care:Clean-label beauty brands specifying plant-derived inputs, with long-term supply agreements displacing spot purchasing to secure traceability documentation.
- Pharmaceutical:Tablet film coatings and excipient applications requiring EMA or FDA qualification, where 18-24 month certification timelines delay revenue recognition for new entrants.
- Automotive:Surface protection and mold release applications, with REACH compliance for chemical imports filtering supplier bases toward pre-registered European refiners.
The food industry absorbs the highest volumes while pharmaceutical applications expand most quickly on excipient demand growth.
Distribution Channel:
Channel selection reflects buyer scale and technical support requirements, with direct sales dominating pharmaceutical procurement and wholesale serving fragmented food industry accounts.
- Direct Sales:Multi-year contracts with certified refiners for cosmetic and pharmaceutical manufacturers requiring traceability documentation and technical collaboration on formulation integration.
- Wholesale:Volume distribution to mid-scale food packaging and candle producers, with Brazilian integrated biorefineries capturing economies of scale in Sao Paulo state processing clusters.
- Specialty Stores:Small-batch supply for artisan candle makers and independent cosmetics formulators seeking certified natural grades.
- Online Retail:Emerging channel for sample quantities and technical documentation access, particularly for Indian and Southeast Asian processors evaluating supplier qualifications.
Direct sales locks in the highest-value contracts while online retail expands most quickly as digital procurement penetrates mid-scale processing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian filter-cake exports flow primarily to German pharmaceutical refiners and Indian biorefinery processors, establishing a three-pole trade architecture that concentrates value-adding steps outside raw material origins.
Brazil
São Paulo state's integrated sugar-to-wax clusters capture economies of scale in upstream extraction, with ANVISA registration requirements for pharmaceutical-grade exports filtering supplier bases toward certified processors. São Paulo city anchors the largest concentration of supercritical CO2 capacity serving European cosmetic formulators.
Germany
REACH compliance thresholds under ECHA mandates redirect cosmetic and pharmaceutical demand toward domestic refiners with established toxicological dossiers. Deurex AG exemplifies the engineering-intensive archetype supplying high-purity grades for tablet coatings. Hamburg and Frankfurt processing hubs concentrate EMA-registered excipient production.
India
CDSCO registration pathways for natural wax excipients remain underdeveloped relative to synthetic alternatives, creating first-mover advantages for integrated domestic biorefineries. Godavari Biorefineries anchors South Asian supply through Maharashtra facilities processing captive sugar streams. Mumbai and Pune clusters drive pharmaceutical formulation demand.
United States
EPA TSCA classifications govern wax shipments for industrial coating applications, shaping cross-border labeling requirements for Brazilian imports. FDA food-contact regulations determine qualification pathways for edible packaging films. Texas and California processing centers concentrate personal care formulation demand.
China
GB standards for food-contact materials and SAMR registration requirements filter import quality tiers, with domestic biorefineries scaling supercritical extraction for pharmaceutical-grade output. Zhejiang and Jiangsu provinces concentrate cosmetic manufacturing demand that pulls certified wax volumes.
Sugarcane Wax Market Vendor Landscape
On the supply side, the industry is consolidating around integrated biorefinery operators with captive supercritical CO2 capacity, compressing the competitive set as solvent-based refiners lose pharmaceutical-grade access. Three strategic archetypes dominate: Brazilian upstream integrators controlling filter-cake flows, German engineering specialists commanding premium pharmaceutical segments, and Asian biorefineries scaling for regional food packaging demand. Dominant competitive moves include backward integration into sugar processing and technology licensing for supercritical extraction systems.
Among German engineering-based specialists, Deurex AG occupies a position exemplifying high-purity pharmaceutical supply, while BASF SE represents the diversified chemical conglomerate archetype extending into bio-based additives. Godavari Biorefineries anchors the integrated Asian biorefinery tier, demonstrating scale advantages from captive sugar sourcing.
| Leading Market Players |
|---|
| Deurex AG |
| Cerax |
| BASF SE |
| Godavari Biorefineries |
| Huzhou Shengtao Biotech LLC |
| Cargill |
| Origen Chemicals |
| Evonik Industries AG |
| Kraton Performance Polymers |
| Others |
Supply Flow & Price Mechanics
São Paulo state's integrated sugar-to-wax processing clusters concentrate upstream extraction capacity, translating raw material dominance into pricing leverage over downstream refiners in Germany and India. This geographic concentration enables Brazilian operators to command premium terms for pharmaceutical-grade filter-cake exports while compressing margins for solvent-based competitors unable to meet REACH purity thresholds.
Pricing Analysis
Supercritical CO2 extraction systems command a 40-60% premium over legacy hexane-based refining methods, creating a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on EMA excipient certification status and residual solvent documentation, with pharmaceutical buyers showing minimal price sensitivity compared to candle manufacturers. Pricing pressure stems from carnauba wax substitution in non-certified applications, forcing mid-tier refiners toward volume discounts. Food packaging buyers exhibit highest price sensitivity, while cosmetics formulators absorb premiums for traceability documentation.
Supply Chain Analysis
EU REACH registration requirements function as de facto export controls, filtering out non-compliant suppliers and restricting pharmaceutical-grade flows to pre-registered European refiners. Supply concentrates in Brazil, Germany, and India, with raw material flows drawing from sugarcane filter-cake, supercritical CO2 equipment, and EMA toxicological dossiers. Single-source vulnerability runs through São Paulo's harvest-dependent filter-cake collection networks. Distribution runs through direct sales contracts for pharmaceutical and cosmetic buyers, with wholesale channels serving fragmented food industry accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment protects incumbent positions. EMA and REACH compliance timelines create switching costs that lock pharmaceutical buyers into qualified supplier relationships.
For Market Incumbents: Entrench market position by deepening backward integration into captive sugarcane sourcing in São Paulo state, eliminating filter-cake supply volatility. Invest in supercritical CO2 capacity expansion to defend against emerging Asian biorefineries. Lock in multi-year offtake agreements with German and French cosmetics formulators before CDSCO pathways mature in India.
For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical excipient supply, where CDSCO registration gaps create first-mover windows against synthetic alternatives. Target food packaging barrier film applications in EU Green Deal procurement windows, where bio-content mandates outpace certified supply. Lead with supercritical CO2 technology licensing rather than capital-heavy capacity builds.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because compliance infrastructure appreciates as REACH and EMA thresholds tighten. Target integrated biorefineries with captive sugar streams and existing ECHA registrations. Watch for Brazilian harvest shortfalls as inflection indicators that would compress filter-cake availability and accelerate consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sugarcane Processing | Captive filter-cake supply insulates margin from Brazilian harvest volatility and ethanol pricing arbitrage. |
| Supercritical CO2 Capacity Expansion | Pharmaceutical-grade purity without solvent residues opens EMA-registered excipient segments closed to competitors. |
| EMA Excipient Pre-Registration | Toxicological dossier submission creates 18-24 month competitive moats against unregistered imports. |
| Long-Term Supply Agreement with Cosmetics Formulators | Multi-year contracts with German and French brands secure traceability documentation for clean-label claims. |
| Joint Venture with Indian Biorefinery | CDSCO registration leverage and Maharashtra processing access unlock pharmaceutical demand in underserved South Asian markets. |
Methodological Framework
Two parallel data streams informed the analysis: structured interviews with sugarcane wax refinery plant managers, procurement leads at German pharmaceutical OEMs, distribution channel partners in São Paulo, and technical R&D directors at supercritical equipment manufacturers; and secondary validation through customs/trade data, ECHA registration databases, SEC filings from diversified chemical conglomerates, and ANVISA export certification records. Bottom-up volume estimates from filter-cake processing capacities were triangulated against top-down demand projections from cosmetics and pharmaceutical formulation trends.
Forecast inputs span product type segmentation across natural, coating, synthetic, and blended wax grades; application dimensions covering cosmetics, food packaging, candles, and industrial coatings; and end-user categories including personal care, pharmaceutical, food industry, and automotive. CAGRs were derived from regression analysis against historical sugarcane harvest volumes, ethanol pricing spreads, and REACH compliance adoption curves across European formulators. Industry-specific inputs include supercritical CO2 equipment deployment timelines and EMA excipient qualification pipeline data.
Stress conditions across Brazilian sugarcane yield variance, REACH registration fee escalation, and carnauba wax price competition were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology adoption rates and regulatory enforcement intensity. Material shifts in EU Green Deal bio-content mandate timelines or CDSCO excipient pathway acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Chemical Vapor Deposition (CVD) Market
Specialty Chemicals
Cellulose Acetate Phthalate Market
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market
Specialty Chemicals
North America Sulfonylureas Market
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
Dimethyl Silicone Market
Specialty Chemicals
Copovidone Market
Specialty Chemicals
North America Sugarcane Wax Market
Specialty Chemicals
Carbocernaite Market
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
Precipitated Barium Sulfate Market