
 Phenol Market | 2026-2036
Phenol Market Size, Share, and Industry Trends Forecast 2026-2036
Phenol Market Intelligence
The EU Green Deal's industrial decarbonization mandates is expanding pressure on phenol producers to cut process emissions and adopt circular feedstock models. INEOS Phenol leverages its integrated cumene-to-phenol infrastructure across Rotterdam and Antwerp to sustain cost-advantaged supply to European resin makers. Mitsubishi Chemical Group Corporation anchors its position through specialized high-purity phenol grades for electronic materials, while SABIC competes via backward integration into refinery-sourced benzene in Saudi Arabia.
Phenol is an aromatic organic compound with the formula C₆H₅OH, produced primarily through the cumene oxidation process involving air oxidation of cumene to cumene hydroperoxide followed by acid-catalyzed cleavage. Its hydroxyl group attached to a benzene ring enables reactivity with formaldehyde to form phenol-formaldehyde resins and with acetone to yield bisphenol A, the backbone of polycarbonate plastics and epoxy coatings. The phenol derivatives segment dominates value capture due to bisphenol A's entrenched role in automotive and electronics supply chains, while pharmaceutical-grade phenol posts faster structural growth driven by vaccine stabilizers and topical antiseptic demand. Acetone co-production economics heavily influence regional operating rates, with integrated producers holding margin advantages over merchant phenol buyers.
EPA air toxics standards and OSHA permissible exposure limits shape US plant design and worker safety protocols, while China's MEE enforces wastewater discharge limits on phenol concentration in the Yangtze River basin. The EU F-Gas Regulation indirectly affects phenol demand through refrigerant phase-downs that shift insulation foam chemistry toward phenolic alternatives. Stakeholders must monitor cumene supply tightness, bio-phenol pilot scale-up timelines, and regional carbon border adjustments that could restructure trade flows between Middle Eastern feedstock hubs and Asian derivative manufacturers.
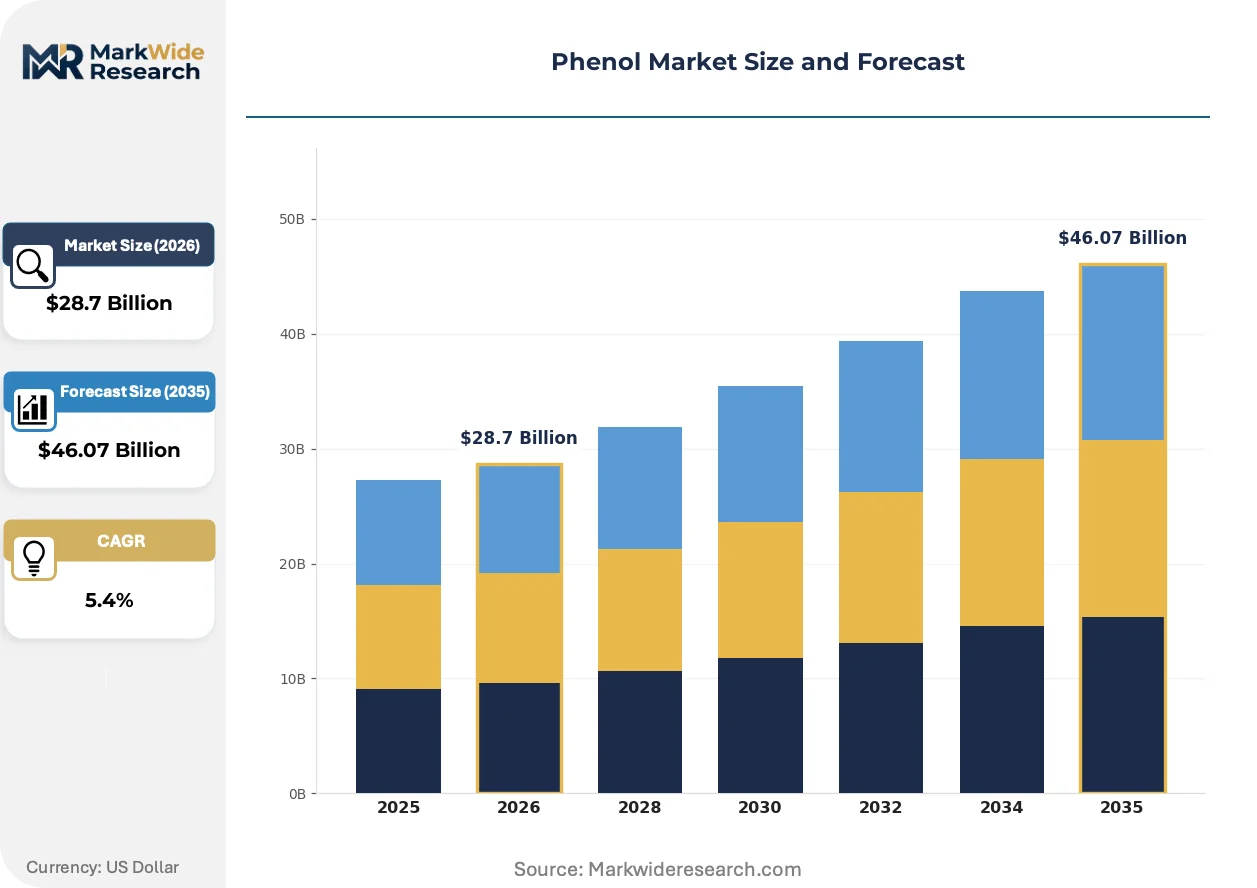
Market Dynamics
Automotive electrification is compressing demand cycles for phenolic composites as electric vehicle manufacturers redesign thermal management systems and battery enclosures around lightweight, fire-resistant materials. This structural shift is pulling cumene-phenol capacity toward specialized resin grades and away from commodity bisphenol A feedstock.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates are redirecting polyurethane foam chemistry toward phenolic insulation alternatives in European HVAC retrofit markets.
- Electric vehicle battery housings:Thermal runaway protection requirements are embedding phenolic composites into EV underbody shields and module separators.
- China's dual carbon goals:National emissions intensity targets are accelerating cumene-to-phenol process optimization investments in Shandong and Zhejiang province clusters.
Market Restraints
- Benzene cost volatility:Refinery feedstock price swings transmit directly into cumene economics, compressing merchant phenol margins during crude oil spikes.
- Propylene co-dependency:Acetone oversupply in Middle Eastern export hubs forces operating rate cuts at integrated phenol-acetone complexes regardless of phenol demand.
- REACH substance restrictions:ECHA candidate list scrutiny on formaldehyde-based resins is creating downstream substitution pressure in European construction adhesives.
Strategic Opportunities
- India PLI scheme for chemicals:Production-linked incentive allocations for specialty chemicals are drawing phenol derivative investments toward Gujarat and Maharashtra industrial corridors.
- Bio-cumene pilot scale-up:Lignin-to-cumene technology convergence offers pathway to renewable phenol for cosmetics and pharmaceutical-grade applications.
- Phenolic aerogel insulation:Emerging building energy codes in Japan and South Korea are opening specification channels for high-performance thermal barriers in net-zero retrofits.
Industry Challenges
- Process safety certification:OSHA PSM and Seveso III compliance timelines extend by 18-24 months for cumene oxidation unit expansions due to hydroperoxide handling protocols.
- Skilled operations talent:Experienced cumene oxidation operators and catalytic cleavage specialists are concentrating at legacy US Gulf Coast and Rotterdam-Antwerp complexes, constraining greenfield staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenol Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $46.07 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenol Derivatives, Aniline, Formaldehyde, Acetone Application: Plastics, Pharmaceuticals, Resins, Paints End User: Chemical Industry, Automotive Sector, Healthcare, Consumer Goods Distribution Channel: Direct Sales, Online, Distributors, Retail |
| Companies Covered | Kumho P&B Chemicals, Chang Chun Group, INEOS Phenol, Zhejiang Petroleum & Chemical Co Ltd, Moeve, Mitsubishi Chemical Group Corporation, Formosa Chemicals & Fibre Corporation, SABIC, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenol Market Strategic Shifts & Innovations
Process intensification and feedstock diversification are splitting the phenol competitive landscape into two tracks: legacy cumene oxidation optimization versus bio-based aromatic pilot commercialization. Technology deployment pace varies sharply by end-use purity requirements.
Membrane-assisted cumene oxidation is expanding into commercial units at select European and Chinese complexes. This technology replaces traditional air-sparged reactors with selective oxygen permeation membranes, cutting energy intensity and peroxide decomposition losses. Automotive resin producers in Germany and Japan are qualifying output from these units for high-purity phenolic novolac specifications, compressing the cost gap between standard and electronic-grade material.
REACH authorization procedures for formaldehyde-releasing substances are tightening disclosure requirements across European wood panel and insulation supply chains. Manufacturers are reformulating phenol-formaldehyde resins toward lower free-formaldehyde emission profiles or shifting toward phenol-resorcinol alternatives in structural adhesives. Construction-grade phenolic producers in Belgium and the Netherlands are investing in continuous resin cookers with real-time emission monitoring to maintain specification access.
Buyer consolidation among polycarbonate compounders is lengthening contract durations and compressing spot market liquidity for merchant phenol. Tier-one automotive suppliers in China and Mexico are negotiating three-to-five-year offtake agreements directly with integrated cumene-phenol-bisphenol A producers, displacing traditional distributor intermediaries in volume procurement. This pattern is most visible in Yangtze River Delta electronics manufacturing clusters where just-in-time resin delivery requirements favor captive supply relationships.
Phenol Market Segmentation
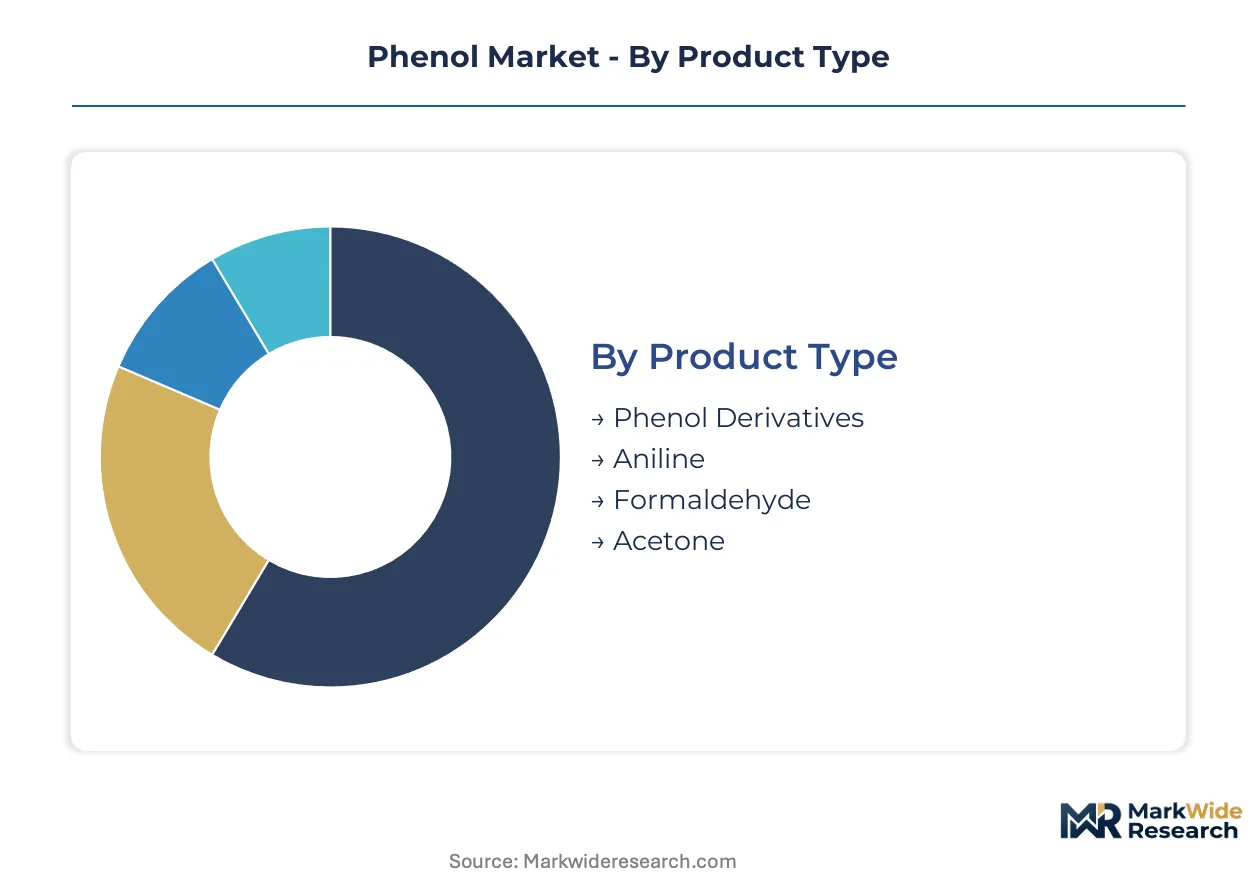
Phenol market segmentation reveals distinct upgrade cycles across derivative chemistry and end-use specifications. Each dimension carries specific margin structures and regulatory exposure that reshape procurement patterns for integrated versus merchant buyers.
Product Type:
Replacement cycles vary sharply by derivative complexity, with commodity-grade materials facing shorter specification horizons than pharmaceutical and electronic grades.
- Phenol Derivatives:Bisphenol A and phenolic resins constitute the primary value capture, with cumene-to-phenol-bisphenol A complexes in China and the Middle East driving volume economics. Automotive polycarbonate and epoxy coating specifications are pulling capacity toward high-purity grades.
- Aniline:MDI precursor demand anchors this segment, with polyurethane flexible foam applications in furniture and automotive seating concentrating consumption in East Asian manufacturing clusters. REACH substance restrictions on isocyanates are tightening handling protocols.
- Formaldehyde:Urea-formaldehyde resins for wood panel binders dominate volume, though ECHA scrutiny on emission profiles is accelerating low-emission formulation upgrades in European construction.
- Acetone:Co-product economics from cumene oxidation heavily influence phenol operating rates, with solvent and methyl methacrylate applications absorbing Middle Eastern export volumes.
Volume placements concentrate in phenol derivatives; the faster expansion belongs to pharmaceutical-grade aniline for vaccine adjuvant applications.
Application:
Cost tier differentiation separates specification-intensive applications from commodity volume plays, with certification requirements driving margin stratification.
- Plastics:Polycarbonate and epoxy resin formulations absorb the majority of bisphenol A output, with electric vehicle battery housing specifications embedding fire-resistant phenolic composites. China's Yangtze River Delta electronics clusters anchor derivative demand.
- Pharmaceuticals:Vaccine stabilizers and topical antiseptics require USP-grade phenol with stringent impurity limits, constraining qualified supply to dedicated pharmaceutical chemical producers in Germany, Switzerland, and India.
- Resins:Phenol-formaldehyde novolac and resole grades serve friction materials, foundry binders, and insulation foam, with EU F-Gas Regulation phase-downs redirecting HVAC chemistry toward phenolic alternatives.
- Paints:Epoxy coating systems for marine and industrial protection consume specialty phenolic resins, though waterborne formulation shifts are compressing solvent-based demand in European regulatory jurisdictions.
Margin concentration sits with pharmaceutical applications; paints are gaining share fastest through industrial protective coating specifications in Asian shipbuilding.
End User:
Customer type determines contract structure, with integrated chemical producers favoring long-term offtake while automotive and healthcare buyers prioritize just-in-time qualification.
- Chemical Industry:Captive consumption within cumene-phenol-bisphenol A complexes dominates, with INEOS Phenol and SABIC leveraging backward integration into refinery feedstocks to secure cost-advantaged supply.
- Automotive Sector:Electric vehicle thermal management redesigns are embedding phenolic composites into battery enclosures and underbody shields, with OEMs in Germany, Japan, and China qualifying specialized resin grades.
- Healthcare:Vaccine manufacturers and hospital supply chains drive pharmaceutical-grade phenol demand, with FDA and EMA GMP certification requirements limiting qualified supplier pools.
- Consumer Goods:Electronics housings and appliance components consume polycarbonate derivatives, with brand-owner sustainability mandates pressuring recycled-content specifications.
Procurement scale concentrates in chemical industry captives; healthcare is climbing the fastest on pandemic-era vaccine capacity investments.
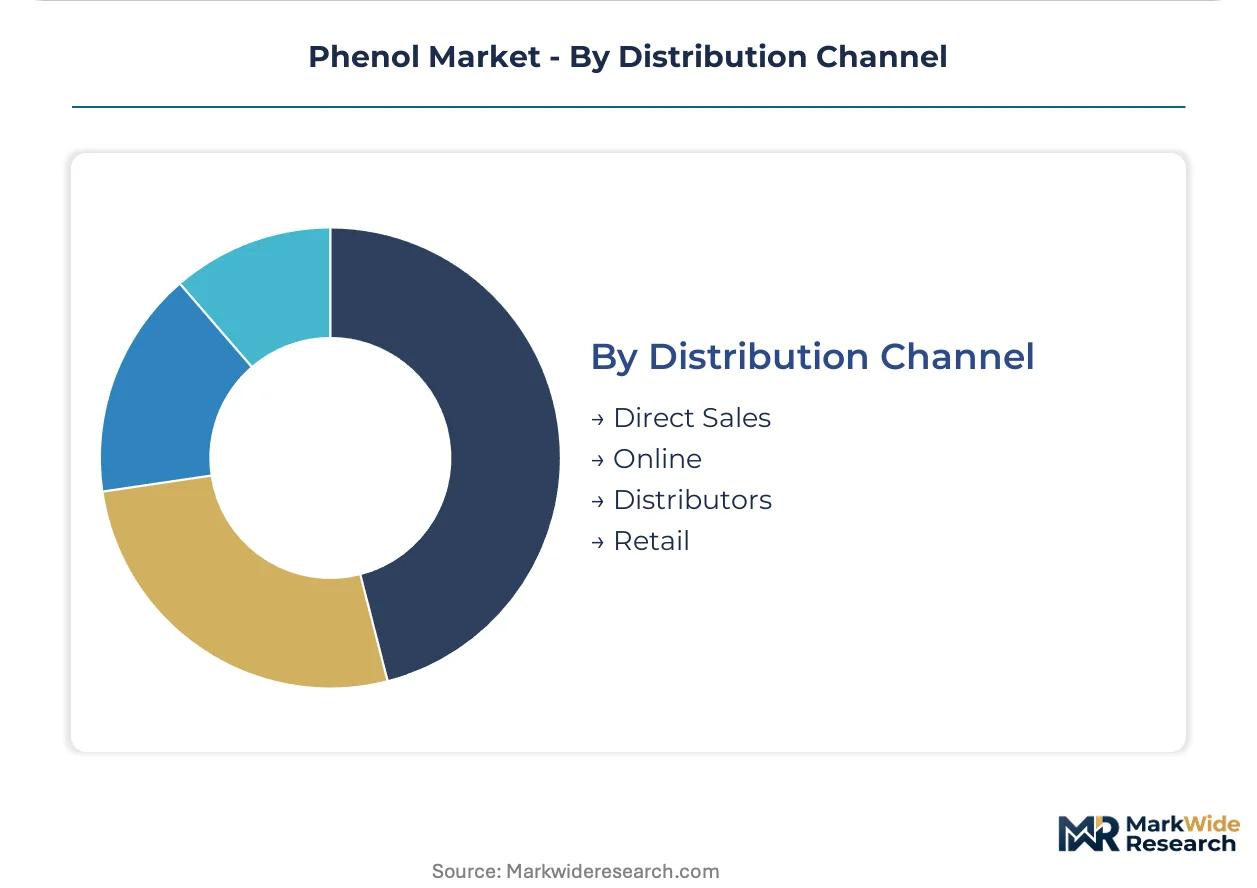
Distribution Channel:
Supply chain configuration directly shapes pricing transparency and working capital requirements across merchant and captive procurement models.
- Direct Sales:Integrated producers negotiate multi-year contracts with polycarbonate compounders and resin formulators, displacing distributor intermediaries in volume procurement across China and Mexico manufacturing corridors.
- Online:Specialty chemical marketplaces are gaining traction for laboratory-grade and small-batch pharmaceutical phenol, though bulk commodity volumes resist digital channel migration.
- Distributors:Regional chemical distributors maintain inventory positions for mid-tier resin producers and paint formulators in markets lacking integrated phenol capacity.
- Retail:Pharmacy and laboratory supply chains handle gram-scale pharmaceutical phenol for antiseptic and reagent applications, with negligible share in total volume.
Contract value concentrates in direct sales; online channels are expanding most quickly for specialty-grade spot purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam-Antwerp petrochemical corridor anchors European phenol capacity, while Shandong and Zhejiang province clusters concentrate Chinese expansion. Regulatory divergence and feedstock access are reshaping regional investment patterns.
China
Zhejiang Petroleum & Chemical and Chang Chun Group are scaling integrated cumene-phenol-bisphenol A complexes to serve domestic plastics manufacturers. MEE enforces wastewater discharge limits on phenol concentration in the Yangtze River basin. Ningbo-Zhoushan port cluster handles cumene import logistics for Zhejiang province derivative producers.
United States
OSHA PSM compliance timelines extend cumene oxidation unit expansions due to hydroperoxide handling protocols. EPA air toxics standards shape Gulf Coast plant design and worker safety protocols. Texas-Louisiana chemical corridor retains experienced cumene oxidation operators at legacy complexes.
Germany
EU F-Gas Regulation phase-downs redirect polyurethane foam chemistry toward phenolic insulation alternatives in HVAC retrofit markets. REACH authorization procedures tighten disclosure requirements across wood panel supply chains. Ludwigshafen and Marl industrial sites host resin formulators qualifying high-purity phenolic novolac specifications.
Saudi Arabia
SABIC leverages backward integration into refinery-sourced benzene to compete on feedstock cost. SFDA pharmaceutical-grade certification requirements constrain qualified supply pools for vaccine stabilizer applications. Jubail industrial city concentrates phenol-acetone complex capacity serving Middle Eastern export hubs.
India
PLI scheme allocations for specialty chemicals draw phenol derivative investments toward Gujarat and Maharashtra industrial corridors. CDSCO pharmaceutical regulator enforces impurity limits on USP-grade phenol for topical antiseptic applications. Mumbai-Pune manufacturing belt anchors mid-tier resin producer demand.
Phenol Market Key Industry Players
The competitive structure tilts toward integrated petrochemical conglomerates with captive benzene supply. Capacity concentration favors players controlling cumene-to-phenol-bisphenol A value chains. Three archetypes dominate: refinery-integrated Middle Eastern producers, Asia-Pacific scale operators with downstream plastics integration, and European specialty-grade specialists serving pharmaceutical and electronic material specifications. Competitive moves center on process intensification licensing and long-term offtake contracting with polycarbonate compounders.
Among Asia-Pacific scale operators, Zhejiang Petroleum & Chemical Co Ltd and Chang Chun Group exemplify the integrated conglomerate archetype with downstream plastics control. INEOS Phenol occupies a position within the European specialty infrastructure tier, leveraging Rotterdam-Antwerp corridor assets. Mitsubishi Chemical Group Corporation represents the high-purity grade specialist segment serving electronic materials applications.
| Leading Market Players |
|---|
| Kumho P&B Chemicals |
| Chang Chun Group |
| INEOS Phenol |
| Zhejiang Petroleum & Chemical Co Ltd |
| Moeve |
| Mitsubishi Chemical Group Corporation |
| Formosa Chemicals & Fibre Corporation |
| SABIC |
| LG Chem |
| Others |
Cost & Logistics Intelligence
Pharmaceutical-grade versus commodity-grade phenol bifurcation creates divergent margin architectures that reshape procurement patterns across the value chain. USP-grade certification ladders in Germany and Switzerland command sustained premiums through FDA and EMA GMP qualification barriers, while standard bisphenol A feedstock pricing tracks benzene-cumene cost pass-through mechanics in Rotterdam and Singapore trading hubs.
Pricing Analysis
Yield-locked pricing tied to cumene oxidation throughput governs integrated phenol-acetone complex economics, with acetone co-production volumes directly offsetting unit costs. Price differentiation separates electronic-grade novolac specifications from construction adhesive resins through purity thresholds and thermal stability certifications. Cost compression in commodity bisphenol A feedstock is intensifying because Middle Eastern export hub oversupply forces operating rate discipline regardless of phenol demand. Merchant buyers in India's Maharashtra corridor exhibit highest price sensitivity due to working capital constraints, while polycarbonate compounders in China's Yangtze River Delta accept longer contract tenures for supply security.
Supply Chain Analysis
Refurbished cumene oxidation catalyst recovery and spent acid regeneration flows are emerging as circular economy nodes at Rotterdam-Antwerp corridor facilities. Supply concentrates in China, Saudi Arabia, and Belgium, with Zhejiang province complexes and Jubail industrial city anchoring Asian and Middle Eastern volume. Raw material dependencies rest on refinery-sourced benzene, propylene for cumene synthesis, and sulfuric acid for hydroperoxide cleavage. Single-source vulnerability from concentrated cumene supply tightness poses structural risk to European resin formulators lacking backward integration. Distribution runs through direct long-term offtake contracts with polycarbonate compounders, displacing traditional distributor intermediaries in high-volume procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phenol sector sits at a process technology inflection as membrane-assisted cumene oxidation displaces conventional air-sparged reactor configurations. Lignin-to-cumene bio-aromatic pilot scale-up represents the parallel feedstock transition pathway reshaping competitive economics.
For Market Incumbents: Deploy membrane-assisted oxidation licensing to European and Chinese joint-venture partners, capturing technology royalties while limiting capital exposure. Secure cumene supply through refinery partnership structures in Rotterdam and Antwerp, insulating against benzene volatility that compresses merchant margins. Counter bio-phenol entrants by accelerating pharmaceutical-grade qualification investments at Ludwigshafen and Marl sites, raising certification barriers for renewable alternatives. For New Entrants and Emerging Players: India's PLI scheme for specialty chemicals in Gujarat and Maharashtra opens a window for phenol derivative investments serving domestic resin formulators underserved by integrated complexes. Target pharmaceutical-grade phenol production leveraging CDSCO regulatory alignment with USP standards, where qualified supplier scarcity limits incumbent capacity expansion. Pursue toll manufacturing arrangements with existing cumene oxidation operators to bypass Seveso III compliance timelines and skilled operator recruitment constraints. For Investors and Strategic Acquirers: Re-rating potential sits with European specialty-grade specialists given REACH authorization tightening on formaldehyde-releasing substances, which redirects construction adhesive demand toward phenol-resorcinol alternatives. Long-term viability favors players controlling cumene-to-phenol-bisphenol A value chains with captive benzene supply and downstream polycarbonate integration. Monitor bio-cumene pilot commercialization timelines at lignin conversion facilities as the inflection signal for renewable feedstock cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refinery-Sourced Benzene | SABIC's Jubail complex demonstrates feedstock cost advantages over merchant cumene buyers in European markets. |
| Membrane-Assisted Cumene Oxidation Scale-Up | Energy intensity reductions at select European units compress electronic-grade phenol cost premiums for automotive resin specifications. |
| Long-Term Supply Agreement with Polycarbonate Compounders | Three-to-five-year offtake structures in China's Yangtze River Delta displace distributor intermediaries and lock volume commitments. |
| Pharmaceutical-Grade Certification Investment | FDA and EMA GMP qualification at German and Swiss facilities constrains qualified supply pools and sustains margin premiums. |
| Joint Venture for Bio-Cumene Pilot Commercialization | Lignin-to-cumene technology partnerships offer pathway to renewable phenol for cosmetics and vaccine stabilizer applications. |
Research Approach
Multi-period observation of cumene oxidation operating rates, acetone co-product spreads, and pharmaceutical-grade phenol import flows anchored the trend analysis, supplemented by interviews with plant managers at integrated phenol-acetone complexes, procurement leads at polycarbonate compounders, distribution channel partners in European resin markets, and technical R&D directors at phenolic novolac formulators. Secondary validation drew from customs and trade data, Cefic and ACC chemical industry reports, SEC 10-K filings from listed petrochemical conglomerates, and MEE wastewater discharge enforcement records. Bottom-up capacity modeling and top-down derivative demand triangulation cross-checked volume estimates across the analysis window.
Input-output matrices mapping cumene supply through phenol production to bisphenol A and phenolic resin offtake structured the analytical framework across the modeling period. Segmentation dimensions included grade tier (pharmaceutical, electronic, industrial), end-use industry (automotive, construction, healthcare, electronics), and regional production hub (China, Middle East, Europe, North America). CAGRs were derived from regression-weighted capacity expansion schedules and substitution elasticity estimates for phenolic insulation versus polyurethane foams. Forecast inputs incorporated EU F-Gas Regulation phase-down compliance timelines and China's dual carbon goals emissions intensity targets.
Caveats apply where benzene cost volatility, acetone market oversupply, or REACH substance restriction scope expansions could materially shift the outlook for integrated complex economics. Practitioners should monitor bio-phenol pilot scale-up milestones, cumene supply tightness indicators, and carbon border adjustment implementation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
2,5-Dimethyl-2,4-Hexadiene Market
Organic Chemicals
Acetic Acid Market
Organic Chemicals
Global Glycolic Acid Market
Organic Chemicals
North America Organic Acid Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
Nonylphenol Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
US Humate Market
Organic Chemicals
Organic Matting Agent Market
Organic Chemicals
Chloroacetyl Chloride Market
Organic Chemicals
Trimethylcyclohexanone Market
Organic Chemicals
Phenolic Board Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Organic Peroxide Market