
 Lignin-Based Graphene Market | 2026-2036
Lignin-Based Graphene Market Size, Share, and Industry Trends Forecast 2026-2036
Lignin-Based Graphene Market Analytics
The capital-intensity divergence between pilot-scale producers and commercial-ready operators is unwinding as lignin-based graphene crosses the threshold from laboratory curiosity to industrial material. Domtar leverages its integrated pulp-to-lignin infrastructure to secure feedstock cost advantages that laboratory competitors cannot replicate. Bright Day Graphene anchors its position through proprietary extraction protocols that preserve graphene sheet integrity during lignin pyrolysis. NanoXplore Inc competes by extending its carbon nanomaterial expertise into bio-derived architectures, positioning against petroleum-based supply chains.
Lignin-based graphene denotes a class of carbon nanomaterials synthesized from lignin biomass through thermal exfoliation, chemical reduction, or catalytic graphitization, typically yielding few-layer graphene with oxygen content between 5% and 20% depending on process severity. Its primary commercial purpose centers on displacing synthetic graphite and chemical vapor deposition graphene in applications where sustainability credentials and feedstock circularity command procurement premiums. Reduced graphene oxide from lignin sources leads product-type margins due to established dispersion protocols in conductive ink formulations, while graphene nanoplatelets represent the fastest-growing structural category as automotive composite specifications tighten weight-to-conductivity ratios. Energy storage applications concentrate demand volume, though coatings applications in aerospace retain the deepest margin pools through qualification barriers that limit supplier switching.
EPA bio-preferred procurement guidelines and REACH substance registration requirements shape product standards by mandating renewable carbon content thresholds and lifecycle disclosure, respectively. FDA scrutiny of graphene in healthcare applications adds a compliance layer that favors producers with established quality management systems over emerging entrants. Stakeholders must monitor how EU Green Deal carbon border adjustments recalibrate the cost structure of lignin-derived versus petroleum-derived graphene as the mechanism expands beyond pilot phases.
Market Dynamics
Pulp and paper industry consolidation is compressing lignin feedstock availability, forcing graphene producers to secure long-term residue supply contracts before competitors lock in regional sourcing rights.
Growth Catalysts
- EPA Bio-Preferred Program:Federal procurement mandates favor renewable carbon materials in US government contracts, creating preferential pathways for lignin-derived graphene in public sector energy storage applications.
- Battery anode specifications:Automotive OEMs are tightening sustainability criteria for lithium-ion components, pulling bio-based carbon feedstocks into qualified supplier lists ahead of petroleum alternatives.
- German industrial cluster density:Concentrated pulp processing infrastructure in Baden-Württemberg and Bavaria enables integrated lignin-to-graphene production with logistics costs below dispersed competitors.
Market Restraints
- Pyrolysis energy intensity:Thermal exfoliation of lignin requires sustained temperatures exceeding 1000°C, tying production economics to regional electricity and natural gas price volatility.
- Graphite price suppression:Synthetic graphite from Chinese electrode manufacturers trades at cost structures that bio-based alternatives cannot match without carbon credit monetization.
- REACH registration timelines:ECHA substance dossier requirements for novel carbon allotropes extend 18-36 months, freezing commercial rollout until full hazard data packages are accepted.
Strategic Opportunities
- EU Green Deal carbon border adjustments:Import tariffs on embodied carbon will reprice Chinese synthetic graphite upward, narrowing the cost gap for European-produced lignin graphene.
- Aerospace EMI shielding:Lightweight conductive coatings for satellite and aircraft structures remain underpenetrated by bio-based nanomaterials despite qualifying performance benchmarks.
- Continuous flow pyrolysis:Converging reactor engineering from petrochemical catalysis with lignin feedstock handling is enabling throughput scales impossible in batch furnace operations.
Industry Challenges
- Interlayer spacing consistency:Lignin-derived graphene exhibits variable d-spacing that complicates electrode slurry formulation, requiring batch-specific process adjustments that erode manufacturing efficiency.
- ISO/TC 229 nanomaterial standards:Pending terminology and measurement protocols for bio-based graphene create certification uncertainty that delays customer qualification cycles.
- Cross-functional talent scarcity:Simultaneous competence in biomass chemistry, carbon nanomaterial characterization, and battery electrochemistry concentrates in a narrow specialist pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lignin-Based Graphene Market |
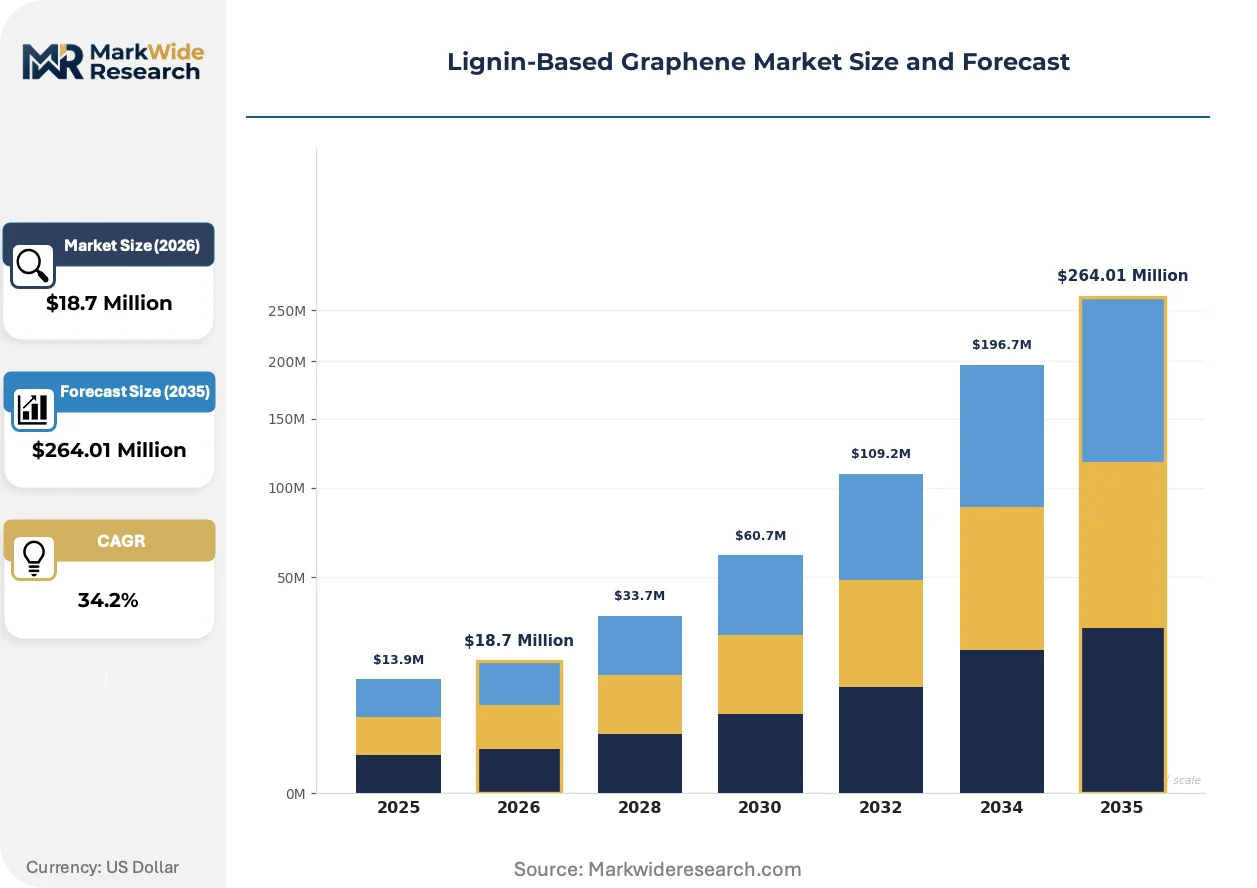
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $264.01 Million |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphene Oxide, Reduced Graphene Oxide, Graphene Nanoplatelets, Graphene Carbon Nanotubes Application: Energy Storage, Coatings, Composites, Conductive Inks End User: Electronics, Aerospace, Automotive, Healthcare Distribution Channel: Online Retail, Direct Sales, Distributors, Resellers |
| Companies Covered | Domtar, Bright Day Graphene, Unilong Industry, Shandong Longlive Bio-Technology, Graphenea, Lignin Solutions, BASF, Grafoid Inc, NanoXplore Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lignin-Based Graphene Market Evolving Landscape
Process intensification and regulatory carbon accounting are rewriting competitive boundaries between laboratory-scale innovators and industrial chemical producers with captive feedstock positions.
Catalytic graphitization using transition metal promoters is fragmenting the traditional pyrolysis-dominated process landscape. Battery manufacturers in South Korea and Japan are piloting lignin-derived few-layer graphene for silicon-composite anodes at 50-kilogram monthly volumes. This process diversity is fragmenting equipment supplier relationships as specialized reactor vendors displace generalist furnace manufacturers.
REACH substance registration deadlines for nanomaterials are compressing development timelines for European entrants. ECHA's 2024 guidance on graphene oxide hazard classification triggered reformulation efforts across conductive ink suppliers. German and Finnish producers with early dossier submissions are securing first-mover regulatory clearance that locks out later applicants from qualified supplier lists.
Automotive tier-one suppliers are unbundling material certification from volume procurement commitments. Cell producers now demand stage-gate qualification data before contract execution, replacing the historical model of parallel development partnerships. This behavioral shift is most pronounced in Germany and the United States, where OEM sustainability scorecards weight renewable carbon content in supplier selection algorithms.
Lignin-Based Graphene Market Segmentation
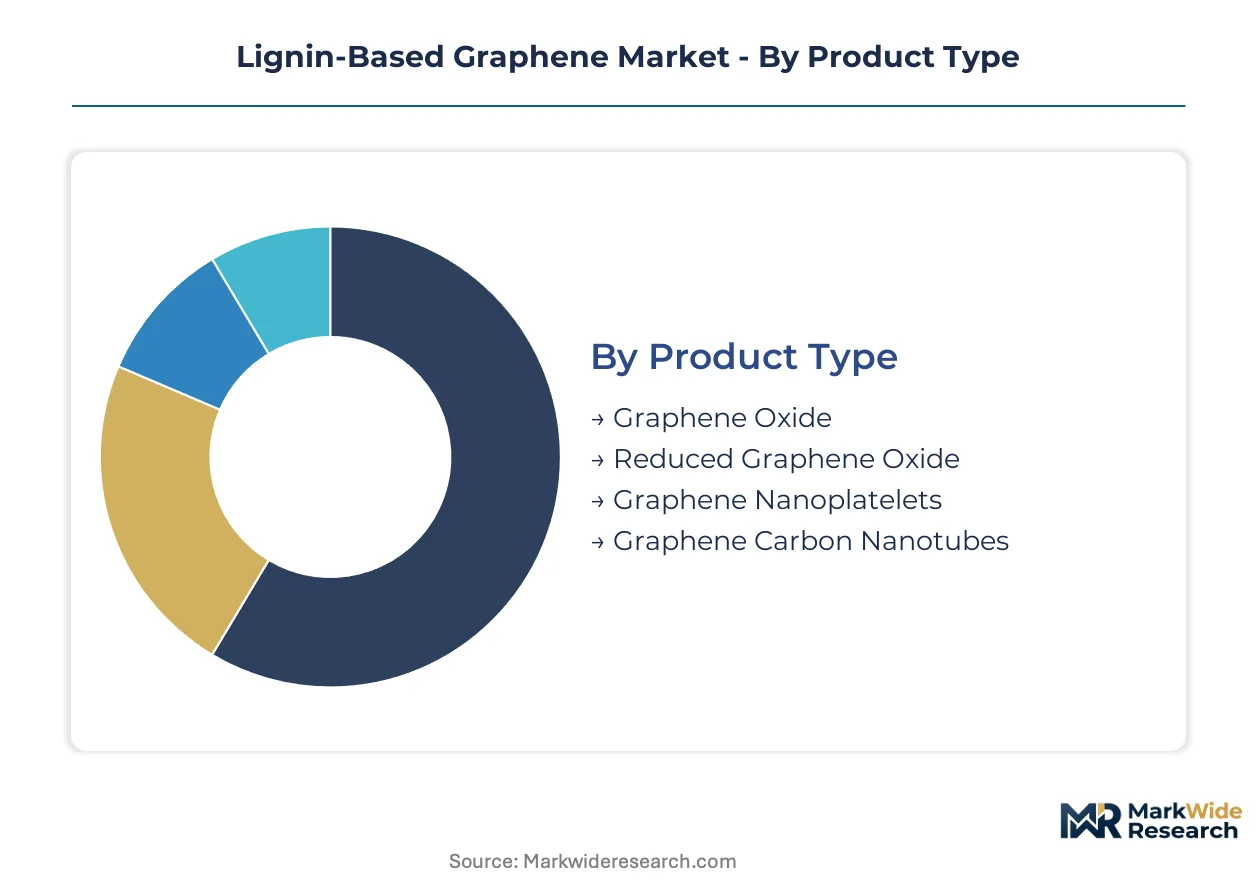
Segmentation in lignin-based graphene reveals how process chemistry, application performance thresholds, and procurement channel economics partition margin capture. Producers must align product specifications with end-use qualification requirements to avoid commoditization in undifferentiated carbon additive markets.
Product Type:
Margin pools concentrate in reduced graphene oxide and graphene nanoplatelets where dispersion protocols and structural consistency command formulation premiums.
- Reduced Graphene Oxide:Oxygen content typically falls between 5% and 15% after hydrazine or thermal reduction, delivering conductivity sufficient for battery anode slurries. Energy storage manufacturers in Germany and South Korea specify this grade for silicon-composite electrodes where surface chemistry compatibility determines cycle life.
- Graphene Nanoplatelets:Few-layer structures with lateral dimensions exceeding 5 micrometers provide mechanical reinforcement in thermoplastic composites. Automotive lightweighting programs in Stuttgart and Detroit are qualifying these materials for EMI shielding housings where weight-to-conductivity ratios exceed metal alternatives.
- Graphene Oxide:Higher oxygen loadings (20-40%) enable aqueous dispersion for coating applications without surfactant addition.
- Graphene Carbon Nanotubes:Hybrid architectures combining sheet and tubular morphologies target niche thermal interface materials in electronics packaging.
The dominant share belongs to Reduced Graphene Oxide, while Graphene Nanoplatelets is closing the gap fastest.
Application:
Volume concentration and pricing power diverge sharply between qualified energy storage supply chains and speculative coatings development programs.
- Energy Storage:Battery anode and cathode formulations consume the largest production volumes, with qualification timelines spanning 18-24 months for automotive cell producers. Cell manufacturers in Japan require batch-to-batch consistency metrics that exclude pilot-scale suppliers from procurement lists.
- Coatings:Aerospace EMI shielding and corrosion protection applications retain the deepest margins through specification barriers that limit qualified supplier counts. FAA certification requirements for conductive primers on aluminum airframes create sticky supplier relationships once initial qualification completes.
- Composites:Polymer matrix integration for structural components targets automotive under-hood applications where thermal conductivity replaces metal heat sinks.
- Conductive Inks:Screen-printed and inkjet formulations for flexible electronics represent a developing segment with unproven scale economics.
Energy Storage commands the largest volume position, though Coatings generates superior unit economics through qualification moats.
End User:
Customer sophistication and technical specification stringency sort producers into tiered supply relationships with diverging contract terms.
- Electronics:Semiconductor packaging and thermal management applications demand sub-50-nanometer thickness control that only continuous-flow pyrolysis systems achieve. South Korean electronics conglomerates are integrating lignin-derived graphene into vapor chamber designs for smartphone thermal dissipation.
- Aerospace:Satellite and aircraft OEMs require traceable supply chains with REACH-compliant hazard documentation, favoring European producers with established ECHA dossiers. Airbus qualification protocols for lightning strike protection on composite wings specify bio-derived carbon content thresholds.
- Automotive:Tier-one battery suppliers weight sustainability scorecards heavily, pulling renewable carbon feedstocks into qualified supplier lists ahead of regulatory mandates.
- Healthcare:FDA scrutiny of graphene biocompatibility has stalled commercial adoption despite promising drug delivery research programs.
Electronics leads procurement volume, with Aerospace expanding most quickly through sustainability-driven specification revisions.
Distribution Channel:
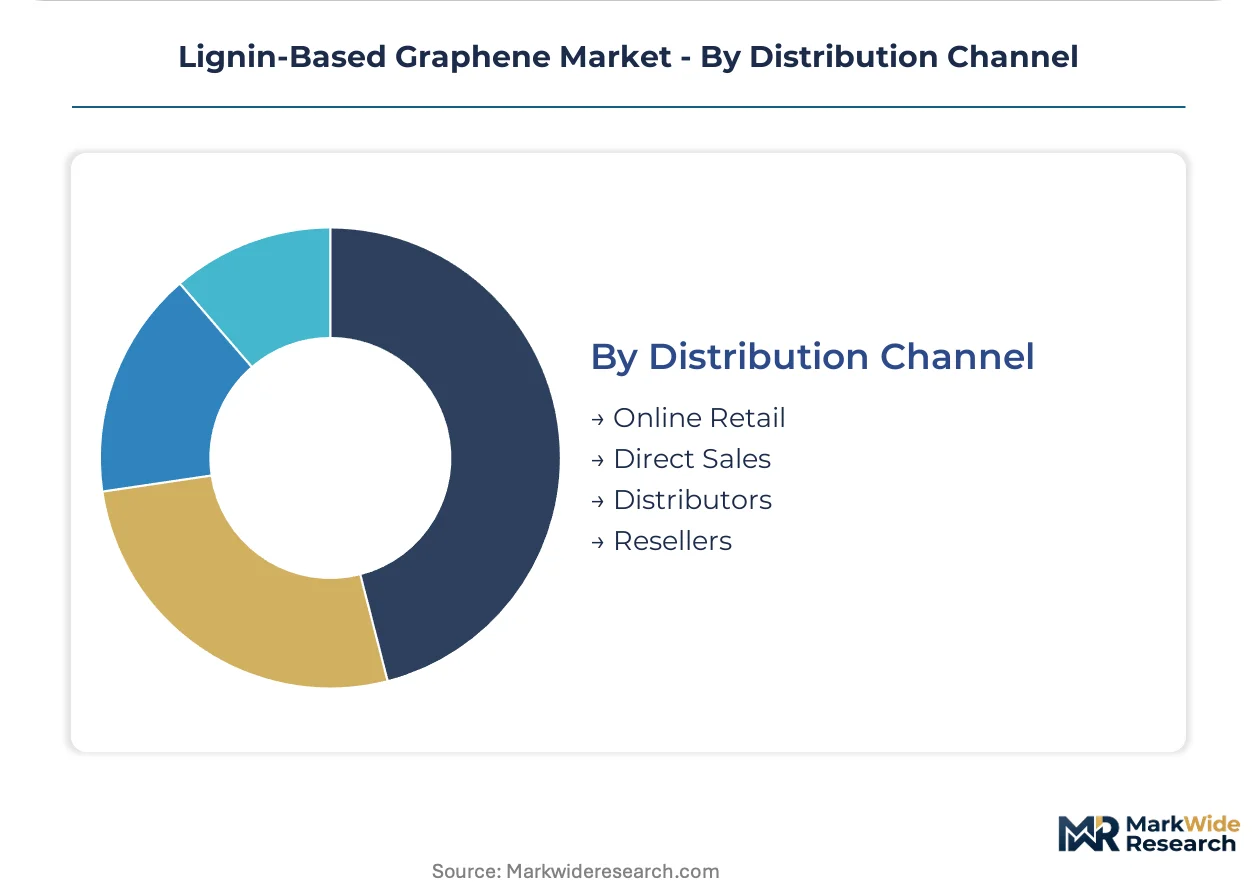
Channel selection reflects customer scale and technical support requirements, with direct relationships dominating qualified industrial supply chains.
- Direct Sales:Large-volume battery and composite manufacturers negotiate multi-year supply agreements with technical service attachments. BASF and Dow have established direct procurement channels for lignin graphene integration into their formulated product lines.
- Distributors:Regional chemical distributors serve mid-tier coatings and ink formulators with smaller batch requirements and less specialized technical support needs.
- Online Retail:Research-grade quantities for academic and pilot-scale industrial customers transact through specialized nanomaterial marketplaces with limited quality assurance.
- Resellers:Value-added resellers provide formulation services for customers lacking in-house dispersion capabilities, capturing margin through technical service bundling.
Direct Sales maintains the dominant channel position, while Distributors is gaining share fastest among emerging regional formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, accepting premiums for qualified bio-derived carbon in battery supply chains. Chinese purchasers remain highly price-sensitive, benchmarking lignin graphene against suppressed synthetic graphite costs. The United States occupies a middle position, where EPA procurement preferences partially offset cost disadvantages.
Germany
Automotive OEMs in Stuttgart and Munich specify renewable carbon content in battery anode contracts. REACH registration requirements through ECHA mandate full hazard data packages for nanomaterial commercialization. The Baden-Württemberg pulp processing cluster enables integrated lignin-to-graphene production with logistics advantages over dispersed competitors.
United States
Battery manufacturers in Michigan and California face sustainability scorecard pressure from Detroit and Silicon Valley OEMs. EPA Bio-Preferred procurement guidelines create preferential pathways for lignin-derived materials in federal energy storage contracts. The Pacific Northwest pulp and paper residue streams supply scalable feedstock to emerging graphene producers.
China
Domestic battery cell producers in Fujian and Jiangsu prioritize cost minimization over bio-derived feedstock premiums. MIIT industrial policy supports carbon nanomaterial development though implementation remains fragmented across provincial jurisdictions. The Yangtze River Delta concentrates electrode manufacturing demand that pulls in imported lignin graphene for qualification trials.
Japan
Electronics conglomerates in Tokyo and Osaka integrate lignin-derived graphene into thermal management components for smartphones and servers. METI funding programs support pilot-scale production of bio-based carbon nanomaterials for automotive applications. The Kansai industrial corridor hosts specialized reactor engineering firms advancing continuous-flow pyrolysis technologies.
South Korea
Cell producers in Gyeonggi Province pilot lignin-derived few-layer graphene for silicon-composite anodes at commercial evaluation volumes. MFDS regulatory frameworks for nanomaterial safety assessment create compliance timelines that favor early dossier submissions. The Seoul Capital Area concentrates battery R&D facilities demanding batch-to-batch consistency metrics from qualified suppliers.
Lignin-Based Graphene Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Pulp-integrated chemical producers command feedstock cost advantages that laboratory-scale innovators cannot replicate. Three archetypes dominate: integrated forest products companies with captive lignin streams, specialized nanomaterial ventures with proprietary extraction protocols, and diversified chemical conglomerates extending carbon expertise into bio-derived architectures. Capacity expansion through continuous-flow reactor deployment and strategic partnerships for REACH registration acceleration represent the dominant competitive moves.
Among North American integrated producers, Domtar exemplifies the pulp-to-lignin infrastructure archetype with feedstock security advantages. Bright Day Graphene occupies a position within the specialized extraction protocol tier. NanoXplore Inc represents diversified carbon nanomaterial expertise extending into bio-derived supply chains. European specialists including Graphenea and Lignin Solutions sit within the regulatory-first mover tier, leveraging early ECHA dossier submissions. Chinese producers such as Unilong Industry and Shandong Longlive Bio-Technology anchor the scale-driven manufacturing segment.
| Leading Market Players |
|---|
| Domtar |
| Bright Day Graphene |
| Unilong Industry |
| Shandong Longlive Bio-Technology |
| Graphenea |
| Lignin Solutions |
| BASF |
| Grafoid Inc |
| NanoXplore Inc |
| Others |
Value Network & Pricing Analysis
Continuous-flow reactor deployment at commercial scale in Germany and Japan establishes cost floors that batch-furnace operators cannot undercut without sacrificing sheet integrity. This scale differential concentrates pricing power among producers with captive lignin streams from integrated pulp processing, while forcing laboratory-scale competitors toward premium niche applications or exit.
Pricing Analysis
After-sales technical service contracts for electrode slurry formulation support lifetime value capture beyond base material sales. Three-tier pricing structure across battery-grade, composite-grade, and research-grade specifications reflects certification burden and batch consistency metrics. Pricing pressure stems from Chinese synthetic graphite cost structures that bio-based alternatives match only through carbon credit monetization. Automotive cell producers in Japan demonstrate the lowest price elasticity, while Chinese purchasers benchmark strictly against petroleum-derived alternatives.
Supply Chain Analysis
Strait of Malacca transit vulnerability for hardwood lignin feedstocks from Southeast Asia underwrites inventory carrying costs at European processors. Supply concentrates in Germany, the United States, and Finland where pulp and paper residue streams feed integrated production. Raw material dependencies span Kraft lignin, organosolv lignin, and pyrolysis catalyst metals. Single-source vulnerability in hardwood lignin from Brazilian eucalyptus plantations creates concentration risk. Distribution runs through direct sales relationships with qualified battery and composite manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Simultaneous competence in biomass chemistry, carbon nanomaterial characterization, and battery electrochemistry concentrates in a narrow specialist pool that constrains expansion velocity for all archetypes. This capability scarcity rewards first movers who lock in cross-functional talent before competitor hiring drives compensation inflation.
For Market Incumbents: Shield margin position by securing long-term residue supply contracts with Baden-Württemberg and Pacific Northwest pulp processors before consolidation eliminates alternative sourcing. Accelerate REACH dossier submissions to exploit ECHA registration timelines that freeze out later applicants from qualified supplier lists at German automotive OEMs. For New Entrants and Emerging Players: Lead with aerospace EMI shielding applications where FAA certification requirements create sticky supplier relationships and limit qualified competitor counts. Target South Korean cell producers piloting silicon-composite anodes, as their batch-to-batch consistency demands exclude established petroleum-based suppliers from procurement lists. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated forest products companies with captive lignin infrastructure over pure-play nanomaterial ventures lacking feedstock security. Long-term viability hinges on carbon border adjustment implementation breadth across the projection horizon. The acquisition target archetype combines continuous-flow reactor engineering with early ECHA dossier clearance. The signal to watch is EU Green Deal carbon border adjustment expansion beyond pilot phases, which would reprice Chinese synthetic graphite upward and narrow the cost gap for European-produced lignin graphene.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Residue Streams | Domtar's captive lignin infrastructure secures feedstock cost advantages laboratory competitors cannot replicate. |
| Continuous-Flow Pyrolysis Scale-Up | Converging reactor engineering from petrochemical catalysis enables throughput scales impossible in batch furnace operations. |
| REACH Registration Acceleration | German and Finnish producers with early ECHA dossier submissions lock out later applicants from qualified supplier lists. |
| Silicon-Composite Anode Qualification | South Korean and Japanese battery manufacturers pilot lignin-derived few-layer graphene at commercial evaluation volumes. |
| Aerospace EMI Shielding Certification | Airbus qualification protocols for lightning strike protection specify bio-derived carbon content thresholds favoring early movers. |
Research Methodology
The analysis maps reduced graphene oxide, graphene nanoplatelets, graphene oxide, and hybrid carbon nanotube architectures, each validated through interviews with battery cell procurement directors, pulp mill operations managers, carbon nanomaterial R&D leads, and aerospace qualification engineers. Secondary sources include ECHA substance dossiers, EPA bio-preferred procurement databases, SEC filings from integrated forest products companies, and customs trade data for lignin derivative flows. Bottom-up capacity estimates from identified producers triangulate against top-down demand projections from end-use applications.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, application, end user, and distribution channel segmentation alongside regional production cluster economics. CAGRs derive from installed capacity buildout timelines, qualification cycle durations, and carbon credit monetization trajectories. Forecast inputs include electricity and natural gas price volatility for pyrolysis operations, pulp and paper industry consolidation rates, and EU carbon border adjustment implementation scope.
The analysis sits within stated boundaries; outcomes outside sustained EPA bio-preferred program support and REACH registration pathway stability would require recalibration. Forecasts reflect assumptions regarding pyrolysis energy intensity trends, graphite price suppression persistence, and cross-functional talent availability. Practitioners should keep alternative scenarios live as EU Green Deal carbon border adjustment mechanisms and ISO nanomaterial standard finalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Isostatic Graphite Market
Composite Materials
Global Honeycomb Core Materials Market
Composite Materials
Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market
Composite Materials
Low Temperature Sealing Glass Composite Powder Market
Composite Materials
Asia Pacific Bio Composites Market
Composite Materials
Composite Cans Market
Composite Materials
Europe Marine Composites Market
Composite Materials
Composite Metal Finishing Market
Composite Materials
Automotive Carbon Fiber Materials Market
Composite Materials
Synthetic Rope Market
Composite Materials
Pcb Laminate Materials Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Composite Process Material Kits Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
Thermoplastic Prepreg Market
Composite Materials
High Pressure Laminate (HPL) Market