
 Photoinitiators Market | 2026-2036
Photoinitiators Market Size, Share, and Industry Trends Forecast 2026-2036
Photoinitiators Market Outlook
Automotive coatings demand is recalibrating as electric vehicle manufacturers prioritize low-VOC curing processes for battery housings and interior trim. Evonik Industries AG leverages its specialty chemicals portfolio to serve high-performance UV formulations across European automotive tiers. Tianjin Jiuri New Materials Co. Ltd anchors regional supply chains through backward integration into key raw material intermediates. IGM Resins specializes in customized photoinitiator blends for industrial wood and furniture coatings.
Photoinitiators are light-sensitive compounds that absorb ultraviolet or visible radiation to generate reactive species—free radicals or cations—initiating polymerization in monomer and oligomer systems, typically operating at wavelengths between 200 and 450 nanometers depending on the chromophore structure. Their primary industrial purpose is enabling solvent-free, rapid-cure manufacturing across coatings, adhesives, and printing applications. Free radical photoinitiators occupy the dominant volume position due to decades of formulation familiarity and broad resin compatibility, while cationic systems command premium positioning in markets demanding superior adhesion to metals and low shrinkage. Dual cure formulations represent the fastest-growing category as hybrid epoxy-acrylate systems penetrate electronics encapsulation and medical device assembly where single-cure chemistry falls short.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based coating operations, directly expanding addressable demand for UV-cure alternatives in U.S. manufacturing facilities. REACH registration requirements and the EU Green Deal's chemical sustainability targets are forcing reformulation cycles across European coatings value chains, favoring photoinitiator suppliers with comprehensive toxicological dossiers. China's GB standards on industrial VOC emissions, enforced by MEE provincial branches, are accelerating domestic substitution away from imported solvent-cure systems. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation threatens to segment product portfolios and complicate scale economics for multinational suppliers.
Market Dynamics
Dual-cure photoinitiator systems are compressing formulation cycles across electronics encapsulation, forcing suppliers to merge radical and cationic chemistries within single product portfolios. This technological convergence is redrawing competitive boundaries between specialty chemical houses and resin formulators.
Growth Catalysts
- EPA NESHAP enforcement:U.S. manufacturing facilities face escalating penalties for solvent-based coating emissions, accelerating UV-cure line conversions in metal finishing and wood furniture operations.
- Electric vehicle battery housings:Automotive OEMs specify low-VOC curing for thermal management coatings on lithium-ion enclosures, creating dedicated demand for high-performance radical photoinitiators.
- China's MEE provincial enforcement:GB standards on industrial VOC emissions are eliminating imported solvent-cure systems from packaging and electronics manufacturing clusters in Jiangsu and Guangdong provinces.
Market Restraints
- Benzophenone derivative supply concentration:Chinese manufacturers control over 70% of key intermediate production, exposing European and North American formulators to freight cost volatility and tariff uncertainty.
- Amine synergist price instability:Photoinitiator efficiency depends on tertiary amine co-initiators whose pricing tracks petrochemical feedstock fluctuations, compressing margin predictability for coating producers.
- Cationic system resin incompatibility:Epoxy-based formulations require moisture-free handling protocols that legacy manufacturing infrastructure cannot accommodate without capital-intensive environmental controls.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic PCB and semiconductor packaging investment is attracting photoinitiator suppliers to establish localized blending operations ahead of import substitution mandates.
- Waterborne UV hybrid systems:Formulations combining aqueous delivery with photoinitiator activation are penetrating textile coating applications previously blocked by flammability constraints on solvent-based alternatives.
- EU Green Deal chemical sustainability targets:REACH registration holders with comprehensive toxicological dossiers are capturing reformulation contracts from competitors facing authorization sunset dates.
Industry Challenges
- Photochemistry formulation expertise scarcity:UV-cure system design requires cross-disciplinary knowledge spanning polymer science, radiometry, and application engineering that university programs are not producing at sufficient scale.
- Dual-cure process validation timelines:Medical device manufacturers face 18-24 month qualification cycles for hybrid epoxy-acrylate encapsulants, delaying revenue recognition despite technical validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photoinitiators Market |
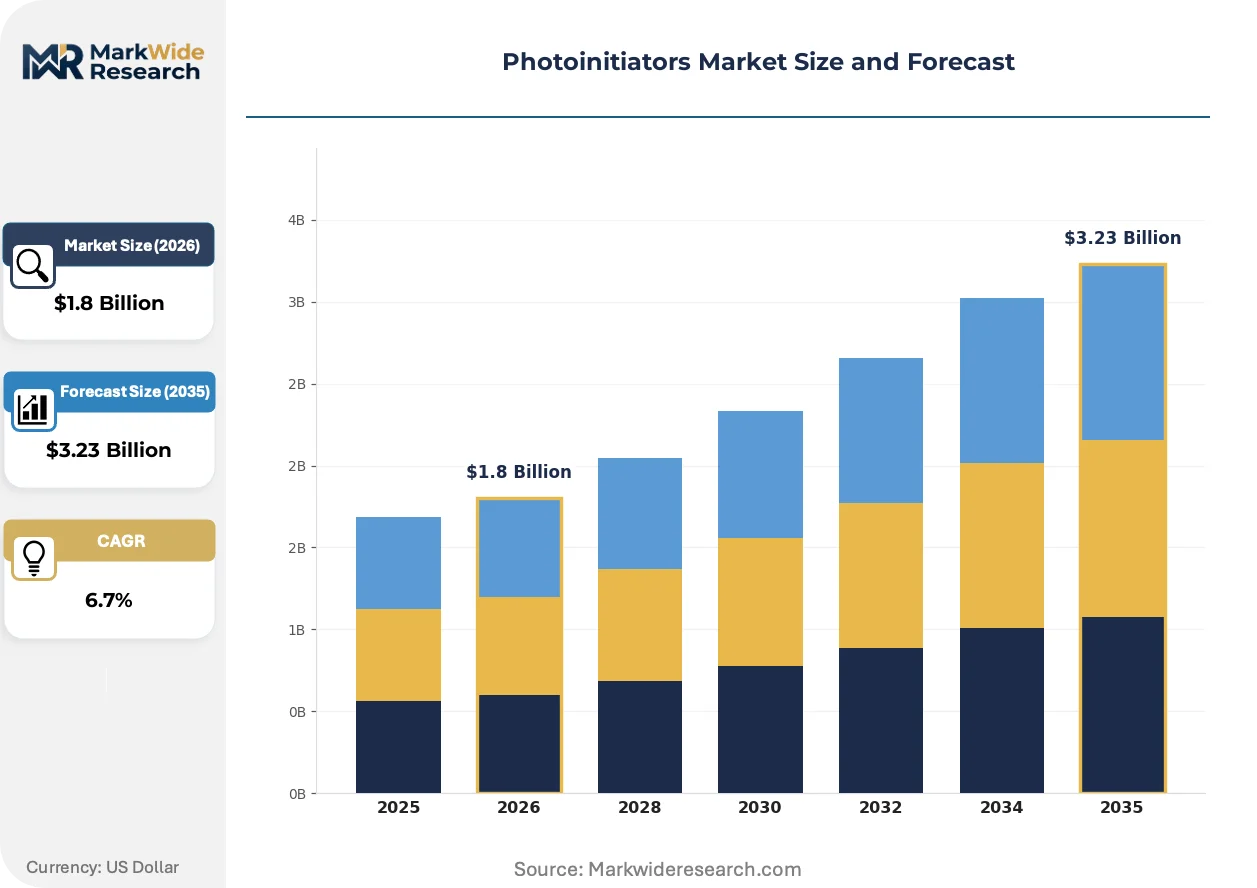
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cationic, Free Radical, Dual Cure, Photobase Application: Coatings, Adhesives, Inks, Composites End User: Manufacturing, Automotive, Construction, Electronics Form: Solid, Liquid, Powder, Gel |
| Companies Covered | Evonik Industries AG, Tianjin Jiuri New Materials Co. Ltd, IGM Resins, Changzhou Tronly New Electronic Materials Co. Ltd, Zhejiang Yangfan Material Co. Ltd, ADEKA Corporation, Rahn AG, BASF SE, Lambson Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoinitiators Market Strategic Shifts
Photoinitiator chemistry is fragmenting into application-specific architectures as end-users abandon universal formulations. Suppliers are engineering chromophore structures for narrow wavelength bands rather than broad-spectrum compatibility.
Type II photoinitiator systems incorporating thioxanthone derivatives and amine synergists are unifying cost efficiency with through-cure performance in pigmented coatings. Automotive refinishing shops in Germany and the United States are adopting these systems to replace mercury-arc dependent formulations. This unification is collapsing the historical trade-off between surface cure speed and shadow-area through-polymerization that constrained UV adoption in complex geometries.
REACH authorization requirements for existing photoinitiator substances are forcing portfolio rationalization across European suppliers. ECHA's evaluation of reproductive toxicity endpoints for benzoin ether derivatives is accelerating substitution investments. Formulators serving food-contact packaging applications are migrating to Norrish Type I cleavage systems with cleaner toxicological profiles to preempt regulatory exclusion.
Specification-driven procurement is consolidating buyer power among multinational coating houses with centralized technical approval authority. Regional distributors and independent formulators are losing access to premium photoinitiator grades as manufacturers prioritize direct relationships with volume accounts. This concentration is most visible in China's Yangtze River Delta, where electronics contract manufacturers have established approved vendor lists with single-source photoinitiator designations.
Photoinitiators Market Segmentation
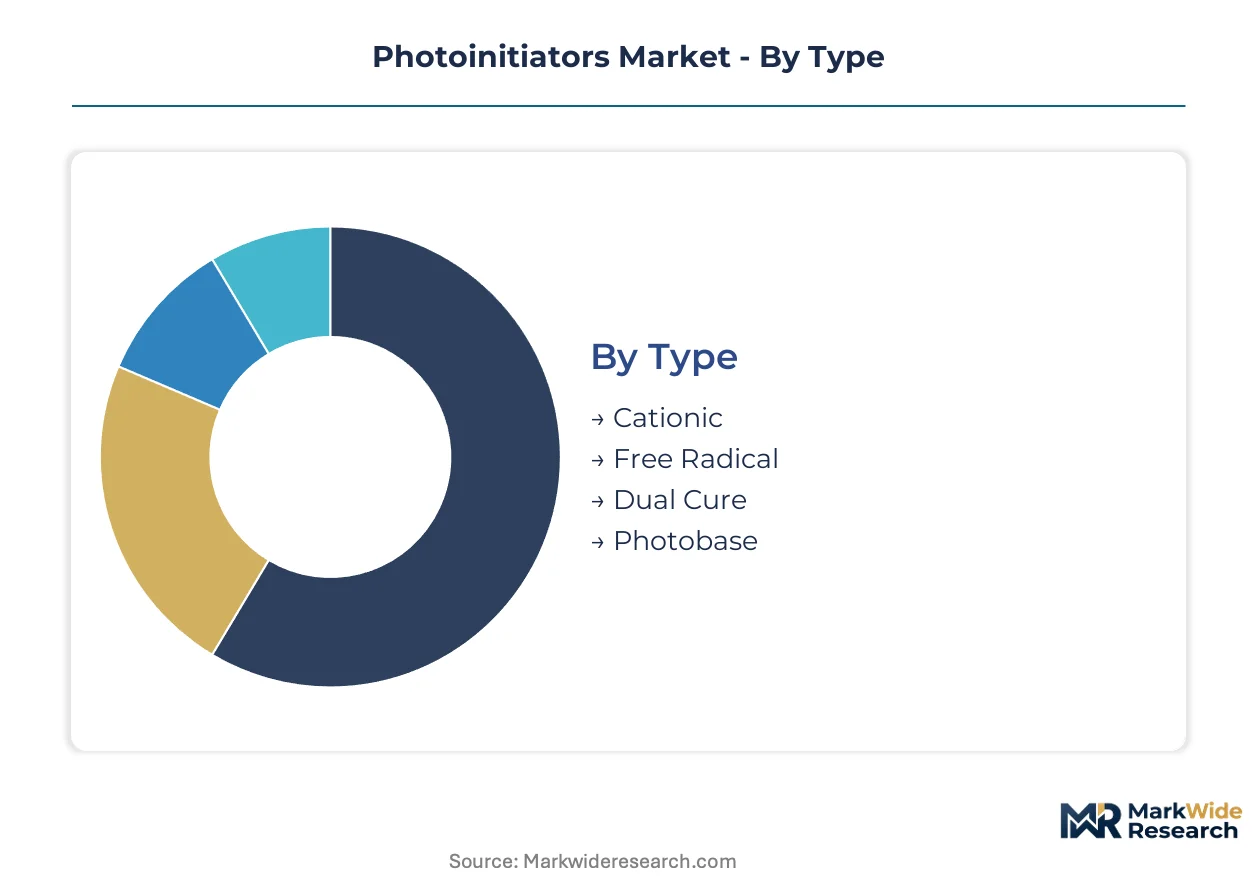
Photoinitiator selection hinges on matching chromophore absorption spectra to lamp emission profiles and substrate cure requirements. Formulators segment procurement by chemistry type, application viscosity constraints, and end-use regulatory exposure.
Type:
Photochemistry architecture dictates resin compatibility, cure depth, and oxygen inhibition sensitivity.
- Free Radical:Acylphosphine oxide and alpha-hydroxyketone structures dominate acrylate formulations across wood coatings and graphic arts. These systems absorb at 250-420 nanometers and tolerate ambient oxygen levels that would quench cationic initiation. Demand concentrates in Chinese packaging converters serving export markets where through-cure speed determines line economics.
- Dual Cure:Hybrid radical-cationic packages enable epoxy-acrylate networks with combined surface hardness and substrate adhesion. Electronics encapsulation in Jiangsu province drives specification, as hybrid systems penetrate moisture-sensitive PCB protection where single-cure chemistry fails.
- Cationic:Sulfonium and iodonium salt photoinitiators generate Brønsted acids for epoxy ring-opening polymerization. Automotive metal primers in Germany specify these for low-shrinkage adhesion to aluminum battery housings.
- Photobase:Amine-generating structures cure anionic resins without thermal activation. Niche penetration in Japan's precision optical adhesive sector addresses temperature-sensitive polycarbonate substrates.
Mature deployment sits with Free Radical systems. Newer deployment is concentrated in Dual Cure formulations.
Application:
Film thickness and substrate geometry determine photoinitiator loading rates and spectral targeting.
- Coatings:Architectural wood and industrial metal finishing represent volume concentration. EPA NESHAP enforcement on solvent-based alternatives is accelerating UV line conversions in U.S. furniture manufacturing clusters.
- Adhesives:Medical device assembly and electronics lamination demand low-extractable photoinitiator grades. FDA scrutiny of migration potential in 21 CFR 175.105 compliance is forcing migration to Norrish Type I cleavage structures.
- Inks:Narrow-web flexographic and inkjet formulations require high-molar-extinction photoinitiators for thin-film cure at high line speeds. REACH authorization pressures on benzophenone derivatives are restructuring European supplier portfolios.
- Composites:Fiber-reinforced polymer manufacturing for wind turbine blades and automotive panels employs specialized photoinitiator packages for thick-section cure. Capital intensity limits adoption to high-value structural applications.
Coatings command established infrastructure. Adhesives present the steepest expansion trajectory on medical and electronics qualification cycles.
End User:
Procurement authority varies between centralized technical teams and distributed plant-level buyers.
- Manufacturing:General industrial coating operations span metal finishing, plastic decoration, and assembly bonding. MEE provincial enforcement in Guangdong is eliminating solvent-cure alternatives from facility expansions.
- Automotive:OEM specification power concentrates in thermal management coatings for battery enclosures and interior trim. Low-VOC curing mandates from California Air Resources Board are binding on national supply chains.
- Construction:Flooring and concrete protection applications favor high-dose photoinitiator loadings for thick-film build. Seasonal demand patterns in temperate climates create inventory management complexity.
- Electronics:PCB solder mask and semiconductor packaging demand sub-ppm metal content and comprehensive toxicological dossiers. Approved vendor list consolidation in Taiwan and South Korea is restricting supplier access.
Electronics procurement is tightening qualification requirements. Manufacturing presents the broadest addressable base.
Form:
Physical state determines handling protocols, storage stability, and formulation incorporation methods.
- Liquid:Standard acrylate-diluted solutions dominate high-volume coating formulations. Tianjin Jiuri and IGM Resins supply bulk liquid grades through regional distribution hubs.
- Solid:Crystalline photoinitiators offer extended shelf life and reduced shipping classification constraints. Powder coatings and solid ink applications specify these for dry-blend compatibility.
- Powder:Microencapsulated grades prevent premature activation in UV-curable powder coating systems. European architectural metal finishing is adopting these for zero-VOC compliance.
- Gel:Thixotropic dispersions enable precise metering in automated adhesive dispensing equipment. Medical device assembly lines in Massachusetts and Minnesota specify gel consistency for robotic application.
Liquid formulations anchor industrial scale. Solid and powder forms are gaining share in regulated shipping corridors and zero-VOC mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate photoinitiator demand through electronics contract manufacturing clusters. Jiangsu and Zhejiang provincial governments coordinate MEE enforcement with industrial park incentives.
China
Domestic manufacturers scale acylphosphine oxide capacity to serve PCB solder mask and packaging converters. GB standards on industrial VOC emissions eliminate imported solvent-cure systems from Jiangsu and Guangdong manufacturing parks. Suzhou and Shenzhen electronics clusters drive specification authority through approved vendor list consolidation.
Germany
Automotive OEMs specify low-shrinkage cationic photoinitiators for aluminum battery housing primers. REACH authorization requirements force portfolio rationalization as ECHA evaluates reproductive toxicity endpoints. Bavarian chemical parks near Ludwigshafen anchor specialty photoinitiator blending for European coating formulators.
United States
EPA NESHAP enforcement accelerates UV line conversions in metal finishing and wood furniture operations across Michigan and North Carolina. California Air Resources Board low-VOC mandates bind national automotive supply chains. Massachusetts and Minnesota medical device assembly lines specify gel-consistency photoinitiators for robotic dispensing.
Japan
Precision optical adhesive applications drive photobase system penetration for temperature-sensitive polycarbonate substrates. METI coordinates industrial chemical safety standards with electronics industry roadmaps. Chubu region around Nagoya concentrates photoinitiator distribution for semiconductor packaging materials.
India
PLI scheme incentives for electronics manufacturing attract photoinitiator suppliers to establish localized blending ahead of import substitution mandates. BIS certification requirements tighten specification for food-contact packaging applications. Karnataka and Tamil Nadu PCB fabrication clusters emerge as demand anchors.
Photoinitiators Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with formulation houses commanding premium positioning in regulated applications. The vendor base organizes around three archetypes: integrated chemical conglomerates with raw material backward integration, regional specialists serving single geographies, and application-focused blenders for electronics and medical niches. M&A activity concentrates on toxicological dossier acquisition for REACH compliance, while capacity expansion targets China and India to capture import substitution cycles.
Among Germany-based diversified chemical groups, Evonik Industries AG exemplifies the integrated archetype through specialty chemicals portfolio breadth. Tianjin Jiuri New Materials Co. Ltd anchors Chinese supply chains through in-house production of key intermediates. IGM Resins occupies a position within the application-specialist tier, focusing customized blends on industrial wood and furniture coating segments. These three represent distinct strategic postures: conglomerate diversification, regional vertical integration, and niche formulation expertise.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Tianjin Jiuri New Materials Co. Ltd |
| IGM Resins |
| Changzhou Tronly New Electronic Materials Co. Ltd |
| Zhejiang Yangfan Material Co. Ltd |
| ADEKA Corporation |
| Rahn AG |
| BASF SE |
| Lambson Ltd |
| Others |
Value Chain & Pricing Dynamics
Photochemistry formulation expertise concentration in Germany's Ludwigshafen chemical corridor widens pricing-tier spreads, as labor-cost differentials between European technical specialists and Asian manufacturing engineers compress margins on standard-grade photoinitiators while amplifying premiums for REACH-compliant specialty blends.
Pricing Analysis
Short lead-time premiums command substantial markups in photoinitiator procurement, with spot inventory availability from Chinese manufacturers trading at discounts against six-month contracted supply from European houses. Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant medical grades from industrial coating specifications and commodity packaging alternatives. Cost compression in standard acrylate formulations is intensifying because Jiangsu province capacity additions outpace demand absorption. Small regional formulators exhibit highest price sensitivity, while multinational coating houses with centralized technical approval authority accept premium positioning for toxicological dossier completeness.
Supply Chain Analysis
Freight cost volatility from Shanghai to Rotterdam disrupts quarterly procurement planning for European formulators dependent on Chinese benzophenone derivative intermediates. Supply concentrates in China, Germany, and the United States, with acylphosphine oxide production anchored in Tianjin and Ludwigshafen chemical parks. Raw material dependencies center on acetophenone derivatives, phosphorous trichloride, and tertiary amine synergists sourced from petrochemical feedstocks. Single-source vulnerability from Chinese manufacturers controlling over 70% of key intermediate production exposes North American buyers to tariff uncertainty. Distribution runs through regional blending facilities serving electronics clusters in Suzhou and automotive coating networks in Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The photoinitiators market functions as a cost-of-compliance story, where REACH authorization requirements for benzoin ether derivatives create a substantial barrier-to-entry moat for suppliers with comprehensive toxicological dossiers.
For Market Incumbents: Extend toxicological dossier coverage ahead of ECHA reproductive toxicity endpoint evaluations to capture reformulation contracts from competitors facing authorization sunset dates. Deepen backward integration into phosphorous trichloride intermediates to insulate margin structures from petrochemical feedstock volatility. Consolidate approved vendor list positions in Taiwan and South Korea electronics clusters through direct technical service relationships, displacing regional distributors losing access to premium grades. For New Entrants and Emerging Players: Launch via localized blending operations in Karnataka and Tamil Nadu ahead of India's PLI scheme import substitution mandates for PCB fabrication. Target waterborne UV hybrid system formulations for textile coating applications previously blocked by flammability constraints, where incumbent solvent-cure suppliers lack aqueous delivery expertise. Penetrate through medical device assembly qualifications in Massachusetts and Minnesota, where 18-24 month validation cycles deter established players from reallocating technical resources. For Investors and Strategic Acquirers: Re-rating potential sits with REACH registration holders given EU Green Deal chemical sustainability targets accelerating portfolio rationalization. Long-term viability over the next decade favors suppliers with dual-cure formulation capabilities spanning radical and cationic chemistries, as hybrid epoxy-acrylate systems displace single-cure alternatives in electronics encapsulation. Monitor ECHA authorization timelines for benzophenone derivatives as the critical inflection signal for substitution investment cycles and acquisition target availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediates | In-house production of phosphorous trichloride reduces exposure to petrochemical price swings and freight volatility. |
| REACH Dossier Expansion | Comprehensive toxicological data capture reformulation contracts from competitors facing ECHA authorization sunset dates. |
| Dual-Cure Formulation Development | Hybrid radical-cationic packages penetrate moisture-sensitive PCB protection where single-cure chemistry fails. |
| Localized Blending in India | Karnataka and Tamil Nadu facilities position ahead of PLI scheme import substitution mandates for electronics. |
| Waterborne UV Hybrid Systems | Aqueous delivery with photoinitiator activation penetrates textile coatings blocked by solvent flammability constraints. |
Study Parameters
Trade databases, ECHA substance registration filings, and SEC 10-K disclosures formed the secondary backbone, cross-referenced with primary interviews spanning coating formulators, photoinitiator procurement leads at multinational OEMs, distribution channel partners, and technical R&D directors at specialty chemical houses. Bottom-up volume estimates from individual application segments triangulated against top-down market sizing from customs data and industry association reports.
Historical trendline analysis across photoinitiator consumption patterns informed projection frameworks, with segmentation modeling by chemistry type, application viscosity constraints, end-use regulatory exposure, and regional production hub. CAGRs derived from weighted average of demand drivers including EPA NESHAP enforcement trajectories, electric vehicle battery housing specification rates, and MEE provincial VOC emission compliance timelines. Forecast inputs incorporated lamp emission profile evolution and chromophore absorption efficiency improvements.
Regulatory authorization delays, raw material intermediate supply disruptions, and dual-cure process validation timeline extensions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about enforcement consistency across MEE provincial branches and ECHA evaluation pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Copovidone Market
Specialty Chemicals
Perfluoroalkoxy Alkane (PFA) Market
Specialty Chemicals
Releasing Agents Market
Specialty Chemicals
Toner Spray Market
Specialty Chemicals
Sialic Acid Market
Specialty Chemicals
Copper Ammonium Carbonate Market
Specialty Chemicals
Xanthene Derivatives Market
Specialty Chemicals
Ursolic Acid Market
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Middle East and Africa Polyvinylpyrrolidone (PVP) Market
Specialty Chemicals
Biodegradable Chelating Agents Market