
 Betulinic Acid Market | 2026-2036
Betulinic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Betulinic Acid Market Analysis
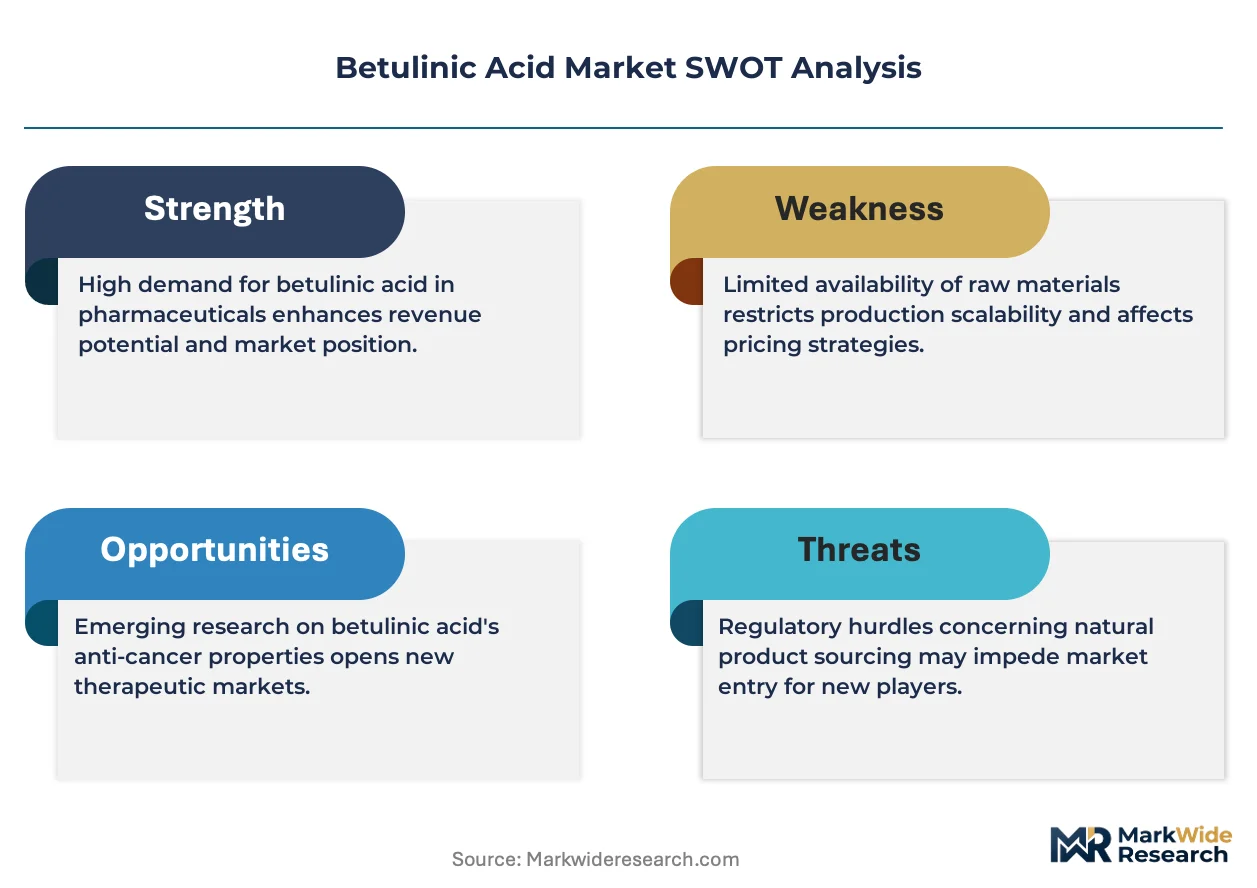
Chinese birch bark extractors is broadening output capacity for high-purity betulinic acid to serve contract API demand. Capot Chemicals leverages vertical integration from raw bark sourcing to GMP-grade isolation, sustaining cost advantages across Asian supply chains. Symrise BioActives GmbH anchors European pharmaceutical offtake through specialized purification protocols that meet EMA impurity thresholds.
Betulinic acid is a pentacyclic triterpenoid (C30H48O3) extracted primarily from birch bark through solvent or supercritical CO2 extraction, valued for its apoptosis-inducing and anti-inflammatory bioactivity in drug development. Purified betulinic acid commands premium positioning in pharmaceutical applications where USP-grade specifications determine clinical trial eligibility, while crude betulinic acid serves broader nutraceutical compounding at lower purity thresholds. The cosmetics application segment is gaining traction as formulators incorporate betulinic acid derivatives for melanin-inhibiting and collagen-preserving properties in dermocosmetic lines.
FDA botanical drug guidance, EMA quality guidelines for herbal medicinal products, and REACH chemical safety registration collectively elevate barriers for non-compliant producers seeking market access in regulated jurisdictions. These frameworks compel manufacturers to invest in validated analytical methods and stability data packages before commercial supply agreements. Stakeholders must monitor evolving pharmacopeial monograph revisions and botanical API master file requirements to sustain competitive positioning in clinical-grade supply chains.
Market Dynamics
Pharmaceutical-grade purity mandates from FDA botanical drug guidance and EMA quality guidelines are compressing supplier margins while concentrating procurement among vertically integrated extractors capable of validated analytical methods and stability data packages.
Growth Catalysts
- Oncology pipeline expansion:Apoptosis-inducing mechanisms in betulinic acid derivatives attract formulation investment from API manufacturers targeting solid tumor indications.
- REACH compliance acceleration:ECHA registration requirements for chemical safety data elevate barriers for non-compliant producers, rewarding established European purification specialists with locked-in offtake agreements.
- Supercritical CO2 extraction maturation:This solvent-free technology reduces residual impurity profiles below USP-grade thresholds, qualifying outputs for clinical trial material supply.
Market Restraints
- Birch bark supply concentration:Raw material sourcing clusters in Nordic and Siberian forest zones, exposing processors to climate-induced harvest volatility and export licensing friction.
- Multi-step purification cost structure:Chromatographic refinement and crystallization sequences consume solvent volumes that scale nonlinearly with purity targets above 98 percent.
- Semi-synthetic substitution threat:Laboratory-derived triterpenoid analogs from microbial fermentation platforms bypass botanical extraction entirely for certain research applications.
Strategic Opportunities
- Dermocosmetic application white space:Melanin-inhibiting and collagen-preserving properties position betulinic acid derivatives for premium skincare lines targeting photodamage repair.
- India CDSCO regulatory pathway:The country's national pharmaceutical regulator is streamlining botanical drug approval frameworks, creating early-mover advantages for compliant suppliers.
- Direct-to-manufacturer channel innovation:API producers are bypassing traditional distributors to secure dedicated extraction partnerships with bark processors.
Industry Challenges
- Pharmacopeial monograph lag:Absence of unified compendial standards for betulinic acid across USP, EP, and ChP forces manufacturers to maintain multiple analytical method validations.
- GMP certification timeline compression:FDA botanical drug master file preparation and EMA herbal medicinal product quality documentation require 18-24 month lead times that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Betulinic Acid Market |
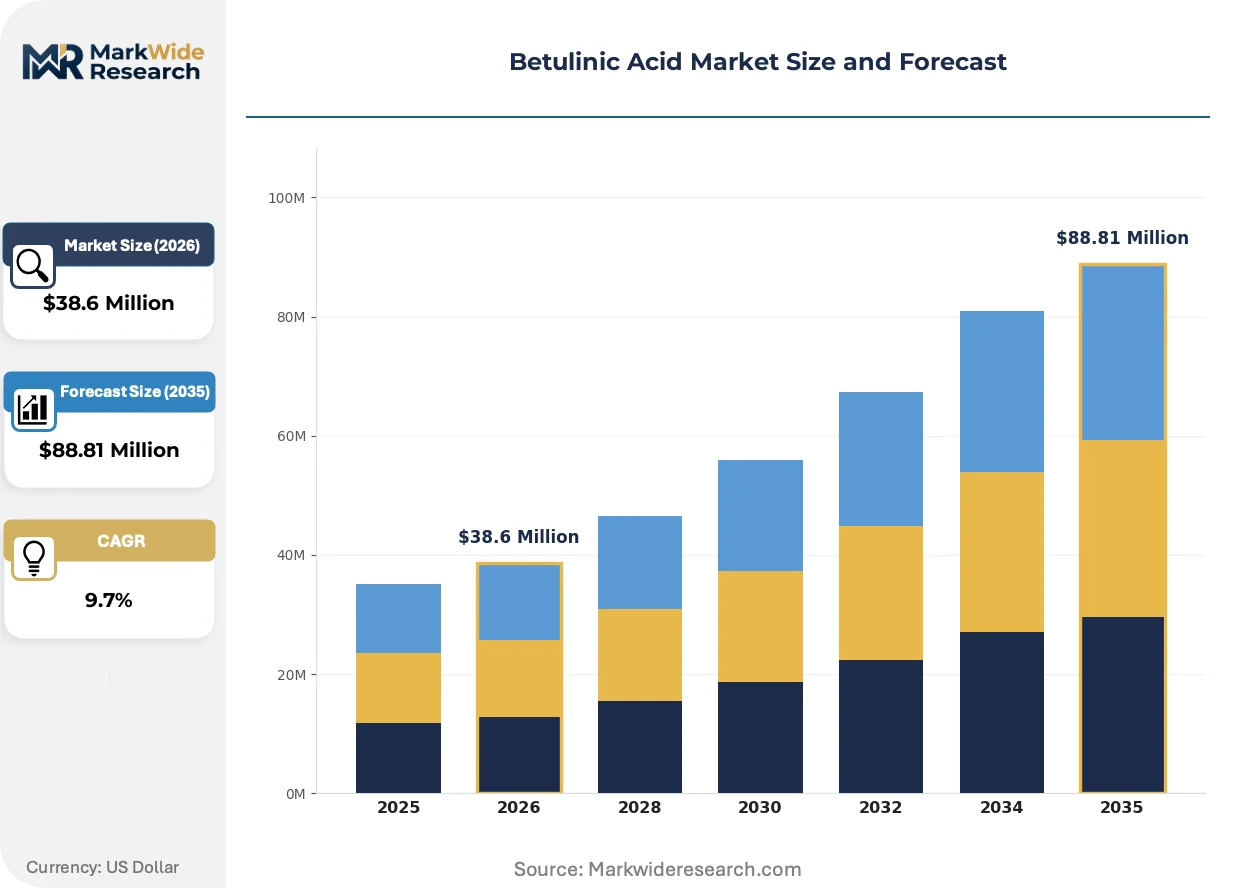
| Market Size in 2026 | $38.6 Million |
| Market Size in 2035 | $88.81 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Betulinic Acid, Purified Betulinic Acid, Betulin, Betulinic Acid Derivatives Application: Pharmaceuticals, Cosmetics, Nutraceuticals, Agrochemicals End User: Healthcare Providers, Cosmetic Manufacturers, Dietary Supplement Companies, Agricultural Firms Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Capot Chemicals, Jigs Chemical Limited, Symrise BioActives GmbH, Tokyo Chemical Industry Co., Ltd., Xi’an Eco Biotech, Manus Aktteva Biopharma LLP, Cayman Chemical, Kono Chem Co., Ltd., Aktin Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Betulinic Acid Market Emerging Trajectories
Supercritical fluid extraction platforms and green chemistry purification protocols are displacing conventional solvent-based methods, while regulatory data requirements force convergence between analytical capabilities and supply chain transparency.
Supercritical CO2 extraction systems are expanding into pharmaceutical-grade betulinic acid production as the dominant isolation technology. European and Chinese API manufacturers deploy these platforms to achieve residual solvent profiles below ICH Q3C thresholds. This diffusion is expanding into contract manufacturing organizations seeking botanical drug master file qualification for oncology pipelines.
EMA quality guidelines for herbal medicinal products now mandate full supply chain traceability from raw bark to isolated active. This regulatory tightening forces extractors to implement geolocation tagging and batch genealogy systems. German and French pharmaceutical offtake contracts now require documented sustainability credentials alongside purity certificates.
Long-term offtake agreements with fixed-volume, variable-price structures are displacing spot market transactions for clinical-grade material. Oncology API manufacturers in the United States and Germany lock in three-to-five year supply commitments to secure master file consistency. This contractual shift concentrates procurement power among extractors with demonstrated GMP compliance and validated stability data packages.
Betulinic Acid Market Segmentation
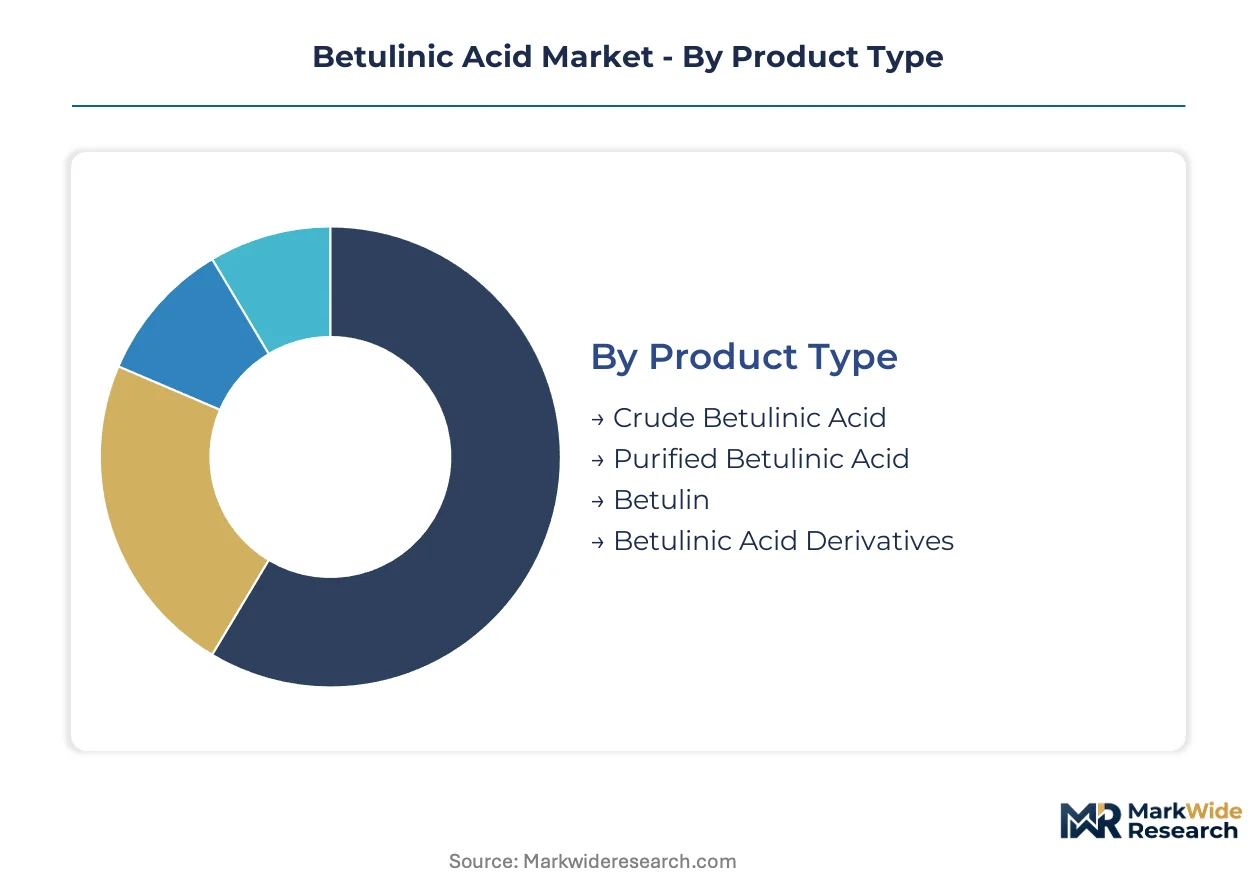
Betulinic acid procurement splits across purity grades and regulatory thresholds. Pharmaceutical formulators, cosmetic chemists, and agricultural researchers each impose distinct specification requirements that reshape supplier capabilities and pricing structures.
Product Type:
Cost tier determines clinical eligibility and formulation access across buyer categories.
- Purified Betulinic Acid:USP-grade material exceeding 98 percent purity qualifies for FDA botanical drug master files and EMA herbal medicinal product submissions. Oncology API manufacturers in Germany and the United States concentrate procurement here, accepting 40-60 percent cost premiums for validated stability data packages and chromatographic impurity profiles below ICH Q3C thresholds.
- Crude Betulinic Acid:Partially refined extract at 70-85 percent purity serves nutraceutical compounding and agricultural research where pharmacopeial compliance is not mandated. Chinese and Indian dietary supplement manufacturers dominate offtake, prioritizing volume scale over monograph precision.
- Betulin:The precursor triterpenoid extracted prior to oxidation serves as feedstock for semi-synthetic betulinic acid production and standalone cosmetic applications.
- Betulinic Acid Derivatives:Functionalized analogs including C-28 esters and amides target specific pharmacokinetic profiles in antiviral and anti-inflammatory pipelines.
Volume sits with Crude Betulinic Acid; growth tilts toward Purified Betulinic Acid.
Application:
Regulatory pathway maturity separates investment-grade segments from commodity positioning.
- Pharmaceuticals:Apoptosis-inducing mechanisms in oncology and antiviral drug development command the steepest expansion trajectory. EMA quality guidelines and FDA botanical drug guidance impose GMP certification and full supply chain traceability, locking in three-to-five year offtake agreements with vertically integrated extractors.
- Cosmetics:Melanin-inhibiting and collagen-preserving properties drive dermocosmetic incorporation. French and German formulators lead derivative adoption for photodamage repair lines, bypassing pharmaceutical-grade purity mandates while requiring documented sustainability credentials.
- Nutraceuticals:Capsule and tablet applications in immune support formulations concentrate demand among Chinese and Indian dietary supplement manufacturers.
- Agrochemicals:Antifungal and plant defense applications remain experimental, with agricultural research institutes evaluating betulinic acid as a botanical pesticide alternative.
Revenue concentrates in Pharmaceuticals; Cosmetics gains share fastest.
End User:
Technical specification authority determines supplier relationship depth.
- Healthcare Providers:Hospital systems and specialty clinics sourcing compounded formulations drive demand for clinical-grade material with batch-specific certificates of analysis.
- Cosmetic Manufacturers:Premium skincare houses in France and Germany require ECHA-registered derivatives with geolocation-tagged birch bark provenance.
- Dietary Supplement Companies:Volume buyers in China and India prioritize cost efficiency over pharmacopeial compliance for encapsulated immune products.
- Agricultural Firms:Research divisions at crop science conglomerates evaluate betulinic acid derivatives for integrated pest management programs.
Procurement scale favors Dietary Supplement Companies; contract duration extends longest with Healthcare Providers.
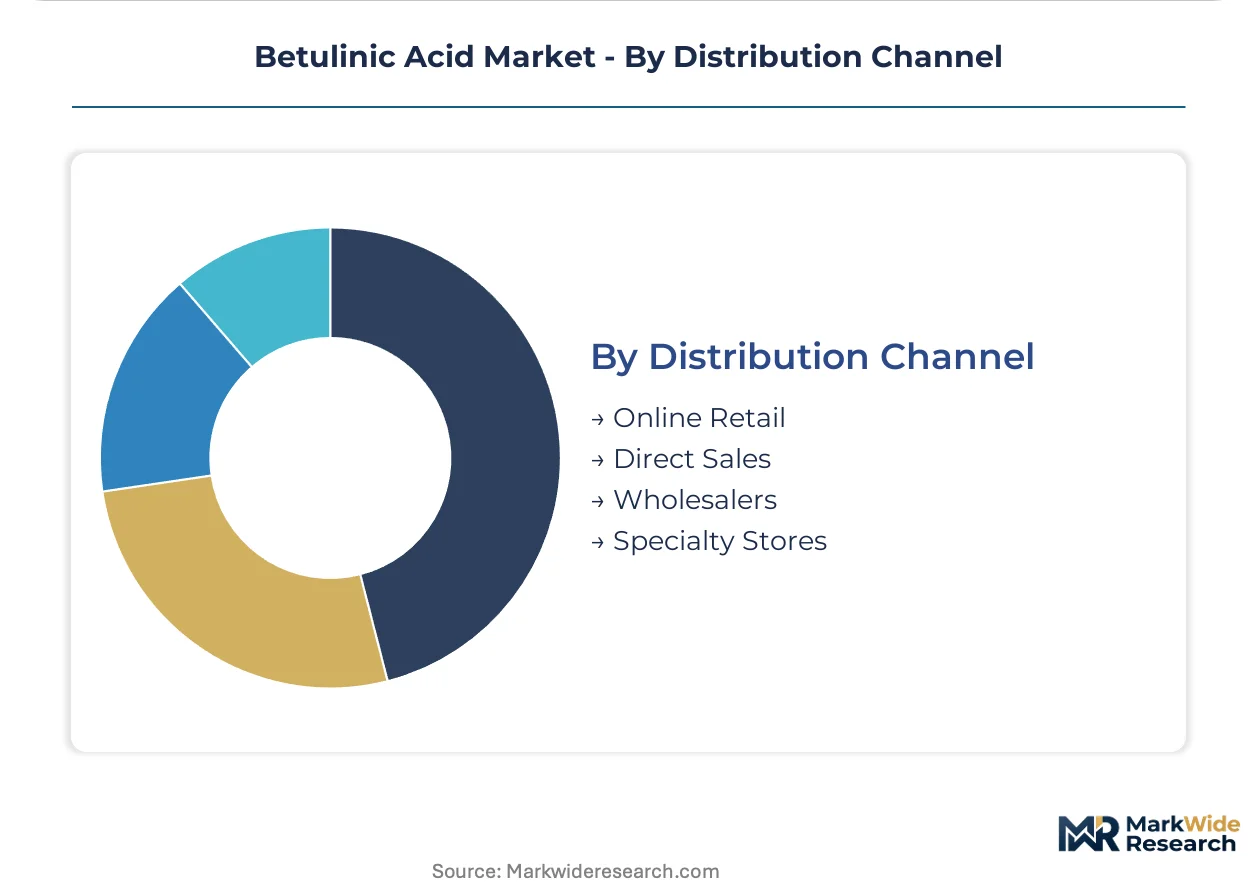
Distribution Channel:
Supply chain transparency requirements reshape channel selection by purity tier.
- Direct Sales:API manufacturers bypass distributors to secure dedicated extraction partnerships with birch bark processors, locking in master file consistency and fixed-volume variable-price structures.
- Wholesalers:Traditional chemical distributors serve nutraceutical and agrochemical buyers with standardized crude material and shorter contract cycles.
- Online Retail:E-commerce platforms capture small-volume cosmetic and research chemical procurement, particularly for derivative samples and reference standards.
- Specialty Stores:Regional distributors with analytical capabilities provide technical support for mid-scale pharmaceutical and cosmetic formulators.
Transaction volume flows through Wholesalers; value concentration shifts toward Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Birch bark harvesting clusters in Nordic and Siberian forest zones shape geographic supply patterns. API manufacturers in Germany, China, and the United States secure dedicated extraction partnerships to lock in clinical-grade material flows.
Germany
Oncology API manufacturers in Baden-Württemberg drive demand for USP-grade betulinic acid with validated stability data packages. EMA quality guidelines for herbal medicinal products mandate full supply chain traceability from raw bark to isolated active. Frankfurt-area pharmaceutical offtake contracts now require documented sustainability credentials alongside chromatographic impurity profiles.
China
Contract API demand from domestic and international formulators accelerates high-purity extraction capacity expansion. NMPA botanical drug guidance aligns with USP-grade specifications for clinical trial material supply. Shaanxi and Sichuan province extractors deploy supercritical CO2 platforms to achieve residual solvent profiles below ICH Q3C thresholds.
United States
FDA botanical drug guidance tightens purity benchmarks for clinical-grade betulinic acid entering oncology pipelines. Boston and San Francisco biotech clusters source three-to-five year offtake agreements to secure master file consistency. Midwestern bark processors implement geolocation tagging systems to satisfy EMA-equivalent traceability requirements.
India
CDSCO regulatory streamlining for botanical drug approvals creates early-mover advantages for compliant suppliers. Maharashtra and Gujarat dietary supplement manufacturers dominate crude betulinic acid procurement for immune support formulations. Hyderabad API producers evaluate dedicated extraction partnerships with Himalayan birch processors.
Japan
PMDA quality guidelines for natural product APIs elevate analytical method validation requirements for imported betulinic acid. Tokyo and Osaka pharmaceutical formulators prioritize Japanese pharmacopeia-compliant material for antiviral drug development. Hokkaido forest zones supply domestic bark processors serving research chemical and cosmetic applications.
Betulinic Acid Market Vendor Landscape
Global majors compete with regional champions across purification technology and regulatory compliance capabilities. Market structure tilts toward vertically integrated extractors capable of GMP-grade isolation from raw bark sourcing. Three archetypes dominate: Asian contract manufacturers with cost-optimized extraction platforms, European specialists with EMA-registered purification protocols, and diversified chemical distributors serving research and nutraceutical tiers. Capacity expansion and backward integration into birch bark supply chains represent the dominant competitive moves.
Among China-based extractors, Capot Chemicals and Xi'an Eco Biotech exemplify the vertically integrated archetype spanning raw material sourcing to GMP-grade output. Symrise BioActives GmbH anchors European pharmaceutical offtake through specialized purification capabilities. Tokyo Chemical Industry Co., Ltd. occupies a position bridging research chemical distribution and pharmaceutical-grade supply. Cayman Chemical represents the North American specialist tier focused on reference standards and analytical-grade material.
| Leading Market Players |
|---|
| Capot Chemicals |
| Jigs Chemical Limited |
| Symrise BioActives GmbH |
| Tokyo Chemical Industry Co., Ltd. |
| Xi'an Eco Biotech |
| Manus Aktteva Biopharma LLP |
| Cayman Chemical |
| Kono Chem Co., Ltd. |
| Aktin Chemicals |
| Others |
Supply Flow & Price Mechanics
Supercritical CO2 extraction maturation is compressing production economics for pharmaceutical-grade material while simultaneously concentrating supply power among extractors capable of GMP-grade validation. This technology transition rewards early adopters in Germany and China with cost positions that solvent-dependent competitors cannot replicate, locking in pricing premiums for clinical trial supply.
Pricing Analysis
Validated stability data packages and chromatographic impurity certificates are bundled into pharmaceutical-grade contracts, while crude material trades unbundled. Three-tier pricing structure across USP-grade, technical-grade, and feedstock levels separates oncology API manufacturers from nutraceutical compounders from agricultural researchers. Price differentiation rests on certification tier and volume commitment scale. Cost compression in the crude tier is intensifying because Chinese extractors are expanding capacity faster than quality-grade demand. Dietary supplement manufacturers in India exhibit highest price sensitivity; German pharmaceutical formulators accept steep premiums for master file consistency.
Supply Chain Analysis
GMP certification and EMA herbal medicinal product registration function as non-negotiable gates for European pharmaceutical offtake. Raw birch bark sourcing clusters in Finland, Russia, and China. Isolated active production draws from Nordic forest harvests, Siberian export licenses, and Shaanxi province extraction platforms. Single-source vulnerability runs through concentrated Nordic bark supply exposed to climate-induced harvest volatility. Distribution runs through direct sales channels for clinical-grade material and traditional chemical wholesalers for nutraceutical tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA botanical drug guidance and EMA quality guidelines have erected a cost-of-compliance barrier that rewards incumbent extractors with locked-in offtake agreements while straining capital reserves for aspirant entrants. REACH registration and pharmacopeial monograph compliance function as durable moats protecting validated suppliers.
For Market Incumbents: To counter semi-synthetic substitution threats from microbial fermentation platforms, deepen backward integration into birch bark supply chains through long-term forest harvesting concessions, and accelerate supercritical CO2 capacity expansion to sustain cost advantages below ICH Q3C thresholds.
For New Entrants and Emerging Players: Cosmetic formulators seeking ECHA-registered derivatives with sustainability credentials represent the most penetrable buyer archetype, bypassing pharmaceutical-grade purity mandates while requiring documented geolocation tagging. Target French and German dermocosmetic houses through specialized purification partnerships. A white-label derivative supply angle unlocks faster revenue traction than clinical-grade API qualification.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified chemical houses seeking botanical API capabilities. Long-term viability favors extractors with demonstrated GMP compliance and validated stability data packages across the extended window. Acquisition target archetype: vertically integrated Chinese or European extractors with captive bark supply and EMA-registered protocols. The signal to watch is CDSCO regulatory streamlining completion, which would trigger Indian market entry acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Enables residual solvent profiles below ICH Q3C thresholds for FDA master file qualification. |
| Backward Integration into Birch Bark Supply | Secures captive raw material flows from Nordic and Siberian forest zones against harvest volatility. |
| EMA Herbal Medicinal Product Registration | Unlocks three-to-five year offtake agreements with German oncology API manufacturers. |
| CDSCO Regulatory Pathway Navigation | Captures early-mover advantages in India's streamlining botanical drug approval framework. |
| Dermocosmetic Derivative Development | Targets melanin-inhibiting applications for French and German premium skincare lines. |
Methodological Framework
Document review covered FDA botanical drug master files, EMA herbal medicinal product submissions, and REACH registration databases, complemented by interviews with API manufacturing executives, regulatory affairs specialists at European pharmaceutical firms, birch bark procurement managers, and supercritical extraction platform engineers. Secondary validation drew from customs trade data, pharmacopeial monograph revisions, and clinical trial registry entries. Bottom-up capacity assessments and top-down demand modeling were triangulated against contract announcement tracking.
Segment-level outputs across purity grades, application verticals, and end-user categories were generated through structured modeling. Oncology pipeline advancement rates, cosmetic formulation adoption curves, and nutraceutical compounding volumes were cross-referenced against regulatory filing timelines. CAGRs were derived from volume trajectory reconciliation between extraction capacity expansion announcements and pharmaceutical offtake contract disclosures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to birch bark harvest volatility, REACH enforcement intensity, and semi-synthetic substitution breakthroughs. Forecasts reflect documented assumptions regarding regulatory pathway timelines and extraction technology diffusion rates. A model refresh is warranted upon material change in FDA botanical drug guidance or EMA herbal medicinal product quality guideline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Ubiquinone Market
Specialty Chemicals
Phenoxycycloposphazene Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Global Metal Chelates Market
Specialty Chemicals
Prils Market
Specialty Chemicals
Automotive Silicone Market
Specialty Chemicals
Bio-Ketones Market
Specialty Chemicals
Toner Spray Market
Specialty Chemicals
Myrcene Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Global Molecular Weight Marker Market
Specialty Chemicals
Isophytol Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Xanthene Derivatives Market
Specialty Chemicals
Taurine Market