
 Erucic Acid Market | 2026-2036
Erucic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Erucic Acid Market Analytics
Petrochemical-derived lubricant basestocks is rebalancing toward plant-based alternatives as engineering specifications tighten. Vantage Specialty Chemicals leverages its North American oleochemical infrastructure to supply high-purity erucic acid fractions. Croda International Plc anchors European demand through backward integration into rapeseed processing. BASF SE competes on surfactant-grade specifications for industrial emulsifier markets.
Erucic acid is a monounsaturated omega-9 fatty acid (C22:1) extracted from high-erucic rapeseed and crambe oils through fractional crystallization or molecular distillation, valued for its long carbon chain that delivers superior oxidative stability and low-temperature fluidity in synthetic lubricants. Refined oil grades dominate value capture due to pharmaceutical and cosmetic compliance requirements, while crude oil segments sustain volume throughput in industrial chemical feedstock channels. Application sector demand concentrates in lubricants and surfactants, where emulsifier functionality commands premium positioning over textile processing aids.
REACH registration requirements in Europe and FDA food-contact substance notifications in the United States constrain market entry for non-compliant producers, while India's BIS certification for edible oil derivatives shapes import quality thresholds. China's GB standards for industrial lubricant base oils are tightening viscosity-index minimums, indirectly filtering erucic acid specification tiers. Stakeholders must monitor regulatory divergence between cosmetic-grade and industrial-grade purity standards to align capacity investments with the stricter of overlapping compliance regimes.
Market Dynamics
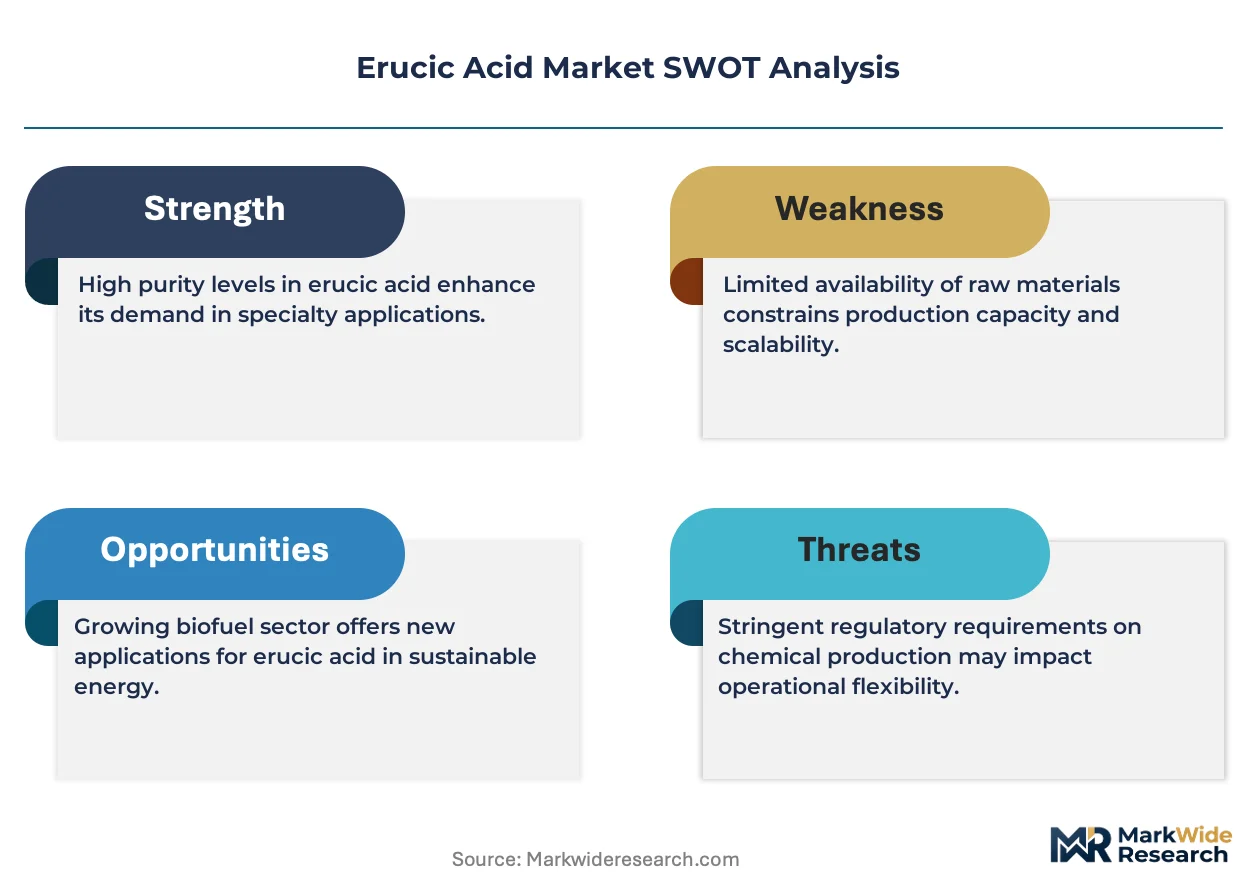
REACH restrictions on mineral oil derivatives in Europe are forcing lubricant formulators to accelerate plant-based feedstock qualification programs, compressing the substitution timeline for petrochemical basestocks.
Growth Catalysts
- ECHA REACH Annex XVII:Restrictions on polycyclic aromatic hydrocarbons in rubber extender oils are diverting demand toward erucic acid-derived synthetic esters for tire manufacturing.
- High-erucic rapeseed breeding programs:Agricultural biotechnology advances in Canada and Eastern Europe are expanding oilseed supply pools with erucic acid content exceeding 50%.
- Wind turbine gearbox lubrication:OEM specifications for biodegradable hydraulic fluids are mandating C22:1 fatty acid esters for offshore installations in the North Sea.
Market Restraints
- Seed oil supply concentration:Over 70% of high-erucic rapeseed cultivation concentrates in Canadian prairies and Polish farmland, exposing processors to weather-driven yield volatility.
- FDA food-contact substance notification:Uncleared erucic acid derivatives face exclusion from food packaging adhesive applications, limiting addressable market scope.
- Polyalphaolefin competition:Synthetic hydrocarbon basestocks offer equivalent viscosity index at lower formulation cost for non-biodegradable industrial lubricants.
Strategic Opportunities
- India BIS certification pipeline:Edible oil derivative standards are creating compliant import pathways for pharmaceutical-grade erucic acid fractions.
- Metathesis chemistry convergence:Cross-coupling of erucic acid with petrochemical olefins is enabling novel surfactant architectures for personal care applications.
- Direct-to-blender distribution:Specialty chemical distributors in China are establishing regional blending facilities to bypass multi-tier margin stacking.
Industry Challenges
- Fractional crystallization expertise:Pharmaceutical-grade purity requires process engineers trained in low-temperature separation physics, a skill set concentrated at European oleochemical specialists.
- Dual-use export classification:High-purity erucic acid fractions face customs scrutiny under chemical weapons precursor monitoring regimes, delaying cross-border shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Erucic Acid Market |
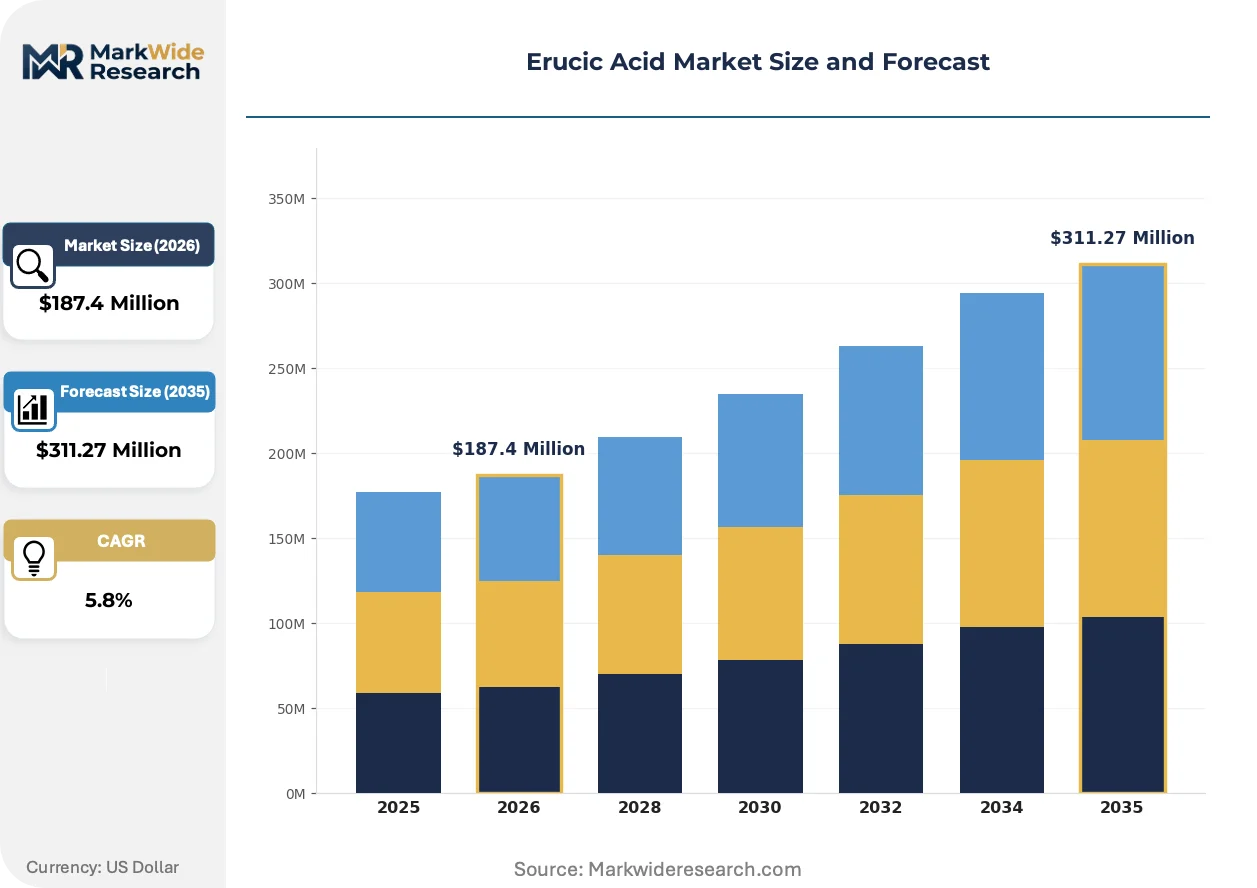
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Crude Oil, Marginally Refined Oil, Blends End Use Industry: Food & Beverage, Cosmetics, Pharmaceuticals, Industrial Chemicals Packaging Type: Bulk Containers, Cans, Drums, Pails Application Sector: Lubricants, Surfactants, Textiles, Emulsifiers |
| Companies Covered | Vantage Specialty Chemicals, Croda International Plc, Cargill, Inc., Godrej Industries Limited, Bunge Limited, Wilmar International Ltd., Evonik Industries, Archer-Daniels-Midland Company, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Erucic Acid Market Evolving Landscape
Process intensification in oleochemical refining is collapsing the cost gap between plant-derived and synthetic lubricant feedstocks. Molecular distillation advances and enzymatic interesterification are reshaping competitive economics.
Supercritical CO2 extraction is electrifying the recovery of high-value erucic acid fractions from crambe oil processing streams. Specialty lubricant blenders in Germany are adopting this technology to secure pharmaceutical-grade supply chains. The process is electrifying margin capture in premium synthetic ester segments previously dominated by petrochemical routes.
China's GB 11121-2021 standard for industrial lubricant base oils is tightening viscosity-index minimums and oxidation stability thresholds. Domestic formulators are reformulating hydraulic fluids to meet these specifications. The regulation is accelerating qualification programs for C22:1-derived synthetic esters in heavy equipment applications.
Blender procurement committees are consolidating supplier panels and demanding certified sustainability credentials alongside technical specifications. Long-term offtake agreements with traceable oilseed origin are displacing spot market purchasing in European lubricant manufacturing. This concentration is most visible in German automotive supplier parks where OEM sustainability scorecards govern feedstock selection.
Erucic Acid Market Segmentation
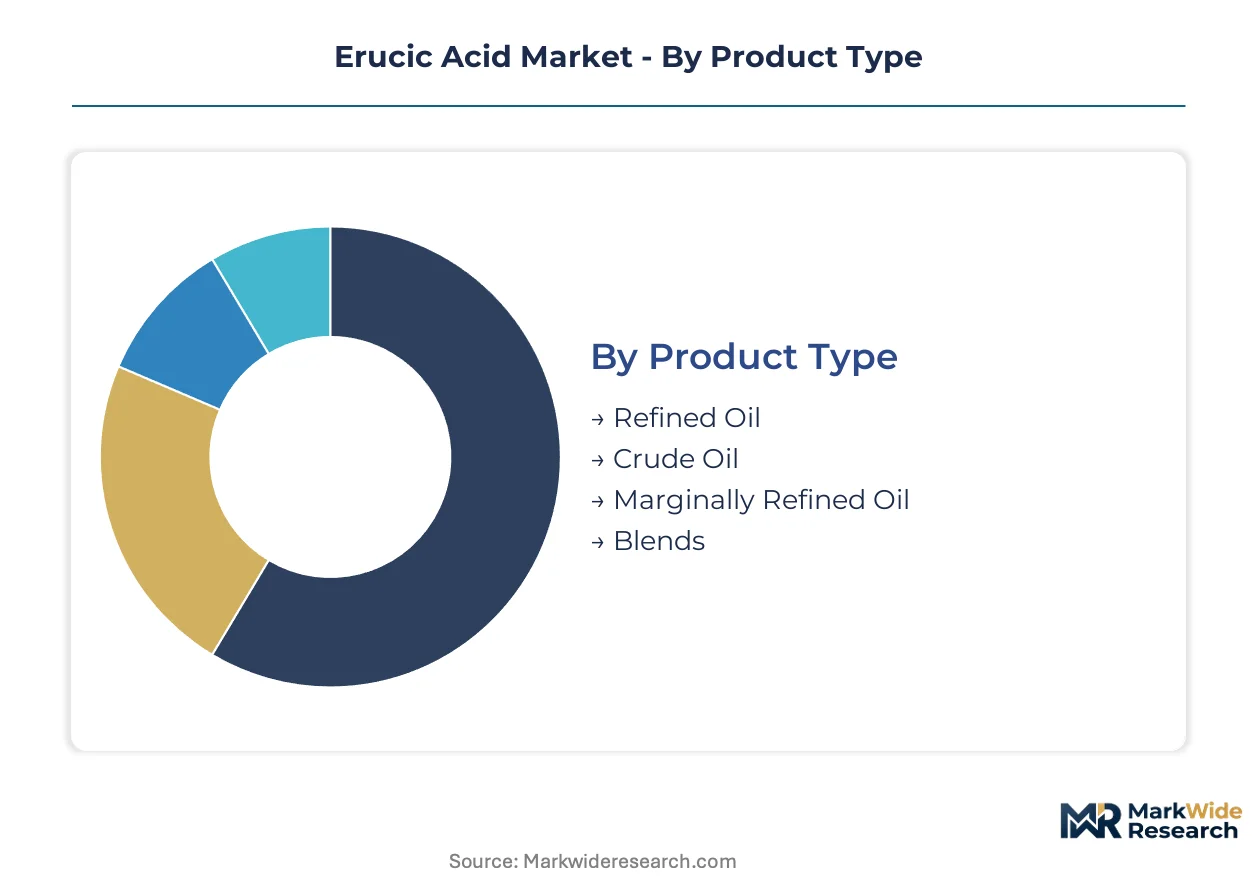
Erucic acid value chains bifurcate sharply between standalone high-purity grades and embedded industrial feedstocks. Segmentation discipline separates pharmaceutical compliance premiums from commodity chemical throughput economics.
Product Type:
Standalone pharmaceutical and cosmetic grades command premium positioning through certification overhead, while embedded industrial feedstocks compete on volume throughput and specification tolerances.
- Refined Oil:Pharmaceutical-grade fractions achieve purity thresholds exceeding pharmaceutical monograph specifications through molecular distillation or supercritical CO2 extraction. Cosmetic formulators in Germany and pharmaceutical excipient suppliers in India prioritize this grade for oxidative stability in lipid-based drug delivery systems. REACH compliance documentation and FDA food-contact substance notifications add fixed certification costs that filter out non-specialized distributors.
- Crude Oil:Unrefined crambe and high-erucic rapeseed oil streams containing 40-55% erucic acid content serve as direct feedstock for industrial esterification. Canadian processors and Polish oilseed crushers dominate supply origination. Bulk chemical purchasers accept higher free fatty acid content in exchange for lower unit economics in surfactant manufacturing.
- Marginally Refined Oil:Partially degummed and neutralized grades bridge specification gaps for textile softener manufacturers.
- Blends:Custom-formulated mixtures with oleic or linoleic acid fractions optimize pour-point depressant performance in synthetic lubricant basestocks.
Crude oil leads volumes today; refined oil is gaining share fastest through pharmaceutical contract manufacturing expansion.
End Use Industry:
Cost tier separation distinguishes compliance-intensive consumer-facing applications from specification-tolerant industrial processing channels.
- Food & Beverage:Erucic acid derivatives face strict regulatory ceilings in edible oil formulations. FDA food-contact substance notifications and EFSA evaluations constrain permissible migration limits into food matrices. Specialty lubricant applications for food processing equipment represent the primary compliant pathway, where incidental contact approvals enable synthetic ester deployment in conveyor systems and packaging machinery.
- Cosmetics:Personal care formulators leverage C22:1 chain length for emollient stability in anhydrous skin care products. REACH registration dossiers and ISO 16128 natural origin certifications filter supplier qualification. European contract manufacturers demand batch-level traceability to specific oilseed cultivars.
- Pharmaceuticals:Excipient-grade specifications for parenteral lipid emulsions and oral drug delivery systems require GMP-compliant production facilities.
- Industrial Chemicals:Surfactant and lubricant intermediate manufacturing absorbs volume throughput with relaxed purity tolerances.
Industrial chemicals leads volumes today; pharmaceuticals is climbing the fastest through lipid nanoparticle formulation demand.
Packaging Type:
Volume scale and customer procurement sophistication determine packaging configuration, with bulk logistics dominating integrated chemical park supply chains.
- Bulk Containers:ISO tank containers and flexitanks serve lubricant blenders and surfactant manufacturers with dedicated tank farm infrastructure. German automotive supplier parks and Chinese regional blending facilities optimize total delivered cost through direct pump-over connections. Minimum order quantities typically exceed 20 metric tons.
- Drums:200-liter steel and polyethylene drums accommodate mid-scale pharmaceutical and cosmetic compounders with limited bulk handling capabilities.
- Cans:Small-format packaging serves laboratory-scale formulators and sampling programs for new product qualification.
- Pails:Intermediate 20-25 liter containers bridge drum and can formats for specialty chemical distributors.
Bulk containers leads volumes today; drums is expanding most quickly through pharmaceutical outsourcing growth.
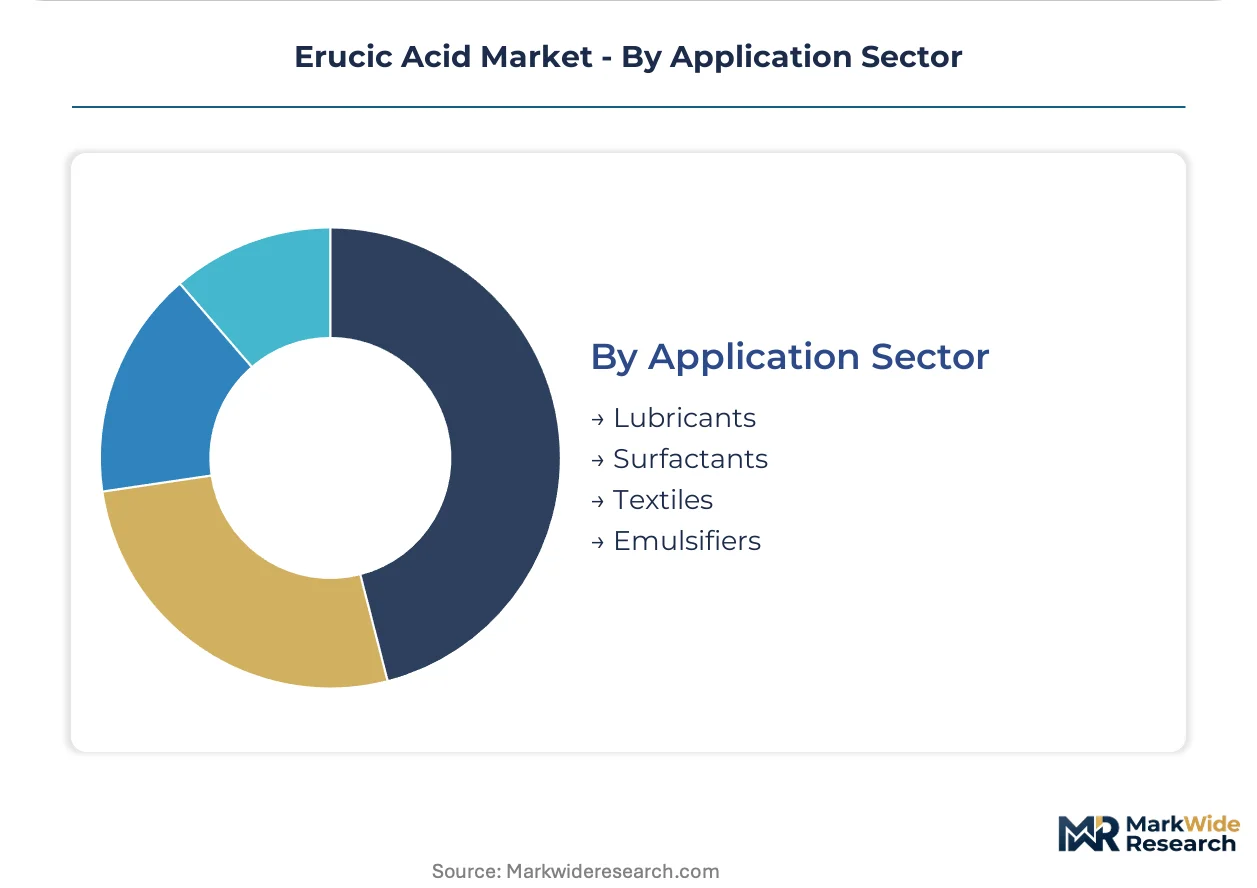
Application Sector:
Application maturity separates established lubricant basestock demand from emerging surfactant architectures enabled by metathesis chemistry advances.
- Lubricants:Synthetic ester basestocks derived from erucic acid deliver viscosity index values exceeding 180 and biodegradability thresholds mandated by EU Ecolabel and Germany's Blue Angel certifications. Wind turbine OEM specifications for offshore hydraulic fluids in the North Sea explicitly require C22:1-derived components for oxidative stability in salt spray environments. Automotive transmission fluid formulators are qualifying high-erucic content for electric vehicle thermal management fluids.
- Surfactants:Long-chain fatty acid derivatives enable low-foaming emulsifier architectures for industrial cleaning and personal care applications.
- Textiles:Fiber lubricants and softening agents utilize erucic acid esters for antistatic properties in synthetic yarn processing.
- Emulsifiers:Food-grade and pharmaceutical-grade emulsifier specifications command premium positioning through dual-use regulatory pathways.
Lubricants leads volumes today; surfactants is gaining share fastest through metathesis-enabled molecular architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German automotive supplier corridor anchors industrial demand for high-purity erucic acid fractions. REACH compliance documentation and OEM sustainability scorecards filter supplier qualification across the value chain. Regional blending facilities in the Ruhr Valley optimize direct pump-over logistics for lubricant manufacturers.
Germany
Wind turbine OEM specifications for offshore hydraulic fluids mandate C22:1-derived synthetic esters for North Sea installations. ECHA REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons divert tire manufacturing demand toward erucic acid-based rubber extenders. The Hamburg-Bremen chemical cluster hosts specialty distributors prioritizing pharmaceutical-grade molecular distillation capacity.
United States
Bio-based lubricant formulators scale purchases as FDA food-contact substance notifications constrain mineral oil alternatives. EPA biodegradable hydraulic fluid specifications for federal procurement filter supplier panels. Texas Gulf Coast petrochemical corridors integrate oleochemical fractionation for domestic synthetic ester supply.
China
GB 11121-2021 viscosity-index minimums force hydraulic fluid reformulation toward plant-derived basestocks. SAMR industrial lubricant quality inspections accelerate qualification programs for C22:1 fractions. Yangtze River Delta regional blending facilities bypass multi-tier margin stacking through direct-to-blender distribution.
India
Pharmaceutical contract manufacturers drive refined oil grade demand for lipid-based drug delivery systems. BIS certification for edible oil derivatives establishes import quality thresholds for excipient-grade supply. Gujarat specialty chemical parks concentrate fractional crystallization capacity serving domestic surfactant producers.
Canada
High-erucic rapeseed breeding programs expand oilseed supply pools with erucic acid content exceeding 50%. Prairie province cultivation concentration exposes processors to weather-driven yield volatility. Saskatchewan crushing facilities supply unrefined crambe oil streams for North American industrial esterification.
Erucic Acid Market Competitive Landscape
Global majors compete with regional champions across certification-tier supply chains, with market structure consolidating around three archetypes. Backward-integrated agribusiness conglomerates control upstream oilseed origination. European oleochemical specialists capture pharmaceutical-grade premiums through molecular distillation expertise. Asian trading houses optimize volume throughput in industrial feedstock channels. Competitive dynamics center on sustainability credential certification and regional blending facility establishment.
Within the European specialist tier, Croda International Plc and BASF SE exemplify compliance-forward positioning. Vantage Specialty Chemicals anchors North American oleochemical infrastructure. Cargill, Inc. represents agribusiness integration from seed breeding through fractionation. These three archetypes illustrate how geographic concentration of process expertise and regulatory proximity shape competitive boundaries.
| Leading Market Players |
|---|
| Vantage Specialty Chemicals |
| Croda International Plc |
| Cargill, Inc. |
| Godrej Industries Limited |
| Bunge Limited |
| Wilmar International Ltd. |
| Evonik Industries |
| Archer-Daniels-Midland Company |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Family-owned Polish oilseed crushers and Canadian prairie cooperatives anchor upstream origination, translating weather-driven yield volatility into asymmetric pricing power over European and Asian processors. Their collective bargaining position tightens feedstock costs for molecular distillation specialists while compressing margins at industrial-grade refiners.
Pricing Analysis
Input-cost pass-through from high-erucic rapeseed and crambe oilseed markets governs contract structures, with Canadian crushers indexing quarterly supply agreements to prairie futures. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade levels separates certification-burdened premiums from volume-driven commodity tiers. Pricing pressure stems from polyalphaolefin competition in non-biodegradable lubricant segments, forcing C22:1 ester producers to absorb margin compression. Industrial chemical purchasers exhibit highest price sensitivity, while pharmaceutical excipient buyers prioritize batch traceability over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Canadian prairie provinces and Polish farmland, where over 70 percent of high-erucic rapeseed cultivation concentrates. The supply chain draws from crambe oilseed genetics, molecular distillation equipment, and supercritical CO2 extraction solvents as critical inputs. Tariff exposure on cross-border specialty chemical shipments creates customs delays under dual-use export classification regimes. Distribution runs through regional blending facilities in Germany's Ruhr Valley and China's Yangtze River Delta, bypassing multi-tier distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in erucic acid value chains rests on pharmaceutical-grade certification premiums and process intensification cost-downs in supercritical extraction. Specialty chemical producers capturing both dynamics will outearn commodity-facing competitors.
For Market Incumbents: Deploy backward integration into high-erucic rapeseed breeding programs to secure cultivars exceeding 50 percent erucic acid content. Incumbents must defend against polyalphaolefin substitution by accelerating REACH-compliant synthetic ester qualification with German automotive OEMs. Capacity addition in Saskatchewan crushing infrastructure locks in origination control before weather volatility intensifies. For New Entrants and Emerging Players: Supercritical CO2 extraction technology offers a defensible entry wedge into pharmaceutical-grade supply chains previously dominated by European oleochemical specialists. White-space targets include India's BIS-certified excipient market and China's GB 11121-2021 compliant hydraulic fluid segment. Go-to-market execution should prioritize direct-to-blender distribution partnerships in Yangtze River Delta chemical parks. For Investors and Strategic Acquirers: Specialty lubricant formulators with sustainability scorecard credentials are the most active acquirer in this space, seeking captive supply of traceable C22:1 fractions. Acquisition targets with molecular distillation expertise and GMP-compliant production facilities command scarcity premiums. Watch for ECHA REACH Annex XVII expansion announcements as inflection signals for rubber extender oil substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Breeding | Cultivar control exceeding 50% erucic acid content secures asymmetric feedstock pricing power against prairie weather volatility. |
| Supercritical CO2 Extraction Scale-Up | Pharmaceutical-grade margin capture electrifies synthetic ester economics previously dominated by petrochemical routes in Germany. |
| REACH-Compliant Certification Investment | Annex XVII documentation unlocks tire manufacturing demand diversion from polycyclic aromatic hydrocarbon-restricted rubber extenders. |
| Direct-to-Blender Distribution Expansion | Yangtze River Delta regional facilities collapse multi-tier margin stacking for Chinese hydraulic fluid formulators. |
| Long-Term Offtake Agreements with Traceability | OEM sustainability scorecards in German automotive supplier parks displace spot market purchasing for lubricant feedstocks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Canadian crushing facilities, procurement leads at German lubricant blenders, distribution channel partners in Indian specialty chemical parks, and technical R&D directors at European oleochemical specialists. Secondary validation drew from customs and trade data, ECHA REACH registration dossiers, SEC 10-K filings of agribusiness conglomerates, and GB standards documentation. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Segment-weighting across the projection horizon applied grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs were derived from historical trajectory analysis and forward-looking qualification pipeline assessment. Forecast inputs incorporated high-erucic rapeseed breeding program yields, wind turbine OEM specification adoption curves, and metathesis chemistry convergence timelines for novel surfactant architectures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA regulatory expansion, prairie weather pattern shifts, and polyalphaolefin price competitiveness in industrial lubricants. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Multichannel Reagent Reservoir Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Silicone Derivative Market
Specialty Chemicals
Barium Derivatives Market
Specialty Chemicals
Global Immersion Oil Market
Specialty Chemicals
Ursolic Acid Market
Specialty Chemicals
Taurine Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market
Specialty Chemicals
Fixing Agent Market
Specialty Chemicals
Thermolysin Market
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
Biocides Market
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
LAMEA Metal Biocides Market