
 Alkoxide Market | 2026-2036
Alkoxide Market Size, Share, and Industry Trends Forecast 2026-2036
Alkoxide Market Analysis
Specialty chemical distribution networks are reconfiguring as regional alkoxide suppliers consolidate warehousing and technical service capabilities closer to pharmaceutical and agrochemical clusters. Evonik Industries AG leverages its integrated organometallic platform to sustain captive supply advantages across European catalyst markets. Albemarle Corporation anchors lithium alkoxide production through upstream control over brine-derived lithium feedstocks. BASF SE competes on formulation breadth, extending technical alkoxide blends to research laboratories with just-in-time delivery protocols.
Alkoxides are metal-organic compounds formed by the reaction of alcohols with alkali or alkaline earth metals, typically characterized by their air-sensitive nature and solubility in polar organic solvents; they function primarily as strong bases, nucleophiles, and precursors in organic synthesis and polymerization catalysis. Sodium alkoxide dominates volume consumption in biodiesel transesterification, where its cost-performance ratio supports continuous-flow reactor designs at industrial scale. Lithium alkoxide occupies premium pricing tiers in pharmaceutical applications, where ultra-low moisture specifications and batch traceability command margin pools exceeding standard catalyst grades. Powder and granule forms are gaining share in automated chemical manufacturing environments, displacing liquid deliveries that require specialized handling infrastructure and nitrogen-blanketed transport.
EPA regulations under the Toxic Substances Control Act constrain per-batch impurity thresholds for alkoxides entering U.S. catalyst supply chains, while REACH registration in Europe mandates full substance dossiers for sodium and potassium alkoxide imports above one-tonne annual volumes. China's SAMR enforces GB standard compliance for domestically produced alkoxides used in agrochemical intermediates, creating divergent testing burdens for multinational suppliers. Stakeholders must monitor regulatory harmonization negotiations between OECD member states and assess whether to standardize formulations across jurisdictions or maintain region-specific product lines.
Market Dynamics
Pharmaceutical manufacturers are consolidating alkoxide procurement contracts around single-source suppliers capable of delivering batch-traceable, ultra-low-moisture grades, compressing the vendor base and elevating technical service requirements above commodity pricing.
Growth Catalysts
- Biodiesel transesterification mandates:China's SAMR enforcement of GB standard compliance for domestically produced sodium alkoxides is accelerating capacity expansion by domestic chemical manufacturers serving fuel additive supply chains.
- REACH registration thresholds:ECHA's one-tonne annual volume dossier requirement for sodium and potassium alkoxide imports is filtering out low-volume traders and concentrating import volumes among compliant distributors.
- Continuous-flow reactor designs:Automated chemical manufacturing environments are displacing liquid alkoxide deliveries with powder and granule forms that integrate directly into nitrogen-blanketed handling systems.
Market Restraints
- Brine-derived lithium feedstock concentration:Upstream control over South American lithium deposits by integrated chemical producers limits independent access to battery-grade lithium alkoxide precursors.
- EPA per-batch impurity thresholds:Toxic Substances Control Act constraints on catalyst-grade alkoxides entering U.S. supply chains impose testing burdens that disproportionately affect smaller import distributors.
- Air-sensitive handling infrastructure:The capital intensity of nitrogen-blanketed transport and storage systems excludes regional distributors lacking integrated warehousing networks.
Strategic Opportunities
- Agrochemical intermediate synthesis:China's domestic scaling of sodium alkoxide capacity creates export surplus potential for Southeast Asian pesticide manufacturers seeking cost-advantaged base catalysts.
- Research laboratory just-in-time protocols:Technical alkoxide blends with customized molar ratios represent underserved demand among contract research organizations requiring sub-kilogram quantities with rapid turnaround.
- EU Green Deal chemical sustainability criteria:Renewable feedstock-derived alkoxides certified under emerging mass-balance standards command premium positioning in European pharmaceutical procurement.
Industry Challenges
- Organometallic synthesis expertise scarcity:The specialized skill set for anhydrous reaction conditions and pyrophoric material handling constrains workforce expansion at regional production facilities.
- Dual regulatory dossier maintenance:Suppliers operating across REACH-registered European formulations and EPA-compliant U.S. product lines face duplicated toxicological testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkoxide Market |
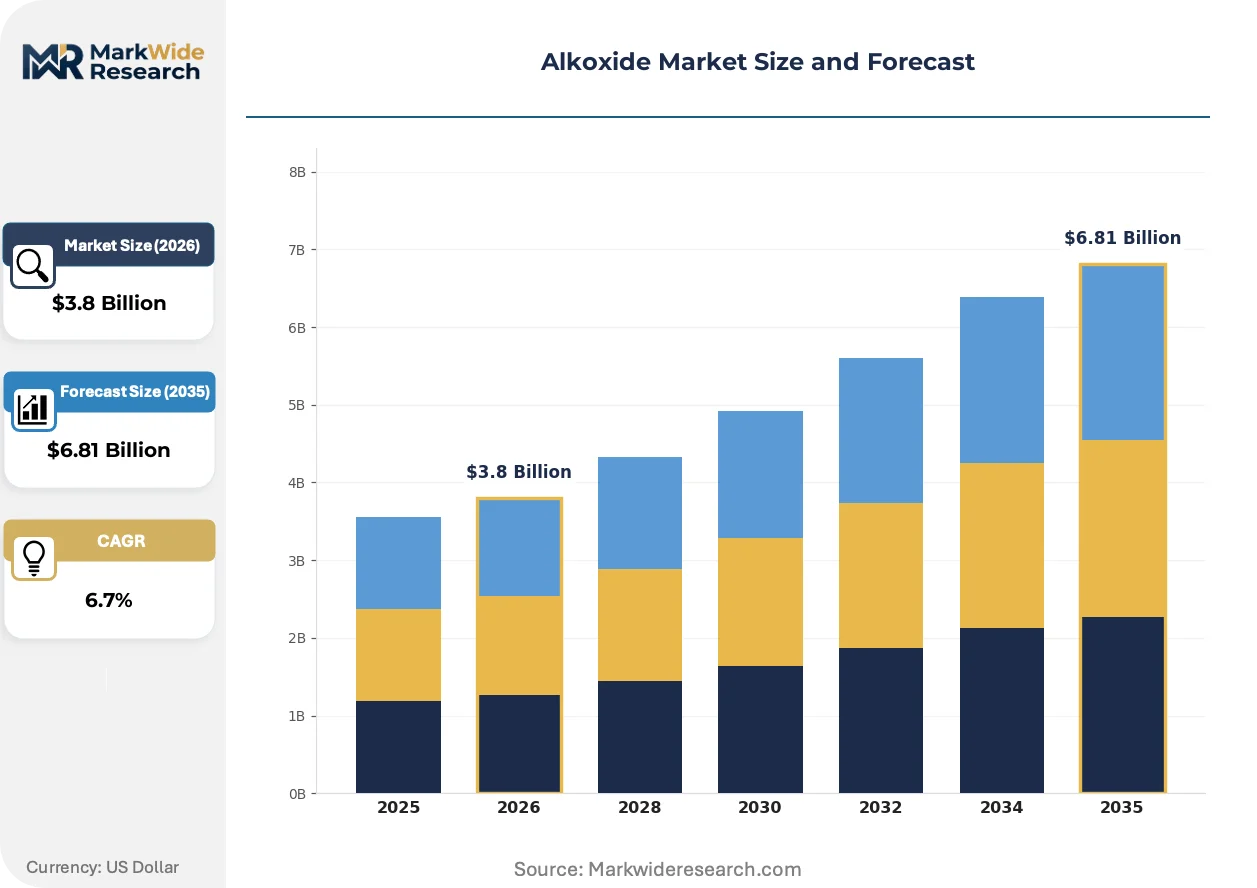
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Alkoxide, Potassium Alkoxide, Lithium Alkoxide, Calcium Alkoxide Application: Biofuels, Pharmaceuticals, Agriculture, Catalysts End User: Chemical Manufacturers, Research Laboratories, Agrochemical Companies, Pharmaceutical Firms Form: Liquid, Solid, Powder, Granule |
| Companies Covered | Evonik Industries AG, Albemarle Corporation, BASF SE, Huntsman Corporation, Sumitomo Chemical, Gelest, Chemtech Alkoxides, Solvay S.A., Tosoh Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkoxide Market Emerging Trajectories
Alkoxide production and distribution are restructuring around automated material handling, regulatory certification premiums, and consolidated procurement relationships that favor integrated suppliers over commodity traders.
Continuous-flow reactor technology is collapsing the traditional batch-processing economics of biodiesel transesterification. Sodium alkoxide producers serving European fuel additive manufacturers are retrofitting existing plants with plug-flow systems that reduce solvent volumes and improve heat transfer efficiency. This compression of unit operating costs is enabling smaller regional producers to compete with established commodity suppliers on total delivered cost rather than scale alone.
REACH substance dossier requirements are fragmenting import channels for sodium and potassium alkoxides entering European catalyst markets. ECHA's full characterization mandates for volumes exceeding one tonne annually have forced non-EU manufacturers to establish EU-based legal entities or surrender market share to registered competitors. The pharmaceutical segment is responding by consolidating procurement around distributors with established Only Representative status, effectively screening out traders lacking regulatory infrastructure.
Pharmaceutical buyers are consolidating active pharmaceutical ingredient synthesis contracts around suppliers offering integrated analytical certification. The traditional model of separate procurement for alkoxide base catalysts and third-party purity testing is yielding to bundled offerings where vendors assume batch-release liability. This concentration of vendor responsibility is most visible in U.S. generic drug manufacturing clusters, where FDA inspection readiness now factors into alkoxide supplier qualification ahead of unit price.
Alkoxide Market Segmentation
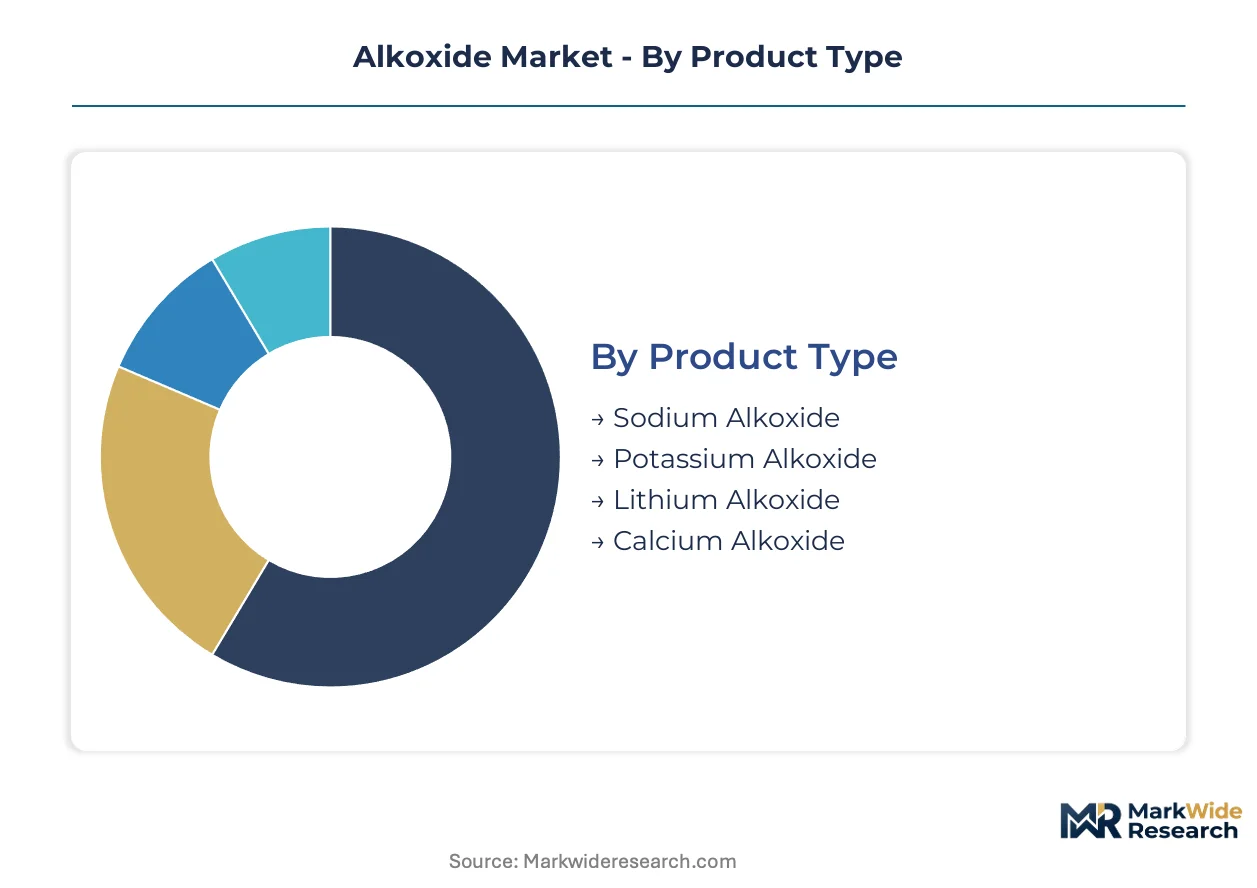
Alkoxide procurement cycles vary dramatically across product grades, with pharmaceutical lithium alkoxides turning over in weeks while industrial sodium grades rotate monthly. Understanding these velocity differentials enables inventory positioning and working capital optimization across the value chain.
Product Type:
Sodium alkoxides rotate fastest through biodiesel transesterification channels, whereas lithium alkoxides sit in pharmaceutical safety stocks for extended qualification periods.
- Sodium Alkoxide:Manufactured from sodium metal and alcohols under anhydrous conditions, this base catalyst dominates continuous-flow reactor designs for fatty acid methyl ester production. Chinese chemical manufacturers are scaling domestic capacity to serve fuel additive supply chains under SAMR-enforced GB standards.
- Lithium Alkoxide:Derived from brine-extracted lithium carbonate and requiring sub-ppm moisture specifications, this premium-grade material anchors active pharmaceutical ingredient synthesis. Ultra-low moisture certification and batch traceability command margin pools exceeding standard catalyst grades in U.S. generic drug manufacturing clusters.
- Potassium Alkoxide:Stronger base strength than sodium analogs supports specialized condensation reactions in agrochemical intermediate synthesis.
- Calcium Alkoxide:Lower solubility profile limits application breadth primarily to polymerization initiators and niche drying agents.
Sodium alkoxide dominates installed base. Lithium alkoxide is where expansion concentrates.
Application:
Margin structures diverge sharply across applications, with pharmaceutical synthesis capturing value through certification premiums while biofuels compete on delivered cost per catalytic turnover.
- Biofuels:Biodiesel transesterification consumes sodium alkoxide in stoichiometric quantities, with process economics hinging on catalyst recovery rates and methanol recycle efficiency. China's enforcement of blending mandates is accelerating capacity absorption at domestic chemical manufacturers.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis demands lithium alkoxides with documented impurity profiles for FDA inspection readiness. Procurement consolidation around single-source suppliers capable of assuming batch-release liability is compressing the vendor base.
- Agriculture:Pesticide intermediate production leverages potassium alkoxide base strength for carbon-carbon bond formation in herbicide synthesis.
- Catalysts:Polymerization initiation and olefin metathesis applications require precise molar ratios achievable through custom-blended alkoxide formulations.
Biofuels anchor volume throughput. Pharmaceuticals capture value expansion.
End User:
Procurement sophistication separates end-user tiers, with pharmaceutical firms demanding integrated analytical certification while chemical manufacturers optimize for total delivered cost.
- Chemical Manufacturers:Integrated producers with captive organometallic synthesis capabilities leverage backward integration into sodium alkoxide production for biodiesel catalyst supply.
- Research Laboratories:Contract research organizations drive demand for sub-kilogram quantities of customized molar ratio blends with rapid turnaround protocols.
- Agrochemical Companies:Southeast Asian pesticide manufacturers seek cost-advantaged base catalysts from Chinese export surplus capacity.
- Pharmaceutical Firms:Generic drug manufacturers in U.S. clusters qualify suppliers on FDA inspection readiness ahead of unit price, consolidating contracts around batch-traceable, ultra-low-moisture grades.
Chemical manufacturers dominate installed base. Pharmaceutical firms concentrate procurement consolidation.
Form:
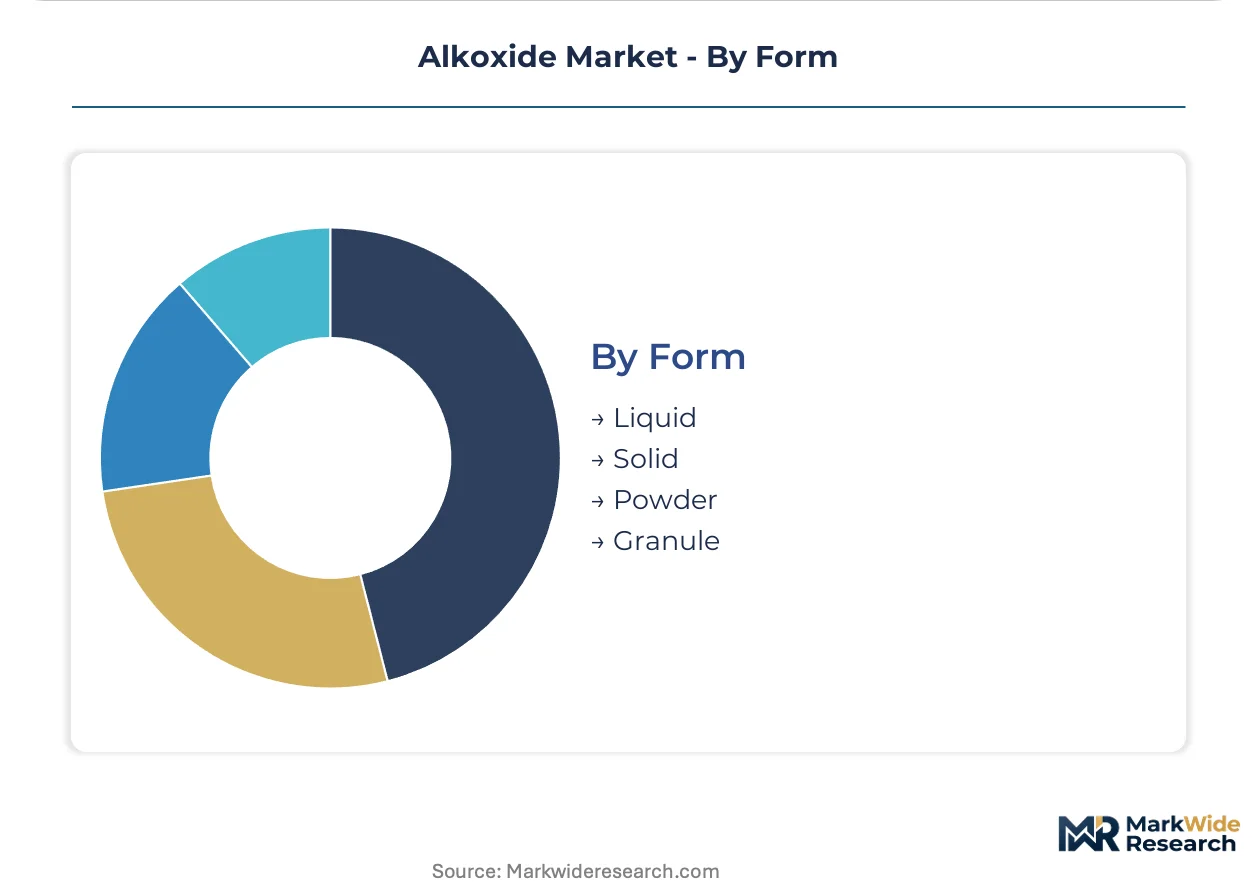
Physical form selection determines handling infrastructure requirements, with automated manufacturing environments driving format conversion across end-user segments.
- Liquid:Traditional delivery format requiring nitrogen-blanketed transport and specialized storage infrastructure excludes regional distributors lacking integrated warehousing networks.
- Solid:Block or flake forms reduce shipping volumes but require mechanical processing at point of use.
- Powder:Fine particulate grades integrate directly into automated chemical manufacturing environments with nitrogen-blanketed handling systems, displacing liquid deliveries in continuous-flow reactor retrofits.
- Granule:Free-flowing granular forms optimize for precision dosing equipment in pharmaceutical tablet production and agrochemical formulation lines.
Liquid forms dominate legacy installed base. Powder and granule formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals anchor European alkoxide import flows, while China's Yangtze River Delta chemical corridor concentrates sodium alkoxide capacity expansion. Rail links connecting the US Gulf Coast petrochemical complex to Midwest biodiesel producers underpin North American distribution economics.
China
Domestic chemical manufacturers are scaling sodium alkoxide output for biodiesel transesterification under SAMR-enforced GB standards. The MIIT's dual carbon goals are accelerating fuel blending mandates that absorb new capacity. Yangtze River Delta producers in Jiangsu and Zhejiang provinces are retrofitting continuous-flow reactor systems to capture export surplus opportunities.
United States
Generic drug manufacturers in New Jersey and Pennsylvania clusters are consolidating lithium alkoxide procurement around batch-traceable suppliers. EPA per-batch impurity thresholds under the Toxic Substances Control Act are filtering smaller import distributors from catalyst supply chains. Gulf Coast petrochemical complexes leverage nitrogen-blanketed rail corridors to serve Midwest biodiesel producers.
Germany
REACH-registered distributors with Only Representative status are capturing pharmaceutical alkoxide volumes as ECHA dossier requirements displace low-volume traders. The EU Green Deal's chemical sustainability criteria are creating premium positioning for renewable feedstock-certified products. BASF SE's Ludwigshafen complex anchors integrated organometallic production serving European catalyst markets.
India
Contract research organizations in Hyderabad and Bengaluru are driving sub-kilogram demand for customized molar ratio alkoxide blends. CDSCO's tightening active pharmaceutical ingredient oversight is elevating batch-release documentation requirements. Gujarat's chemical manufacturing belt is absorbing technology transfers for sodium alkoxide production serving agrochemical intermediates.
Japan
Precision polymerization catalyst manufacturers in the Osaka-Kobe corridor source ultra-low-moisture lithium alkoxides with documented impurity profiles. METI's chemical industry rationalization policies are concentrating organometallic synthesis expertise at integrated producers. Tosoh Corporation's Nanyo complex maintains captive alkoxide production for semiconductor materials supply chains.
Alkoxide Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the alkoxide market structure. The vendor base organizes around three tiers: integrated chemical conglomerates with captive organometallic platforms, mid-scale regional producers serving fuel additive supply chains, and specialty distributors with regulatory certification infrastructure. Strategic moves concentrate on backward integration into lithium brine feedstocks and geographic expansion of nitrogen-blanketed warehousing networks.
Within the integrated chemical conglomerate tier, Evonik Industries AG and BASF SE exemplify platform players with diversified organometallic portfolios. Albemarle Corporation anchors the upstream-controlled segment through brine-derived lithium positioning. Among Japanese producers, Tosoh Corporation and Sumitomo Chemical occupy positions in precision catalyst supply chains serving semiconductor and pharmaceutical end-uses. These named entities represent archetypal competitive positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Albemarle Corporation |
| BASF SE |
| Huntsman Corporation |
| Sumitomo Chemical |
| Gelest |
| Chemtech Alkoxides |
| Solvay S.A. |
| Tosoh Corporation |
| Others |
Supply Flow & Price Mechanics
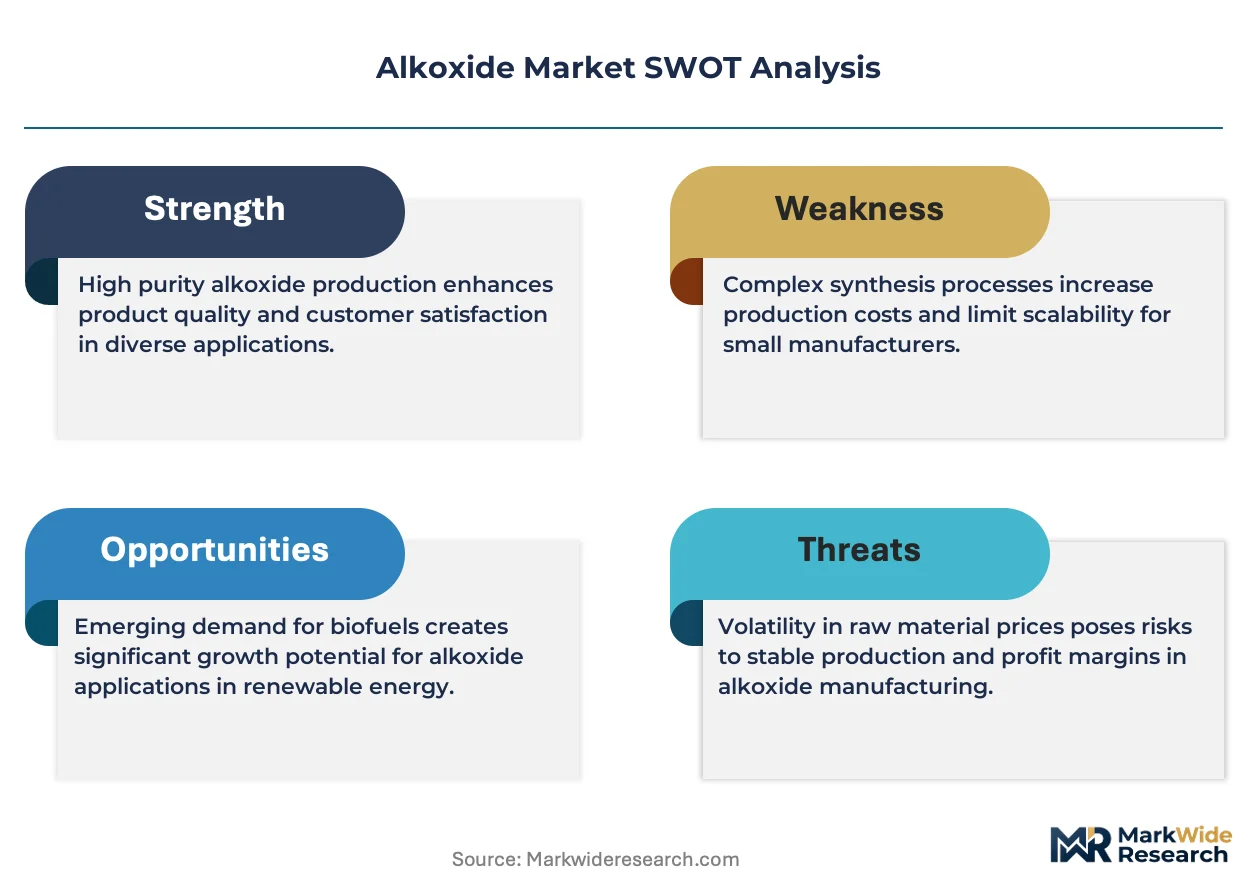
Undercapacity in European lithium alkoxide production is driving suppliers toward premium pricing postures while Chinese sodium alkoxide overcapacity compresses margins in fuel additive channels. This divergence in utilization rates shapes procurement consolidation patterns and regional sourcing strategies across pharmaceutical and biodiesel end-uses.
Pricing Analysis
Volume-discount tiering structures stratify across pharmaceutical certification grades, industrial catalyst specifications, and research laboratory sub-kilogram quantities. Pharmaceutical buyers absorb premium-mid-economy pricing differentiation based on batch traceability and ultra-low moisture certification under FDA inspection protocols. Cost compression in industrial sodium grades intensifies because Chinese domestic capacity expansion outpaces biodiesel blending mandate absorption. Chemical manufacturers exhibit highest price sensitivity, while pharmaceutical firms prioritize batch-release liability transfer over unit cost.
Supply Chain Analysis
Extended payment terms from integrated lithium producers are squeezing regional distributors lacking balance-sheet depth to finance inventory carry. Supply concentrates in China, Germany, and the United States, with brine-derived lithium carbonate from South America feeding pharmaceutical-grade production. The alkoxide supply chain rests on sodium metal, alcohol feedstocks, and nitrogen-blanketed handling infrastructure. Single-source vulnerability around South American lithium deposits exposes European and Asian pharmaceutical manufacturers to supply interruption. Distribution runs through specialty chemical distributors with REACH Only Representative status and nitrogen-blanketed warehousing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and regulatory certification packages are expanding faster than commodity alkoxide volumes, creating attach-rate opportunities for suppliers capable of assuming batch-release liability. This service layer commands recurring revenue streams that outpace hardware-like product sales.
For Market Incumbents: Insulate pharmaceutical market share by deepening backward integration into brine-derived lithium feedstocks and expanding nitrogen-blanketed warehousing networks near New Jersey and Pennsylvania generic drug clusters. Threats from Chinese sodium alkoxide export surplus capacity require defensive positioning through REACH and EPA certification infrastructure that commodity traders cannot replicate. Capacity addition in Jiangsu province serves biodiesel channel defense.
For New Entrants and Emerging Players: Establish a beachhead in contract research organization sub-kilogram supply by offering customized molar ratio blends with rapid turnaround protocols. Southeast Asian agrochemical intermediate synthesis represents the most penetrable geography, with pesticide manufacturers seeking cost-advantaged potassium alkoxide alternatives to Chinese sodium surplus. A technical service-led go-to-market angle bypasses incumbent scale advantages in bulk commodity channels.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because REACH dossier requirements and EPA per-batch testing create durable moats around compliant distributors. Acquisition targets should display integrated organometallic synthesis capabilities and established Only Representative status in Europe. The signal to watch is consolidation of pharmaceutical procurement contracts around single-source suppliers capable of batch-traceable, ultra-low-moisture delivery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Feedstocks | Upstream control over South American brine deposits secures pharmaceutical-grade precursor supply against export restrictions. |
| Nitrogen-Blanketed Warehousing Expansion | Regional distribution nodes near Rotterdam and Houston capture pharmaceutical and biodiesel procurement consolidation. |
| REACH Only Representative Investment | Regulatory infrastructure filters low-volume traders and concentrates import volumes among compliant distributors. |
| Custom Molar Ratio Blend Capability | Sub-kilogram technical service offerings penetrate contract research organization demand with rapid turnaround protocols. |
| Continuous-Flow Reactor Retrofit | Plug-flow system adoption reduces solvent volumes and enables smaller producers to compete on delivered cost. |
Methodological Framework
Operator-level perspectives from plant managers at alkoxide production facilities, procurement leads at pharmaceutical generic drug manufacturers, distribution channel partners with nitrogen-blanketed warehousing networks, and technical R&D directors at catalyst formulation companies anchored the qualitative base. These primary interviews combined with customs and trade data, SEC 10-K filings from integrated chemical producers, ECHA substance dossier databases, and SAMR GB standard compliance records. Bottom-up capacity and utilization estimates triangulated against top-down demand modeling from biodiesel blending mandates and pharmaceutical API production forecasts.
Scenario-bracketing framed the projection horizon through sensitivity analysis of regulatory harmonization outcomes between REACH and EPA regimes, lithium brine supply disruption events, and continuous-flow reactor adoption curves across Chinese biodiesel producers. Segmentation dimensions modeled included alkoxide metal type, pharmaceutical versus industrial grade tier, powder versus liquid packaging format, and regional production hub concentration. CAGRs were derived from installed capacity absorption rates and procurement contract velocity differentials, with specific inputs from SAMR enforcement intensity and ECHA registration timelines.
Sensitivities concentrate around lithium carbonate supply disruptions, REACH-EPA regulatory divergence, and Chinese biodiesel mandate enforcement variability. Forecasts reflect documented assumptions regarding capacity expansion schedules and procurement consolidation patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
VCI Aerosol Market
Specialty Chemicals
Global Acrylic Processing Aid Market
Specialty Chemicals
Monomethylsilanetriol Market
Specialty Chemicals
Structure Directing Agents Market
Specialty Chemicals
Croscarmellose Sodium Market
Specialty Chemicals
Magnesium Chelates Market
Specialty Chemicals
Affinity Chromatography Reagents Market
Specialty Chemicals
Biocides Market
Specialty Chemicals
Isostearyl Alcohol Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Fabric Antibacterial Spray Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
Sol-Gel Processing Market