
 Arginine Market | 2026-2036
Arginine Market Size, Share, and Industry Trends Forecast 2026-2036
Arginine Market Intelligence
Production of pharmaceutical-grade L-Arginine is reshaping the market's margin structure, pulling profitability away from lower-purity feed and food grades. Ajinomoto Co Inc leverages its extensive fermentation technology and global distribution network to serve multiple quality tiers. Evonik Industries AG specializes in high-purity amino acids for pharmaceutical and medical nutrition applications, commanding premium pricing. Meanwhile, Daesang Corporation competes on scale and process efficiency, primarily targeting the food supplement and animal nutrition segments.
Arginine is a semi-essential amino acid that serves as a crucial precursor for the synthesis of nitric oxide, a key molecule for vasodilation. It is primarily produced through microbial fermentation processes that ensure high purity and yield. Its main commercial function is to support cardiovascular health and improve athletic performance. Within applications, dietary supplements and sports nutrition constitute the largest segments. While L-Arginine Base remains the most common product type, specialized forms like L-Arginine Alpha-Ketoglutarate are gaining traction in performance-focused formulations.
The regulatory environment is defined by stringent guidelines for product quality and labeling. In the United States, the FDA oversees arginine sold as dietary supplements under the Dietary Supplement Health and Education Act. In Europe, the European Food Safety Authority (EFSA) evaluates health claims associated with arginine consumption. These regulations dictate purity standards and permissible marketing language. Manufacturers must therefore align their production and documentation with disparate international standards to access key pharmaceutical and nutraceutical markets effectively.
Market Dynamics
The market's central dynamic is a value chain bifurcation driven by purity standards. A distinct and more profitable pharmaceutical-grade segment is separating from the traditional, volume-focused feed and food-grade markets, altering margin structures for all producers.
Growth Catalysts
- Sports Nutrition Expansion:The growing inclusion of arginine in pre-workout and athletic performance supplements, driven by consumer demand for products supporting vasodilation and muscle recovery, is a primary catalyst.
- Stringent Quality Mandates:Regulations from the FDA and EFSA requiring higher purity for dietary supplements create a premium market for manufacturers capable of meeting pharmaceutical-grade specifications.
- Medical Nutrition Applications:Increased use of arginine in clinical nutrition for wound healing, immune support, and managing cardiovascular conditions provides a stable, high-value demand stream outside of consumer wellness.
Market Restraints
- Input Cost Volatility:Production via microbial fermentation is sensitive to price fluctuations in agricultural feedstocks like corn or sugar beets, which can compress manufacturer margins unexpectedly.
- Supply Chain Concentration:Heavy reliance on production facilities in China for both raw and finished arginine creates significant geopolitical and logistical risks for the global supply chain.
- Substitution Threat:In sports nutrition, L-Citrulline is a direct competitor that is perceived by some formulators to offer more stable nitric oxide production, posing a substitution risk.
Strategic Opportunities
- Geographic Market Development:There is an opportunity to cultivate demand in emerging dietary supplement markets like Brazil and India, where a growing middle class shows increased interest in health and wellness products.
- Novel Delivery Systems:Developing advanced formulations such as sustained-release capsules or more bioavailable liquid forms can create product differentiation and command premium pricing in a crowded market.
- Plant-Based Fermentation:Leveraging non-GMO and plant-based fermentation media appeals to consumer demand for clean-label and vegan-certified dietary supplements, opening a new market niche.
Industry Challenges
- Regulatory Compliance Burden:Manufacturers face the operational challenge of aligning production, testing, and documentation with disparate quality and labeling standards across the US, Europe, and Asia to access all key markets.
- Capital-Intensive Scaling:Expanding production capacity for high-purity, pharmaceutical-grade arginine requires significant capital investment in advanced bioreactors, filtration systems, and cleanroom facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arginine Market |
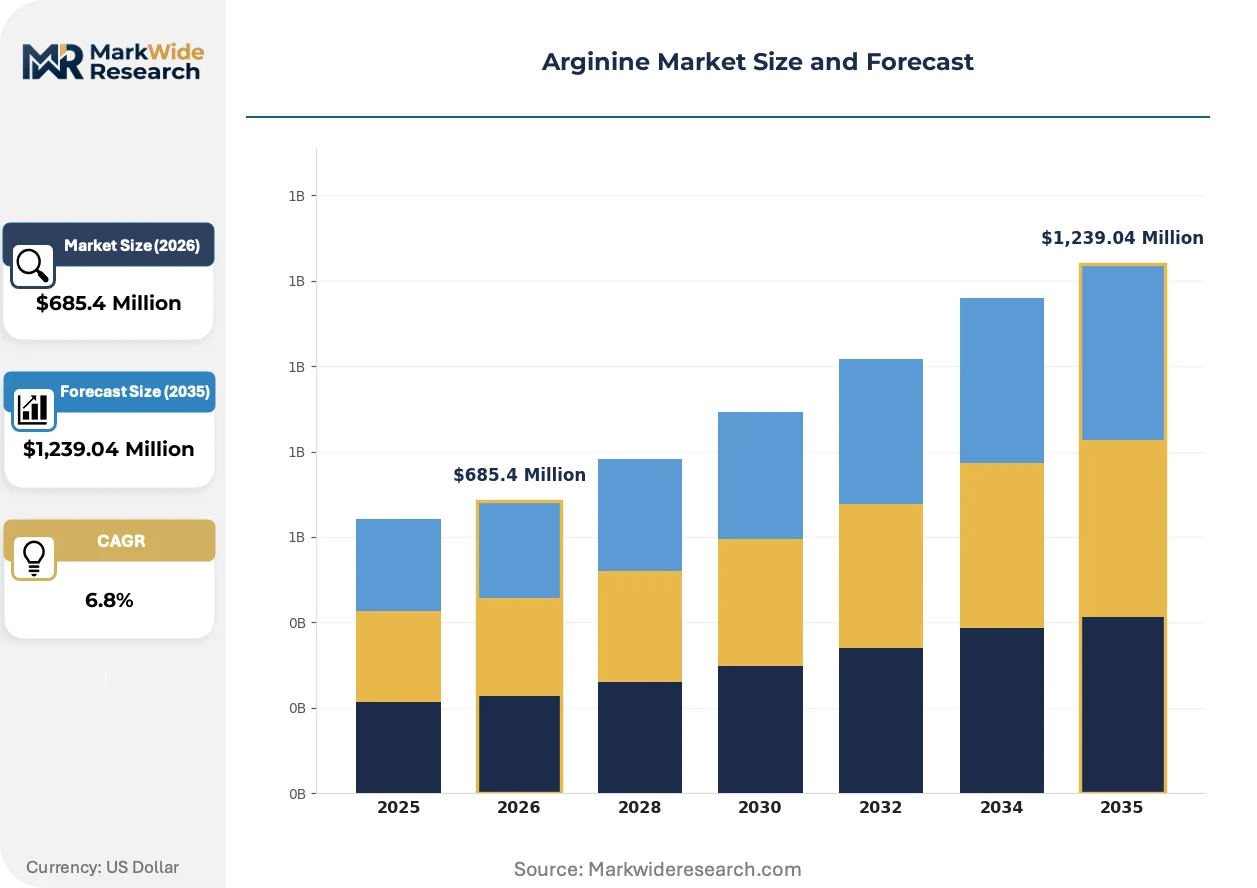
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Arginine Base, L-Arginine Hydrochloride, L-Arginine Alpha-Ketoglutarate, L-Arginine Ethyl Ester, L-Arginine Pyroglutamate Application: Dietary Supplements, Sports Nutrition, Pharmaceuticals, Cosmetics, Animal Nutrition End User: Sports Nutrition Manufacturers, Pharmaceutical Companies, Personal Care Producers, Animal Feed Producers Form: Powder, Tablet, Capsule, Liquid, Granules |
| Companies Covered | Ajinomoto Co Inc, Evonik Industries AG, Daesang Corporation, CJ CheilJedang Corp, DSM Nutritional Products AG, Kyowa Hakko Bio Co Ltd, Jingjing Pharmaceutical Co Ltd, Wuxi Jinghai Amino Acid Co Ltd, Shijiazhuang Jirong Pharmaceutical Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arginine Market Strategic Shifts & Innovations
The arginine market is evolving from a commodity ingredient business into a specialized, science-driven sector. This transition is defined by advancements in production technology and a demand-side pull for application-specific, high-purity products with validated efficacy claims.
Precision fermentation, which utilizes genetically optimized microbial strains, allows for targeted production of L-Arginine with consistently high yields and purity. Pharmaceutical and leading nutraceutical companies are adopting this technology to secure a supply chain that meets stringent quality standards. This advanced biomanufacturing capability is rendering obsolete older, less efficient chemical synthesis pathways and crude extraction methods that result in lower-purity grades.
The European Food Safety Authority's (EFSA) rigorous scrutiny of health claims associated with food supplements is a significant regulatory trend. This forces manufacturers to substantiate marketing claims, such as cardiovascular benefits, with robust scientific and clinical data. The dietary supplement segment is most affected, prompting a strategic pivot toward evidence-based product development and greater transparency in consumer-facing communication.
A notable behavioral change is the shift toward formulation-specific ingredient sourcing, particularly within the sports nutrition vertical. Brand owners are increasingly demanding specialized forms like L-Arginine Alpha-Ketoglutarate (AAKG) for pre-workout blends, disrupting the traditional model of purchasing bulk L-Arginine Base. This trend is most prominent in North American and European markets where product differentiation is a critical component of competitive positioning.
Arginine Market Segmentation
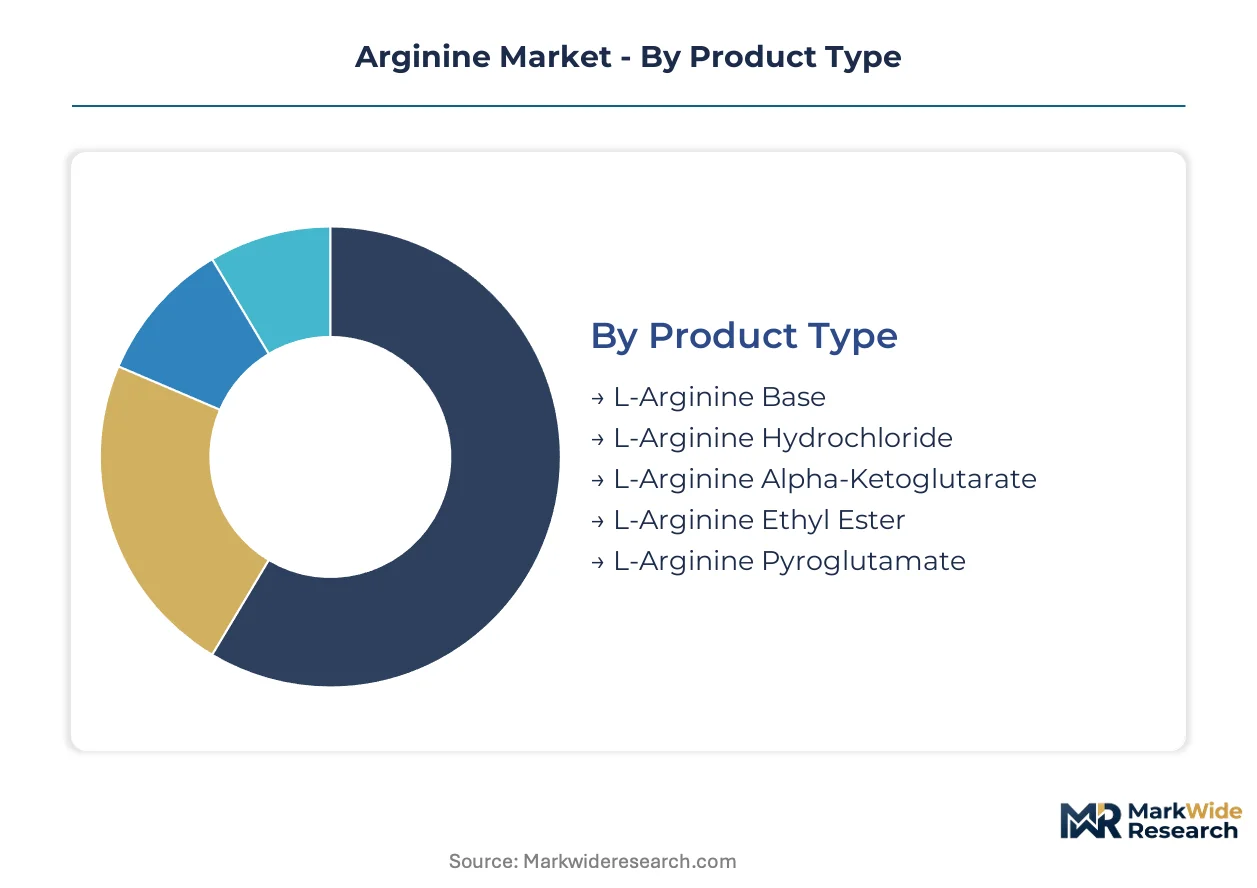
The Arginine market's structure is defined by diverse product forms, applications, and end-user requirements. Understanding these segments reveals the underlying demand drivers and value migration patterns. Each category reflects distinct manufacturing complexities and consumer needs.
Product Type:
The chemical composition of arginine products dictates their functional properties and market value.
- L-Arginine Base:This is the foundational, most common form of arginine, typically produced through microbial fermentation. Demand concentrates in bulk dietary supplements and animal feed additives across China, driven by cost-efficiency and broad application.
- L-Arginine Alpha-Ketoglutarate:AAKG combines L-Arginine with alpha-ketoglutarate, enhancing bioavailability and cellular energy metabolism. Its demand is increasing in performance-focused pre-workout formulations in North American and European sports nutrition markets, driven by product differentiation.
- L-Arginine Hydrochloride:This salt form offers improved solubility and stability, often used in pharmaceutical preparations and specific dietary supplements.
- L-Arginine Ethyl Ester:Known for enhanced absorption, this ester form targets specialized nutraceutical applications requiring higher bioavailability.
- L-Arginine Pyroglutamate:This form combines L-arginine with pyroglutamic acid, focusing on cognitive support and growth hormone release formulations.
L-Arginine Base commands the established base. The steepest expansion runs through L-Arginine Alpha-Ketoglutarate.
Application:
Specific end-use applications shape the market for arginine, influencing purity requirements and formulation complexity.
- Dietary Supplements:This segment encompasses a broad range of health-promoting products where arginine supports cardiovascular health and general wellness. Demand is strong in the United States and Germany, driven by an aging population seeking preventative health solutions.
- Sports Nutrition:Arginine is a staple in pre-workout and muscle recovery formulations, leveraging its role in nitric oxide synthesis for athletic performance. This application sees significant demand in the United Kingdom and Australia, propelled by active lifestyle trends.
- Pharmaceuticals:This segment utilizes high-purity arginine for clinical nutrition, wound healing, and cardiovascular therapies, subject to stringent regulatory standards.
- Cosmetics:Arginine finds use in skincare and haircare products for its moisturizing and conditioning properties, appealing to the personal care industry.
- Animal Nutrition:Incorporated into animal feed, arginine supports growth, immune function, and reproductive health in livestock, particularly in Brazil and India.
Dietary Supplements holds the largest share of consumption. Sports Nutrition is gaining momentum with product innovation.
End User:
The primary customer types for arginine reflect its diverse utility across industries.
- Sports Nutrition Manufacturers:These entities integrate arginine into their performance-enhancing product lines, focusing on blends for pre-workout energy and post-exercise recovery. Their procurement prioritizes specialized forms and consistent supply for global distribution.
- Pharmaceutical Companies:These firms require ultra-high purity arginine for therapeutic applications, including injectables and medical nutrition formulations. Their sourcing demands rigorous quality control and compliance with international pharmacopeial standards.
- Personal Care Producers:These manufacturers incorporate arginine into cosmetic and dermatological products, valuing its skin and hair conditioning attributes.
- Animal Feed Producers:These companies utilize bulk arginine to optimize animal growth and health, focusing on cost-effectiveness and nutritional efficacy for livestock.
Sports Nutrition Manufacturers represent a significant and evolving buyer segment. Pharmaceutical Companies drive demand for premium-grade arginine.
Form:
The physical presentation of arginine determines its ease of integration into various product formulations.
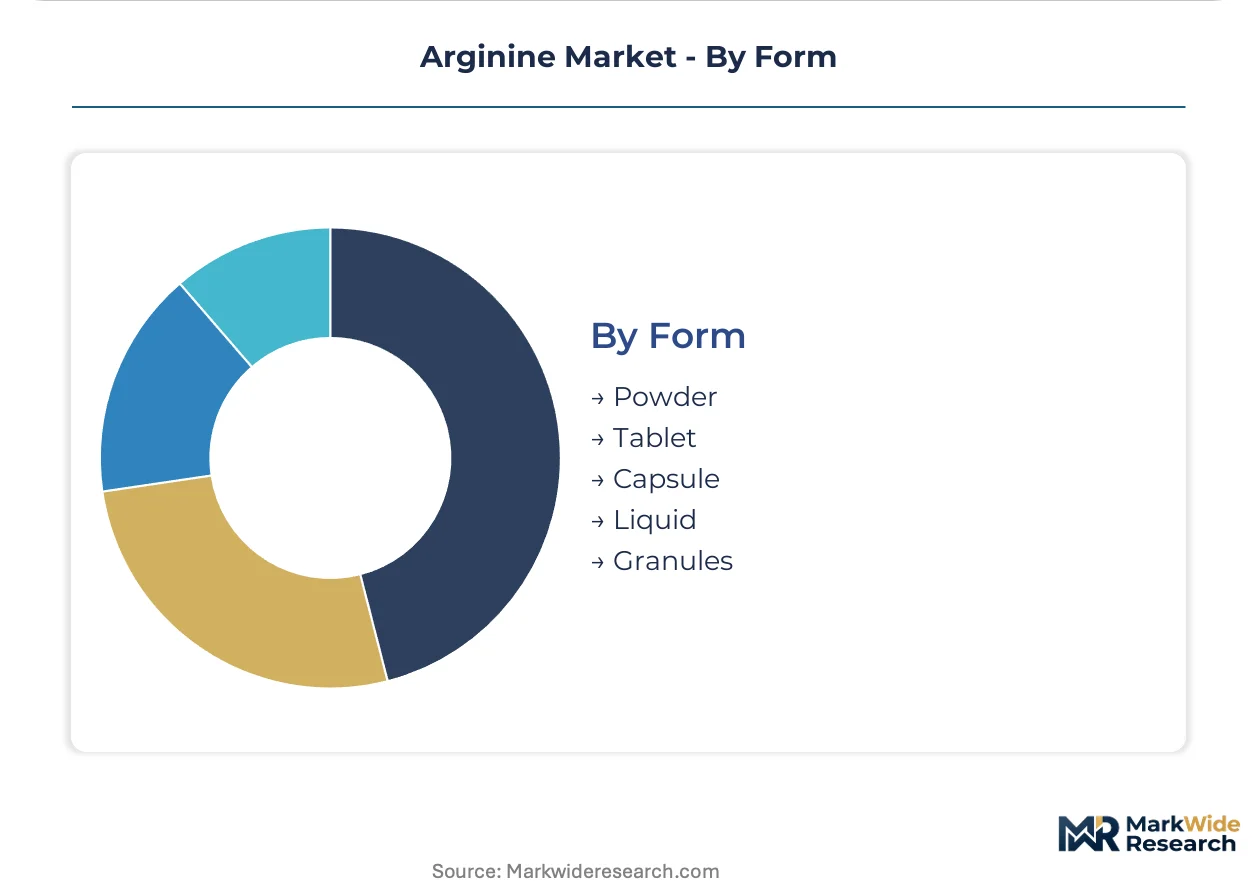
- Powder:This is the most versatile and cost-effective form, widely used in bulk supplements, pre-workout mixes, and animal feed. Demand for powdered arginine is substantial in China and the United States for its flexibility in blending.
- Capsule:Encapsulated arginine provides precise dosing and ease of consumption for consumers, particularly in dietary supplement and pharmaceutical markets. This form is popular in Japan and Canada, favored for convenience and taste masking.
- Tablet:Tablets offer a solid, stable dosage form, preferred for controlled release and specific pharmaceutical or nutraceutical applications.
- Liquid:Liquid arginine provides rapid absorption and is used in ready-to-drink formulations, especially in sports nutrition and medical beverages.
- Granules:Granular forms improve flowability and reduce dusting, making them suitable for direct compression and blending in certain manufacturing processes.
Powdered arginine maintains its dominant market presence. Capsules are experiencing steady uptake due to consumer preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global arginine market exhibits distinct consumption patterns, with China heavily utilizing L-Arginine Base for bulk dietary supplements and animal feed, while North American and European markets prioritize specialized forms like L-Arginine Alpha-Ketoglutarate for performance-focused sports nutrition. This geographic segmentation reflects varying demands for cost-efficiency versus product differentiation and validated efficacy. Pharmaceutical-grade arginine demand also varies regionally based on healthcare infrastructure and regulatory maturity.
China
Demand for L-Arginine Base in China is driven by its extensive use in animal feed and cost-effective dietary supplements. The country's GB standards regulate the purity and safety of food and feed additives containing arginine. Major production hubs in Shandong and Jiangsu provinces demonstrate high-volume manufacturing capabilities for various arginine grades.
United States
The United States market sees strong demand for arginine in dietary supplements and medical nutrition, supported by consumer health awareness. The FDA oversees arginine products as dietary supplements under the Dietary Supplement Health and Education Act. California and New York serve as significant centers for nutraceutical product development and distribution.
Germany
Germany represents a key European market for high-purity arginine, particularly in pharmaceutical and medical nutrition applications. The European Food Safety Authority (EFSA) evaluates health claims, influencing product development and marketing for arginine-containing supplements. The Rhine-Main region hosts numerous pharmaceutical and specialty chemical companies with advanced production capabilities.
United Kingdom
Sports nutrition drives significant arginine consumption in the United Kingdom, where active lifestyle trends fuel demand for pre-workout and muscle recovery formulations. UK Food Standards Agency (FSA) guidelines ensure the safety and appropriate labeling of sports supplements. London and Manchester are central to the sports nutrition industry, with many brand owners and formulators.
Brazil
Brazil presents an emerging market for arginine, with growing interest in dietary supplements among an expanding middle class and continued use in animal nutrition. ANVISA, the Brazilian health regulatory agency, sets standards for food supplements and pharmaceutical ingredients. São Paulo's industrial cluster supports both domestic production and distribution of health and nutrition products.
Arginine Market Key Industry Players
Capability concentration sits with one tier, specializing in high-purity pharmaceutical-grade arginine, while scale advantage sits with another, focusing on volume-driven feed and food grades. The market exhibits a tiered structure, separating producers by their technical expertise and production scale. Archetypes include global fermentation specialists, high-purity amino acid producers, and large-scale commodity manufacturers. Companies primarily engage in capacity expansion for specialized grades and strategic partnerships to access diverse end-markets.
Global fermentation specialists like Ajinomoto Co Inc leverage extensive biotechnology platforms and global distribution networks, representing a broad spectrum of quality tiers. High-purity amino acid producers such as Evonik Industries AG exemplify the premium segment, focusing on pharmaceutical and medical nutrition applications. Daesang Corporation anchors the scale-driven end, competing on process efficiency and large-volume output for the food supplement and animal nutrition segments.
| Leading Market Players |
|---|
| Ajinomoto Co Inc |
| Evonik Industries AG |
| Daesang Corporation |
| CJ CheilJedang Corp |
| DSM Nutritional Products AG |
| Kyowa Hakko Bio Co Ltd |
| Jingjing Pharmaceutical Co Ltd |
| Wuxi Jinghai Amino Acid Co Ltd |
| Shijiazhuang Jirong Pharmaceutical Co Ltd |
| Others |
Cost & Logistics Intelligence
Commodity volatility, particularly in agricultural feedstocks, determines both pricing tier spreads and supply chain shape in the arginine market. This sensitivity directly impacts profitability for manufacturers of lower-purity grades, while pharmaceutical-grade producers maintain more stable margins.
Pricing Analysis
Long-term offtake agreements characterize pricing for high-purity pharmaceutical-grade arginine, ensuring supply stability for critical applications. Price differentiation hinges on quality grade, with pharmaceutical-grade commanding premium pricing due to stringent regulatory requirements and specialized production. Volume scale also influences pricing, favoring large-scale producers for food and feed grades. Pricing softness runs through the bulk L-Arginine Base segment, primarily due to intense competition and input cost volatility. Animal nutrition and bulk dietary supplement manufacturers exhibit the highest price sensitivity, while pharmaceutical companies prioritize consistent quality over marginal cost savings.
Supply Chain Analysis
Supply chain concentration, particularly in China, creates significant geopolitical and logistical risks for global arginine provision. China's Shandong and Jiangsu provinces serve as major production hubs, drawing from agricultural feedstocks like corn and sugar beets. This reliance on a single geographic region presents a single-source vulnerability for many global buyers. Distribution for high-purity products often leverages specialized channels through companies like Evonik, while bulk L-Arginine Base utilizes broad global networks established by players such as Ajinomoto.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a cyclical recovery phase that favors innovation-driven and quality-focused players, propelled by expanding sports nutrition and medical applications.
For Market Incumbents: Insulate core pharmaceutical-grade margins by investing in precision fermentation technology and advanced biomanufacturing facilities. Diversify production capacity outside of China to mitigate geopolitical supply chain risks, countering input cost volatility. Secure long-term contracts for specialized forms like L-Arginine Alpha-Ketoglutarate to defend against substitution threats from L-Citrulline. Strengthen global distribution networks for high-purity products to maintain competitive positioning.
For New Entrants and Emerging Players: Geographic underpenetration in emerging dietary supplement markets like Brazil and India presents significant white-space opportunities. Target the plant-based fermentation niche to appeal to consumer demand for clean-label and vegan-certified products. Develop novel delivery systems such as sustained-release capsules for product differentiation. A go-to-market angle focused on evidence-based efficacy claims, substantiated by clinical data, will resonate in premium segments.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized high-purity producers and technology developers with strong IP. Long-term viability remains robust, driven by sustained demand in medical nutrition and performance-focused sports supplements over the next decade. Acquisition targets should include companies with advanced fermentation capabilities or proprietary delivery system technologies. Increased M&A activity in biomanufacturing represents a key signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Purity Arginine | Meeting stringent regulatory requirements commands premium pricing in pharmaceutical and medical nutrition applications. |
| Long-Term Supply Agreements for Feedstocks | Stabilizing input costs mitigates margin erosion caused by agricultural commodity price volatility for manufacturers. |
| Green Manufacturing Transition to Plant-Based Fermentation | Appealing to clean-label and vegan consumer preferences opens new market niches and commands higher value. |
| Joint Ventures for Novel Delivery Systems | Enhancing bioavailability and consumer convenience differentiates products in competitive dietary supplement markets. |
| Pursue Regulatory Approval Pathways for New Applications | Unlocking high-value therapeutic uses creates stable demand streams and validates efficacy claims for arginine. |
Research Approach
Operator-level perspectives from R&D directors, procurement leads, regulatory affairs specialists, and sports nutrition formulators anchored the qualitative base of this analysis. Primary interviews were triangulated with extensive secondary validation from sources including FDA filings, EFSA reports, trade association publications, and company financial statements. This approach ensured a comprehensive understanding of market dynamics through both bottom-up and top-down data synthesis.
Scenario-bracketing framed the quantitative modeling, projecting market size and growth across the analysis window. Segmentation dimensions modeled included product type, application, end-user, form, and regional regulatory cluster. Compound annual growth rates were derived from historical trends, market drivers, and expert consensus, incorporating forecast inputs such as sports nutrition participation rates and pharmaceutical R&D spending.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new entrants or rapid substitution by alternative ingredients would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Global Fabric Softener Sheet Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Structure Directing Agents Market
Specialty Chemicals
Phenoxycycloposphazene Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Xanthene Derivatives Market
Specialty Chemicals
Global Mannosylerythritol Lipids Market
Specialty Chemicals
Hydroxypropionic Acid Market
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
Bismuth Oxychloride Market
Specialty Chemicals
Undecylenic Acid Market
Specialty Chemicals
VCI Aerosol Market
Specialty Chemicals
Polyimide Varnish Market