
 Natural Ingredient Insect Repellent Market | 2026-2036
Natural Ingredient Insect Repellent Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Ingredient Insect Repellent Market Outlook
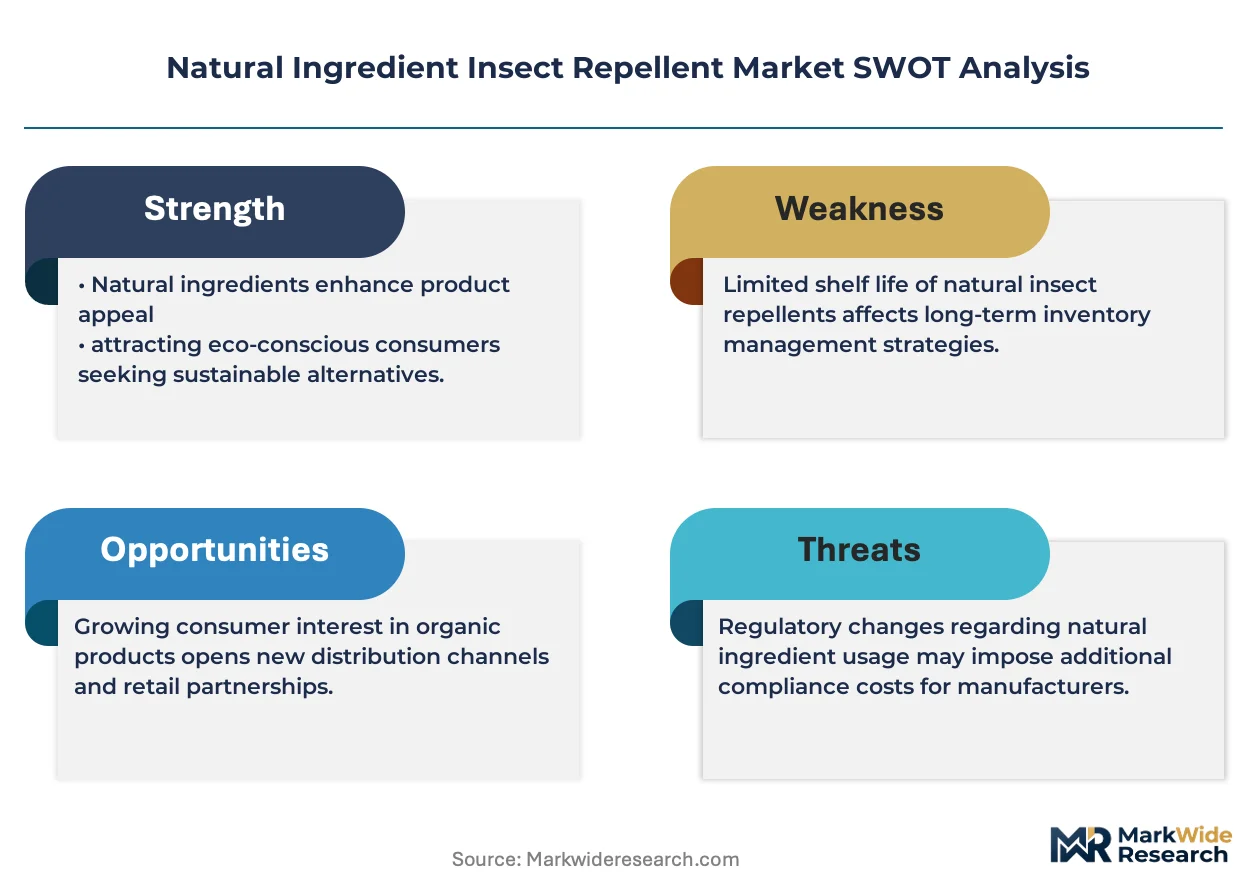
ISO 16128 certification for natural and organic cosmetic ingredients is collapsing the window for unverified market entrants. S.C. Johnson & Son leverages its established household distribution network to sustain shelf presence across mass retail channels. Godrej Consumer Products anchors its position through in-house production of neem-based actives in India. Wondercide LLC differentiates via veterinary-formulation heritage translated into human-use product lines.
Natural ingredient insect repellents are topical formulations incorporating plant-derived volatile oils such as p-menthane-3,8-diol from lemon eucalyptus or citronellal-rich fractions, designed to interfere with arthropod olfactory receptors without synthetic neurotoxicants. Sprays dominate volume due to ease of application and dose consistency, though creams command margin premiums through skin-conditioning positioning. Citronella-based formulations face structural pressure from lemon eucalyptus variants as the latter achieves broader EPA biopesticide registration acceptance.
The U.S. EPA regulates repellent efficacy claims under FIFRA, while the EU REACH framework governs botanical substance registration and hazard classification for products entering European markets. India's BIS standards for ayurvedic and herbal products create a parallel compliance pathway for neem-oil exporters. Stakeholders must monitor evolving biopesticide tolerance thresholds and regional allergen disclosure mandates to preserve market access across jurisdictions.
Market Dynamics
The EPA's tightening FIFRA biopesticide registration thresholds are compressing the competitive set for natural ingredient insect repellents, forcing formulators to invest in clinical efficacy data and toxicology dossiers that smaller entrants cannot fund.
Growth Catalysts
- DEET-free household demand:Parents and outdoor enthusiasts in the United States are rejecting synthetic neurotoxicants, creating pull-through for plant-derived actives at mass retail.
- ISO 16128 certification:The natural and organic cosmetic ingredients standard is legitimizing botanical repellents in European prestige channels, rewarding verified supply chains with shelf placement.
- Lemon eucalyptus oil:The p-menthane-3,8-diol extract is securing broader EPA biopesticide registrations, expanding the addressable market beyond citronella's limited efficacy profile.
Market Restraints
- Neem oil supply concentration:Godrej Consumer Products' captive production in India creates dependency on monsoon-dependent agricultural yields and single-origin extraction capacity.
- Clinical validation costs:EPA-mandated field trials for spatial repellency claims require six-figure investments, erecting barriers for mid-tier formulators.
- Synthetic pyrethroid price competition:Permethrin-treated clothing and gear remains cheaper per-application-hour, pressuring natural alternatives in budget-conscious segments.
Strategic Opportunities
- Veterinary-to-human crossover:Formulators with companion animal repellent heritage can leverage existing EPA registrations and toxicology packages to enter human-use markets faster.
- Ayurvedic export pathway:India's BIS standards for herbal products create a parallel compliance route for neem-based actives entering Middle Eastern and Southeast Asian markets.
- Cream and lotion formats:Skin-conditioning positioning commands margin premiums over sprays, particularly in European pharmacy and apothecary channels.
Industry Challenges
- Botanical chemist scarcity:Formulation expertise in volatile oil stabilization and encapsulation technology concentrates in fragrance houses, creating talent competition.
- Batch-to-batch variability:Natural active concentrations fluctuate with harvest conditions, complicating label claim consistency and regulatory dossier maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Ingredient Insect Repellent Market |
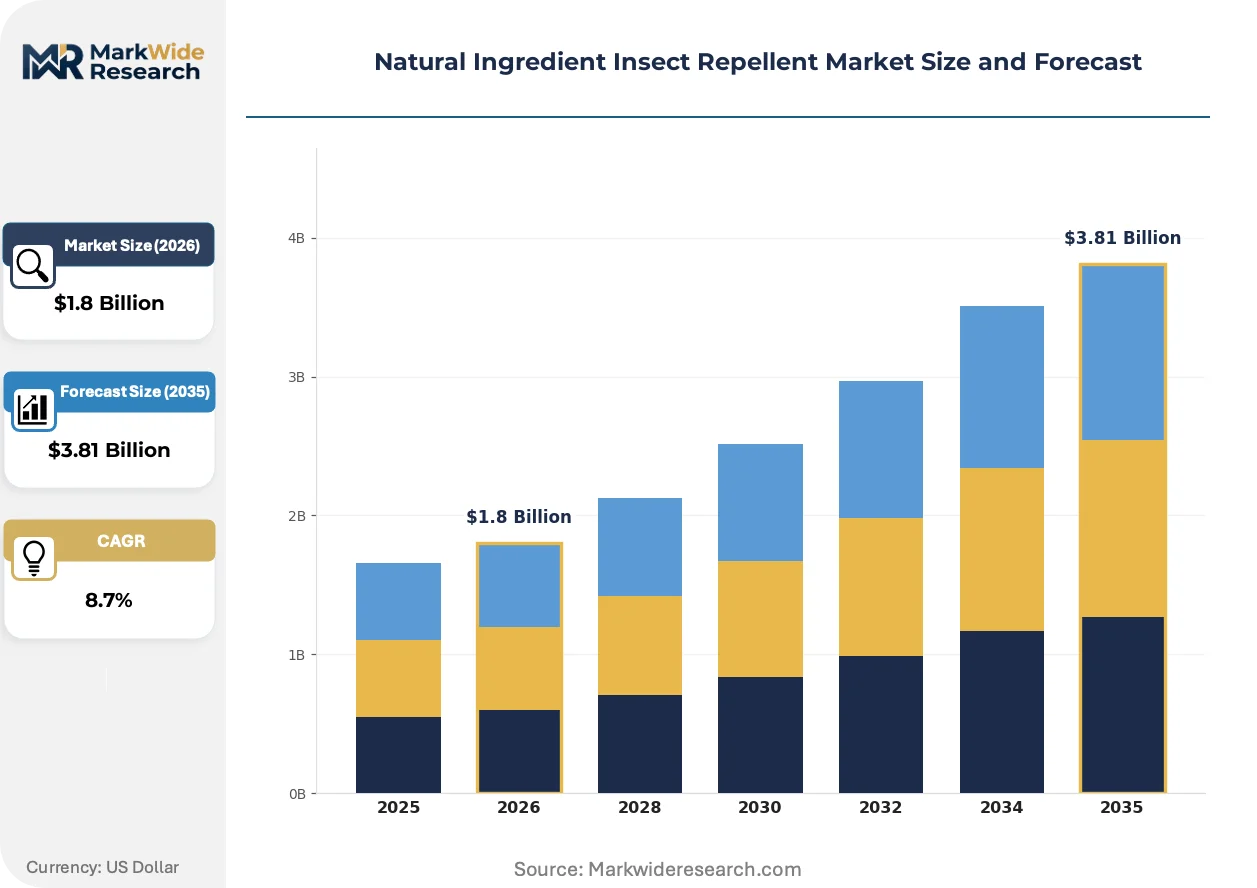
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Sprays, Roll-ons, Wipes Active Ingredient: Citronella, Lemon Eucalyptus, Neem Oil, Lavender Application: Outdoor Use, Indoor Use, Camping, Sports Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | W.S. Badger Company, Godrej Consumer Products, S.C. Johnson & Son, Earthley, Wondercide LLC, Reckitt Benckiser, Dabur International, The Procter & Gamble Company, Spectrum Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Ingredient Insect Repellent Market Strategic Shifts
Formulation science is converging with regulatory data requirements to reshape how botanical actives demonstrate efficacy and stability in commercial repellent products.
Encapsulation technology using cyclodextrin and liposome carriers is supplanting simple oil-in-water emulsions for volatile active delivery. Outdoor apparel brands and military procurement offices are specifying extended-release formulations that maintain efficacy through multiple wash cycles. This shift is compressing margins for commodity spray suppliers while rewarding specialty chemical partners with formulation IP.
REACH framework updates in Europe are reclassifying certain botanical fractions as skin sensitizers, forcing reformulators to isolate specific molecular cuts rather than using whole-plant distillates. The regulatory consequence is a bifurcation between premium single-molecule products and mass-market blends. German and French cosmetic regulators are driving the strictest interpretation, affecting exporters targeting pharmacy channels.
Certification-driven purchasing is restructuring buyer decision hierarchies in United States natural product retail. Clean beauty retailers and co-op grocers are prioritizing EWG-verified and Leaping Bunny-certified repellents over legacy brands, compressing traditional household distribution advantages. This pattern is most visible in coastal metropolitan markets where ingredient transparency ranks above price sensitivity in consumer surveys.
Natural Ingredient Insect Repellent Market Segmentation
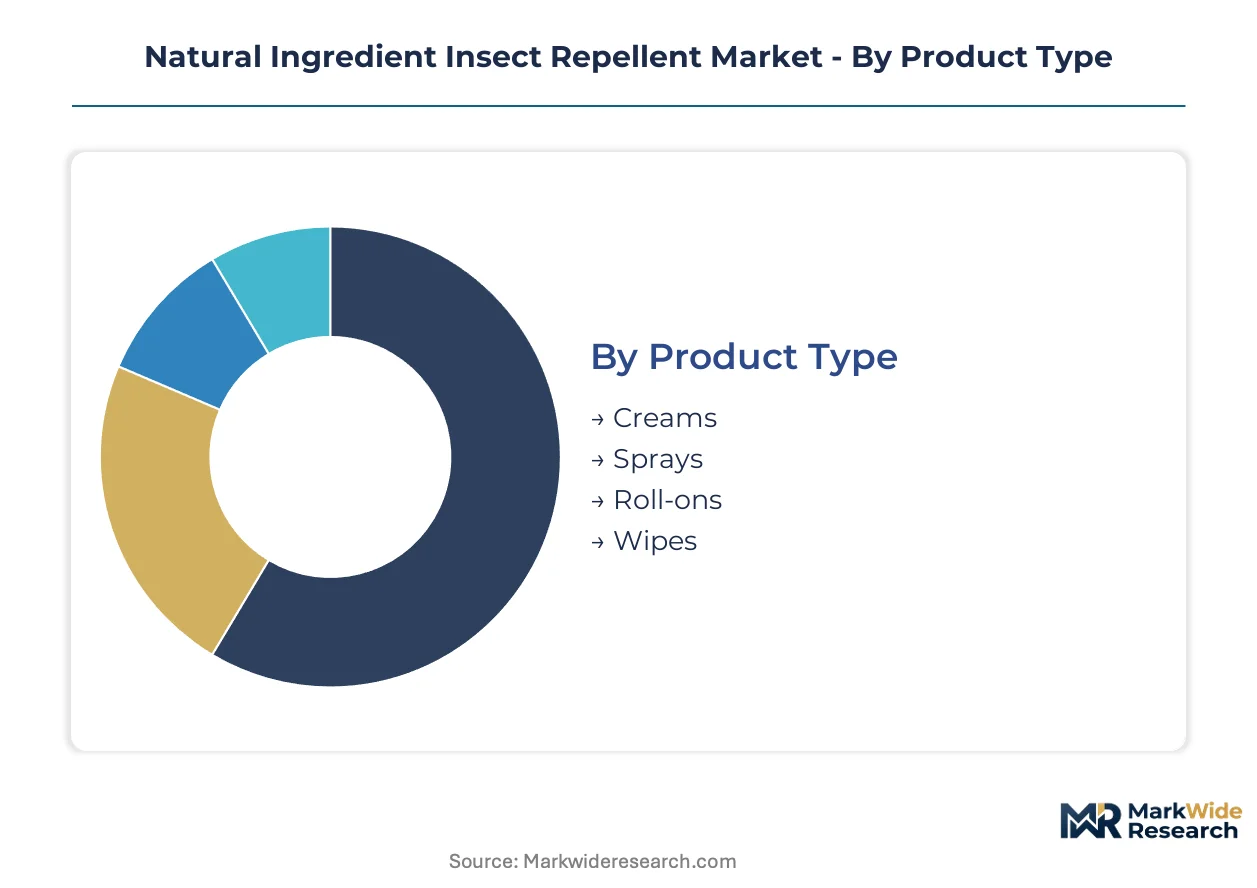
Product format and active ingredient selection determine regulatory pathway complexity and margin capture in botanical repellents. Channel access and application context further stratify competitive positioning across household, outdoor recreation, and institutional procurement segments.
Product Type:
Sprays face the most acute substitution pressure from permethrin-treated textiles and spatial repellent devices, forcing formulators to differentiate through extended-release chemistry and skin-conditioning additives.
- Creams:Oil-in-water emulsions with shea butter or aloe carriers command pharmacy channel placement through dermatological positioning. European apothecary buyers in Germany and France prioritize these formats for pediatric applications, though manufacturing complexity limits mass-market penetration.
- Sprays:Aerosol and pump-dispersed formulations dominate United States mass retail through dose consistency and rapid application. EPA biopesticide registration requirements for spray efficacy claims compress margins for smaller formulators unable to fund field trial dossiers.
- Roll-ons:Precision application format targets facial and neck areas with reduced eye irritation risk. Japanese consumers favor this format for urban commuting contexts.
- Wipes:Single-use towelettes serve airline amenity kits and military field rations with portability advantages. Shelf stability of volatile actives in moist substrates constrains formulation flexibility.
Sprays anchor the volume base while creams gain share at the steepest rate.
Active Ingredient:
Cost tier stratification separates commodity botanicals from premium single-molecule extracts with full regulatory dossiers.
- Lemon Eucalyptus:p-menthane-3,8-diol extracts achieve the broadest EPA biopesticide registration acceptance among plant-derived actives. United States outdoor retailers specify this ingredient for DEET-free product lines targeting parental purchasing decisions.
- Neem Oil:Azadirachtin-rich fractions from Indian agricultural supply chains serve ayurvedic export markets and companion animal formulations. Monsoon-dependent harvest yields create price volatility that complicates contract manufacturing agreements.
- Citronella:Cymbopogon-derived volatile oil blends face structural displacement as EPA efficacy thresholds tighten. Remains viable in candle and diffuser spatial repellent applications where topical registration requirements do not apply.
- Lavender:Lavandula angustifolia distillates occupy premium cosmetic positioning with limited standalone repellency claims. French and Bulgarian extraction capacity supports niche apothecary distribution.
Neem oil anchors the volume base while lemon eucalyptus climbs the fastest.
Application:
Customer type concentration varies sharply between institutional procurement and discretionary household purchasing.
- Outdoor Use:General yard and garden applications compete with synthetic pyrethroid perimeter treatments on cost-per-hour metrics. United States suburban households drive seasonal demand spikes.
- Indoor Use:Bedroom and living space applications favor plug-in diffuser formats over topical products. European Union REACH skin sensitizer classifications restrict whole-plant distillate concentrations.
- Camping:Backcountry multi-day trip contexts prioritize weight reduction and reapplication frequency. United States national park visitation patterns correlate with regional sales velocity.
- Sports:Marathon and trail running applications specify non-greasy, sweat-resistant formulations. Japanese and Australian endurance sports markets show format preference for gel carriers.
Outdoor use anchors the volume base while camping gains share at the steepest rate.
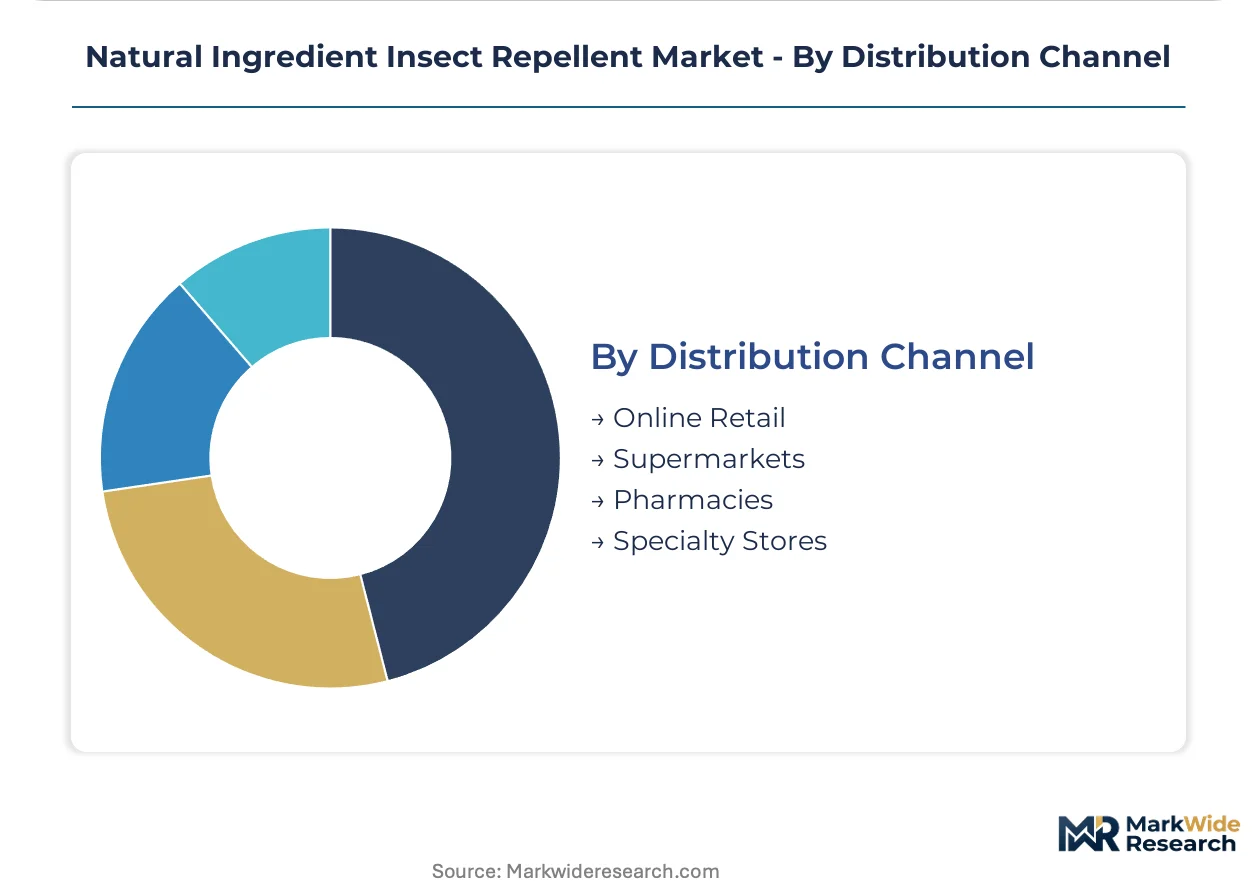
Distribution Channel:
Supply concentration in fragrance house formulation expertise shapes which channels mid-tier brands can access.
- Online Retail:Direct-to-consumer platforms enable subscription models and ingredient transparency storytelling. United States clean beauty e-commerce sites prioritize EWG-verified and Leaping Bunny-certified assortments.
- Supermarkets:Mass retail shelf placement requires slotting fees and household brand recognition that favor established CPG networks. Seasonal merchandising limits year-round SKU retention.
- Pharmacies:German and French pharmacy channels demand cosmetic-grade certification and clinical efficacy documentation. ISO 16128 compliance separates premium from commodity positioning.
- Specialty Stores:Outdoor equipment retailers and natural food co-ops curate assortments around sustainability narratives and local sourcing claims.
Supermarkets anchor the volume base while online retail expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household consumers seeking DEET-free alternatives concentrate most heavily in the United States, where outdoor recreation participation and natural product retail penetration remain highest. This buyer archetype drives regional demand variation more than manufacturing location or raw material sourcing.
United States
National park visitation and suburban yard maintenance sustain seasonal demand spikes for botanical repellents. The EPA's FIFRA biopesticide registration requirements tighten compliance thresholds for new market entrants. California and Colorado outdoor retailers curate assortments around EWG-verified and Leaping Bunny-certified products.
Germany
Pharmacy channel buyers prioritize dermatological-grade formulations for pediatric applications. The ECHA REACH framework governs botanical substance registration and hazard classification for products entering European markets. Bavaria and Baden-Württemberg extraction facilities supply cosmetic-grade essential oils to regional formulators.
India
Ayurvedic heritage and monsoon-driven vector-borne disease pressure sustain neem oil demand across household and companion animal segments. The BIS standards for herbal products create a parallel compliance pathway for exporters targeting Middle Eastern markets. Gujarat and Maharashtra agricultural cooperatives anchor azadirachtin-rich fraction production.
France
Apothecary channels demand ISO 16128-certified natural and organic cosmetic ingredients for premium positioning. ANSM and CNIL oversight drives strict interpretation of skin sensitizer classifications for whole-plant distillates. Provence-Alpes-Côte d'Azur lavender extraction capacity supports niche cosmetic repellent formulations.
Japan
Urban commuting contexts favor precision-application formats for facial and neck protection. The PMDA and METI frameworks regulate cosmetic-functional hybrid products with repellent claims. Tokyo and Osaka metropolitan consumers drive demand for non-greasy, sweat-resistant gel carriers in endurance sports applications.
Natural Ingredient Insect Repellent Market Competitive Environment
Player mix skews toward diversified household consumer goods conglomerates with established mass retail distribution networks. The competitive set compresses as EPA-mandated clinical validation costs erect barriers for mid-tier formulators. Three archetypes dominate: legacy CPG networks leveraging shelf presence, ayurvedic heritage players with captive botanical supply chains, and veterinary-formulation crossover specialists. Dominant competitive moves include strategic partnerships with fragrance houses for encapsulation IP and geographic expansion through ayurvedic export pathways.
Within the diversified CPG tier, S.C. Johnson & Son and Reckitt Benckiser occupy positions anchored by established household distribution infrastructure. Godrej Consumer Products exemplifies the captive supply archetype through in-house production of neem-based actives. Wondercide LLC represents the veterinary-to-human crossover pattern, translating companion animal formulation heritage into human-use product lines. These three companies illustrate how regulatory dossier depth and channel access determine competitive viability more than formulation innovation alone.
| Leading Market Players |
|---|
| W.S. Badger Company |
| Godrej Consumer Products |
| S.C. Johnson & Son |
| Earthley |
| Wondercide LLC |
| Reckitt Benckiser |
| Dabur International |
| The Procter & Gamble Company |
| Spectrum Brands |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Indian azadirachtin extractors and European formulators lock in supply access while capping price visibility against monsoon-driven harvest volatility. These contracts tether pricing to agricultural yield indices rather than spot commodity markets, insulating buyers from seasonal price spikes while exposing them to quality variance risks.
Pricing Analysis
Cost-plus contracts with monsoon-indexed adjustments dominate azadirachtin and p-menthane-3,8-diol procurement, linking final prices to rainfall-dependent harvest yields and extraction yields. Three-tier pricing structure across premium ISO 16128-certified, standard EPA-registered, and economy citronella-blend tiers separates pharmacy channels from mass retail and spatial repellent applications. Cost compression in the economy tier is intensifying because synthetic pyrethroid-treated textiles undercut per-application-hour economics. Budget-conscious suburban households in the United States show highest price sensitivity, while German pharmacy buyers accept dermatological-grade premiums.
Supply Chain Analysis
Inventory cycles stretch six to nine months for lemon eucalyptus oil as Australian and Brazilian harvest seasons determine raw material availability windows. Geographic supply concentration centers on India for neem-derived azadirachtin, Australia and Brazil for Corymbia citriodora essential oil, and Bulgaria and France for Lavandula angustifolia distillates. Raw material dependencies encompass monsoon-dependent agricultural yields, cyclodextrin encapsulation substrates from starch processors, and cosmetic-grade emulsion bases. Single-source vulnerability runs through Godrej Consumer Products' captive neem extraction capacity in Gujarat. Distribution runs through fragrance house formulation partners serving pharmacy and apothecary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as EPA registration barriers splinter the competitive set, creating niches for veterinary-crossover specialists and ayurvedic heritage players to capture underserved segments.
For Market Incumbents: Fortify EPA biopesticide registration dossiers through field trial investments that mid-tier formulators cannot replicate. Deepen backward integration into cyclodextrin encapsulation IP via fragrance house partnerships. Channel control through established mass retail networks remains the critical lever against clean beauty e-commerce entrants. For New Entrants and Emerging Players: ISO 16128 certification fast-track offers pharmacy channel access without full EPA field trial burdens. White-space targets include Japanese precision-application formats for urban commuting and Middle Eastern ayurvedic export corridors leveraging BIS compliance. Direct-to-consumer subscription models with ingredient transparency storytelling provide the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward veterinary-formulation crossover specialists with existing toxicology packages and companion animal EPA registrations. Long-term viability hinges on regulatory dossier depth rather than formulation novelty. Watch EPA biopesticide tolerance threshold revisions as the inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Biopesticide Registration Investment | Clinical field trials for p-menthane-3,8-diol claims lock out undercapitalized competitors from mass retail. |
| Fragrance House Encapsulation Partnership | Cyclodextrin and liposome IP access enables extended-release formulations commanding pharmacy premiums. |
| Ayurvedic Export Pathway Development | BIS certification unlocks Middle Eastern and Southeast Asian markets parallel to EPA-regulated channels. |
| Veterinary-to-Human Product Line Extension | Existing companion animal toxicology dossiers accelerate human-use market entry under EPA frameworks. |
| Clean Beauty Certification Stack | EWG verification and Leaping Bunny certification secure placement in coastal metropolitan natural product retail. |
Study Parameters
Operator-level perspectives from brand managers at natural product retailers, category buyers at outdoor equipment chains, regulatory affairs leads at biopesticide formulators, and procurement directors at fragrance houses anchored the qualitative base. Primary interview insights combined with secondary validation from EPA biopesticide registration databases, ECHA REACH substance classifications, Indian BIS herbal product standards, and customs trade records for essential oil imports. Bottom-up SKU-level enumeration triangulated against top-down category spend estimates.
Sensitivity analysis around EPA registration timeline scenarios and monsoon yield variance shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product format, active ingredient type, application context, and distribution channel, with regulatory pathway complexity serving as an additional cross-cutting variable. CAGRs derived from fitted growth curves applied to validated base-year estimates, incorporating lemon eucalyptus oil EPA registration expansion rates and DEET-free household penetration patterns as industry-specific inputs.
Underlying assumptions cover stable EPA biopesticide tolerance thresholds and intact India-Europe neem oil trade corridors, with deviation risk concentrated in REACH skin sensitizer reclassifications and extreme monsoon disruption events. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Croscarmellose Sodium Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Synthetic and Bio-Based Adipic Acid Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Alpha Bisabolol Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Global Bio Based Esters Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Copovidone Market
Specialty Chemicals
Fragrance-Release Control Agents for Long-Lasting Home Care Scents Market
Specialty Chemicals
Methyltrimethoxysilane Market