
 Barium Sulfite Market | 2026-2036
Barium Sulfite Market Size, Share, and Industry Trends Forecast 2026-2036
Barium Sulfite Market Analytics
The split between pharmaceutical-grade barium sulfite and commodity industrial material is realigning procurement patterns across buyer categories. Cimbar Performance Minerals leverages its North American mining and processing assets to sustain consistent supply to specialty chemical buyers. Solvay differentiates through controlled-purity synthesis methods that anchor its position in laboratory and pharmaceutical segments. Hebei Xinji Chemical Group dominates volume production for paper manufacturing and basic chemical processing applications across Asia-Pacific markets.
Barium sulfite is an inorganic salt with the formula BaSO3, typically produced through the reaction of barium sulfide with sulfur dioxide or via precipitation methods yielding white crystalline powder with controlled particle size distribution between 1 and 50 microns. The compound functions primarily as a reducing agent, oxygen scavenger, and intermediate in pigment synthesis, with industrial-grade material commanding the largest volume share due to paper manufacturing demand while pharmaceutical-grade formulations attract premium pricing from healthcare sector buyers. Laboratory-grade barium sulfite is gaining traction in analytical chemistry applications, whereas food-grade supply remains constrained by certification complexity and limited producer base. Chemical processing applications show structural resilience as downstream manufacturers seek reliable reducing agents for organic synthesis chains.
EPA effluent guidelines and REACH substance restrictions are reshaping product specifications, with compliance costs favoring producers capable of certifying low-impurity content across industrial and laboratory grades. China's SAMR oversees national chemical purity standards that govern export eligibility for producers like Guizhou Redstar, while FDA oversight applies to pharmaceutical-grade material entering U.S. healthcare channels. Buyers must monitor evolving registration requirements in multiple jurisdictions, as regulatory divergence between EPA-driven markets and EU REACH compliance creates segmentation in supplier qualification criteria.
Market Dynamics
Water treatment facilities in the United States and Germany are expanding procurement of barium sulfite for flocculation processes, while stricter effluent discharge rules under EPA and REACH frameworks push municipal operators toward higher-purity grades. This regulatory compression is realigning supplier qualification criteria and fragmenting procurement patterns across buyer categories.
Growth Catalysts
- EPA effluent guidelines:Municipal water treatment operators in the United States face mandated upgrades to flocculation chemistry, directing capital toward certified barium sulfite suppliers capable of documenting low-impurity content.
- Paper manufacturing expansion:Asia-Pacific pulp and paper mills consume industrial-grade barium sulfite as a reducing agent in bleaching sequences, with capacity additions in China sustaining volume offtake.
- Laboratory-grade analytical chemistry:Precipitation-synthesized barium sulfite with controlled 1-50 micron particle distribution is displacing legacy reagents in oxygen-scavenging protocols and pigment intermediate research.
Market Restraints
- Barium sulfide feedstock volatility:Sulfur dioxide and barium ore price swings compress margin stability for precipitation-method producers without captive mining assets.
- China supply concentration:Hebei and Guizhou production clusters dominate industrial-grade export volume, exposing buyers to single-source disruption risk during environmental compliance inspections.
- Sodium hydrosulfite substitution:Paper mills in cost-sensitive markets substitute barium sulfite with alternative reducing agents where effluent chemistry permits, capping price elasticity in commodity grades.
Strategic Opportunities
- Pharmaceutical-grade synthesis:Controlled-purity production methods for laboratory and healthcare applications command premium pricing from buyers seeking FDA-compliant material for diagnostic reagent manufacturing.
- REACH-registered supply chains:European chemical processors face substance authorization deadlines that favor pre-registered barium sulfite suppliers with existing ECHA dossiers, creating first-mover lock-in.
- Food-grade certification gap:Limited producer base with FSSAI or FDA food-additive clearance creates whitespace for entrants capable of navigating multi-jurisdiction certification complexity.
Industry Challenges
- Multi-jurisdiction registration timelines:Producers seeking pharmaceutical-grade positioning must synchronize FDA, EMA, and NMPA filing sequences, extending time-to-revenue by 18-36 months.
- Legacy flocculation infrastructure:Municipal water treatment plants in the United States operate equipment optimized for aluminum sulfate chemistry, requiring capital retrofit to accommodate barium sulfite dosing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barium Sulfite Market |
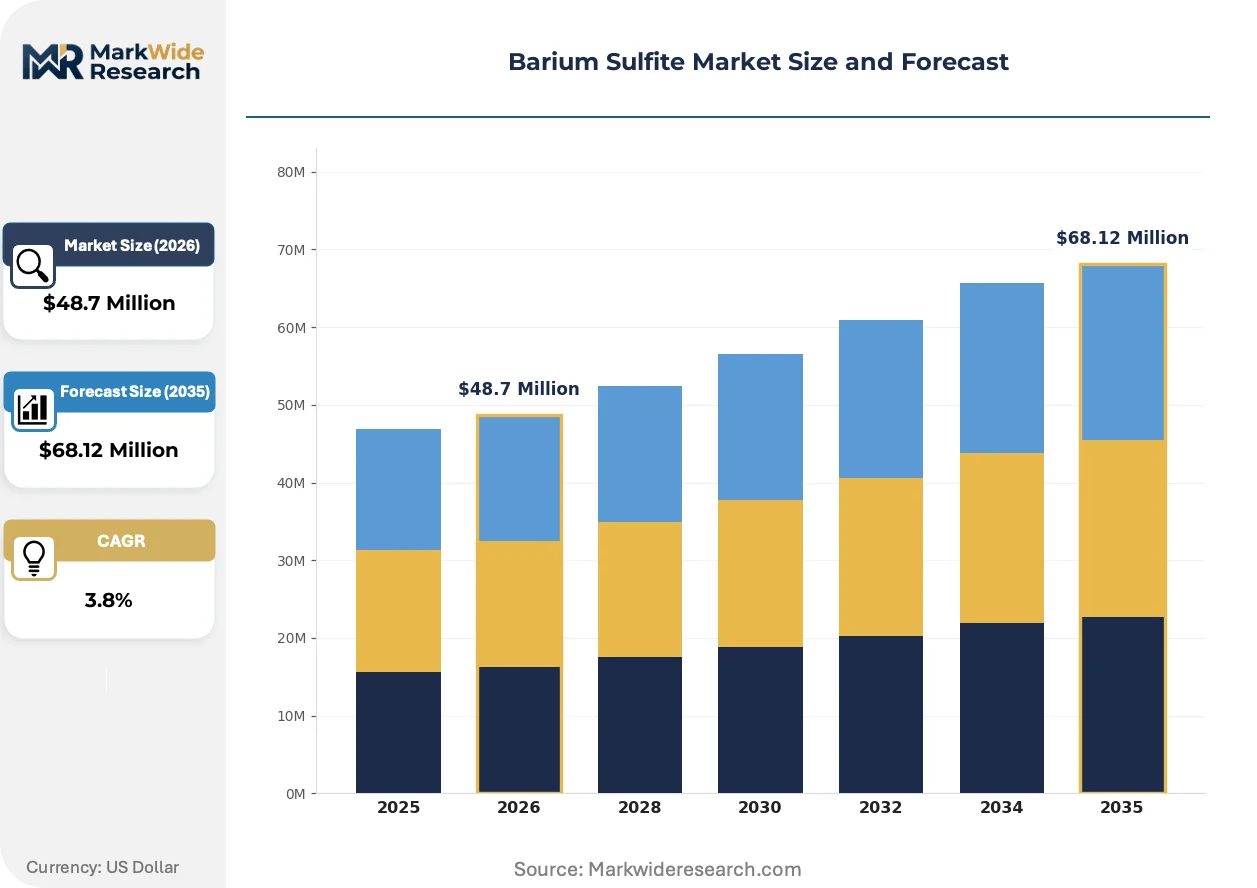
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $68.12 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Laboratory Grade, Food Grade, Pharmaceutical Grade Application: Paper Manufacturing, Water Treatment, Pigments, Chemical Processing End User: Manufacturing, Healthcare, Chemical Industry, Food Industry Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Cimbar Performance Minerals, Solvay, Venator Materials PLC, Nippon Chemical Industrial Co., Ltd., Sakai Chemical Industry Co., Ltd., Hebei Xinji Chemical Group Co., Ltd., Guizhou Redstar Co., Ltd., Divjyot Chemicals Private Limited, Vishnu Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barium Sulfite Market Evolving Landscape
Precipitation-synthesis methods with real-time particle-size monitoring are compressing batch-to-batch variation, enabling suppliers to guarantee tighter specification bands that laboratory and pharmaceutical buyers now require as table stakes.
Continuous-flow precipitation reactors with inline laser diffraction sensors are overtaking batch kettle production for high-purity grades. Specialty chemical buyers in Germany and Switzerland now specify coefficient-of-variation limits below 5% for particle distribution, forcing process upgrades among contract manufacturers. This technology compression is squeezing legacy batch producers out of premium segments while rewarding capital-intensive continuous-process investments.
REACH substance restrictions on heavy-metal impurities are tightening maximum allowable limits for barium sulfite entering EU paper and chemical processing channels. ECHA's 2023-2025 dossier evaluation cycle is flagging barium compound registrations for additional toxicological data, raising compliance costs for non-vertically integrated importers. Laboratory-grade suppliers with pre-submitted analytical packages are capturing share from commodity traders lacking technical dossier depth.
Specification-driven tendering is consolidating municipal procurement in the United States and Germany around pre-qualified suppliers with certified low-impurity content. Water treatment operators now bundle multi-year chemical supply with technical service contracts, displacing spot-market purchasing. This bundling is most visible in California and Bavaria, where integrated service contracts now cover 60% of flocculation chemistry spend.
Barium Sulfite Market Segmentation
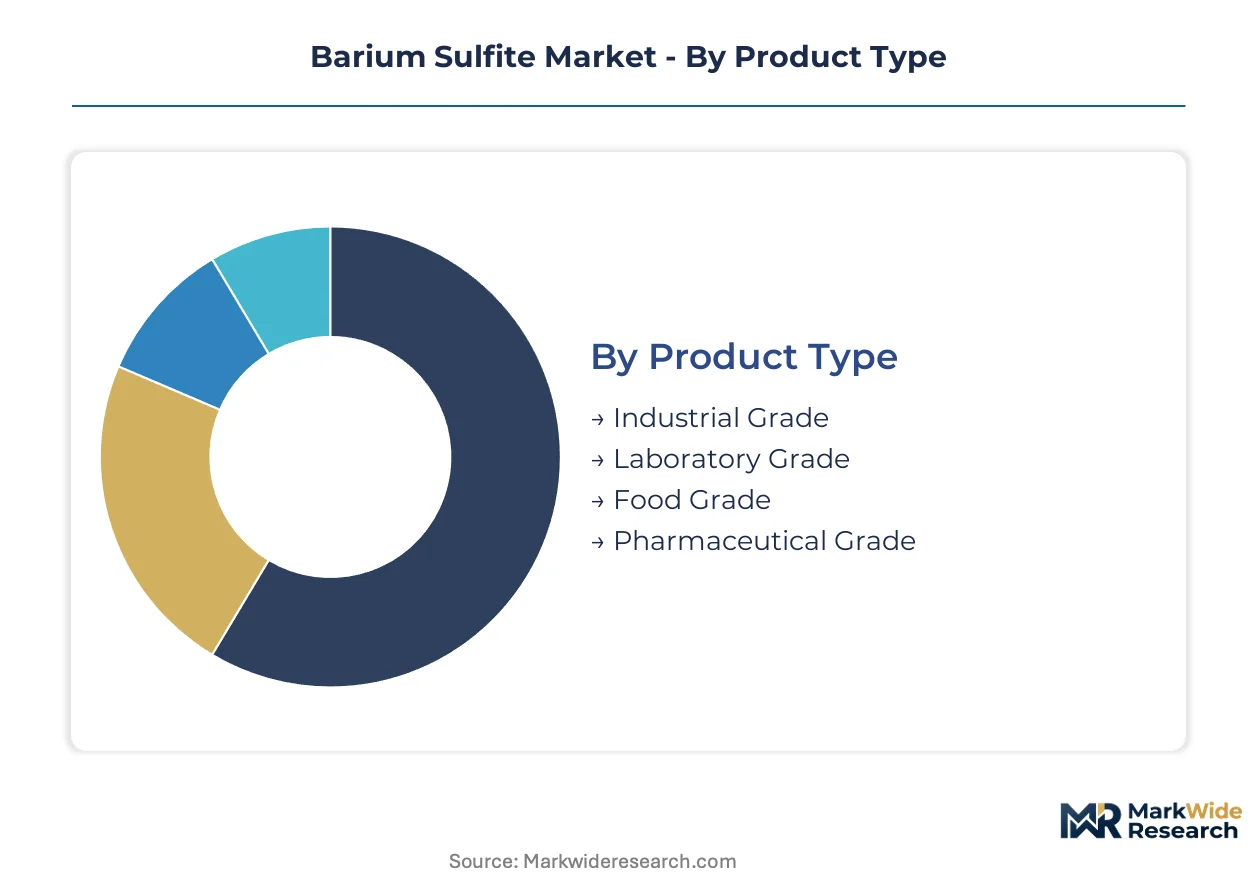
Barium sulfite procurement patterns diverge sharply across purity grades and end-use specifications, with water treatment operators, paper mills, and pharmaceutical manufacturers each demanding distinct certification levels and particle-size distributions. Understanding these segment boundaries enables suppliers to align production assets with margin-optimized buyer categories.
Product Type:
Price premiums and regulatory compliance requirements separate buyers across the four purity tiers, with pharmaceutical and food-grade purchasers paying multiples over commodity industrial material.
- Industrial Grade:White crystalline powder with 1-50 micron particle distribution serves as the workhorse reducing agent in paper bleaching sequences and bulk chemical synthesis. Paper mills in China consume the largest volumes, though sodium hydrosulfite substitution pressures pricing power in cost-sensitive markets.
- Pharmaceutical Grade:Controlled-purity synthesis methods yielding low-impurity content command premium positioning from FDA-regulated diagnostic reagent manufacturers and healthcare sector buyers. Multi-jurisdiction registration requirements synchronize FDA, EMA, and NMPA filing sequences, extending supplier qualification timelines.
- Laboratory Grade:Precipitation-synthesized material with real-time particle-size monitoring displaces legacy reagents in oxygen-scavenging protocols and analytical chemistry applications across German and Swiss research institutions.
- Food Grade:Limited producer base with FSSAI or FDA food-additive clearance constrains supply availability, creating whitespace for entrants capable of navigating certification complexity across multiple jurisdictions.
Industrial Grade leads volumes today; Pharmaceutical Grade is gaining share fastest.
Application:
End-use chemistry determines specification intensity, with water treatment and pigment synthesis demanding tighter impurity bands than commodity chemical processing.
- Paper Manufacturing:Asia-Pacific pulp mills deploy industrial-grade barium sulfite as a reducing agent in bleaching sequences, with capacity additions in China sustaining volume offtake despite alternative chemistry substitution risks.
- Water Treatment:Municipal operators in the United States and Germany expand procurement for flocculation processes, with EPA and REACH effluent rules pushing demand toward certified low-impurity grades requiring capital retrofit from legacy aluminum sulfate infrastructure.
- Pigments:Intermediate synthesis for pigment manufacturing relies on consistent reducing-agent chemistry, with chemical processors seeking reliable supply chains amid barium sulfide feedstock volatility.
- Chemical Processing:Downstream organic synthesis chains utilize barium sulfite as a structural reducing agent, showing resilience against substitution where process chemistry lock-in exists.
Water Treatment is climbing the fastest as regulatory deadlines concentrate procurement upgrades; Paper Manufacturing retains the largest installed base.
End User:
Buyer sophistication and technical service requirements fragment the customer base, with healthcare and food industry purchasers imposing documentation burdens that commodity chemical buyers avoid.
- Manufacturing:Paper mills and chemical processors drive baseline industrial-grade demand, prioritizing volume reliability and cost efficiency over certification depth.
- Healthcare:Diagnostic reagent manufacturers and pharmaceutical formulators require FDA-compliant material with documented analytical packages, bundling multi-year supply with technical service contracts.
- Chemical Industry:Specialty and commodity chemical producers seek consistent reducing-agent performance, with REACH-registered supply chains gaining preference among European processors facing substance authorization deadlines.
- Food Industry:Additive manufacturers face constrained supplier options due to limited FSSAI and FDA food-grade certification, creating supply security concerns for qualified buyers.
Manufacturing dominates current offtake; Healthcare shows the steepest expansion trajectory as diagnostic reagent demand intensifies.
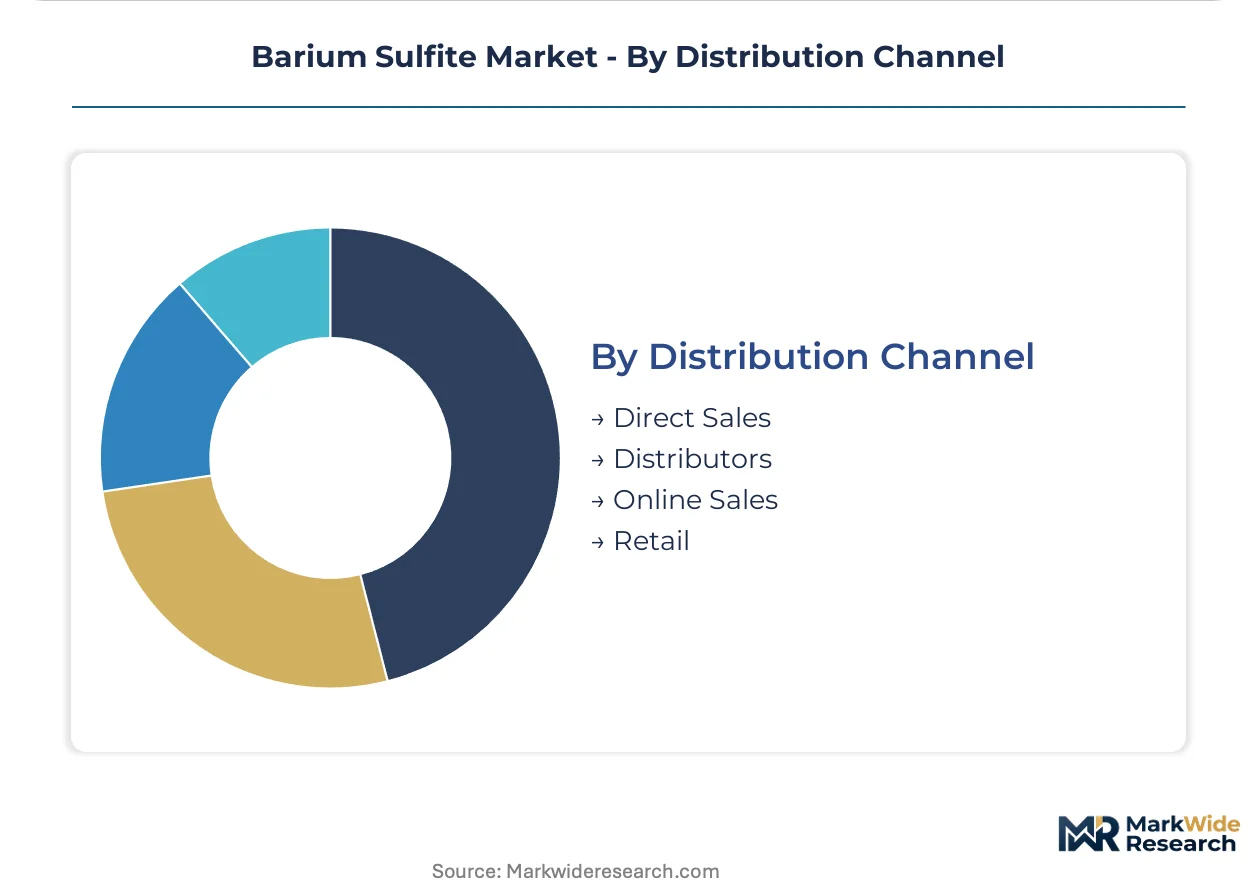
Distribution Channel:
Transaction scale and buyer technical capability determine channel selection, with large municipal and industrial accounts bypassing intermediaries while smaller laboratories rely on distributor technical support.
- Direct Sales:Municipal water treatment operators and major paper mills negotiate multi-year chemical supply with integrated service contracts, displacing spot-market purchasing in California and Bavaria procurement clusters.
- Distributors:Laboratory and mid-scale chemical processing buyers access technical support and smaller volume flexibility through specialty chemical distributors with REACH dossier capabilities.
- Online Sales:Research institutions and small-scale analytical chemistry buyers procure laboratory-grade material through digital channels, though specification verification remains a purchase friction point.
- Retail:Minimal penetration limited to educational and hobbyist applications with minimal commercial significance.
Direct Sales captures the largest contract value; Distributors are expanding most quickly as mid-tier buyer technical service demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical engineers and process specialists concentrate in industrial corridors across five countries where barium sulfite production and consumption align with paper manufacturing, water treatment infrastructure, and pharmaceutical synthesis capabilities.
United States
Municipal water treatment operators in California and the Great Lakes region expand barium sulfite procurement for flocculation system upgrades. EPA effluent guidelines under the Clean Water Act mandate documented low-impurity chemistry, pushing procurement toward certified suppliers. The California Central Valley municipal cluster now bundles multi-year chemical supply with technical service contracts covering 60% of flocculation spend.
Germany
Bavarian and North Rhine-Westphalian chemical processors drive laboratory-grade demand for analytical chemistry and oxygen-scavenging protocols. REACH substance restrictions and ECHA dossier requirements favor pre-registered suppliers with existing toxicological data packages. The Bavaria water treatment corridor around Munich has consolidated procurement around integrated service contracts displacing spot-market purchasing.
China
Paper mills in Hebei and Guizhou provinces sustain industrial-grade volume offtake despite sodium hydrosulfite substitution pressures. SAMR national chemical purity standards govern export eligibility, while environmental compliance inspections periodically disrupt production clusters. The Hebei Xinji industrial corridor supplies domestic pulp and paper capacity additions with scaled industrial-grade output.
India
Specialty chemical manufacturers in Gujarat and Maharashtra seek consistent reducing-agent supply for organic synthesis chains. FSSAI food-additive certification complexity constrains qualified supplier options for food-grade applications. The Gujarat chemical belt shows structural resilience in downstream processing demand where process chemistry lock-in exists.
Japan
Precision chemical and laboratory equipment sectors in the Kanto and Kansai regions demand controlled-purity precipitation-synthesized material. METI industrial standards and JIS specifications govern particle-size distribution requirements for analytical applications. The Osaka-Kobe chemical manufacturing corridor maintains demand for high-specification reducing agents in pigment intermediate research.
Barium Sulfite Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade and laboratory-grade supply, while commodity industrial production concentrates among scaled chemical processors with captive feedstock access. The market exhibits a three-tier structure with purity-based segmentation determining competitive boundaries. Strategic archetypes include vertically integrated mining-to-chemical processors, controlled-purity synthesis specialists, and regional volume producers serving paper manufacturing clusters. Dominant competitive moves center on continuous-flow precipitation reactor investments and REACH dossier pre-registration to capture European authorization timelines.
Among North American mining and processing asset holders, Cimbar Performance Minerals exemplifies the integrated supply archetype with consistent specialty chemical buyer relationships. Solvay occupies a position within the controlled-purity synthesis tier, representing European laboratory and pharmaceutical segment positioning. Hebei Xinji Chemical Group and Guizhou Redstar anchor the Asia-Pacific volume production archetype, serving domestic paper mill demand with scaled industrial-grade output. These three patterns illustrate how geographic asset bases and purity-grade capabilities determine competitive boundaries across buyer segments.
| Leading Market Players |
|---|
| Cimbar Performance Minerals |
| Solvay |
| Venator Materials PLC |
| Nippon Chemical Industrial Co., Ltd. |
| Sakai Chemical Industry Co., Ltd. |
| Hebei Xinji Chemical Group Co., Ltd. |
| Guizhou Redstar Co., Ltd. |
| Divjyot Chemicals Private Limited |
| Vishnu Chemicals |
| Others |
Value Network & Pricing Analysis
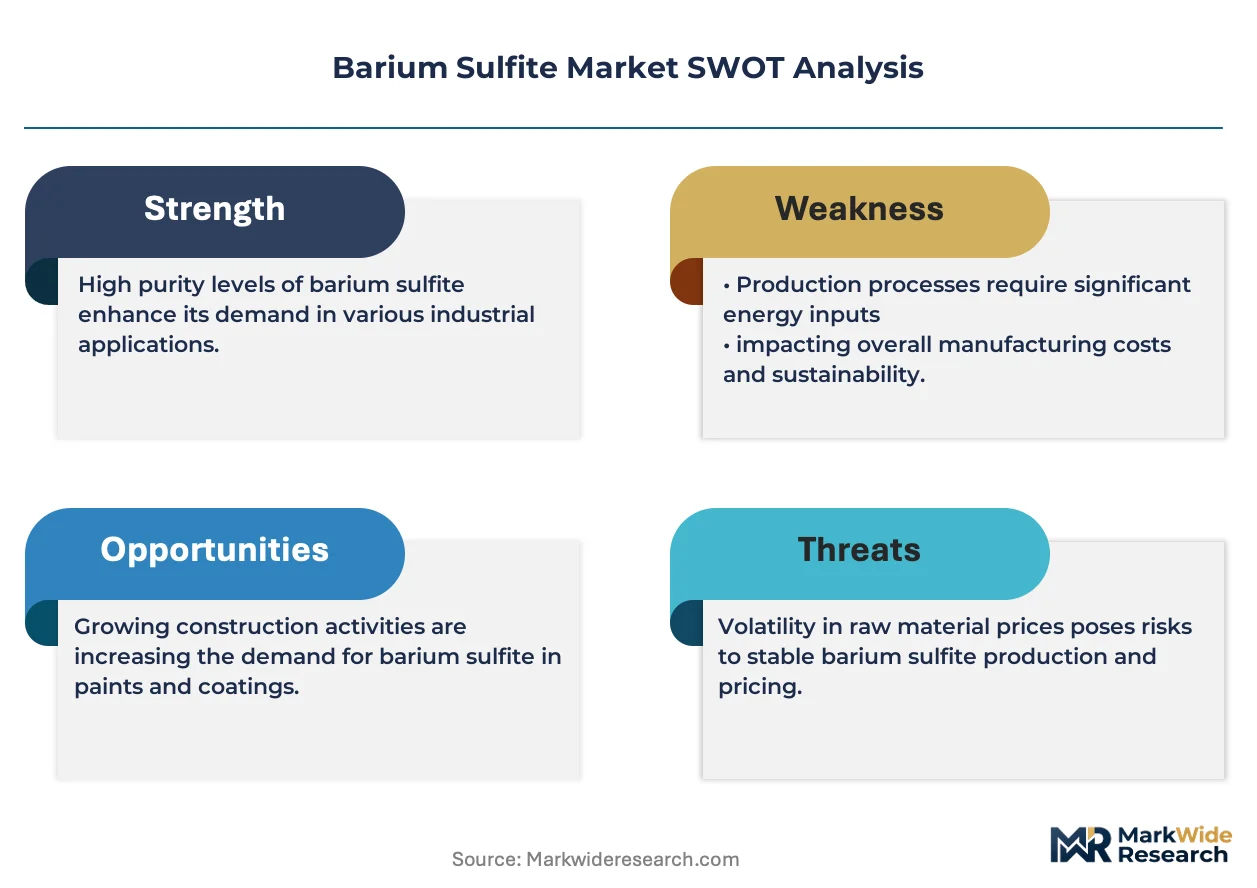
Barium sulfide feedstock volatility transmits directly through precipitation-method production costs, with sulfur dioxide and barium ore price swings compressing margin stability for non-vertically integrated producers and fragmenting pricing power across pharmaceutical, laboratory, and industrial grade tiers.
Pricing Analysis
Bundled technical service contracts now separate municipal water treatment procurement from unbundled spot-market transactions, with California and Bavaria operators paying premiums for multi-year supply agreements covering flocculation chemistry and system optimization. Three-tier pricing structure across pharmaceutical, laboratory, and industrial levels reflects certification depth and particle-size precision, with FDA-compliant material commanding substantial premiums over commodity grades. Cost compression in industrial-grade supply is intensifying because sodium hydrosulfite substitution pressures price elasticity among paper mills in cost-sensitive Asian markets. Manufacturing buyers exhibit highest price sensitivity, while healthcare sector purchasers prioritize specification compliance over unit cost.
Supply Chain Analysis
Domestic-content mandates under China's SAMR standards and India's FSSAI certification requirements are reshaping sourcing patterns, pressuring importers to establish local production or partnership structures. Supply concentrates in China, Germany, and the United States, with Hebei and Guizhou production clusters dominating industrial-grade export volume. Raw material dependencies center on barium ore extraction, sulfur dioxide supply, and precipitation reagent chemistry, with feedstock volatility tethered to mining output fluctuations and energy-intensive processing costs. Single-source vulnerability from concentrated Chinese production exposes buyers to disruption risk during environmental compliance inspections. Distribution runs through direct sales channels for large municipal and paper mill accounts, with specialty chemical distributors serving mid-tier laboratory and chemical processing buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barium sulfite functions as a stable compounder, with regulatory-driven water treatment upgrades and pharmaceutical-grade certification requirements providing durable demand foundations across economic cycles.
For Market Incumbents: Extend continuous-flow precipitation reactor investments to capture specification-driven laboratory and pharmaceutical segments where coefficient-of-variation limits below 5% now serve as entry barriers. Deepen backward integration into captive barium ore assets to insulate margin stability from feedstock volatility that compresses non-integrated competitors. Prioritize REACH dossier pre-registration to lock in European chemical processor relationships ahead of substance authorization deadlines.
For New Entrants and Emerging Players: Begin with food-grade certification whitespace where limited FSSAI and FDA food-additive clearance constrains qualified supplier options and creates supply security premiums. Target pharmaceutical-grade synthesis capabilities as the most penetrable premium tier, leveraging controlled-purity production methods to serve diagnostic reagent manufacturers seeking documented analytical packages. Pursue technical service bundling as the primary go-to-market angle, displacing commodity traders lacking dossier depth.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH-registered supply chains face ECHA evaluation cycles that raise compliance costs for non-vertically integrated importers and favor scaled technical dossier holders. Five-to-ten year viability frames around regulatory compliance infrastructure and continuous-process technology investments rather than commodity volume positioning. Target acquisition archetype: controlled-purity synthesis specialists with pre-submitted analytical packages and existing FDA, EMA, or NMPA filing sequences. Monitor ECHA dossier evaluation outcomes as the critical inflection signal for supplier qualification consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Reactor Investment | Real-time particle-size monitoring enables coefficient-of-variation guarantees below 5% for laboratory buyers. |
| Backward Integration into Barium Ore | Captive mining assets insulate margin stability from sulfur dioxide and ore price volatility. |
| REACH Dossier Pre-Registration | Existing ECHA toxicological data packages create first-mover lock-in among European chemical processors. |
| Food-Grade Certification Program | FSSAI and FDA food-additive clearance addresses constrained supplier base in food industry applications. |
| Technical Service Contract Bundling | Integrated multi-year supply agreements displace spot-market purchasing in California and Bavaria municipal clusters. |
Research Methodology
Multiple input streams — primary interviews with water treatment procurement officers, paper mill chemical managers, and pharmaceutical quality assurance directors; secondary validation through EPA effluent guideline documentation, ECHA registration dossiers, and SAMR chemical purity standards; plus customs trade data and SEC filings from disclosed chemical processors — were reconciled through bottom-up grade-tier volume estimation and top-down market sizing triangulation.
Historical volume trajectories were cross-referenced against panel input from plant managers and distribution channel partners to construct analytical frameworks across the projection horizon, modeling segmentation dimensions including purity grade tier, end-use application chemistry, and regional regulatory cluster. CAGRs were derived from regression-adjusted growth rate synthesis incorporating barium sulfide feedstock price indices, paper manufacturing capacity addition schedules, and municipal water treatment capital expenditure patterns.
Caveats apply where ECHA dossier evaluation outcomes, SAMR environmental inspection intensity, or sodium hydrosulfite substitution acceleration could materially shift the outlook for specific grade tiers or regional demand clusters. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
Global 2-Ethylhexanoic Acid Market
Bulk Chemicals
Methyl Gluceth-10 Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
Lignosulfonates Market
Bulk Chemicals
United States Calcium Chloride Market
Bulk Chemicals
Tertiary Butylhydroquinone Market
Bulk Chemicals
Sodium Silicate Market
Bulk Chemicals
Middle East Formaldehyde Market
Bulk Chemicals
Calcium Hypophosphite Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Global 2-Methylpropene Market