
 Lightweight Materials Market | 2026-2036
Lightweight Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Lightweight Materials Market Intelligence
A transition from single-source contracts toward multi-source procurement for critical composites is shifting supplier relationships in high-performance applications. This environment benefits specialized producers like Hexcel Corporation, which specializes in advanced composite technologies for aerospace. Toray Industries Inc. leverages its scale in carbon fiber production to serve diverse end-use industries. Solvay differentiates through its broad portfolio of specialty polymers and composite materials.
Lightweight materials encompass a range of substances engineered to provide high strength and stiffness at a low density. These materials, including alloys and composites, are often produced through processes like pultrusion or advanced weaving to achieve specific performance characteristics. While aluminum remains a foundational material type due to its cost-effectiveness, carbon fiber composites represent the fastest-growing segment, driven by premium applications in aerospace. Consumer electronics and industrial machinery are also significant end-use industries for these materials.
Regulatory frameworks are pivotal in shaping material selection across key industries. In the United States, EPA emissions standards for vehicles push for lighter components, while Europe’s REACH regulation governs the chemical composition of polymers and composites. China's dual carbon goals further incentivize the adoption of energy-saving materials in manufacturing. Consequently, material suppliers must continuously balance the pursuit of higher performance with the need for scalable and cost-effective production.
Market Dynamics
Intensifying regulatory mandates for emissions reduction and energy efficiency serve as the central force shaping material selection. Frameworks from the US EPA and the EU Green Deal are compelling automotive and aerospace manufacturers to accelerate the substitution of heavier metals with advanced lightweight alternatives.
Growth Catalysts
- Automotive Electrification:The global transition to electric vehicles creates substantial demand for lightweight materials to offset heavy battery packs, extend vehicle range, and improve overall performance efficiency.
- Aerospace Modernization:Demand from the aerospace sector for next-generation aircraft with superior fuel economy and lower operational costs drives the adoption of carbon fiber composites and advanced aluminum alloys in airframes and engines.
- Chinese Industrial Policy:China's dual carbon goals and related industrial policies incentivize the use of energy-saving materials across manufacturing sectors, creating a large, policy-driven market for lightweight solutions in industrial machinery and construction.
Market Restraints
- High Production Costs:The elevated cost of producing and processing advanced materials like carbon fiber composites, relative to conventional steel and aluminum, limits their application in mass-market, cost-sensitive sectors.
- Recycling and Circularity Hurdles:Technical difficulties and high costs associated with recycling thermoset composites present a significant sustainability challenge, hindering their alignment with circular economy objectives and creating end-of-life disposal issues.
- Complex Manufacturing Processes:Specialized and often slow manufacturing techniques, such as autoclave curing for aerospace-grade composites, create production bottlenecks and limit the scalability required for high-volume automotive applications.
Strategic Opportunities
- Renewable Energy Sector:The wind energy industry presents a major opportunity, with demand for longer, lighter, and more durable turbine blades driving innovation in glass and carbon fiber composites.
- Smart Material Integration:Incorporating sensors and conductive fibers directly into composite structures offers a path to creating smart materials that enable real-time structural health monitoring in aircraft, bridges, and vehicles.
- Medical Device Applications:The biocompatibility and radiolucency of certain polymers and composites, such as PEEK, create opportunities in medical implants, surgical instruments, and advanced prosthetics where strength and low weight are critical.
Industry Challenges
- Lack of Standardization:A deficit in globally harmonized standards for the testing, characterization, and certification of new composite materials slows their qualification and adoption, particularly in safety-critical applications like aerospace and automotive.
- Capital-Intensive Production:The requirement for significant capital investment in specialized equipment, including automated fiber placement machines and high-pressure resin transfer molding systems, acts as a barrier to entry for new and smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lightweight Materials Market |
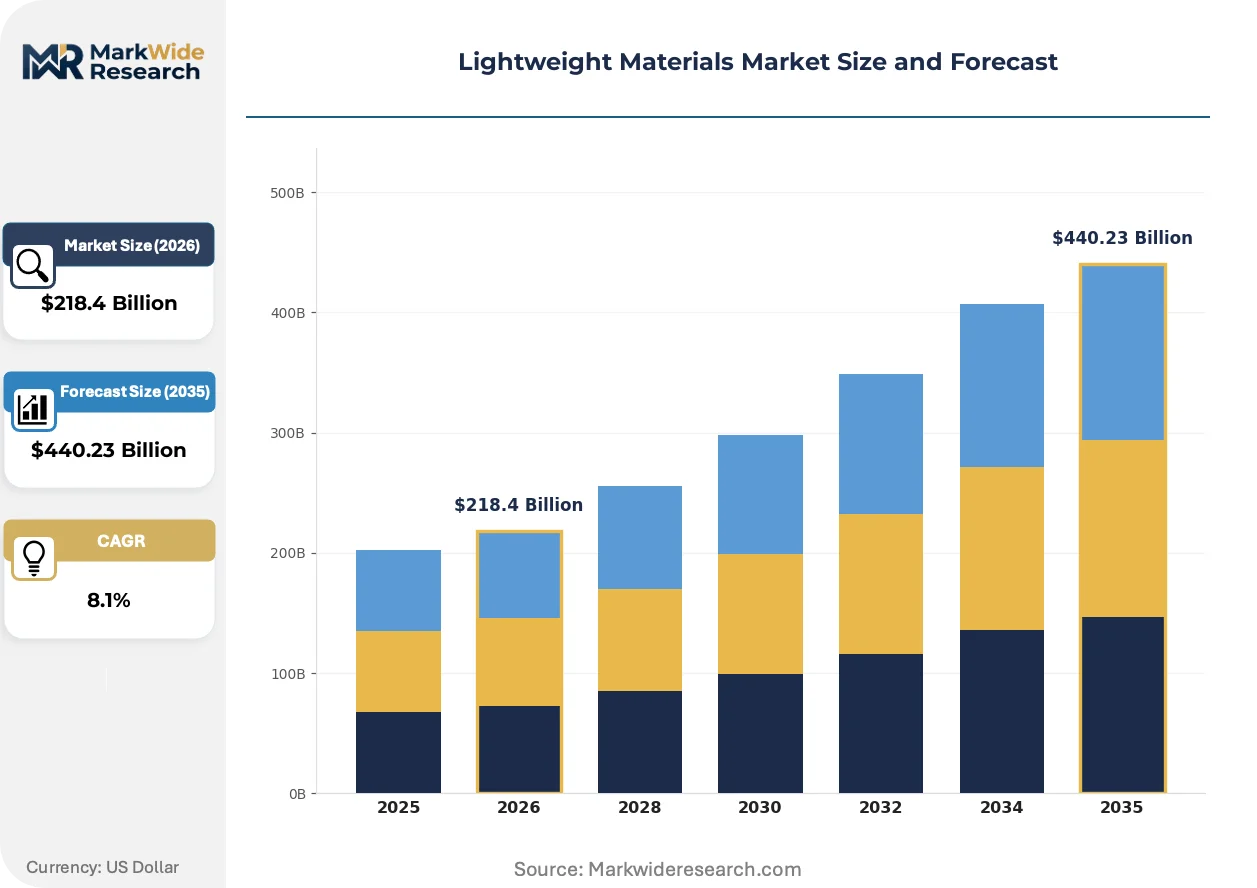
| Market Size in 2026 | $218.4 Billion |
| Market Size in 2035 | $440.23 Billion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Magnesium, Carbon Fiber, Glass Fiber, Titanium, Polymer Composite End Use Industry: Aerospace, Consumer Electronics, Sports Equipment, Marine Craft, Packaging, Industrial Machinery Application: Structural Components, Interior Parts, Protective Gear, Enclosures, Load Bearing Elements, Insulation Form: Sheet, Foam, Rod, Fabric, Powder, Profile |
| Companies Covered | Alcoa Corporation, Novelis Inc., Toray Industries Inc., SABIC, PPG Industries Inc., ArcelorMittal, Hexcel Corporation, Solvay, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lightweight Materials Market Strategic Shifts & Innovations
The industrialization of composite manufacturing is a defining theme, as processes once confined to niche, high-performance applications are adapted for higher volume and lower cost. This evolution is enabling lightweight materials to penetrate new end-use markets previously dominated by traditional metals.
Multi-material design, which strategically combines different fibers and resins, is gaining traction as a core product evolution. Automotive and consumer electronics manufacturers are the primary adopters, seeking to optimize components for both performance and cost. This approach is modularizing component engineering, allowing designers to precisely tailor properties like stiffness, impact resistance, and thermal conductivity to specific zones within a single integrated part.
Europe’s REACH regulation continues to govern the chemical inputs for polymers and composites, restricting certain substances and driving research into safer alternatives. This framework compels material suppliers to invest heavily in compliance and reformulation, directly influencing supply chains for resins, additives, and coatings. The automotive sector is most affected, actively seeking REACH-compliant materials to ensure uninterrupted market access within the European Union.
A definitive shift toward qualifying multiple suppliers for critical material programs is altering OEM-supplier dynamics. Aerospace and automotive prime contractors are actively building redundant supply chains to mitigate geopolitical risks and enhance their negotiating leverage on price. This pattern is most visible in North American aerospace hubs, forcing suppliers to differentiate based on supply assurance and application engineering support rather than on material specifications alone.
Lightweight Materials Market Segmentation
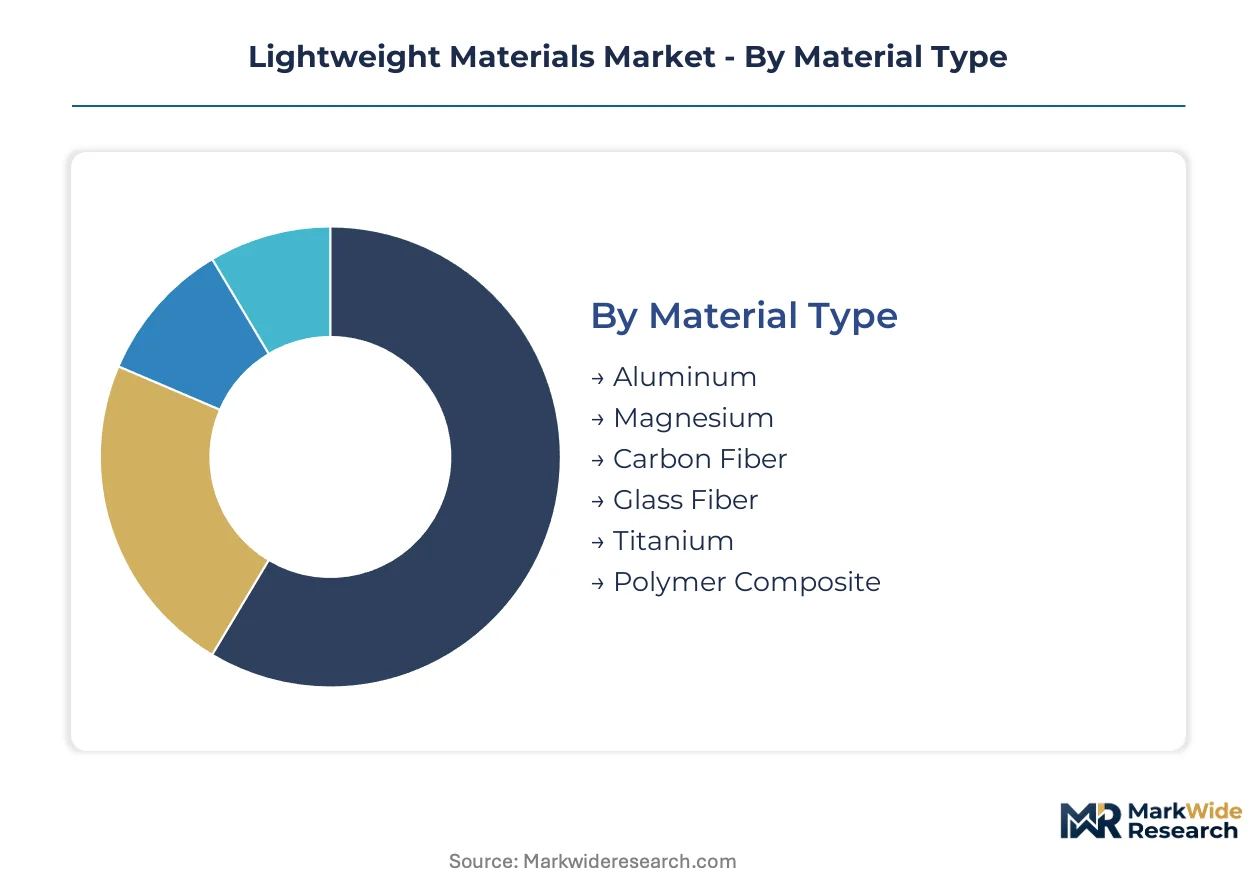
Understanding the Lightweight Materials Market through segmentation reveals distinct value propositions and operational complexities for suppliers. Material properties, end-use applications, and processing methods vary significantly, requiring specialized manufacturing capabilities and investment. This detailed breakdown helps identify areas of concentrated demand and emerging growth trajectories across the value chain.
Material Type:
The capital intensity associated with producing different lightweight materials significantly influences market entry and competitive dynamics.
- Aluminum:A foundational lightweight metal, aluminum offers an excellent strength-to-weight ratio and corrosion resistance, making it cost-effective for high-volume automotive and construction applications. Established production infrastructure supports its widespread use in diverse sectors.
- Carbon Fiber:Characterized by exceptional strength and stiffness at very low weight, carbon fiber is critical for premium applications in aerospace and high-performance automotive. Its production requires specialized, energy-intensive processes and advanced manufacturing techniques.
- Magnesium:As the lightest structural metal, magnesium provides significant weight reduction benefits for automotive components and consumer electronics. Its processing requires specific handling due to reactivity.
- Glass Fiber:A cost-effective reinforcement for composite materials, glass fiber is extensively used in wind energy, marine, and construction for its strength and durability.
- Titanium:Renowned for its high strength-to-weight ratio and superior corrosion resistance, titanium is indispensable for demanding aerospace and medical applications.
- Polymer Composite:These materials combine various polymers with reinforcing fibers, offering tailored performance characteristics for diverse structural and functional needs.
Aluminum absorbs the bulk of installed capacity; carbon fiber is expanding most quickly.
End Use Industry:
The diverse application requirements across end-use industries dictate material selection and performance specifications.
- Aerospace:This sector demands materials with extreme strength-to-weight ratios and fatigue resistance for fuel-efficient aircraft and spacecraft components. Advanced composites and high-performance alloys are critical for airframes and engines.
- Industrial Machinery:Manufacturers seek durable and lightweight materials to reduce operational energy consumption and extend equipment lifespan. China's dual carbon goals provide a strong incentive for adopting these materials in this sector.
- Consumer Electronics:Lightweight materials are crucial for enhancing portability, improving thermal management, and enabling sleek designs in devices like smartphones and laptops.
- Sports Equipment:This industry leverages material lightness and strength to improve athletic performance and durability in products such as bicycles, rackets, and protective gear.
- Marine Craft:Corrosion-resistant and lightweight materials contribute to improved speed, fuel economy, and reduced maintenance for various marine vessels.
- Packaging:Lightweight plastics and composites help reduce shipping costs, material consumption, and environmental impact in the packaging sector.
Demand from the aerospace sector drives premium material innovation, while industrial machinery prioritizes cost-effective volume solutions.
Application:
Performance criticality dictates the material properties required for specific lightweight applications.
- Structural Components:These applications require exceptional strength, stiffness, and fatigue resistance to ensure the integrity and safety of vehicles, aircraft, and infrastructure. Material choice is paramount for load-bearing capabilities.
- Enclosures:Focuses on weight reduction, aesthetic integration, and protection for consumer electronics, automotive interiors, and industrial equipment. These often combine lightweight polymers with metallic elements.
- Interior Parts:Emphasizes aesthetics, comfort, and lightweighting for passenger cabins in automotive and aerospace, contributing to overall vehicle efficiency.
- Protective Gear:Utilizes high-impact resistant composites and advanced polymers for safety in sports, military, and industrial environments.
- Load Bearing Elements:Demands high tensile strength, compressive strength, and fatigue resistance for heavy machinery and critical infrastructure.
- Insulation:Employs lightweight foams and advanced aerogels for thermal management, acoustic dampening, and energy efficiency in various systems.
High-performance structural component applications drive material innovation, while interior parts focus on cost-effective mass production.
Form:
The form in which lightweight materials are supplied directly impacts manufacturing processes and scalability across industries.
- Sheet:Offers versatility for stamping, forming, and cutting, widely used in automotive body panels, aerospace skins, and construction. Aluminum and composite sheets provide significant weight savings.
- Fabric:Composed of woven or non-woven fibers, fabric forms the basis for advanced composites used in aerospace, wind turbine blades, and sporting goods. Automated fiber placement processes utilize these forms.
- Foam:Provides lightweight core structures, insulation, and energy absorption, common in sandwich panels, automotive components, and packaging.
- Rod:Used for structural elements, fasteners, and reinforcement, particularly in high-strength alloy and composite applications.
- Powder:Essential for additive manufacturing processes, enabling the creation of complex geometries and customized parts with reduced material waste.
- Profile:Extruded or pultruded shapes offer tailored structural properties for construction, automotive frames, and industrial applications.
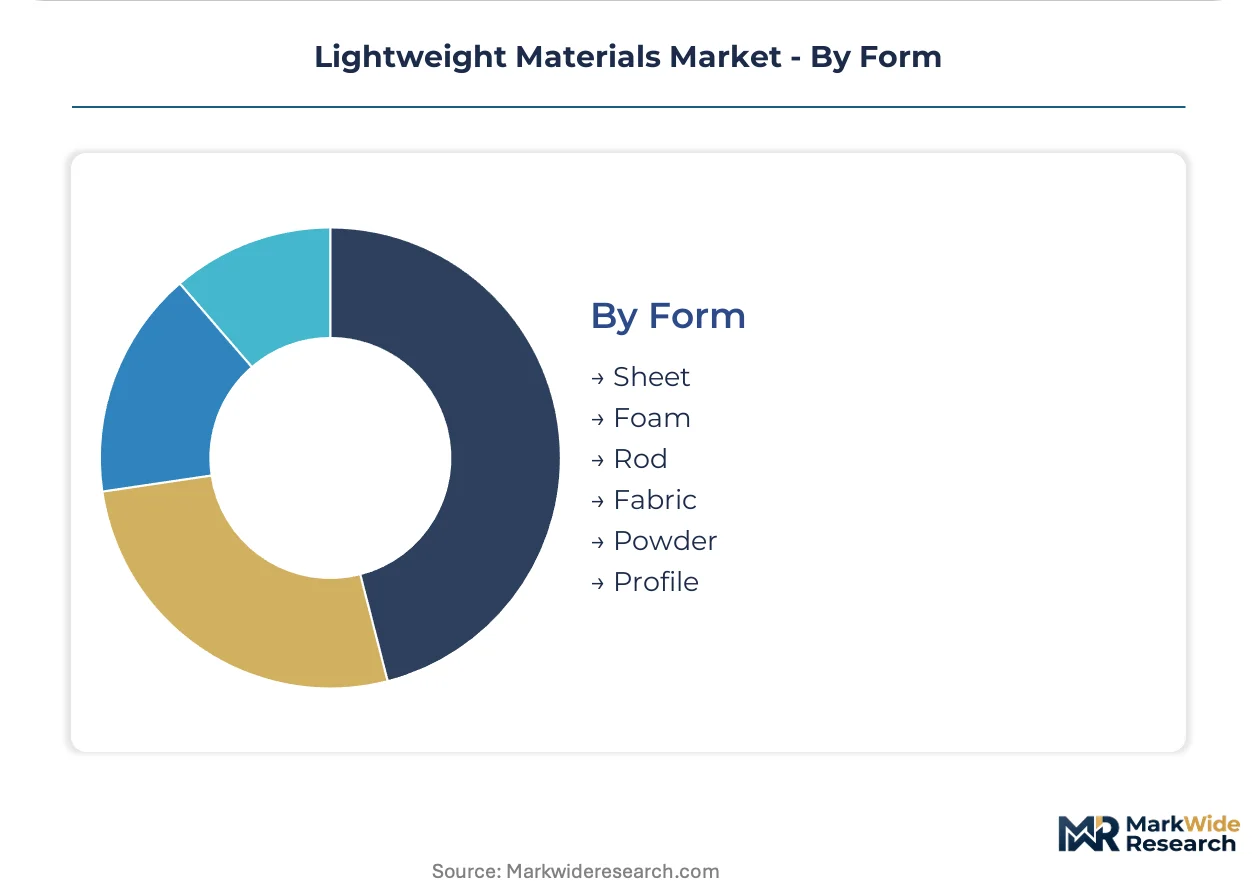
The demand for sheet forms is driven by traditional manufacturing, whereas powder forms enable advanced fabrication techniques.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive raw material production and manufacturing capacity anchors the global lightweight materials market, influencing supply chains and demand patterns worldwide. Regulatory frameworks across key regions are pivotal, driving material selection and innovation in response to emissions targets and energy efficiency mandates. Automotive and aerospace manufacturing hubs globally continue to shape regional demand for advanced lightweight solutions.
China
Automotive electrification and industrial machinery modernization are significant demand drivers for lightweight materials across China. The nation's dual carbon goals provide strong policy incentives for manufacturers to integrate energy-saving materials into production processes. Major EV and industrial manufacturing clusters in the Yangtze River Delta region are actively adopting advanced composites and lightweight alloys.
United States
Aerospace modernization initiatives and stringent vehicle emissions standards propel demand for high-performance lightweight materials in the United States. US EPA regulations for automotive emissions actively push for material substitution to reduce vehicle weight. The aerospace manufacturing hub around Seattle drives innovation and adoption of advanced carbon fiber composites in airframes and engine components.
Germany
High-performance automotive applications and advanced industrial machinery manufacturing fuel the lightweight materials market in Germany. The EU Green Deal and REACH regulation influence material selection, requiring compliance and sustainable solutions for polymers and composites. Bavaria's strong automotive industry and research institutions concentrate demand for specialized lightweight alloys and advanced plastics.
Japan
Consumer electronics and the automotive sector are primary demand sources for lightweight materials in Japan. Policies from METI encourage research and development into advanced materials for energy efficiency and product miniaturization. The Nagoya region, a major automotive production center, focuses on optimizing material use for vehicle performance and fuel economy.
India
The expanding automotive sector and infrastructure development projects create substantial demand for lightweight materials in India. Government initiatives like the PLI scheme for advanced manufacturing support domestic production and material innovation. Automotive manufacturing clusters in Chennai and Pune are adopting lightweight solutions to meet evolving efficiency standards.
Lightweight Materials Market Key Industry Players
Portfolio diversification dominates the current landscape, as material suppliers expand their offerings to serve a broader range of end-use industries and applications. The market exhibits a tiered structure, with large, diversified chemical and metals companies competing alongside specialized composite manufacturers. Strategic partnerships and capacity expansions are common competitive moves, aimed at securing supply chains and developing new material solutions.
Within the specialized materials tier, Hexcel Corporation exemplifies focused expertise in advanced composite technologies, particularly for the demanding aerospace sector. Toray Industries Inc. occupies a position as a scale leader in carbon fiber production, serving diverse end-use industries from aerospace to sports equipment. Solvay, a European-based chemical company, represents a broad portfolio approach, offering a wide array of specialty polymers and composite materials across multiple applications.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Novelis Inc. |
| Toray Industries Inc. |
| SABIC |
| PPG Industries Inc. |
| ArcelorMittal |
| Hexcel Corporation |
| Solvay |
| Evonik Industries |
| Others |
Cost & Logistics Intelligence
EU Green Deal mandates for sustainable manufacturing gate qualified supply and premium-tier pricing access for advanced lightweight materials. This regulatory pressure influences material selection and production strategies, particularly for high-performance applications in Europe.
Pricing Analysis
Warranty and service bundling increasingly differentiate material suppliers, moving beyond basic product specifications. Contract-based long-term offtake agreements dominate pricing for aerospace and high-performance automotive applications. Certification level, such as aerospace-grade qualification, and customization drive price differentiation. Pricing softness affects standard aluminum and glass fiber grades due to increased competition, while premium carbon fiber maintains high prices. Mass-market automotive and consumer electronics manufacturers exhibit the most price sensitivity, whereas aerospace and medical device sectors prioritize performance over cost.
Supply Chain Analysis
China's dual carbon goals and related industrial policies reshape material sourcing, driving localized production and supply chain resilience. Geographic supply concentrates in China for raw materials, the United States for advanced aerospace composites, and Germany for specialized automotive alloys. The industry draws from carbon fiber precursors, specialized resins, and bauxite. Single-source vulnerability for aerospace-grade carbon fiber presents a significant supply chain risk. Distribution runs through direct sales channels for high-performance materials to OEMs, while commodity forms utilize broader distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
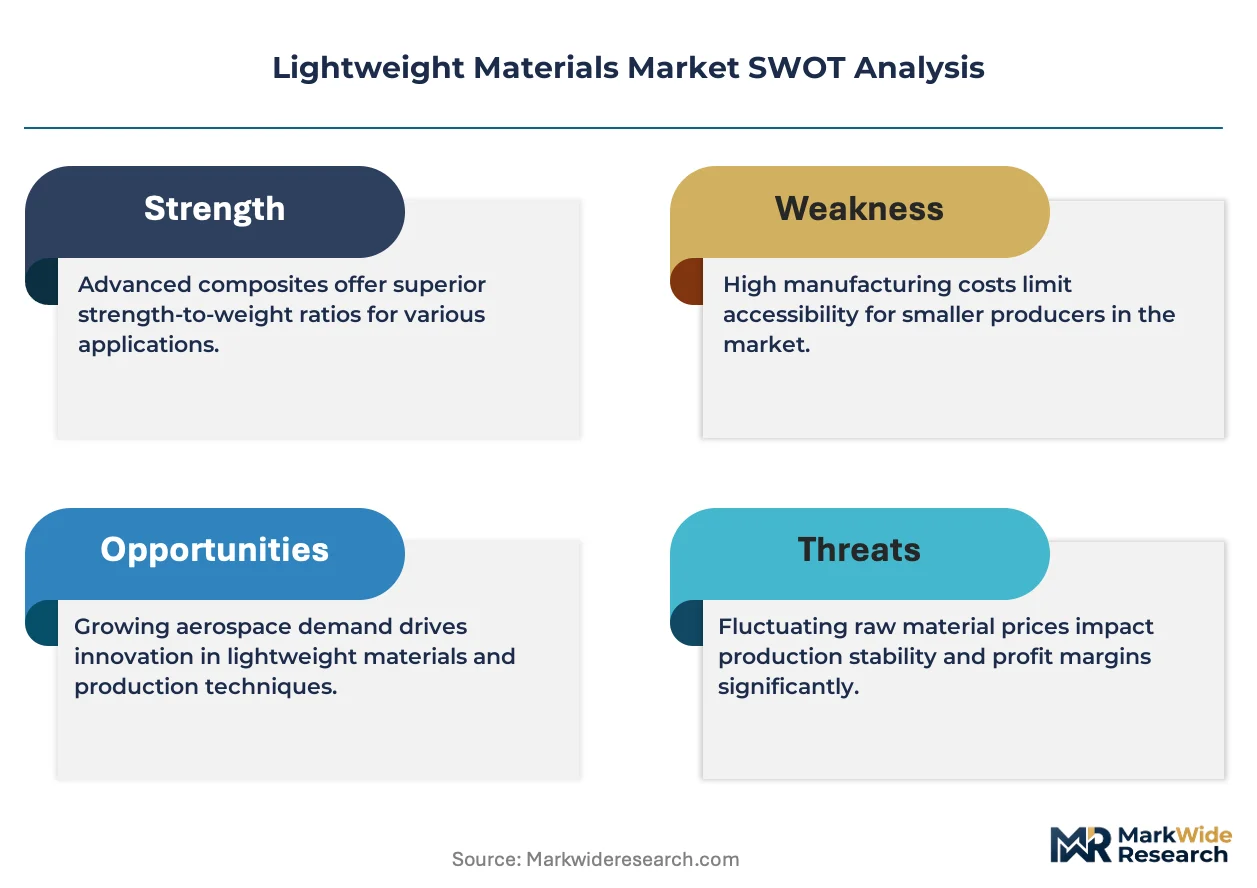
This market operates as a supply-constrained environment, with specialized carbon fiber production capacity acting as a bottleneck propping pricing.
For Market Incumbents:Acquire advanced composite recycling technologies to manage end-of-life challenges and meet circular economy objectives. Invest in capacity additions for high-performance resins in North American aerospace hubs to mitigate geopolitical supply risks. This strategy counters margin pressure from emerging cost-effective alternatives and strengthens compliance with evolving regulatory frameworks like REACH.
For New Entrants and Emerging Players:Capture market share in industrial machinery by offering cost-effective, multi-material solutions tailored for high-volume applications. Target the renewable energy sector with novel glass and carbon fiber composite designs for longer, more durable wind turbine blades. Focus on scalable production methods, such as pultrusion and advanced weaving, to achieve competitive pricing and rapid market penetration.
For Investors and Strategic Acquirers:Increasing M&A activity in composite manufacturing is the leading indicator that consolidation will accelerate across specialized segments. Long-term viability remains strong for mid-cap specialists holding proprietary intellectual property in aerospace and medical-grade materials. Target companies with unique material formulations, such as advanced PEEK polymers, or specialized manufacturing processes that offer high barriers to entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Enlarges production scale for high-demand materials like carbon fiber, meeting growing aerospace and automotive needs. |
| Green Manufacturing Transition | Ensures compliance with environmental regulations and appeals to sustainability-focused automotive and electronics OEMs. |
| Long-term Supply Agreement | Secures stable raw material access for specialized resins and fibers, mitigating commodity price volatility. |
| Joint Venture | Combines expertise in material science with processing technology, accelerating development of new composite solutions. |
| Product Launch | Introduces novel lightweight alloys or composites, opening new application areas in consumer electronics and medical devices. |
Research Approach
Multi-period observation of material consumption rates and regulatory compliance investments anchored the trend analysis, supplemented by interviews with industry stakeholders. This study integrated insights from R&D directors, procurement leads at automotive and aerospace OEMs, material scientists, and regulatory compliance officers. Secondary data sources included EPA emissions reports, EU Green Deal impact assessments, company annual reports, and industry association publications. The research employed both bottom-up and top-down triangulation for data validation.
Segment-weighting across material type, end-use industry, and application formed the core of the quantitative analytical framework. This approach modeled market dynamics across the analysis window, considering various segmentation dimensions including form and regional regulatory intensity. Compound annual growth rates were derived from historical growth trends and projected demand elasticity. Key forecast inputs included electric vehicle production forecasts and aerospace build rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts and raw material price volatility. Forecasts reflect assumptions regarding regulatory enforcement and technological adoption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Stone Plastic Composite Flooring Market
Composite Materials
Global Carbon Graphite Bushings Market
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
Reinforced Plastics Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Fiber Reinforced Polymer (FRP) Panels and Sheets Market
Composite Materials
Aluminum Composite Materials Market
Composite Materials
Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Global FRP Vessels Market
Composite Materials
Wall Cladding Materials Market
Composite Materials
Global Honeycomb Core Materials Market
Composite Materials
Global Thermoplastic Composites Market
Composite Materials
Glass Fiber Reinforced Plastic (GFRP) Market
Composite Materials
Acrylic Laminates Market
Composite Materials
Europe Marine Composites Market
Composite Materials
Europe Composites Market