
 United States Industrial Wood Coatings Market | 2026-2036
United States Industrial Wood Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
United States Industrial Wood Coatings Market Outlook
Asset-light leasing models for spray application equipment are reshaping competitive entry in the United States Industrial Wood Coatings Market, allowing mid-sized woodworking shops to access high-performance coating systems without capital-intensive ownership. PPG Industries Inc. leverages its broad distribution network to sustain national coverage across furniture and cabinetry clusters. The Sherwin Williams Company anchors its position through vertical integration into resin supply and dedicated wood coatings R&D facilities. RPM International Inc. specializes in niche protective formulations for flooring applications where abrasion resistance commands premium positioning.
United States Industrial Wood Coatings comprise formulated film-building materials—typically alkyd, polyurethane, acrylic, or nitrocellulose resins dissolved or dispersed in water, solvent, or 100% solids UV-curable systems—applied to wood substrates to provide moisture barrier, aesthetic enhancement, and mechanical protection in industrial manufacturing environments. Water-based technology leads volume growth as EPA VOC regulations tighten permissible solvent emissions in production facilities. UV-cured systems occupy the fastest-expanding margin pool, offering instant cure and line-speed advantages for high-throughput furniture OEMs. Solvent-based coatings still dominate legacy musical instrument finishing where depth and rub-out aesthetics remain non-negotiable specifications.
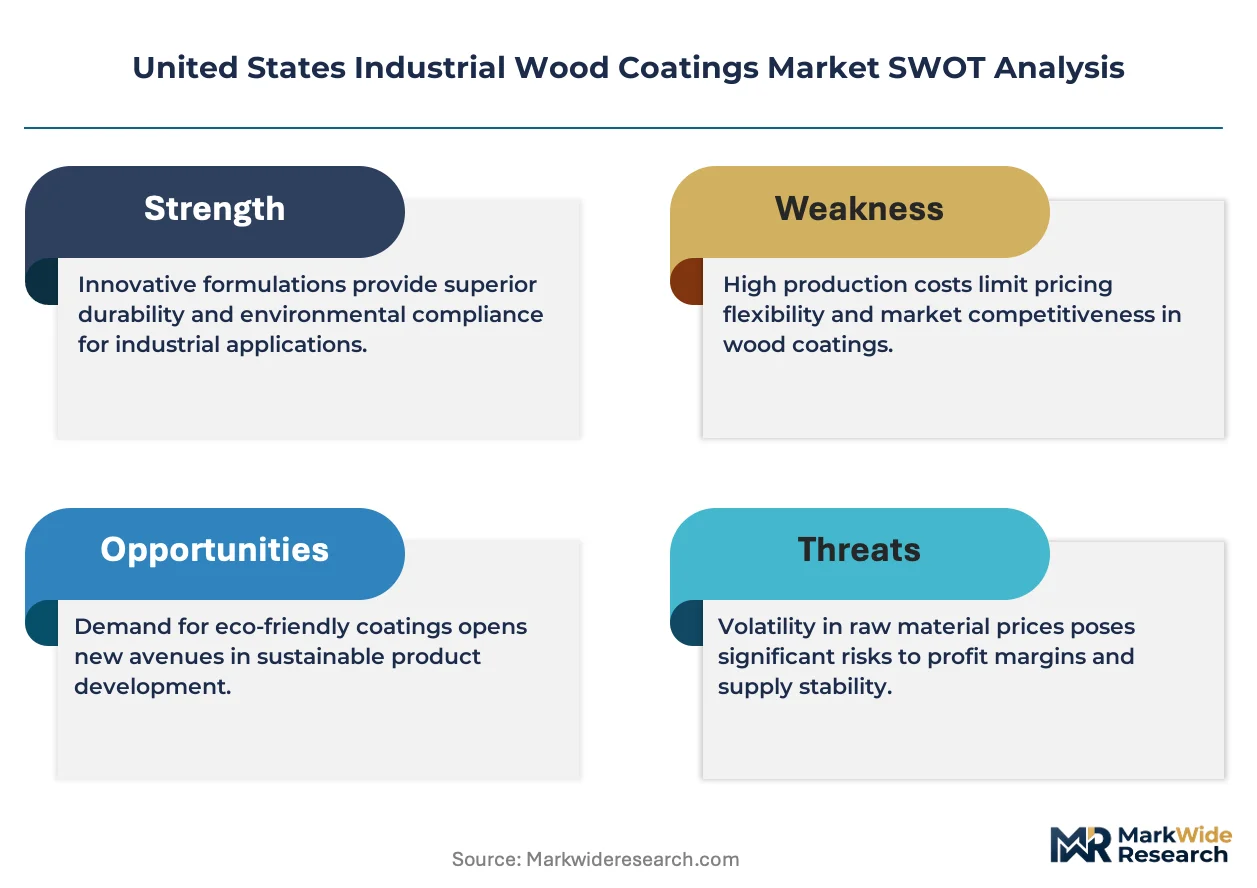
EPA VOC regulations, OSHA workplace exposure limits, and state-level air quality mandates in California and the Northeast shape product formulation decisions and manufacturing site compliance investments across the value chain. The FDA's indirect food contact guidelines influence coatings deployed on kitchen cabinetry and food-service furniture surfaces. Stakeholders must monitor emerging PFAS restrictions and bio-based content mandates that could force reformulation cycles before the next capital planning horizon.
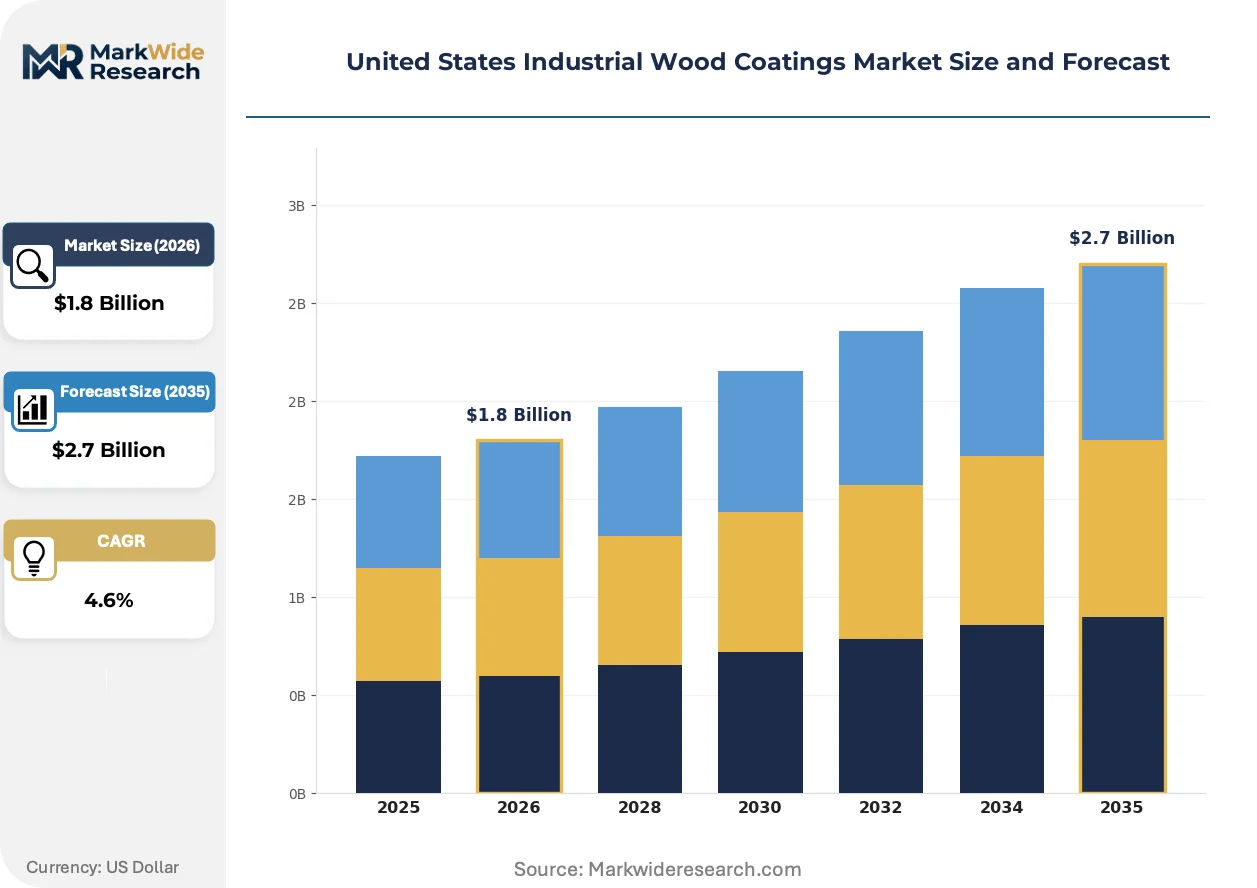
Market Dynamics
EPA VOC regulations are compressing solvent-based coating demand while water-based and UV-curable technologies capture incremental volume in furniture manufacturing clusters across Georgia and North Carolina.
Growth Catalysts
- EPA VOC compliance mandates:Tightening emission limits in production facilities accelerate water-based formulation adoption by furniture OEMs seeking permit certainty.
- UV-curable line-speed advantages:High-throughput furniture manufacturers deploy instant-cure systems to eliminate drying bottlenecks and reduce WIP inventory.
- Southeast manufacturing corridor concentration:Georgia and North Carolina wood products clusters generate localized demand density that supports dedicated distribution infrastructure.
Market Restraints
- Titanium dioxide and acrylic resin cost volatility:Raw material price swings compress margin stability for formulators serving price-sensitive cabinetry segments.
- Technical performance gaps in water-based systems:Solvent-based coatings retain irreplaceable rub-out depth specifications in musical instrument finishing applications.
- California Air Resources Board (CARB) fragmentation:State-level emission standards exceed federal baselines, forcing dual-formulation inventories and compliance complexity.
Strategic Opportunities
- PFAS-free formulation white space:Anticipated EPA restrictions on per- and polyfluoroalkyl substances create first-mover advantage for compliant kitchen cabinetry coatings.
- Asset-light spray equipment leasing:Mid-sized woodworking shops access high-performance application systems without capital ownership, expanding addressable customer base.
- Bio-based resin convergence:Integration of renewable feedstocks with existing acrylic and alkyd chemistries addresses emerging sustainability procurement criteria.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in water-based resin compatibility and UV photoinitiator selection commands premium compensation and extended hiring cycles.
- Dual-cure system integration complexity:Hybrid UV-thermal processes require retrofitting legacy finishing lines with synchronized conveyor and lamp arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Industrial Wood Coatings Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stains, Varnishes, Sealers, Lacquers Application: Furniture, Flooring, Cabinetry, Musical Instruments End User: Woodworking Shops, Furniture Manufacturers, OEMs, Contractors Technology: Water-Based, Solvent-Based, UV-Cured, Electrostatic |
| Companies Covered | The Sherwin Williams Company, PPG Industries Inc., Akzo Nobel N.V., Axalta Coating Systems, RPM International Inc., BASF SE, Jotun, Hempel A/S, Teknos Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Industrial Wood Coatings Market Strategic Shifts
Formulation chemistry is pivoting toward instant-cure and low-emission platforms while application equipment models and buyer procurement patterns undergo parallel restructuring.
UV-curable wood coating technology delivers instantaneous polymerization through photoinitiator activation under high-intensity lamp arrays. Furniture OEMs in North Carolina and Virginia deploy these systems to compress finishing cycle times from hours to seconds. Demand is migrating from conventional thermal-cure alkyd and polyurethane lines toward UV-capable installations that eliminate drying rack footprint and reduce energy consumption.
EPA National Emission Standards for Hazardous Air Pollutants (NESHAP) for wood furniture manufacturing operations mandate Maximum Achievable Control Technology (MACT) compliance for coating application and drying. Facilities in the Southeast manufacturing corridor invest in thermal oxidizers and carbon adsorption systems to meet residual solvent limits. Water-based primer and topcoat formulations capture volume in kitchen cabinetry production where FDA indirect food contact guidelines apply.
Furniture manufacturers are consolidating coating procurement through direct mill relationships rather than distributor intermediaries. Large-scale OEMs in Georgia negotiate formulation customization and dedicated technical service support in exchange for volume commitments. This pattern concentrates in solid wood and engineered wood panel segments where finish consistency across batch runs determines rejection rates and warranty exposure.
United States Industrial Wood Coatings Market Segmentation
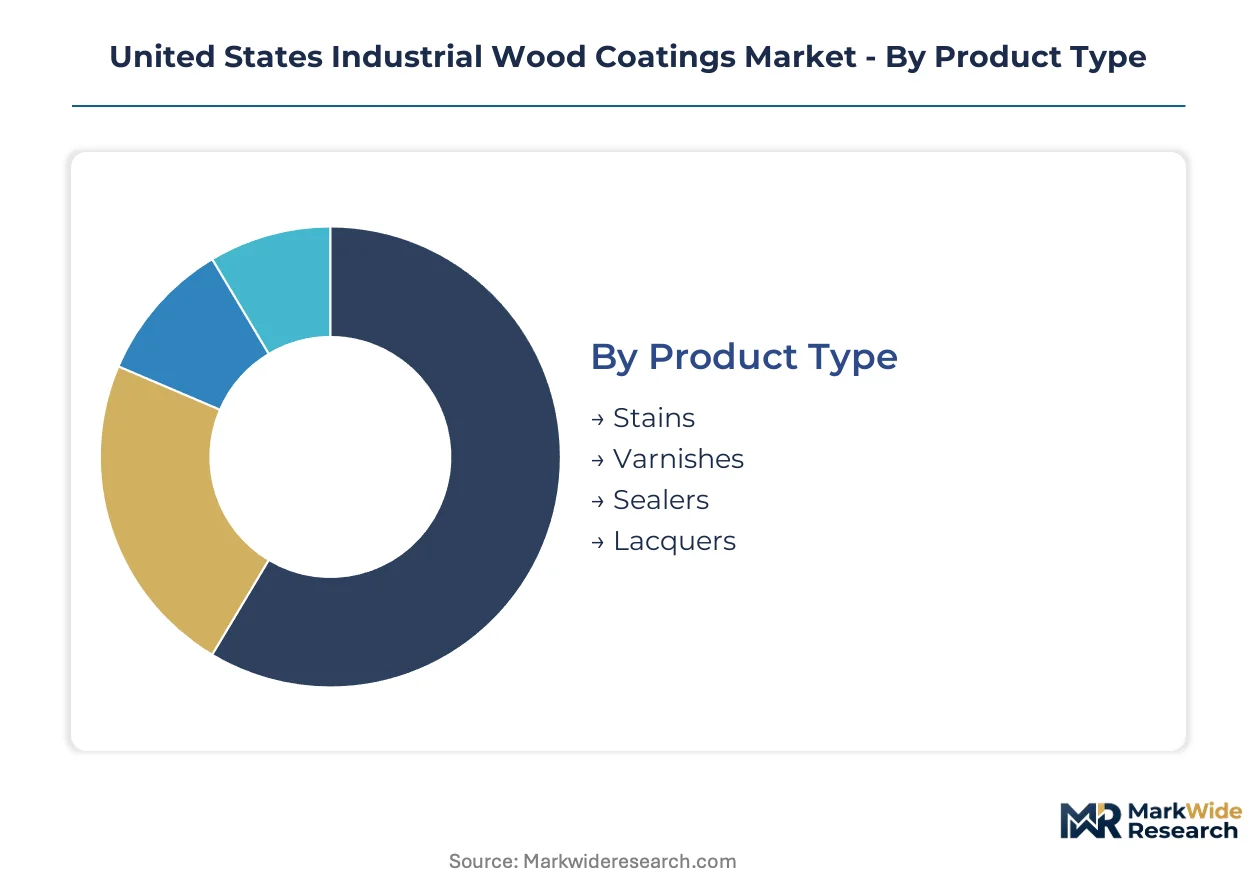
Industrial wood coatings in the United States fragment across multiple dimensions that determine formulation chemistry, application equipment, and distribution channel design. Understanding these segment boundaries clarifies where technology transitions concentrate and where legacy specifications persist.
Product Type:
Mature film-building categories coexist with emerging protective systems as furniture OEMs balance aesthetic depth against throughput requirements.
- Stains:Penetrating colorants that enhance wood grain visibility without obscuring substrate texture. Demand clusters in high-end residential furniture manufacturing across North Carolina where designers specify open-grain appearances.
- Varnishes:Oil-modified urethane or alkyd resin films providing moisture barrier and gloss control. Musical instrument finishing in Tennessee and Kentucky maintains solvent-borne varnish specifications for rub-out depth that water-based alternatives cannot replicate.
- Sealers:Low-solids barrier coats that prevent tannin bleed and raise grain before topcoating. Kitchen cabinetry producers in Georgia deploy water-based sealers to meet EPA VOC compliance without sacrificing production line compatibility.
- Lacquers:Rapid-drying nitrocellulose or acrylic systems enabling same-day sanding and recoating. Custom woodworking shops in the Northeast retain lacquer preference for repairability and hand-rubbed finish restoration.
Varnishes retain volume leadership in legacy musical instrument and premium furniture segments; sealers hold the steepest expansion curve as water-based formulations displace solvent-borne primers in cabinetry production.
Application:
End-use differentiation drives specification divergence between mass-production environments and craft-scale finishing operations.
- Furniture:Residential and commercial seating, tables, and case goods requiring balanced aesthetic and mechanical performance. North Carolina and Virginia furniture clusters generate concentrated demand for UV-curable systems that eliminate drying rack constraints.
- Flooring:Hardwood and engineered plank surfaces demanding abrasion resistance and chemical spill protection. Premium flooring manufacturers specify aluminum oxide-enhanced polyurethane coatings where wear layer durability determines warranty terms.
- Cabinetry:Kitchen, bath, and built-in storage products subject to FDA indirect food contact guidelines. Southeast cabinetry OEMs consolidate procurement through direct mill relationships to secure formulation customization and batch consistency.
- Musical Instruments:Guitars, pianos, and orchestral woodwheels where finish acoustics and visual depth carry brand equity. Nashville and Southern California instrument makers enforce solvent-based lacquer specifications that resist water-based substitution.
Furniture commands the largest addressable base across industrial coating volumes; cabinetry is climbing the fastest as kitchen remodeling activity and new residential construction drive specification upgrades.
End User:
Customer scale determines whether coating procurement flows through distribution intermediaries or direct manufacturer relationships.
- Woodworking Shops:Small-to-mid-scale custom fabricators serving local residential and commercial projects. Asset-light spray equipment leasing models expand high-performance system access without capital ownership burdens.
- Furniture Manufacturers:Large-scale OEMs producing standardized lines for retail and contract channels. Georgia-based producers negotiate dedicated technical service support in exchange for volume formulation commitments.
- OEMs:Original equipment manufacturers integrating coated components into broader product assemblies. Flooring and cabinetry OEMs drive water-based adoption through sustainability procurement criteria and permit certainty requirements.
- Contractors:On-site finishing specialists serving renovation and repair markets. Field application constraints sustain solvent-based demand where ambient temperature and humidity variability complicate water-based curing.
Furniture Manufacturers dominate procurement volume through consolidated mill-direct relationships; Woodworking Shops are gaining share fastest as leasing models democratize advanced spray system access.
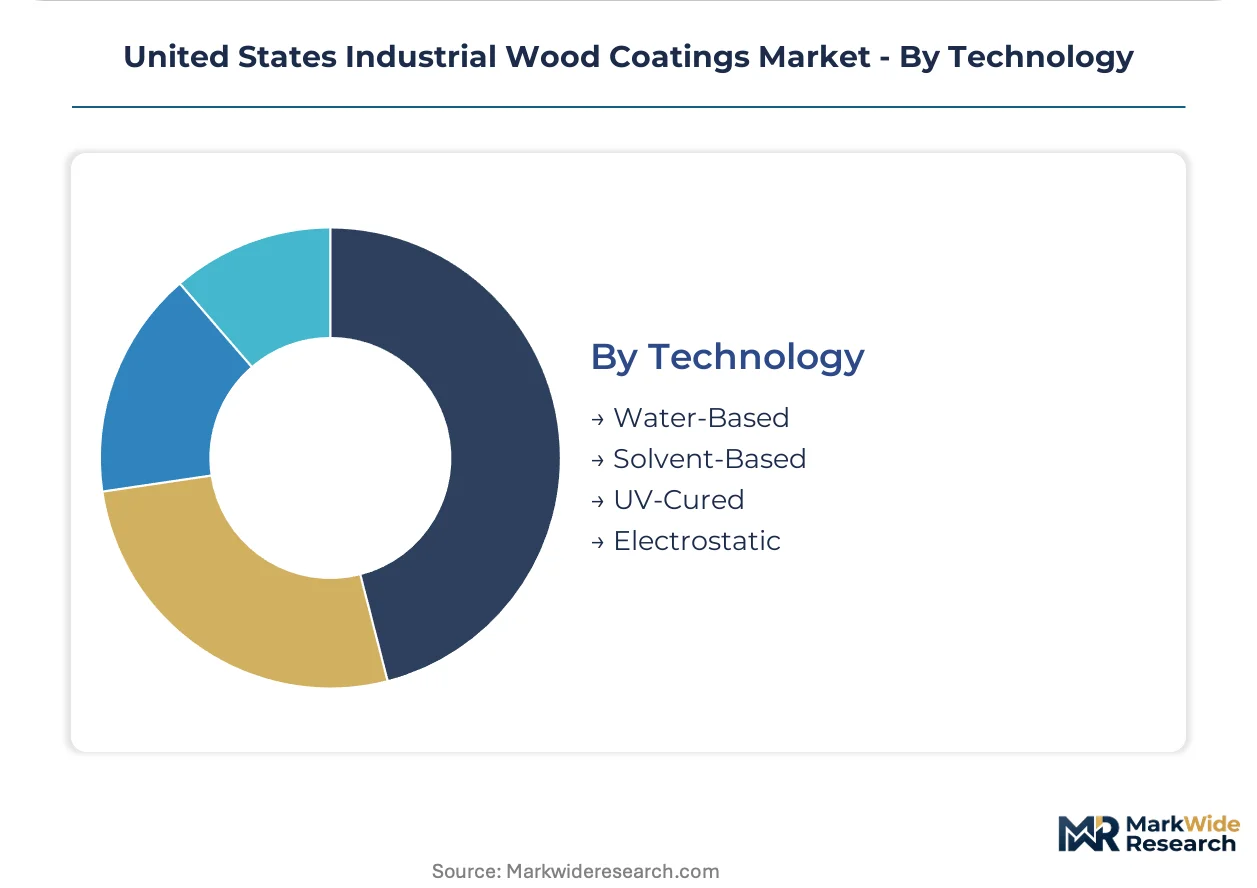
Technology:
Regulatory pressure and line-speed economics are restructuring the technology mix across production environments.
- Water-Based:Acrylic and polyurethane dispersions with VOC content below EPA NESHAP thresholds. Cabinetry and furniture OEMs in the Southeast manufacturing corridor deploy these systems to secure air quality permit renewals without thermal oxidizer investments.
- Solvent-Based:Traditional alkyd, nitrocellulose, and polyurethane solutions in hydrocarbon or oxygenated solvent blends. Musical instrument finishing and certain high-gloss cabinetry applications retain solvent specifications where water-based alternatives exhibit insufficient flow-and-leveling.
- UV-Cured:100% solids formulations polymerizing instantly under high-intensity lamp arrays. High-throughput furniture producers in North Carolina eliminate work-in-process inventory and reduce finishing line footprint through sub-second cure cycles.
- Electrostatic:Charged particle application systems maximizing transfer efficiency on conductive substrates. Limited penetration in wood coatings due to substrate resistivity challenges, with niche adoption in metalized or conductive-primed engineered panels.
Solvent-Based coatings retain residual volume in specification-sensitive finishing segments; UV-Cured systems are expanding most quickly as furniture OEMs prioritize line-speed optimization and energy cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA VOC regulations and state-level air quality mandates are redistributing production capacity toward jurisdictions with clearer permitting pathways. Furniture and cabinetry manufacturers cluster in states offering regulatory certainty combined with established hardwood supply chains.
Southeast Manufacturing Corridor
Georgia and North Carolina anchor the nation's densest concentration of wood furniture and cabinet production. EPA NESHAP compliance investments dominate capital allocation decisions as facilities upgrade thermal oxidizers and carbon adsorption systems. High Point, North Carolina maintains its position as the center of residential furniture finishing where UV-curable systems eliminate drying bottlenecks.
California
CARB emission standards exceed federal EPA baselines, forcing dual-formulation inventories for suppliers serving the state. Kitchen cabinetry producers in the Central Valley deploy water-based sealers and topcoats to meet indirect food contact guidelines under FDA oversight. Los Angeles and Orange County manufacturing zones concentrate on premium architectural millwork where sustainability procurement criteria drive bio-based resin adoption.
Northeast
New York and Pennsylvania custom woodworking shops sustain solvent-based lacquer demand for repairable hand-rubbed finishes. OSHA workplace exposure limits shape spray booth ventilation investments across Connecticut and Massachusetts. Rochester, New York hosts specialty musical instrument finishing operations where nitrocellulose specifications remain non-negotiable for acoustic properties.
Tennessee and Kentucky
Nashville's musical instrument cluster enforces solvent-borne varnish specifications for tonal depth and visual aesthetics that water-based alternatives cannot replicate. Kentucky hardwood flooring manufacturers specify aluminum oxide-enhanced polyurethane coatings where abrasion resistance determines warranty coverage. EPA compliance timelines vary across state lines, creating fragmented formulation requirements for regional suppliers.
Pacific Northwest
Oregon and Washington timber processing infrastructure supports engineered wood panel production with specialized coating requirements for moisture resistance. Seattle-area architectural millwork shops serve commercial construction markets with custom stain and sealer specifications. State environmental agencies coordinate with EPA regional offices on permitting timelines that lag behind Southeast corridor efficiency.
United States Industrial Wood Coatings Market Competitive Environment
On the supply side, the industry is consolidating around integrated coating-resin systems and dedicated distribution infrastructure. Tiered competitive positioning separates national formulators with captive R&D facilities from regional specialists serving niche abrasion-resistant or food-contact applications. Strategic archetypes include vertically integrated resin producers, application equipment bundlers, and sustainability-certified formulation houses. Dominant competitive moves encompass backward integration into raw material supply and geographic densification through dedicated technical service teams.
Within the integrated formulation tier, The Sherwin Williams Company and PPG Industries Inc. exemplify scale-driven competitors with national distribution networks. RPM International Inc. occupies a specialist position focused on protective systems for flooring applications. These three anchors demonstrate how coating suppliers differentiate through supply chain control and segment-specific technical service depth rather than commodity pricing alone.
| Leading Market Players |
|---|
| The Sherwin Williams Company |
| PPG Industries Inc. |
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| RPM International Inc. |
| BASF SE |
| Jotun |
| Hempel A/S |
| Teknos Group |
| Others |
Value Chain & Pricing Dynamics
The I-85 freight corridor linking Georgia resin suppliers to North Carolina furniture manufacturers concentrates logistics cost exposure, amplifying pricing power for integrated formulators while compressing margins for distributors serving price-sensitive cabinetry OEMs.
Pricing Analysis
Certification level (FDA indirect food contact compliance) creates the primary spread between premium kitchen cabinetry coatings and standard furniture-grade formulations. Pricing stratifies across premium, standard, and economy tiers based on VOC compliance tier and volume commitment scale. Cost compression in water-based resin feedstocks is intensifying because titanium dioxide and acrylic monomer volatility persists. Small woodworking shops exhibit highest price sensitivity, while large furniture OEMs with dedicated mill relationships absorb premium pricing for batch consistency guarantees.
Supply Chain Analysis
Upstream acrylic and polyurethane resin production draws from Texas petrochemical corridors and Ohio specialty chemical clusters, with photoinitiator supply anchored in Chinese and German manufacturing bases. Titanium dioxide pigment sources from Mississippi sulfate-process facilities and imported chloride-grade material. Single-source vulnerability concentrates in UV photoinitiator supply where two German suppliers dominate global output. Distribution runs through manufacturer-direct channels for large OEMs and regional distributor networks serving mid-scale woodworking operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist expertise in water-based resin compatibility and UV photoinitiator selection has become the constraining asset, with hiring cycles extending and compensation premiums widening the competitive moat for incumbents with captive technical talent.
For Market Incumbents: Insulate margin position through backward integration into alkyd resin production and captive UV photoinitiator blending capacity in the Southeast corridor. Lock in multi-year supply agreements with Georgia and North Carolina furniture OEMs before PFAS-free formulation mandates accelerate. Prioritize certification investment for FDA indirect food contact compliance to capture cabinetry specification upgrades.
For New Entrants and Emerging Players: Build out asset-light spray equipment leasing operations targeting mid-scale woodworking shops in Tennessee and Kentucky, where capital constraints limit high-performance system adoption. Penetrate the musical instrument finishing segment in Nashville where solvent-based varnish specifications resist substitution and incumbent technical service coverage remains thin. Deploy direct technical sales teams rather than distributor intermediaries to secure formulation customization relationships.
For Investors and Strategic Acquirers: Regional specialists with EPA NESHAP-compliant water-based formulation capabilities and established Southeast distribution infrastructure represent the highest-conviction acquisition archetype. Long-term viability hinges on defensible regulatory compliance positions rather than commodity scale. Watch for CARB-aligned state adoption timelines as the inflection signal for PFAS-free formulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive alkyd and acrylic production secures margin control against titanium dioxide volatility. |
| PFAS-Free Formulation Development | Anticipated EPA restrictions create first-mover positioning in kitchen cabinetry coatings. |
| Asset-Light Equipment Leasing Model | Expands addressable base to mid-sized woodworking shops without capital ownership barriers. |
| Direct Mill Technical Service Teams | Dedicated Georgia and North Carolina presence secures furniture OEM volume commitments. |
| UV-Curable Line Retrofit Partnerships | Eliminates drying bottlenecks for high-throughput manufacturers in the Southeast corridor. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA NESHAP compliance filings, American Coatings Association technical bulletins, and SEC 10-K disclosures from publicly traded formulators. Primary interviews engaged coating application engineers at North Carolina furniture OEMs, procurement directors at Georgia cabinetry manufacturers, distribution channel managers in the Southeast, and formulation R&D leads at integrated resin producers. Bottom-up volume estimates derived from production capacity and line-speed assumptions triangulate against top-down market sizing from customs trade data and industry association shipment reports.
Forecast inputs incorporate resin price indices, EPA regulatory timeline probabilities, and furniture production forecasts across the analysis window. Segmentation modeling covers product chemistry, application end-use, technology platform, and customer scale tier. CAGRs reflect slope analysis of historical adoption curves for water-based and UV-curable technologies, adjusted for regulatory compliance acceleration scenarios. Industry-specific inputs include thermal oxidizer installation rates and spray equipment leasing penetration assumptions.
Sensitivities concentrate around titanium dioxide cost trajectories, PFAS restriction implementation timelines, and UV photoinitiator supply disruptions. Forecasts reflect documented assumptions about regulatory enforcement consistency and furniture OEM capital expenditure cycles. Cross-checking against American Coatings Association market bulletins and EPA compliance database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Plastic Coatings Market
Coatings
Camouflage Coatings Market
Coatings
Packaging Coatings Market
Coatings
Wood Preservative Coatings Market
Coatings
Coating Pre-Treatment Market
Coatings
Antimicrobial Coil Coating Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Canada Industrial Wood Coatings Market
Coatings
Marine Anti Fouling Coatings Market
Coatings
Silicate Coatings Market
Coatings
Wire Enamels Market
Coatings
Global Water-Based Coatings Market
Coatings
Dispersion Coating Market
Coatings
Chemical Resistant Coatings Market
Coatings
Anti-Friction Coatings Market
Coatings
Conductive Polymer Coatings Market