
 Europe Marine Composites Market | 2026-2036
Europe Marine Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Marine Composites Market Intelligence
Multi-source resin procurement is realigning supply security strategies across European boatyards. Gurit AG leverages its Swiss prepreg manufacturing base to sustain consistent deliveries to Nordic shipbuilders. Owens Corning anchors the fiberglass segment through its broad E-glass product range serving mass-market craft producers. Solvay SA differentiates via high-performance thermoplastic composites targeting military and superyacht applications.
Europe marine composites encompass fiber-reinforced polymer systems combining glass, carbon, or aramid fibers with epoxy, polyester, or vinyl ester matrices, cured through vacuum infusion, prepreg lamination, or resin transfer molding to achieve specific strength-to-weight ratios and corrosion resistance for saltwater environments. Fiberglass dominates volume across recreational craft and commercial hull production due to established tooling economics and repair familiarity. Carbon fiber commands premium positioning in yacht construction and military vessels where stiffness and weight reduction justify material costs. Hybrid composites are gaining traction in offshore platforms seeking balanced performance across fatigue resistance and impact tolerance.
REACH compliance through ECHA governs chemical inputs across the supply chain, while the EU Green Deal's maritime emissions framework incentivizes lightweight hull designs that reduce fuel consumption. CE marking requirements under the EU's recreational craft directive establish structural performance benchmarks that composite manufacturers must validate through notified body certification. Stakeholders should monitor evolving MDR-aligned material traceability rules and the F-Gas Regulation's potential extension to foam core blowing agents used in sandwich construction.
Market Dynamics
The EU Green Deal's maritime emissions framework is compressing design cycles across European shipyards as lightweight hull mandates force rapid substitution of conventional metals with fiber-reinforced polymer systems.
Growth Catalysts
- Regulatory stringency:The EU Green Deal's emissions targets for maritime transport mandate fuel efficiency gains that only composite hull architectures can deliver at scale.
- Superyacht construction:Italian and Dutch builders are expanding carbon fiber hull orders as ultra-high-net-worth buyers demand extended range and reduced operating costs.
- Material substitution:Epoxy-infused glass fiber systems are displacing aluminum in commercial workboats across Mediterranean ferry operators seeking corrosion resistance.
Market Restraints
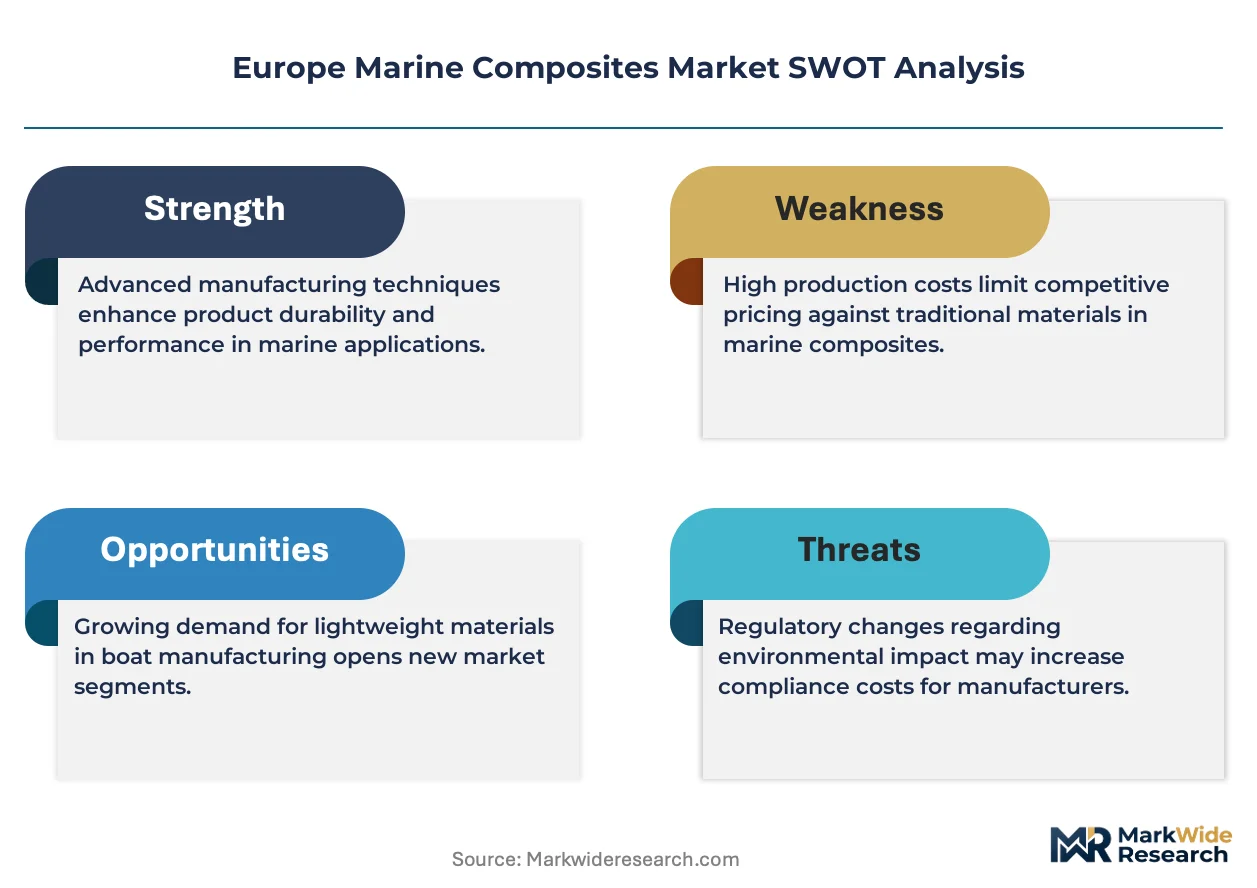
- Carbon fiber cost volatility:Aerospace sector competition for polyacrylonitrile precursor keeps marine-grade carbon fiber pricing structurally elevated.
- Prepreg supply concentration:Swiss and German autoclave-capable prepreg manufacturers control critical supply nodes for superyacht lamination.
- REACH compliance friction:ECHA substance authorization requirements for epoxy hardeners extend formulation validation timelines by 18-24 months.
Strategic Opportunities
- Eastern Mediterranean expansion:Greek and Turkish shipyards remain underpenetrated for vacuum-infused composite production relative to Italian and French clusters.
- Offshore wind service vessels:Crew transfer vessels for North Sea wind farms require hybrid glass-carbon sandwich structures optimized for impact tolerance.
- CE marking acceleration:Notified body pre-certification partnerships can compress time-to-market for novel core materials in recreational craft.
Industry Challenges
- Laminator skill scarcity:Vacuum infusion and prepreg layup expertise concentrates in aging workforces along the Italian Riviera and Dutch Flevoland.
- Tooling capex intensity:Female mold fabrication for hull series production requires seven-figure capital commitments before first delivery.
- MDR traceability alignment:Medical device-grade material tracking requirements are bleeding into marine composite documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Marine Composites Market |
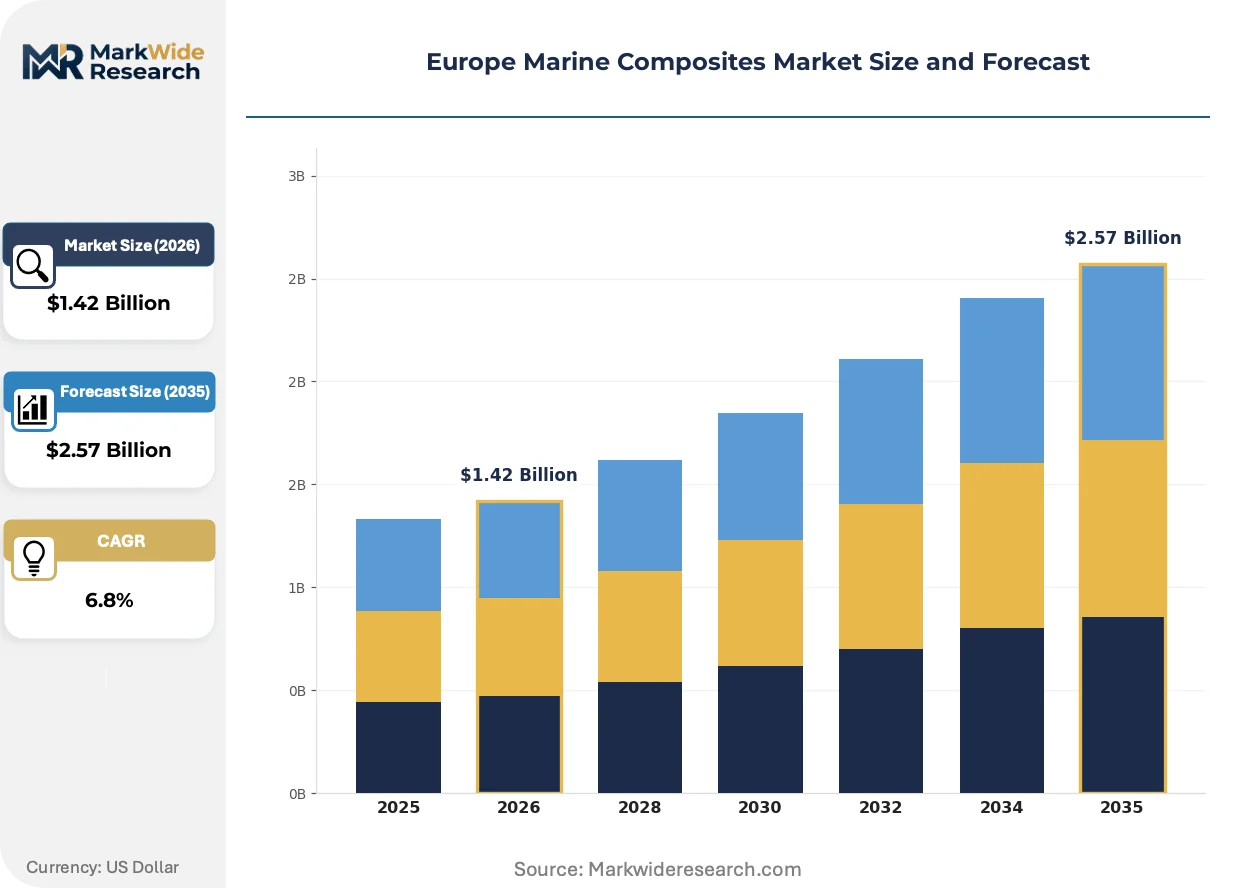
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Carbon Fiber, Aramid Fiber, Hybrid Composites Application: Boat Manufacturing, Yacht Construction, Offshore Platforms, Recreational Craft End User: Marine Industry, Recreational Users, Commercial Shipping, Military Sector Installation: In-Field, Factory-Built, Retrofit, Custom Solutions |
| Companies Covered | Toray Industries, Inc., Owens Corning, Hexcel Corporation, Gurit AG, SGL Carbon SE, Huntsman International LLC, Solvay SA, Compagnie de Saint-Gobain S.A., Teijin Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Marine Composites Market Strategic Shifts & Innovations
Material science advances and regulatory compression are forcing convergence between thermoset legacy systems and thermoplastic processability across European marine manufacturing.
Thermoplastic composite tapes are converging with automated fiber placement systems to enable welded hull joints without adhesive curing cycles. Dutch superyacht builders are piloting these systems for interior structural elements where fire regulation compliance is critical. This convergence is compressing hull module assembly time by eliminating climate-controlled layup environments.
The F-Gas Regulation's extension to hydrofluorocarbon blowing agents is forcing sandwich core manufacturers toward bio-based alternatives. ECHA enforcement timelines have compressed reformulation windows to 36 months for established suppliers. Nordic shipbuilders dependent on polyurethane cores are accelerating qualification of cork and recycled PET foam substitutes.
Buyer consortiums among Mediterranean charter operators are consolidating hull procurement into multi-year framework agreements. These contracts specify performance warranties rather than material grades, transferring laminate design risk to builders. French Côte d'Azur and Croatian Adriatic clusters show the highest concentration of this specification inversion.
Europe Marine Composites Market Segmentation
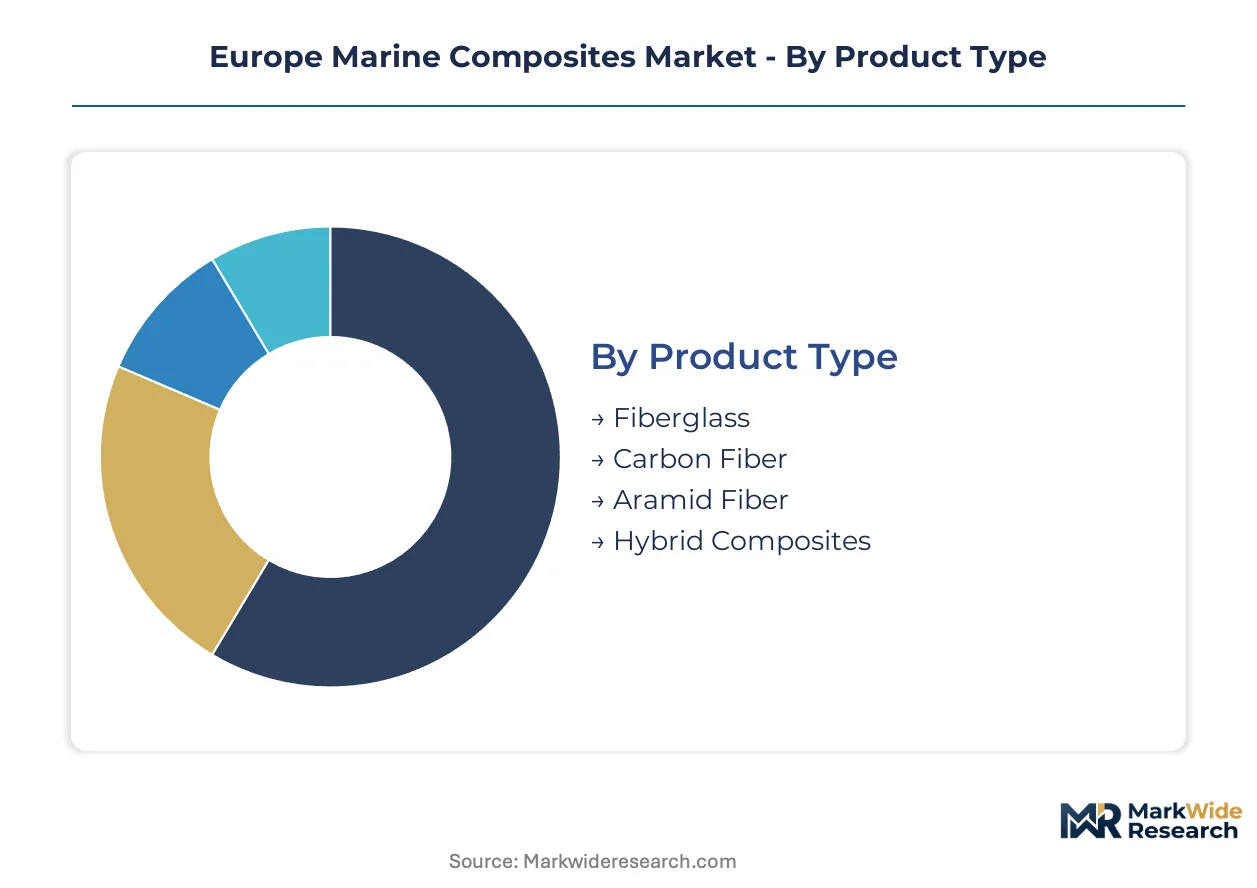
Segmentation in Europe marine composites reflects divergent capital requirements across fiber systems, application engineering, and installation modalities. Builders align procurement with hull performance specifications, regulatory compliance burdens, and series production economics rather than material cost alone.
Product Type:
Carbon fiber and hybrid composite systems demand the heaviest upfront tooling investment, while fiberglass leverages depreciated infrastructure across Mediterranean boatyards.
- Carbon Fiber:Polyacrylonitrile precursor-based systems deliver exceptional stiffness-to-weight ratios for superyacht hull structures. Dutch and Italian builders dominate procurement as ultra-high-net-worth buyers prioritize range extension over acquisition cost.
- Fiberglass:E-glass reinforced polymer systems anchor volume production across recreational craft and commercial workboats. Established tooling economics and repair familiarity sustain dominance in French Côte d'Azur and Croatian Adriatic clusters.
- Aramid Fiber:Kevlar-based reinforcements serve military and high-impact applications requiring ballistic tolerance.
- Hybrid Composites:Glass-carbon combinations balance fatigue resistance with cost containment in offshore platform decking.
Most installed capacity flows through fiberglass. Expansion is steepest in carbon fiber.
Application:
Volume concentrates in recreational craft where standardized hull molds amortize across production runs, while yacht construction absorbs premium fiber grades at lower unit velocity.
- Yacht Construction:Custom superyacht lamination requires climate-controlled prepreg facilities and autoclave-capable supply chains. Italian Riviera builders command premium positioning through carbon fiber hull integration.
- Boat Manufacturing:Series production of recreational vessels exploits vacuum infusion economies across Nordic and Mediterranean yards. CE marking compliance under the EU recreational craft directive shapes laminate validation protocols.
- Offshore Platforms:Corrosion-resistant decking and structural modules serve North Sea energy infrastructure.
- Recreational Craft:Mass-market kayaks, sailboats, and personal watercraft consume commodity fiberglass volumes.
Yacht construction commands the highest margin per kilogram. Boat manufacturing delivers the steepest volume trajectory.
End User:
Procurement authority separates consolidated military buyers from fragmented recreational consumers, with commercial shipping operators occupying an intermediate negotiation position.
- Marine Industry:Integrated shipyards and OEMs specify laminate architectures across hull, deck, and superstructure applications. REACH compliance through ECHA governs resin formulation selections.
- Commercial Shipping:Ferry operators and cargo vessel owners prioritize fuel efficiency gains from lightweight composite superstructures. Mediterranean operators lead aluminum-to-composite substitution.
- Military Sector:Stealth and ballistic requirements drive aramid and carbon fiber demand for patrol craft.
- Recreational Users:Individual buyers influence aftermarket repair specifications rather than primary laminate design.
The marine industry concentrates the most technical specification authority. Commercial shipping is gaining share fastest on emissions compliance urgency.
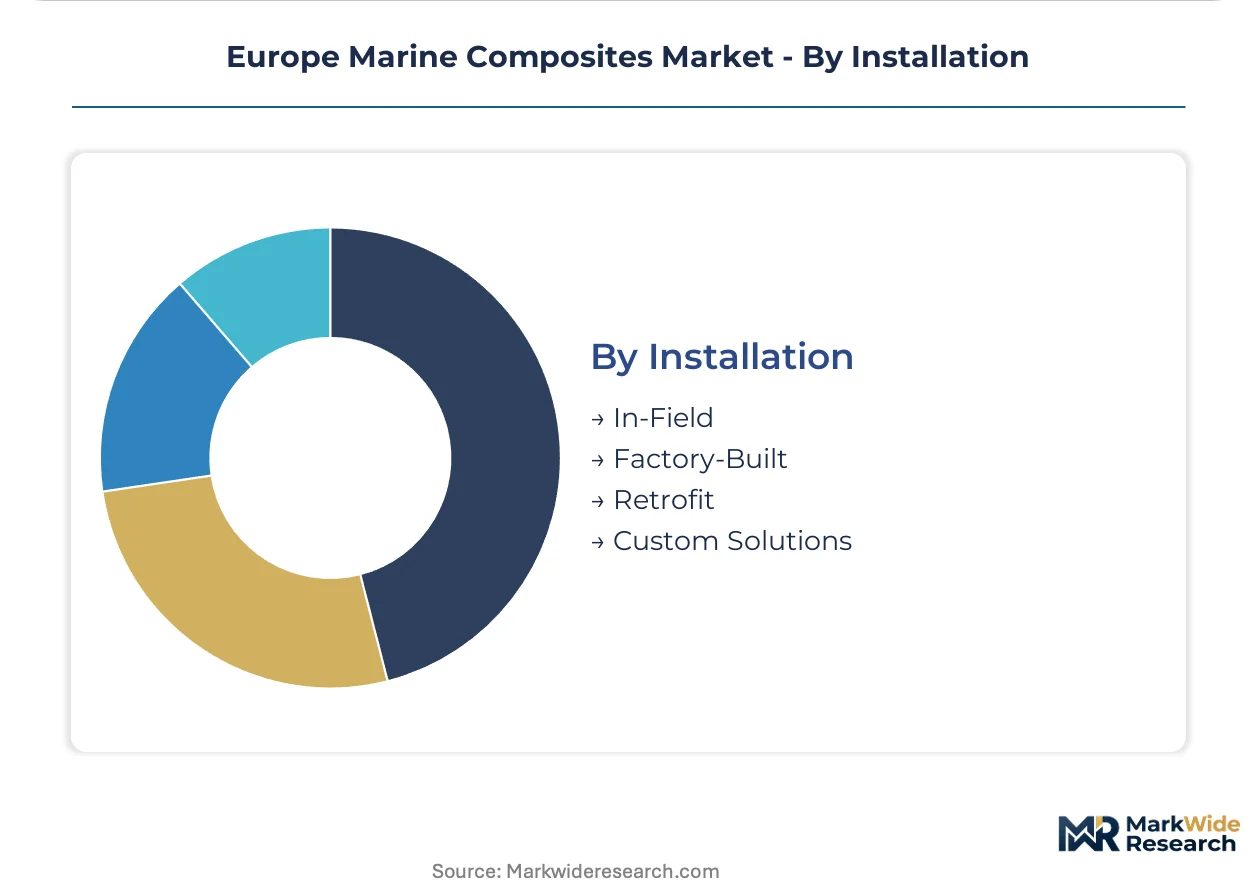
Installation:
Factory-built systems dominate where quality certification and warranty transferability determine contract awards, while in-field and retrofit installations serve lifecycle extension economics.
- Factory-Built:Controlled-environment lamination under vacuum infusion or prepreg protocols ensures consistent void content and fiber volume fractions. Dutch Flevoland and Italian Riviera clusters concentrate this capability.
- Custom Solutions:One-off superyacht commissions require flexible tooling investments and direct builder-owner specification relationships. Turkish and Greek yards are expanding capacity here.
- In-Field:Emergency hull repair and damage remediation relies on ambient-cure resin systems.
- Retrofit:Composite superstructure additions to existing steel hulls demand interface engineering and galvanic isolation.
Factory-built installation carries the most certified output. Custom solutions are climbing the fastest on superyacht order expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Italian Riviera anchors composite hull production across Europe, with Dutch Flevoland and French Mediterranean coastlines forming complementary manufacturing corridors. Regulatory pressure from Brussels accelerates material substitution timelines. Builder consortiums concentrate procurement authority in these three clusters.
Italy
Superyacht carbon fiber demand concentrates along the Ligurian coast, with Genoa and Viareggio builders expanding autoclave capacity. EU Green Deal maritime emissions targets force rapid aluminum-to-composite substitution in ferry fleets. The Italian Riviera sustains Europe's densest concentration of climate-controlled prepreg lamination facilities serving ultra-high-net-worth buyers.
Netherlands
Dutch Flevoland shipyards specialize in vacuum-infused glass fiber production for commercial workboats and offshore service vessels. REACH compliance through ECHA governs resin formulation selections across Rotterdam supply chains. Amsterdam-Utrecht corridor distributors maintain just-in-time carbon fiber deliveries to superyacht builders facing compressed design cycles.
France
Côte d'Azur charter operators consolidate hull procurement through multi-year framework agreements specifying performance warranties. CE marking under the EU recreational craft directive shapes laminate validation protocols for Cannes and Antibes builders. Mediterranean ferry operators lead epoxy-infused glass fiber adoption for corrosion-resistant superstructures.
Germany
Bavaria and North Rhine-Westphalia host specialized core material manufacturers responding to F-Gas Regulation deadlines on hydrofluorocarbon blowing agents. German autoclave-capable prepreg suppliers control critical nodes for superyacht lamination. Hamburg shipyards integrate hybrid glass-carbon sandwich structures for North Sea wind farm crew transfer vessels.
Turkey
Turkish Aegean shipyards remain underpenetrated for vacuum-infused composite production relative to Italian clusters. Builders near Istanbul and Izmir expand custom superyacht capacity through flexible tooling investments. Eastern Mediterranean expansion opportunities concentrate in these yards as Greek operators seek alternative supply sources.
Europe Marine Composites Market Key Industry Players
Global majors compete with regional champions across fiber systems and resin formulation expertise. The vendor base organizes around three tiers: integrated chemical conglomerates controlling precursor supply, specialized composite material formulators serving marine-specific certifications, and regional distributors managing logistics for boatyard procurement. Strategic moves center on backward integration into carbon fiber precursor production and geographic expansion into underpenetrated Eastern Mediterranean yards.
Among Swiss and German material specialists, Gurit AG and SGL Carbon SE exemplify the prepreg formulator archetype, while Solvay SA anchors the integrated chemical conglomerate tier. These three occupy positions spanning thermoset legacy systems and emerging thermoplastic processability. Their geographic proximity to Dutch and Italian manufacturing clusters reinforces supply security for autoclave-dependent superyacht builders.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Owens Corning |
| Hexcel Corporation |
| Gurit AG |
| SGL Carbon SE |
| Huntsman International LLC |
| Solvay SA |
| Compagnie de Saint-Gobain S.A. |
| Teijin Limited |
| Others |
Cost & Logistics Intelligence
EU Green Deal emissions mandates for maritime transport are forcing Mediterranean ferry operators and Dutch superyacht builders into accelerated procurement of carbon fiber and epoxy-infused glass fiber systems, compelling suppliers to absorb precursor cost volatility while buyers demand performance-based warranties that compress margin buffers.
Pricing Analysis
Polyacrylonitrile precursor cost pass-through from aerospace competitors keeps marine-grade carbon fiber pricing structurally elevated against fiberglass alternatives. Three-tier pricing structure across superyacht-specification, commercial workboat-grade, and recreational craft-commodity levels separates buyers by certification complexity and volume scale. Pricing pressure stems from REACH compliance validation timelines extending formulation approval cycles. Recreational craft manufacturers exhibit highest price sensitivity, while superyacht builders prioritize stiffness-to-weight performance over acquisition cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Italian and Dutch shipyards, while regional distributors serve fragmented Mediterranean boatyards. Supply concentrates in Germany, Switzerland, and the Netherlands for autoclave-capable prepreg manufacturing. Raw material dependencies rest on polyacrylonitrile precursor from petrochemical suppliers, epoxy resin from specialty chemical producers, and E-glass from Owens Corning's European operations. Single-source vulnerability pervades superyacht-grade carbon fiber supply nodes. Distribution runs through Rotterdam and Genoa logistics hubs serving Riviera and Flevoland manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe marine composites function as a stable compounder anchored by regulatory-driven material substitution that sustains multi-year procurement cycles across Mediterranean and North Sea shipbuilding corridors.
For Market Incumbents: Hedge aerospace sector competition for polyacrylonitrile precursor by securing long-term supply agreements with petrochemical suppliers or developing in-house precursor production capability. Expand autoclave capacity in Dutch Flevoland to capture superyacht order expansion before Turkish yards scale vacuum-infusion expertise. CE marking pre-certification partnerships compress time-to-market for novel core materials.
For New Entrants and Emerging Players: EU Green Deal maritime emissions targets in the Netherlands and Italy open a window for bio-based sandwich core alternatives as F-Gas Regulation deadlines force polyurethane reformulation. Target Greek and Turkish shipyards with vacuum-infusion equipment and training services, the most penetrable geography given underinvestment relative to Italian clusters. Pursue crew transfer vessel contracts for North Sea wind farms requiring hybrid glass-carbon structures.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized prepreg formulators possessing ECHA compliance documentation and autoclave supply relationships. Five-to-ten year viability favors backward integration into carbon fiber precursor or forward integration into Turkish yard partnerships. Monitor laminator workforce age demographics along the Italian Riviera as inflection indicator for automation investment necessity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive polyacrylonitrile supply insulates German and Swiss formulators from aerospace sector competition. |
| CE Marking Pre-Certification Partnerships | Notified body relationships compress laminate validation timelines for French Côte d'Azur builders. |
| Eastern Mediterranean Capacity Expansion | Turkish Aegean yards capture superyacht orders seeking alternatives to Italian Riviera pricing. |
| Bio-Based Core Material Qualification | Cork and recycled PET foam substitutes secure Nordic shipbuilder procurement as F-Gas Regulation enforcement tightens. |
| Automation Investment for Laminator Scarcity | Robotic fiber placement addresses aging workforce constraints in Dutch Flevoland climate-controlled facilities. |
Research Approach
Direct dialogue with superyacht procurement directors, commercial ferry fleet managers, ECHA compliance officers, prepreg manufacturing plant managers, and Mediterranean boatyard owners grounded qualitative findings. Secondary validation drew from EU recreational craft directive documentation, ECHA substance authorization databases, SEC filings of listed composite material suppliers, and customs trade data for carbon fiber imports. Bottom-up hull production estimates triangulated against top-down maritime emissions compliance spending projections.
Bottom-up modeling segmented volume and value across fiber type, application, end user, and installation modality, then cross-referenced against country-level shipbuilding output data. CAGRs were derived from regression analysis of historical substitution rates and regulatory compliance deadlines. Forecast inputs incorporated EU Green Deal implementation timelines, REACH authorization backlogs, and superyacht order book visibility from Italian and Dutch builders.
Revisions become necessary when ECHA accelerates substance authorization timelines, F-Gas Regulation enforcement extends to additional blowing agent categories, or Turkish shipyards achieve vacuum-infusion scale rivaling Italian clusters. Periodic stress-testing of base assumptions against laminator workforce retirement rates and aerospace precursor demand fluctuations is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Composite Drums Market
Composite Materials
LAMEA Composite Process Material Kits Market
Composite Materials
Balsa Core Materials Market
Composite Materials
Wall Cladding Materials Market
Composite Materials
FRP Grating Market
Composite Materials
Global Honeycomb Core Materials Market
Composite Materials
Thermoset Composites Market
Composite Materials
FRP Reactor Market
Composite Materials
Composites Testing Market
Composite Materials
Lignin-Based Graphene Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Biocomposites Market
Composite Materials
Global Carbon Fiber Reinforced Plastic Market
Composite Materials
Epoxy Composite Market