
 Europe Composites Market | 2026-2036
Europe Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Composites Market Analytics
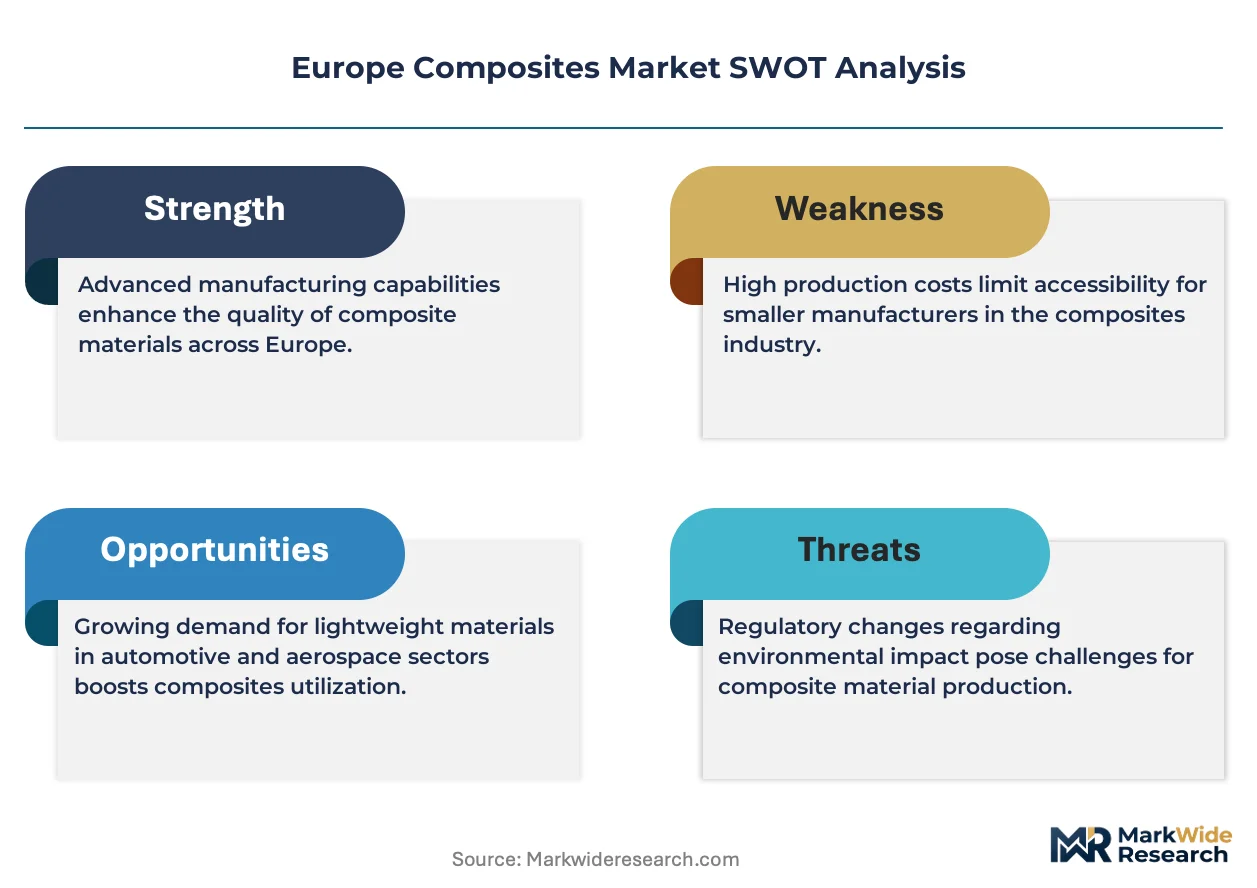
Multi-source carbon fiber procurement is hardening across Tier-1 European aerospace and automotive supply chains. SGL Carbon leverages its Moses Lake precursor facility to sustain stable pitch-carbon fiber deliveries to BMW and Airbus. Gurit Holding anchors wind blade pet preform supply for Vestas and Siemens Gamesa installations from Denmark to Portugal. Owens Corning competes through differentiated glass fiber formulations targeting construction and marine hull applications.
Europe composites comprise engineered materials combining reinforcement fibers with polymer, metal, or ceramic matrices to achieve strength-to-weight ratios exceeding conventional metals, typically manufactured through resin infusion or compression molding processes for structural load-bearing applications. Polymer matrix composites dominate current volume owing to mature epoxy and thermoplastic supply chains serving automotive OEMs and wind turbine manufacturers. Ceramic matrix composites represent the fastest-expanding technology segment as Safran and Rolls-Royce qualify silicon carbide components for next-generation turbine hot sections.
EMA's Medical Device Regulation and REACH chemical compliance frameworks govern raw material approval timelines, while the EU Green Deal's carbon border adjustments reshape resin sourcing economics for importers. The F-Gas Regulation phases down hydrofluorocarbon blowing agents used in polyurethane core production, forcing reformulation across sandwich panel suppliers. Stakeholders must monitor evolving CSRD disclosure requirements for embodied carbon reporting, as Scope 3 tracking becomes a procurement gate for Airbus and automotive OEM supplier qualification.
Market Dynamics
The EU Green Deal's industrial decarbonization mandates are compressing resin formulation cycles while aerospace OEMs in France and Germany harden multi-source carbon fiber procurement for next-generation narrowbody programs.
Growth Catalysts
- Aerospace OEM Procurement Hardening:Tier-1 suppliers across France and Germany are qualifying second-source carbon fiber precursors for narrowbody wing structures, diversifying beyond single-source dependencies.
- F-Gas Regulation Phase-Down:The European Union's hydrofluorocarbon blowing agent restrictions are forcing polyurethane core reformulation, accelerating bio-based alternatives in sandwich panel production.
- Wind Energy Cluster Expansion:Spain's manufacturing corridors are scaling glass and carbon fiber preform capacity to serve Iberian and North African offshore installations.
Market Restraints
- Precursor Supply Concentration:Pitch-carbon fiber feedstock relies on a limited set of European and North American refiners, creating vulnerability for BMW and Airbus supply chains.
- REACH Compliance Friction:ECHA's chemical authorization timelines extend raw material approval cycles by 18-24 months for novel bio-resin formulations.
- Steel Substitution Economics:High-strength automotive steel alloys retain cost advantages in non-structural chassis components below 150 kg vehicle weight reduction thresholds.
Strategic Opportunities
- Eastern European Manufacturing Migration:Poland and Romania are attracting thermoplastic composite stamping operations to serve German automotive OEMs with lower labor and energy inputs.
- Ceramic Matrix Composite Qualification:Silicon carbide fiber-reinforced ceramics are penetrating turbine hot sections as Safran and Rolls-Royce advance next-generation engine architectures.
- CSRD-Driven Embodied Carbon Services:The EU's Corporate Sustainability Reporting Directive creates consultancy and software demand for Scope 3 composite lifecycle tracking.
Industry Challenges
- Automated Fiber Placement Talent Scarcity:Aerospace and wind sectors compete for programmers and technicians capable of operating multi-axis robotic layup systems.
- Multi-Material Joining Certification:Bonding dissimilar composites to aluminum and titanium in hybrid aircraft structures requires extended airworthiness testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Composites Market |
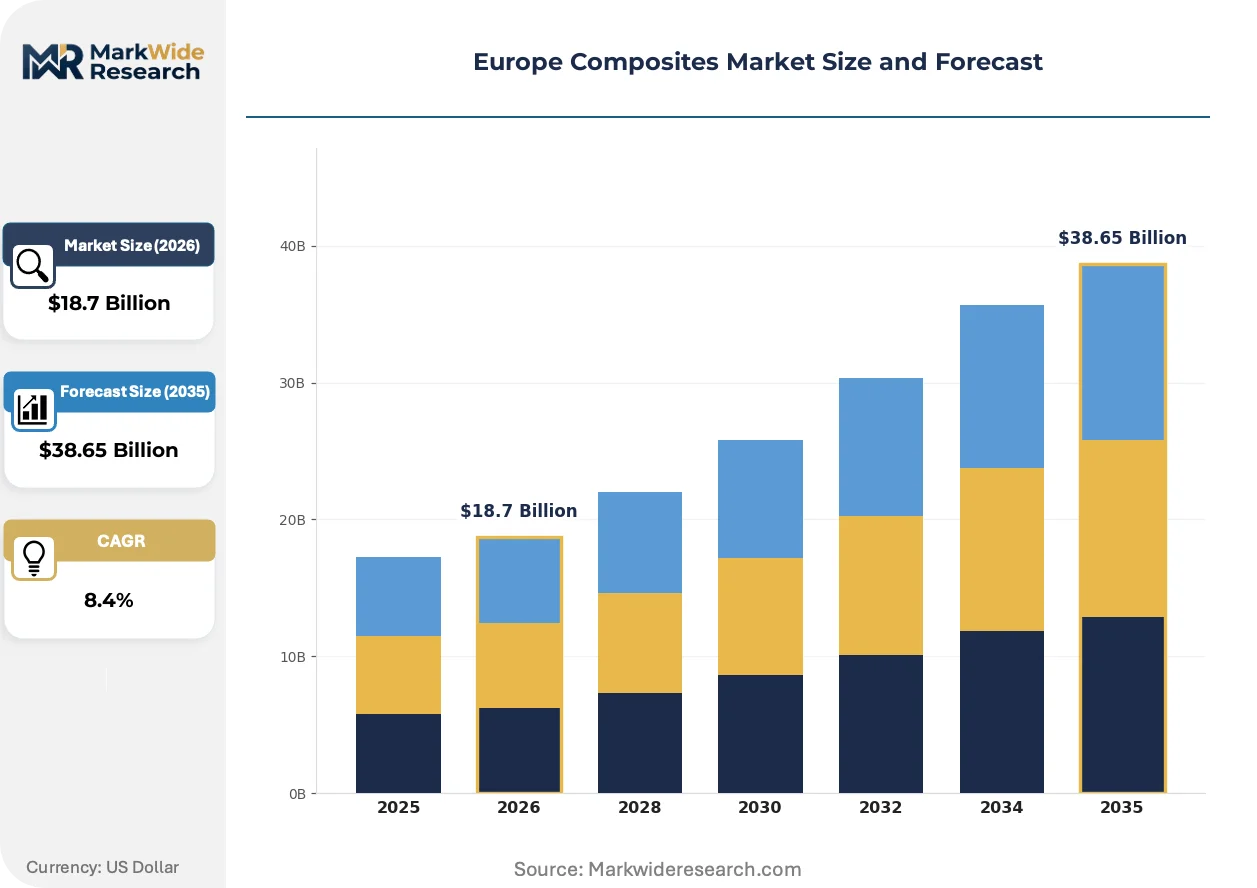
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Matrix Composites, Metal Matrix Composites, Ceramic Matrix Composites, Hybrid Composites End User: Aerospace, Automotive OEMs, Construction, Marine Application: Structural Components, Engine Parts, Wind Turbines, Sporting Goods Technology: Filament Winding, Compression Molding, Injection Molding, Resin Infusion |
| Companies Covered | SGL Carbon, Gurit Holding, Owens Corning, Mitsubishi Chemical Group, Teijin Limited, Toray Industries, Solvay, BASF, Hexcel Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Composites Market Evolving Landscape
Resin formulation and fiber placement technologies are converging to reduce cure cycle times while regulatory pressure on embodied carbon intensifies supply chain transparency requirements across Tier-1 procurement.
Thermoplastic composite welding is modularizing structural assembly for automotive battery enclosures and aerospace interior panels. BMW and Airbus suppliers are adopting induction welding to eliminate adhesive bonding steps. This compression of joining operations is modularizing supply chain nodes, allowing Tier-2 converters to deliver finished sub-assemblies rather than raw prepregs.
CSRD disclosure mandates are forcing raw material provenance documentation through composite value chains. EFRAG's sustainability reporting standards require granular Scope 3 emissions data from carbon fiber and resin suppliers. German automotive OEMs are now embedding lifecycle tracking clauses into supplier qualification agreements.
Buyers are consolidating procurement around qualified material sets rather than qualifying new formulations per program. Airbus and Vestas have reduced approved resin platforms to three core chemistries, compressing supplier R&D recovery windows. This standardization concentrates volume with incumbent formulators in Germany and Denmark.
Europe Composites Market Segmentation
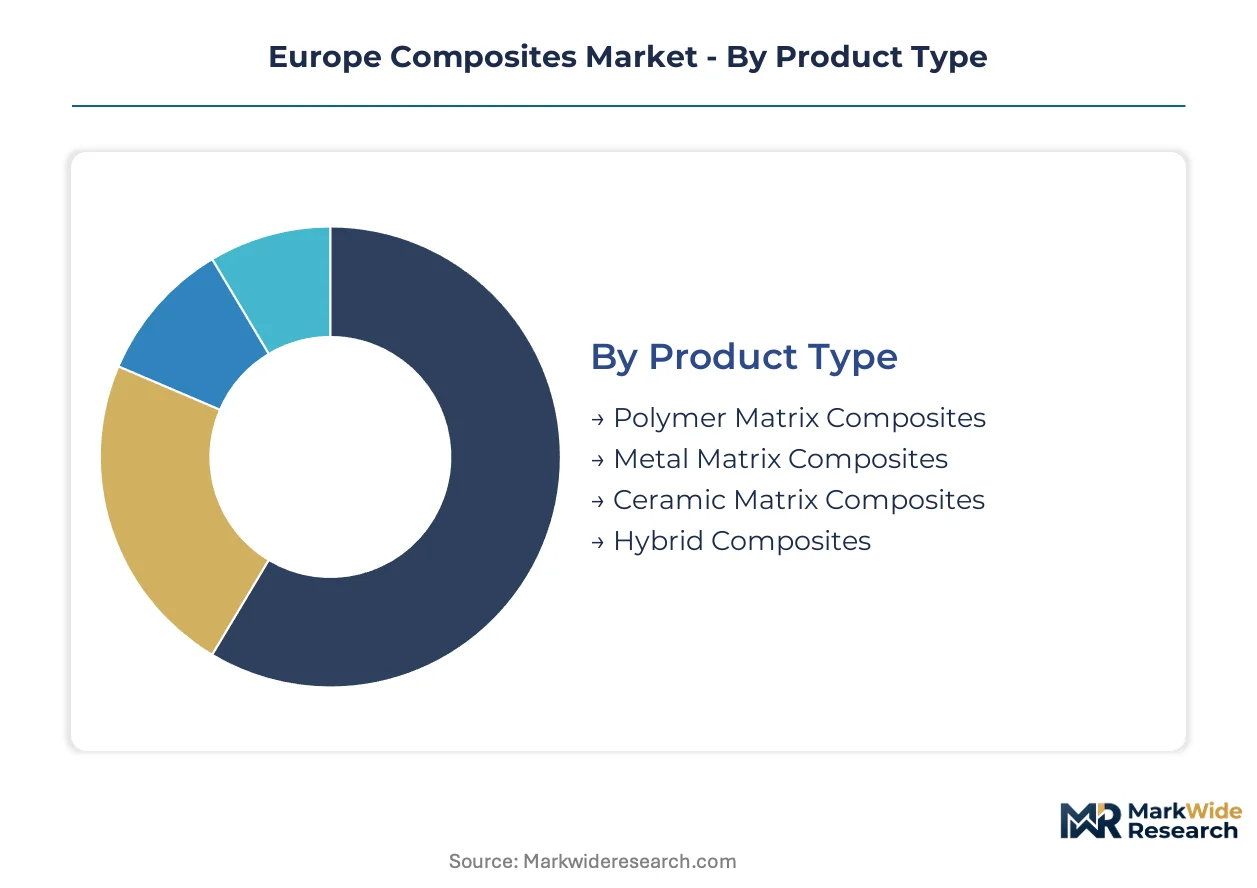
Segmentation in the Europe Composites Market reflects divergent material specifications across aerospace qualification protocols, automotive weight-reduction targets, and wind energy blade length requirements. Procurement teams in Germany and France prioritize segments offering certified supply chains and embodied carbon traceability under CSRD mandates.
Product Type:
Material selection hinges on thermal performance thresholds and manufacturing process compatibility with existing European tooling infrastructure.
- Polymer Matrix Composites:Reinforcement fibers bound in epoxy, polyester, or thermoplastic matrices dominate current European volume. BMW and Vestas procurement concentrates in Germany and Denmark, where established prepreg supply chains support high-throughput automated fiber placement.
- Ceramic Matrix Composites:Silicon carbide fiber-reinforced ceramics withstand turbine hot-section temperatures exceeding 1200°C. Safran and Rolls-Royce qualification programs in France and the UK are accelerating adoption for next-generation engine architectures.
- Metal Matrix Composites:Aluminum or titanium matrices with ceramic reinforcement offer intermediate thermal conductivity for brake systems and electronic packaging.
- Hybrid Composites:Multi-material laminates combining glass and carbon fiber layers optimize cost-performance ratios for construction and marine applications.
Volume sits with Polymer Matrix Composites; growth tilts toward Ceramic Matrix Composites.
End User:
Customer procurement power varies sharply, with aerospace and automotive OEMs dictating qualification timelines and resin platform standardization.
- Aerospace:Wing structures, fuselage panels, and interior components require certified prepreg systems meeting EASA flame-smoke-toxicity standards. Airbus narrowbody programs in France and Germany harden multi-source carbon fiber procurement.
- Automotive OEMs:Battery enclosures and structural members utilize thermoplastic composites for crashworthiness and recyclability. BMW's Leipzig and Dingolfing plants anchor German demand for recycled carbon fiber compounds.
- Construction:Bridge decks, cladding panels, and reinforcement bars exploit corrosion resistance. Infrastructure renewal programs in Spain and Italy drive specification adoption.
- Marine:Hull structures and supercomponents leverage glass fiber vinyl ester systems for osmosis resistance. Yacht builders in Italy and the Netherlands concentrate demand for large-format infusion.
Aerospace commands premium pricing; automotive OEMs scale fastest through platform standardization.
Application:
Functional requirements determine fiber architecture, with load-bearing applications demanding unidirectional tapes and complex curvature favoring woven preforms.
- Structural Components:Primary load-bearing elements in aircraft wings, automotive chassis, and wind turbine blades require high-modulus carbon fiber with void content below 1%. Vestas and Siemens Gamesa blade manufacturing in Spain and Denmark concentrates demand for 80+ meter preform kits.
- Wind Turbines:Glass and carbon fiber hybrid preforms enable 100+ meter offshore blade lengths. Iberian manufacturing clusters scale capacity to serve North African and Baltic installations.
- Engine Parts:Turbine vanes, combustor liners, and exhaust nozzles utilize ceramic matrix composites for thermal protection.
- Sporting Goods:Bicycle frames, hockey sticks, and racing equipment exploit high stiffness-to-weight ratios in niche volume.
Structural Components absorb majority fiber volume; Wind Turbines expand most quickly through offshore scaling.
Technology:
Process selection balances part complexity, production rate, and capital equipment requirements across European manufacturing footprints.
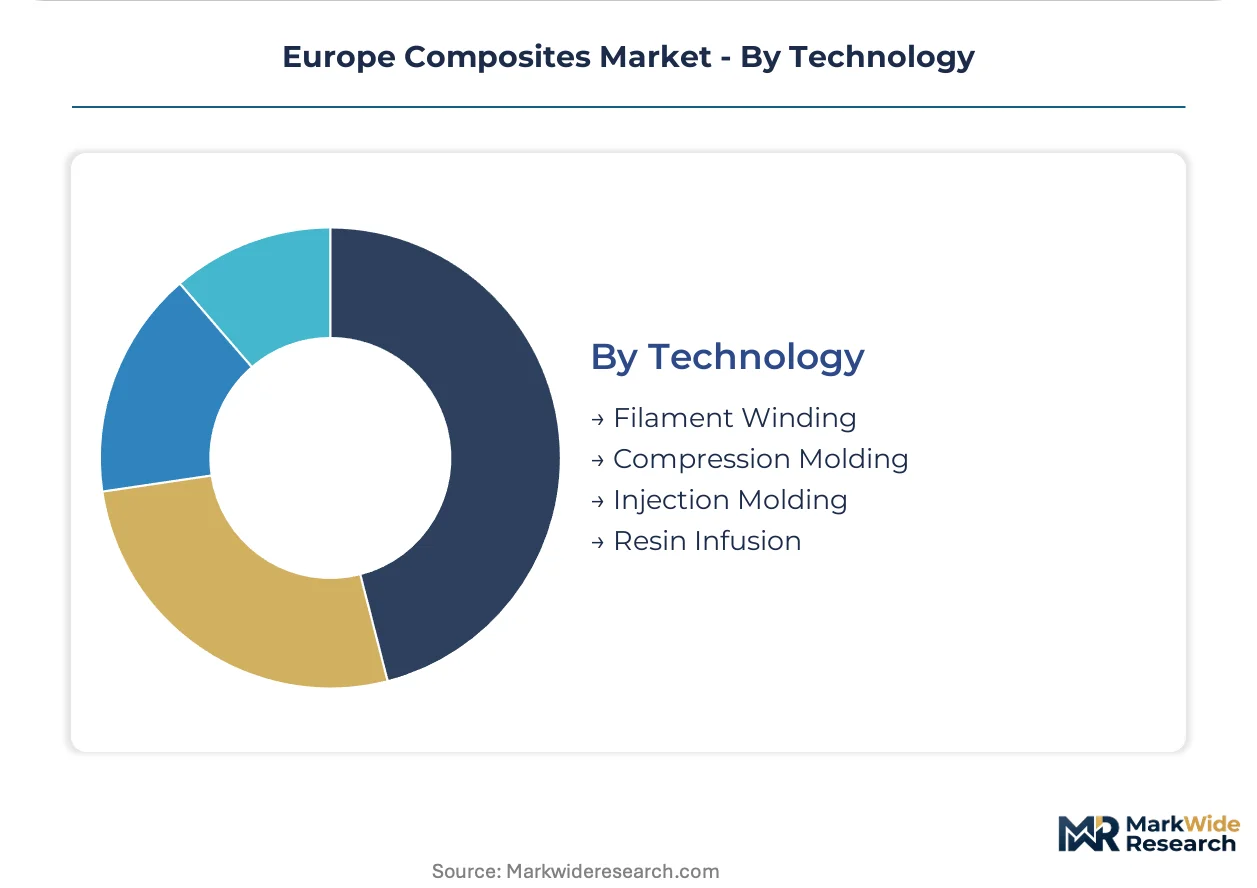
- Resin Infusion:Vacuum-assisted resin transfer molding produces large, complex geometries with consistent fiber volume fraction. Wind blade manufacturers in Spain and Denmark rely on infusion for 80-meter-plus preform consolidation.
- Automated Fiber Placement:Multi-axis robotic layup deposits thermoset or thermoplastic tapes with precision for aerospace contours. Airbus suppliers in Germany and France compete for programmer and technician talent to operate these systems.
- Filament Winding:Continuous fiber deposition around mandrels produces pressure vessels and pipe structures with high hoop strength.
- Compression Molding:Matched die forming of sheet molding compound enables high-rate automotive component production with cycle times under three minutes.
- Injection Molding:Short fiber thermoplastic compounding serves non-structural automotive and electronics housings.
Resin Infusion dominates blade and marine volume; Automated Fiber Placement gains share through aerospace qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pitch-carbon fiber precursor from SGL Carbon's Moses Lake facility anchors transatlantic supply chains serving BMW's Leipzig assembly complex and Airbus Hamburg wing fabrication. German automotive and French aerospace OEMs drive procurement hardening across the continent.
Germany
BMW's Dingolfing and Leipzig plants consume recycled carbon fiber compounds for battery enclosures and structural members. The EU Green Deal's industrial decarbonization mandates accelerate bio-based resin formulation in Baden-Württemberg chemical corridors. Bavaria's automated fiber placement talent pools face competition from wind energy and aerospace sectors for multi-axis robotic layup technicians.
France
Airbus Toulouse and Nantes facilities qualify second-source carbon fiber precursors for narrowbody wing structures under EASA certification protocols. The F-Gas Regulation phases down hydrofluorocarbon blowing agents used in polyurethane core production, forcing reformulation across sandwich panel suppliers. Safran's ceramic matrix composite qualification programs in Paris-Saclay advance silicon carbide turbine components.
Spain
Vestas and Siemens Gamesa blade manufacturing clusters in Castilla y León scale glass and carbon fiber preform capacity for 100+ meter offshore installations. Infrastructure renewal programs in Madrid and Barcelona drive specification adoption for bridge decks and cladding panels. Iberian manufacturing corridors now serve North African and Baltic wind farm developments.
Denmark
Gurit Holding anchors wind blade pet preform supply from its Danish base for installations stretching to Portugal. The country's national wind energy regulator enforces blade recyclability standards that reshape composite material selection. Copenhagen's thermoplastic composite welding R&D supports modular assembly innovations for automotive battery enclosures.
United Kingdom
Rolls-Royce Derby advances ceramic matrix composite qualification for next-generation turbine hot sections alongside Safran collaboration. REACH compliance friction from ECHA extends raw material approval cycles for novel bio-resin formulations entering UK aerospace supply chains. Bristol's composite research corridor concentrates automated fiber placement expertise for defense and civil aviation applications.
Europe Composites Market Competitive Landscape
Multi-source carbon fiber procurement dominates the current landscape as Tier-1 suppliers diversify beyond single-source dependencies. The vendor base concentrates around three strategic archetypes: integrated carbon fiber producers controlling precursor-to-fabrication chains, specialized resin formulators serving qualified aerospace platforms, and regional preform converters supporting wind energy clusters. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing qualified material positions ahead of CSRD-driven embodied carbon disclosure requirements.
Among integrated carbon fiber specialists, SGL Carbon and Toray Industries occupy positions anchoring precursor supply for European automotive and aerospace OEMs. Gurit Holding exemplifies the wind-focused preform converter archetype, while Owens Corning represents diversified glass fiber formulation across construction and marine applications. These three companies illustrate how competitive positioning hardens around qualified supply chain nodes rather than product differentiation alone.
| Leading Market Players |
|---|
| SGL Carbon |
| Gurit Holding |
| Owens Corning |
| Mitsubishi Chemical Group |
| Teijin Limited |
| Toray Industries |
| Solvay |
| BASF |
| Hexcel Corporation |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's industrial decarbonization mandates gate qualified supply access and premium-tier pricing for compliant resin formulators and carbon fiber suppliers serving Airbus and BMW procurement teams.
Pricing Analysis
Warranty and certification-bundling separates qualified aerospace prepreg from commodity-grade construction materials. Three-tier pricing structure across premium, standard, and economy levels reflects EASA flame-smoke-toxicity certification status and CSRD-compliant embodied carbon documentation. Pricing pressure stems from BMW and Vestas consolidating procurement around three core resin chemistries, compressing supplier R&D recovery. Automotive OEMs exhibit highest price sensitivity; aerospace wing-structure suppliers accept premium pricing for qualified second-source carbon fiber.
Supply Chain Analysis
Pitch-carbon fiber precursor supply rests on European and North American refiners with limited qualified capacity for BMW and Airbus multi-source procurement strategies. Raw material dependencies include acrylonitrile monomer, petroleum pitch feedstock, and bio-based epoxy hardeners. Single-source vulnerability concentrates in SGL Carbon's Moses Lake facility anchoring transatlantic deliveries. Distribution runs through Tier-1 preform converters in Germany and Denmark serving qualified aerospace and wind energy platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Composites Market reads as a cost-of-compliance story where REACH authorization timelines and CSRD disclosure requirements create barrier-to-entry moats for incumbent formulators with established ECHA dossiers.
For Market Incumbents: Acquire automated fiber placement programming talent pools before wind energy and aerospace sectors exhaust Bavaria's technician supply. Consolidate backward integration into bio-based epoxy hardener production to capture EU Green Deal procurement preference. Defend against Eastern European thermoplastic stamping migration by embedding lifecycle tracking clauses into German OEM supplier agreements.
For New Entrants and Emerging Players: CSRD-driven embodied carbon services in Germany open a window for software and consultancy providers targeting Scope 3 tracking gaps in Tier-2 converter networks. White-space concentrates in Polish and Romanian thermoplastic composite stamping serving German automotive OEMs with lower labor inputs. Go-to-market through embedded carbon accounting partnerships with preform converters lacking in-house sustainability reporting capability.
For Investors and Strategic Acquirers: Ceramic matrix composite qualification completion at Safran and Rolls-Royce is the leading indicator that silicon carbide fiber-reinforced ceramic suppliers will command scarcity premiums. Long-term viability favors qualified material positions ahead of F-Gas Regulation phase-down completion and bio-resin platform consolidation. Target acquisition archetype: wind-focused preform converters with established Vestas or Siemens Gamesa supply relationships and recyclable blade technology alignment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Epoxy | Captures EU Green Deal preference for renewable feedstock resins in automotive battery enclosures. |
| Ceramic Matrix Composite Qualification | Positions suppliers for Safran and Rolls-Royce turbine hot-section contracts exceeding 1200°C thresholds. |
| Automated Fiber Placement Talent Acquisition | Secures scarce multi-axis robotic layup technicians before wind and aerospace competition intensifies. |
| CSRD-Compliant Lifecycle Tracking Systems | Meets EFRAG sustainability reporting standards embedded in German OEM supplier qualification agreements. |
| Eastern European Thermoplastic Stamping Expansion | Serves BMW and automotive OEMs with lower labor and energy inputs in Poland and Romania. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe Composites Market assessment. Primary interviews with aerospace procurement directors, automotive platform engineers, wind blade manufacturing managers, resin formulation R&D leads, and ECHA regulatory affairs specialists validated supply chain and pricing dynamics. Secondary sources included Cefic chemical industry reports, EASA certification databases, EU customs trade statistics, and SEC filings from listed carbon fiber producers. Bottom-up fiber volume estimates by application triangulated against top-down OEM procurement value projections.
Data-stream reconciliation across resin formulation volumes, carbon fiber precursor shipments, and finished composite component trade flows shaped the analytical framework. Segmentation dimensions modeled include matrix type, end-use industry, manufacturing technology, and regional production cluster. CAGRs derived from fitted trend analysis of historical procurement patterns and OEM platform rollout schedules. Industry-specific forecast inputs incorporated F-Gas Regulation phase-down timelines and ceramic matrix composite qualification milestones.
The model assumes a particular technology adoption path; alternative pathways for thermoplastic composite welding modularization would alter the outlook for adhesive bonding step elimination. Forecasts reflect assumptions regarding REACH authorization progression, CSRD disclosure enforcement intensity, and aerospace narrowbody program procurement schedules. A small set of named triggers—ECHA bio-resin approval acceleration, ceramic matrix composite airworthiness certification completion, and Baltic offshore wind auction awards—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Medical Composite Material Market
Composite Materials
Carbon Composites Market
Composite Materials
FRP Reactor Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Synthetic Rope Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
Aramid Fiber Reinforced Polymer Market
Composite Materials
Europe Aluminium Composite Panel Market
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
Isostatic Graphite Market
Composite Materials
Phenolic Panel Market
Composite Materials
FRP Tanks Market
Composite Materials
Short Fiber Thermoplastic Composites Market
Composite Materials
Asia-Pacific Natural Fiber Composites Market
Composite Materials
Wind Turbine Composites Market
Composite Materials
Automotive Carbon Fiber Materials Market