
 Rubber Reinforcing Chemicals Market | 2026-2036
Rubber Reinforcing Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Reinforcing Chemicals Market Analytics
China is reconfiguring regional supply dynamics through carbon black capacity additions in Shandong and Jiangsu provinces. LANXESS AG leverages backward integration into precursor chemicals to secure cost positions in high-performance silica grades. Evonik Industries sustains technology leadership through precipitated silica innovations targeting tire-labeling compliance. Kumho Petrochemical anchors Northeast Asian supply with integrated carbon black operations serving domestic tire producers.
Rubber reinforcing chemicals comprise particulate and polymeric additives—carbon black, precipitated silica, organosilanes, and resorcinol-formaldehyde resins—dispersed into elastomer matrices to enhance tensile strength, abrasion resistance, and dynamic fatigue life, typically at loadings of 30–70 phr depending on performance requirements. The primary industrial purpose centers on extending service intervals and enabling thinner-gauge tire construction without sacrificing durability. Carbon black retains volume dominance across tire and industrial rubber applications due to established compounding knowledge and cost efficiency, while silica grades command margin premiums in fuel-efficient tire segments where coupling-agent technology determines performance thresholds. The automotive application dimension concentrates procurement scale, though construction and electrical segments generate specialized demand for heat-resistant and insulating compound formulations.
EPA emissions standards in the United States, REACH chemical registration requirements in Europe, and China's MEE environmental compliance mandates collectively tighten production permits for carbon black furnaces and precipitated silica plants, elevating capital requirements for capacity expansion. Tire-labeling regulations in the European Union and analogous schemes under development in South Korea and Brazil directly specify rolling-resistance and wet-grip performance thresholds, translating into compound reformulation mandates that favor advanced silica-silane systems. Stakeholders must monitor regulatory divergence between jurisdictions and align R&D portfolios with the specific test protocols each market adopts.
Market Dynamics
The rubber reinforcing chemicals sector is pivoting around silica-silane coupling systems as EU tire-labeling mandates force compound reformulation across automotive supply chains. This technology transition is redrawing procurement priorities and supplier hierarchies.
Growth Catalysts
- EU tire-labeling compliance:Rolling-resistance and wet-grip performance thresholds under Regulation (EC) No 1222/2009 compel tire manufacturers to substitute carbon black with precipitated silica grades in passenger-vehicle tread compounds.
- Electric-vehicle range optimization:OEMs in Germany, China, and the United States are reformulating tire compounds to reduce rolling resistance and extend battery range, concentrating demand for advanced reinforcing systems.
- Silica capacity expansion:New precipitated silica plants in Shandong and Jiangsu provinces are augmenting regional supply availability for domestic tire producers serving export markets.
Market Restraints
- Petroleum feedstock volatility:Carbon black production remains tethered to oil-derived feedstocks, exposing margins to crude price swings and naphtha supply interruptions.
- Environmental permit scarcity:EPA emissions standards, REACH registration requirements, and China's MEE compliance mandates are elevating capital barriers for new furnace black and precipitated silica capacity.
- High-performance silica technical thresholds:Coupling-agent chemistry and dispersion quality requirements limit qualified supply sources for fuel-efficient tire grades.
Strategic Opportunities
- South Korean regulatory alignment:Developing tire-labeling schemes under KBA protocols create early-mover advantages for silica-silane system suppliers preparing for 2026-2027 implementation.
- Construction rubber heat-resistance demand:Mining and infrastructure applications require specialized reinforcing packages for conveyor belts and hoses operating in high-temperature environments.
- Bio-based carbon black development:Pyrolysis-derived feedstocks from end-of-life tires are converging with traditional furnace processes to address circularity mandates in the EU Green Deal framework.
Industry Challenges
- Compounding expertise scarcity:Formulation chemists capable of optimizing silica dispersion and silane coupling in mixed filler systems command premium compensation and limited availability.
- Multi-jurisdiction certification timelines:Divergent test protocols between EU, South Korean, and Brazilian tire-labeling schemes force redundant compound validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Reinforcing Chemicals Market |
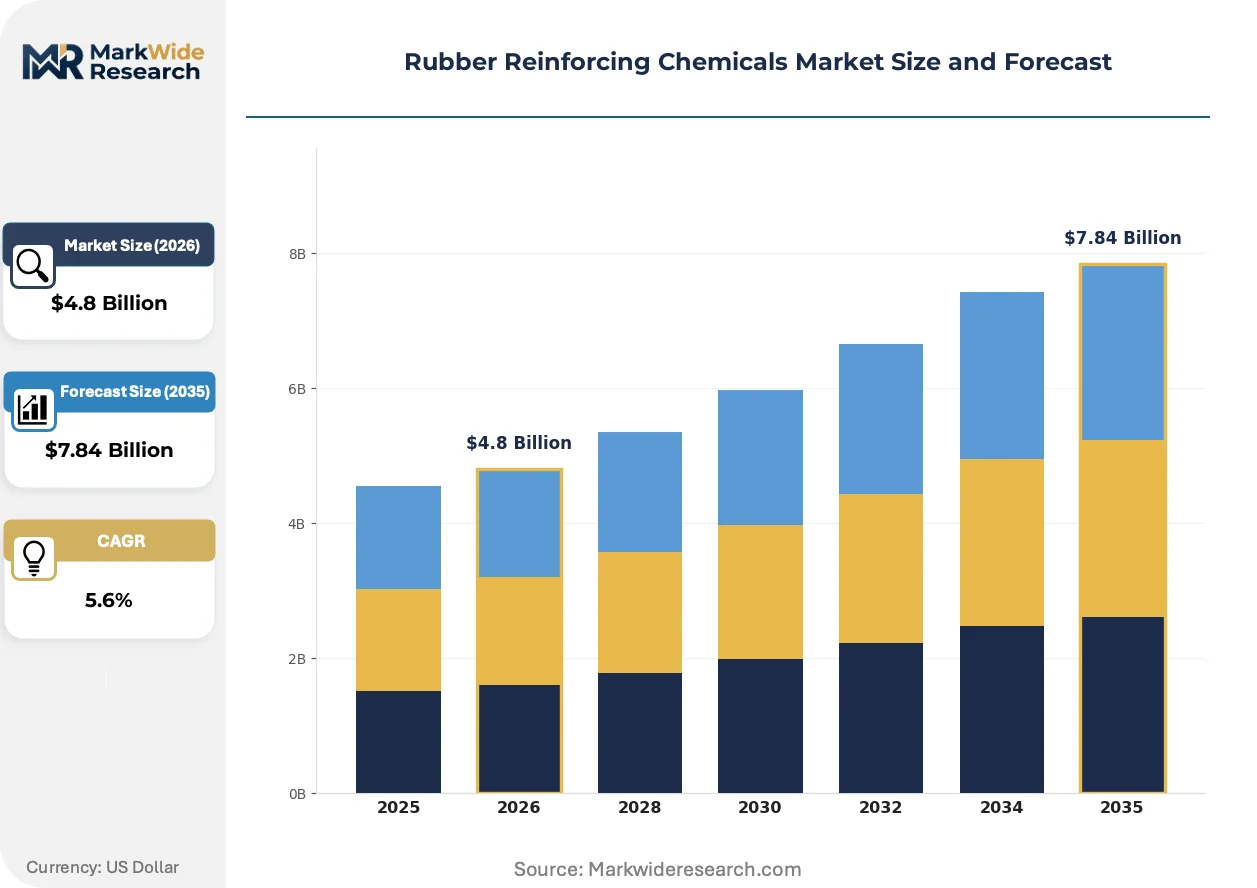
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Black, Silica, Clay, Nylon End User: Tire Manufacturers, Industrial Rubber, Footwear, Adhesives Application: Automotive, Construction, Electrical, Marine Technology: Vulcanization, Polymerization, Mixing, Coating |
| Companies Covered | LANXESS AG, Evonik Industries, SI Group, Nocil Limited, Akrochem Corporation, BASF SE, Eastman Chemical Company, Kumho Petrochemical, Arkema SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Reinforcing Chemicals Market Evolving Landscape
Compound architecture is evolving through filler hybridization strategies that balance cost, performance, and regulatory compliance. Three interconnected developments are restructuring how reinforcing chemicals are specified, supplied, and integrated.
Dual-filler hybrid systems combining carbon black with precipitated silica are migrating from premium passenger-tire segments into standard-grade Original Equipment Manufacturer specifications. Tier-one tire producers in Germany and Japan are accelerating adoption to meet fleet-average rolling-resistance targets without sacrificing tread-wear durability. This migration is compressing the performance gap between commodity and specialty reinforcing grades.
REACH chemical registration requirements in Europe are tightening substance evaluation protocols for organosilane coupling agents and resorcinol-formaldehyde resins used in tire manufacturing. The industrial consequence is extended authorization timelines for novel reinforcing additives and heightened documentation burdens for existing formulations. Tire compounders serving EU export markets are consolidating supplier relationships to reduce regulatory exposure.
Automotive OEMs are consolidating reinforcing chemical procurement through direct specification of approved silica grades and coupling-agent systems rather than delegating formulation freedom to tire suppliers. This concentration of buying influence is displacing traditional compounder-led material selection in electric-vehicle platform development. The shift is most visible in German and Chinese automotive supply chains where range certification carries brand liability.
Rubber Reinforcing Chemicals Market Segmentation
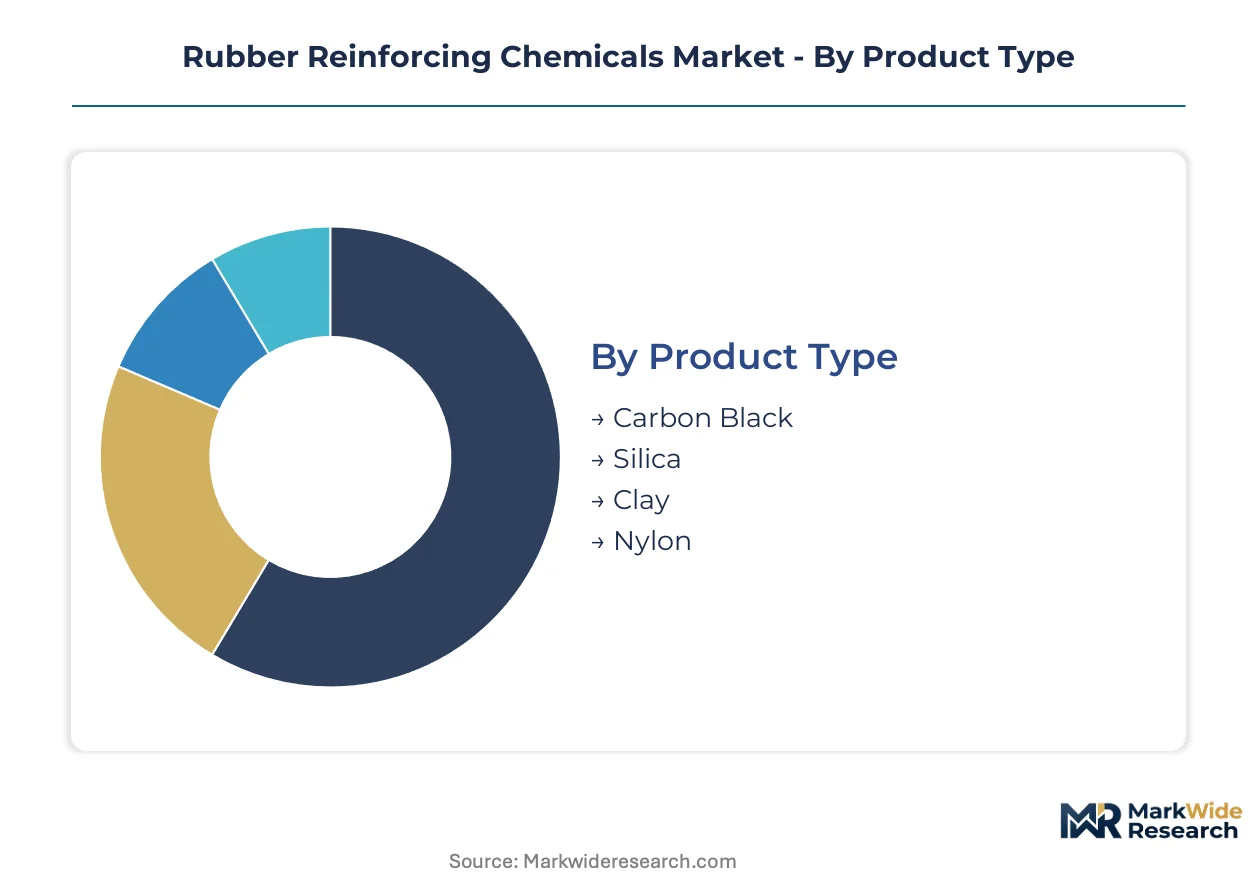
Reinforcing chemical specifications diverge sharply across end-use stress profiles and regulatory compliance tiers. Procurement patterns fragment by product chemistry, with carbon black and silica serving fundamentally different performance-cost tradeoffs in tire and industrial compounds.
Product Type:
Cost tier differentiation separates commodity furnace blacks from premium precipitated silica grades, with intermediate fillers occupying technical niches.
- Carbon Black:Furnace and thermal process particulates delivering tensile reinforcement and abrasion resistance at 30–70 phr loadings. Tire manufacturers in Germany and the United States specify N-series grades for tread compounds where rolling-resistance mandates remain secondary to durability targets. Petroleum feedstock volatility constrains margin stability.
- Silica:Precipitated amorphous silicas combined with organosilane coupling agents reduce hysteresis loss in fuel-efficient tire formulations. Demand concentrates in EU export production from Shandong and Jiangsu province plants serving tire-labeling compliance requirements. Coupling-agent chemistry limits qualified supply sources.
- Clay:Kaolin and calcined aluminum silicates provide semi-reinforcing properties at lower cost points for industrial rubber goods.
- Nylon:Short-fiber polyamide reinforcements enhance tear strength and dynamic fatigue resistance in specialized hose and belt applications.
Carbon Black commands the established base. The steepest expansion runs through Silica.
End User:
Application maturity separates volume-driven tire procurement from specialized industrial compound requirements.
- Tire Manufacturers:Original equipment and replacement tire producers specify reinforcing packages against rolling-resistance, wet-grip, and wear-performance targets. EU tire-labeling regulations and emerging South Korean KBA protocols compel silica-silane adoption in passenger-vehicle segments. OEMs in Germany and China increasingly dictate approved material lists.
- Industrial Rubber:Conveyor belt, hose, and seal producers specify heat-resistant and abrasion-tolerant reinforcing systems. Mining and infrastructure applications in the United States drive demand for specialized carbon black grades and short-fiber reinforcements. Compounding expertise scarcity limits formulation optimization.
- Footwear:Soling compounds utilize semi-reinforcing fillers balancing flex resistance and cost efficiency.
- Adhesives:Tackifier and reinforcing resin systems modify elastomer-based bonding formulations.
Tire Manufacturers anchor procurement scale. Industrial Rubber is gaining share fastest.
Application:
Performance requirements and regulatory exposure concentrate demand in automotive segments while construction and electrical applications generate specialized specifications.
- Automotive:Tire and underhood rubber components dominate reinforcing chemical consumption. Electric-vehicle range optimization in Germany, China, and the United States accelerates low-rolling-resistance compound reformulation. OEM consolidation of material specification authority reshapes supplier relationships.
- Construction:Conveyor belts, hoses, and sealing systems require heat-resistant and weather-stable reinforcing packages. Infrastructure investment cycles in the United States influence demand timing for heavy-duty industrial grades.
- Electrical:Cable insulation and jacketing compounds specify reinforcing fillers balancing mechanical protection with dielectric properties.
- Marine:Dock fenders, seals, and hose systems utilize salt-water-resistant elastomer formulations with specialized reinforcing systems.
Automotive represents the volume anchor. Construction shows the most pronounced cyclical sensitivity.
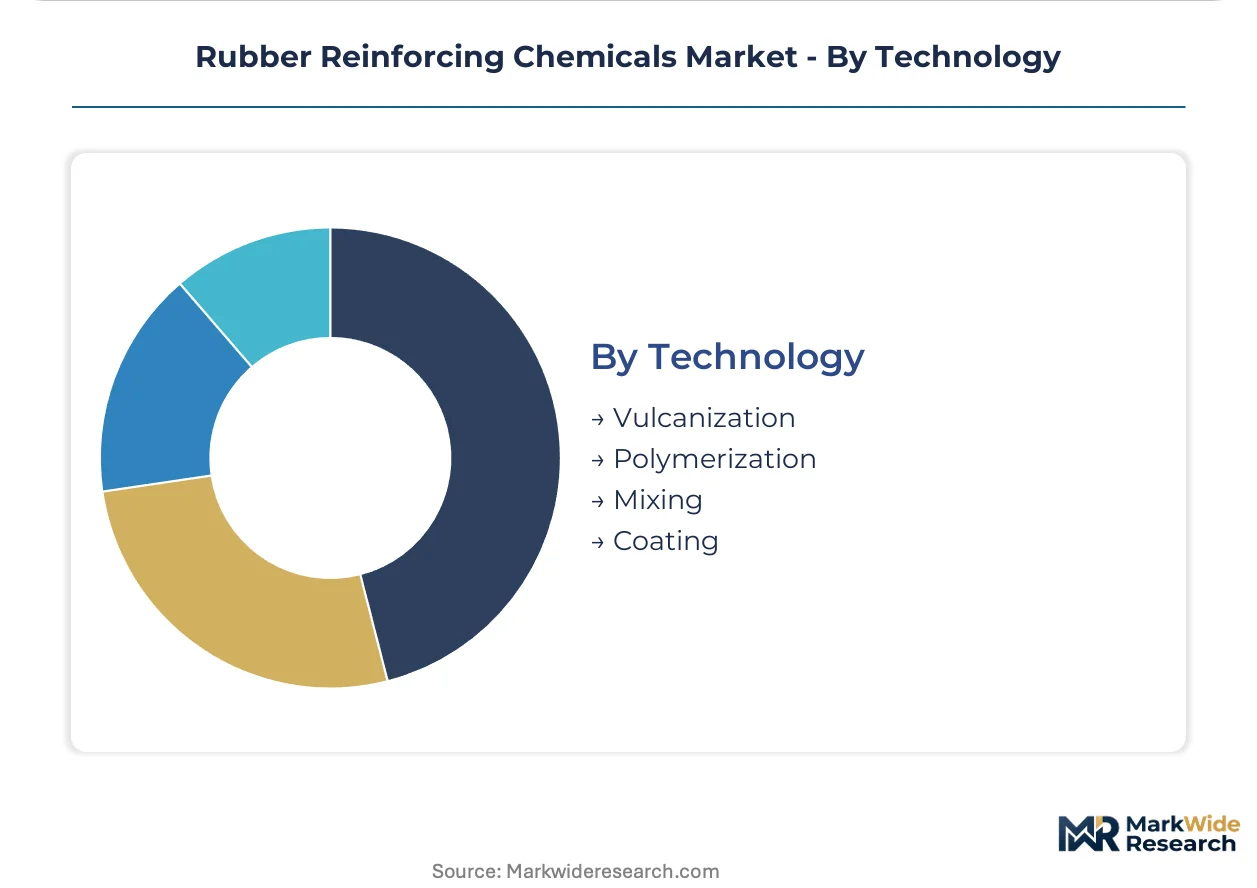
Technology:
Process chemistry determines filler dispersion quality and interfacial bonding efficiency in final compound properties.
- Vulcanization:Sulfur-based crosslinking chemistry integrates reinforcing fillers into three-dimensional elastomer networks. Carbon black and silica surface chemistry interacts with vulcanization accelerators to determine final mechanical properties. REACH registration requirements in Europe constrain novel accelerator systems.
- Polymerization:In-situ filler incorporation during elastomer synthesis creates masterbatch concentrates for downstream compounding.
- Mixing:Internal mixer and continuous mixer technologies disperse reinforcing fillers at controlled temperature and shear profiles.
- Coating:Surface treatment processes modify filler-polymer interfacial adhesion for specialized performance requirements.
Vulcanization retains process dominance. Mixing technology is climbing fastest on precision dispersion requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH chemical registration requirements in Europe anchor regulatory stringency for rubber reinforcing chemicals, while EPA emissions standards and China's MEE environmental compliance mandates shape parallel compliance frameworks across major production geographies.
Germany
Tire-labeling regulations under EU Regulation (EC) No 1222/2009 compel silica-silane adoption in passenger-vehicle tread compounds. KBA protocols influence testing methodologies that German OEMs export to affiliated plants worldwide. The Cologne-Düsseldorf industrial corridor hosts formulation centers where LANXESS AG backward integrates into precursor chemicals for high-performance silica grades.
China
Domestic tire producers serving export markets drive precipitated silica demand for EU tire-labeling compliance. MEE environmental mandates tighten production permits for carbon black furnaces and silica plants, elevating capital barriers. Shandong and Jiangsu provinces concentrate new silica capacity additions that augment regional supply availability.
United States
EPA emissions standards constrain carbon black furnace operations while electric-vehicle range optimization accelerates low-rolling-resistance compound reformulation. NHTSA fuel economy regulations indirectly pressure tire performance specifications. The Gulf Coast petrochemical corridor sustains carbon black feedstock access despite petroleum price volatility.
South Korea
Developing KBA-aligned tire-labeling schemes under transport ministry protocols create early-mover opportunities for silica-silane system suppliers. MFDS chemical registration requirements parallel REACH substance evaluation timelines. The Yeosu industrial complex anchors Kumho Petrochemical's integrated carbon black operations serving domestic tire producers.
Brazil
Emerging tire-labeling schemes under ANVISA and transport ministry coordination introduce compound reformulation mandates for export-oriented tire plants. Port infrastructure limitations intermittently constrain carbon black import logistics. The São Paulo state manufacturing belt concentrates tire production requiring specialized reinforcing packages.
Rubber Reinforcing Chemicals Market Competitive Landscape
Capability concentration sits with integrated chemical specialists; scale advantage sits with diversified petrochemical conglomerates. The sector structures around three tiers: multinational diversifieds with backward integration into precursors, regional carbon black specialists with furnace technology mastery, and silica-focused innovators with coupling-agent chemistry expertise. Dominant competitive moves include capacity expansion in low-cost manufacturing geographies and strategic partnerships bridging filler production with tire compounder technical service capabilities.
Within the multinational diversified tier, LANXESS AG and Evonik Industries exemplify European chemical conglomerates with reinforcing chemical portfolios. LANXESS AG occupies a position anchored in German industrial heritage, while Evonik Industries represents specialized silica innovation capacity. Kumho Petrochemical anchors the Northeast Asian supply vector as a Korean petrochemical group with integrated carbon black operations.
| Leading Market Players |
|---|
| LANXESS AG |
| Evonik Industries |
| SI Group |
| Nocil Limited |
| Akrochem Corporation |
| BASF SE |
| Eastman Chemical Company |
| Kumho Petrochemical |
| Arkema SA |
| Others |
Value Network & Pricing Analysis
Overcapacity in Shandong and Jiangsu precipitated silica plants is compressing regional margins while tightening environmental permits in Germany and the United States sustain premium pricing for compliant grades. This utilization divergence rewards integrated producers with captive precursor supply while forcing merchant suppliers into volume-driven pricing postures.
Pricing Analysis
Price spreads between EU-compliant precipitated silica and standard furnace black grades widen as REACH registration costs embed into specialty chemical premiums. Three-tier pricing structure across premium coupling-agent grades, standard silica, and commodity carbon black reflects certification burden and dispersion quality. Cost compression in standard carbon black intensifies because petroleum feedstock volatility erodes fixed-contract value. Tire manufacturers exhibit highest price sensitivity in carbon black procurement, while automotive OEMs direct-buying silica grades show lowest sensitivity due to range-certification liability.
Supply Chain Analysis
Contract manufacturing concentration sits with LANXESS AG and Evonik Industries operating integrated precipitated silica facilities, while Kumho Petrochemical anchors carbon black furnace capacity. Supply concentrates in China, Germany, and the United States, with Shandong province hosting expanding silica capacity and the Cologne-Düsseldorf corridor retaining high-performance grade production. Feedstock dependencies draw from petroleum-derived naphtha for carbon black and sodium silicate precursors for silica. Single-source vulnerability in organosilane coupling agents creates bottleneck exposure. Distribution runs through tire compounder technical service partnerships rather than merchant chemical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists capable of optimizing silica dispersion and silane coupling command premium compensation that constrains compound innovation velocity. This talent scarcity elevates strategic value for technical service capabilities and backward-integrated precursor control.
For Market Incumbents: Pre-empt margin erosion in commodity carbon black by securing captive naphtha supply through refinery partnerships or storage infrastructure. Deepen coupling-agent chemistry expertise to defend premium silica positioning against emerging Chinese capacity. Capacity addition in Jiangsu province threatens European export markets; accelerate R&D in bio-based carbon black to meet EU Green Deal circularity mandates. For New Entrants and Emerging Players: Build out technical service capabilities targeting South Korean tire producers preparing for KBA-aligned labeling implementation. Industrial rubber heat-resistance applications in United States mining and infrastructure present underpenetrated demand with less stringent formulation barriers than automotive segments. Partner with regional distributors possessing existing relationships with conveyor belt and hose manufacturers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among silica-silane system suppliers with automotive OEM direct-specification relationships. Long-term viability over the analysis window favors integrated producers with environmental permit access in constrained jurisdictions. Acquisition target archetype: mid-cap silica innovators with coupling-agent patents and established tire compounder validation. Watch for EPA enforcement intensity and MEE compliance cost escalation as margin inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemicals | LANXESS AG secures cost positions in high-performance silica grades against merchant competitors. |
| Silica Capacity Expansion | New Shandong and Jiangsu plants augment regional supply for EU tire-labeling compliance exports. |
| Long-term Supply Agreement | Automotive OEMs consolidate procurement through approved material lists with direct specification authority. |
| Green Manufacturing Transition | Pyrolysis-derived feedstocks from end-of-life tires address EU Green Deal circularity mandates. |
| Joint Venture | Strategic partnerships bridge filler production with tire compounder technical service capabilities. |
Research Methodology
Initial hypotheses were tested against primary input from tire compounder procurement directors, automotive OEM material specification engineers, carbon black plant managers, and silica R&D technical leads and refined through secondary validation. Sources included customs and trade flow databases, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and EPA emissions compliance records. Bottom-up capacity and utilization estimates triangulated against top-down demand modeling from vehicle production and tire shipment data.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeled by product chemistry grade, end-use industry application, automotive versus industrial rubber demand, and regional production hub concentration. CAGRs were derived from regression analysis of historical pricing and volume trajectories, incorporating silica-silane adoption curves tied to tire-labeling regulatory phase-ins and electric-vehicle platform rollout schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated petrochemical conglomerates entering precipitated silica would shift outcomes through accelerated capacity addition. Regulatory enforcement intensity, petroleum feedstock price spikes, and automotive OEM specification consolidation pace constitute primary revision risks. Quarterly review of EPA permit issuance rates, MEE compliance cost indices, and KBA protocol development milestones is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
EPDM Rubber Market
Rubber
Global Styrene Butadiene Styrene Market
Rubber
Medical Rubber and Balloon Products Market
Rubber
Isobutylene Market
Rubber
Rubber Block Market
Rubber
Rubber Rollers Market
Rubber
Rubber Masterbatch Market
Rubber
Tire Reinforcement Materials Market
Rubber
Metallurgical Rubber Roller Market
Rubber
Global Hydraulic Rubber Hose Market
Rubber
Isoprene Rubber (IR) Latex Market
Rubber
Recycled Elastomers Market
Rubber
Liquid Silicone Rubber Market
Rubber
Rubber Bulb Seals Market
Rubber
Rubber Foam Market
Rubber
Polyisoprene Market