
 Global FRP Vessels Market | 2026-2036
Global FRP Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Global FRP Vessels Market Foresight
The global FRP vessels market is restructuring around a widening performance gap between engineered pressure vessels and commodity storage tanks. Hexagon Composites ASA dominates high-pressure hydrogen containment through filament-wound carbon fiber expertise. Everest Kanto Cylinders anchors industrial gas distribution with specialized Type 3 and Type 4 cylinder portfolios. NOV competes in offshore oilfield applications where saltwater corrosion resistance commands premium specifications.
Fiber-reinforced plastic vessels combine thermoset resin matrices with glass, carbon, or aramid fibers to achieve strength-to-weight ratios exceeding steel by four to six times while eliminating electrochemical corrosion. Filament winding produces the highest-pressure ratings through automated fiber tension control, while hand layup retains cost advantages for large-diameter chemical storage tanks below ten bar operating pressure. Chemical processing applications lead absolute volume through reactor and separator demand, yet water treatment infrastructure represents the fastest-expanding segment as utilities replace aging concrete and steel assets.
EPA corrosion prevention standards and OSHA process safety management rules govern US installations, while REACH chemical compatibility testing and CE pressure equipment directives shape European procurement specifications. China's GB standards and MEE environmental enforcement tighten manufacturing quality thresholds for domestic and export supply. Stakeholders must monitor regulatory divergence between ASME RTP-1 and EN 13121 design codes as certification fragmentation threatens cross-border project economics.
Market Dynamics
The FRP vessels market is bifurcating around pressure-rated containment systems versus atmospheric storage, with filament-wound carbon fiber technology pulling capital toward hydrogen infrastructure and corrosive chemical handling applications.
Growth Catalysts
- EU Green Deal decarbonization mandates:Hydrogen transport and storage targets are accelerating Type 4 composite cylinder deployment across industrial gas networks in Germany, the Netherlands, and Denmark.
- China's petrochemical capacity expansion:MEE environmental enforcement is mandating corrosion-resistant reactor vessels in new refinery and chemical complex construction along the Yangtze River Delta.
- Automated filament winding:Precision fiber tension control is extending pressure ratings beyond 700 bar for hydrogen mobility applications while reducing manufacturing defect rates.
Market Restraints
- Epoxy resin price volatility:Bisphenol-A and amine hardener feedstock costs fluctuate with crude oil derivatives, compressing margins for hand layup tank producers.
- Carbon fiber supply concentration:Toray, SGL Carbon, and Hexcel control 70% of aerospace-grade fiber output, creating allocation risk for pressure vessel manufacturers scaling hydrogen storage.
- ASME RTP-1 versus EN 13121 code divergence:Certification incompatibility forces dual design cycles for exporters, adding engineering cost and delivery delays.
Strategic Opportunities
- India's water infrastructure deficit:Jal Jeevan Mission rural distribution networks require 100,000+ composite storage tanks, with BIS IS 12709 standards opening to FRP alternatives.
- Offshore wind platform ballast:Seawater-resistant FRP caissons are displacing coated steel in floating turbine foundations for North Sea installations.
- Japan's ammonia fuel transition:METI hydrogen-ammonia co-firing roadmaps are creating demand for low-temperature composite pressure vessels at power plant conversion sites.
Industry Challenges
- Filament winding technician scarcity:Automated programming and composite laminate engineering skills concentrate in aerospace supply chains, leaving pressure vessel producers competing for talent.
- Multi-code certification timelines:Simultaneous ASME, CE, and GB standard approvals extend product qualification from 18 to 36 months for global project suppliers.
- End-of-life thermoset recycling:Pyrolysis and solvolysis infrastructure for decommissioned chemical tanks remains underdeveloped, exposing owners to landfill liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global FRP Vessels Market |
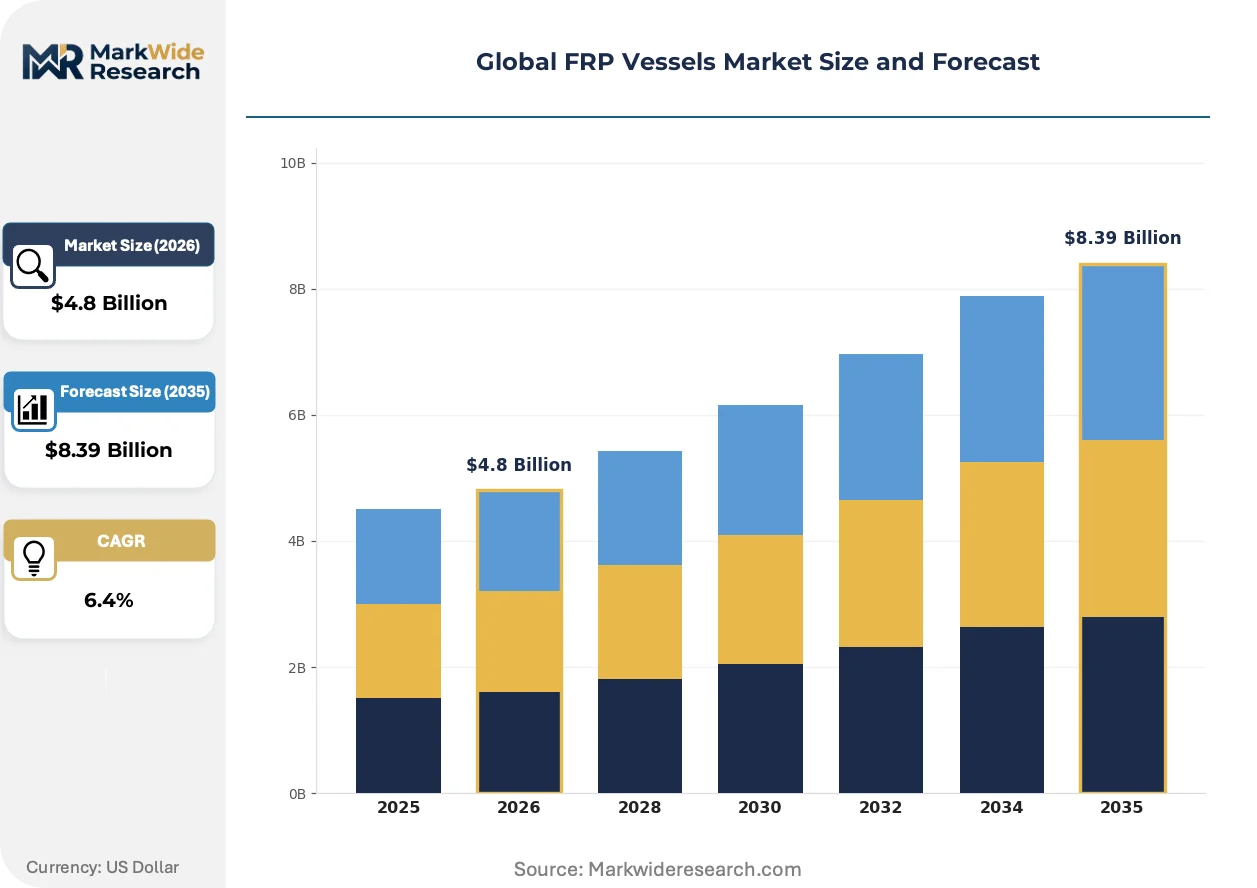
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Vessels, Storage Tanks, Chemical Reactors, Heat Exchangers, Separators Technology: Filament Winding, Hand Layup, Spray-up, Pultrusion, Resin Transfer Molding Application: Chemical Processing, Water Treatment, Food & Beverage, Pharmaceutical Manufacturing, Pulp & Paper End User: Oil Refineries, Metallurgical Plants, Water Utilities, Beverage Producers, Biopharmaceutical Firms |
| Companies Covered | Everest Kanto Cylinders, Faber Industrie, Hexagon Composites ASA, NOV, Future Pipe Industries, Luxfer Group, Quantum Fuel Systems, Plasticon Composites, Worthington Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global FRP Vessels Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are converging to reshape vessel design priorities, with sustainability compliance and hydrogen containment emerging as the dominant innovation vectors.
Continuous fiber thermoplastic composites are integrating into high-cycle pressure vessel applications, combining polyamide or PEEK matrices with glass or carbon reinforcement to enable automated welding and end-of-life recyclability. Automotive and aerospace suppliers are piloting these materials for hydrogen fuel cell vehicle tanks, seeking to bypass thermoset curing bottlenecks. The technology is integrating pressure vessel manufacturing into existing thermoplastic component supply chains, compressing lead times and enabling localized production.
REACH SVHC candidate list expansion is restricting legacy vinyl ester and polyester resin formulations across EU chemical processing installations. ECHA substance evaluation is driving substitution toward bio-based epoxy and furan resin systems with improved styrene emission profiles. German and Belgian chemical processors are front-running compliance by specifying next-generation resin matrices in new procurement tenders, forcing reformulation across Mediterranean and Eastern European fabricators.
Asset life-cycle service contracts are displacing transactional vessel sales in municipal water treatment and industrial chemical storage. French and Italian utilities are bundling 25-year composite tank provision with inspection, repair, and decommissioning obligations, transferring technical risk to manufacturers. This model concentrates contract awards among vertically integrated fabricators with in-service monitoring capabilities, squeezing pure-play tank producers from large-scale infrastructure programs.
Global FRP Vessels Market Segmentation
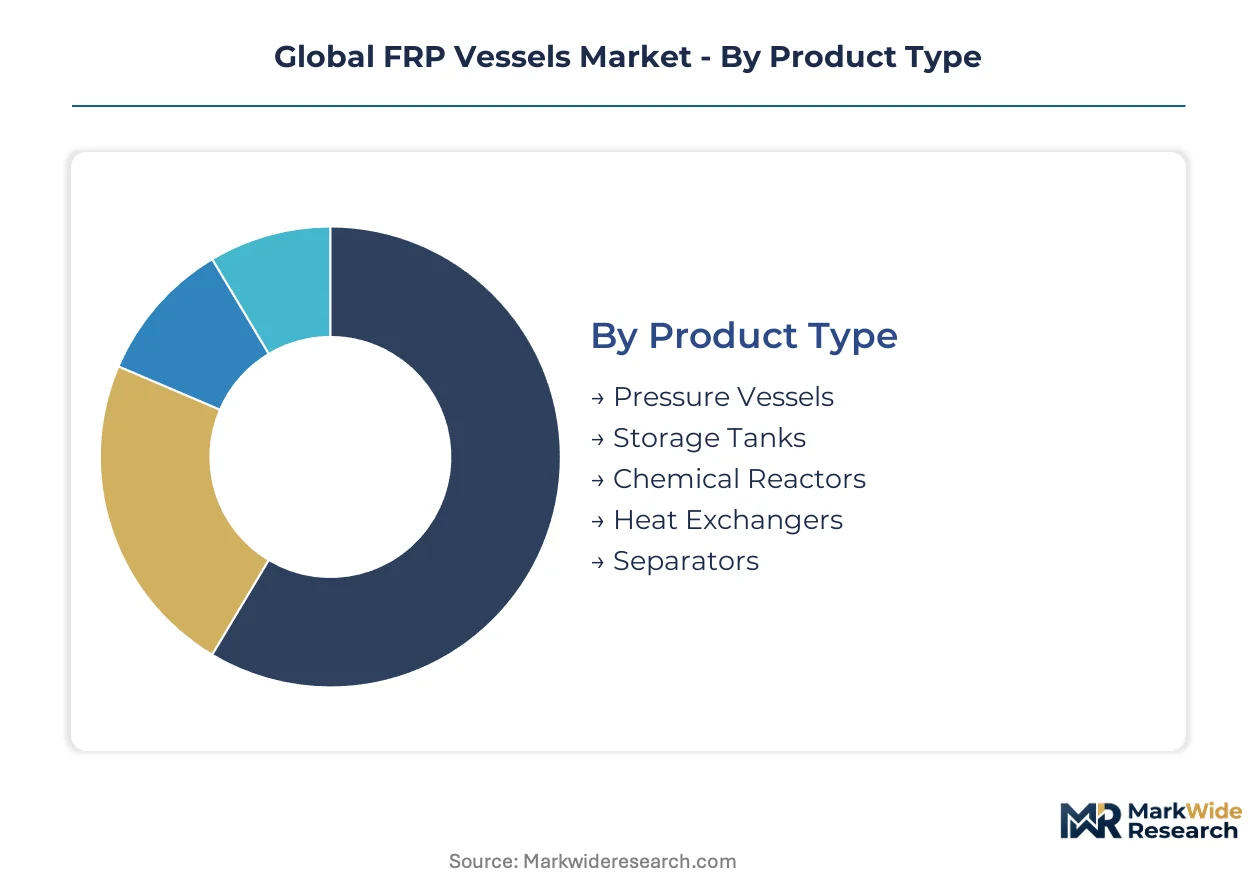
FRP vessel procurement patterns diverge sharply across pressure ratings, manufacturing methods, and regulatory exposure. Buyers in hydrogen infrastructure, chemical processing, and municipal water sectors apply fundamentally different specification filters that reshape vendor selection and pricing structures.
Product Type:
Pressure tolerance and containment duty separate buyers into distinct specification tiers with non-overlapping vendor pools.
- Pressure Vessels:Filament-wound carbon fiber construction achieves operating pressures exceeding 700 bar for hydrogen mobility and industrial gas containment. German and Dutch hydrogen transport networks are mandating Type 4 composite cylinders under EU Green Deal targets, concentrating procurement among certified high-pressure specialists.
- Storage Tanks:Large-diameter atmospheric and low-pressure tanks dominate absolute unit volumes through chemical processing and water infrastructure demand. China's MEE environmental enforcement is accelerating FRP tank deployment in Yangtze River Delta refinery complexes to replace corroded steel assets.
- Chemical Reactors:Corrosion-resistant vessel internals handle aggressive chemistries in specialty chemical and pharmaceutical synthesis.
- Heat Exchangers:FRP shell-and-tube designs eliminate fouling in brine and acid service applications.
- Separators:Three-phase separation vessels deploy in offshore oilfield environments where saltwater exposure degrades conventional steel.
Storage tanks lead volumes today; pressure vessels are gaining share fastest.
Technology:
Automation intensity and fiber tension precision determine which fabricators can access premium hydrogen and chemical processing contracts.
- Filament Winding:Automated fiber placement with computerized tension control produces the highest-pressure ratings and lowest defect rates. REACH SVHC restrictions on legacy resins are forcing German and Belgian processors to qualify next-generation epoxy matrices for this equipment class.
- Hand Layup:Manual lamination retains cost advantages for large-diameter tanks below ten bar operating pressure. Indian Jal Jeevan Mission rural water programs are specifying hand-layup composite tanks under revised BIS IS 12709 standards.
- Spray-up:Chopped glass deposition suits medium-volume chemical tank production with moderate corrosion duty.
- Pultrusion:Continuous profile manufacturing produces structural shapes and small-diameter piping components.
- Resin Transfer Molding:Closed-mold infusion enables complex geometries with controlled styrene emissions for food-contact applications.
Hand layup commands the largest installed base; filament winding is climbing the fastest.
Application:
Regulatory chemistry restrictions and asset replacement cycles are resequencing priority across end-use sectors.
- Chemical Processing:Reactor vessels, acid storage, and scrubber systems handle sulfuric, hydrochloric, and sodium hypochlorite chemistries. ECHA substance evaluation is driving EU processors toward bio-based epoxy and furan resin systems with improved emission profiles.
- Water Treatment:Municipal distribution, desalination, and wastewater infrastructure represents the steepest expansion trajectory as utilities replace aging concrete and steel. French and Italian utilities are bundling 25-year service contracts with composite tank provision.
- Food & Beverage:Potable water storage and processing vessels require FDA-compliant resin formulations and extraction testing.
- Pharmaceutical Manufacturing:High-purity water systems and solvent containment demand validated cleaning protocols.
- Pulp & Paper:Chlorine dioxide and white liquor handling vessels resist aggressive bleaching chemistries.
Chemical processing anchors current revenue; water treatment is expanding most quickly.
End User:
Capital intensity and technical risk tolerance shape whether buyers favor transactional procurement or integrated service contracts.
- Oil Refineries:Corrosion-resistant crude unit overhead systems and sour water strippers operate in hydrogen sulfide environments. China's petrochemical capacity additions along the Bohai Rim are mandating FRP vessel specifications under tightened MEE enforcement.
- Water Utilities:Municipal storage and distribution networks favor long-term service agreements over equipment purchase. Asset life-cycle contracts are displacing transactional sales in French and Italian infrastructure programs.
- Metallurgical Plants:Acid pickling lines and electrowinning tankhouses deploy FRP containment for sulfuric and hydrofluoric acid service.
- Beverage Producers:Carbonated soft drink and brewing operations specify FDA-compliant storage for ingredient water and syrups.
- Biopharmaceutical Firms:Single-use compatible vessels and validated cleaning systems support batch pharmaceutical manufacturing.
Water utilities dominate unit demand; oil refineries command the highest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium hydrogen containment contracts, whereas India concentrates atmospheric storage tank procurement for rural water infrastructure. Regulatory divergence between ASME RTP-1 and EN 13121 codes fragments cross-border project economics.
United States
EPA corrosion prevention standards and OSHA process safety management rules govern chemical processing installations. Hydrogen mobility pilots in California and Texas accelerate Type 4 composite cylinder deployment for fuel cell vehicle refueling networks. Houston anchors offshore oilfield demand where NOV supplies saltwater-resistant separation vessels.
Germany
EU Green Deal decarbonization mandates drive Type 4 composite cylinder procurement for industrial hydrogen transport networks. ECHA REACH SVHC restrictions force reformulation toward bio-based epoxy matrices in chemical processing applications. The Ruhr industrial cluster sees fabricators qualifying next-generation resin systems for filament-wound pressure equipment.
China
MEE environmental enforcement mandates corrosion-resistant reactor vessels in Yangtze River Delta petrochemical expansions. GB standards tighten manufacturing quality thresholds for domestic and export supply chains. Bohai Rim refinery complexes specify FRP sour water strippers under tightened emissions controls.
India
Jal Jeevan Mission rural distribution networks require over 100,000 composite storage tanks for potable water infrastructure. BIS IS 12709 standards are opening to FRP alternatives for municipal procurement. Gujarat and Maharashtra industrial corridors deploy hand-layup tanks for chemical processing and water treatment applications.
Japan
METI hydrogen-ammonia co-firing roadmaps create demand for low-temperature composite pressure vessels at power plant conversion sites. JIS standards govern high-pressure containment specifications for industrial gas networks. Osaka-Kobe manufacturing belt concentrates filament-winding expertise for hydrogen infrastructure export contracts.
Global FRP Vessels Market Competitive Landscape
Top-tier vendors anchor high-pressure hydrogen and offshore containment segments, while mid-tier fabricators compete on atmospheric storage tank volumes. The market structures around certification depth, with ASME RTP-1 and CE marking holders accessing premium project economics. Three archetypes dominate: filament-wound carbon fiber specialists, hand-layup chemical tank producers, and vertically integrated service contract providers. Competitive moves concentrate on multi-code certification acquisition and automated manufacturing capacity expansion.
Among the named players, Hexagon Composites ASA and Everest Kanto Cylinders occupy positions within the high-pressure containment archetype, exemplifying the filament-wound carbon fiber specialization vector. NOV represents the offshore oilfield application segment where saltwater corrosion resistance commands premium specifications. These three companies illustrate how geographic clustering around hydrogen infrastructure, industrial gas distribution, and offshore energy shapes competitive positioning without overlapping customer segments.
| Leading Market Players |
|---|
| Everest Kanto Cylinders |
| Faber Industrie |
| Hexagon Composites ASA |
| NOV |
| Future Pipe Industries |
| Luxfer Group |
| Quantum Fuel Systems |
| Plasticon Composites |
| Worthington Industries |
| Others |
Supply & Pricing Matrix
EU Green Deal decarbonization mandates gate qualified supply and premium-tier pricing access, as hydrogen infrastructure certification requirements concentrate procurement among filament-wound specialists while excluding commodity tank producers from high-pressure contracts.
Pricing Analysis
Capacity additions in China are reshaping price floors for atmospheric storage tanks, compressing margins for hand-layup producers serving chemical processing and water infrastructure. Pricing stratifies across ASME-certified pressure equipment, CE-marked industrial containment, and uncertified commodity storage tiers. Price differentiation hinges on certification depth and fiber grade, with carbon fiber-reinforced Type 4 cylinders commanding substantial premiums over glass-reinforced alternatives. Cost compression in the hand-layup segment is intensifying because epoxy resin feedstock volatility squeezes producers without long-term supply agreements. Municipal water utilities exhibit the highest price sensitivity, whereas hydrogen mobility developers prioritize performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Toray, SGL Carbon, and Hexcel controlling aerospace-grade carbon fiber output, exposing pressure vessel manufacturers to allocation risk during hydrogen infrastructure scaling. Manufacturing concentrates in China, Germany, and India, with filament-winding automation clustering around the Ruhr and Osaka-Kobe industrial belts. Raw material dependencies span carbon fiber tow, epoxy resin systems, and amine hardeners. Tariff exposure on carbon fiber imports threatens cost structures for European and North American fabricators lacking captive supply. Distribution runs through project-based EPC channels for industrial installations and OEM direct supply for hydrogen mobility applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU Green Deal hydrogen storage targets and China's MEE environmental enforcement together accelerating corrosion-resistant vessel deployment across industrial gas and petrochemical sectors.
For Market Incumbents: Anchor filament-winding automation capacity in hydrogen corridor geographies to defend against emerging thermoplastic composite entrants. Secure backward integration into carbon fiber prepreg supply through long-term offtake agreements with Toray or SGL Carbon. Invest in simultaneous ASME RTP-1, CE marking, and GB standard certification to capture cross-border project economics without dual engineering cycles. For New Entrants and Emerging Players: Continuous fiber thermoplastic composites offer a technology-first wedge into automotive hydrogen fuel cell vehicle tank supply chains, bypassing thermoset curing bottlenecks that constrain incumbent throughput. Target India's Jal Jeevan Mission rural water infrastructure, where BIS IS 12709 standard revisions have opened municipal procurement to FRP alternatives with limited established supplier presence. Pursue joint development agreements with European automotive OEMs seeking localized, recyclable pressure vessel sourcing. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier hand-layup tank fabricators because asset life-cycle service contract bundling is displacing transactional sales and concentrating awards among vertically integrated providers. Five-to-ten-year viability hinges on successful certification portfolio expansion and in-service monitoring capability acquisition. Watch for ECHA REACH SVHC list expansion announcements as the signal indicating accelerated resin reformulation investment requirements across European chemical processing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Code Certification Acquisition | Simultaneous ASME RTP-1, CE marking, and GB qualification unlocks cross-border hydrogen and chemical project participation. |
| Filament-Winding Automation Scale-Up | Computerized tension control capacity expansion reduces defect rates for 700-bar hydrogen containment applications. |
| Carbon Fiber Supply Agreement | Long-term prepreg offtake with Toray or SGL Carbon mitigates allocation risk during aerospace demand surges. |
| Asset Life-Cycle Service Contract | Twenty-five-year bundled provision with inspection and decommissioning obligations transfers technical risk from utilities to manufacturers. |
| Thermoplastic Composite Pilot Line | Polyamide or PEEK matrix development enables automotive OEM integration and end-of-life recyclability compliance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at chemical processing facilities, procurement leads at hydrogen infrastructure developers, filament-winding equipment specialists, and aftermarket service directors with secondary validation through customs trade data, ACC and Cefic industry reports, SEC 10-K filings from listed composites manufacturers, and ECHA substance evaluation databases. Bottom-up vessel shipment aggregation and top-down end-use demand estimation were cross-referenced for triangulation.
Segment-weighting approaches modeled pressure rating tiers, manufacturing method automation levels, resin matrix chemistry classes, and regional regulatory framework clusters across the projection horizon. CAGRs were derived from installed base replacement cycles, capacity expansion announcements, and hydrogen infrastructure deployment roadmaps. Industry-specific forecast inputs included MEE environmental enforcement timelines for Yangtze River Delta petrochemical complexes and EU Green Deal hydrogen storage target trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon fiber supply allocation decisions, REACH SVHC list expansion scope, and thermoplastic composite qualification timelines in automotive applications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market
Composite Materials
FRP Reactor Market
Composite Materials
Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
Europe Aluminium Composite Panel Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
Molded Underfill Material Market
Composite Materials
Structural Composites Market
Composite Materials
Global Carbon Fiber Resin Market
Composite Materials
Low Temperature Sealing Glass Composite Powder Market
Composite Materials
Marine Composites Market
Composite Materials
Decorative High-Pressure Laminates Market
Composite Materials
Composite Cans Market
Composite Materials
Global Carbon Fiber Composite Heating Elements Market
Composite Materials
Polypropylene and Polypropylene Composites Market
Composite Materials
Global Sports Composites Market