
 Metal Forming Fluids Market | 2026-2036
Metal Forming Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Forming Fluids Market Outlook
Consolidation among tier-one automotive stampers is recalibrating procurement volumes and technical specifications across the supply base. Quaker Houghton leverages its integrated metalworking chemistry platform to serve high-volume OEM contracts in North America. Fuchs SE anchors European demand through specialized cold-rolling and deep-drawing fluid formulations. Blaser Swisslube differentiates via precision machining expertise in the premium segment.
Metal forming fluids are lubricating coolants formulated with mineral oils, synthetic esters, or water-soluble polymers, engineered to reduce friction and dissipate heat during deformation processes at pressures exceeding 1,000 MPa. Their primary purpose is to prevent galling and tool wear while enabling tight dimensional tolerances in stamped, drawn, or extruded metal components. Synthetic fluids command expanding share in aerospace stamping applications where thermal stability and extended sump life offset higher unit cost. Oil-based formulations retain dominance in heavy-gauge construction equipment forming where extreme-pressure additives protect carbide tooling. Water-based emulsions lead metalworking shop environments through lower mist generation and easier waste-treatment compliance.
REACH restrictions on boron and chlorinated paraffins, EPA reporting requirements under TSCA Section 8(a), and OSHA permissible exposure limits for metalworking fluid mist collectively reshape formulation priorities and facility capital planning. The EU Green Deal's chemical sustainability targets are accelerating biodegradable formulation development, while EPA enforcement of effluent guidelines tightens discharge standards for metalworking operations. Stakeholders must monitor regulatory divergence between jurisdictions and align R&D pipelines accordingly.
Market Dynamics
REACH and EU Green Deal mandates are forcing formulators to eliminate boron and formaldehyde releasers from water-based fluids, compressing R&D timelines and raising compliance costs across European supply chains.
Growth Catalysts
- Sustainability Mandates:The EU Green Deal's chemical sustainability targets accelerate demand for biodegradable ester formulations in precision metalworking clusters.
- Automotive Lightweighting:OEM stampers in Germany adopt high-performance synthetics to enable aluminum-intensive body-in-white production.
- Aerospace Thermal Requirements:Extended sump life specifications from Tier-1 aerospace suppliers pull synthetic fluid adoption in high-pressure forming operations.
Market Restraints
- Base Oil Volatility:Group II/III mineral oil price swings compress margin predictability for legacy emulsion suppliers.
- Additive Supply Concentration:Extreme-pressure additive production concentrates in Northeast Asian chemical corridors, exposing formulators to freight and tariff risk.
- Substitution Pressure:Dry film lubricants and plasma-assisted forming displace fluid-intensive processes in select precision stamping niches.
Strategic Opportunities
- India Manufacturing Expansion:PLI scheme incentives for automotive and white goods production create first-mover advantage for localized biodegradable fluid supply.
- Closed-Loop Fluid Management:Reconditioning-as-a-service models penetrate high-volume German stamping operations seeking waste reduction.
- Hydrogen Infrastructure Fabrication:Cryogenic-compatible forming fluids address emerging demand from high-pressure vessel manufacturing for hydrogen storage.
Industry Challenges
- Tribology Talent Scarcity:Formulation chemists with expertise in high-pressure metal deformation command premium compensation, constraining mid-tier R&D expansion.
- Multi-Jurisdiction Certification Lag:Divergent EPA effluent guidelines and REACH substance restrictions force parallel testing protocols, extending product launch timelines.
- Legacy Equipment Compatibility:Synthetic ester incompatibility with older sump monitoring systems requires costly retrofitting at independent job shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Forming Fluids Market |
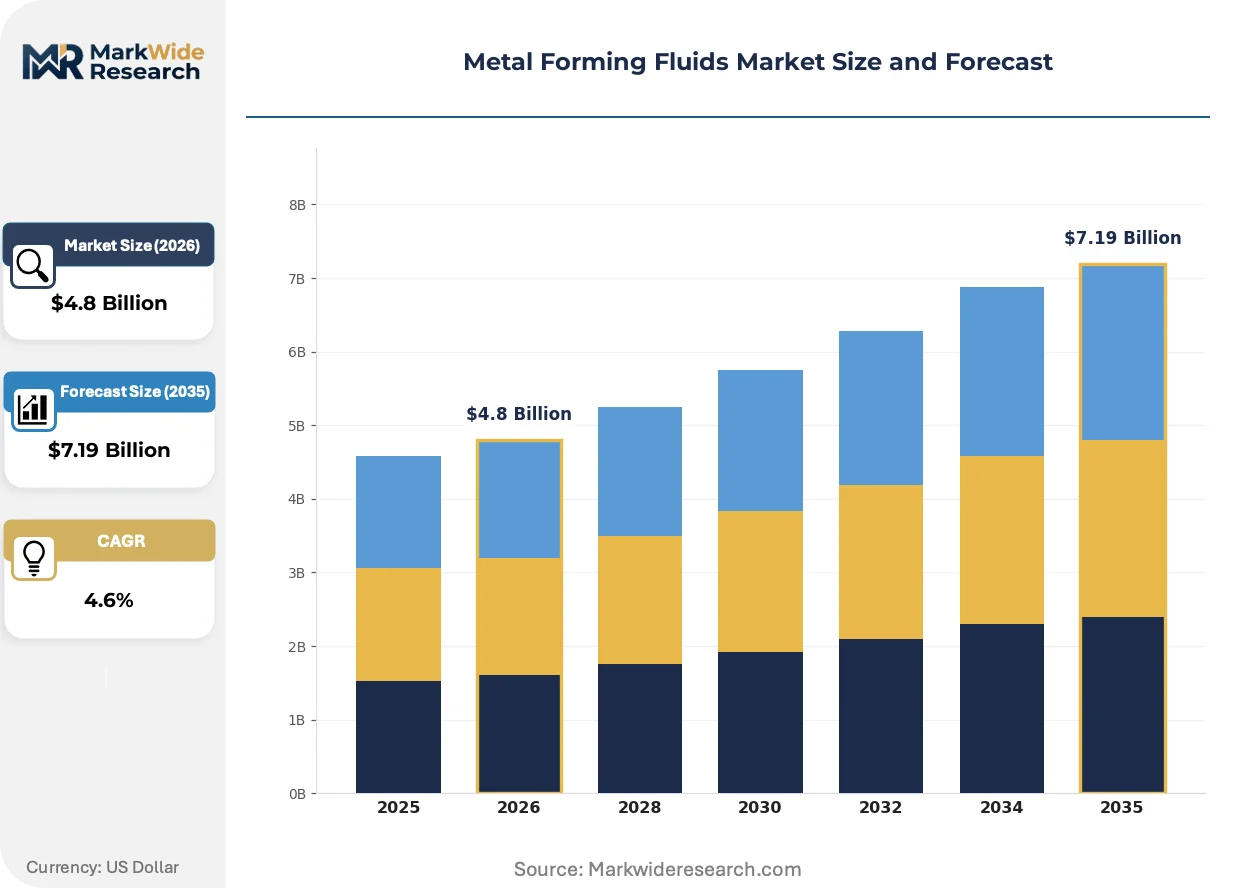
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Fluids, Oil-Based Fluids, Emulsifiable Fluids, Synthetic Fluids End User: Aerospace, Automotive Manufacturing, Metalworking Shops, Construction Equipment Application: Stamping, Drawing, Machining, Extrusion Formulation: Biodegradable, Additive-Enriched, Non-Toxic, High-Performance |
| Companies Covered | Quaker Houghton, Fuchs SE, ExxonMobil, BP, TotalEnergies, Chevron, Houghton International, Blaser Swisslube, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Forming Fluids Market Strategic Shifts
Digital fluid monitoring systems and bio-based chemistry platforms are converging to transform how metal formers manage consumption, waste, and tool life across distributed production networks.
Smart sensor arrays embedded in stamping press sumps are modularizing maintenance workflows by enabling predictive additive replenishment and real-time contamination alerts. Tier-1 automotive stampers in Stuttgart and Wolfsburg deploy these systems to compress unplanned downtime intervals. The technology is modularizing traditional preventive maintenance schedules into condition-based interventions that reduce fluid waste volumes.
REACH restrictions on chlorinated paraffins and boron derivatives force reformulation of legacy extreme-pressure additives across European metalworking operations. ECHA substance evaluation timelines compress supplier response windows to 18-24 months. German precision forming clusters accelerate adoption of sulfurized ester and ionic liquid alternatives to maintain tool protection standards.
Fluid-as-a-service contracting is displacing transactional bulk purchasing among high-volume OEM stampers seeking to transfer technical risk to suppliers. Quaker Houghton and Fuchs SE pilot outcome-based agreements tied to tool life metrics rather than volume throughput. This model concentrates in North American automotive contracts where procurement functions seek working capital efficiency.
Metal Forming Fluids Market Segmentation
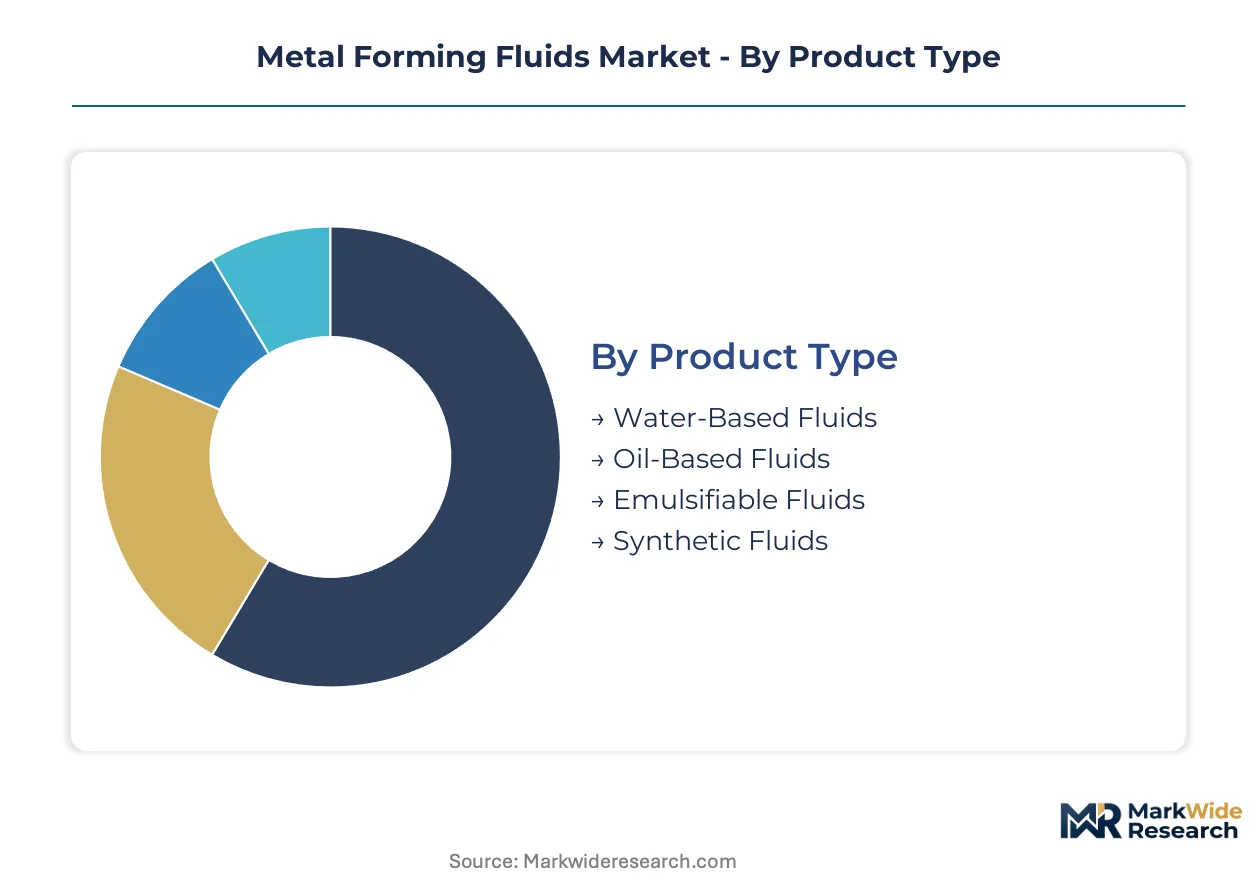
Metal forming fluid procurement diverges sharply across end-use industries, with aerospace and automotive buyers prioritizing thermal stability and sump longevity while metalworking shops optimize for mist control and waste-treatment simplicity. Formulation chemistry and application severity further stratify technical specifications, creating distinct supply relationships between fluid formulators and equipment OEMs.
Product Type:
Cost tier separates buyers in this category, with premium synthetics commanding 3-4x unit pricing against commodity emulsions and driving divergent R&D investment patterns among suppliers.
- Synthetic Fluids:Engineered from polyalkylene glycol and ester base stocks, these formulations deliver thermal stability above 150°C and extended sump life exceeding 12 months. Demand concentrates in aerospace stamping operations around Toulouse and Seattle where tool protection specifications justify premium unit economics.
- Water-Based Fluids:Dilutable concentrates combining mineral oil, emulsifiers, and corrosion inhibitors form the workhorse of high-volume automotive stamping. German OEM stampers in Stuttgart and Wolfsburg specify these formulations for aluminum body-in-white production, balancing cooling efficiency against boron-free compliance mandates.
- Oil-Based Fluids:Straight mineral oil formulations with extreme-pressure sulfur-phosphorus additives dominate heavy-gauge forming of construction equipment components in Caterpillar and Komatsu supply chains.
- Emulsifiable Fluids:Semi-synthetic concentrates offering intermediate performance between straight oils and full synthetics find adoption in independent job shops seeking formulation flexibility across mixed metal workloads.
Water-based formulations lead volumes today; synthetic fluids are gaining share fastest.
End User:
Application severity and regulatory exposure differentiate buyers, with aerospace and automotive facing the most stringent substance restrictions while construction equipment prioritizes extreme-pressure performance over environmental compliance.
- Automotive Manufacturing:OEM stampers and tier-one suppliers drive specification authority, mandating REACH-compliant formulations and digital sump monitoring integration. German clusters around Stuttgart and Wolfsburg anchor European demand for high-performance synthetics in aluminum-intensive platforms.
- Aerospace:Tier-1 suppliers including Spirit AeroSystems and GKN Aerospace impose extended sump life requirements and thermal stability specifications that pull synthetic fluid adoption. Formulators must navigate FAA fire-resistance standards alongside REACH substance restrictions.
- Metalworking Shops:Independent job shops prioritize mist control and waste-treatment simplicity, favoring water-based emulsions with lower OSHA exposure compliance burdens.
- Construction Equipment:Heavy-gauge forming of structural components for excavators and loaders retains oil-based formulations where extreme-pressure additives protect carbide tooling under deformation pressures exceeding 1,500 MPa.
Automotive manufacturing dominates current procurement volumes; aerospace specifications are climbing the fastest.
Application:
Process kinematics and contact pressure separate applications, with high-speed stamping demanding thermal management and deep-drawing requiring boundary lubrication under sustained loads.
- Stamping:High-speed progressive die operations generate friction heat exceeding 200°C at die-metal interfaces, requiring formulations with rapid film formation and thermal conductivity. Automotive body panel production in Germany and the US Midwest concentrates demand for synthetic and semi-synthetic chemistries.
- Drawing:Deep-drawing of cylindrical and box-shaped components subjects fluid films to sustained hydrostatic pressure, driving specification of extreme-pressure additives in stainless steel and aluminum beverage can manufacturing.
- Extrusion:Continuous deformation of aluminum and copper profiles requires lubricants compatible with elevated billet temperatures, with synthetic esters displacing graphite-based formulations in precision architectural extrusion.
- Machining:Cutting and grinding operations intersect with metal forming fluid portfolios in hybrid manufacturing cells, particularly in aerospace structural component production.
Stamping commands the largest fluid consumption footprint; drawing applications are expanding most quickly.
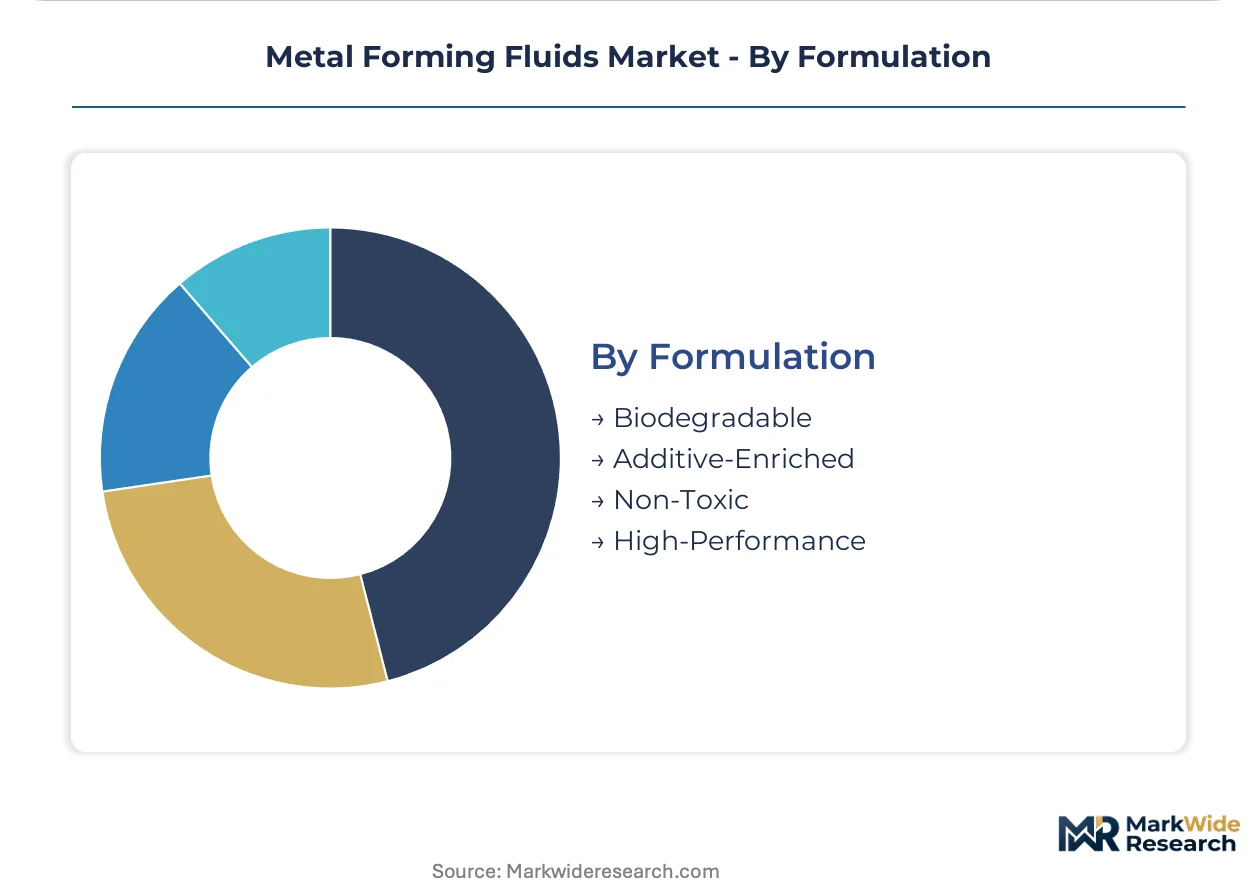
Formulation:
Regulatory jurisdiction and sustainability target maturity differentiate buyers, with EU-based manufacturers accelerating biodegradable adoption while North American facilities prioritize performance certification.
- Biodegradable:Ester-based formulations meeting OECD 301B biodegradability thresholds capture specification share in German precision metalworking clusters facing EU Green Deal chemical sustainability targets. Vegetable oil and synthetic ester base stocks command premium positioning against mineral oil alternatives.
- High-Performance:Formulations engineered for extended sump life and multi-metal compatibility address total cost-of-ownership optimization in high-volume automotive contracts, with synthetic platforms dominating this specification tier.
- Additive-Enriched:Concentrated packages of extreme-pressure agents, corrosion inhibitors, and biocides allow end-users to customize fluid performance across varying water hardness and metal alloy combinations.
- Non-Toxic:Formaldehyde-releaser-free and boron-free formulations address REACH substance restrictions and OSHA hazard communication requirements in European and North American facilities respectively.
Additive-enriched formulations retain the largest installed base; biodegradable specifications are ascending the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium fluid consumption through precision metalworking density, while the United States sustains high-volume demand across automotive and aerospace supply chains. China scales manufacturing capacity for domestic automotive stampers. India builds localized supply under industrial policy incentives. Japan maintains exacting formulation standards for precision component exports.
Germany
Automotive OEM stampers and tier-one suppliers drive specification authority for REACH-compliant synthetics. The EU Green Deal accelerates biodegradable ester adoption timelines. Stuttgart and Wolfsburg clusters anchor European demand for aluminum body-in-white forming fluids.
United States
Aerospace tier-one suppliers and automotive OEMs pull extended-sump-life synthetic formulations. EPA TSCA Section 8(a) reporting requirements reshape formulation transparency obligations. Seattle-Tacoma aerospace corridor and Detroit automotive belt concentrate high-performance fluid procurement.
China
Domestic automotive stamping expansion and white goods manufacturing scale emulsion consumption. MIIT industrial standards and dual carbon goals pressure local formulators toward cleaner chemistries. Yangtze River Delta precision metalworking clusters upgrade from commodity emulsions to semi-synthetics.
India
PLI scheme incentives for automotive and appliance manufacturing attract first-mover biodegradable fluid suppliers. BIS standards alignment with REACH substance restrictions lags, creating formulation complexity. Tamil Nadu and Maharashtra automotive corridors drive volume growth in water-based emulsions.
Japan
Precision component exporters and domestic machine tool builders demand thermal-stable synthetics for micro-forming applications. METI chemical management guidelines and JIS standards enforce formulation consistency. Nagoya automotive and Kansai machinery clusters sustain premium pricing for high-performance chemistries.
Metal Forming Fluids Market Competitive Environment
German producers anchor one tier through specialized cold-rolling and deep-drawing formulations; North American integrated chemistry platforms hold high-volume OEM contract positions. The vendor base stratifies across three tiers: multinational integrated suppliers, regional formulation specialists, and national distributors with blending capabilities. Competitive moves concentrate on fluid-as-a-service contracting models and reconditioning service network expansion.
Within the integrated chemistry tier, Quaker Houghton and Fuchs SE exemplify divergent geographic anchoring strategies. Quaker Houghton occupies a position tied to North American automotive procurement consolidation. Fuchs SE represents European precision metalworking specialization. Blaser Swisslube sits within the premium precision machining segment, demonstrating how geographic origin signals formulation philosophy.
| Leading Market Players |
|---|
| Quaker Houghton |
| Fuchs SE |
| ExxonMobil |
| BP |
| TotalEnergies |
| Chevron |
| Houghton International |
| Blaser Swisslube |
| Henkel |
| Others |
Value Chain & Pricing Dynamics
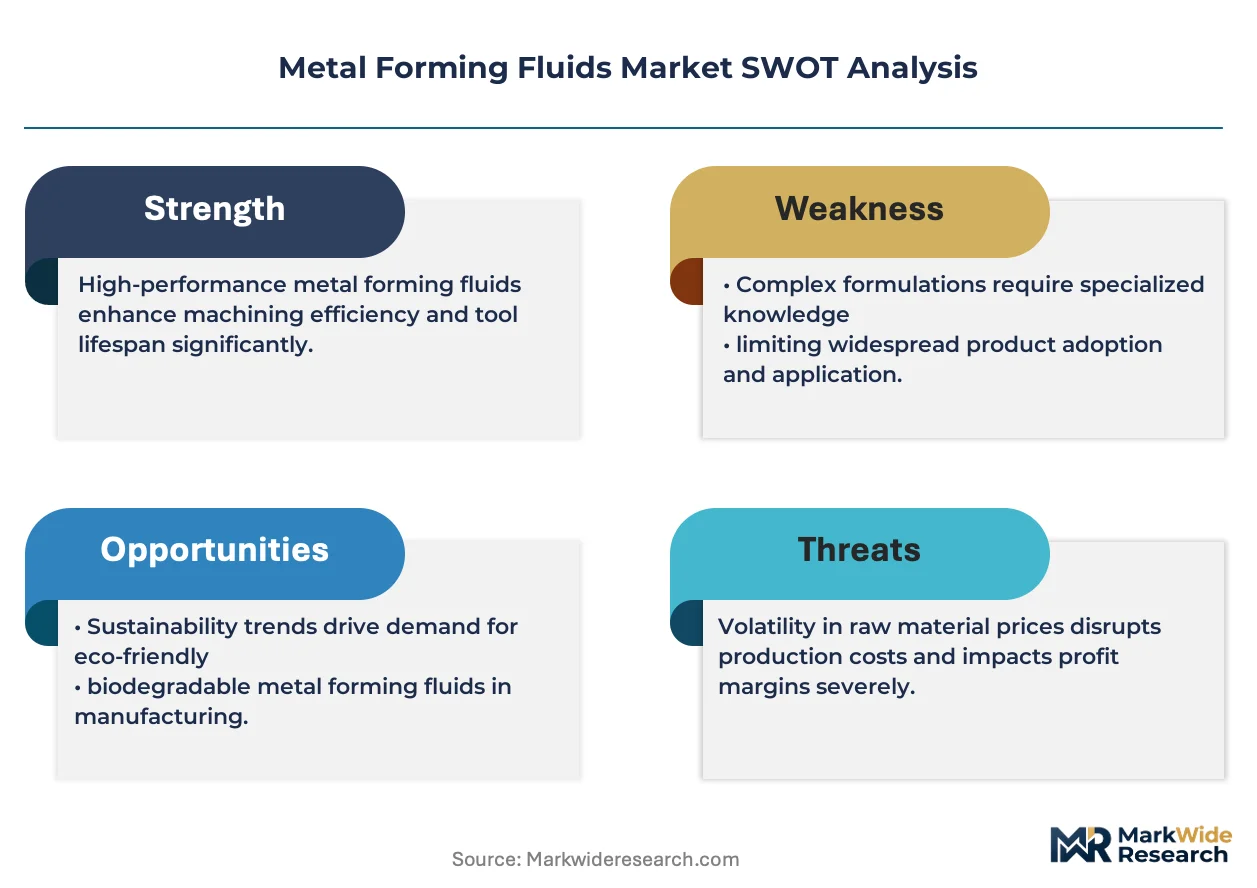
REACH-mandated elimination of boron and formaldehyde releasers from water-based formulations is compressing R&D timelines and forcing supply chains to absorb reformulation costs across European metalworking clusters.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity emulsion concentrates, while German precision formulators maintain premium positioning through REACH-compliant synthetic platforms. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade synthetics from automotive water-based formulations and job-shop mineral oil blends. Price differentiation hinges on certification tier and volume scale, with OEM stampers securing contract-based long-term offtake agreements. Cost compression in mid-tier semi-synthetics is intensifying because of Group II/III base oil volatility. Independent job shops exhibit highest price sensitivity; aerospace tier-one suppliers demonstrate lowest sensitivity due to tool-life total cost-of-ownership calculations.
Supply Chain Analysis
Extreme-pressure additive production rests on Japanese and South Korean specialty chemical corridors, with German and U.S. formulators dependent on Northeast Asian supply for sulfur-phosphorus packages and ionic liquid alternatives. Base oil feedstocks draw from U.S. Gulf Coast refineries and Middle Eastern crude streams, while ester base stocks for biodegradable formulations source from Malaysian and Indonesian palm oil derivatives. Single-source vulnerability concentrates in chlorinated paraffin substitutes following REACH restrictions. Distribution runs through regional blending facilities co-located with automotive stamping clusters in Stuttgart, Wolfsburg, and Detroit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in metal forming fluids stems from biodegradable premium-tier adoption outpacing commodity emulsion erosion, with sustainability premiums offsetting base oil cost volatility.
For Market Incumbents: Extend fluid-as-a-service contracting models to capture working capital efficiency demand from high-volume OEM stampers. Deepen backward integration into ester base stock production to secure supply continuity for REACH-compliant formulations. Counter dry film lubricant substitution threats by embedding smart sensor arrays in sump monitoring systems that demonstrate measurable tool-life extension. For New Entrants and Emerging Players: The 3-4x unit pricing gap between aerospace synthetics and job-shop emulsions creates entry space for mid-tier semi-synthetics with multi-metal compatibility. Target India's Tamil Nadu and Maharashtra automotive corridors where PLI scheme incentives concentrate first-mover biodegradable fluid demand. Penetrate through localized blending partnerships that navigate BIS standards alignment complexity. For Investors and Strategic Acquirers: Asymmetric upside sits with regional formulation specialists possessing captive ester synthesis capabilities and established REACH registration portfolios. Long-term viability favors suppliers with demonstrated biodegradability certification and closed-loop reconditioning service infrastructure. Watch ECHA substance evaluation timelines for boron derivative restrictions as inflection indicator for accelerated synthetic adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ester Base Stocks | Captive supply of biodegradable feedstocks insulates margins from palm oil volatility and REACH compliance delays. |
| Closed-Loop Reconditioning Service Expansion | Waste-reduction mandates from German automotive clusters pull reconditioning-as-a-service adoption. |
| Smart Sensor Array Deployment | Predictive additive replenishment compresses unplanned downtime for Stuttgart and Wolfsburg stampers. |
| Localized Blending Capacity in India | PLI scheme incentives for automotive manufacturing create first-mover advantage in biodegradable supply. |
| Hydrogen Infrastructure Fluid Development | Cryogenic-compatible formulations address emerging demand from high-pressure vessel manufacturing. |
Study Parameters
Coverage spans Germany, the United States, China, India, and Japan, with primary inputs from each market through structured interviews with formulation chemists, automotive procurement directors, aerospace tier-one supplier technical leads, and metalworking shop operations managers. Secondary validation draws from ECHA substance evaluation databases, EPA TSCA Section 8(a) filings, MIIT industrial standards publications, and customs trade data for base oil and additive flows. Bottom-up demand modeling triangulates against top-down supply capacity assessments across regional blending facilities.
Granularity-level modeling disaggregates volume and value across synthetic, water-based, oil-based, and emulsifiable fluid chemistries; automotive, aerospace, metalworking shop, and construction equipment end-use sectors; stamping, drawing, extrusion, and machining applications; and biodegradable, high-performance, additive-enriched, and non-toxic formulation tiers. CAGRs derive from segment-level growth rate reconciliation against macro manufacturing output indices and regulatory compliance timeline assumptions. Industry-specific inputs include aluminum body-in-white production forecasts and REACH substance restriction implementation schedules.
Caveats apply where ECHA evaluation timeline acceleration, EPA effluent guideline tightening, or base oil price spike magnitude could materially shift the outlook. Forecasts reflect assumptions about biodegradable formulation adoption elasticity and synthetic fluid sump life performance in high-pressure forming operations. A small set of named triggers—regulatory divergence between REACH and EPA timelines, extreme-pressure additive supply disruption, and dry film lubricant technology maturation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
North America Quicklime Market
Industrial Chemicals
Paraffin Inhibitors Market
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
Commercial Electronic Detonator Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
Global Battery Grade Lithium Hydroxide Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Heat Shrink Tubes Market
Industrial Chemicals
General Industrial Oils Market
Industrial Chemicals
Industrial Cyclohexylamine Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Decahydronaphthalene (Decalin) Market
Industrial Chemicals
Soil Treatment Chemicals Market