
 Global Carbon Graphite Bushings Market | 2026-2036
Global Carbon Graphite Bushings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbon Graphite Bushings Market Analysis
Specialized graphite machining talent is bifurcating the competitive landscape, separating shops with precision grinding capability from commodity producers. Graphite Metallizing leverages captive carbon processing to control raw material consistency across its bushing lines. SGL Carbon sustains technology leadership through isostatic pressing expertise for high-temperature grades. St Marys Carbon anchors North American supply with vertically integrated baking and impregnation operations.
Carbon graphite bushings are self-lubricating bearing components manufactured from engineered carbon-graphite composites, typically impregnated with resins or metals to achieve porosity below 15 percent and compressive strength exceeding 20,000 psi for operation in corrosive or dry environments. Their primary industrial purpose is eliminating external lubrication in pumps, valves, and rotating equipment exposed to chemicals, steam, or extreme temperatures. Self-lubricating bushings lead product type demand due to maintenance reduction in chemical processing and marine propulsion systems, while custom bushings capture premium margin pools from aerospace tier-one suppliers requiring lot-traceable material certification. Heavy machinery and marine end users represent the fastest-growing application clusters as OEMs specify dry-running bearings for underwater valves and hydroelectric turbines.
FDA food-contact regulations, EPA TSCA substance reporting, and REACH Annex XIV authorization requirements constrain resin binder chemistries and metal impregnants permitted in carbon graphite bushings sold into regulated end uses. CE marking under the EU Machinery Directive further shapes product testing protocols for European pump and valve integrators. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as PTFE-impregnated grades face prospective substitution pressure from phenolic and antimony-impregnated alternatives.
Market Dynamics
Specialized graphite machining capability is concentrating competitive advantage among shops with precision grinding and isostatic pressing assets, separating premium suppliers from commodity producers as aerospace and heavy machinery OEMs tighten material certification requirements.
Growth Catalysts
- EPA emissions rules:The Environmental Protection Agency's tightening emissions standards for industrial equipment are forcing pump and valve manufacturers toward dry-running bearings that eliminate lubricant leakage risks in chemical processing plants.
- Self-lubricating material grades:Advancements in resin and metal impregnation chemistry are extending bushing service life in corrosive environments, driving replacement demand across marine propulsion and hydroelectric turbine installations.
- Precision machining clusters:Concentrated supplier networks in Germany, China, and the United States are reducing lead times for custom aerospace bushings requiring lot-traceable material certification from tier-one integrators.
Market Restraints
- Petroleum coke price volatility:Raw material costs for synthetic graphite feedstock fluctuate with oil refining economics, compressing margins for producers without backward integration into carbon processing.
- REACH Annex XIV authorization:The European Chemicals Agency's substance restrictions on certain resin binders and metal impregnants are forcing reformulation of established product grades for EU market access.
- Ceramic bearing substitution:Silicon nitride and alumina ceramic alternatives are capturing select high-temperature applications above 500°C where graphite oxidation limits performance.
Strategic Opportunities
- India industrial infrastructure:The country's expanding chemical processing and power generation capacity creates underpenetrated demand for corrosion-resistant pump bearings as domestic OEMs expand production.
- PTFE restriction tailwinds:Anticipated per- and polyfluoroalkyl substance regulations across multiple jurisdictions are positioning phenolic and antimony-impregnated graphite grades as compliant alternatives for food-contact and marine applications.
- Additive manufacturing convergence:Binder jetting and selective laser sintering of carbon-graphite composites are enabling geometrically complex bushing designs previously impossible with conventional machining.
Industry Challenges
- Isostatic pressing operator scarcity:The specialized skill required for uniform density distribution in high-temperature grades limits production scaling at mid-cap manufacturers competing for aerospace contracts.
- CE marking compliance timelines:European pump and valve integrators face extended testing protocols under the EU Machinery Directive, delaying product launches for bushing suppliers without established notified body relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbon Graphite Bushings Market |
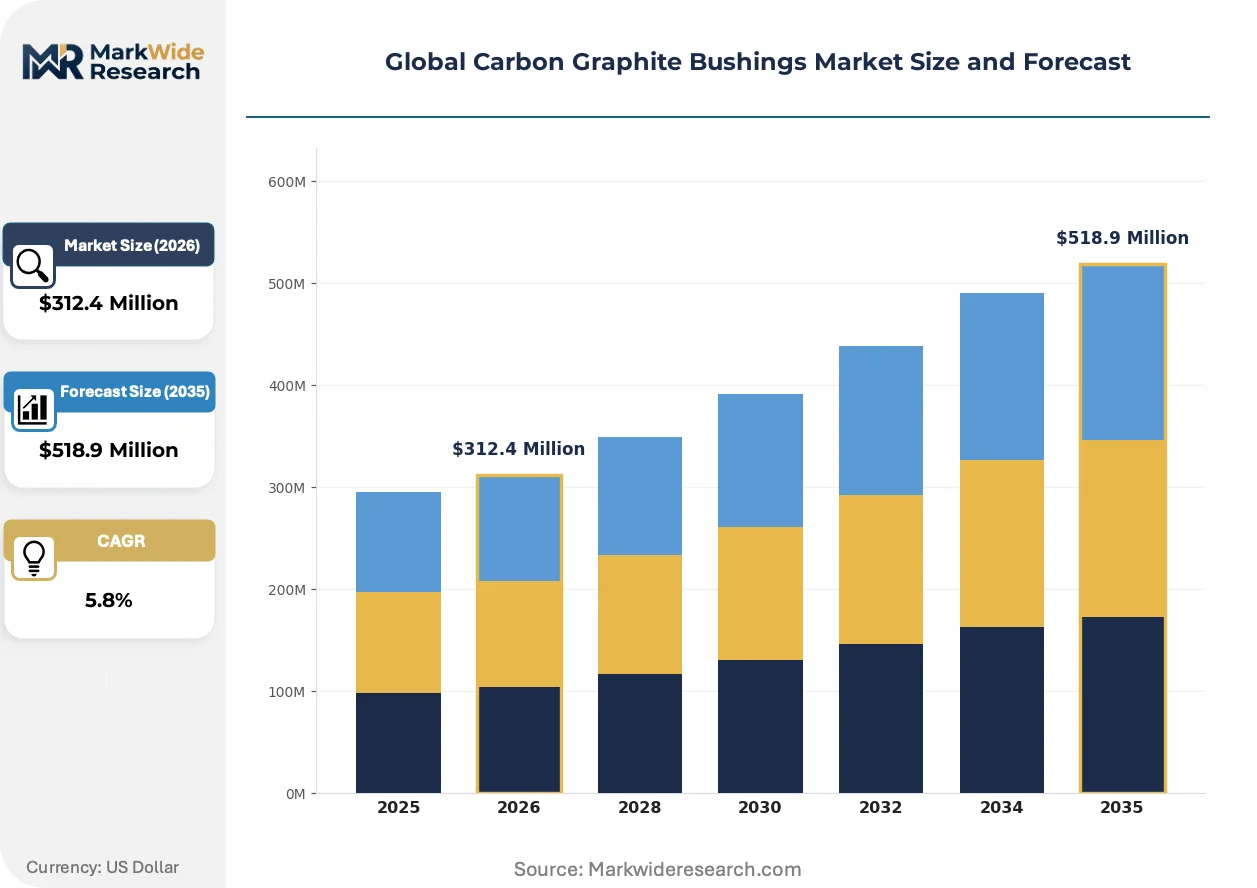
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bushings, Custom Bushings, Self-Lubricating Bushings, High-Temperature Bushings End User: Aerospace, Automotive, Marine, Heavy Machinery Application: Bearing, Valve, Pump, Electrical Equipment Installation Type: Integral, Press-Fit, Slip-Fit, Welded |
| Companies Covered | Graphite Metallizing, High Temp Bearings, St Marys Carbon, Federal Mogul, USG GLEDCO, Helwig Carbon Products, Trench, SGL Carbon, ROC Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbon Graphite Bushings Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are actively restructuring how carbon graphite bushings are formulated, tested, and specified across industrial end uses.
Antimony-impregnated graphite formulations are fragmenting traditional PTFE-dominated market positions in chemical processing equipment. Pump OEMs in Germany and the United States are accelerating qualification of these alternatives ahead of anticipated fluoropolymer restrictions. The shift is compressing margins for incumbent resin suppliers while creating entry points for specialized impregnation houses with metallurgical expertise.
REACH substance restrictions and EPA TSCA reporting requirements are forcing systematic reformulation of legacy binder chemistries across the supplier base. European valve manufacturers now demand full material disclosure documentation that traces resin components through the supply chain. High-purity grades for semiconductor and pharmaceutical applications face the steepest compliance burdens as ECHA evaluates additional substances for Annex XIV listing.
Direct technical collaboration between bushing suppliers and aerospace landing gear engineers is displacing traditional distributor-mediated specification processes. Tier-one manufacturers in France and Japan are embedding material scientists within procurement teams to accelerate qualification cycles for self-lubricating grades. This pattern concentrates volume with vertically integrated producers capable of delivering lot-traceable isostatically pressed components on compressed timelines.
Global Carbon Graphite Bushings Market Segmentation
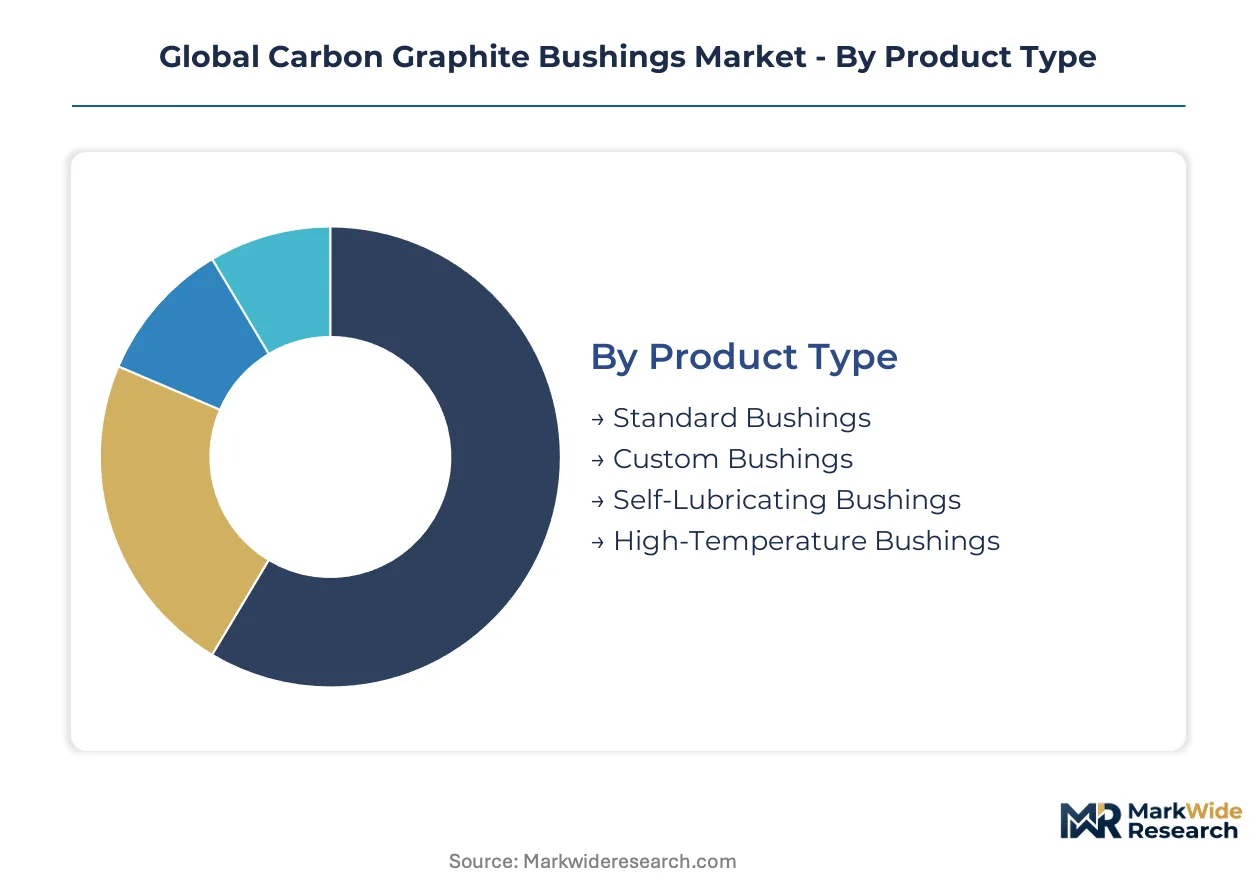
Carbon graphite bushing specifications fragment across performance tiers, installation geometries, and regulatory compliance levels. Procurement teams in aerospace and chemical processing select grades based on traceability requirements, temperature thresholds, and lubrication elimination needs.
Product Type:
Premium margin pools concentrate in custom-engineered grades requiring lot-traceable certification and isostatic pressing capability.
- Self-Lubricating Bushings:Engineered with resin or metal impregnants achieving porosity below 15 percent and compressive strength exceeding 20,000 psi. Demand concentrates in Germany and the United States where chemical processing OEMs specify dry-running bearings for pumps and valves exposed to corrosive media under EPA emissions rules.
- Custom Bushings:Precision-ground components manufactured to aerospace tier-one specifications with full material disclosure documentation. France and Japan anchor procurement volume as landing gear engineers embed material scientists within sourcing teams to accelerate qualification cycles.
- Standard Bushings:Catalog-grade components for general industrial maintenance serving mid-tier pump and valve rebuilders.
- High-Temperature Bushings:Isostatically pressed grades for service above 400°C in steam turbines and exhaust systems.
Self-lubricating grades hold installed capacity. Custom bushings are rotating up the share rankings.
End User:
Application complexity and certification burden separate aerospace procurement from industrial maintenance purchasing.
- Heavy Machinery:OEM specifications for hydroelectric turbines and mining equipment drive dry-running bearing adoption. China and Germany concentrate demand as domestic manufacturers expand precision machining clusters for corrosion-resistant installations.
- Aerospace:Landing gear assemblies require self-lubricating grades with full supply chain traceability under FAA airworthiness standards. Tier-one integrators in France and Japan compress qualification timelines through direct technical collaboration with material scientists.
- Marine:Underwater valves and propulsion systems specify antimony-impregnated alternatives ahead of anticipated fluoropolymer restrictions.
- Automotive:Limited penetration concentrated in high-temperature exhaust and turbocharger applications.
Heavy machinery anchors volume scale. Aerospace is climbing the fastest as certification requirements tighten.
Application:
Functional load conditions and media exposure determine impregnant chemistry selection and geometric tolerancing.
- Pump:Dry-running bearings eliminate seal leakage risks in chemical processing plants under EPA emissions rules. German and United States OEMs accelerate qualification of antimony-impregnated grades as PTFE alternatives.
- Valve:Stem and seat bushings in corrosive service require REACH-compliant resin binders with full material disclosure documentation for European market access.
- Bearing:General rotating equipment maintenance represents replacement demand volume across industrial end uses.
- Electrical Equipment:Limited specialty applications in high-voltage switchgear and furnace components.
Pump applications hold established specification share. Valve is gaining share fastest as REACH compliance reshapes material selection.
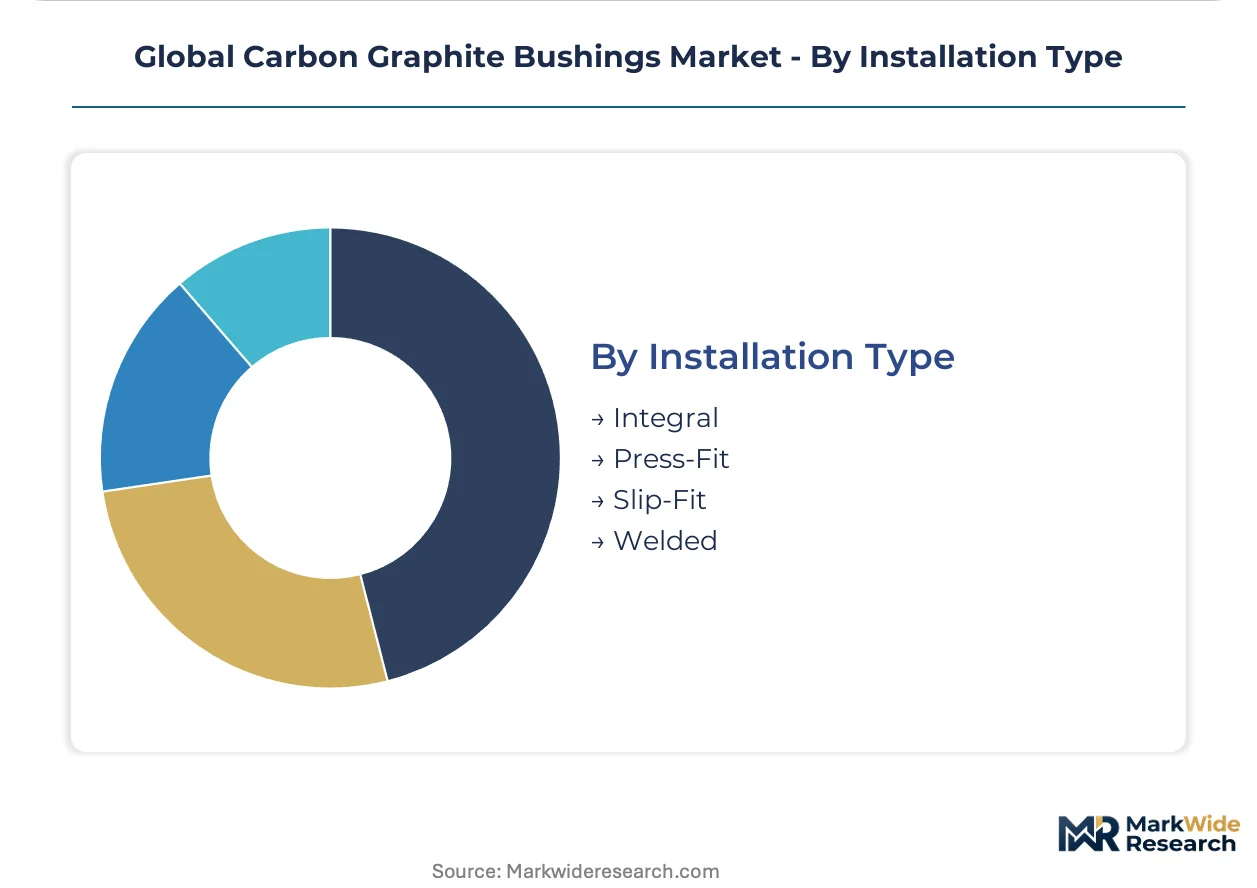
Installation Type:
Mounting geometry dictates machining tolerances and field service protocols across maintenance-intensive industries.
- Press-Fit:Interference-fit designs dominate pump and valve OEM specifications requiring precise bore tolerances and surface finish control. United States and German machining clusters concentrate production capacity for chemical processing integrators.
- Integral:Cast-in or molded configurations for original equipment manufacturing in heavy machinery and marine propulsion systems.
- Slip-Fit:Clearance-fit designs for maintenance replacement in accessible rotating equipment.
- Welded:Permanent attachment for high-vibration environments in mining and construction equipment.
Press-fit commands the specification base. Integral is expanding most quickly as OEMs design for lifecycle cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions enforcement in the United States shapes material compliance requirements that cascade through supplier networks in Germany and China. Precision machining clusters in these three countries concentrate capacity for aerospace and chemical processing specifications.
United States
Chemical processing OEMs in Texas and Louisiana specify dry-running pump bearings under EPA emissions rules to eliminate lubricant leakage risks. FDA food-contact regulations constrain resin binder chemistries for pharmaceutical and food-grade applications. Houston-area machining clusters serve heavy machinery rebuilders with press-fit bushing geometries.
Germany
Valve manufacturers in the Ruhr region accelerate qualification of antimony-impregnated grades as REACH Annex XIV restrictions threaten PTFE alternatives. CE marking under the EU Machinery Directive extends testing protocols for pump integrators. Stuttgart precision engineering networks supply lot-traceable components to aerospace tier-one suppliers.
China
Hydroelectric turbine OEMs in Sichuan and Yunnan provinces drive demand for corrosion-resistant bearings in water infrastructure expansion. GB standards and dual carbon goals from MEE shape domestic material specifications. Yangtze River Delta machining clusters export standard-grade bushings to Southeast Asian maintenance markets.
Japan
Aerospace landing gear engineers in Nagoya embed material scientists within procurement teams to compress qualification timelines. METI industrial standards govern high-temperature grades for steam turbine applications. Osaka-area carbon processors supply isostatically pressed components to domestic heavy machinery manufacturers.
India
Domestic chemical processing and power generation capacity expansion creates demand for corrosion-resistant pump bearings. BIS certification requirements and PLI scheme incentives support local manufacturing scale-up. Maharashtra and Gujarat industrial corridors attract precision grinding capability from multinational suppliers.
Global Carbon Graphite Bushings Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on machining precision and material certification. The structure concentrates premium volume among producers with captive carbon processing and isostatic pressing assets. Two archetypes dominate: vertically integrated carbon processors controlling feedstock consistency, and precision machining houses serving aerospace lot-traceability requirements. Competitive moves center on backward integration into carbon baking operations and direct technical collaboration with OEM engineering teams to displace distributor-mediated specifications.
Among North American integrated producers, St Marys Carbon and Graphite Metallizing occupy positions anchored by in-house carbon processing capabilities. SGL Carbon represents the European isostatic pressing specialist archetype with technology leadership in high-temperature grades. These three companies exemplify how control over raw material consistency and density distribution separates premium suppliers from commodity competitors in aerospace and heavy machinery procurement.
| Leading Market Players |
|---|
| Graphite Metallizing |
| High Temp Bearings |
| St Marys Carbon |
| Federal Mogul |
| USG GLEDCO |
| Helwig Carbon Products |
| Trench |
| SGL Carbon |
| ROC Carbon |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for isostatically pressed aerospace grades concentrate pricing power with German and United States machining clusters, while commodity standard bushings from Yangtze River Delta producers face persistent margin compression. This lead-time dispersion creates a dual-track market where captive carbon processing capability commands premium positioning against import-dependent competitors.
Pricing Analysis
Geographic price spreads of 40-60 percent separate German isostatically pressed components from Chinese standard grades, with three-tier pricing structure across premium, standard, and economy levels anchored by certification burden and lot-traceability requirements. Price differentiation rests on isostatic pressing capability and REACH-compliant material disclosure documentation. Cost compression in standard grades is intensifying because petroleum coke feedstock volatility transfers margin risk to non-integrated producers. Chemical processing OEMs in Texas and Louisiana exhibit highest price sensitivity, while aerospace tier-one integrators in France and Japan prioritize qualification speed over unit cost.
Supply Chain Analysis
Inventory cycles of 45-75 days for synthetic graphite feedstock expose producers to petroleum coke price swings that cascade through formulation costs. Supply concentrates in Germany, China, and the United States, with isostatic pressing assets anchoring premium capacity and Yangtze River Delta clusters serving volume production. Raw material dependencies include petroleum coke for synthetic graphite, phenolic resin binders, and antimony metal impregnants. Single-source vulnerability concentrates in isostatic pressing operator talent pools. Distribution runs through direct technical collaboration with OEM engineering teams for aerospace grades, and distributor networks for industrial maintenance replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
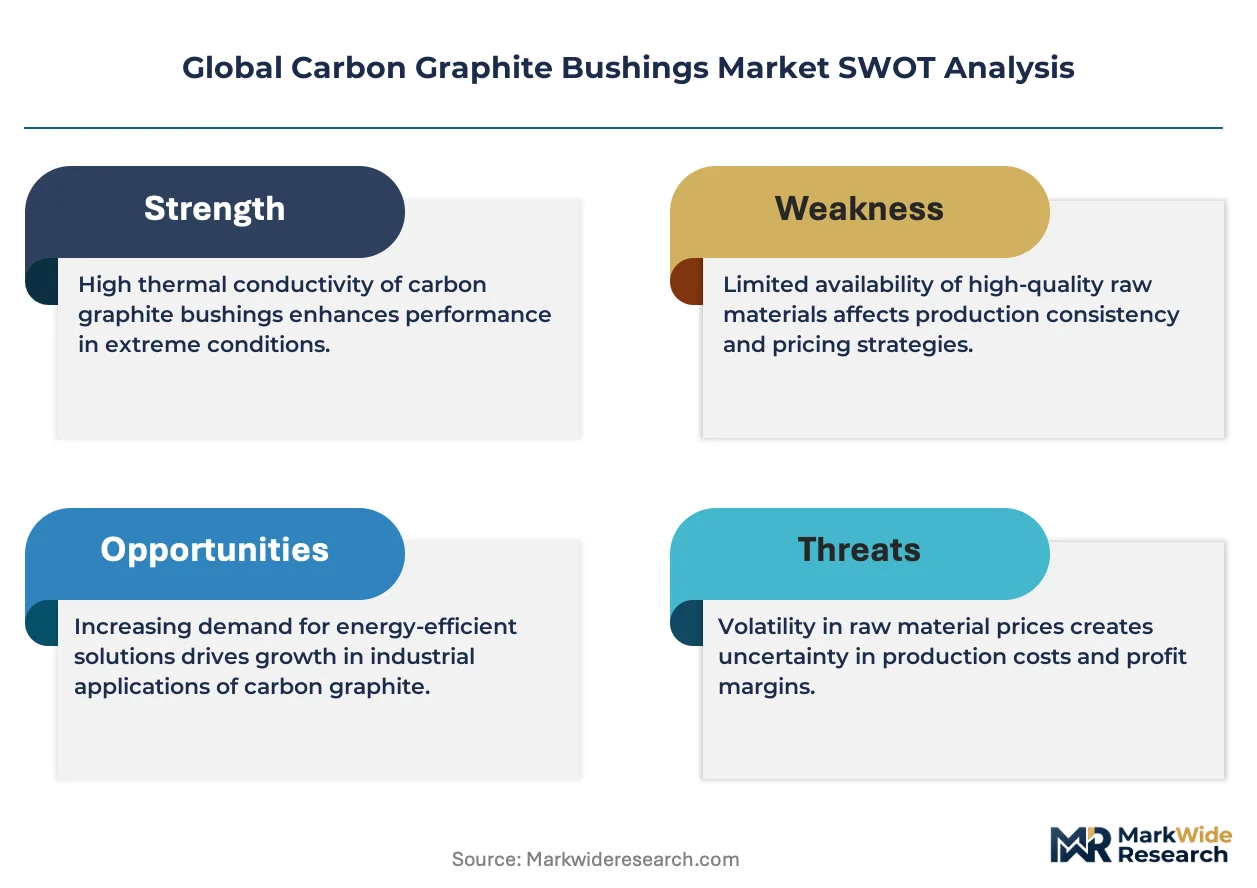
Isostatic pressing expertise and REACH-compliant material certification constitute scarce, defensible capabilities that separate premium suppliers from commodity competitors in this market. The bifurcation rewards backward-integrated carbon processors while squeezing machining-only houses dependent on spot-market feedstock.
For Market Incumbents: Consolidate around captive carbon baking and impregnation operations to insulate margins from petroleum coke volatility, while embedding material scientists within customer procurement teams to accelerate qualification cycles and lock out distributor-mediated competitors. Ceramic bearing substitution above 500°C threatens graphite oxidation-limited applications, demanding R&D investment in high-purity antioxidant formulations. For New Entrants and Emerging Players: Aftermarket technical service for chemical processing pump rebuilders represents an underserved layer where incumbents rely on distributor technical support. Target India's Maharashtra and Gujarat industrial corridors with phenolic-impregnated grades positioned ahead of anticipated PTFE restrictions, leveraging BIS certification requirements as a barrier to established import competition. Go-to-market execution should prioritize direct mill relationships over distributor networks to capture specification influence. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because isostatic pressing asset scarcity and REACH compliance burdens favor scaled, vertically integrated producers over fragmented machining houses. Acquisition focus should center on German and United States precision grinding shops with dormant carbon processing relationships that could be activated. The signal to watch is ECHA Annex XIV expansion timelines, which would accelerate substitution demand for antimony-impregnated grades and reshape competitive positioning among resin suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Baking | Captive petroleum coke processing insulates margin from oil refining economics volatility. |
| Isostatic Pressing Capacity Expansion | Uniform density distribution capability captures aerospace tier-one qualification volume. |
| REACH-Compliant Formulation Development | Phenolic and antimony-impregnated grades position ahead of PTFE restriction timelines. |
| Direct OEM Technical Collaboration | Embedded material scientists displace distributor-mediated specification processes. |
| India Manufacturing Scale-Up | Maharashtra and Gujarat corridors access PLI scheme incentives and domestic OEM expansion. |
Methodological Framework
Desk research of customs trade data, SEC filings from carbon and graphite producers, and ECHA regulatory submissions preceded structured interviews with aerospace procurement managers, chemical processing plant engineers, and isostatic pressing operations directors. Primary fieldwork with pump and valve OEM specification teams in Germany and the United States was cross-validated against secondary analysis of REACH Annex XIV substance evaluation timelines and EPA emissions enforcement patterns. Bottom-up segment sizing and top-down macro constraint triangulation produced volume and value estimates.
Variance decomposition across product type, end-use industry, installation geometry, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro industrial production indices. Industry-specific forecast inputs included hydroelectric turbine installation pipelines in Sichuan and Yunnan provinces, and aerospace landing gear platform development schedules from Nagoya engineering centers.
Underlying assumptions cover sustained EPA emissions enforcement, REACH substance restriction expansion, and petroleum coke supply continuity, with deviation risk concentrated in ceramic bearing substitution rates above 500°C and unanticipated fluoropolymer regulatory acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Aluminum Composite Materials Market
Composite Materials
Thermoset Composites Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Fiber Reinforced Polymer (FRP) Panels and Sheets Market
Composite Materials
Composite Coatings Market
Composite Materials
Global Carbon Fiber Reinforced Plastic Market
Composite Materials
Carbon Composites Market
Composite Materials
Composites Testing Market
Composite Materials
Pcb Laminate Materials Market
Composite Materials
Malaysia High Pressure Laminate Market
Composite Materials
Polyurethane Composites Market
Composite Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market
Composite Materials
Fiber Reinforced Composite Tapes Market
Composite Materials
Tow Prepreg Market