
 Thermoplastic Honeycomb Market | 2026-2036
Thermoplastic Honeycomb Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Honeycomb Market Outlook
Asset-light leasing arrangements for continuous honeycomb production lines is reconfiguring capital barriers for mid-tier material converters. Hexcel Corporation leverages its aerospace qualification heritage to sustain premium positioning in cabin interior structures. EconCore N.V. anchors European supply through in-line thermoplastic composite sheet integration. Plascore Inc. dominates North American distribution with automated panel fabrication capabilities.
Thermoplastic honeycomb denotes a cellular core structure manufactured from melt-processable polymers, typically featuring 6-12 mm cell diameters and densities ranging from 40-200 kg/m³, engineered to deliver specific stiffness-to-weight ratios for load-bearing sandwich constructions. Polypropylene cores lead volume shipments due to cost-efficient extrusion welding and chemical resistance in marine environments, while Nomex segments command margin pools from flame-retardant aerospace specifications. Automotive applications in structural panels represent the fastest-growing end-use channel as OEMs pursue mass reduction targets without sacrificing crash performance.
EPA emissions standards and FAA fire-smoke-toxicity regulations jointly dictate material selection thresholds for transportation applications, with REACH restrictions on halogenated additives reshaping polyester core formulations in European supply chains. China's GB standards for rail vehicle interiors and SAMR product safety certifications create parallel compliance architectures for Asian market entry. Stakeholders must monitor evolving lifecycle assessment methodologies as procurement criteria shift from unit cost to embodied carbon accounting.
Market Dynamics
The EU Green Deal's embodied carbon thresholds are forcing aerospace and automotive OEMs to abandon thermoset honeycomb cores in favor of recyclable thermoplastic alternatives, rewiring supplier qualification pipelines across three continents.
Growth Catalysts
- FAA fire-smoke-toxicity mandates:Stringent cabin interior regulations are disqualifying traditional thermoset cores from commercial aircraft retrofit programs, opening procurement channels for polypropylene and PPS-based alternatives that meet 12-second vertical burn requirements.
- Automotive lightweighting corridors:Germany's OEM consortiums are specifying thermoplastic honeycomb sandwich panels for battery enclosure floors, exploiting the material's energy absorption characteristics to offset lithium-ion pack mass.
- Continuous extrusion welding:Advances in in-line thermoforming are collapsing unit production costs for polypropylene cores, enabling price parity with aluminum honeycomb in marine decking and recreational vehicle applications.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene resin prices fluctuate with propylene monomer supply disruptions from Gulf Coast crackers, compressing converter margins during crude oil price spikes.
- Qualification timeline compression:Aerospace OEMs demand 18-month certification cycles for new core suppliers, creating insurmountable barriers for mid-tier converters lacking Airbus or Boeing approved supplier status.
- Thermoset incumbent lock-in:Nomex and aluminum honeycomb specifications dominate military aviation maintenance contracts, resisting substitution despite thermoplastic performance equivalence in non-structural applications.
Strategic Opportunities
- Rail vehicle interior mandates:China's GB/T 32347 standards for smoke toxicity are creating first-mover advantages for domestic thermoplastic core producers serving CRRC's high-speed train refurbishment programs.
- Wind blade root inserts:Convergence of thermoplastic honeycomb with recycled carbon fiber nonwovens is enabling root reinforcement structures that eliminate balsa wood core supply chain fragility.
- Leased production line models:Asset-light equipment financing from European machinery vendors is lowering capital barriers for Southeast Asian converters targeting Japanese automotive Tier-1 supply chains.
Industry Challenges
- Multi-physics simulation expertise:Sandwich panel designers lack training in coupled thermal-mechanical finite element modeling for thermoplastic cores, forcing reliance on expensive physical prototyping.
- REACH additive reformulation:ECHA restrictions on halogenated flame retardants are requiring polyester core manufacturers to requalify entire product lines with phosphorus-based alternatives, extending R&D cycles by 24-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Honeycomb Market |
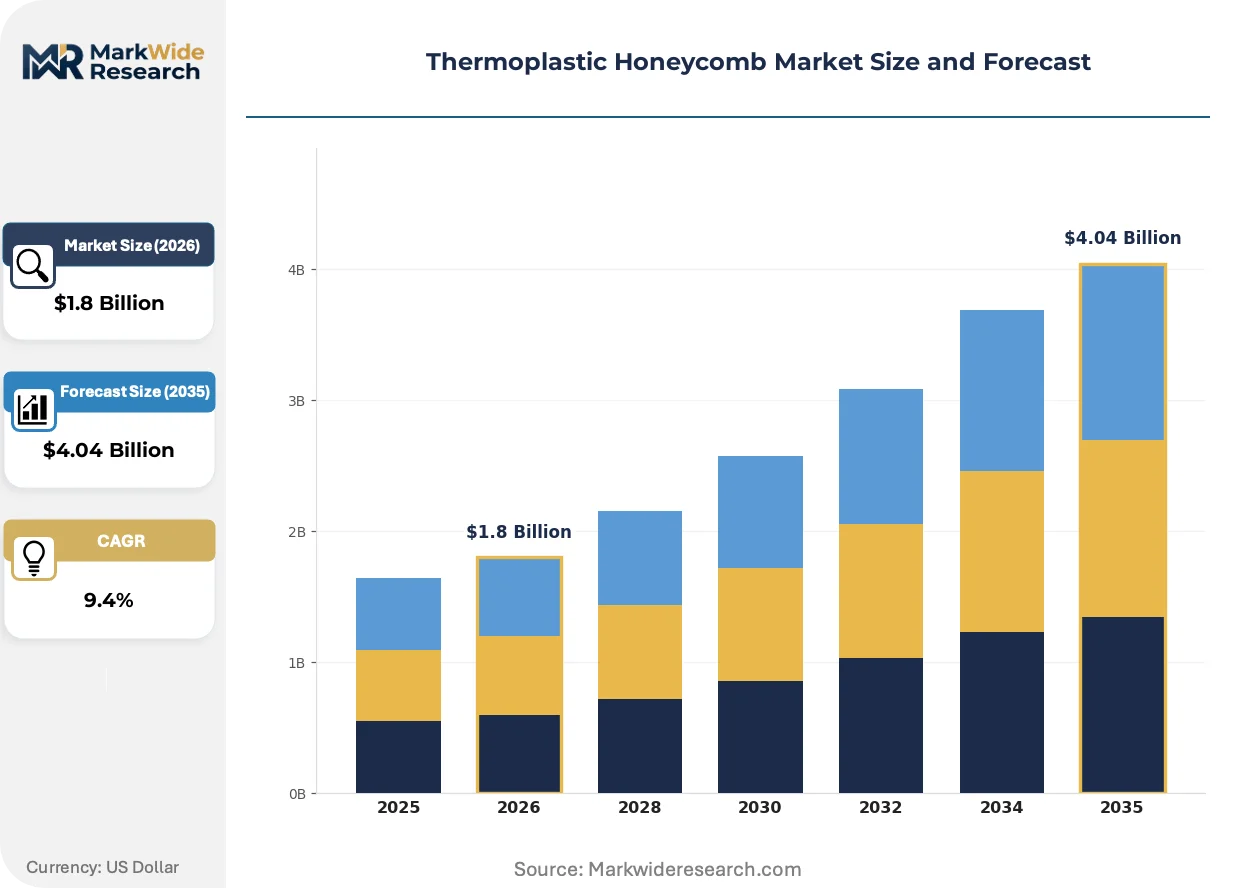
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nomex, Polypropylene, Polyester, PVC End User: Aerospace, Automotive, Construction, Marine Application: Structures, Panels, Insulation, Packaging Technology: Injection Molding, Thermoforming, Extrusion, Compression Molding |
| Companies Covered | Hexcel Corporation, ThermHex Waben GmbH, EconCore N.V., Euro-Composites S.A., Plascore Inc., The Gill Corporation, Toray Advanced Composites, 3M Company, Schweiter Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Honeycomb Market Strategic Shifts
Continuous fiber-reinforced thermoplastic (CFRTP) integration with honeycomb cores is collapsing the performance gap between commodity polymers and aerospace-grade composites, redrawing material selection boundaries across transportation sectors.
Hybrid core manufacturing is collapsing the traditional separation between extruded polypropylene and composite-reinforced structures. Tier-1 suppliers in Stuttgart and Nagoya are adopting dual-material production lines that switch between commodity and high-performance grades within single shifts. This capability is collapsing the premium that aerospace-specification cores command over industrial variants, forcing incumbent suppliers to defend margin pools through captive resin compounding.
REACH restrictions on persistent organic pollutants are compelling reformulation of polyester-based honeycomb cores across European supply chains. ECHA's 2023 amendments to Annex XVII restricted halogenated flame retardants in rail and marine interior applications, triggering substitution with intumescent phosphorus-nitrogen systems. German automotive suppliers are responding by consolidating procurement with converters holding EMAS environmental certification, creating tiered supplier qualification barriers.
Buyer consolidation among European aerospace OEMs is compressing supplier negotiation leverage and extending payment terms. Airbus and Safran's centralized core procurement functions now demand lifecycle carbon footprint data through CSRD-aligned reporting templates, displacing spot-market purchasing for long-term framework agreements. This concentration is most visible in Toulouse and Hamburg, where panel fabricators report 18-month qualification backlogs for new thermoplastic core sources.
Thermoplastic Honeycomb Market Segmentation
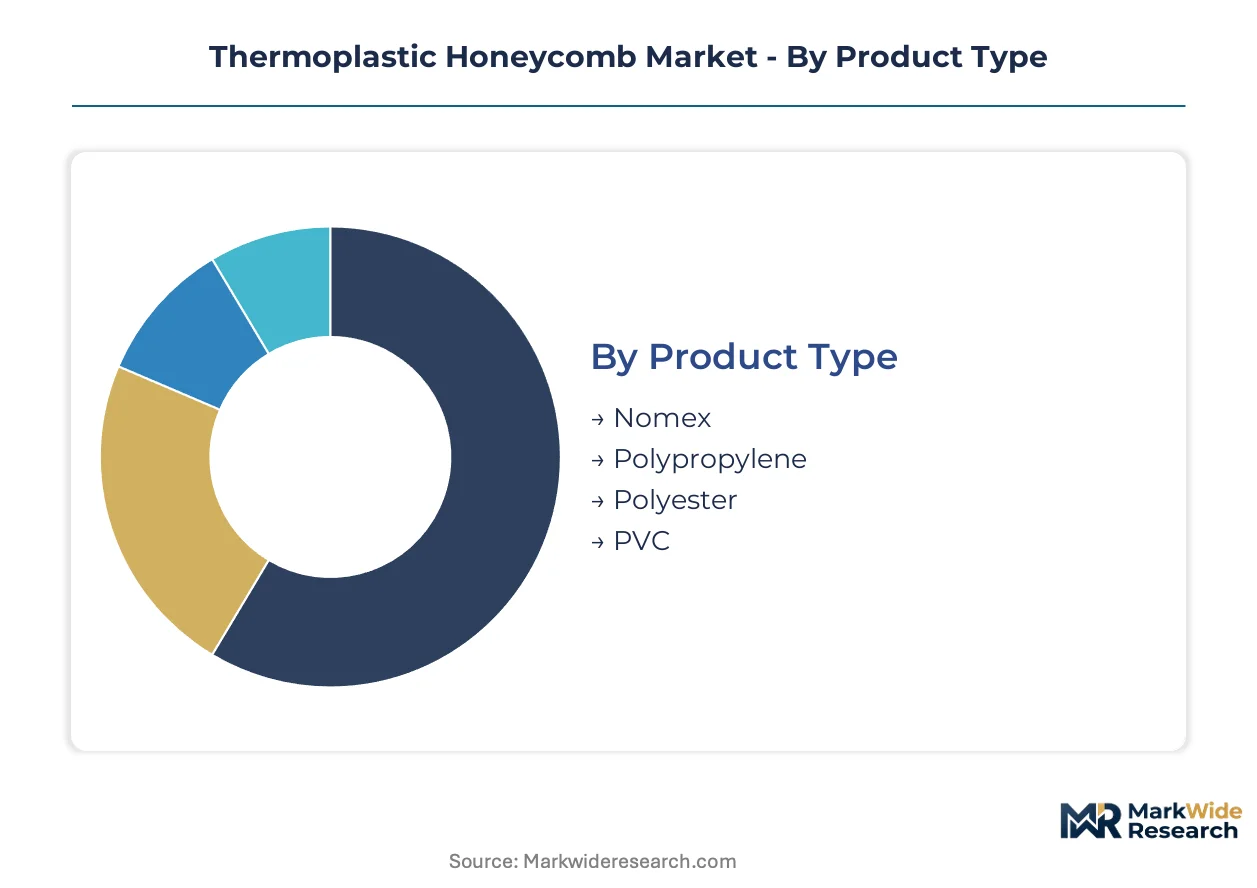
Thermoplastic honeycomb segments reflect divergent material performance thresholds and processing economics across transportation and industrial end-uses. Each category isolates distinct procurement criteria—flame retardancy, crash energy management, thermal insulation, or manufacturing scalability—that reshape supplier positioning and margin capture.
Product Type:
The use-case spectrum spans fire-critical aerospace cabins to cost-sensitive marine decking, with polymer chemistry dictating regulatory compliance and recyclability profiles.
- Polypropylene:Manufactured through continuous extrusion welding of melt-processable polymer ribbons, delivering 40-200 kg/m³ density ranges with chemical resistance against saltwater degradation. Procurement concentrates in China's recreational boat manufacturing clusters and Germany's automotive Tier-1 panel suppliers, where REACH-compliant formulations without halogenated additives are displacing legacy PVC alternatives in rail interior specifications.
- Nomex:Aramid-based meta-aramid honeycomb cores engineered for 12-second vertical burn compliance under FAA fire-smoke-toxicity mandates, with cell geometries optimized for sandwich panel shear strength in aircraft flooring and bulkhead applications. Airbus and Boeing approved supplier status restricts viable sources to converters with aerospace qualification heritage, sustaining premium positioning despite thermoplastic substitution pressure in non-structural cabin elements.
- Polyester:Thermoplastic polyester cores offer intermediate flame retardancy between commodity polypropylene and aerospace-grade aramids, finding adoption in European rail vehicle interiors where ECHA Annex XVII restrictions on persistent organic pollutants are forcing phosphorus-nitrogen intumescent system reformulation.
- PVC:Chlorinated polymer honeycomb dominates legacy marine and construction applications through lowest unit material cost, though regulatory pressure from EU Green Deal embodied carbon accounting is accelerating phase-out in favor of recyclable thermoplastic alternatives.
Established volume favors Polypropylene; emerging adoption favors Nomex in next-generation electric aircraft cabin architectures.
End User:
Customer procurement power varies dramatically—airframe OEMs demand 18-month qualification cycles while automotive converters prioritize line-speed compatibility.
- Automotive:Battery enclosure floors and structural sandwich panels exploit thermoplastic honeycomb energy absorption to offset lithium-ion pack mass, with Germany's OEM consortiums specifying polypropylene cores for crash-managed electric vehicle platforms. Stuttgart-based Tier-1 suppliers are consolidating procurement with converters holding EMAS environmental certification.
- Aerospace:Cabin interior panels, galleys, and lavatory structures drive Nomex and PPS-based core demand under FAA fire-smoke-toxicity regulations, with centralized procurement functions at Airbus and Safran now requiring lifecycle carbon footprint data through CSRD-aligned reporting templates.
- Marine:Decking and hull reinforcement applications favor polypropylene chemical resistance against saltwater exposure, with production gravity centering on China's recreational boat manufacturing exports and Southeast Asian converter expansion through leased European extrusion line equipment.
- Construction:Temporary formwork and modular wall panels represent emerging volume for recycled-content thermoplastic cores, though building code fire rating requirements limit penetration against mineral wool and aluminum alternatives.
Procurement consolidation favors Automotive; qualification timeline compression favors Aerospace incumbents with existing airframe approvals.
Application:
Functional requirements split between load-bearing structural performance and non-structural thermal or protective attributes.
- Structures:Load-bearing sandwich constructions in aircraft flooring, automotive battery enclosures, and wind blade root inserts demand calibrated stiffness-to-weight ratios with multi-physics simulation validation, creating capability scarcity among panel fabricators lacking coupled thermal-mechanical finite element modeling expertise.
- Panels:Non-structural interior partitions and decorative facings represent highest shipment volumes through automated fabrication lines, with Plascore's North American distribution network and EconCore's European in-line thermoplastic composite sheet integration capturing margin through captive resin compounding.
- Insulation:Thermal and acoustic barrier applications in rail vehicles and commercial buildings favor lower-density polypropylene configurations, with China's GB/T 32347 smoke toxicity standards creating compliance-driven specification divergence from European EN 45545 requirements.
- Packaging:Returnable transit packaging and protective dunnage exploit thermoplastic honeycomb reusability and recyclability, though unit economics struggle against expanded polystyrene in cost-sensitive logistics corridors.
Margin capture favors Structures; volume scaling favors Panels through automated production line amortization.
Technology:
Process selection trades capital intensity against geometric complexity and fiber reinforcement integration capability.
- Extrusion:Continuous ribbon welding of polypropylene dominates commodity core production through lowest unit capital cost and highest line speeds, with advances in in-line thermoforming collapsing price parity thresholds against aluminum honeycomb in marine and recreational vehicle applications.
- Thermoforming:Vacuum and pressure forming of pre-extruded sheets enables complex cell geometries and dual-material hybrid cores, with Stuttgart and Nagoya Tier-1 suppliers adopting production lines that switch between commodity and high-performance grades within single shifts.
- Injection Molding:High-pressure molding of reinforced thermoplastics produces integrated core-skin sandwich structures for automotive structural components, though tool costs restrict viability to annual volumes exceeding 50,000 units.
- Compression Molding:Matched-die forming of continuous fiber-reinforced thermoplastic prepregs enables aerospace-grade core performance, with CFRTP integration collapsing the traditional performance gap between commodity polymers and composite-reinforced structures.
Cost efficiency favors Extrusion; performance advancement favors Thermoforming with hybrid material flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a structural export surplus in thermoplastic honeycomb cores, while China and the United States absorb the bulk of import demand for aerospace and automotive conversion. Trade flows concentrate through Rotterdam and Hamburg for European distribution, with Shenzhen and Tianjin anchoring Asian supply consolidation.
United States
FAA fire-smoke-toxicity mandates are retrofitting commercial aircraft interiors across Delta and United fleets, disqualifying thermoset alternatives from cabin panel specifications. EPA emissions standards for transportation equipment are accelerating lightweight material substitution in heavy-duty truck sleeper cabs. Wichita's aviation manufacturing corridor hosts Tier-1 panel fabricators supplying Boeing's 737 MAX interior refresh programs.
Germany
BMW and Mercedes-Benz consortiums are specifying thermoplastic honeycomb battery enclosure floors for electric vehicle platforms launching in 2026-2027. ECHA REACH restrictions on halogenated flame retardants are forcing phosphorus-nitrogen reformulation across polyester core supply chains. Stuttgart's automotive lightweighting corridor concentrates converter capacity with EMAS-certified facilities serving Porsche and Audi structural programs.
China
CRRC's high-speed train refurbishment programs are absorbing domestic polypropylene core production under GB/T 32347 smoke toxicity standards. SAMR product safety certifications are creating parallel compliance architectures for rail vehicle interior exports to Belt and Road markets. Shanghai's Yangtze River Delta manufacturing base hosts leased European extrusion line installations targeting Japanese automotive Tier-1 supply chains.
France
Airbus centralized procurement at Toulouse is demanding CSRD-aligned lifecycle carbon footprint data from core suppliers, displacing spot-market purchasing with long-year framework agreements. EU Green Deal embodied carbon thresholds are accelerating thermoset substitution in A320 family cabin retrofits. The Occitanie aerospace cluster reports 18-month qualification backlogs for new thermoplastic core sources seeking approved supplier status.
Japan
Toyota and Honda are integrating thermoplastic honeycomb structural panels into next-generation hybrid vehicle platforms under METI carbon neutrality roadmaps. JIS standards for automotive crash performance are validating energy absorption characteristics against aluminum honeycomb benchmarks. Nagoya's Chubu manufacturing region hosts dual-material production lines switching between commodity polypropylene and high-performance PPS grades within single shifts.
Thermoplastic Honeycomb Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in resin compounding and extrusion equipment supply. The vendor base stratifies across three tiers: aerospace-qualified incumbents with airframe OEM approvals, automotive-scaled converters with captive panel fabrication, and regional extrusion specialists serving marine and construction verticals. Two dominant competitive moves are reshaping positioning: backward integration into resin compounding to defend margin pools, and asset-light leasing arrangements for continuous production lines to lower capital barriers for mid-tier entrants.
Within the aerospace-qualified tier, Hexcel Corporation and Toray Advanced Composites exemplify heritage-dependent positioning where airframe OEM approvals sustain premium capture. EconCore N.V. anchors European supply through in-line thermoplastic composite sheet integration, representing the hybrid manufacturing archetype that collapses traditional separations between extruded and reinforced structures. Among North American fabricators, Plascore Inc. occupies a scale-driven position with automated panel fabrication capabilities.
| Leading Market Players |
|---|
| Hexcel Corporation |
| ThermHex Waben GmbH |
| EconCore N.V. |
| Euro-Composites S.A. |
| Plascore Inc. |
| The Gill Corporation |
| Toray Advanced Composites |
| 3M Company |
| Schweiter Technologies AG |
| Others |
Value Chain & Pricing Dynamics
Stuttgart's automotive lightweighting corridor concentrates polypropylene core converter capacity, translating EMAS-certified environmental compliance into pricing premiums that Tier-1 suppliers pass through to BMW and Mercedes-Benz procurement functions. This geographic concentration of qualified supply creates asymmetric leverage where panel fabricators extract margin through captive resin compounding while downstream OEMs absorb qualification-driven cost premiums.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in thermoplastic honeycomb procurement. Aerospace-grade Nomex cores command substantial premiums over commodity polypropylene due to FAA fire-smoke-toxicity certification requirements and 18-month supplier qualification timelines. Price differentiation rests on flame-retardant certification tier and volume scale, with automotive battery enclosure contracts driving cost compression through multi-year offtake agreements. Marine decking converters exhibit highest price sensitivity, while aerospace OEMs prioritize performance compliance over unit economics.
Supply Chain Analysis
Propylene monomer feedstock draws from Gulf Coast petrochemical crackers, tethering converter margins to crude oil volatility and regional refinery operating rates. Manufacturing concentrates in Germany, China, and the United States, with extrusion welding equipment sourced from European machinery vendors. Single-source vulnerability persists in aerospace-qualified aramid fiber supply. Distribution runs through Rotterdam and Hamburg for European panel fabricators, with Shenzhen and Tianjin anchoring Asian supply consolidation for CRRC rail programs and Japanese automotive Tier-1 networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lifecycle carbon accounting services and CSRD-aligned reporting templates are expanding faster than hardware shipments, creating recurring-revenue layers that converters can attach to core supply contracts. This service-attach opportunity restructures customer relationships from transactional spot purchasing toward multi-year framework agreements with embedded compliance support.
For Market Incumbents: Entrench aerospace qualification heritage by accelerating phosphorus-nitrogen flame-retardant reformulation ahead of ECHA Annex XVII enforcement timelines. Consolidate procurement relationships through EMAS environmental certification and captive resin compounding capabilities that mid-tier converters cannot replicate. Defend margin pools against thermoplastic substitution pressure in non-structural cabin elements by embedding carbon footprint data services into long-term supply agreements. For New Entrants and Emerging Players: Build out leased production line capacity in China's Yangtze River Delta to capture Japanese automotive Tier-1 supply chain migration. Target wind blade root insert applications where balsa wood supply fragility creates specification openness for recycled carbon fiber nonwoven hybrids. Penetrate through asset-light equipment financing models that collapse capital barriers for Southeast Asian converters serving marine decking and recreational vehicle markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with dual-material production line flexibility switching between commodity polypropylene and high-performance PPS grades. The 5-10 year viability window rewards upstream integration into resin compounding and in-line thermoplastic composite sheet manufacturing. Watch for inflection in CRRC high-speed train refurbishment procurement volumes under GB/T 32347 smoke toxicity standards as the signal for Chinese domestic producer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene formulation control defends margins against Gulf Coast feedstock volatility. |
| Dual-Material Production Line Deployment | Stuttgart and Nagoya Tier-1 suppliers collapse premium capture through single-shift grade switching. |
| CSRD-Aligned Carbon Reporting Service Launch | Airbus centralized procurement at Toulouse mandates lifecycle data through long-term framework agreements. |
| Phosphorus-Nitrogen Flame Retardant Reformulation | ECHA Annex XVII compliance secures European rail vehicle interior specifications against REACH restrictions. |
| Leased Extrusion Line Expansion | European machinery vendor financing lowers capital barriers for Southeast Asian marine decking entrants. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Conversations captured input from aerospace procurement directors at Airbus and Boeing approved suppliers, automotive Tier-1 panel fabrication engineers in Stuttgart and Nagoya, marine decking converters in China's recreational boat manufacturing clusters, and EMAS-certified facility managers. Secondary sources included ECHA REACH regulatory filings, FAA fire-smoke-toxicity certification databases, CRRC procurement announcements under GB/T 32347 standards, and customs trade data tracking propylene monomer feedstock flows. Bottom-up volume modeling triangulated against top-down market sizing across polymer chemistry segments.
Forecast inputs considered continuous extrusion welding cost curves, qualification timeline compression effects, and REACH-driven formulation transition rates. Segmentation dimensions spanned polymer chemistry, end-use industry, cell geometry specifications, and regional regulatory compliance clusters. CAGRs were derived from production capacity expansion announcements, OEM platform launch schedules, and substitution elasticity estimates for thermoset honeycomb displacement. Industry-specific inputs included battery enclosure floor adoption rates in German electric vehicle platforms and wind blade root insert specification shifts away from balsa wood cores.
Stress conditions across propylene monomer price volatility, aerospace qualification timeline extensions, and ECHA enforcement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about CFRTP integration rates and EU Green Deal embodied carbon threshold implementation timelines. Cross-checking against IHS Markit automotive production forecasts and CRRC high-speed train delivery schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
GCC Decorative Laminates Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
Glass Fiber Reinforced Plastic (GFRP) Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
FRP Grating Market
Composite Materials
Polyurethane Composites Market
Composite Materials
Low Temperature Sealing Glass Composite Powder Market
Composite Materials
Transportation Composites Market
Composite Materials
Lithium Battery Copper Aluminum Composite Pole Market
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
Asia-Pacific Natural Fiber Composites Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Expandable Graphite Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
High Performance Composites Market
Composite Materials
Hybrid Composites Market