
 Global Thermoplastic Composites Market | 2026-2036
Global Thermoplastic Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermoplastic Composites Market Intelligence
The shift towards modularized component systems in automotive and aerospace manufacturing is consolidating material specifications around high-performance thermoplastic composites. Solvay specializes in advanced materials for demanding aerospace applications, including structural parts and interiors. Toray Industries, Inc. leverages its backward integration into carbon fiber to offer complete material systems. BASF SE competes with a broad portfolio targeting automotive and industrial end-users, focusing on large-scale production.
Thermoplastic composites consist of a polymer matrix, such as PEEK or polyamide, reinforced with fibers like carbon or glass. These materials are valued for their high strength-to-weight ratio, recyclability, and rapid processing cycles compared to thermosets. Carbon Fiber Reinforced composites lead in performance and value, driven by aerospace component requirements. In terms of technology, injection molding is prevalent for consumer goods, while thermoforming and automated tape laying are expanding in automotive and aerospace.
Adoption in aviation is governed by strict airworthiness directives from the US Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA). Chemical regulations, including the EU's REACH framework and EPA standards in the United States, dictate polymer and additive formulations. These rules shape material selection for end-users like OEMs and Tier-1 Suppliers. Success depends on navigating these intersecting performance and compliance demands.
Market Dynamics
The central tension shaping the thermoplastic composites market is the drive to industrialize materials originally developed for niche, high-performance applications. Aerospace demand for ultimate weight savings is balanced against automotive sector requirements for rapid cycle times and cost-effective, large-scale production.
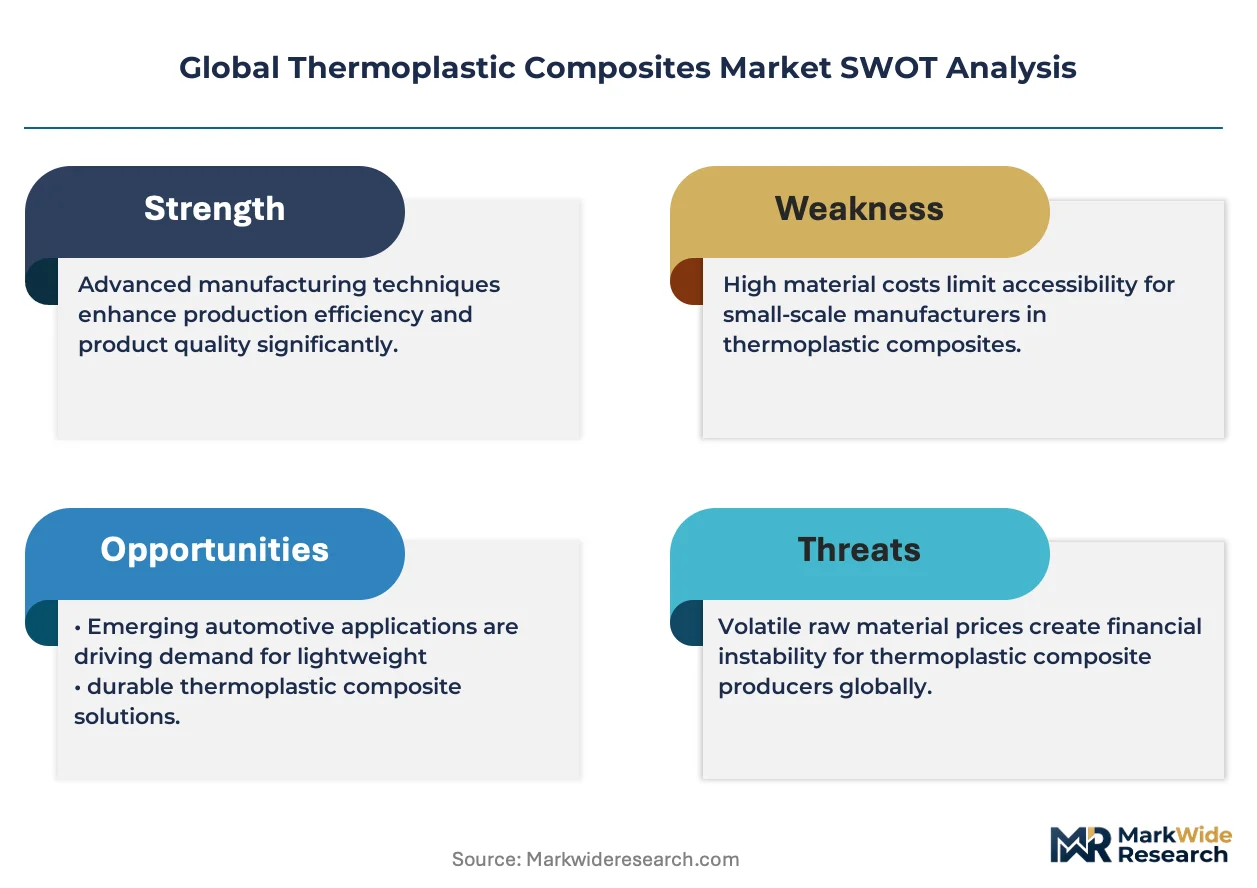
Growth Catalysts
- Emissions Reduction Mandates:Regulations such as the EU's Green Deal and US CAFE standards compel automotive and aerospace OEMs to adopt lightweight materials like thermoplastic composites to improve fuel efficiency and reduce carbon emissions, directly stimulating material substitution.
- Automated Manufacturing Processes:Innovations in automated tape laying (ATL) and thermoforming are reducing cycle times and improving part consistency. This enables the high-volume production necessary for adoption in mainstream automotive platforms beyond luxury or performance models.
- Geographic Industrial Clusters:The high concentration of automotive and aerospace end-users in regions like Germany and the southeastern United States creates dense ecosystems. This proximity accelerates collaborative development between material suppliers, part fabricators, and OEMs.
Market Restraints
- High Raw Material Costs:The price of reinforcing fibers, particularly aerospace-grade carbon fiber, remains a significant barrier. Similarly, high-performance polymer matrices like PEEK and PEKK are substantially more expensive than commodity plastics or traditional metals like aluminum.
- Complex Processing and Tooling:While faster than thermosets, processing thermoplastic composites requires high temperatures and pressures. The associated capital investment in specialized presses, molds, and automated equipment can be prohibitive for many potential applications and smaller manufacturers.
- Competition from Incumbent Materials:Thermoplastic composites face strong competition from well-understood and lower-cost materials, including advanced aluminum alloys and established thermoset composites. Overcoming engineering inertia and extensive legacy material databases is a significant hurdle.
Strategic Opportunities
- Medical Device and Implant Sector:The biocompatibility and radiolucency of materials like PEEK composites create opportunities in medical applications. These include orthopedic implants, surgical instruments, and fixtures where metal-free imaging and high strength are required.
- Additive Manufacturing Integration:Combining continuous fiber reinforcement with 3D printing technologies offers a path to producing highly complex, topologically optimized parts on-demand. This opens new design possibilities for low-to-mid volume applications in aerospace, defense, and motorsport.
- Expansion in Emerging Economies:Government initiatives like India's PLI scheme to boost domestic manufacturing present an opportunity. As automotive and aerospace production grows in these regions, local demand for advanced materials will follow, creating new markets.
Industry Challenges
- Composite Design Skill Gaps:A shortage of engineers and technicians with expertise in anisotropic material behavior, composite-specific FEA simulation, and advanced manufacturing processes limits the speed and effectiveness of adoption by OEMs and their suppliers.
- Recycling Infrastructure Scalability:While thermoplastics are inherently more recyclable than thermosets, the practical infrastructure for collecting, sorting, and reprocessing fiber-reinforced composite scrap at an industrial scale remains underdeveloped, hindering circular economy goals.
- Standardization and Qualification Delays:The lack of universally accepted material and process standards across different industries slows down material qualification. This increases testing costs and time-to-market for new applications, particularly in regulated sectors like aviation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermoplastic Composites Market |
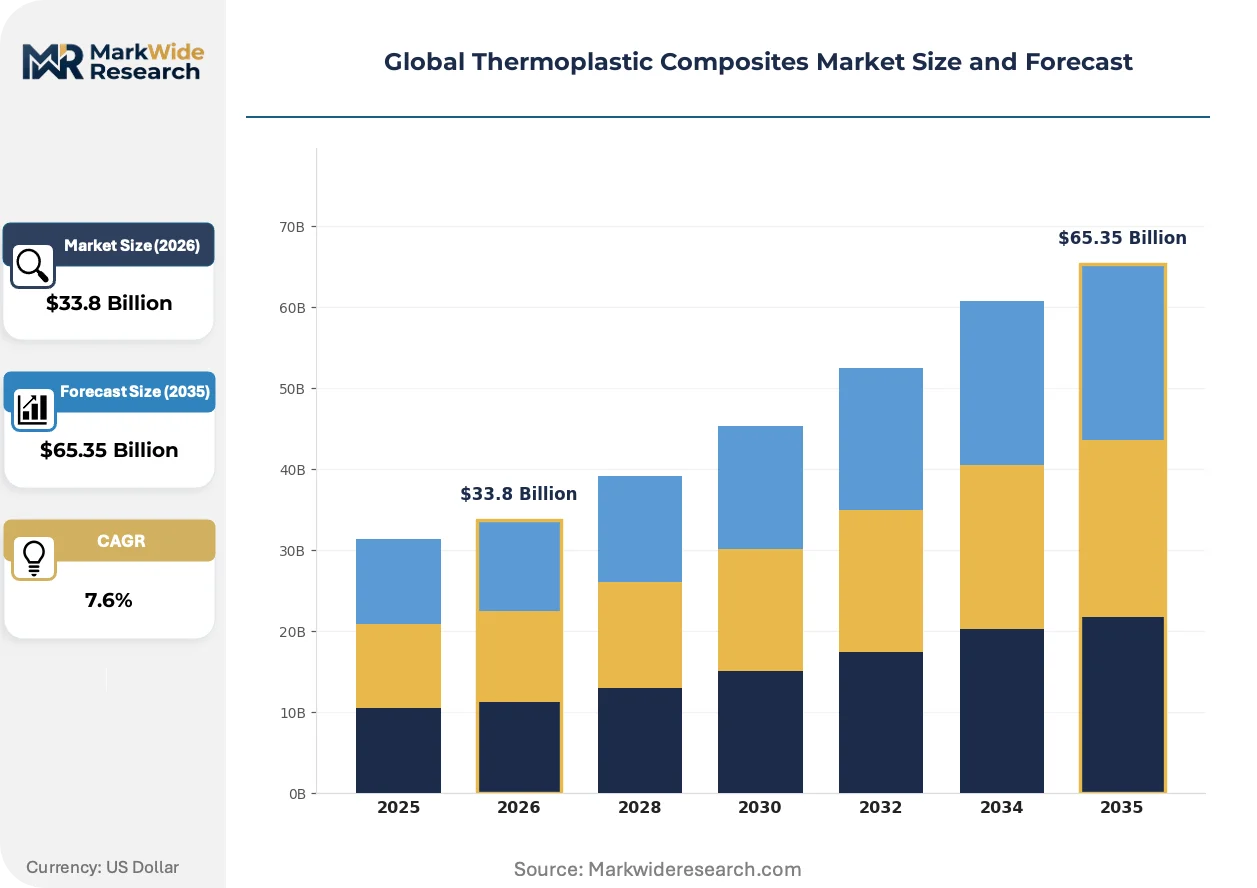
| Market Size in 2026 | $33.8 Billion |
| Market Size in 2035 | $65.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Fiber Reinforced, Carbon Fiber Reinforced, Aramid Fiber Reinforced, Natural Fiber Reinforced Technology: Injection Molding, Compression Molding, Thermoforming, Pultrusion, Extrusion Application: Aerospace Components, Electrical & Electronics, Consumer Goods, Sports Equipment, Marine Parts End User Industry: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Industrial Machinery Manufacturers |
| Companies Covered | Teijin Limited, Celanese Corporation, Toray Industries, Inc., BASF SE, Hexcel Corporation, Solvay, Covestro AG, LANXESS AG, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermoplastic Composites Market Strategic Shifts & Innovations
Industrialization is the dominant theme, as manufacturing technologies mature to move thermoplastic composites from bespoke aerospace components toward scalable, cost-effective solutions for automotive and industrial markets. This shift is supported by digital design tools and evolving regulatory frameworks that prioritize performance and sustainability.
Automated Fiber Placement (AFP) technology, which robotically lays down composite tapes to build a component layer by layer, is a core process innovation. Originally perfected for large aircraft fuselages and wings, AFP is now being adapted by automotive suppliers for producing structural chassis and battery enclosure components. This technology is converging with digital twin simulation software to allow for virtual prototyping, which drastically shortens development timelines and material waste.
European Union regulations, particularly the REACH framework, exert significant influence over material formulation. REACH mandates strict registration and safety validation for all chemical substances, including the monomers, polymers, and additives used in thermoplastic composites. This forces material science companies to invest heavily in compliance and seek safer alternatives, directly impacting the chemical composition of products sold within the EU market and influencing global formulation strategies.
Specification patterns are evolving from material-centric to performance-based procurement. Major end-users in aerospace and automotive are increasingly defining performance envelopes for a component—such as stiffness, impact resistance, and fire safety—and outsourcing the integrated design and fabrication to specialized suppliers. This model favors vertically capable suppliers over simple material distributors and is most visible in the German automotive supply chain.
Global Thermoplastic Composites Market Segmentation
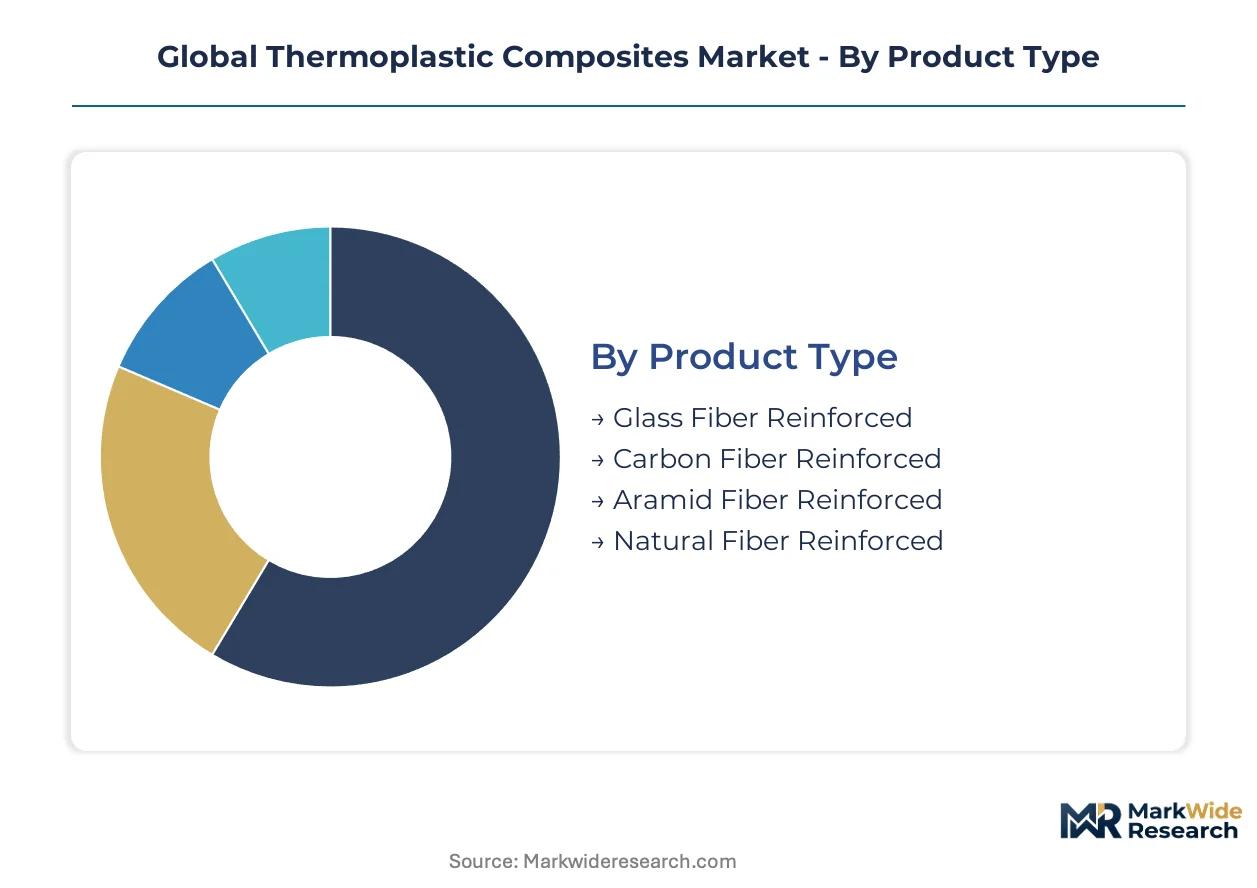
The thermoplastic composites market exhibits diverse segmentation, reflecting varied material compositions, processing methods, and end-use requirements. Understanding these segments is crucial for identifying areas of high-value growth and optimizing material development. Each category presents unique performance benchmarks and commercial viability trade-offs for manufacturers.
Product Type:
The product type segmentation differentiates between high-performance, premium materials and more cost-effective, volume-driven solutions.
- Carbon Fiber Reinforced:These composites utilize carbon fibers embedded in a thermoplastic matrix, offering exceptional strength-to-weight ratio and stiffness. Demand concentrates in aerospace components and high-performance automotive applications, driven by stringent weight reduction mandates from the US Federal Aviation Administration (FAA) and European Union Aviation Safety Agency (EASA).
- Glass Fiber Reinforced:Comprising glass fibers within a thermoplastic resin, these materials provide good mechanical properties at a lower cost compared to carbon fibers. The automotive sector utilizes these widely for structural parts and semi-structural components, balancing performance with cost-efficiency for large-scale production platforms in Germany.
- Aramid Fiber Reinforced:Aramid fibers enhance impact resistance and vibration damping in thermoplastic matrices. These find niche applications requiring ballistic protection or specific vibration control.
- Natural Fiber Reinforced:Utilizing plant-derived fibers like flax or hemp, these composites offer sustainable and lightweight alternatives. The automotive interior components sector shows interest in these materials for eco-friendly solutions.
Today's leader: Carbon Fiber Reinforced. Tomorrow's challenger: Natural Fiber Reinforced.
Technology:
Processing technology dictates the types of parts that can be manufactured, influencing production speed and part complexity.
- Injection Molding:This high-volume process involves injecting molten thermoplastic composite into a mold, suitable for complex geometries and rapid cycle times. Consumer goods and electrical & electronics sectors widely employ injection molding for intricate parts and enclosures.
- Thermoforming:Sheet-based thermoplastic composites are heated and formed over a mold, enabling efficient production of large, complex structural and semi-structural parts. Automotive and aerospace applications increasingly adopt thermoforming for interior panels and lightweight structures.
- Compression Molding:Pre-impregnated composite sheets are compressed in a heated mold, yielding high-strength parts with good surface finish. This method is common for larger, flatter components in industrial machinery.
- Pultrusion:Continuous fibers are pulled through a resin bath and then a heated die to create profiles with constant cross-section. Pultrusion produces strong, lightweight beams and rods for construction and infrastructure projects.
- Extrusion:Thermoplastic composites are melted and pushed through a die to create continuous profiles or sheets. The process suits high-volume production of pipes, films, and various profiles for industrial use.
The most mature technology is Injection Molding, while Thermoforming is gaining traction rapidly.
Application:
Applications range from highly regulated, performance-critical sectors to high-volume consumer markets, each with distinct material requirements.
- Aerospace Components:This sector demands ultimate strength-to-weight ratios, high temperature resistance, and stringent flame retardancy for structural elements, interiors, and engine components. Material selection adheres to strict airworthiness directives from the US Federal Aviation Administration (FAA) and European Union Aviation Safety Agency (EASA).
- Electrical & Electronics:Thermoplastic composites provide lightweight, insulating, and often flame-retardant solutions for housings, circuit board components, and connectors. Miniaturization and performance demands drive material innovation in this segment.
- Consumer Goods:Composites offer design flexibility, durability, and a premium feel for products like mobile device casings, sporting goods, and domestic appliances. Cost-effectiveness and aesthetic appeal are key considerations for these applications.
- Sports Equipment:High-performance sports gear, including bicycle frames, tennis rackets, and skis, benefits from the lightweight and stiffness properties of thermoplastic composites. These materials enhance athletic performance and product longevity.
- Marine Parts:Corrosion resistance, light weight, and durability are critical for components in boats and ships, such as hull structures, interior panels, and specialized equipment. Composites reduce vessel weight and improve fuel efficiency.
Aerospace Components currently command the highest value, with Electrical & Electronics showing significant expansion.
End User Industry:
The end-user landscape reflects the complex supply chains involved in bringing composite parts to market, from design to final assembly.
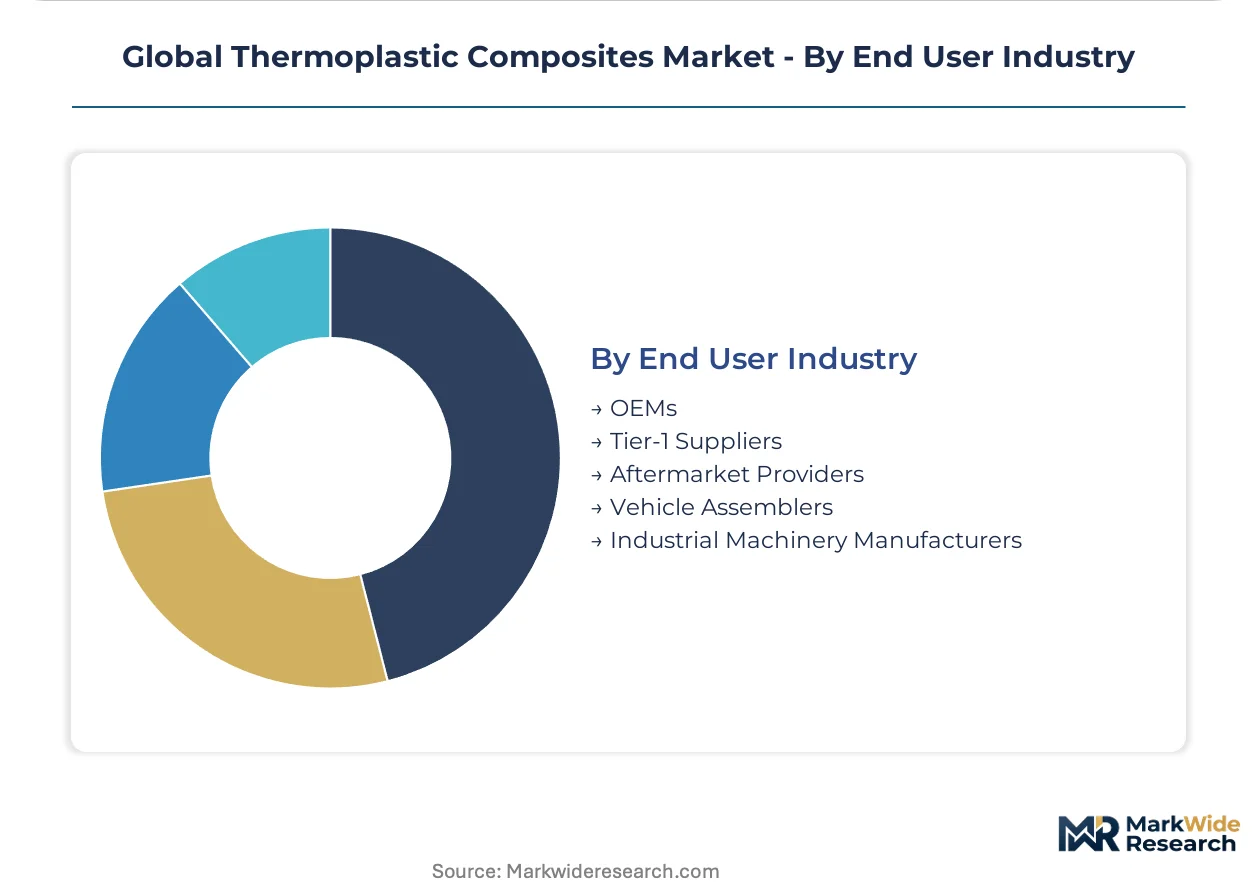
- OEMs (Original Equipment Manufacturers):OEMs design and assemble final products, dictating material specifications and performance requirements for their platforms. Automotive and aerospace OEMs drive significant demand for advanced thermoplastic composites in their vehicle and aircraft programs.
- Tier-1 Suppliers:These companies supply major sub-assemblies or systems directly to OEMs, often undertaking advanced material processing and part fabrication. German automotive Tier-1 suppliers are critical integrators of thermoplastic composite solutions for vehicle platforms.
- Aftermarket Providers:Aftermarket companies supply parts for repair, replacement, or upgrades after the initial sale of a product. This segment requires durable and readily available composite components.
- Vehicle Assemblers:These entities focus on the final assembly of vehicles, integrating components sourced from OEMs and Tier-1 suppliers. They influence material choices through assembly process requirements and cost considerations.
- Industrial Machinery Manufacturers:This segment uses thermoplastic composites for lightweighting, corrosion resistance, and improved performance in various industrial equipment. Applications range from robotics to manufacturing line components.
OEMs hold the most influential position in the supply chain, while Tier-1 Suppliers are crucial for material integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrialization of thermoplastic composites first gained significant traction in Germany's advanced manufacturing sectors. Early adoption in automotive and aerospace applications established a foundation for material innovation and process development. This regional expertise continues to influence global market dynamics and technological advancements.
Germany
Demand for thermoplastic composites in Germany stems from its robust automotive and aerospace manufacturing clusters, which prioritize lightweighting for performance and efficiency. The EU's Green Deal mandates compel German OEMs to integrate advanced materials for emissions reduction. The Stuttgart region, with its dense concentration of automotive suppliers and research institutions, accelerates collaborative material development and application.
United States
The United States drives demand for high-performance thermoplastic composites, particularly within its expansive aerospace and defense industries. US Federal Aviation Administration (FAA) airworthiness directives necessitate rigorous material qualification for new aircraft programs. The southeastern United States, including states like South Carolina and Georgia, forms a growing hub for aerospace component fabrication and advanced materials research.
China
China's rapidly expanding automotive production and ambitious aerospace programs are fueling significant demand for thermoplastic composites. The country's dual carbon goals encourage the adoption of lightweight, fuel-efficient materials across industrial sectors. Manufacturing clusters in the Yangtze River Delta actively develop and scale composite production capabilities for both domestic and international markets.
Japan
Japan's advanced materials sector, exemplified by companies like Toray Industries, Inc., sustains strong demand for thermoplastic composites in automotive and industrial applications. Strict national emissions targets push Japanese automakers towards innovative lightweighting solutions. The Nagoya region, a major automotive and aerospace manufacturing center, fosters continuous material science research and process optimization.
India
India represents a significant emerging market for thermoplastic composites, driven by its growing automotive sector and increasing investments in defense and aerospace manufacturing. Government initiatives like the PLI scheme incentivize domestic production of advanced materials and components. Manufacturing zones around Pune and Chennai are seeing increased interest in composite fabrication for vehicle platforms and industrial machinery.
Global Thermoplastic Composites Market Key Industry Players
Premium-margin players sit above commodity-margin players across the thermoplastic composite value chain, differentiating through specialized material formulations and processing expertise. The market exhibits a tiered structure, with a few large chemical companies providing base polymers and a broader set of specialists offering integrated solutions. Key strategic archetypes include integrated material suppliers, specialized compounders, and advanced part fabricators. Capacity expansion and strategic partnerships represent dominant competitive moves.
Integrated material suppliers, such as Solvay, exemplify the high-performance end of the market, offering advanced materials for demanding aerospace applications. Toray Industries, Inc. represents a vertically integrated model, leveraging its backward integration into carbon fiber to provide complete material systems. BASF SE, a German chemical giant, occupies a position as a broad portfolio provider, targeting large-scale automotive and industrial end-users with its diverse range of thermoplastic solutions.
| Leading Market Players |
|---|
| Teijin Limited |
| Celanese Corporation |
| Toray Industries, Inc. |
| BASF SE |
| Hexcel Corporation |
| Solvay |
| Covestro AG |
| LANXESS AG |
| SABIC |
| Others |
Cost & Logistics Intelligence
Backward integration into critical raw materials anchors both the supply position and the pricing power for several major thermoplastic composite manufacturers. This strategic choice allows companies to control input costs and maintain competitive pricing in a market driven by performance specifications.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing within the high-performance thermoplastic composites market. Price differentiation often stems from the stringent certification level required by regulators like the FAA and EASA, alongside the volume scale of procurement. Pricing pressure stems from the inherent raw material cost volatility, particularly for aerospace-grade carbon fiber. Aerospace components exhibit the least price sensitivity, while consumer goods applications remain the most sensitive.
Supply Chain Analysis
Single-source vulnerability sits with specialized producers of high-performance polymer matrices and aerospace-grade carbon fiber. Supply concentration for advanced thermoplastic composite manufacturing clusters in Germany, Japan, and the southeastern United States. Raw material dependencies include carbon fiber and specialized polymers like PEEK and PEKK, leading to commodity price volatility as a structural risk. Distribution runs through direct channels to OEMs and Tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global thermoplastic composites market presents a late-cycle quality story, driven by a pronounced demand shift toward premium specifications for lightweighting in aerospace and automotive applications.
For Market Incumbents: Anticipate continued consolidation within the material supply base, driven by the need for economies of scale and integrated solutions. Incumbents should pursue strategic capacity expansion in high-demand regions like the southeastern United States to meet growing aerospace requirements. Investing in R&D for advanced automation, such as Automated Fiber Placement (AFP), can counter margin pressure from traditional metal suppliers. Certification investment for new material systems strengthens market position against emerging threats.
For New Entrants and Emerging Players: Enter via niche applications requiring specific performance attributes where incumbent solutions are less optimized. Target the rapidly expanding medical device sector, leveraging biocompatibility for orthopedic implants. Additive manufacturing integration for topologically optimized parts offers another white space for low-to-mid volume aerospace and defense applications. A performance-based procurement angle, showcasing superior material properties for specific use cases, can accelerate market penetration.
For Investors and Strategic Acquirers: Roll-up economics work for specialized part fabricators because capability scarcity sits with advanced processing expertise and complex tooling investments. The market offers long-term viability, underpinned by sustained demand for lightweighting and sustainability across regulated industries. Target Tier-1 suppliers possessing proprietary thermoforming or Automated Fiber Placement (AFP) capabilities. Increased M&A activity among composite automation technology providers signals market readiness for broader industrialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Key Geographies | Increases supply availability for automotive and aerospace OEMs in high-demand regions. |
| Investment in Automated Processing | Reduces cycle times and labor costs, enabling high-volume production for mainstream applications. |
| Advanced Material Certification | Qualifies new composite systems for stringent airworthiness directives from FAA and EASA. |
| Partnership with Additive Manufacturers | Expands design freedom and enables rapid prototyping for complex, low-volume components. |
| Development of Recyclable Solutions | Addresses circular economy goals and complies with evolving environmental regulations like REACH. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, providing a comprehensive view of the global thermoplastic composites market. Primary research involved discussions with R&D directors, OEM procurement leads, Tier-1 fabrication specialists, and regulatory compliance officers. Secondary validation drew from FAA and EASA certification documents, automotive industry reports, and chemical association publications. This approach ensured robust bottom-up and top-down triangulation for market estimates.
Segment-weighting across product type, technology, application, and end-user industry formed the core of the analytical framework over the projection horizon. The model incorporated regional manufacturing output as a key dimension across the analysis window. Compound annual growth rates were derived from historical trends and future projections. Key forecast inputs included new aircraft program schedules and regulatory compliance deadlines.
Inputs from chemical association reports and regulatory filings were available through the study window; gaps in emerging economy production data introduce uncertainty. Forecasts reflect assumptions regarding raw material price volatility and new regulatory mandates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Composite Cans Market
Composite Materials
Core Material for Composites Market
Composite Materials
Global Sports Composites Market
Composite Materials
FRP Tanks Market
Composite Materials
GCC Decorative Laminates Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
Molded Underfill Material Market
Composite Materials
Europe Aluminium Composite Panel Market
Composite Materials
PCR Laminates Market
Composite Materials
Global Carbon Fiber Resin Market
Composite Materials
Transportation Composites Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
High Performance Composites Market
Composite Materials
Global Honeycomb Core Materials Market
Composite Materials
Global Carbon Graphite Bushings Market