
 Aluminum Composite Materials Market | 2026-2036
Aluminum Composite Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Composite Materials Market Outlook
Commercial facade contractors are redrawing procurement priorities as transit authorities and airport developers scale aluminum composite panel orders. 3A Composites GmbH leverages its European manufacturing base to supply fire-certified cladding systems for German and Swiss infrastructure bids. Mitsubishi Chemical Corporation anchors its position through captive polymer core production, controlling raw material quality for high-performance architectural grades. Alstrong Enterprises India Pvt. Ltd. competes on cost-optimized panel output for South Asian commercial construction, while Jyi Shyang Industrial Co., Ltd. dominates Taiwan's domestic signage and transport interior markets.
Aluminum composite materials consist of two thin aluminum skins bonded to a non-aluminum core, typically polyethylene or mineral-filled polymer, yielding a rigid yet lightweight sandwich structure with flexural strength exceeding solid aluminum at 40% lower mass. The primary industrial purpose centers on architectural envelopes, transport interiors, and corporate signage where weather resistance, formability, and surface finish consistency matter. Fire-retardant panels lead product type demand as building codes tighten, while lightweight grades capture the fastest growth in electric bus and rail car manufacturing where every kilogram of mass reduction extends battery range. Facades command the largest application volume, though transport cladding offers superior margin pools due to crashworthiness certification requirements and smaller batch production.
Europe's ECHA enforces REACH restrictions on hexavalent chromium in surface pretreatments, compelling mills to shift toward trivalent passivation or anodized finishes. The EU Construction Products Regulation mandates CE marking for facade panels, creating a two-tier market between certified suppliers and non-compliant imports. China's GB standards and MIIT technical directives govern aluminum composite panel flame spread ratings for public buildings, with provincial fire bureaus conducting random site inspections. Stakeholders must monitor regulatory divergence between European chemical restrictions and Chinese performance-based standards, as dual compliance will determine which producers retain access to both markets.
Market Dynamics
Fire-retardant core technology is forcing a wholesale recalibration of raw material sourcing and manufacturing certification across aluminum composite panel supply chains. European facade retrofits and Chinese transit infrastructure mandates are compressing lead times for compliant material qualification.
Growth Catalysts
- REACH chemical restrictions:European ECHA mandates on hexavalent chromium passivation are accelerating trivalent and anodized finish adoption, creating premium tier demand for certified mills.
- Transit electrification:Battery-electric bus and rail car manufacturers specify lightweight aluminum composite interiors to extend range, pulling volume from traditional steel and solid aluminum.
- China MIIT directives:Provincial flame spread standards for public buildings are institutionalizing aluminum cladding in airport terminals and municipal transit hubs.
Market Restraints
- Aluminum ingot volatility:Primary aluminum price swings on LME directly compress panel fabricator margins, especially for spot-contract residential projects.
- Core polymer concentration:Polyethylene and mineral-filled polymer supply clusters in East Asian petrochemical corridors, exposing European and North American panel makers to freight and duty exposure.
- Fire-test certification backlog:Extended queue times at notified bodies for CE marking under Construction Products Regulation delay project handoffs.
Strategic Opportunities
- Indian commercial construction:Cost-optimized panel demand in South Asian high-rise and retail development remains underpenetrated by fire-certified European suppliers.
- Photovoltaic integration:Building-integrated solar facades converge aluminum composite substrates with thin-film mounting systems, opening architectural energy-generation contracts.
- German KfW green building subsidies:Federal efficiency incentives for envelope retrofits expand addressable project volume for low-emissivity and recycled-content panel grades.
Industry Challenges
- Coil coating technician scarcity:Skilled operators for continuous anodizing and fluoropolymer coating lines are retiring faster than vocational programs replace them.
- Dual compliance engineering:Simultaneous satisfaction of European REACH chemical restrictions and Chinese GB performance standards requires parallel R&D tracks and duplicate testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Composite Materials Market |
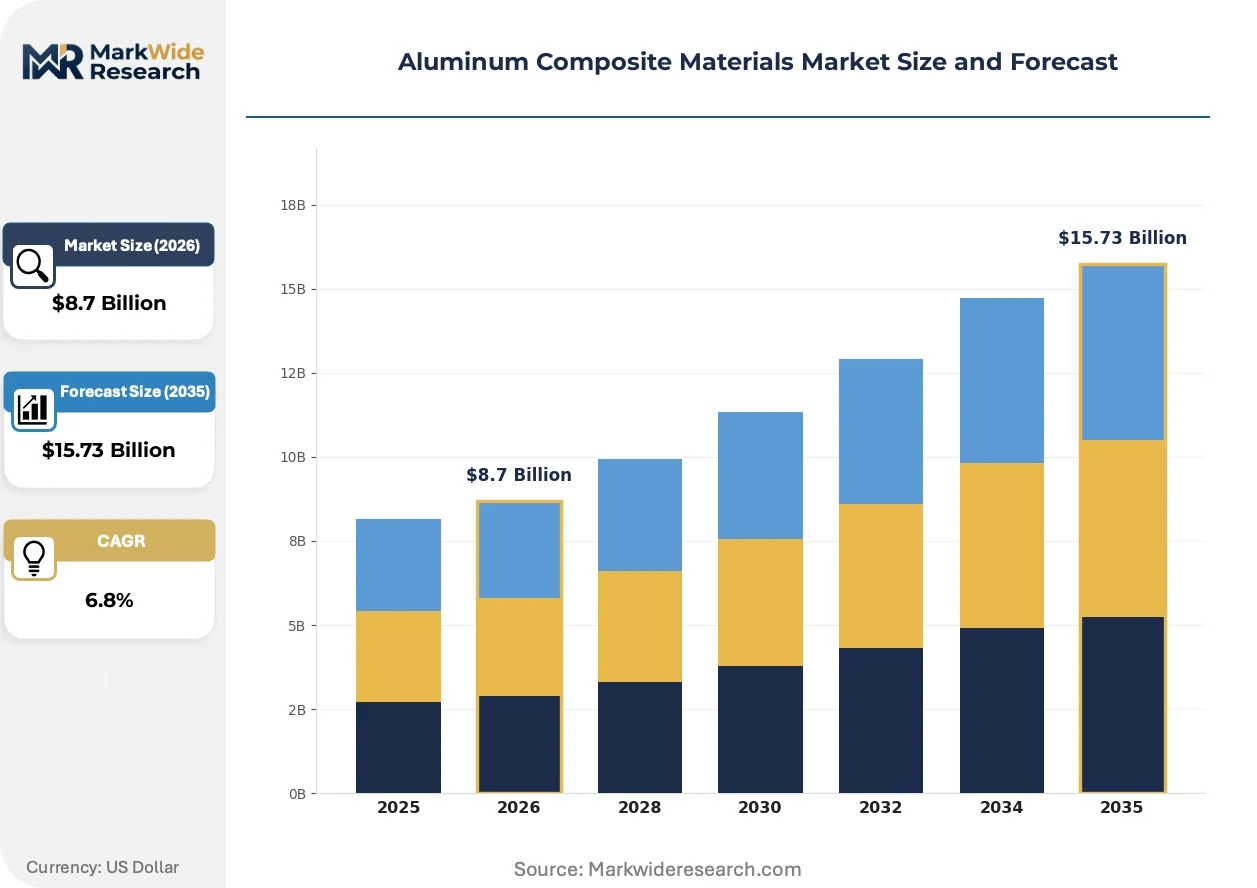
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Retardant, Lightweight, High-Strength, Anti-Corrosive End Use Industry: Building & Construction, Automotive, Aerospace, Signage Form: Sheets, Panels, Rolls, Custom Shapes Application: Facades, Interior Design, Transport, Cladding |
| Companies Covered | 3A Composites GmbH, Arconic Inc., Mitsubishi Chemical Corporation, Alstrong Enterprises India Pvt. Ltd., Jyi Shyang Industrial Co., Ltd., Alubond USA, Alucoil, Yaret Industrial Group, Fairview Architectural, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Composite Materials Market Strategic Shifts
Material science advances and regulatory stringency are converging to redefine competitive advantage around certified fire performance rather than surface aesthetics alone. Panel fabricators are reorganizing R&D spending toward core engineering and adhesive chemistry.
Mineral-filled polymer cores with engineered flame-retardant loading are supplanting standard polyethylene in high-rise facade specifications. German and Swiss commercial contractors now specify these cores as baseline for projects above 20 meters. The shift is compressing demand for uncertified commodity panels in premium architectural segments.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon blowing agents in insulation-adjacent building materials. Panel manufacturers are reformulating core expansion processes to comply while maintaining density tolerances. Transport interior applications face the tightest substitution timelines as rail car builders front-load compliance for cross-border rolling stock.
Specification authority is migrating from general contractors to facade engineering consultants who bundle fire certification, thermal modeling, and installation liability. This channel consolidation favors panel suppliers with in-house testing laboratories and established notified body relationships. The pattern is most pronounced in London, Frankfurt, and Singapore commercial tower developments.
Aluminum Composite Materials Market Segmentation
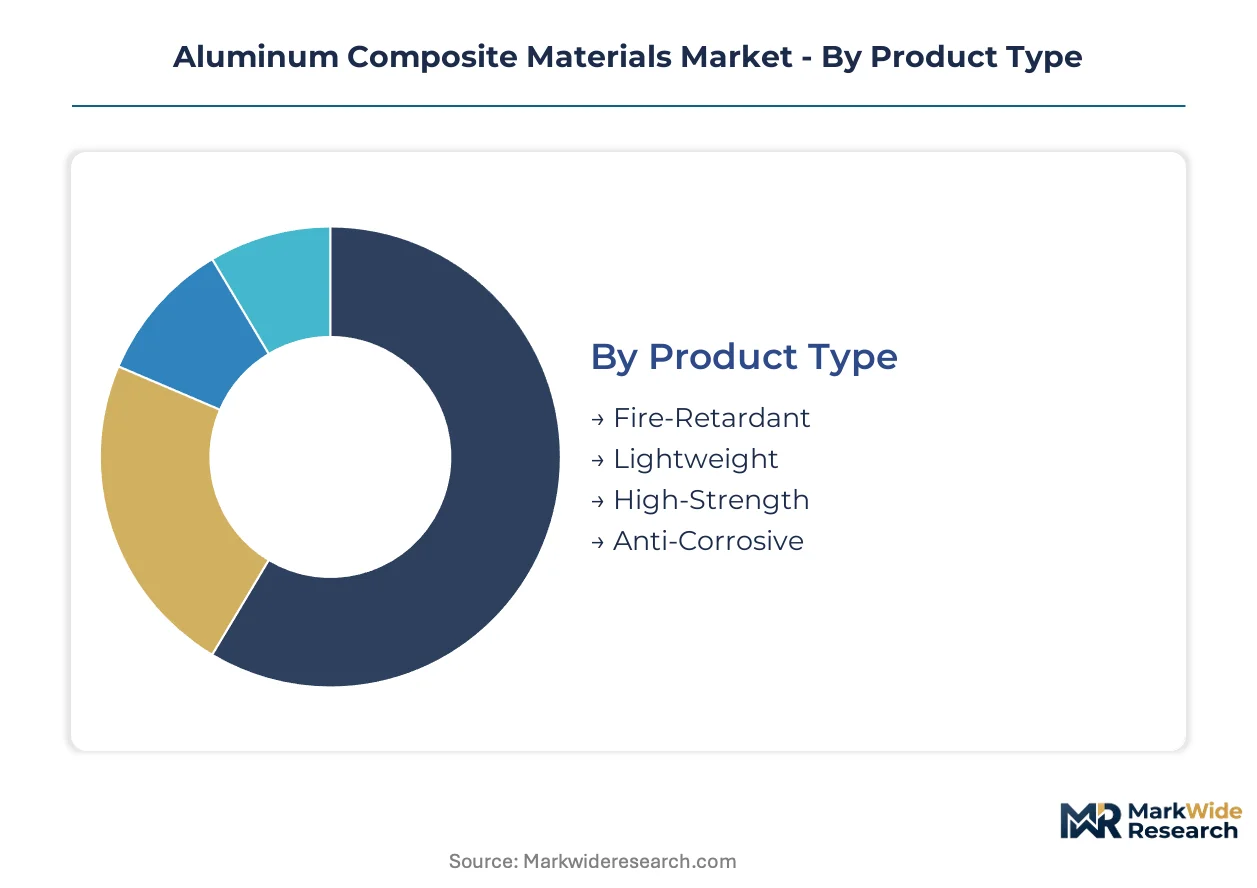
Aluminum composite material specifications diverge sharply across procurement channels, with facade engineering consultants driving fire-retardant grades while transport OEMs pull lightweight formulations through direct mill relationships. Segment boundaries are hardening as certification requirements fragment supply chains into parallel qualification tracks.
Product Type:
Channel mix splits between project-specified architectural grades and OEM-direct transport materials, with distributors handling commodity signage stock.
- Fire-Retardant:Mineral-filled polymer cores with engineered flame-retardant loading meet German and Swiss facade codes for structures above 20 meters. European retrofit contractors and Chinese transit authorities compress lead times for compliant material qualification.
- Lightweight:Density-optimized cores reduce mass 40% below solid aluminum while maintaining flexural rigidity. Battery-electric bus and rail car manufacturers specify these grades to extend range, pulling volume from steel interiors.
- High-Strength:Reinforced core structures for structural load-bearing applications in aerospace and heavy transport.
- Anti-Corrosive:Specialized surface treatments for marine and chemical exposure environments.
By volume, Fire-Retardant leads. By growth pace, Lightweight is climbing the fastest.
End Use Industry:
Cost tier stratification separates premium certified architectural supply from economy signage stock, with transport applications commanding mid-tier pricing.
- Building & Construction:Facade envelopes and interior cladding dominate volume, with German KfW subsidies expanding retrofit project pipelines for low-emissivity grades. CE marking requirements under EU Construction Products Regulation bifurcate the supplier base.
- Automotive:Electric bus and commercial vehicle interior panels require crashworthiness certification and smaller batch production, yielding superior margin pools.
- Aerospace:Weight-critical structural and interior applications with stringent material traceability requirements.
- Signage:Taiwan's domestic market and South Asian retail development drive cost-optimized panel demand with minimal certification overhead.
Building & Construction commands the largest share. Aerospace shows the steepest expansion trajectory.
Form:
Volume concentration favors standardized sheet and panel formats, with custom fabrication serving project-specific architectural contracts.
- Sheets:Continuous coil-coated aluminum skins bonded to polymer cores, fed into downstream panel fabrication and signage processing.
- Panels:Rigid sandwich structures constitute the primary architectural specification, with dimensional tolerances critical for facade system integration.
- Rolls:Flexible formats for curved surface applications and transport interior lining systems.
- Custom Shapes:Project-engineered geometries for complex envelope designs and branded corporate installations.
Panels generate the highest revenue concentration. Custom Shapes are gaining share fastest in premium architectural segments.
Application:
Application mix reflects diverging margin structures, with facades scaling through general contracting channels and transport cladding flowing through OEM-direct procurement.
- Facades:Weather-resistant architectural envelopes command the largest application volume, with specification authority migrating to facade engineering consultants who bundle fire certification and thermal modeling. London, Frankfurt, and Singapore tower developments consolidate this channel.
- Transport:Rail car and electric bus interiors combine lightweight requirements with crashworthiness standards, creating certification barriers that protect qualified suppliers.
- Interior Design:Corporate and retail fit-out applications emphasizing surface finish consistency and rapid installation.
- Cladding:Protective and aesthetic envelope systems for industrial and infrastructure buildings.
Facades lead by project count. Transport offers the strongest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen-Zhongshan Bridge and expanding Guangzhou-Shenzhen-Hong Kong high-speed rail corridor anchor China's procurement dominance for transit-grade aluminum composite panels. German and Swiss facade retrofit pipelines draw from Rhine-Ruhr industrial logistics networks. India's Delhi-Mumbai Industrial Corridor and Saudi Arabia's NEOM giga-project reshape regional demand concentration.
China
Provincial transit authorities in Guangdong and Jiangsu mandate aluminum cladding for airport terminals and metro extensions under MIIT technical directives. GB standards governing flame spread ratings drive specification uniformity across municipal fire bureaus. Shanghai and Beijing tower developments compress lead times for fire-retardant panel qualification through bundled engineering consultant contracts.
Germany
KfW federal subsidies for envelope retrofits expand project pipelines for low-emissivity panel grades in Frankfurt and Munich commercial districts. ECHA REACH restrictions on hexavalent chromium accelerate trivalent passivation adoption among coil-coating mills. The Rhine-Ruhr corridor concentrates notified body relationships and CE marking expertise for Construction Products Regulation compliance.
India
Cost-optimized panel demand in South Asian high-rise and retail development remains underpenetrated by fire-certified European suppliers. BIS technical standards for building materials are converging with international fire-test protocols. Maharashtra and Gujarat industrial corridors host domestic fabricators competing on volume output for commercial construction.
Switzerland
Swiss facade codes for structures above 20 meters institutionalize mineral-filled polymer cores as baseline specification. Swissmedic-aligned material traceability requirements extend to architectural envelope components in pharmaceutical and biotech campus developments. Zurich and Geneva engineering consultants consolidate specification authority through bundled fire certification and thermal modeling services.
Saudi Arabia
NEOM and Red Sea Project giga-developments specify aluminum composite cladding for hospitality and transport infrastructure at unprecedented scale. The country's national building code regulator enforces Gulf-standard fire performance ratings for public buildings. Riyadh and Jeddah fabrication clusters are expanding coil-coating capacity to serve domestic project demand.
Aluminum Composite Materials Market Competitive Environment
Concentration sits with European mill-based suppliers and Asian polymer-integrated fabricators competing across parallel certification tracks. The vendor base stratifies into three tiers: premium architectural specialists with captive testing laboratories, mid-scale regional fabricators serving domestic transit and signage markets, and commodity distributors handling uncertified stock. Strategic moves center on backward integration into polymer core production and geographic licensing partnerships to bypass freight exposure.
Among European mill-based suppliers, 3A Composites GmbH exemplifies the premium architectural archetype through its German manufacturing footprint and notified body relationships. Mitsubishi Chemical Corporation anchors the polymer-integrated tier through captive core production controlling raw material quality pathways. Alstrong Enterprises India Pvt. Ltd. occupies a position within the cost-optimized regional fabricator segment serving South Asian commercial construction volume. Jyi Shyang Industrial Co., Ltd. represents the domestic market specialist archetype concentrated on Taiwan's signage and transport interior procurement channels.
| Leading Market Players |
|---|
| 3A Composites GmbH |
| Arconic Inc. |
| Mitsubishi Chemical Corporation |
| Alstrong Enterprises India Pvt. Ltd. |
| Jyi Shyang Industrial Co., Ltd. |
| Alubond USA |
| Alucoil |
| Yaret Industrial Group |
| Fairview Architectural |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between European facade contractors and German coil-coating mills lock in aluminum skin supply and insulate project bids from LME spot volatility. These arrangements bundle fire-retardant core certification with volume commitments, compressing price uncertainty for transit infrastructure tenders in China and retrofit pipelines in Switzerland.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates fire-certified architectural grades from commodity signage stock. Price differentiation rests on CE marking status and REACH-compliant surface treatments, with German and Swiss specifications commanding premiums. Pricing pressure stems from aluminum ingot volatility on spot-contract residential projects. Cost-optimized South Asian commercial construction exhibits highest price sensitivity, while Chinese transit authorities prioritize certification compliance over unit economics.
Supply Chain Analysis
Strait of Malacca transit underwrites polymer core feedstock flows from East Asian petrochemical corridors to European and North American panel fabricators. Supply concentrates in China, South Korea, and Taiwan for polyethylene and mineral-filled polymer cores. Raw material dependencies span primary aluminum ingots, flame-retardant additives, and fluoropolymer coil coatings. Single-source vulnerability sits with East Asian core polymer concentration, exposing mills to freight cost spikes. Distribution runs through facade engineering consultants who bundle specification authority with certified product sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tracks creates niche entry points as specification authority migrates from general contractors to engineering consultants bundling fire performance and thermal modeling.
For Market Incumbents: Shield margin pools in transport interiors by deepening captive polymer core production and accelerating notified body relationships for CE marking queue priority. Coil-coating technician scarcity threatens capacity utilization; defend through vocational program partnerships in the Rhine-Ruhr corridor. Certification investment remains the priority lever against Asian cost-optimized imports. For New Entrants and Emerging Players: Lead with fire-retardant panel qualification for Indian commercial construction, where BIS standards convergence creates first-mover advantage before European suppliers establish local fabrication. Cost-optimized output for Maharashtra and Gujarat high-rise development offers the most penetrable white-space. Go-to-market through domestic distributor networks with bundled installation support. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale fabricators with established MIIT compliance for Chinese transit infrastructure and latent capacity for European REACH adaptation. Long-term viability favors suppliers with parallel qualification tracks across both regulatory regimes. Watch for aluminum ingot price inflection as signal for margin compression severity in spot-exposed segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Core Production | Mitsubishi Chemical's captive supply model controls raw material quality pathways for high-performance grades. |
| CE Marking Fast-Track Investment | Notified body relationships compress qualification timelines for German KfW-subsidized retrofit pipelines. |
| Regional Fabrication Licensing | Geographic partnerships bypass freight exposure from East Asian petrochemical corridors to European mills. |
| Flame-Retardant Core R&D Expansion | Mineral-filled polymer engineering meets Swiss facade codes for structures above 20 meters. |
| Vocational Training Partnerships | Coil-coating technician pipelines address retirement-driven skill scarcity in continuous anodizing lines. |
Study Parameters
Initial hypotheses were tested against primary input from facade engineering consultants, coil-coating mill technical directors, transit authority procurement officers, and polymer core R&D leads, then refined against secondary validation. Trade flow data from customs authorities, ECHA REACH restriction filings, MIIT technical directive archives, and Construction Products Regulation notification databases anchored supply-side assessment. Bottom-up project pipeline analysis across Chinese airport terminals and German commercial retrofits was triangulated with top-down market sizing.
Variance decomposition across product type, end-use industry, form factor, and application channel shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit trends across fire-retardant, lightweight, and commodity grades. Forecast inputs incorporated aluminum ingot price elasticity assumptions and certification adoption curves for electric bus interior specifications.
Forecasts assume regulatory continuity in ECHA REACH enforcement and China MIIT flame spread standards; material policy shifts would require re-modeling. Aluminum price volatility, core polymer supply disruptions, or fire-test certification backlog extensions represent specific revision triggers. Practitioners should keep alternative scenarios live as F-Gas Regulation phase-down timelines and provincial Chinese fire bureau inspection intensities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Thermoset Composites Market
Composite Materials
Epoxy Composite Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
Scrim Reinforced Films Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Stone Plastic Composite Flooring Market
Composite Materials
Polypropylene and Polypropylene Composites Market
Composite Materials
Glass Fiber Reinforced Plastic (GFRP) Market
Composite Materials
Acrylic Laminates Market
Composite Materials
Composite Market
Composite Materials
Composites Distributor Market
Composite Materials
Wall Cladding Materials Market
Composite Materials
Short Fiber Thermoplastic Composites Market
Composite Materials
Graphite Carbon Raiser Market
Composite Materials
High Performance Carbon Fiber Precursor Market
Composite Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market