
 Global Honeycomb Core Materials Market | 2026-2036
Global Honeycomb Core Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Honeycomb Core Materials Market Intelligence
The shift towards modular, pre-fabricated composite panels is recalibrating buyer preferences away from raw material sheets. This trend favors suppliers who can deliver integrated, ready-to-install solutions. Hexcel Corporation leverages its extensive qualification portfolio to dominate the aerospace segment. In contrast, Plascore, Inc. competes on its broad product range, serving diverse industrial applications from marine to transportation. The Gill Corporation specializes in high-performance floor panels and cargo liners for aircraft.
Honeycomb core materials are lightweight structural components featuring a hexagonal cell geometry that provides high strength relative to their density. The core, typically made from materials like aluminum or Nomex, achieves its properties by resisting shear forces and stabilizing the outer skins of a sandwich panel. Aluminum and Nomex product types command the largest market share due to their established use in aerospace applications. The wind energy segment, however, is a significant growth area, requiring advanced materials for larger and more efficient turbine blades.
Strict airworthiness standards from the United States' FAA and the European Union Aviation Safety Agency (EASA) govern material use in aircraft. These regulations mandate extensive testing and certification, creating high barriers to entry for new material suppliers in the aerospace sector. ISO standards also define quality and performance metrics for industrial-grade materials. The central challenge for producers involves balancing the high cost of advanced thermoplastic development against the proven performance of traditional thermoset composites.
Market Dynamics
The market's central tension involves the intense pressure for lightweighting from transportation sectors, driven by fuel efficiency mandates, against the high costs and protracted certification cycles associated with introducing new materials into safety-critical applications, particularly in aerospace.
Growth Catalysts
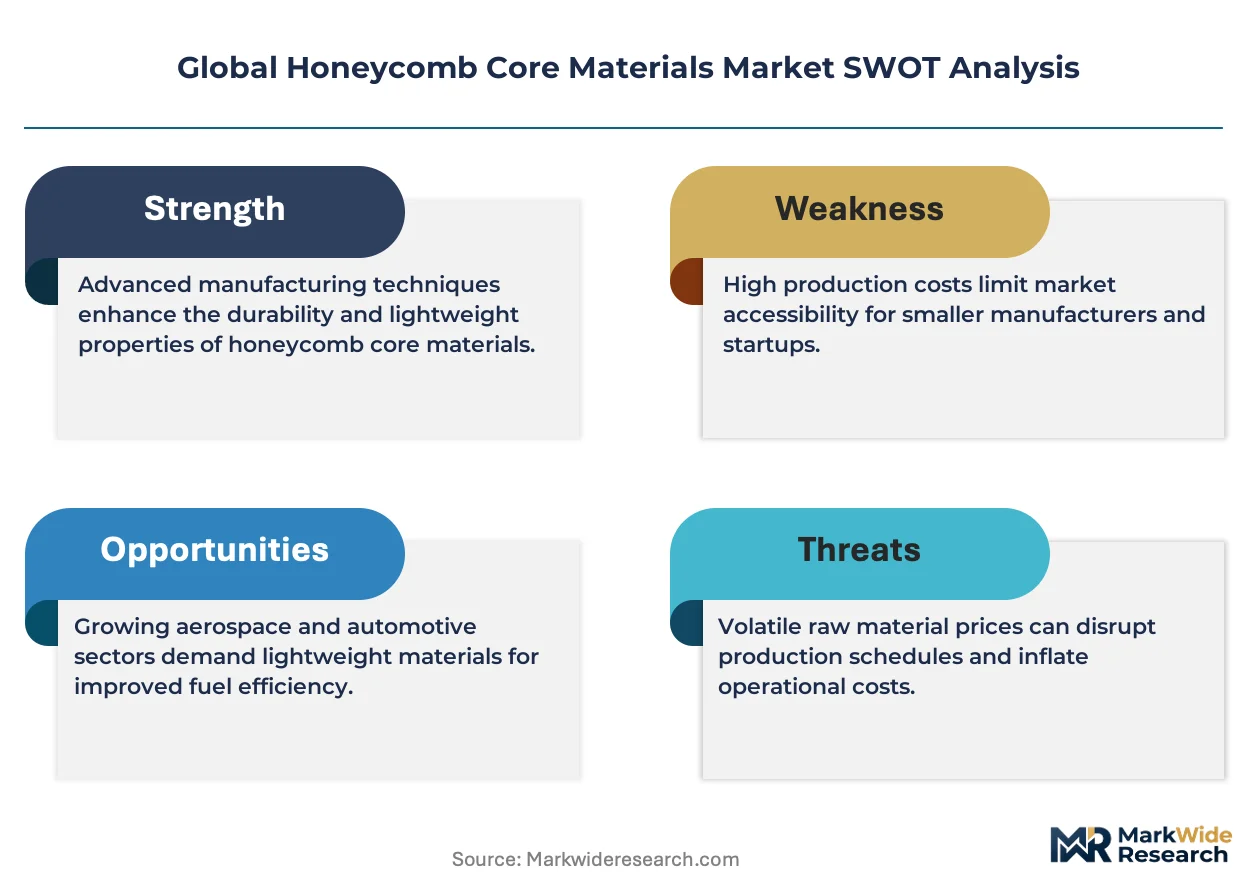
- Fuel Efficiency Mandates:Regulations such as the EU Green Deal and corresponding emissions standards in other regions compel aerospace and automotive manufacturers to adopt lighter components, directly benefiting honeycomb core materials.
- Infrastructure Expansion in China:The country's continued investment in high-speed rail networks and the development of its domestic commercial aircraft industry creates substantial, concentrated demand for structural composite panels.
- Manufacturing Automation:The maturation of automated fiber placement, robotic core shaping, and panel assembly processes is reducing manufacturing costs and cycle times, making composite sandwich structures more competitive against traditional metal fabrications.
Market Restraints
- High Raw Material Costs:The price of key precursor materials, particularly aerospace-grade Nomex aramid paper and high-purity aluminum foil, constitutes a significant portion of the final product cost, limiting adoption in cost-sensitive applications.
- Stringent Certification Hurdles:The extensive and costly testing and qualification processes mandated by bodies like the FAA and EASA create high barriers to entry and slow the adoption of new material innovations in aviation.
- Threat from Alternative Cores:In non-aerospace segments like marine and industrial, honeycomb cores face competition from structural foams and balsa wood, which can offer a different balance of cost, weight, and performance characteristics.
Strategic Opportunities
- Wind Energy Sector:The demand for larger and more efficient wind turbine blades presents a significant opportunity for lightweight, high-stiffness honeycomb materials capable of withstanding long-term fatigue and environmental exposure.
- Recyclable Thermoplastics:Developing and scaling production of thermoplastic honeycomb cores, such as PEI or PEEK, addresses circular economy goals and opens new applications where end-of-life recycling is a primary design constraint.
- Urban Air Mobility (UAM):The emerging UAM vehicle market requires novel, ultra-lightweight structural solutions that can be produced at higher volumes than traditional aerospace, creating a new demand category for advanced honeycomb composites.
Industry Challenges
- Capital-Intensive Production:The manufacturing of high-performance honeycomb cores requires significant capital investment in specialized equipment such as large-format presses, autoclaves, and precision cutting machinery, which can be a barrier for smaller producers.
- Composite Repair Expertise:A shortage of technicians skilled in the inspection, repair, and certification of damaged honeycomb composite structures limits the material's lifecycle and increases operational costs for end-users, especially in aviation maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Honeycomb Core Materials Market |
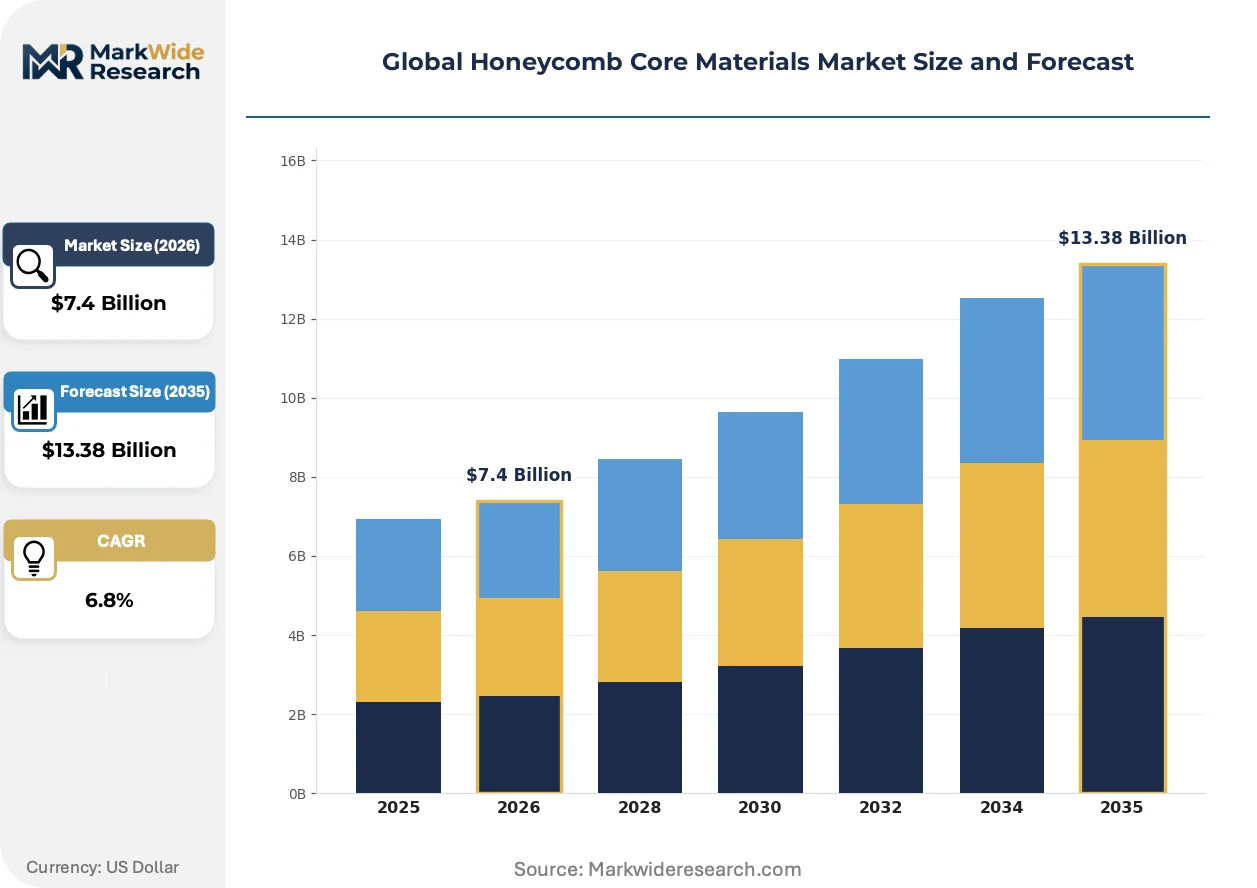
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Nomex, Thermoplastic, Paper, Titanium, Stainless Steel Application: Aerospace, Marine, Wind Energy, Defense, Transportation, Packaging Industry Sector: Aircraft Manufacturers, Shipbuilders, Renewable Energy Firms, Defense Contractors, Vehicle Producers, Consumer Packagers Material Form: Sheet, Panel, Folded, Molded, Sandwich, Structural |
| Companies Covered | Hexcel Corporation, Euro-Composites S.A., Plascore, Inc., The Gill Corporation, Corex Honeycomb, Advanced Honeycomb Technologies, HONYLITE, ACP Composites, EconCore N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Honeycomb Core Materials Market Strategic Shifts & Innovations
Material science innovation is reshaping the market by intersecting with industrial-scale manufacturing demands. This creates a new performance frontier where material properties must be balanced with processability and lifecycle sustainability for adoption in next-generation aerospace and transportation platforms.
Advanced thermoplastic honeycomb cores, such as those made from PEKK, provide superior fire resistance and recyclability over traditional thermosets. The emerging urban air mobility sector is adopting these materials for its fast-paced development cycles. This material innovation is converging with automated thermoforming and robotic assembly to enable high-rate production of complex structural components, a historical bottleneck for composites.
The EU's Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure on environmental impacts. This policy is forcing honeycomb core producers and their customers to track and report the full lifecycle carbon footprint of their products. Aerospace and automotive suppliers selling into the European Union are most impacted, which is accelerating the search for bio-based resins and recyclable core materials.
A behavioral shift is evident as airframers move from purchasing raw material sheets to procuring fully integrated, pre-fabricated composite panels. This model disrupts traditional distributors, favoring suppliers who offer design, kitting, and sub-assembly services as a bundled solution. This pattern is most pronounced in the United States and French commercial aerospace supply chains, where prime contractors seek to de-risk and simplify final assembly lines.
Global Honeycomb Core Materials Market Segmentation
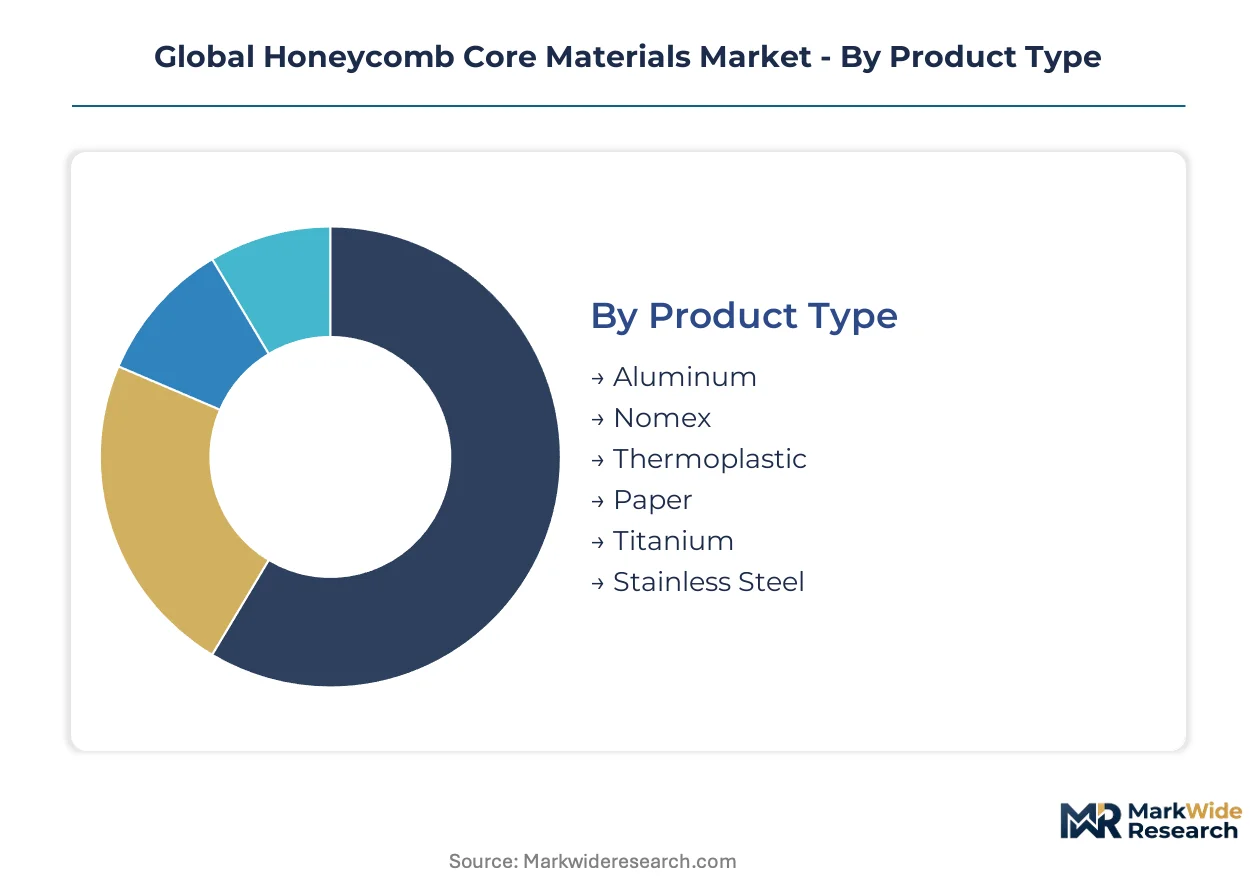
The global honeycomb core materials market differentiates across several dimensions, reflecting the specialized performance needs of diverse end-use industries. Understanding these segmentations provides critical insight into material selection drivers, technological advancements, and shifting demand concentrations within the global market.
Product Type:
The market classifies core materials by their fundamental composition, reflecting distinct performance profiles and application suitability for various engineering challenges.
- Aluminum:These cores feature a hexagonal cell structure made from aluminum alloy foil, offering high strength-to-weight ratio, excellent fire resistance, and superior electromagnetic shielding properties. Demand concentrates in commercial aircraft structures and high-speed rail, where lightweighting and structural integrity are paramount.
- Nomex:Composed of aramid paper impregnated with phenolic resin, Nomex cores provide exceptional fire resistance, high dielectric strength, and good fatigue performance, making them critical for aircraft interiors and military applications. The aerospace sector drives significant procurement due to stringent airworthiness standards from the FAA and EASA.
- Thermoplastic:These cores, often made from PEI or PEEK, offer enhanced recyclability and improved impact resistance over traditional thermosets, finding adoption in emerging urban air mobility vehicles.
- Paper:Typically made from kraft paper, these cores provide cost-effective lightweighting for non-structural applications like packaging and interior doors.
- Titanium:Offering superior high-temperature performance and corrosion resistance, titanium cores serve niche, high-performance applications in advanced aerospace and defense systems.
- Stainless Steel:These cores provide high strength and corrosion resistance in extreme environments, primarily used in industrial processing equipment and marine applications.
Aluminum cores lead on scale; thermoplastic cores lead on momentum.
Application:
Demand patterns for honeycomb core materials vary significantly across diverse end-use applications, each presenting unique performance requirements.
- Aerospace:This segment utilizes honeycomb cores extensively for aircraft wings, fuselage panels, and interior components, driven by the critical need for lightweighting, fuel efficiency, and structural rigidity. Airframers in the United States and Europe are major consumers.
- Wind Energy:Honeycomb materials are employed in manufacturing larger, more efficient wind turbine blades, providing stiffness and reducing overall weight to improve energy capture. European and Chinese wind farm developers accelerate this demand.
- Marine:Honeycomb cores reduce weight in boat hulls, decks, and interior panels, enhancing fuel efficiency and speed for commercial and recreational vessels.
- Defense:Military aircraft, naval vessels, and ballistic protection systems use honeycomb cores for their high strength-to-weight ratio and impact absorption capabilities.
- Transportation:Automotive and rail industries use these materials for interior panels, flooring, and structural components to reduce vehicle mass and improve fuel economy.
- Packaging:Honeycomb paperboard provides lightweight, protective cushioning for sensitive goods during transport, particularly for electronics and industrial components.
Aerospace applications drive significant volume, while the wind energy segment shows the steepest expansion trajectory.
Industry Sector:
The customer base for honeycomb core materials spans several industrial sectors, each with specialized procurement needs and material specifications.
- Aircraft Manufacturers:These firms procure high-performance aluminum and Nomex cores for structural and interior applications in commercial and military aircraft. Boeing and Airbus are major buyers.
- Renewable Energy Firms:Companies involved in wind turbine manufacturing specify lightweight, durable honeycomb materials for blade construction. Vestas and Siemens Gamesa represent key demand sources.
- Shipbuilders:These companies integrate honeycomb cores into marine vessels for weight reduction and structural enhancement, improving performance and fuel efficiency.
- Defense Contractors:Firms supplying military equipment utilize honeycomb composites for their strength, ballistic resistance, and radar transparency in defense platforms.
- Vehicle Producers:Automotive and rail vehicle manufacturers incorporate honeycomb cores to achieve lightweight designs and improve structural integrity.
Aircraft manufacturers represent the largest purchasing entities, with renewable energy firms demonstrating rapid procurement growth.
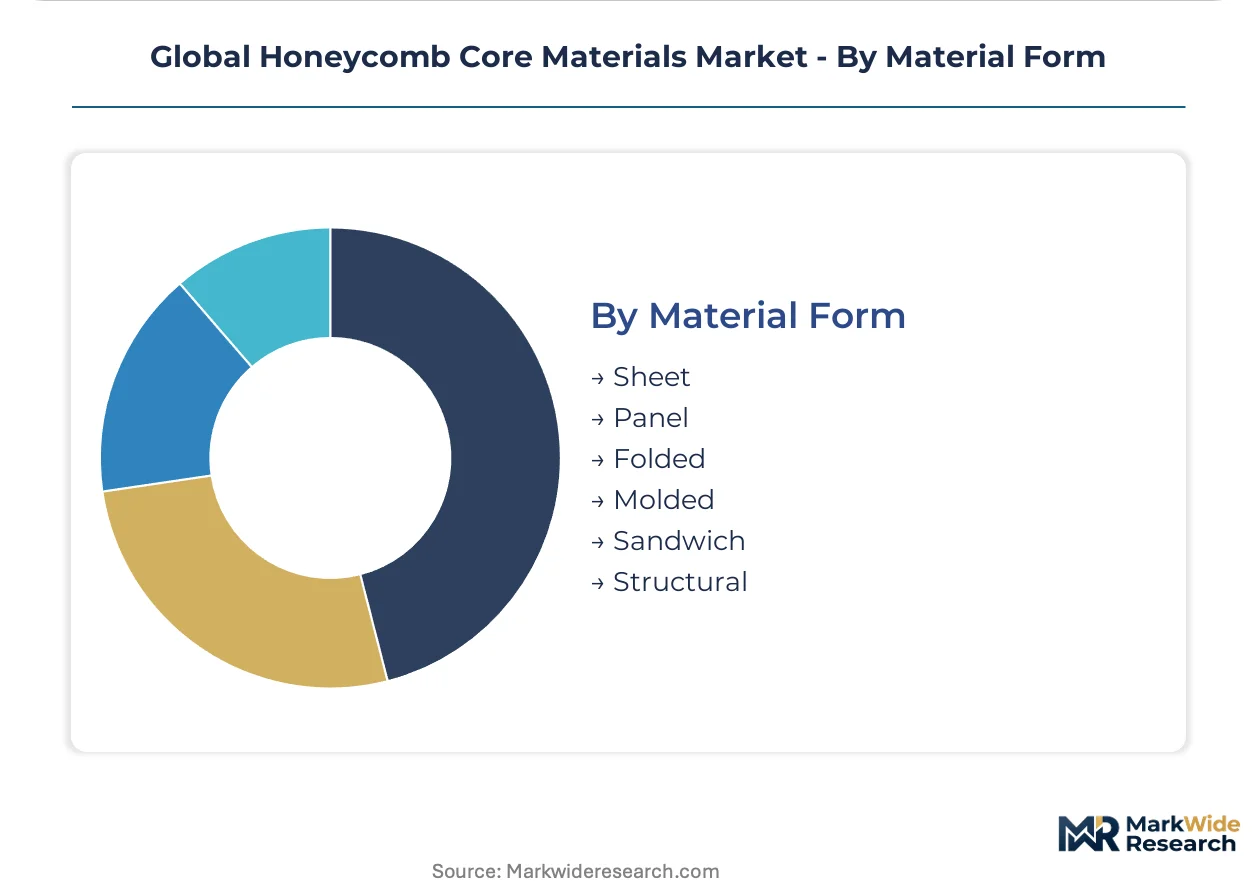
Material Form:
Honeycomb core materials are supplied in various processed forms, influencing manufacturing efficiency and final product integration.
- Panel:Pre-fabricated honeycomb panels, often with pre-bonded skins, offer ready-to-install solutions that reduce assembly time and complexity for end-users. This form is increasingly preferred by aerospace prime contractors in France and the United States.
- Sandwich:This fundamental structural configuration involves a honeycomb core bonded between two outer skins, creating a lightweight, high-stiffness composite structure. It forms the basis for many aerospace and wind energy applications.
- Sheet:Raw honeycomb sheets are supplied in expanded or unexpanded forms, allowing manufacturers to cut and shape the core to specific component geometries.
- Folded:This form provides a flexible core that can be shaped into complex curves or angles before final bonding.
- Molded:Honeycomb cores can be molded into specific three-dimensional shapes, enabling the production of complex components with minimal waste.
- Structural:This classification refers to honeycomb cores specifically designed and certified for load-bearing applications, meeting stringent engineering specifications.
Panel forms simplify assembly for end-users, and sandwich structures remain the foundational material configuration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The honeycomb core materials industry traces its origins to early aerospace applications, where lightweighting was paramount for flight. This foundational demand has expanded globally, with specialized production and consumption centers emerging across continents. Key regions now drive innovation and adoption in diverse end-use sectors.
United States
United States demand for honeycomb core materials is driven by a robust aerospace sector and emerging urban air mobility (UAM) vehicle production. Stringent FAA airworthiness standards mandate extensive material testing and certification for aircraft components. Commercial aerospace supply chains in Wichita and Seattle procure pre-fabricated panels for final assembly.
China
China's substantial infrastructure expansion, including high-speed rail and domestic commercial aircraft, creates concentrated demand for structural composite panels. The country's dual carbon goals accelerate the adoption of lightweight materials in transportation and wind energy. Manufacturing hubs in the Yangtze River Delta are increasing production capacity for advanced honeycomb structures.
Germany
Germany's advanced manufacturing base drives demand for honeycomb cores in wind energy and automotive applications, emphasizing efficiency. The EU Green Deal and CE marking regulations encourage lightweighting and material performance across transport sectors. Northern Germany's wind turbine manufacturers in Rostock are integrating larger, more efficient composite blades.
France
French commercial aerospace and defense industries are significant consumers of high-performance honeycomb core materials. EASA airworthiness standards govern material use, ensuring safety and performance in aircraft structures. Toulouse, a major aerospace hub, sees prime contractors procuring integrated composite panels for efficient aircraft assembly.
Japan
Japanese high-speed rail and advanced automotive sectors seek lightweight honeycomb solutions for improved energy efficiency and structural integrity. METI policies and JIS standards promote material innovation and quality in manufacturing processes. The Nagoya region, a hub for transportation equipment, develops specialized composite components.
Global Honeycomb Core Materials Market Key Industry Players
The competitive structure tilts toward a tiered landscape, with established players dominating high-value segments. A few large, specialized manufacturers hold significant market share in aerospace, while numerous smaller firms cater to diverse industrial applications. Archetypes include high-performance aerospace specialists, broad industrial suppliers, and niche product innovators. Companies pursue portfolio diversification and strategic partnerships to offer integrated, ready-to-install solutions.
Within the high-performance aerospace specialist tier, Hexcel Corporation exemplifies market dominance through its extensive qualification portfolio for critical aircraft components. Plascore, Inc. occupies a position as a diversified supplier, serving a broad range of industrial applications, from marine to transportation. The Gill Corporation anchors the segment for specialized high-performance floor panels and cargo liners, particularly for aircraft interiors. These firms represent distinct strategic approaches to capturing value across the varied demands of the honeycomb core materials market.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Euro-Composites S.A. |
| Plascore, Inc. |
| The Gill Corporation |
| Corex Honeycomb |
| Advanced Honeycomb Technologies |
| HONYLITE |
| ACP Composites |
| EconCore N.V. |
| Others |
Cost & Logistics Intelligence
The shift towards modular, pre-fabricated composite panels recalibrates buyer preferences in aerospace, directly influencing supply chain adaptations and pricing structures. This demand-side pressure compels suppliers to offer integrated solutions, moving beyond raw material sheets.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing for high-performance aerospace and wind energy applications. Price differentiation stems from the stringent FAA and EASA certification levels, coupled with the degree of customization for ready-to-install panels. Pricing softness reflects competition from alternative core materials in non-aerospace segments. Packaging and non-structural applications exhibit the highest price sensitivity, while aerospace buyers prioritize performance over cost.
Supply Chain Analysis
Domestic-content mandates and strategic national investments reshape sourcing patterns for honeycomb core materials. Supply concentrates in China for high-speed rail and wind energy components, alongside specialized production in the United States and Germany for aerospace and advanced industrial applications. The supply chain draws from critical inputs like Nomex aramid paper and high-purity aluminum foil. Commodity price volatility for these precursor materials presents a structural risk. Distribution typically runs through direct sales channels to large original equipment manufacturers (OEMs).
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage opportunity, leveraging lower manufacturing costs in regions like China against the higher value of certified components in the EU and US aerospace sectors.
For Market Incumbents: Cement market position by investing in advanced thermoplastic material development, particularly for urban air mobility (UAM) applications. Deepen vertical integration into automated pre-fabricated panel assembly to counter the threat from alternative core materials and reduce manufacturing costs. Prioritize FAA and EASA certification investments for new material innovations, securing access to critical aerospace platforms.
For New Entrants and Emerging Players: Begin with niche segments offering lower barriers to entry and higher growth potential, such as thermoplastic cores for the urban air mobility sector. Target underpenetrated industrial applications or specialized packaging solutions requiring lightweighting. A go-to-market strategy focusing on recyclable and bio-based composite solutions aligns with evolving sustainability mandates, particularly in the European Union.
For Investors and Strategic Acquirers: Asymmetric upside sits with niche specialists in advanced thermoplastic materials and automated composite manufacturing. Demand for lightweighting remains a structural trend across transportation sectors over the long term. Identify acquisition targets offering proprietary processing technologies or established qualification portfolios in emerging high-growth segments. Increased M&A activity in urban air mobility component suppliers signals an inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Thermoplastics | Addresses growing demand from UAM and circular economy goals in Europe. |
| Certification Investment (FAA/EASA) | Secures market access in high-value aerospace applications for new materials. |
| Automated Panel Assembly | Reduces manufacturing costs and cycle times for integrated composite solutions. |
| Bio-based Resin Development | Aligns with EU CSRD mandates for sustainable materials in aerospace. |
| Strategic Partnership with UAM OEM | Guarantees early integration into next-generation urban air mobility platforms. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core for this market study. Primary interviews with aerospace engineers, wind turbine blade designers, material procurement managers, and R&D directors informed qualitative insights. Secondary validation drew from EASA and FAA reports, industry association publications, company financial filings, and specialized trade journals.
Historical trendline analysis established the baseline for market sizing and growth projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, material form, and geographic region. Compound annual growth rates were derived through regression analysis and validated with expert consensus, incorporating inputs like aircraft delivery schedules and wind turbine installation forecasts.
Caveats apply where raw material price volatility, geopolitical trade policies, or new certification standards could materially shift the outlook. Forecasts reflect assumptions documented through extensive primary and secondary research. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
LAMEA Composite Process Material Kits Market
Composite Materials
FRP Tanks Market
Composite Materials
Balsa Core Materials Market
Composite Materials
Global Composites Cylinder Market
Composite Materials
High Temperature Composite Resin Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Marine Composites Market
Composite Materials
Global Sports Composites Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Transportation Composites Market
Composite Materials
Composite Rollers Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
Carbon Composites Market
Composite Materials
Molded Underfill Material Market
Composite Materials
Composite Process Material Kits Market
Composite Materials
Composite Quartz Stone Market