
 Stone Plastic Composite Flooring Market | 2026-2036
Stone Plastic Composite Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Stone Plastic Composite Flooring Market Intelligence
Subscription-based floor monitoring and predictive maintenance software is pivoting how SPC flooring vendors monetize installations beyond the initial sale. Mohawk Industries leverages its captive resin compounding to control raw material quality across North American plants. Tarkett competes through architect-specified commercial portfolios that emphasize acoustic performance and slip resistance. Shaw Industries Group anchors its position with integrated backing and underlayment technologies that reduce third-party dependencies.
Stone plastic composite flooring combines calcium carbonate, polyvinyl chloride, and stabilizers into a rigid core typically measuring 4-8 millimeters, engineered for dimensional stability under moisture exposure and heavy foot traffic. Luxury vinyl tile and plank formats lead residential replacement cycles due to DIY-friendly click-lock profiles, while glue-down sheet applications dominate healthcare and education institutional budgets where seam welding and infection control matter. Click-lock installation methods are displacing traditional floating systems in multi-family housing renovations because they tolerate subfloor imperfections without adhesive cost or cure time.
Flooring products sold into the European Union must satisfy REACH chemical restrictions and CE marking for construction products, while US EPA TSCA Title VI limits formaldehyde emissions from composite wood components used in hybrid assemblies. California's Department of Public Health maintains VOC emission standards that de facto shape nationwide product formulation decisions for brands distributing across US states. Stakeholders should monitor how evolving extended producer responsibility frameworks in Germany and France reshape end-of-life collection costs and core material recyclability requirements.
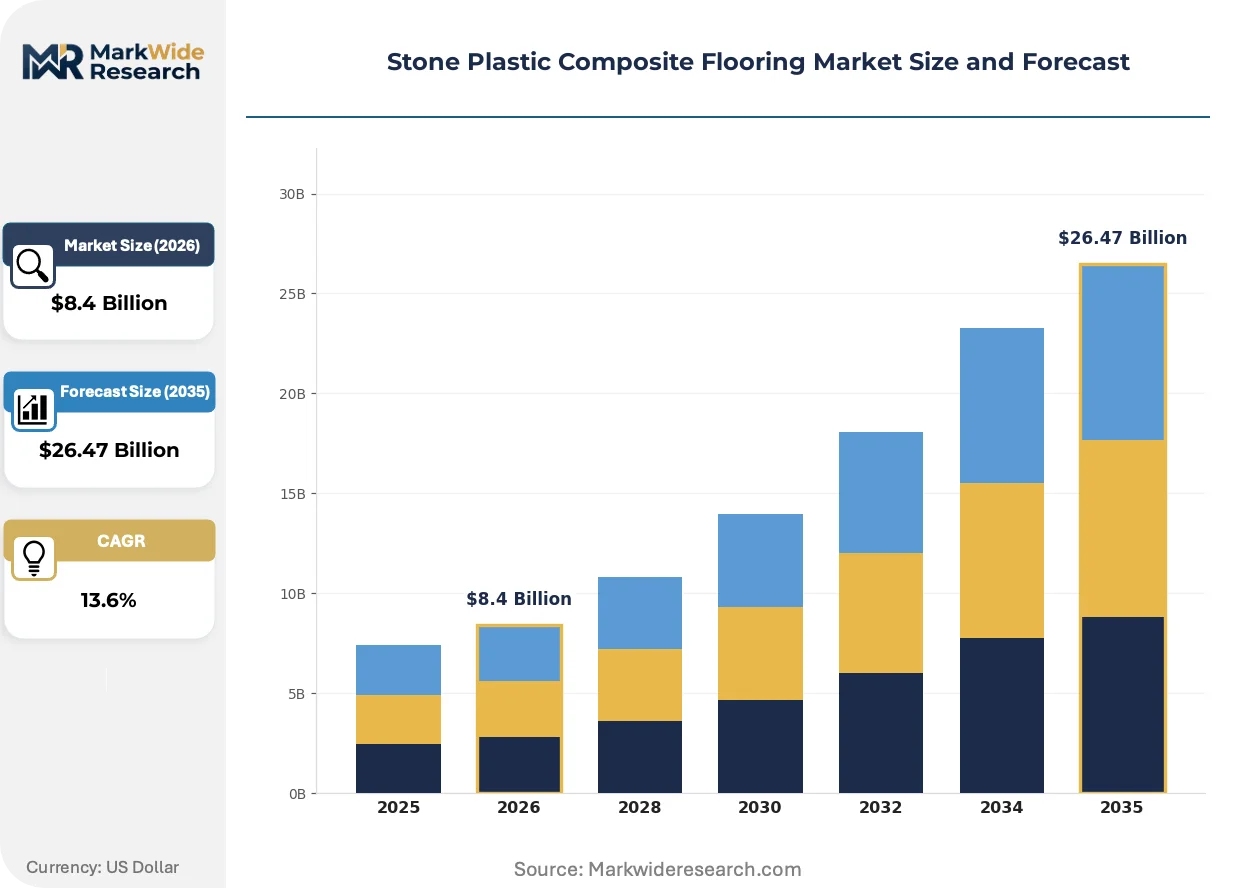
Market Dynamics
Residential renovation spending compression and REACH-driven formulation shifts are forcing SPC flooring manufacturers to restructure resin sourcing and core composition strategies across multiple continents simultaneously.
Growth Catalysts
- REACH and RoHS compliance mandates:European chemical restrictions accelerate low-VOC formulation R&D, creating first-mover advantages for producers with certified product lines.
- Multi-family housing renovation cycles:Click-lock SPC tolerates subfloor imperfections without adhesive cure time, capturing replacement demand in aging apartment stock across Germany and France.
- Calcium carbonate supply clustering:Domestic raw material concentration in China's Hebei and Shandong provinces compresses input costs for export-oriented manufacturers.
Market Restraints
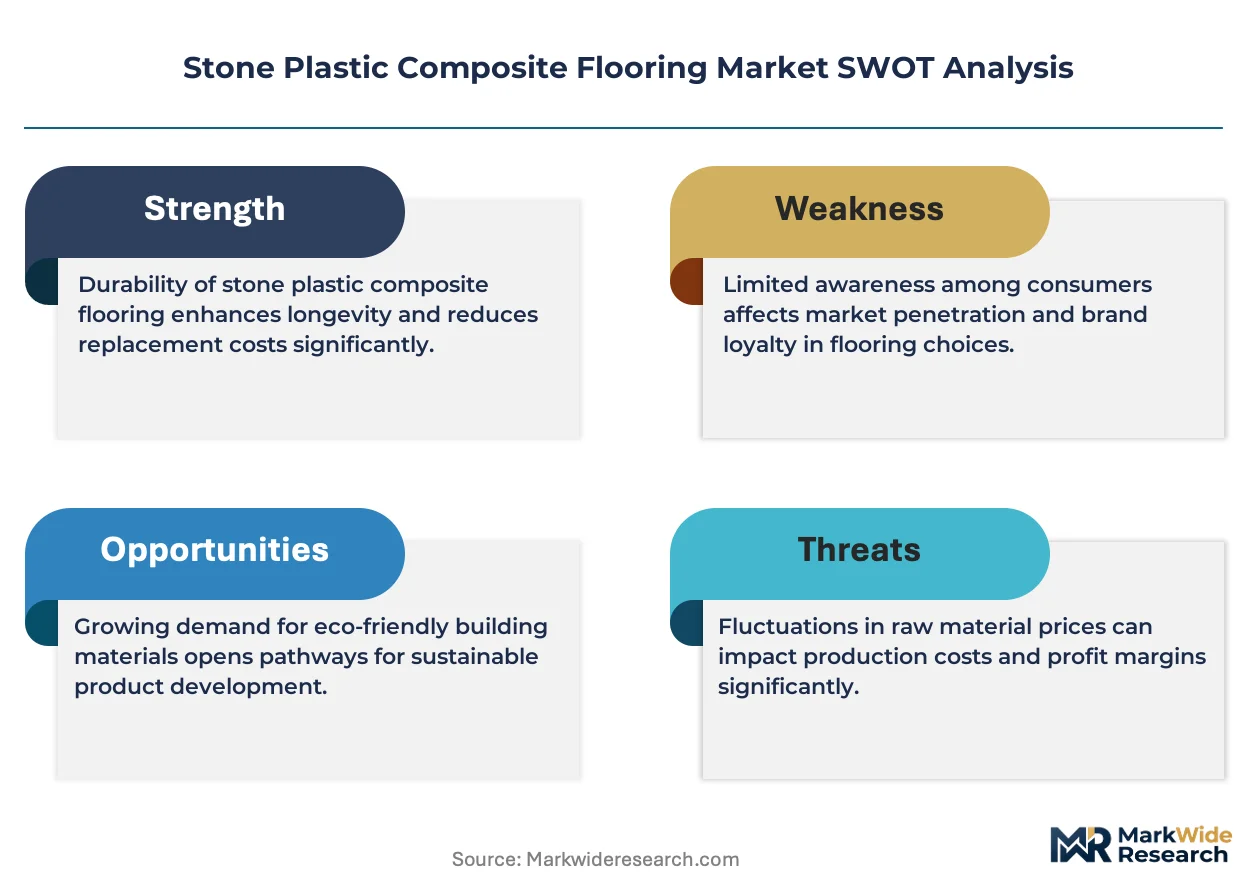
- PVC resin price volatility:Ethylene feedstock fluctuations and energy cost spikes in European petrochemical corridors compress margin predictability for non-integrated producers.
- Core material recyclability gaps:Calcium carbonate-PVC bonding chemistry limits closed-loop recovery options, exposing producers to Germany's extended producer responsibility fee escalations.
- Engineered hardwood substitution:Cross-laminated timber and modified wood products capture premium residential segments where natural material aesthetics dominate specification.
Strategic Opportunities
- India's underpenetrated commercial flooring:Healthcare and education infrastructure expansion creates specification openings for infection-control-rated SPC sheet products.
- Subscription-based floor monitoring:Sensor-embedded SPC combined with predictive maintenance software creates recurring revenue streams beyond initial installation.
- EU Green Deal renovation wave:Building energy retrofit mandates accelerate flooring replacement timelines in public sector budgets across member states.
Industry Challenges
- CE marking certification timelines:Construction Products Regulation testing protocols delay product launches by 8-14 months for new core formulations.
- Acoustic performance integration:Multi-layer underlayment bonding with rigid SPC cores requires capital-intensive lamination line reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stone Plastic Composite Flooring Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.47 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Vinyl Tile, Plank, Sheet, Others Application: Residential, Commercial, Industrial, Institutional Installation Method: Glue Down, Click Lock, Loose Lay, Floating End User: Homeowners, Contractors, Architects, Designers |
| Companies Covered | Armstrong Flooring, Novalis Innovative Flooring, Mohawk Industries, Gerflor, Tarkett, Shaw Industries Group, CFL Flooring, Zhejiang Walrus New Material, Mannington Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stone Plastic Composite Flooring Market Strategic Shifts & Innovations
Digital manufacturing controls and connected floor systems are restructuring how SPC products are specified, installed, and monetized across residential and commercial channels.
Embedded sensor networks within SPC flooring substrates is modularizing how facility managers monitor foot traffic patterns, moisture intrusion, and structural wear in real time. Hospitality chains and retail operators in the United States are piloting these systems to compress maintenance response windows. The technology is modularizing vendor revenue models from product sales toward data-service subscriptions.
ECHA's expanding SVHC candidate list is forcing reformulation of tin-based stabilizers and phthalate plasticizers ahead of sunset date announcements. Manufacturers serving EU distribution channels are accelerating calcium-zinc stabilizer transitions and third-party emissions testing. Healthcare and education segments face the steepest compliance costs due to stringent indoor air quality specifications.
Direct-to-installer digital platforms are compressing traditional distributor markups in North American residential replacement markets. Contractors now source SPC planks through manufacturer-operated portals with project-based volume pricing and installation training modules. This channel shift is most advanced in Florida and Texas metropolitan markets where renovation contractor density supports platform economics.
Stone Plastic Composite Flooring Market Segmentation
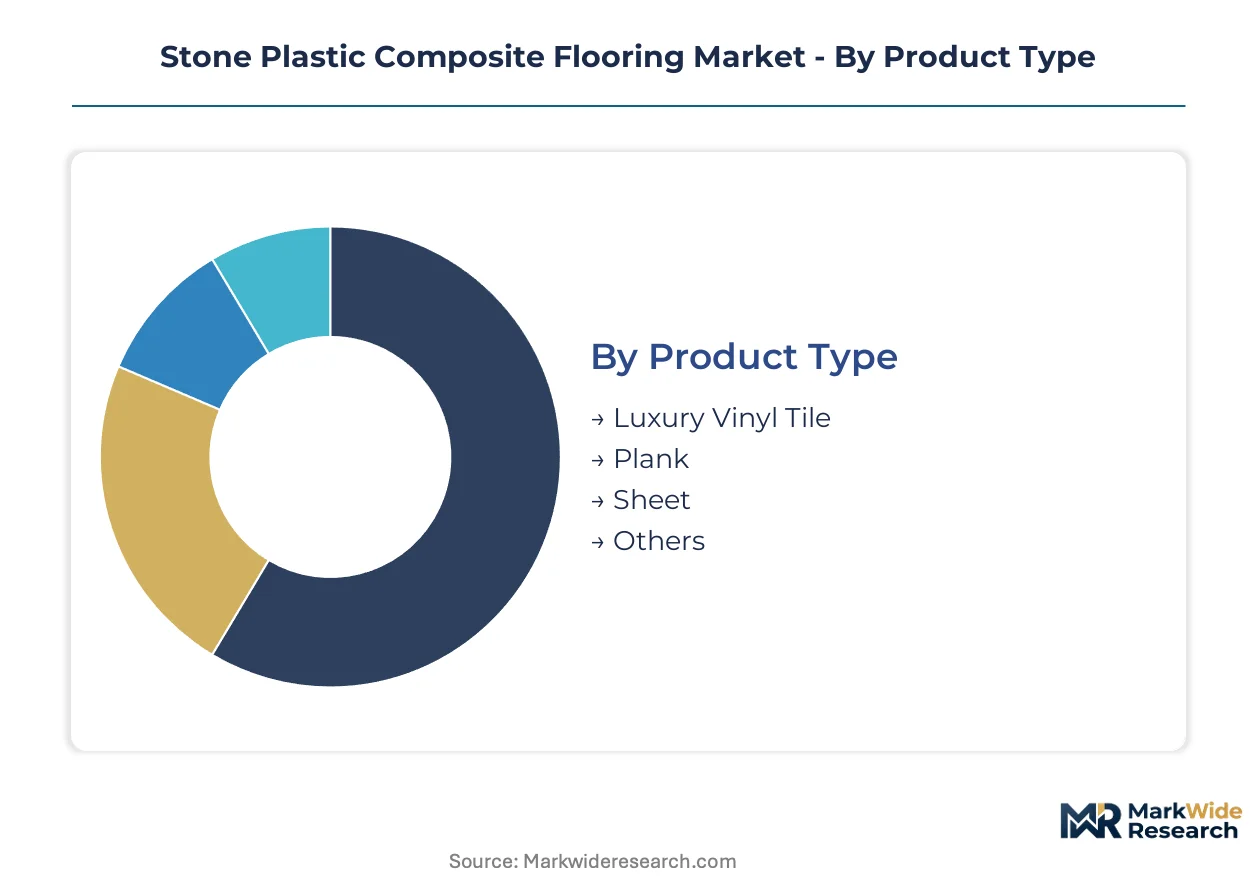
SPC flooring segmentation reflects divergent buyer priorities across residential renovation and institutional specification channels. Product format and installation method determine margin structures, while end-user professionalization shapes channel economics and brand positioning requirements.
Product Type:
Buyer sophistication separates DIY renovators seeking modular formats from facility managers demanding seamless sheet performance.
- Luxury Vinyl Tile:Square-cut rigid core units measuring 12x12 to 18x18 inches with grout-line embossing simulate ceramic and natural stone aesthetics. Demand concentrates in US kitchen and bathroom renovations where moisture resistance and underfoot comfort drive specification.
- Plank:Rectangular 4-8mm rigid core boards with registered emboss texture replicate hardwood grain patterns. German and French multi-family housing contractors favor click-lock plank systems for rapid turnaround on aging apartment stock replacement cycles.
- Sheet:Continuous roll goods requiring seam welding deliver infection-control performance for healthcare and education budgets. Glue-down installation tolerates heavy rolling loads in hospital corridors and commercial kitchens.
- Others:Specialty formats include rigid core herringbone patterns and mixed-width bundles targeting premium residential segments.
Volume sits with Plank formats; growth tilts toward Sheet specifications in healthcare infrastructure expansion.
Application:
Project scale and specification authority distinguish fragmented residential replacement from centralized institutional procurement.
- Residential:Single-family and multi-family renovation projects drive click-lock volume through big-box retail and direct-to-installer digital platforms. Florida and Texas metropolitan markets exhibit the densest contractor network adoption of manufacturer portal purchasing.
- Commercial:Retail, hospitality, and office fit-outs prioritize acoustic underlayment integration and slip resistance certification. Tarkett's architect-specified portfolios capture specification share through CE-marked performance documentation.
- Industrial:Manufacturing and warehouse flooring demands chemical resistance and static control properties from thicker 6-8mm core constructions.
- Institutional:Healthcare and education budgets in India and EU member states specify infection-control-rated sheet products with seam-welded hygiene barriers.
Residential channels absorb the highest unit volume; institutional specification commands the steepest compliance-driven expansion trajectory.
Installation Method:
Labor cost structure and subfloor condition tolerance separate adhesive-dependent systems from mechanical interlock alternatives.
- Click Lock:Tongue-and-groove mechanical fastening eliminates adhesive cure time and tolerates subfloor imperfections to 3/16 inch over 10 feet. German apartment renovation contractors displace floating systems with rigid interlock speed advantages.
- Glue Down:Pressure-sensitive or hard-set adhesive application delivers permanent bond for commercial sheet goods and high-traffic plank installations. US EPA TSCA Title VI compliance requirements shape adhesive formulation selection for hybrid assemblies.
- Loose Lay:Friction-backed plank systems rely on perimeter weight and dimensional stability for temporary or semi-permanent commercial installations.
- Floating:Traditional underlayment-dependent systems require expansion gaps and transition moldings, losing share to click-lock tolerance advantages.
Click Lock dominates residential renovation velocity; Glue Down retains institutional specification loyalty.
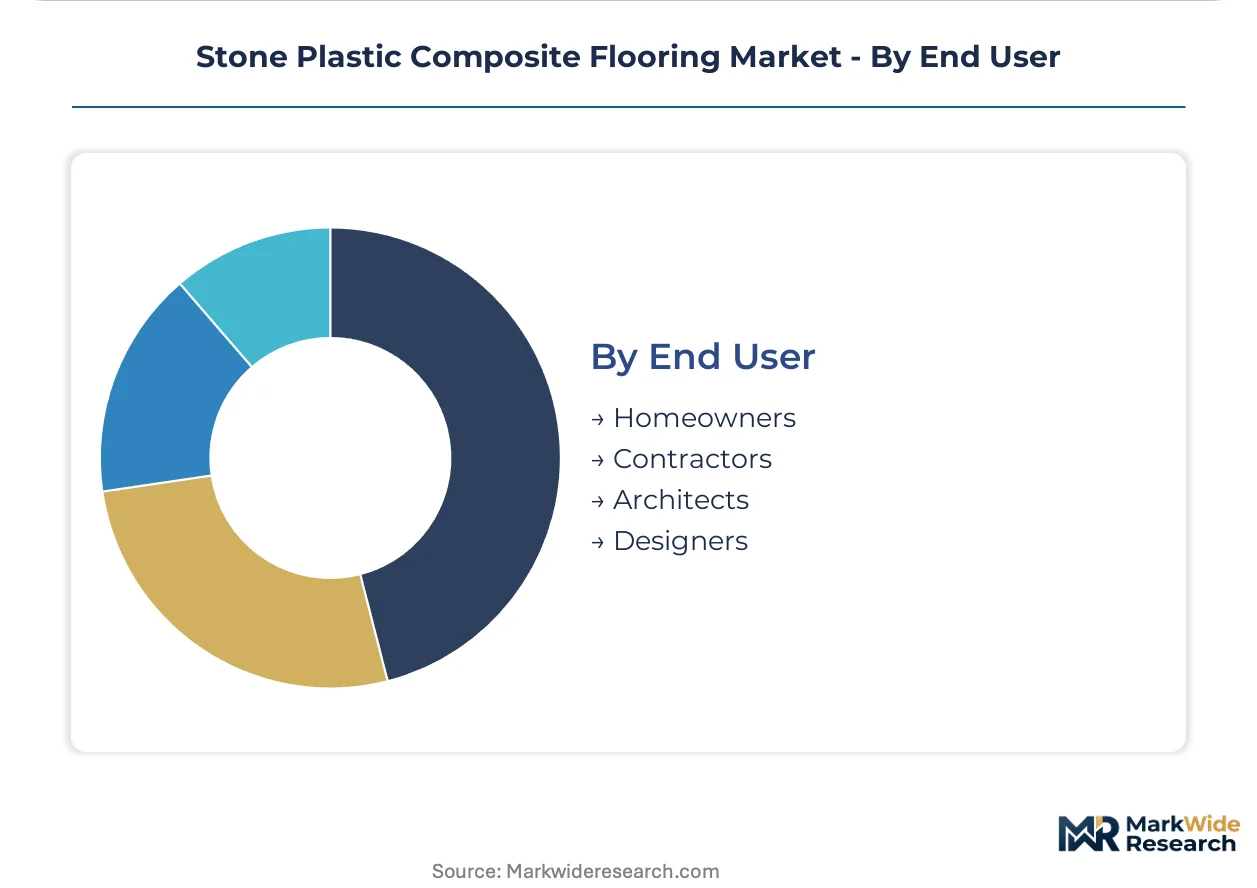
End User:
Technical specification authority and procurement scale fragment the buyer base across amateur renovators and professional intermediaries.
- Homeowners:DIY purchasers prioritize visual sampling, installation tutorial availability, and retail return policies. Direct-to-installer platform expansion in North America compresses traditional distributor markups for this segment.
- Contractors:Volume-based project purchasing through manufacturer portals combines with installation training module requirements. This segment drives click-lock adoption through speed-to-completion economics.
- Architects:Specification professionals demand acoustic performance data, slip resistance certification, and CE marking documentation for commercial and institutional projects.
- Designers:Interior design consultants influence residential premium segment selection through aesthetic trend alignment and sample library access.
Contractor procurement represents the highest transaction frequency; architect specification controls commercial project value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of SPC flooring output while the United States and Germany absorb the highest per-capita consumption volumes. This production-consumption divide shapes trade flows, raw material sourcing, and regulatory compliance investments across the value chain.
United States
Residential renovation contractors in Florida and Texas metropolitan markets drive click-lock plank demand through manufacturer direct-to-installer portals. EPA TSCA Title VI limits formaldehyde emissions from composite wood components in hybrid flooring assemblies. Manufacturing concentration sits in Georgia and South Carolina where resin compounding and rigid core extrusion lines serve domestic distribution networks.
Germany
Multi-family housing renovation cycles in Berlin and Hamburg accelerate replacement flooring demand from aging apartment stock. REACH chemical restrictions and CE marking under the Construction Products Regulation mandate low-VOC formulation compliance. Extended producer responsibility frameworks in North Rhine-Westphalia reshape end-of-life collection cost structures for calcium carbonate-PVC bonded materials.
China
Export-oriented manufacturers in Hebei and Shandong provinces leverage domestic calcium carbonate clustering to compress input costs for North American and European shipments. MIIT industrial standards and dual carbon goals pressure energy-intensive PVC resin and stabilizer production. The Yangtze River Delta hosts the densest concentration of rigid core lamination and click-lock profile finishing capacity.
France
Public sector building energy retrofit mandates under the EU Green Deal accelerate flooring replacement timelines in healthcare and education budgets. ECHA SVHC candidate list expansion forces tin-based stabilizer phase-outs ahead of regulatory sunset dates. Manufacturing activity clusters in the Hauts-de-France region where resin formulation and acoustic underlayment bonding lines serve architect-specified commercial projects.
India
Healthcare and education infrastructure expansion creates specification openings for infection-control-rated SPC sheet products in Delhi-NCR and Mumbai metropolitan corridors. BIS certification requirements and CDSCO medical device adjacent standards shape product testing protocols for institutional procurement. Gujarat and Maharashtra states attract glue-down sheet manufacturing investments targeting commercial flooring retrofit demand.
Stone Plastic Composite Flooring Market Key Industry Players
Top-tier vendors anchor specification-driven commercial and institutional channels, while mid-scale fabricators compete on residential renovation velocity and direct-to-installer platform economics. The vendor base stratifies across integrated resin compounders, architect-specified portfolio builders, and export-focused rigid core specialists. Three archetypes dominate: captive raw material controllers, acoustic performance differentiators, and digital channel first-movers. Competitive moves concentrate on backward integration into resin compounding and direct platform expansion to compress distributor markups.
Among North American integrated manufacturers, Mohawk Industries and Shaw Industries Group exemplify the captive supply archetype through in-house PVC resin and stabilizer production. Tarkett occupies a position within the architect-specified tier, representing European compliance-forward portfolio construction. CFL Flooring and Zhejiang Walrus New Material sit within the export-oriented specialist tier, anchoring Chinese manufacturing cluster output for international distribution.
| Leading Market Players |
|---|
| Armstrong Flooring |
| Novalis Innovative Flooring |
| Mohawk Industries |
| Gerflor |
| Tarkett |
| Shaw Industries Group |
| CFL Flooring |
| Zhejiang Walrus New Material |
| Mannington Mills |
| Others |
Cost & Logistics Intelligence
Ethylene feedstock indices and calcium carbonate benchmark pricing cascade through SPC flooring supply chains into three distinct procurement tiers. Manufacturers with captive resin compounding command margin insulation against petrochemical volatility, while non-integrated fabricators absorb input cost swings through project-based contract renegotiation with distributor networks.
Pricing Analysis
Margin tightening in standard-grade plank production reflects PVC resin price volatility and energy cost spikes across European petrochemical corridors. Three-tier pricing structure across premium, standard, and economy levels separates architect-specified acoustic systems from big-box retail SKUs and direct-to-installer bulk contracts. Certification grade under CE marking and volume scale through manufacturer portals drive price differentiation. Cost-down pressure on economy-tier products accelerates because calcium carbonate-PVC bonded materials face limited closed-loop recovery options. Residential renovation contractors exhibit highest price sensitivity; institutional specification buyers prioritize infection-control performance over unit cost.
Supply Chain Analysis
Calcium carbonate feedstock supply rests on domestic clustering in China's Hebei and Shandong provinces, where quarry proximity compresses input costs for export-oriented manufacturers. PVC resin production draws from ethylene crackers concentrated in the United States Gulf Coast, Germany's North Rhine-Westphalia chemical corridor, and China's Yangtze River Delta. Stabilizer chemistry transitions—calcium-zinc replacing tin-based formulations—create single-source vulnerability during REACH compliance deadlines. Distribution runs through manufacturer-operated direct-to-installer portals in North American metropolitan markets and traditional distributor networks for European specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SPC flooring has become a vertical-integration race where backward control over resin compounding and stabilizer chemistry determines margin durability. Players capturing upstream supply positions insulate against petrochemical volatility while locking formulation compliance ahead of regulatory sunset dates.
For Market Incumbents: Hedge margin erosion through captive calcium-zinc stabilizer production and acoustic underlayment lamination line investments. Engineered hardwood substitution in premium residential segments and REACH-driven reformulation costs threaten non-integrated producers. Prioritize CE marking certification acceleration to compress 8-14 month approval timelines for new core formulations. For New Entrants and Emerging Players: Capture specification share in India's underpenetrated healthcare and education infrastructure where infection-control-rated sheet products face limited domestic competition. Delhi-NCR and Mumbai metropolitan corridors offer penetrable procurement openings against established export brands. Lead with glue-down sheet manufacturing investments targeting BIS certification compliance as the go-to-market anchor. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale fabricators with existing CE marking documentation and established direct-to-installer platform economics in Florida and Texas metropolitan markets. Long-term viability hinges on recyclability technology investments ahead of Germany's extended producer responsibility fee escalations. Watch ECHA SVHC candidate list expansion velocity as the inflection indicator for reformulation cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Mohawk Industries and Shaw Industries Group control PVC quality across North American plants. |
| Acoustic Underlayment Lamination Capacity | Tarkett's CE-marked performance documentation captures architect-specified commercial projects. |
| Direct-to-Installer Platform Expansion | Manufacturer portals in Florida and Texas compress traditional distributor markups for contractors. |
| Calcium-Zinc Stabilizer Transition | ECHA's SVHC candidate list forces tin-based phase-outs ahead of regulatory sunset dates. |
| Sensor-Embedded Flooring Development | Subscription-based predictive maintenance software creates recurring revenue beyond installation. |
Research Approach
Trade association filings, customs export records, and construction products certification databases formed the secondary backbone for this analysis. Primary interviews with resin compounding plant managers, multi-family housing renovation contractors, architect specification leads, and flooring distributor procurement heads combined with bottom-up and top-down triangulation across these sources. Secondary validation drew from MIIT industrial standards documentation, ECHA SVHC candidate list updates, and EPA TSCA Title VI compliance disclosures.
Bottom-up modeling aggregated unit economics across product format, installation method, and end-user segments; top-down verification cross-checked against regional construction spending and renovation cycle data. Segmentation dimensions included product type, application channel, installation technology, and specification authority level across the projection horizon. CAGRs derived from trajectory analysis of residential renovation spending patterns, REACH compliance cost absorption, and calcium carbonate supply clustering effects.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ethylene feedstock volatility and ECHA regulatory expansion timelines. Forecasts reflect documented assumptions around renovation spending durability and stabilizer chemistry transition costs. PVC resin price spikes, extended producer responsibility fee escalations, and engineered hardwood substitution velocity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
PCR Laminates Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Carbon Aerogel Market
Composite Materials
Isostatic Graphite Market
Composite Materials
Lithium Battery Copper Aluminum Composite Pole Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
Global Composite Materials Market
Composite Materials
Tow Prepreg Market
Composite Materials
Scrim Reinforced Films Market
Composite Materials
FRP Tanks Market
Composite Materials
Carbon Composites Market
Composite Materials
Malaysia High Pressure Laminate Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
North America Molded FRP Grating Market
Composite Materials
Global Carbon Felt and Graphite Felt Market