
 Composite Quartz Stone Market | 2026-2036
Composite Quartz Stone Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Quartz Stone Market Insights
Vietnam is reconfiguring regional supply dynamics through new quartz slab manufacturing clusters near Hanoi and Ho Chi Minh City. Cosentino leverages vertically integrated Breton technology to sustain premium positioning across European and North American distribution channels. Caesarstone anchors Australasian demand while competing aggressively in North American kitchen specification markets. Cambria specializes in domestic U.S. production with captive resin supply, differentiating on American-sourced content claims.
Composite quartz stone combines engineered mineral filler, predominantly crystalline silica, with polymer resin binders under vacuum vibration compression to produce non-porous surfaces exceeding Mohs hardness 7. These materials serve high-wear residential and commercial interior applications requiring stain resistance, thermal stability, and design consistency absent in natural granite or marble. Countertops command the largest value share within product type segmentation, though slabs are gaining specification traction among fabricators seeking custom dimension flexibility. The residential end user segment leads volume absorption, while hospitality applications are expanding fastest as hotel chains standardize on quartz for bathroom vanities and reception surfaces.
EPA guidelines on crystalline silica exposure and REACH substance restrictions in Europe are reshaping resin formulation requirements and fabrication shop ventilation mandates. The U.S. Occupational Safety and Health Administration enforces permissible exposure limits that elevate compliance costs for dry-cutting operations. Stakeholders must monitor evolving silica classification debates and resin substitution research to anticipate product reformulation timelines and regional manufacturing relocation patterns.
Market Dynamics
Silica exposure regulations are compressing fabrication economics and forcing resin reformulation across manufacturing footprints, while residential renovation cycles in mature economies pull volume toward premium surface specifications.
Growth Catalysts
- EPA permissible exposure limits:Fabricators investing in wet-cutting infrastructure capture market share from competitors facing OSHA enforcement actions.
- Hotel chain standardization:Hospitality procurement mandates for quartz bathroom vanities and reception surfaces accelerate specification velocity across mid-tier properties.
- Crystalline silica substitution research:Polymer resin binders incorporating alternative mineral fillers reduce compliance burden while maintaining Mohs hardness thresholds.
Market Restraints
- Resin input cost volatility:Petroleum-derived unsaturated polyester prices fluctuate with crude oil benchmarks, compressing margin predictability for slab producers.
- Vietnam manufacturing concentration:New quartz slab clusters near Hanoi and Ho Chi Minh City create geographic supply risk if regional logistics corridors face disruption.
- REACH substance restrictions:ECHA classification debates on crystalline silica content force premature product reformulation ahead of scientific consensus.
Strategic Opportunities
- India middle-class housing expansion:Urban residential construction in Mumbai and Bangalore generates unmet demand for stain-resistant kitchen surfaces.
- EU Green Deal procurement incentives:Public building specifications favor low-VOC engineered stone, creating preferential access for compliant manufacturers.
- Digital templating convergence:CNC fabrication software integrated with 3D measurement tools reduces waste and accelerates custom dimension turnaround.
Industry Challenges
- Fabricator skill shortages:Wet-cutting certification requirements outpace vocational training program output in North American metropolitan markets.
- Legacy equipment retrofit costs:Dry-cutting shops face capital intensity for ventilation and dust collection upgrades to meet OSHA permissible exposure limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Quartz Stone Market |
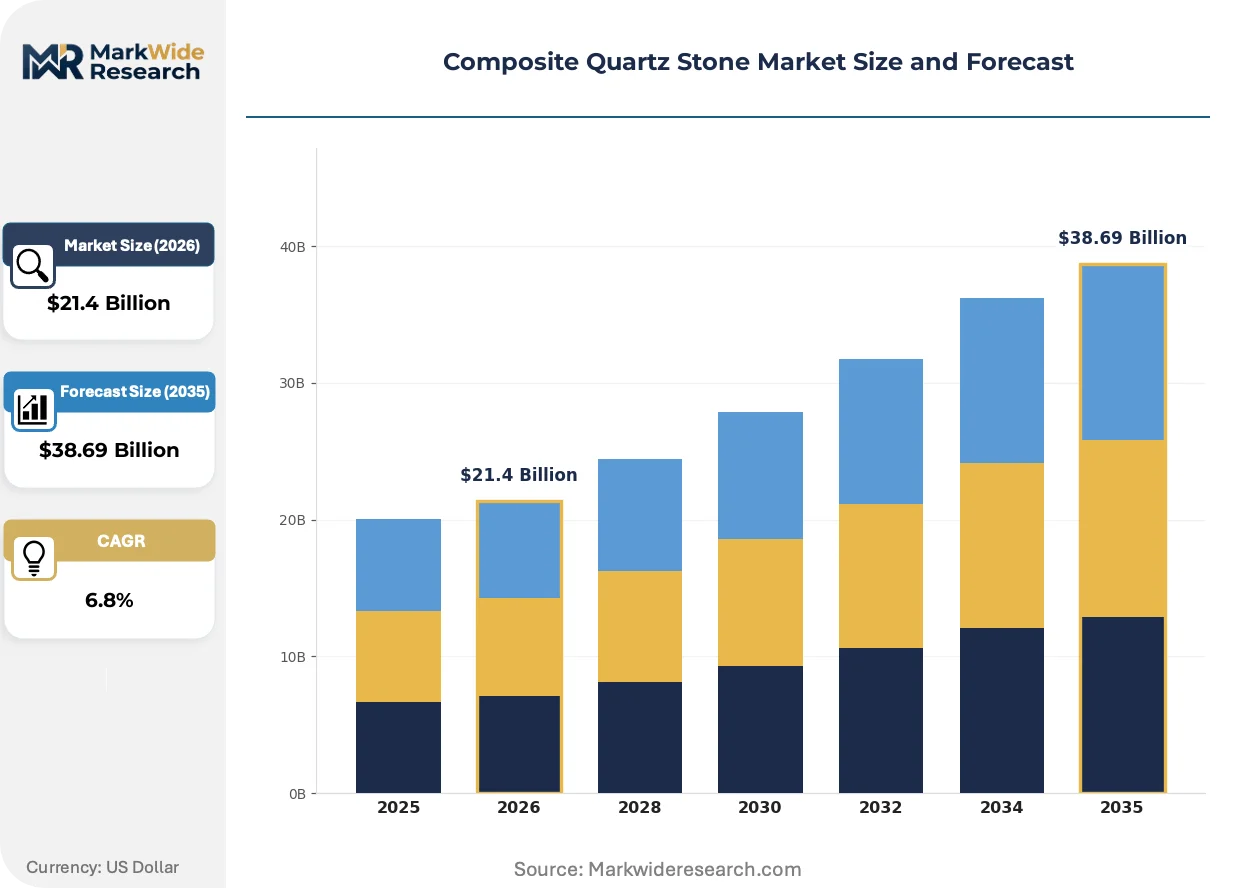
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $38.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slabs, Tiles, Countertops, Sheets End User: Residential, Commercial, Hospitality, Industrial Application: Kitchen, Bathroom, Flooring, Walls Distribution Channel: Online, Retail, Direct Sales, Partnerships |
| Companies Covered | Cosentino, Caesarstone, Cambria, MSI Surfaces, LG Hausys, DuPont, Wilsonart, Vicostone, Compac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Quartz Stone Market Trends and Innovations
Digital fabrication workflows and regulatory pressure on silica content are compressing traditional supply chain configurations while opening specification pathways for reformulated surface materials.
Automated CNC templating systems are digitizing measurement-to-installation workflows for residential kitchen renovations. Custom fabricators in North American metropolitan markets adopt cloud-connected cutting equipment to reduce dimensional error and material waste. This compression of specification-to-fabrication timelines is digitizing competitive differentiation away from inventory scale toward software-enabled precision.
REACH substance restriction proposals from ECHA are forcing resin formulation pivots across European manufacturing footprints. Crystalline silica content thresholds under regulatory review threaten existing product portfolios and accelerate alternative filler research. Slab producers serving EU specification markets face compressed reformulation timelines while awaiting final classification determinations.
Direct-to-fabricator distribution models are displacing traditional distributor intermediaries in North American supply chains. Large kitchen and bath retailers consolidate procurement through captive fabrication networks, compressing independent distributor margins. This channel consolidation is most visible in Texas and Florida metropolitan corridors where volume concentration enables bypass economics.
Composite Quartz Stone Market Segmentation
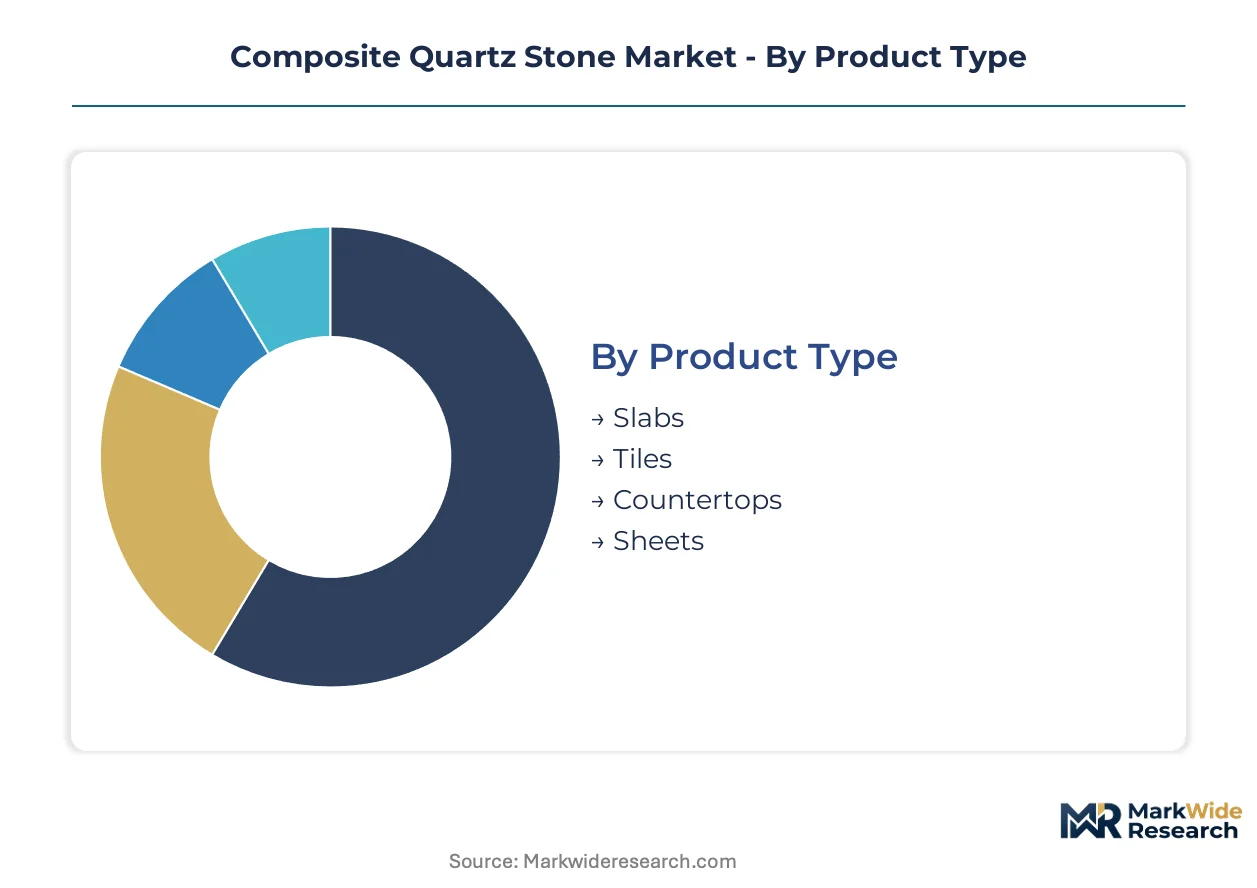
Segmentation in the composite quartz stone market reveals distinct specification cycles across product forms and end-use environments. Fabricators, contractors, and homeowners each drive different velocity requirements that reshape inventory and production priorities.
Product Type:
Cycle times compress from months for standard slabs to weeks for templated countertops, with tiles and sheets occupying intermediate velocity tiers based on project scale and customization depth.
- Slabs:Large-format engineered stone panels measuring 3000x1400mm or larger, supplied to fabrication shops for custom cutting and edge profiling. Demand concentrates in North American metropolitan renovation corridors where homeowners prioritize dimensional flexibility over prefabricated solutions, though OSHA wet-cutting mandates elevate shop-level compliance costs.
- Countertops:Finished surface assemblies cut to specification with integrated sinks, backsplashes, and edge treatments. Residential kitchen renovations across Texas and Florida metropolitan areas pull volume toward templated solutions, with digital measurement tools compressing specification-to-installation timelines.
- Tiles:Standardized rectangular or square units for flooring and wall cladding applications. Commercial hospitality specifications in Vietnam manufacturing clusters favor large-format tiles for bathroom and reception surface standardization.
- Sheets:Thin-profile panels for vertical surfacing and specialty architectural applications. Healthcare and laboratory end-uses in European markets specify sheets for wall cladding requiring seamless hygiene performance.
Slabs dominate installed base. Countertops are where expansion concentrates.
End User:
Cost tiers separate specification authority, with residential homeowners prioritizing aesthetic differentiation, commercial developers emphasizing lifecycle economics, and hospitality procurement standardizing on brand consistency.
- Residential:Single-family and multi-family homeowners specifying kitchen and bathroom surfaces through renovation contractors or direct retail procurement. North American metropolitan markets absorb the largest volume share as aging housing stock drives replacement cycles.
- Hospitality:Hotel chains and resort operators mandating quartz surfaces for bathroom vanities, reception desks, and guest room wet bars. Mid-tier property renovation programs across India and Vietnam accelerate specification velocity through centralized procurement.
- Commercial:Office developers, retail operators, and institutional clients specifying high-traffic surfaces for lobbies, restrooms, and food service areas. EU Green Deal procurement incentives in public building segments favor low-VOC engineered stone compliance.
- Industrial:Manufacturing facilities, laboratories, and cleanroom environments requiring chemical-resistant, non-porous work surfaces. Specialized resin formulations serve semiconductor and pharmaceutical production contexts with enhanced thermal stability.
Residential commands volume leadership. Hospitality climbs the fastest.
Application:
Volume concentration varies by wear intensity and moisture exposure, with kitchen surfaces absorbing the heaviest mechanical stress and bathroom applications demanding superior stain resistance.
- Kitchen:Primary food preparation surfaces requiring Mohs hardness above 7, thermal shock resistance, and impermeability to acidic spills. North American and European renovation markets specify engineered stone as the dominant replacement for natural granite.
- Bathroom:Vanity tops, shower surrounds, and tub decks exposed to constant moisture and cosmetic chemical contact. Hotel chain standardization programs across Asia-Pacific markets accelerate volume absorption for bathroom applications.
- Flooring:High-traffic pedestrian surfaces in commercial and hospitality environments. Large-format tile specifications favor engineered stone for lobbies and corridors requiring design consistency across extensive surface areas.
- Walls:Vertical cladding for feature walls, backsplashes, and full-height surfacing. Healthcare and institutional specifications in European markets prioritize seamless sheet applications for hygiene-critical environments.
Kitchen anchors revenue concentration. Bathroom gains specification momentum.
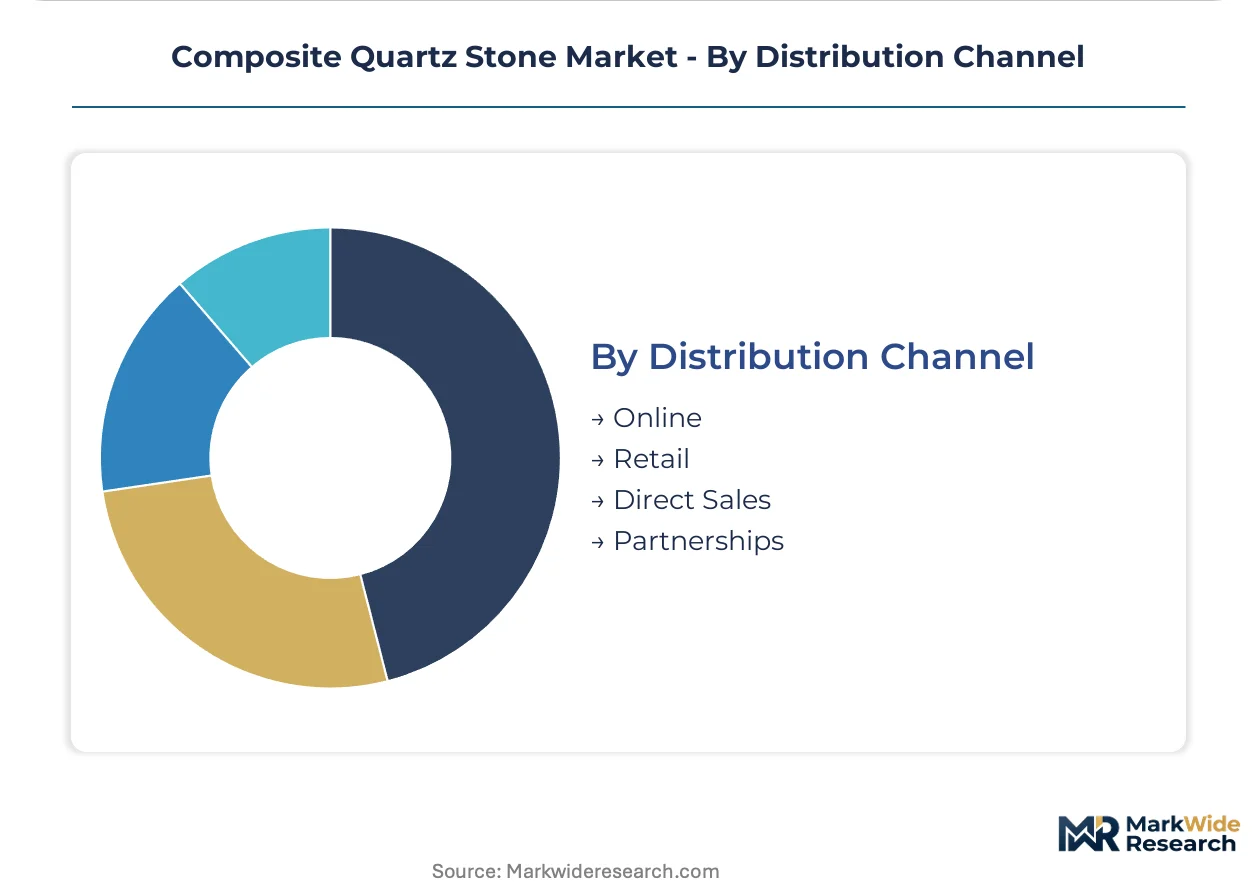
Distribution Channel:
Customer type determines channel preference, with homeowners fragmenting across retail and online research while contractors and developers consolidate through direct procurement relationships.
- Retail:Big-box home improvement stores and specialty kitchen and bath showrooms serving homeowner-directed renovation projects. Texas and Florida metropolitan corridors exhibit the most visible channel consolidation as volume concentration enables captive fabrication networks.
- Direct Sales:Manufacturer-to-fabricator or manufacturer-to-developer relationships bypassing distributor intermediaries. Large kitchen and bath retailers consolidate procurement through captive fabrication networks, compressing independent distributor margins.
- Online:Digital templating platforms and e-commerce portals for sample ordering, visualization tools, and contractor matching. Cloud-connected cutting equipment adoption among North American fabricators enables remote specification workflows.
- Partnerships:Strategic alliances between slab producers, cabinet manufacturers, and home builders for new construction specification. Production homebuilders in India and Vietnam middle-class housing markets bundle engineered stone surfaces with kitchen packages.
Retail holds the broadest footprint. Direct sales capture margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing footprints for engineered stone surfaces concentrate in Vietnam, China, and India as resin-formulation expertise migrates toward lower-cost production basins. Fabrication economics now hinge on proximity to wet-cutting infrastructure and compliance-ready logistics corridors.
United States
Residential kitchen renovations in Texas and Florida metropolitan corridors absorb the largest volume of imported slabs for custom templating. OSHA enforces permissible exposure limits for crystalline silica that elevate compliance costs for dry-cutting fabrication shops. Domestic producers with captive resin supply chains in Minnesota and North Carolina differentiate on American-sourced content claims.
China
Urban middle-class housing expansion in Shanghai and Shenzhen generates specification pull for large-format engineered stone surfaces. MIIT oversees industrial standards for polymer resin binders used in construction materials. Manufacturing clusters in Guangdong Province export prefabricated countertops to North American and European distribution channels.
Vietnam
New quartz slab production facilities near Hanoi and Ho Chi Minh City are reconfiguring regional supply dynamics for Asia-Pacific markets. The country's national environmental regulator monitors volatile organic compound emissions from resin-curing operations. Export-oriented manufacturing parks in Binh Duong Province serve hospitality procurement mandates from hotel chains across Southeast Asia.
Germany
Commercial construction specifications in Berlin and Munich favor low-VOC engineered stone compliant with EU Green Deal procurement incentives. ECHA classification debates on crystalline silica content force premature product reformulation timelines. Fabrication shops in North Rhine-Westphalia invest in wet-cutting infrastructure to meet REACH substance restriction requirements.
India
Middle-class housing stock expansion in Mumbai and Bangalore drives unmet demand for stain-resistant kitchen surfaces. BIS certification requirements for construction materials shape import substitution patterns for domestic slab producers. Manufacturing investments in Gujarat and Tamil Nadu target captive supply for residential real estate developers bundling engineered stone with kitchen packages.
Composite Quartz Stone Market Competitive Landscape
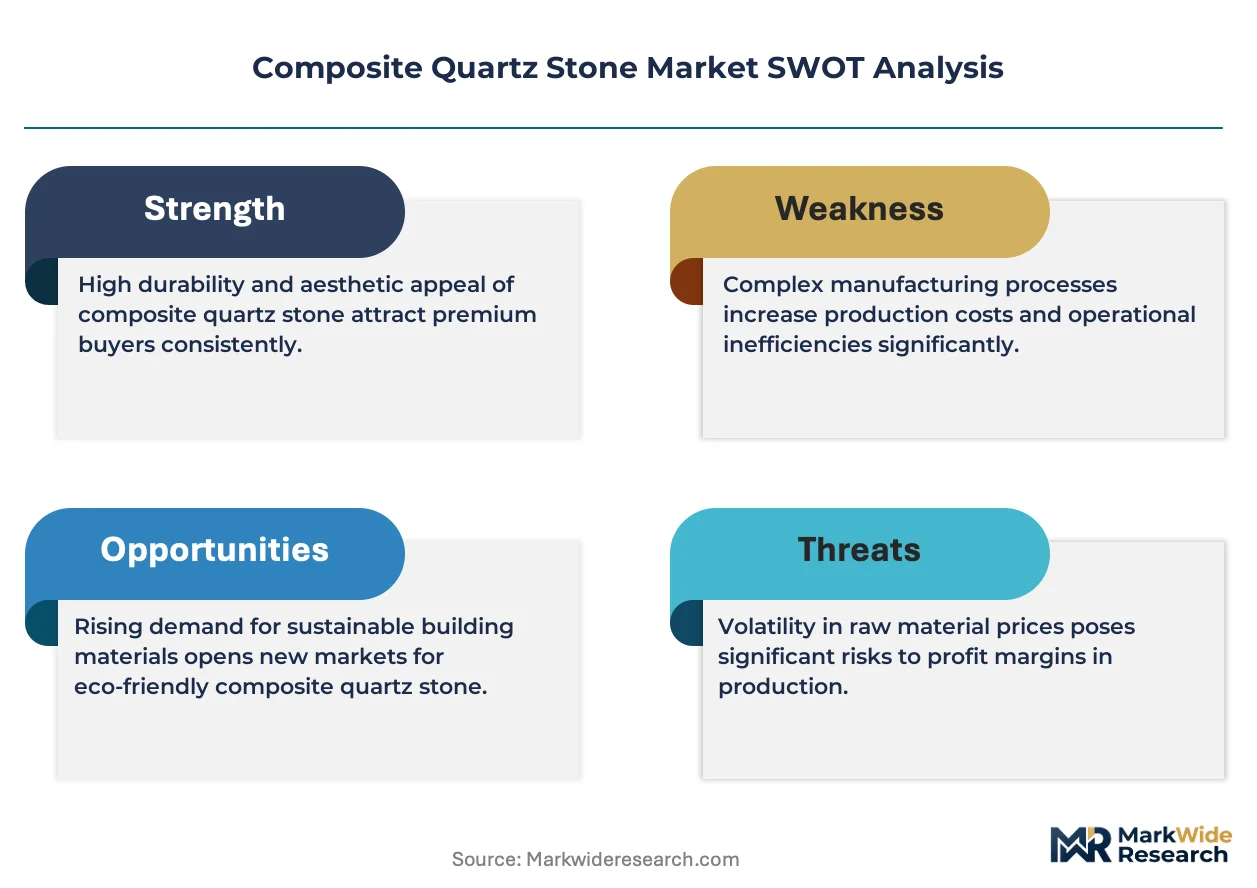
Vertically integrated multinationals and specialized regional fabricators split the market between premium brand positioning and cost-driven volume capture. Consolidation pressure intensifies as wet-cutting compliance costs eliminate smaller fabrication shops. Three archetypes dominate: technology licensors with proprietary Breton systems, domestic producers with captive resin supply, and Asian manufacturers with scale-driven export models. Competitive moves center on backward integration into resin production and geographic expansion through direct-to-fabricator distribution channels.
Within the premium-tier vector, Cosentino exemplifies technology-licensing dominance through vertically controlled Breton manufacturing systems. Caesarstone occupies a position bridging Australasian market anchoring with North American specification aggression. Cambria represents domestic U.S. production archetype with Minnesota-based captive resin operations. These three entities illustrate how competitive positioning stratifies across technology control, geographic focus, and supply chain configuration rather than product differentiation alone.
| Leading Market Players |
|---|
| Cosentino |
| Caesarstone |
| Cambria |
| MSI Surfaces |
| LG Hausys |
| DuPont |
| Wilsonart |
| Vicostone |
| Compac |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific container freight corridors from Shanghai to Long Beach transmit petroleum-derived resin cost volatility directly into slab landed costs, compressing margin buffers for North American fabricators while amplifying price spreads between premium Breton-system products and standard-grade alternatives.
Pricing Analysis
EPA permissible exposure limits dictate the pricing tier structure by elevating wet-cutting infrastructure costs for fabrication shops. Three-tier pricing structure across premium, standard, and economy levels separates Cosentino's vertically integrated offerings from regional Vietnamese producers and commoditized Chinese exports. Cost compression in economy tiers is intensifying because resin input prices fluctuate with crude oil benchmarks. Residential renovation contractors exhibit highest price sensitivity, while hospitality procurement managers prioritize lifecycle economics over unit cost.
Supply Chain Analysis
Export-control restrictions on Breton vacuum-vibration-compression technology limit proprietary system deployment to licensed partners, constraining premium-tier supply expansion. Manufacturing concentrates in Vietnam, China, and India as resin-formulation expertise migrates toward lower-cost basins. Raw material flows draw from petroleum-derived unsaturated polyester, crystalline silica filler, and pigment additives. Single-source vulnerability concentrates in Vietnamese logistics corridors serving Asia-Pacific hospitality mandates. Distribution runs through direct-to-fabricator channels displacing traditional distributor intermediaries in North American metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital templating platforms are reconfiguring this market toward platform-economics dynamics, where software-enabled precision and cloud-connected fabrication workflows create winner-take-most concentration among fabricators with integrated measurement-to-installation capabilities.
For Market Incumbents: Pre-empt resin formulation disruption by accelerating crystalline silica substitution research ahead of ECHA classification finalization. Secure captive supply of alternative mineral fillers through backward integration into mining partnerships or long-term offtake agreements with Indian and Vietnamese raw material processors.
For New Entrants and Emerging Players: Pursue underpenetrated hospitality procurement in India and Vietnam middle-class housing corridors, where hotel chain standardization programs generate specification velocity without entrenched incumbent relationships. Lead with digital templating partnerships that compress specification-to-installation timelines for mid-tier property developers.
For Investors and Strategic Acquirers: Carve-out targets emerge from distressed North American fabrication shops facing OSHA wet-cutting compliance retrofits. Long-term viability hinges on software-enabled precision capabilities rather than inventory scale. Monitor ECHA crystalline silica classification determinations as inflection indicator for product reformulation timelines and manufacturing relocation patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| Resin Formulation Pivot | Alternative mineral filler research reduces ECHA compliance burden while maintaining Mohs hardness thresholds. |
| Wet-Cutting Infrastructure Deployment | Fabricators investing in OSHA-compliant ventilation capture market share from enforcement-vulnerable competitors. |
| Direct-to-Fabricator Distribution | Channel bypass economics compress independent distributor margins in Texas and Florida metropolitan corridors. |
| Digital Templating Integration | Cloud-connected CNC equipment reduces dimensional error and accelerates custom dimension turnaround. |
| Captive Resin Supply Integration | Domestic producers with in-house polymer operations differentiate on American-sourced content claims. |
Research Methodology
The analysis maps slab production clusters, countertop fabrication networks, and hospitality procurement channels, each validated through plant managers at Vietnamese and Chinese manufacturing facilities, procurement leads at North American kitchen and bath retailers, technical R&D directors at resin formulation specialists, and distribution channel partners across Asia-Pacific logistics corridors. Secondary sources include customs and trade data from Vietnam's General Department of Customs, MIIT industrial standards filings, EPA enforcement action records, and SEC 10-K disclosures from publicly traded surface material producers. Bottom-up volume triangulation from fabrication shop throughput intersects with top-down market sizing from construction spending data.
Assumptions held fixed include REACH substance restriction timelines, OSHA permissible exposure limit enforcement intensity, and petroleum price correlation with resin input costs. Variables tested across the projection horizon encompass ECHA crystalline silica classification scenarios, wet-cutting infrastructure adoption rates, and digital templating platform penetration. Segmentation dimensions modeled include product form, end-user vertical, application environment, and distribution channel configuration. CAGRs derive from regression analysis against housing renovation cycle indicators and commercial construction permit data.
Macroeconomic conditions sit as an overlay; deviation in residential construction spending, crude oil benchmarks, or trans-Pacific freight rates would shift the trajectory. Material shifts in ECHA regulatory classification or OSHA enforcement posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
Global FRP Vessels Market
Composite Materials
Reinforced Carbon-Carbon Composite Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
Graphite Carbon Raiser Market
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
Epoxy Composite Market
Composite Materials
High Performance Composites Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Copper Clad Laminates Market
Composite Materials
Global Carbon Fiber Resin Market
Composite Materials
Decorative High-Pressure Laminates Market
Composite Materials
GCC Decorative Laminates Market
Composite Materials
Aramid Fiber Reinforced Polymer Market
Composite Materials
Global Honeycomb Core Materials Market