
 Advanced Carbon Materials Market | 2026-2036
Advanced Carbon Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Carbon Materials Market Analysis
The capital-intensity divergence between pilot-scale graphene producers and multi-thousand-ton carbon fiber manufacturers is collapsing as equipment costs fall and process yields improve. Toray Industries anchors the carbon fiber segment through backward integration into precursor chemicals and proprietary oxidation ovens. SGL Carbon competes in specialty graphite and carbon composites for automotive OEMs through dedicated European production assets. Hexcel Corporation dominates aerospace-qualified prepreg formulations, leveraging AS9100 certification barriers to sustain premium positioning.
Advanced carbon materials encompass engineered allotropes and composites including carbon fibers exceeding 3,000 MPa tensile strength, graphene monolayers with 5,300 W/mK thermal conductivity, and activated carbons with surface areas above 1,500 m²/g, manufactured through controlled pyrolysis, chemical vapor deposition, or electrochemical exfoliation to deliver lightweight structural reinforcement, electrical conductivity, or molecular adsorption. Carbon fibers leads product type demand due to mature qualification pathways in aerospace primary structures, while graphene posts the fastest application growth in thermal interface materials for electronics. Energy storage applications concentrate margin pools in battery anode materials, where electrochemical reduction processes command pricing premiums over thermal oxidation routes.
EPA emissions standards under the Clean Air Act constrain pitch-based carbon production in U.S. manufacturing zones, while REACH registration requirements in Europe govern graphene nanoparticle commercialization and worker exposure limits. FAA certification protocols for composite airframe structures create decade-long qualification barriers that lock in incumbent suppliers. Stakeholders must monitor evolving ISO standards for nanomaterial characterization and decide between early compliance investments versus reactive adaptation as regulatory thresholds tighten.
Market Dynamics
The EU Green Deal's industrial decarbonization mandates are compressing qualification timelines for carbon fiber composites in aerospace primary structures while collapsing capital barriers between pilot-scale graphene and mass-market carbon fiber production.
Growth Catalysts
- Aerospace Lightweighting Mandates:Boeing and Airbus procurement specifications now require carbon fiber-reinforced polymer content exceeding 50% in new airframe programs, locking in decade-long supply agreements with qualified prepreg formulators.
- REACH Nanomaterial Registration:ECHA's streamlined graphene nanoparticle authorization pathway accelerates commercial deployment in thermal interface materials for European electronics manufacturing.
- Ruhr Valley Processing Cluster:Germany's concentrated carbon precursor and oxidation capacity creates captive supply chains for automotive OEMs transitioning body-in-white structures from aluminum to carbon composites.
Market Restraints
- Acrylonitrile Price Volatility:Polyacrylonitrile precursor costs swing with propylene feedstock markets, compressing carbon fiber margins during petrochemical upcycles.
- Pitch-Based Carbon Emissions Constraints:EPA Clean Air Act standards limit coal-tar pitch carbon production in U.S. manufacturing zones, forcing capacity relocation or abatement investments.
- Aluminum-Lithium Substitution:Arconic and Constellium's third-generation Al-Li alloys retain cost advantages in narrow-body fuselage applications where carbon fiber qualification remains incomplete.
Strategic Opportunities
- Solid-State Battery Anode Materials:Silicon-carbon composite architectures demand high-purity synthetic graphite with tailored porosity, opening premium pricing tiers for electrochemical reduction processes.
- India PLI Scheme for Advanced Materials:Production-linked incentives for electric vehicle manufacturing create localized demand for carbon fiber components in two-wheeler and passenger vehicle structural reinforcement.
- AI-Driven Process Control Convergence:Machine learning optimization of oxidation oven temperature profiles reduces energy intensity and yield loss in carbon fiber production lines.
Industry Challenges
- FAA Composite Certification Timelines:AS9100-qualified prepreg formulations require 8-12 year airframe integration cycles, freezing out new entrants regardless of technical performance.
- Pyrolysis Technician Skill Scarcity:Controlled carbonization expertise concentrates among aging workforces in Japan and Germany, constraining greenfield capacity expansion.
- ISO Nanomaterial Characterization Gaps:Absence of standardized graphene layer-count measurement protocols creates specification disputes between suppliers and electronics thermal management buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Carbon Materials Market |
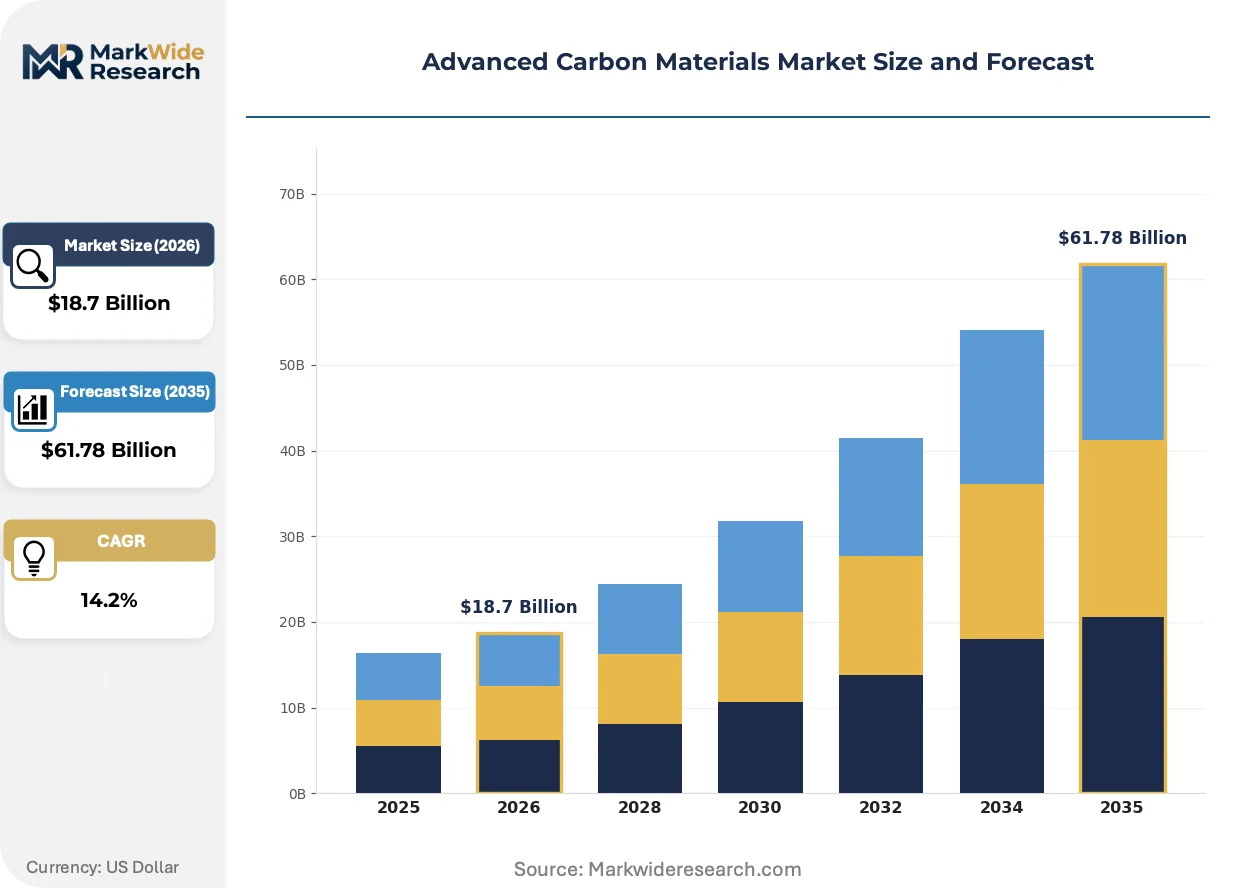
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphene, Carbon Nanotubes, Activated Carbon, Carbon Fibers Application: Composite Materials, Energy Storage, Coatings, Electronics End User: Aerospace, Automotive OEMs, Electronics Manufacturers, Construction Technology: CVD, Thermal Oxidation, Electrochemical Reduction, Chemical Vapor Deposition |
| Companies Covered | Toray Industries, SGL Carbon, Toyo Tanso, Showa Denko, Arkema Group, GrafTech International, Global Graphene Group, Hexcel Corporation, Mitsubishi Rayon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Carbon Materials Market Emerging Trajectories
Graphene-enhanced thermal interface materials are compressing heat dissipation bottlenecks in high-performance computing while regulatory frameworks crystallize around nanomaterial safety protocols and aerospace qualification pathways.
Thermal interface material formulations incorporating few-layer graphene are displacing conventional metal-based thermal pads in data center GPU cooling assemblies. Hyperscale operators including Google and Microsoft now specify graphene-polymer composites for direct-die attachment in AI training clusters. The technology is miniaturizing thermal management subsystems, enabling denser chip packaging without liquid cooling infrastructure.
REACH registration requirements for graphene nanoparticles now mandate full toxicological dossiers before commercial volumes exceed one ton annually. ECHA's 2023 updated guidance on nanomaterial worker exposure limits forces manufacturers to implement closed-loop production or localized exhaust ventilation. Specialty chemical distributors in the Netherlands and Belgium are consolidating graphene sourcing to reduce compliance fragmentation across EU member states.
Automotive OEMs now contract directly with carbon fiber precursor producers rather than through tiered composite suppliers, compressing margin pools at intermediate prepreg stages. BMW and Mercedes-Benz procurement teams have established technical liaison offices in Germany's Ruhr Valley to secure oxidation oven capacity allocations. This channel consolidation is most advanced in European electric vehicle platform programs where body-in-white carbon content targets exceed 15% by mass.
Advanced Carbon Materials Market Segmentation
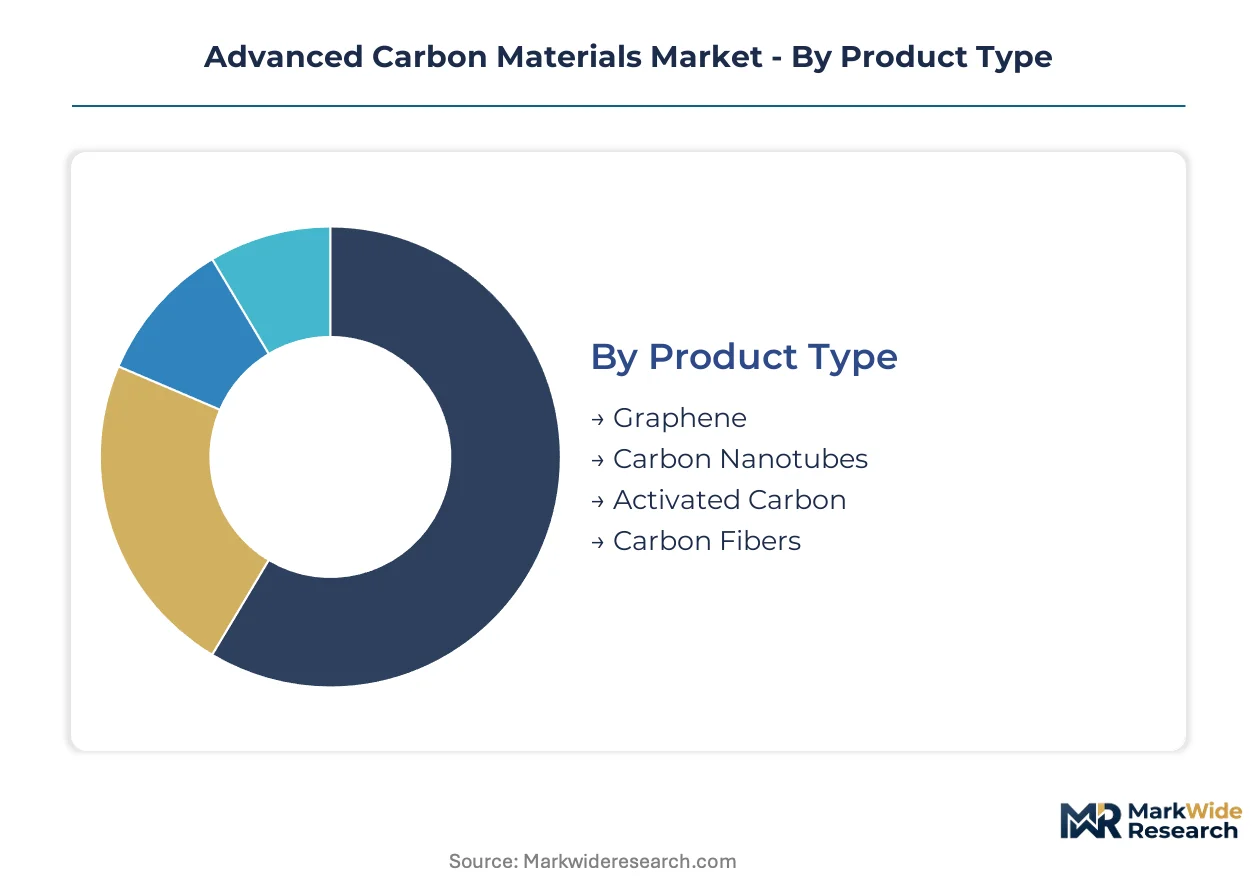
Margin concentration in advanced carbon materials splits between aerospace-qualified carbon fiber prepreg and battery-grade synthetic graphite anodes. The report dissects four critical dimensions—product type, application, end user, and manufacturing technology—to map where pricing power concentrates and where commoditization threatens returns.
Product Type:
Premium pricing tiers concentrate in materials with decade-long qualification barriers and electrochemical performance specifications that thermal processes cannot replicate.
- Carbon Fibers:PAN-based and pitch-based variants exceeding 3,000 MPa tensile strength dominate aerospace primary structures. Boeing and Airbus procurement specifications now mandate CFRP content above 50% in new airframe programs, locking in supply agreements with AS9100-certified prepreg formulators.
- Graphene:Few-layer and monolayer structures with 5,300 W/mK thermal conductivity command pricing premiums in thermal interface materials for AI training clusters. Google and Microsoft now specify graphene-polymer composites for direct-die GPU attachment, compressing heat dissipation bottlenecks without liquid cooling infrastructure.
- Activated Carbon:Surface areas above 1,500 m²/g serve molecular adsorption in water purification and air filtration systems.
- Carbon Nanotubes:Single-walled and multi-walled architectures reinforce polymer matrices for automotive lightweighting applications.
Carbon Fibers holds installed capacity across Japan and Germany. Graphene is rotating up the share rankings as thermal management specifications tighten in hyperscale data centers.
Application:
Volume scale diverges sharply from value capture, with energy storage applications concentrating margin pools in electrochemically reduced materials while composite materials dominate tonnage.
- Energy Storage:Silicon-carbon composite anodes for solid-state batteries demand high-purity synthetic graphite with tailored porosity. Electrochemical reduction processes command pricing premiums over thermal oxidation routes, opening premium tiers for producers with closed-loop purification capabilities.
- Composite Materials:CFRP primary structures in aerospace and automotive body-in-white applications represent the largest volume consumption category. BMW and Mercedes-Benz procurement teams have established technical liaison offices in Germany's Ruhr Valley to secure oxidation oven capacity allocations directly from precursor producers.
- Electronics:Thermal interface materials and conductive films leverage graphene's in-plane thermal conductivity for chip packaging applications.
- Coatings:Corrosion-resistant and anti-fouling carbon-based surface treatments serve marine and industrial infrastructure markets.
Composite Materials anchors current volume demand. Energy Storage is climbing the fastest as battery OEMs qualify next-generation anode architectures.
End User:
Procurement authority is consolidating upstream, with automotive and aerospace OEMs bypassing tiered composite suppliers to contract directly with precursor and oxidation capacity holders.
- Aerospace:Boeing and Airbus airframe programs require 8-12 year qualification cycles for new prepreg formulations, freezing out new entrants regardless of technical performance. FAA certification protocols for composite primary structures sustain incumbent supplier margins through AS9100 barriers.
- Automotive OEMs:European electric vehicle platforms target body-in-white carbon content exceeding 15% by mass, driving direct procurement relationships with Ruhr Valley oxidation oven operators. India's PLI scheme for electric vehicle manufacturing is creating localized demand for carbon fiber structural reinforcement in two-wheeler and passenger vehicle segments.
- Electronics Manufacturers:Hyperscale data center operators and semiconductor packaging houses specify graphene thermal interface materials for high-performance computing cooling subsystems.
- Construction:CFRP reinforcement bars and prestressing cables serve bridge and building retrofit applications where corrosion resistance outweighs first-cost premiums.
Aerospace maintains the deepest qualification moats. Automotive OEMs is gaining share fastest as electric vehicle lightweighting mandates compress adoption timelines.
Technology:
Process yield and energy intensity separate commodity producers from premium-positioned suppliers, with machine learning optimization now penetrating oxidation oven control systems.
- Thermal Oxidation:Stabilization and carbonization of PAN precursor in controlled atmosphere ovens produces aerospace-grade carbon fiber. AI-driven temperature profile optimization is reducing energy intensity and yield loss in production lines operated by Toray Industries and SGL Carbon.
- Electrochemical Reduction:Purification of synthetic graphite for battery anodes achieves higher crystallinity and lower impurity levels than thermal routes. This process commands pricing premiums in solid-state battery supply chains where silicon-carbon composite architectures demand tailored porosity.
- Chemical Vapor Deposition:Gas-phase synthesis of carbon nanotubes and graphene films enables controlled layer count and defect density for electronics applications.
- Electrochemical Exfoliation:Liquid-phase production of few-layer graphene from graphite feedstock serves thermal interface material formulators requiring scalable, cost-competitive supply.
Thermal Oxidation holds the largest installed capacity base. Electrochemical Reduction is rotating up the share rankings as battery OEMs prioritize anode purity specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German oxidation oven operators command 40-60% pricing premiums over Asian carbon fiber producers, while Indian PLI subsidies compress landed costs for European automotive OEMs sourcing from South Asian contract manufacturers.
Germany
BMW and Mercedes-Benz procurement teams have established technical liaison offices in the Ruhr Valley to secure precursor chemical allocations for electric vehicle body-in-white programs. The EU Green Deal's industrial decarbonization mandates accelerate aluminum-to-carbon composite substitution in automotive platforms. Oxidation oven capacity concentrates in North Rhine-Westphalia, where SGL Carbon operates dedicated production assets serving captive automotive supply chains.
United States
Boeing and Airbus airframe programs drive demand for AS9100-certified prepreg formulations in Washington and South Carolina manufacturing corridors. EPA Clean Air Act emissions standards constrain pitch-based carbon production, forcing capacity relocation or abatement investments in Ohio and Alabama. The Pacific Northwest hosts concentrated aerospace composite engineering talent pools that sustain decade-long qualification cycles.
Japan
Toray Industries anchors global PAN-based carbon fiber supply through backward integration into precursor chemicals and proprietary oxidation oven technology. METI's carbon recycling roadmap prioritizes sustainable aviation fuel co-processing with composite waste streams. Chubu and Kanto regions concentrate pyrolysis technician expertise among aging workforces that constrain greenfield capacity expansion timelines.
China
MIIT's dual carbon goals accelerate domestic carbon fiber capacity expansion for wind turbine blade and electric vehicle applications, displacing Japanese import dependence. GB standards for composite material characterization remain less stringent than FAA or EASA protocols, enabling faster commercial deployment in non-aerospace segments. Yangtze River Delta chemical parks attract electrochemical reduction investments for battery-grade synthetic graphite production.
India
The PLI scheme for electric vehicle manufacturing creates localized demand for carbon fiber structural reinforcement in two-wheeler and passenger vehicle segments. BIS certification requirements for composite automotive components remain under development, creating regulatory uncertainty for European precursor suppliers. Gujarat and Maharashtra industrial corridors host emerging carbon composite fabrication clusters serving export-oriented automotive tier-1 suppliers.
Advanced Carbon Materials Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with Japanese and German incumbents dominating aerospace-qualified formulations while Chinese and Indian entrants capture scale-driven segments through process automation. The vendor base splits into three strategic tiers: vertically integrated chemical conglomerates with precursor-to-fiber control, specialized composite formulators with AS9100 certification moats, and emerging graphene producers with electrochemical exfoliation capabilities. Competitive moves concentrate on backward integration into acrylonitrile supply and AI-driven oxidation oven optimization to compress energy intensity.
Within the integrated chemical tier, Toray Industries and Mitsubishi Rayon exemplify backward control over precursor supply chains. Among specialized formulators, Hexcel Corporation occupies a position defined by aerospace qualification barriers. SGL Carbon anchors European automotive composite supply through Ruhr Valley production assets. These three company structures represent distinct competitive positions: conglomerate diversification, certification-locked premium positioning, and regional cluster captivity.
| Leading Market Players |
|---|
| Toray Industries |
| SGL Carbon |
| Toyo Tanso |
| Showa Denko |
| Arkema Group |
| GrafTech International |
| Global Graphene Group |
| Hexcel Corporation |
| Mitsubishi Rayon |
| Others |
Supply Flow & Price Mechanics
FAA certification protocols for composite airframe structures gate both supply qualification timelines and price differentiation simultaneously, with AS9100-certified prepreg formulators commanding sustained premiums over uncertified competitors regardless of technical parity. This regulatory moat compresses buyer negotiation leverage while locking in decade-long offtake agreements that insulate incumbent margins from commodity carbon fiber pricing cycles.
Pricing Analysis
Configured-to-order pricing for aerospace-qualified carbon fiber prepreg commands substantial premiums over standard-grade industrial carbon fiber, with AS9100 certification tier and volume scale serving as the primary price differentiation drivers. Pricing pressure stems from automotive OEMs consolidating procurement authority upstream to precursor producers, bypassing intermediate composite suppliers. Battery-grade synthetic graphite buyers exhibit highest price sensitivity due to electrochemical purity specification commoditization, while aerospace procurement teams remain least sensitive given qualification lock-in.
Supply Chain Analysis
Strategic stockpiling of polyacrylonitrile precursor dominates over just-in-time approaches, reflecting acrylonitrile price volatility exposure and multi-month oxidation oven scheduling constraints. Supply concentrates in Japan, Germany, and China, with raw material dependencies centering on propylene feedstocks, coal-tar pitch, and high-purity graphite ore. Single-source vulnerability in aerospace-qualified prepreg formulators creates structural risk, as distribution runs through direct OEM contracts rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating upstream as automotive and aerospace OEMs bypass tiered suppliers to contract directly with precursor and oxidation capacity holders, fragmenting intermediate composite formulators while consolidating margin capture at raw material and finished component stages.
For Market Incumbents: Fortify backward integration into acrylonitrile supply chains to insulate margins from petrochemical feedstock volatility. Expand oxidation oven capacity in Germany's Ruhr Valley to capture automotive OEM direct procurement shifts. Lock in long-term offtake agreements with Boeing and Airbus before Al-Li alloy substitution advances in narrow-body programs. For New Entrants and Emerging Players: Differentiate on electrochemical reduction capabilities for battery-grade synthetic graphite, where purity specifications remain less commoditized than thermal oxidation routes. Target India's PLI-subsidized electric vehicle manufacturing corridor for carbon fiber structural reinforcement in two-wheeler segments. Pursue technical partnership strategies with Ruhr Valley oxidation operators rather than greenfield capacity builds. For Investors and Strategic Acquirers: ECHA's REACH nanomaterial registration milestones reshape the acquisition landscape, favoring targets with existing toxicological dossiers over early-stage graphene producers facing compliance cliffs. Five-to-ten year viability hinges on certification asset durability rather than process technology alone. Watch for FAA composite qualification timeline compression as the inflection signal indicating incumbent moat erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemicals | Toray Industries' acrylonitrile supply control insulates margins from propylene volatility. |
| AS9100 Certification Investment | Hexcel Corporation's aerospace qualification barriers sustain decade-long supply agreement premiums. |
| Ruhr Valley Oxidation Capacity Expansion | SGL Carbon's dedicated automotive assets capture BMW and Mercedes-Benz direct procurement shifts. |
| Electrochemical Reduction Process Scale-Up | Solid-state battery anode purity specifications command pricing premiums over thermal oxidation routes. |
| AI-Driven Oxidation Oven Optimization | Machine learning temperature profiling reduces energy intensity and yield loss in carbon fiber production. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the advanced carbon materials value chain, including aerospace procurement directors, automotive lightweighting engineers, battery anode material scientists, and carbon fiber plant managers. Secondary validation drew from FAA certification databases, ECHA REACH registration filings, SEC 10-K disclosures from listed producers, and customs trade flow records. Bottom-up capacity assessments and top-down demand modeling were triangulated to cross-verify volume estimates.
Across the analysis window, forecasts employed segment-level modeling across product type, application, end user, and manufacturing technology dimensions, with additional stratification by certification tier and regional production hub. CAGRs were derived from fitted growth curves applied to qualified demand segments, incorporating electrochemical reduction yield improvements, oxidation oven energy efficiency gains, and aerospace program delivery schedules as industry-specific inputs.
Material uncertainties — propylene feedstock price spikes, REACH nanomaterial exposure limit revisions, and FAA composite qualification timeline accelerations — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained aerospace demand and automotive electrification penetration. Revision becomes warranted when aluminum-lithium alloy substitution rates in narrow-body fuselage applications cross technical performance parity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Corundum Market
Advanced Materials
North America Plasma Powder Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Wood Foam Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
Global Electrochromic Materials Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
Boron Nitride Market
Advanced Materials
North America Next Generation Anode Materials Market
Advanced Materials
North America Advanced Phase Change Materials Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Extracellular Matrix Proteins Market
Advanced Materials
Lab-Grown Rough Diamond Market