
 Glass Fiber Reinforced Plastic (GFRP) Market | 2026-2036
Glass Fiber Reinforced Plastic (GFRP) Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Fiber Reinforced Plastic (GFRP) Market Foresight
High-performance aerospace-grade specification tiers is collapsing into broader industrial accessibility as manufacturing scales. Owens Corning leverages its integrated glass melting and fiber forming operations to command premium supply chains. Jushi Group Co., Ltd. anchors its position through massive Chinese production bases serving Asian wind energy and construction markets. Chongqing Polycomp International Corporation differentiates via specialized roving products for high-strength thermoplastic applications.
Glass Fiber Reinforced Plastic comprises thermoset or thermoplastic polymer matrices reinforced with continuous or discontinuous glass fibers, typically achieving tensile strengths of 300-600 MPa depending on fiber orientation and resin chemistry. Its primary purpose is to deliver metallic strength-to-weight ratios at substantially lower densities for structural load-bearing applications. Continuous roving dominates volume flows into wind turbine blade manufacturing where filament winding and pultrusion processes consume the largest tonnage. Sheet molding compound holds mature positions in automotive body panel applications with stable margins, while prepregs represent the fastest-growing form segment as aerospace and sports equipment manufacturers demand precision-engineered resin-to-fiber ratios.
The European Chemicals Agency enforces REACH substance restrictions on styrene emissions from unsaturated polyester resins, compelling reformulation investments across GFRP compounders. China's Ministry of Ecology and Environment applies dual carbon goals to glass melting furnace operations, elevating energy compliance costs for domestic fiber producers. The US Environmental Protection Agency monitors air toxics standards at fiberglass manufacturing facilities under Clean Air Act provisions. Stakeholders must track evolving recyclability mandates for thermoset composites as circular economy frameworks extend material recovery obligations.
Market Dynamics
Aircraft manufacturers are compressing design cycles by expanding thermoplastic GFRP adoption in primary fuselage structures, forcing resin compounders to retool formulation lines for higher-temperature processing windows.
Growth Catalysts
- Wind energy capacity mandates:China's 14th Five-Year Plan targets massive offshore wind installations, pulling continuous roving volumes into turbine blade manufacturing corridors along the eastern coast.
- REACH chemical reformulation:ECHA's tightening styrene emission restrictions on unsaturated polyester resins are accelerating low-VOC epoxy system development across European automotive panel suppliers.
- Thermoplastic pultrusion maturation:High-speed automated processing is collapsing cycle times for structural profiles, enabling GFRP penetration into mass-transit interior components previously served by aluminum extrusions.
Market Restraints
- Borosilicate glass input volatility:Energy-intensive melting furnace operations face escalating natural gas and electricity costs, compressing margin structures for fiber producers in Germany and China.
- Recyclability dead-end for thermosets:Cross-linked polymer matrices resist mechanical or chemical reclamation, exposing manufacturers to pending extended producer responsibility frameworks in France and the Netherlands.
- Carbon fiber substitution pressure:Aerospace tier-one suppliers are qualifying T800-grade carbon prepregs for secondary structures where GFRP previously held cost advantages.
Strategic Opportunities
- India infrastructure buildout:National highway expansion and smart city initiatives are creating specification pathways for GFRP rebar and utility poles in corrosion-prone coastal states.
- EU Green Deal circularity mandates:Upcoming construction product regulations will favor recyclable thermoplastic composites over thermoset alternatives in public procurement frameworks.
- Digital twin integration:Convergence of finite element analysis with automated fiber placement is enabling mass-customization of structural preforms for medical imaging equipment housings.
Industry Challenges
- Multi-physics simulation expertise gap:Composite design engineers capable of integrating anisotropic material models with crash and fatigue analysis command premium compensation, constraining workforce scaling.
- Aerospace certification timelines:FAA and EASA qualification protocols for new resin systems extend 18-36 months, freezing formulation innovation cycles for tier-two suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Fiber Reinforced Plastic (GFRP) Market |
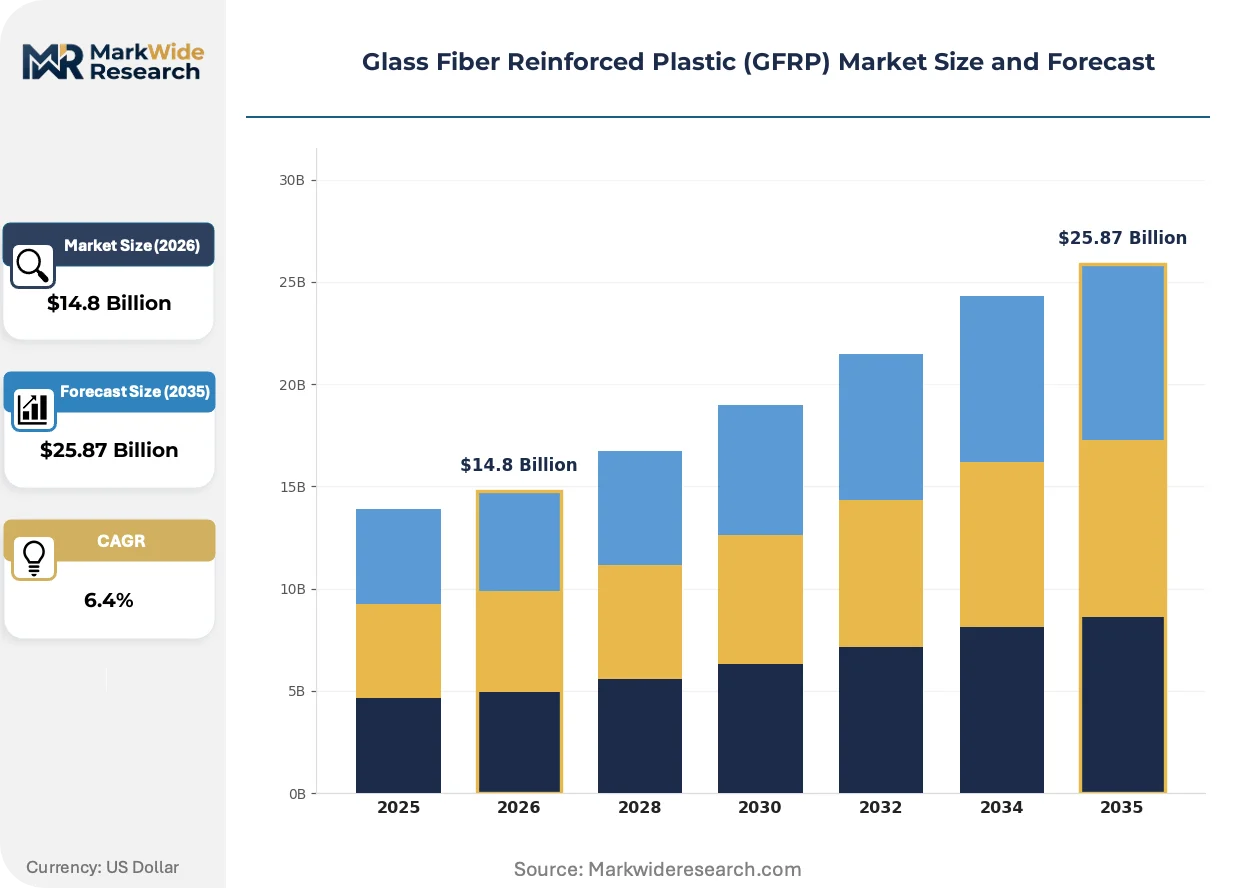
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
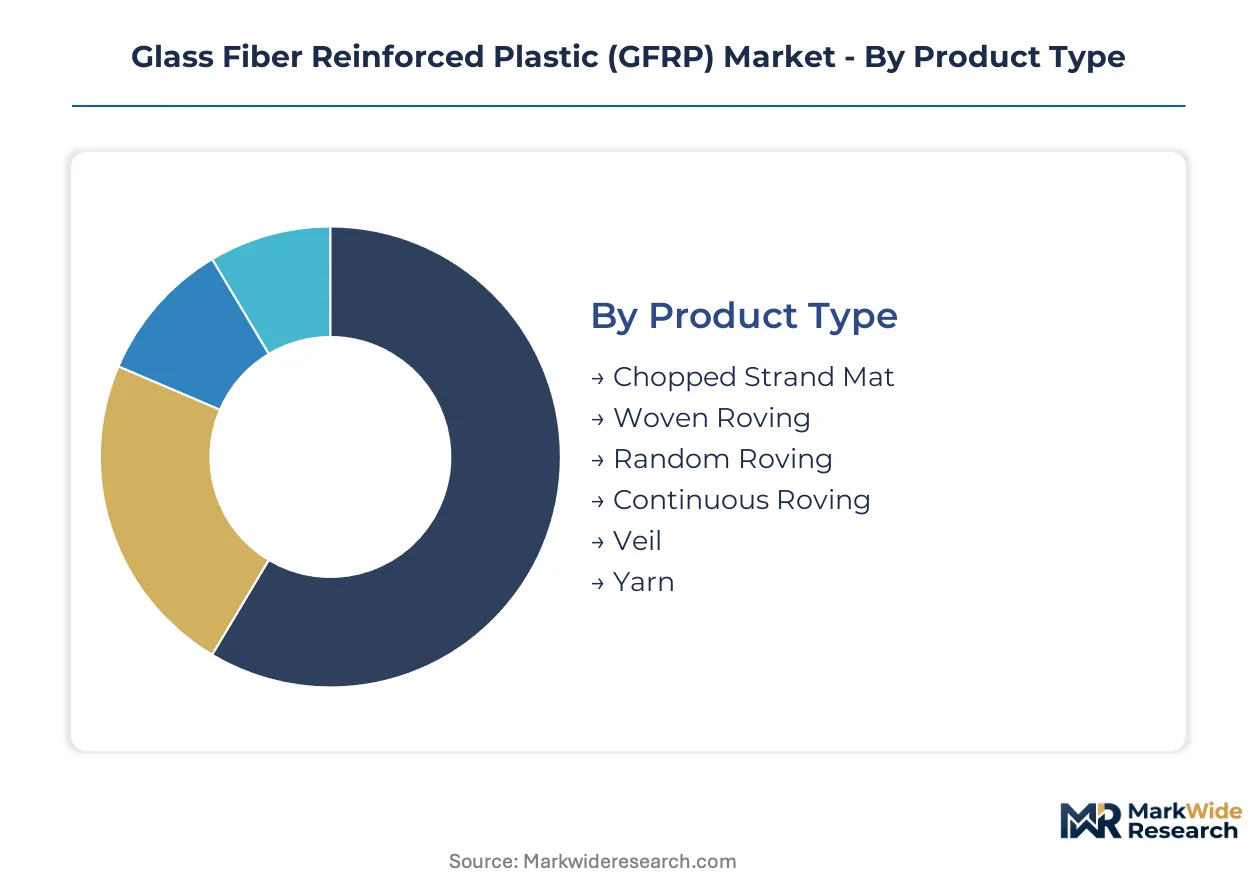
| Segmentation | Product Type: Chopped Strand Mat, Woven Roving, Random Roving, Continuous Roving, Veil, Yarn Form: Sheet Molding Compound, Bulk Molding Compound, Pultruded Rods, Prepregs, Filament Winding Application: Construction Components, Electrical Insulation, Marine Components, Aerospace Structures, Sports Equipment End User Industry: Shipbuilders, Aircraft Manufacturers, Building Contractors, Electronics Manufacturers, Recreation Goods |
| Companies Covered | Owens Corning, Jushi Group Co., Ltd., Chongqing Polycomp International Corporation, Johns Manville Corporation, Saint-Gobain Vetrotex, PPG Industries, Inc., Nippon Electric Glass Co., Ltd., Taishan Fiberglass Inc., AGY Holding Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Fiber Reinforced Plastic (GFRP) Market Shifts & Advancements
Thermoplastic matrix systems are actively restructuring competitive positioning by collapsing the traditional performance-cost tradeoff that favored thermosets in high-volume applications.
Continuous fiber-reinforced thermoplastic (CFRTP) tapes are supplanting sheet molding compounds in automotive underbody shields and seat structures. BMW and Volkswagen have qualified unidirectional tape laying processes for A-pillar reinforcements, compressing part consolidation ratios from multiple steel stampings to single molded assemblies. This technology is supplanting incumbent compression molding lines across European tier-one interiors suppliers.
ECHA's 2023 update to REACH Annex XVII restrictions on styrene monomer content is forcing polyester resin reformulation across marine and construction sectors. Compounders are migrating to vinyl ester and epoxy hybrid systems, elevating raw material costs but opening compliance pathways for Scandinavian boat builders. Wind blade manufacturers in Denmark and Spain are absorbing the transition costs to maintain CE marking access.
Specification consolidation among wind turbine OEMs is compressing supplier qualification cycles from 24 months to 12 months. Vestas and Siemens Gamesa are unifying blade material standards across offshore and onshore platforms, displacing fragmented regional sourcing with global frame agreements. This pattern is most visible in China's Jiangsu and Guangdong manufacturing clusters where blade fabricators are consolidating resin purchasing through centralized procurement platforms.
Glass Fiber Reinforced Plastic (GFRP) Market Segmentation
Channel configuration varies dramatically across GFRP product categories. Continuous roving flows predominantly through direct mill contracts to wind blade manufacturers, while sheet molding compound distributes via regional compounder networks to automotive tier suppliers.
Product Type:
Channel-mix patterns separate commodity mat products from specialized roving grades, with distribution intensity inversely correlated to technical specification tiers.
- Continuous Roving:Unidirectional glass fiber bundles wound onto cylindrical packages, typically E-glass or E-CR glass formulations with 1200-4800 tex linear densities. Demand concentrates in China's Jiangsu and Guangdong provinces where Vestas and Siemens Gamesa blade fabricators pull volumes through centralized procurement platforms facing dual carbon compliance costs from MEE regulations.
- Chopped Strand Mat:Randomly oriented glass fiber strands held together by powder or emulsion binders, engineered for hand lay-up and spray-up processes in marine hull construction. Boat builders in Denmark and Spain absorb reformulation costs to maintain CE marking access under ECHA's tightening styrene restrictions.
- Woven Roving:Bidirectional fabric construction offering balanced in-plane strength properties for large-surface laminate applications.
- Random Roving:Discontinuous fiber format optimized for bulk molding compound feedstock in automotive compression molding.
- Veil:Thin surfacing tissue providing resin-rich surface layers for corrosion barrier applications in chemical storage tanks.
- Yarn:Twisted fiber bundles serving textile reinforcement and specialty electrical insulation sleeving markets.
Continuous Roving dominates installed base. Chopped Strand Mat is where expansion concentrates as marine sector reformulation completes.
Form:
Cost tier stratification separates high-volume compression molding compounds from precision-engineered prepreg systems commanding formulation premiums.
- Prepregs:Fiber reinforcement pre-impregnated with catalyzed resin systems achieving controlled fiber volume fractions of 55-65%. Aerospace tier-one suppliers at Boeing and Airbus facilities qualify these materials through 18-36 month FAA and EASA certification protocols, freezing innovation cycles for tier-two resin compounders.
- Sheet Molding Compound:Glass-reinforced polyester or vinyl ester dough formulated for matched-die compression molding, historically serving automotive body panels. BMW and Volkswagen have displaced SMC volumes in A-pillar reinforcements with unidirectional tape laying processes, compressing part consolidation ratios from multiple steel stampings to single molded assemblies.
- Bulk Molding Compound:Extrusion-compounded dough for injection and transfer molding of complex electrical component housings.
- Pultruded Rods:Continuous profiles manufactured through heated die forming for structural rebar and utility pole applications.
- Filament Winding:Automated fiber placement process consuming the largest tonnage of continuous roving into pressure vessels and pipe structures.
Sheet Molding Compound dominates installed base. Prepregs represent the fastest-growing trajectory as aerospace specification tightens.
Application:
Volume concentration tracks infrastructure investment cycles, with margin distribution favoring aerospace qualification premiums over construction commodity flows.
- Construction Components:GFRP rebar, grating, and structural profiles replacing steel in corrosion-prone environments. India's national highway expansion and smart city initiatives in coastal states create specification pathways for these materials, with procurement shifting toward centralized government frameworks.
- Aerospace Structures:Primary and secondary airframe components exploiting thermoplastic GFRP's damage tolerance and recyclability advantages. Aircraft manufacturers compress design cycles by expanding adoption in fuselage structures, forcing resin compounders to retool formulation lines for higher-temperature processing windows.
- Electrical Insulation:Transformer housings, switchgear components, and printed circuit board substrates leveraging dielectric properties.
- Marine Components:Hull laminates, deck structures, and superstructure elements facing REACH-driven resin system migration.
- Sports Equipment:Bicycle frames, hockey sticks, and protective gear utilizing tailored stiffness-to-weight ratios.
Construction Components dominates installed base. Aerospace Structures is where expansion concentrates as thermoplastic qualification accelerates.
End User Industry:
Customer-type segmentation reveals procurement pattern divergence between project-based contractors and integrated manufacturing operations.
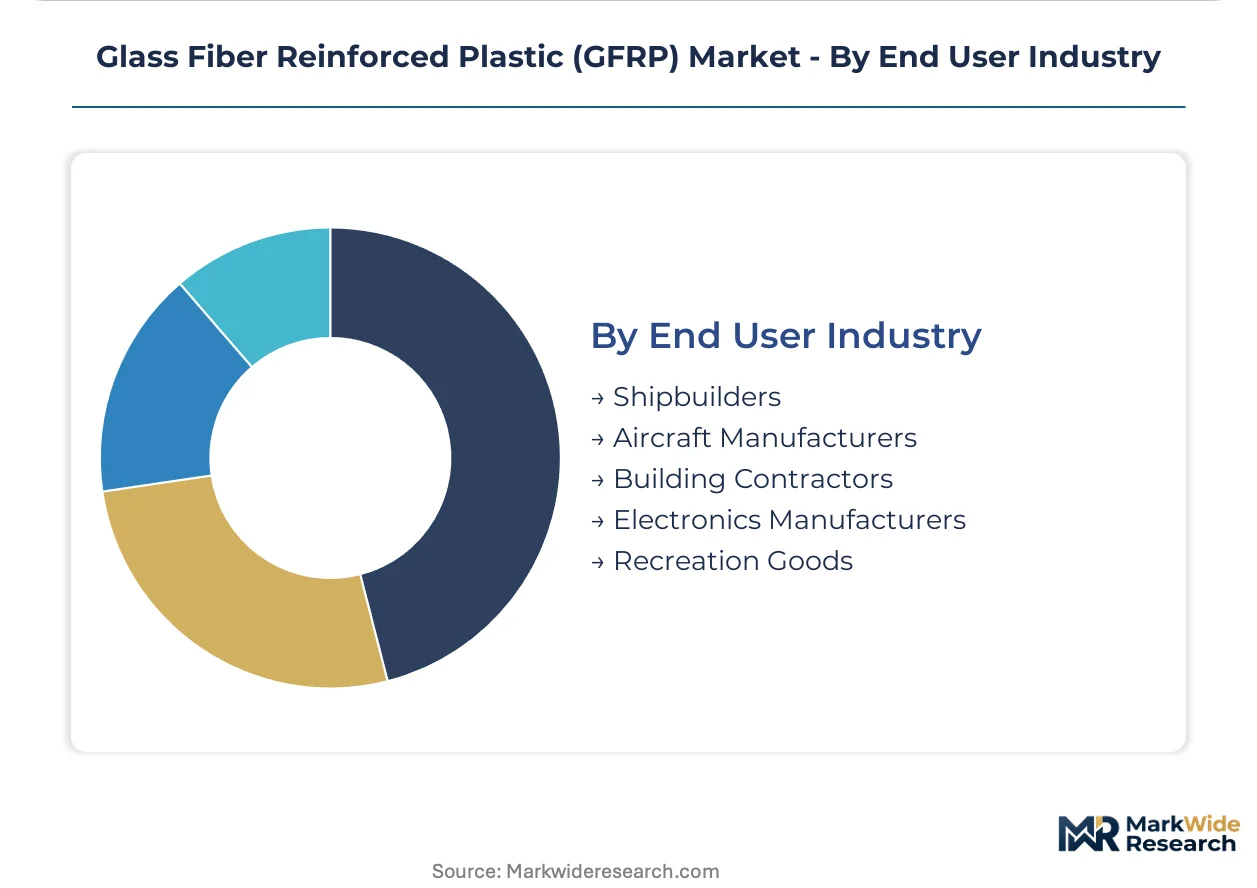
- Aircraft Manufacturers:Boeing, Airbus, and Bombardier operations specifying materials through qualified supplier lists with embedded regulatory compliance documentation. These buyers compress supplier qualification cycles from 24 months to 12 months through unified material standards across offshore and onshore platforms.
- Building Contractors:Project-based procurement of structural profiles and rebar for infrastructure applications, with sourcing fragmented across regional distributors. India's coastal state governments increasingly specify GFRP alternatives for corrosion resistance in bridge decks and marine pilings.
- Shipbuilders:Scandinavian and Mediterranean boat builders migrating resin systems to maintain CE marking access under ECHA restrictions.
- Electronics Manufacturers:Insulation component buyers with stable demand for bulk molding compound in switchgear housings.
- Recreation Goods:Sports equipment brands with seasonal demand patterns and rapid product cycle turnover.
Building Contractors dominates installed base. Aircraft Manufacturers is where expansion concentrates as thermoplastic adoption penetrates primary structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping regional supply configurations as energy costs and regulatory stringency diverge across major producing economies. Countries with integrated glass melting and fiber forming capabilities command pricing leverage in cross-border trade, while import-dependent markets absorb freight premiums and currency volatility.
China
Offshore wind installations under the 14th Five-Year Plan are pulling continuous roving volumes into Jiangsu and Guangdong manufacturing clusters. The Ministry of Ecology and Environment applies dual carbon goals to glass melting furnace operations, elevating energy compliance costs for domestic fiber producers. Vestas and Siemens Gamesa blade fabricators in these coastal provinces are consolidating resin purchasing through centralized procurement platforms.
United States
Aerospace tier-one suppliers at Boeing facilities are qualifying thermoplastic GFRP systems for primary fuselage structures, compressing supplier innovation cycles. The Environmental Protection Agency monitors air toxics standards at fiberglass manufacturing facilities under Clean Air Act provisions. Production gravity concentrates in Texas and Ohio corridor operations serving automotive and construction end-uses.
Germany
BMW and Volkswagen have displaced sheet molding compound volumes in A-pillar reinforcements with unidirectional tape laying processes, altering demand composition. ECHA's REACH Annex XVII restrictions on styrene monomer content are forcing polyester resin reformulation across automotive and marine sectors. Bavarian and North Rhine-Westphalian compounders are absorbing transition costs to maintain CE marking access.
India
National highway expansion and smart city initiatives in coastal states are creating specification pathways for GFRP rebar and utility poles in corrosion-prone environments. The Bureau of Indian Standards is developing construction product regulations favoring corrosion-resistant infrastructure materials. Procurement is shifting toward centralized government frameworks in Maharashtra and Gujarat manufacturing corridors.
Denmark
Wind blade manufacturers are absorbing ECHA-driven resin system transition costs to maintain CE marking access for offshore turbine exports. The country's national environmental regulator enforces stringent emission controls on composite manufacturing operations. Copenhagen-area blade engineering centers are unifying material standards across offshore and onshore platforms.
Glass Fiber Reinforced Plastic (GFRP) Market Competitive Landscape
Concentration sits with integrated glass-to-fiber producers commanding captive raw material access and premium supply chain positioning. Market structure exhibits tiered segmentation between multinational chemical conglomerates with full portfolio coverage and specialized fiber producers focused on roving and mat formulations. Two dominant strategic archetypes prevail: integrated glass melting operations leveraging upstream energy and mineral control, and downstream compounders specializing in resin system formulation for qualification-intensive end-uses. Competitive moves center on capacity expansion in low-energy-cost geographies and strategic partnerships with wind turbine OEMs for multi-year offtake agreements.
Among integrated glass-to-fiber producers, Owens Corning exemplifies the archetype of captive mineral and energy integration, while Jushi Group Co., Ltd. represents scale-driven positioning through massive Chinese production bases. Chongqing Polycomp International Corporation occupies a specialized tier focused on high-strength thermoplastic applications, differentiating via roving product engineering rather than commodity volume.
| Leading Market Players |
|---|
| Owens Corning |
| Jushi Group Co., Ltd. |
| Chongqing Polycomp International Corporation |
| Johns Manville Corporation |
| Saint-Gobain Vetrotex |
| PPG Industries, Inc. |
| Nippon Electric Glass Co., Ltd. |
| Taishan Fiberglass Inc. |
| AGY Holding Corp. |
| Others |
Supply & Pricing Matrix
Thermoplastic matrix substitution for thermoset systems in automotive A-pillar reinforcements is simultaneously shifting supply geography toward German tape-laying facilities and compressing pricing premiums previously commanded by compression-molded compounds. This substitution dynamic concentrates procurement leverage with BMW and Volkswagen engineering centers while fragmenting legacy SMC compounder margins across Bavarian and North Rhine-Westphalian supplier networks.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that stratifies across aerospace certification tier, volume scale, and geographic delivery cost. Price differentiation separates FAA-qualified prepreg systems from industrial-grade roving bundles, with wind turbine OEMs extracting maximum leverage through centralized procurement platforms in Jiangsu and Guangdong. Pricing pressure stems from ECHA-driven resin reformulation costs that polyester compounders absorb to maintain CE marking access. Tier-one automotive suppliers demonstrate lowest price sensitivity due to qualification lock-in, while regional construction contractors face acute margin compression.
Supply Chain Analysis
Inventory cycles for continuous roving extend 8-12 weeks at Vestas and Siemens Gamesa blade fabricators, reflecting just-in-time filament winding schedules tied to offshore wind installation windows. Geographic supply concentrates in China, the United States, and Germany, with Jiangsu province and Texas corridor operations commanding integrated glass melting advantages. Raw material dependencies rest on borosilicate glass batch formulations, natural gas furnace energy, and epoxy-vinyl ester hybrid resin systems. Single-source vulnerability runs through Chinese E-glass roving capacity controlled by state-affiliated producers. Distribution feeds from direct mill contracts into wind blade manufacturing corridors, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic GFRP penetration in primary aerospace structures signals early-cycle expansion, with Boeing and Airbus qualification protocols creating a 12-24 month adoption runway before volume inflection.
For Market Incumbents: Consolidate backward integration into borosilicate glass batch supply and captive furnace energy contracts to defend margin position against natural gas volatility in German and Chinese production bases. Lock multi-year offtake agreements with Vestas and Siemens Gamesa before supplier qualification cycles compress further. Prioritize thermoplastic roving R&D to offset carbon fiber substitution pressure in secondary aerospace structures. For New Entrants and Emerging Players: Anchor in India's coastal state infrastructure buildout where Bureau of Indian Standards corrosion-resistant specifications create first-mover specification pathways for GFRP rebar and utility pole applications. Target Maharashtra and Gujarat government procurement frameworks with localized compounding partnerships. Pursue a technical certification-first go-to-market angle leveraging BIS compliance documentation as competitive barrier. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors integrated glass-to-fiber producers with captive mineral access and multi-regional furnace footprints. Long-term viability hinges on thermoplastic matrix transition completion and circular economy regulatory alignment. Acquisition focus should center on mid-cap compounders with aerospace qualification pipelines. Monitor EASA and FAA certification timeline compression as inflection signal for formulation innovation unlock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Supply | Captive glass batch control insulates Owens Corning and Jushi from mineral price volatility. |
| Thermoplastic Pultrusion Capacity Buildout | High-speed automated lines enable BMW-qualified A-pillar reinforcement at compressed cycle times. |
| Long-term Supply Agreement with Wind OEMs | Centralized procurement platforms in Jiangsu favor frame agreements over spot purchasing. |
| REACH Compliance Reformulation Investment | Vinyl ester migration maintains CE marking access for Scandinavian boat builders under ECHA restrictions. |
| Joint Venture in Indian Coastal Manufacturing | Maharashtra and Gujarat corridors position entrants for Bureau of Indian Standards infrastructure specifications. |
Research Methodology
Operator-level perspectives from plant managers at integrated glass melting facilities, procurement leads at wind turbine OEMs, distribution channel partners serving automotive tier suppliers, and technical R&D directors at resin compounders anchored the qualitative base. Primary interview findings triangulated against secondary validation from customs and trade data, SEC 10-K filings of listed fiber producers, ACC and Cefic chemical industry reports, and FAA airworthiness directive databases. Bottom-up volume estimates from end-use application consumption patterns reconciled with top-down market sizing across product type, form, and regional production hub segmentation.
Sensitivity analysis tested forecast robustness across the projection horizon by varying thermoplastic adoption rates in aerospace applications, ECHA enforcement stringency on styrene emissions, and Chinese dual carbon compliance cost pass-through assumptions. The analytical framework modeled continuous roving, chopped strand mat, woven roving, prepregs, sheet molding compound, and bulk molding compound segments across construction, aerospace, electrical insulation, marine, and sports equipment end-uses. CAGRs derived from regression analysis of historical capacity utilization, OEM procurement pipeline visibility, and regulatory timeline acceleration. Forecast inputs incorporated filament winding process throughput rates and pultrusion line automation adoption curves as industry-specific volume drivers.
Decision-makers should treat outputs as directional under assumptions of sustained wind energy capacity mandates, REACH Annex XVII enforcement continuity, and thermoplastic qualification timeline compression; material deviation in aerospace certification protocols or Chinese environmental policy enforcement would warrant model refresh. Specific risk factors include carbon fiber substitution acceleration in secondary structures, extended producer responsibility framework implementation in France and the Netherlands, and energy cost volatility at German glass melting operations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
PCR Laminates Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Molded Underfill Material Market
Composite Materials
Fiber Reinforced Composite Tapes Market
Composite Materials
Fiber Reinforced Polymer (FRP) Panels and Sheets Market
Composite Materials
Polycarbonate Composites Market
Composite Materials
Global Coupling Agents Market
Composite Materials
Wall Cladding Materials Market
Composite Materials
Pcb Laminate Materials Market
Composite Materials
Asia Pacific Bio Composites Market
Composite Materials
Composite Drums Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Short Fiber Thermoplastic Composites Market
Composite Materials
Composite Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
Global Carbon Graphite Bushings Market