
 Reinforced Plastics Market | 2026-2036
Reinforced Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Reinforced Plastics Market Analysis
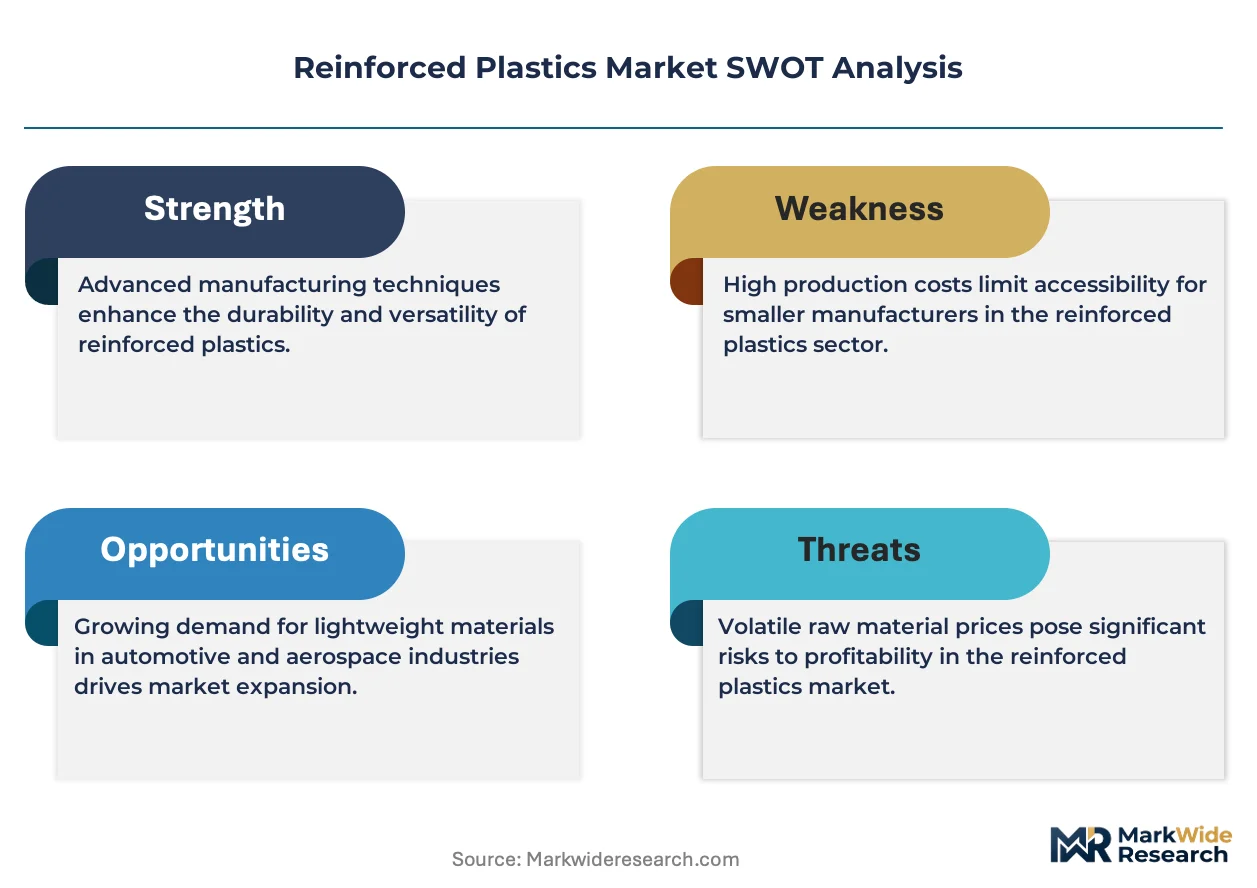
Glass fiber is repositioning steel in automotive underbody components and structural panels, cutting mass by up to forty percent while maintaining crashworthiness. Owens Corning leverages its vertical integration from glass melt to finished composite to sustain cost leadership in North American supply chains. Toray Industries anchors its position through proprietary carbon fiber precursor chemistry that differentiates its aerospace-grade offerings from commodity alternatives.
Reinforced plastics are composite materials combining a polymer matrix with embedded fibers to achieve strength-to-weight ratios exceeding those of most metals, typically manufactured through pultrusion, resin transfer molding, or filament winding processes depending on part geometry and volume requirements. Glass fiber reinforced plastics dominate by installed capacity across construction and marine applications where cost sensitivity outweighs premium performance needs, while carbon fiber reinforced plastics command the fastest expansion in aerospace structural components where specific stiffness drives specification. Automotive parts as an application segment sits at the intersection of these two dynamics, with hybrid glass-carbon layups emerging as the pragmatic compromise between weight reduction targets and bill-of-material constraints.
The EU Green Deal and REACH framework constrain halogenated flame retardants and mandate recyclability disclosures, redirecting formulation R&D toward bio-based thermoset resins and thermoplastic matrices that enable end-of-life reprocessing. FAA certification standards for composite airframes and EPA automotive emissions benchmarks both translate directly into material qualification protocols that suppliers must satisfy before contract eligibility. Stakeholders should monitor the divergence between European regulatory timelines for circular material content mandates and the pace at which Asian manufacturing clusters can certify equivalent supply chains, as this gap will determine regional competitive positioning in export markets.
Market Dynamics
Automotive electrification is compressing design cycles and mandating mass reduction targets that reinforced plastics uniquely satisfy, while EU circular economy mandates force simultaneous recyclability investment into thermoplastic matrix development.
Growth Catalysts
- EU Green Deal emissions benchmarks:Tightening CO2 fleet targets compel OEMs to substitute steel with glass fiber reinforced plastics in structural panels, creating specification pull across German and French automotive supply chains.
- China electric vehicle production scale:Domestic battery-electric vehicle output concentrates demand for lightweight battery enclosures and body-in-white components, pulling carbon fiber reinforced plastics into high-volume manufacturing.
- Thermoplastic resin advancement:Polyamide and PEEK matrices enabling end-of-life reprocessing are displacing thermosets in aerospace interiors as airlines face circular material disclosure requirements.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs fluctuate with petrochemical feedstock markets, compressing margin predictability for aerospace-grade material suppliers.
- Autoclave capacity concentration:Large-tow carbon fiber curing infrastructure clusters in Japan and the United States, creating geographic supply risk for European aerostructures manufacturers.
- REACH chemical registration friction:Novel bio-based hardeners face multi-year toxicity evaluation timelines, delaying commercialization of sustainable thermoset formulations.
Strategic Opportunities
- India infrastructure buildout:National highway expansion and smart city programs create specification pull for glass fiber reinforced plastic rebar and utility poles in corrosion-exposed environments.
- Wind blade recycling mandates:End-of-service blade disposal regulations in Germany and Denmark drive development of thermoplastic-compatible fiber architectures for next-generation turbine manufacturing.
- Digital twin convergence:Finite element analysis software integrating with automated fiber placement equipment reduces prototype iteration cycles for aerospace component qualification.
Industry Challenges
- Composite repair technician scarcity:FAA-certified NDT inspection and bonded repair skills concentrate in aging workforce pools, constraining MRO capacity expansion for composite airframes.
- Multi-material joining complexity:Dissimilar coefficient of thermal expansion between carbon fiber and aluminum creates galvanic corrosion risk in automotive hybrid structures, demanding specialized adhesive development.
- Recyclate certification timelines:Pyrolysis-recovered carbon fiber requires requalification for aerospace load-bearing applications, extending circular material adoption cycles.
Report Scope
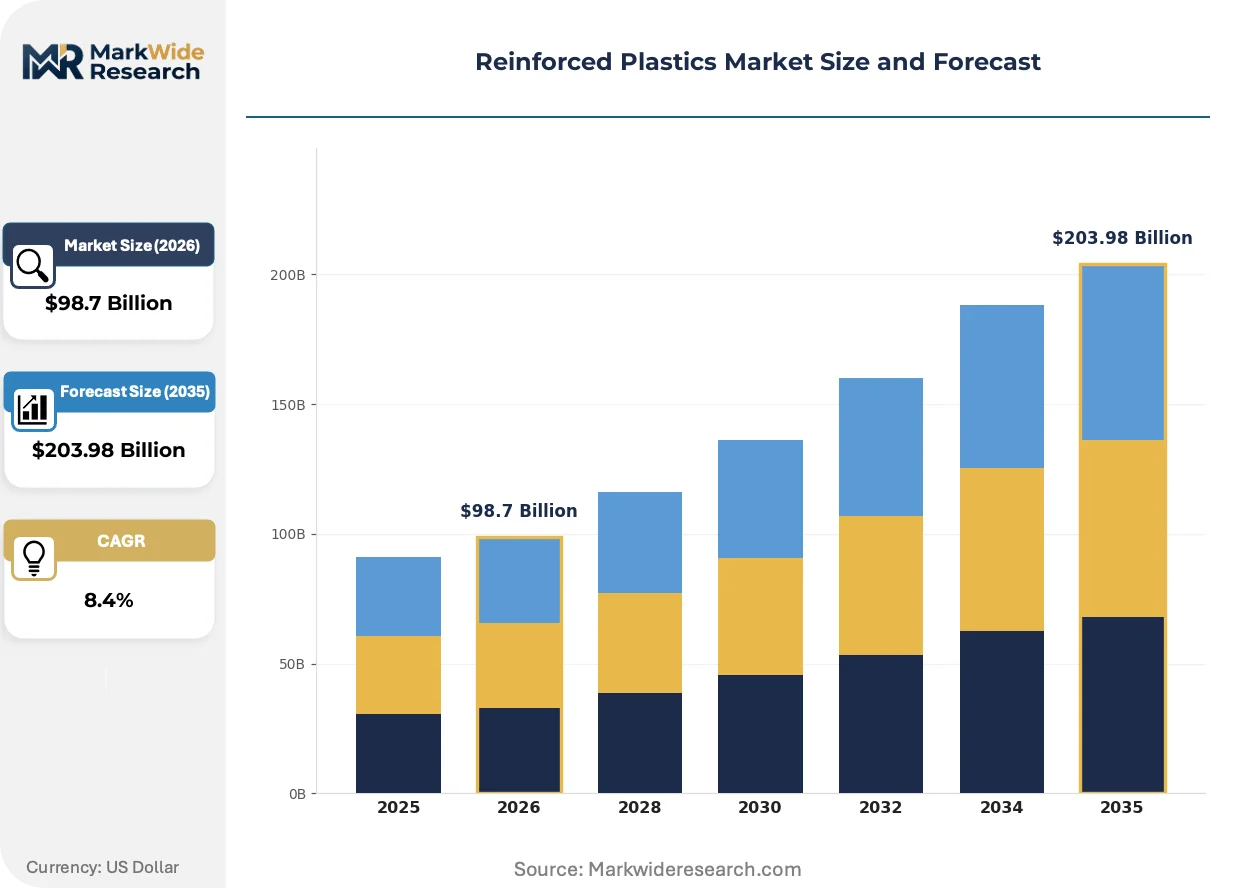
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reinforced Plastics Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Fiber Reinforced Plastics, Carbon Fiber Reinforced Plastics, Aramid Fiber Reinforced Plastics, Natural Fiber Reinforced Plastics End User: Aerospace, Automotive, Construction, Marine Application: Structural Components, Insulators, Automotive Parts, Consumer Goods Form: Sheets, Rods, Tubes, Molding |
| Companies Covered | Teijin Limited, Solvay, Toray Industries, Owens Corning, BASF, Hexcel Corporation, SGL Carbon, Huntsman Corporation, Mitsubishi Chemical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reinforced Plastics Market Emerging Trajectories
Material science, digital manufacturing, and regulatory disclosure requirements are simultaneously rewriting specification protocols and production economics across reinforced plastics value chains.
Thermoplastic composites with continuous fiber reinforcement are converging with automated tape laying systems to enable out-of-autoclave processing for aerospace secondary structures. Tier 1 suppliers in Germany and Japan are qualifying these materials for wing access panels and fairings, compressing cure cycles from hours to minutes while maintaining damage tolerance requirements.
REACH Article 33 substance disclosure obligations now mandate supply chain transparency for SVHC content above threshold limits in reinforced plastic articles placed on the European market. Automotive and electronics OEMs are responding by auditing glass fiber sizing chemistries and resin formulations, redirecting procurement toward suppliers with certified substance data management systems.
Buyers in the construction sector are consolidating specifications around pre-certified pultruded profiles that bundle structural calculation software with material supply. This unbundling of engineering services from product sales compresses project timelines for infrastructure contractors in the United States and Australia, while displacing traditional distributor technical support roles.
Reinforced Plastics Market Segmentation
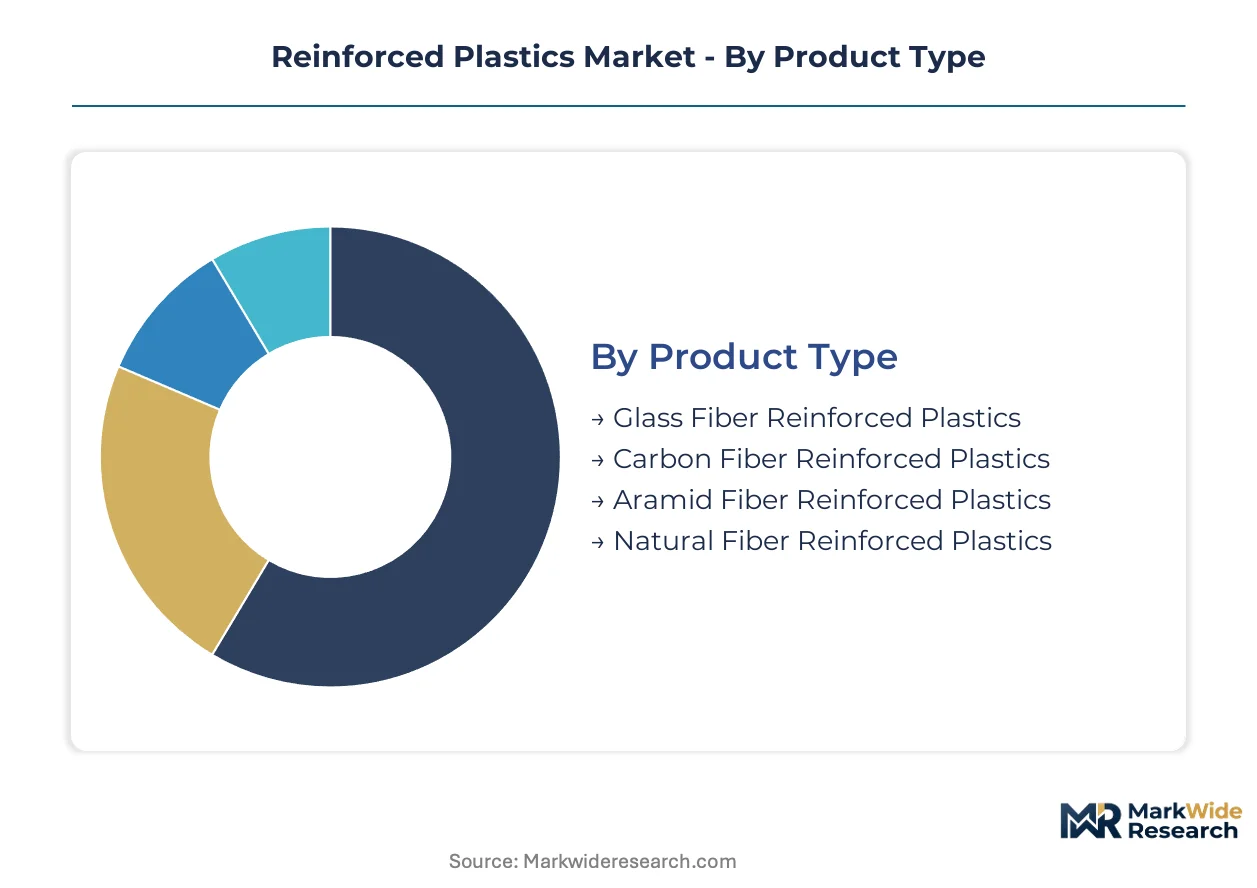
Material specification in reinforced plastics hinges on the strength-to-weight ratio required versus cost tolerance, with fiber type and matrix selection cascading through downstream form factors and end-use qualification protocols. Segmentation reveals how aerospace-grade carbon fiber commands premium positioning while construction-grade glass fiber drives installed volume, creating distinct competitive arenas within the same broad material class.
Product Type:
Buyers segment primarily by performance tier against structural load requirements, with fiber modulus and matrix chemistry determining qualification pathways.
- Glass Fiber Reinforced Plastics:E-glass and S-glass variants embedded in polyester or vinyl ester matrices deliver tensile strength sufficient for infrastructure rebar and marine hulls. Construction contractors in the United States and Australia specify pultruded profiles for corrosion-exposed bridge components, with Owens Corning's vertical integration from melt to finished composite sustaining cost leadership in North American supply chains.
- Carbon Fiber Reinforced Plastics:PAN-based and pitch-based precursors achieve specific stiffness metrics that satisfy FAA certification for primary aerostructures. Toray Industries anchors aerospace-grade supply through proprietary precursor chemistry, while automotive OEMs in Germany and China accelerate adoption for battery enclosures and body-in-white components under EU Green Deal emissions benchmarks.
- Aramid Fiber Reinforced Plastics:Kevlar and Twaron reinforcements absorb impact energy in ballistic protection and high-performance marine sails.
- Natural Fiber Reinforced Plastics:Flax, hemp, and jute composites serve interior automotive panels and consumer goods where bio-content disclosure satisfies EU circular economy procurement rules.
Volume sits with Glass Fiber Reinforced Plastics; growth tilts toward Carbon Fiber Reinforced Plastics.
End User:
Regulatory intensity varies sharply across end-use verticals, with certification timelines and liability exposure reshaping supplier qualification barriers.
- Aerospace:FAA and EASA airworthiness directives mandate damage tolerance and flame-smoke-toxicity testing that extends material qualification to multi-year cycles. Boeing and Airbus tier suppliers by autoclave capacity and NDT certification, with large-tow carbon fiber curing infrastructure clustering in Japan and the United States.
- Automotive:NHTSA crashworthiness and EPA emissions benchmarks translate directly into material specifications, with OEMs substituting steel for hybrid glass-carbon layups in underbody components to achieve mass reduction targets.
- Construction:ACI 440 and Eurocode 2 standards govern glass fiber reinforced plastic rebar in concrete structures exposed to de-icing salts and marine atmospheres.
- Marine:ISO 12215 structural scantling rules and IMO fire safety codes dictate laminate schedules for hulls and superstructures.
Procurement concentration clusters in Automotive; qualification complexity peaks in Aerospace.
Application:
Functional load-bearing requirements determine fiber architecture and processing method, with structural applications demanding continuous reinforcement versus discrete-fiber molding for cosmetic parts.
- Structural Components:Wing spars, wind turbine blades, and bridge decks employ unidirectional or woven continuous fiber architectures processed via resin transfer molding or filament winding to achieve anisotropic strength distribution.
- Automotive Parts:Compression-molded sheet molding compound and bulk molding compound serve non-structural body panels and underhood components where Class A surface finish competes with mass reduction priorities.
- Insulators:Glass fiber reinforced epoxy and polyester shapes provide electrical isolation and mechanical support in transformer bushings and switchgear housings.
- Consumer Goods:Short-fiber thermoplastic injection molding enables sporting equipment and electronics enclosures where cost sensitivity outweighs modulus requirements.
Revenue contribution concentrates in Structural Components; margin expansion tracks Automotive Parts.
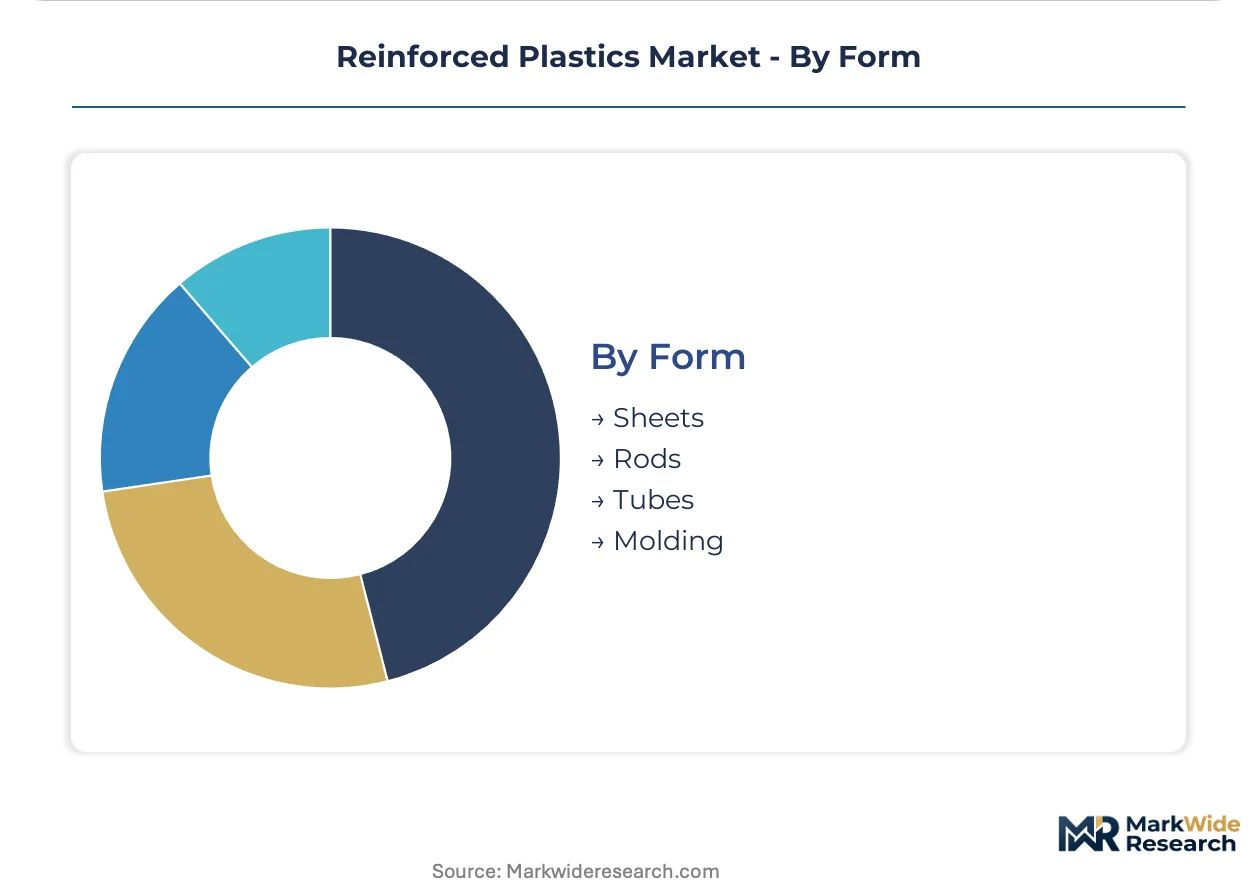
Form:
Processing economics and part geometry constraints segment form selection, with continuous forms suiting linear profiles and molding compounds enabling complex three-dimensional shapes.
- Sheets:Prepregs and thermoplastic organosheets feed automated tape laying and press forming operations for aerospace skin panels and automotive floor pans, with out-of-autoclave processing gaining traction for secondary structures.
- Molding:Injection, compression, and transfer molding compounds accommodate high-volume production of geometrically complex automotive and consumer parts.
- Rods:Pultruded solid sections serve tool handles, electrical insulators, and civil engineering tendons.
- Tubes:Filament-wound and pultruded hollow sections provide torsional rigidity for drive shafts, masts, and utility poles.
Sheets command premium positioning; Molding captures highest shipment volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates reinforced plastics demand through battery-electric vehicle production scale and infrastructure investment, while EU Green Deal emissions benchmarks redirect European automotive specifications toward lightweight composites.
China
Domestic EV manufacturers specify carbon fiber reinforced plastics for battery enclosures and body-in-white components as production volumes scale. MIIT dual carbon goals mandate lightweighting in automotive supply chains. Yangtze River Delta manufacturing clusters around Shanghai host filament winding operations for wind turbine blade production.
Germany
OEMs substitute steel with glass fiber reinforced plastics in underbody components to meet EU Green Deal CO2 fleet targets. KBA type-approval protocols extend to composite crash structures. Bavaria's automotive supply corridor concentrates resin transfer molding capacity for structural panels.
United States
FAA certification standards for composite airframes sustain demand for aerospace-grade carbon fiber in Washington and Kansas manufacturing hubs. EPA automotive emissions benchmarks translate into material qualification requirements. Pacific Northwest clusters around Seattle anchor large-tow carbon fiber curing infrastructure.
Japan
METI industrial policy supports carbon fiber precursor chemistry R&D for aerospace and automotive applications. JIS standards govern quality protocols for continuous fiber reinforced thermoplastics. Nagoya aerospace manufacturing corridor concentrates autoclave capacity for primary aerostructures.
India
National highway expansion and smart city programs create specification pull for glass fiber reinforced plastic rebar in corrosion-exposed environments. BIS certification requirements for composite utility poles streamline public procurement. Gujarat industrial corridors host pultrusion operations for infrastructure applications.
Reinforced Plastics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with aerospace qualification barriers concentrating premium supply around precursor chemistry owners while construction applications fragment among regional pultruders. Three archetypes dominate: integrated fiber-to-composite producers, resin formulators with compounding assets, and specialized prepeg converters serving tiered certification requirements. Capacity expansion and backward integration into precursor production represent the dominant competitive vectors as margin pressure intensifies on commodity grades.
Among integrated fiber producers, Toray Industries and Teijin Limited occupy positions defined by proprietary precursor chemistry and aerospace-grade certification heritage. Owens Corning exemplifies the glass fiber vertical integration model, with captive melt-to-finished-composite operations sustaining cost leadership in North American construction supply chains. Solvay represents the resin-centric archetype, with formulation expertise spanning thermoset and thermoplastic matrices for automotive and aerospace qualification protocols.
| Leading Market Players |
|---|
| Teijin Limited |
| Solvay |
| Toray Industries |
| Owens Corning |
| BASF |
| Hexcel Corporation |
| SGL Carbon |
| Huntsman Corporation |
| Mitsubishi Chemical Group |
| Others |
Supply Flow & Price Mechanics
FAA-certified NDT inspection technicians concentrate in Seattle and Wichita manufacturing corridors, with labor-cost differentials between these US aerospace hubs and emerging pultrusion clusters in Gujarat widening pricing-tier spreads across carbon fiber and glass fiber reinforced plastics.
Pricing Analysis
Volume concentrates in construction-grade glass fiber reinforced plastics where commodity competition compresses margins, while aerospace-grade carbon fiber commands premium positioning through multi-year qualification protocols. Price differentiation rests on certification tier—FAA airworthiness versus ACI 440 structural compliance—and captive precursor production. Cost compression in automotive hybrid layups is intensifying as OEMs consolidate supplier panels under EU Green Deal procurement rules. Construction contractors exhibit highest price sensitivity; aerospace tier-1 suppliers prioritize supply security over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Boeing and Airbus tier suppliers mandate qualified carbon fiber precursor supply from both Japan and the United States, fragmenting procurement leverage. Geographic supply concentration centers on Japan for PAN-based aerospace precursors, China for wind blade filament winding capacity, and Germany for automotive resin transfer molding. Raw material dependencies span acrylonitrile monomer, epoxy hardeners, and glass melt formulations. Single-source vulnerability concentrates in large-tow autoclave curing infrastructure. Distribution runs through qualified tier-1 converters holding OEM-specific certification heritage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reinforced plastics market sits in a technology-transition phase as thermoplastic matrices displace thermosets under circular economy mandates.
For Market Incumbents: Extend qualification heritage into thermoplastic continuous fiber architectures before out-of-autoclave processing becomes standard for aerospace secondary structures. Lock in long-term precursor supply agreements to defend against acrylonitrile price volatility. Accelerate backward integration into bio-based hardener chemistry to preempt REACH registration delays. For New Entrants and Emerging Players: EU Green Deal circular material content mandates in Germany open a window for recycled carbon fiber requalification services. Target India's infrastructure rebar segment where BIS certification streamlines public procurement. Lead with bundled engineering software and pre-certified pultruded profiles to displace traditional distributor technical support roles. For Investors and Strategic Acquirers: Re-rating potential sits with resin formulators holding thermoplastic matrix patents given automotive electrification mass reduction targets. Long-term viability favors specialists with dual aerospace-automotive certification heritage. Watch for thermoplastic tape laying equipment utilization rates as inflection indicator for out-of-autoclave adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemistry | Captive acrylonitrile supply insulates Toray and Teijin from petrochemical feedstock volatility. |
| Thermoplastic Matrix Patent Portfolio Expansion | Polyamide and PEEK formulation ownership determines automotive circular material qualification priority. |
| Out-of-Autoclave Processing Qualification | Automated tape laying certification for secondary aerostructures compresses cure cycles from hours to minutes. |
| Recycled Carbon Fiber Requalification Investment | Pyrolysis-recovered fiber certification for aerospace load-bearing applications extends circular material adoption. |
| Digital Twin Software Integration | Finite element analysis convergence with automated fiber placement reduces prototype iteration cycles. |
Methodological Framework
Document review covered customs and trade data, SEC 10-K filings, and ACC industry reports, complemented by interviews with plant managers at composite manufacturing facilities, procurement leads at Tier 1 automotive suppliers, distribution channel partners in North American construction supply, and technical R&D directors at resin formulators. Bottom-up capacity and shipment estimates were triangulated against top-down demand modeling across end-use verticals.
Segmented outputs across fiber type, matrix chemistry, end-use industry, and regional production hub were generated over the projection horizon. CAGRs were derived from regression analysis against automotive production forecasts, wind energy installation pipelines, and aerospace delivery schedules. Model inputs included acrylonitrile price indices, autoclave capacity utilization surveys, and REACH substance disclosure compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for thermoplastic composite qualification would alter the outlook if out-of-autoclave processing achieves primary aerostructure certification earlier than baseline assumptions. Deviation in EU circular material content mandate enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Polycarbonate Composites Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
Europe Marine Composites Market
Composite Materials
Wind Turbine Composites Market
Composite Materials
Global Carbon Graphite Bushings Market
Composite Materials
Global Sports Composites Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Plastic Composites Market
Composite Materials
Biocomposites Market
Composite Materials
Global Geocomposites Market
Composite Materials
Lignin-Based Graphene Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Acrylic Laminates Market
Composite Materials
Aramid Fiber Reinforced Polymer Market
Composite Materials
Automotive Carbon Fiber Materials Market
Composite Materials
FRP Reactor Market