
 Polyphenylene Sulfide (PPS) Composites Market | 2026-2036
Polyphenylene Sulfide (PPS) Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Polyphenylene Sulfide (PPS) Composites Market Analytics
Polyamide is restructuring competitive economics in high-temperature thermoplastic applications as PPS composites capture share in connector housings and pump components. Solvay leverages its integrated polymer chain from sulfur chemistry through compounding to sustain margin control in European aerospace grades. Celanese Corporation anchors North American supply through its Fortron PPS platform, while DIC Corporation dominates Asian resin production with captive chlorination technology.
Polyphenylene sulfide composites are semi-crystalline thermoplastic formulations combining PPS resin with glass fiber, carbon fiber, or mineral fillers to achieve continuous service temperatures exceeding 200°C and inherent flame resistance without halogenated additives. These materials serve primarily as metal replacements in corrosive, high-heat environments where dimensional stability and chemical resistance prove critical. Reinforced grades command the deepest margin pools due to compound complexity and qualification barriers in automotive and aerospace channels. Electrical insulation applications represent the fastest-expanding demand segment as EV power electronics drive specifications for tracking resistance and thermal cycling endurance.
EPA tailpipe regulations and the EU F-Gas Regulation are accelerating material transitions toward lighter, chemically resistant polymers in thermal management systems. FDA food-contact and EMA medical device frameworks additionally shape product development pathways for PPS composite processors seeking multi-sector qualification. Stakeholders must monitor evolving battery electric vehicle platform architectures where thermal runaway protection specifications will determine next-generation material selection criteria.
Market Dynamics
Metal-to-polymer substitution in automotive thermal management systems is compressing design cycles and forcing compounders to synchronize resin development with OEM platform roadmaps. This structural shift concentrates purchasing power among vehicle electrification programs.
Growth Catalysts
- EPA emissions standards:Tailpipe regulations are accelerating polymer adoption in charge air coolers and exhaust gas recirculation modules. OEMs specify PPS composites for weight reduction in under-the-hood applications.
- EV power electronics:Battery electric vehicle architectures demand tracking resistance and thermal cycling endurance in connector housings. PPS compounds qualify for 800V inverter systems.
- China's eastern manufacturing corridor:Domestic resin compounding capacity has scaled rapidly, reducing import dependency for automotive tier suppliers.
Market Restraints
- Chlorination chemistry concentration:Captive production of para-dichlorobenzene feedstock concentrates among Asian integrated producers, exposing non-integrated compounders to input cost volatility.
- REACH compliance burden:ECHA substance registration requirements impose documentation costs that disproportionately burden small-batch aerospace grade suppliers.
- Polyamide 46 substitution:DSM Stanyl and similar high-heat polyamides compete in connector applications above 150°C continuous service temperature.
Strategic Opportunities
- Thermal runaway protection:EV battery enclosure specifications are creating qualification pathways for flame-resistant PPS grades without halogenated additives.
- EMA medical device frameworks:European sterilization-resistant component demand is expanding beyond traditional pharmaceutical processing equipment into surgical robotics housings.
- Long-fiber thermoplastic hybridization:Overmolding PPS with continuous fiber composites is enabling structural electronics integration in aerospace interior modules.
Industry Challenges
- Qualification timeline compression:Automotive OEMs demand PPAP submission in 18-month windows while aerospace OEMs maintain 36-48 month certification cycles, straining compounder R&D allocation.
- Multi-sector regulatory navigation:Simultaneous FDA food-contact, EMA medical, and FAA flammability qualification requires dedicated regulatory affairs capacity that mid-size processors struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyphenylene Sulfide (PPS) Composites Market |
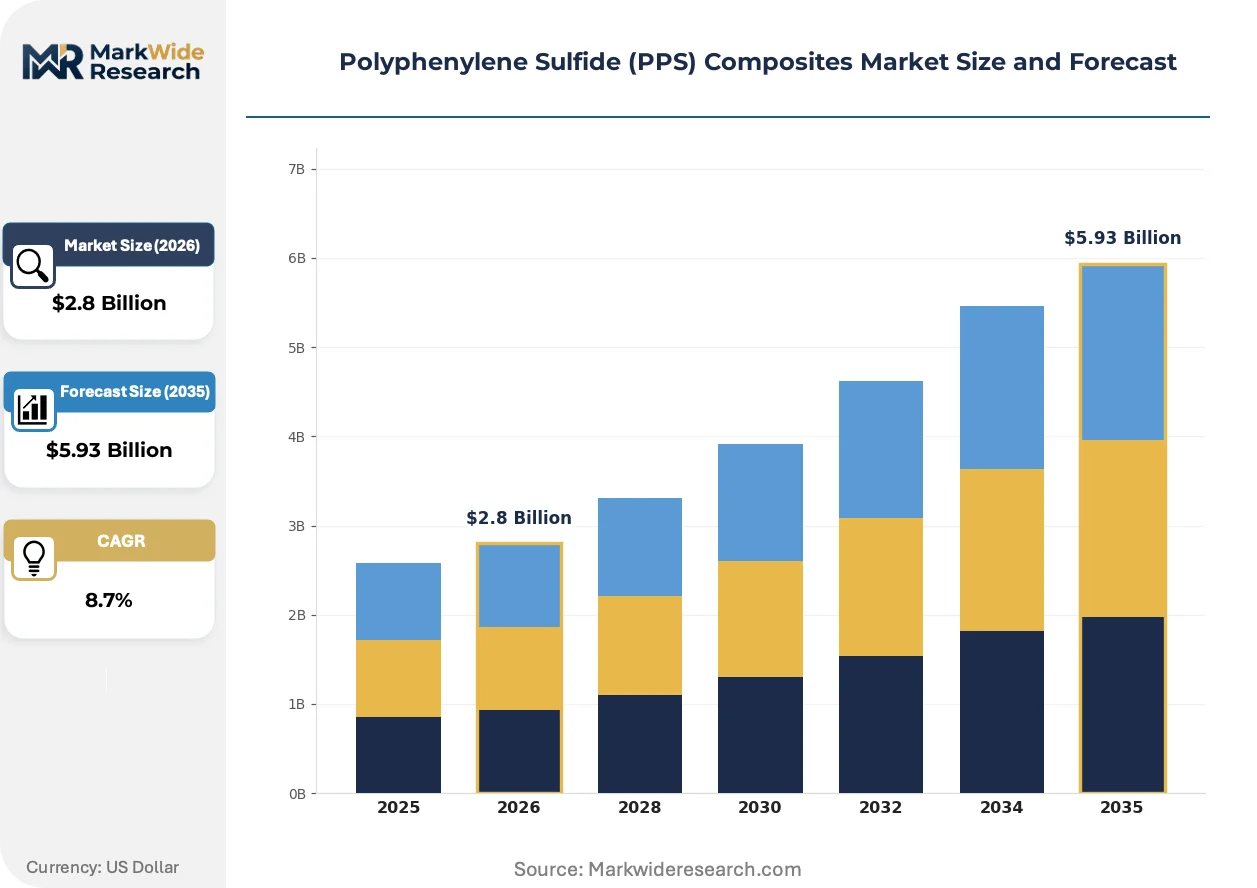
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filled, Unfilled, Liquid Crystal Polymer, Reinforced End User: Aerospace, Automotive, Electronics, Industrial Application: Electrical Insulation, Structural Components, Chemical Processing, Aerospace Components Form: Sheet, Rod, Film, Powder |
| Companies Covered | Solvay, Celanese Corporation, DIC Corporation, Toray Industries, Kureha Corporation, Tosoh Corporation, SABIC, Polyplastics Co., NHU Materials Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyphenylene Sulfide (PPS) Composites Market Evolving Landscape
Material qualification protocols are fragmenting across end-use verticals as automotive electrification timelines compress while aerospace and medical channels maintain legacy validation cycles. This temporal misalignment is reshaping how compounders structure R&D portfolios.
Hybrid carbon-glass fiber PPS formulations are decentralizing structural electronics manufacturing from machined aluminum toward injection-molded thermal management substrates. EV inverter suppliers in Germany and South Korea are adopting these grades for 800V busbar integration. The shift is compressing secondary machining operations and enabling part consolidation in power module housings.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon-based cooling in automotive climate systems. PPS composites are capturing specification in next-generation refrigerant-resistant compressor components and heat exchanger manifolds. Tier suppliers in Stuttgart and Turin are accelerating mold trials for R-1234yf compatibility validation.
Consolidated procurement by EV platform architects is displacing fragmented purchasing across internal combustion engine component families. Battery pack integrators in Shanghai and Detroit now specify resin grades directly, bypassing traditional tier-two compounder relationships. This concentration is compressing margin structures for non-integrated resin suppliers.
Polyphenylene Sulfide (PPS) Composites Market Segmentation
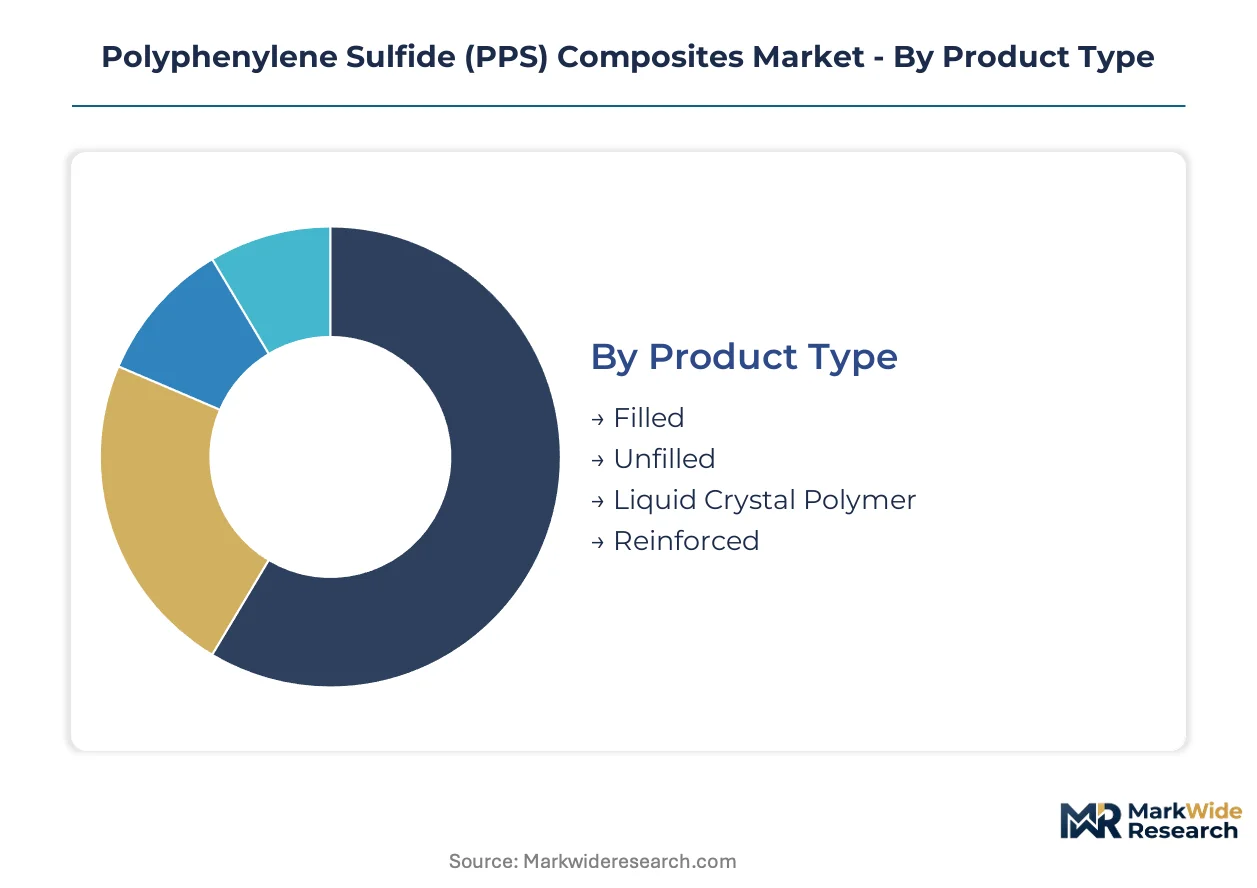
PPS composite formulations diverge sharply across thermal, mechanical, and electrical performance requirements. Specification decisions cascade from resin grade selection through reinforcement architecture to final conversion process.
Product Type:
Cost tiers separate commodity compounders from specialty resin houses capable of aerospace qualification.
- Reinforced:Glass and carbon fiber loadings between 30-60% achieve continuous service temperatures exceeding 220°C. Automotive under-the-hood applications in Stuttgart and Detroit specify these grades for charge air cooler housings and EGR modules.
- Filled:Mineral-reinforced formulations reduce raw material costs while maintaining dimensional stability for pump housings and valve bodies. Chinese resin compounders in Jiangsu province have scaled capacity for these grades, compressing import premiums for Asian automotive tier suppliers.
- Unfilled:Virgin PPS resin serves specialty coating and filtration membrane applications requiring maximum chemical resistance.
- Liquid Crystal Polymer:LCP-modified PPS blends target ultra-thin-wall connector applications in 5G base station equipment.
Reinforced grades lead volumes today; LCP blends are gaining share fastest.
End User:
Application maturity cycles stretch from 18-month automotive PPAP windows to 48-month aerospace qualification timelines.
- Automotive:Metal-to-polymer substitution accelerates across thermal management systems as EPA emissions standards tighten. OEMs in Michigan and Bavaria specify PPS composites for weight reduction in electrified powertrains.
- Electronics:EV power electronics demand tracking resistance above 600V and thermal cycling endurance across 800V inverter architectures. Connector housings for battery management systems represent the steepest expansion trajectory.
- Aerospace:FAA flammability certification and OEM-specific material qualification create multi-year barriers to entry. Interior structural modules and electrical insulation components dominate specification.
- Industrial:Chemical processing equipment and oilfield components exploit inherent corrosion resistance without protective coatings.
Automotive captures the largest revenue pool; electronics is climbing the fastest.
Application:
Performance thresholds separate commodity substitution from premium specification.
- Electrical Insulation:Dielectric strength and comparative tracking index requirements intensify with EV voltage architectures. Busbar integration in 800V systems drives specification for hybrid carbon-glass formulations.
- Structural Components:Load-bearing brackets and housings substitute aluminum in corrosive environments. Long-fiber thermoplastic hybridization enables part consolidation in power module assemblies.
- Chemical Processing:Pumps, valves, and filtration systems exploit resistance to acids and hydrocarbons at elevated temperatures.
- Aerospace Components:Flame resistance without halogenated additives satisfies strict OEM smoke toxicity requirements.
Structural components anchor current volumes; electrical insulation shows the steepest growth curve.
Form:
Conversion technology dictates resin morphology and additive dispersion requirements.
- Sheet:Compression-molded plates serve chemical tank linings and semiconductor processing equipment. Japanese processors in Osaka prefecture specialize in thick-gauge formulations for wet bench applications.
- Powder:Fine-ground resin enables coating applications and selective laser sintering additive manufacturing. Medical device housings in Switzerland exploit powder grades for complex geometries.
- Rod:Extruded stock shapes feed precision machining operations for prototype and low-volume production.
- Film:Thin-gauge calendered sheet targets capacitor dielectrics and flexible circuit substrates.
Sheet dominates tonnage today; powder formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor concentrates the world's largest PPS resin compounding capacity. Domestic producers in Jiangsu and Zhejiang provinces have scaled output to serve automotive tier suppliers. This concentration is compressing import premiums and reshaping procurement patterns across Asia-Pacific.
China
EV battery pack integrators in Shanghai and Detroit now specify resin grades directly, bypassing traditional tier-two relationships. MIIT's dual carbon goals are accelerating metal-to-polymer substitution in thermal management systems. Domestic compounders in Suzhou and Ningbo have captured qualification for 800V inverter housings.
United States
EPA tailpipe regulations are forcing OEMs in Michigan to adopt PPS composites for charge air coolers and EGR modules. The Inflation Reduction Act's domestic content provisions are reshaping supply chain decisions for electrified powertrains. Compounders in the Detroit metro area are synchronizing R&D with shortened 18-month automotive PPAP windows.
Germany
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon cooling in automotive climate systems. Tier suppliers in Stuttgart and Turin are accelerating mold trials for R-1234yf compatibility in compressor components. KBA certification requirements for thermal management components are tightening material performance benchmarks.
Japan
Hybrid carbon-glass fiber PPS formulations are decentralizing structural electronics from machined aluminum toward injection-molded substrates. METI's semiconductor equipment subsidies are expanding demand for thick-gauge sheet in wet bench applications. Processors in Osaka prefecture specialize in semiconductor processing equipment grades.
South Korea
MFDS medical device frameworks are expanding sterilization-resistant component demand into surgical robotics housings. EV inverter suppliers in Seoul and Busan are adopting hybrid formulations for 800V busbar integration. Domestic compounders are qualifying long-fiber thermoplastic grades for power module structural integration.
Polyphenylene Sulfide (PPS) Composites Market Competitive Landscape
Global majors compete with regional champions across integrated sulfur chemistry and captive chlorination technology. The vendor base splits between European aerospace-grade specialists, North American automotive-focused compounders, and Asian resin producers with backward integration into para-dichlorobenzene feedstock. Three archetypes dominate: integrated polymer chain operators, regional compounding specialists, and captive chlorination technology holders. Capacity expansion and qualification timeline compression represent the dominant competitive moves as automotive electrification accelerates.
Within the integrated polymer chain tier, Solvay and Celanese Corporation exemplify margin control through upstream sulfur chemistry ownership. DIC Corporation anchors the Asian captive chlorination archetype with resin production concentration in Japan. These three companies occupy positions that reflect the geographic fragmentation of qualification requirements—European aerospace, North American automotive, and Asian electronics respectively.
| Leading Market Players |
|---|
| Solvay |
| Celanese Corporation |
| DIC Corporation |
| Toray Industries |
| Kureha Corporation |
| Tosoh Corporation |
| SABIC |
| Polyplastics Co. |
| NHU Materials Co. |
| Others |
Value Network & Pricing Analysis
Chlorination chemistry consolidation among Asian integrated producers is simultaneously compressing compounder margins and reshaping procurement risk profiles as para-dichlorobenzene feedstock concentration exposes non-integrated processors to input cost volatility. This technological lock-in at the monomer stage feeds directly into pricing power asymmetries across the value chain.
Pricing Analysis
Input-cost pass-through from captive chlorination operators in Japan and China dominates pricing dynamics for non-integrated compounders in North America and Europe. Three-tier pricing structure across aerospace-qualified, automotive-grade, and industrial-economy levels separates margin pools by certification burden and volume scale. Pricing pressure stems from polyamide 46 substitution in connector applications above 150°C continuous service temperature. Tier-two automotive suppliers exhibit highest price sensitivity due to consolidated procurement by EV platform architects, while aerospace OEMs accept premium positioning for multi-year qualification cycles.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs mandate multi-supplier qualification for 800V inverter housing grades, fragmenting procurement across Solvay, Celanese, and DIC Corporation channels. Geographic supply concentration centers on China, Japan, and Germany for resin compounding, with para-dichlorobenzene feedstock anchored in Asian chlorination complexes. Raw material dependencies rest on sulfur chemistry intermediates, glass fiber rovings, and carbon fiber precursors. Single-source vulnerability concentrates in para-dichlorobenzene supply from integrated Japanese and Chinese producers. Distribution runs through direct OEM specification for EV battery integrators, bypassing traditional tier-two compounder relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA tailpipe standards and EU F-Gas Regulation phase-down schedules are accelerating material transitions toward lighter, chemically resistant polymers in thermal management systems.
For Market Incumbents: Deepen backward integration into sulfur chemistry or captive chlorination technology to defend margin control against para-dichlorobenzene cost volatility. Expand compounding capacity in China's eastern manufacturing corridor to capture domestic qualification pathways for 800V inverter systems. Prioritize aerospace certification investment to maintain premium positioning as automotive timelines compress. For New Entrants and Emerging Players: Launch via long-fiber thermoplastic hybridization partnerships with EV battery enclosure integrators seeking thermal runaway protection specifications. Target medical device sterilization-resistant components under EMA frameworks as the most penetrable segment given extended qualification timelines that favor specialized compounders. Pursue surgical robotics housing applications as a white-space entry point with lower incumbent saturation. For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounding specialists without captive feedstock integration but with established automotive PPAP qualifications. Long-term viability over the next decade hinges on positioning for EV platform consolidation and battery electric vehicle thermal management specification. Watch for inflection in 800V architecture adoption rates across German and South Korean inverter suppliers as the signal determining next-generation material selection criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Chemistry | Celanese and Solvay anchor margin control through upstream monomer ownership. |
| Automotive PPAP Acceleration | Compounders in Detroit and Stuttgart compress development cycles to 18-month windows. |
| Aerospace Certification Investment | FAA flammability qualification creates multi-year barriers protecting premium pricing tiers. |
| EV Battery Enclosure Qualification | Thermal runaway protection specifications open pathways for halogen-free flame-resistant grades. |
| Medical Device Framework Navigation | EMA sterilization-resistant demand expands from pharmaceutical processing into surgical robotics. |
Research Methodology
Multiple input streams — technical discussions with resin compounder R&D directors, procurement leads at automotive Tier 1 suppliers, and regulatory affairs specialists at aerospace OEMs — were reconciled against customs trade data, SEC 10-K filings from polymer majors, and MIIT production statistics from China's eastern manufacturing corridor. Primary interviews with plant managers at Jiangsu and Zhejiang compounding facilities supplemented secondary validation from chemical industry association reports. Bottom-up volume modeling across reinforcement architectures and end-use applications was cross-checked against top-down market sizing from resin production disclosures.
Data-stream reconciliation anchored the forecast framework across the analysis window, with segmentation dimensions spanning product type, end-user industry, application performance threshold, and regional production hub. CAGRs were derived from trend extrapolation of EV power electronics content per vehicle, EPA regulatory stringency indices, and aerospace build rate projections. Industry-specific inputs included 800V inverter adoption curves, EU F-Gas Regulation implementation schedules, and medical device sterilization protocol evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt polyamide substitution acceleration or para-dichlorobenzene supply disruption scenarios. Deviation in EV platform architecture standardization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Carbon Graphite Bushings Market
Composite Materials
Thermoplastic Prepreg Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Ultra-Lightweight Cement Composites Market
Composite Materials
High Performance Composites Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
Copper Clad Laminates Market
Composite Materials
FRP Reactor Market
Composite Materials
Fiber Reinforced Composite Tapes Market
Composite Materials
Global Composites Cylinder Market
Composite Materials
Stone Plastic Composite Flooring Market
Composite Materials
Graphite Felt Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Short Fiber Thermoplastic Composites Market