
 Wall Cladding Materials Market | 2026-2036
Wall Cladding Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Wall Cladding Materials Market Analytics
The EU Green Deal is realigning procurement criteria for exterior wall systems across European commercial construction. James Hardie Industries leverages its fiber cement technology leadership to compete in low-carbon specification markets. Saint-Gobain anchors its position through integrated insulation-cladding systems that address thermal bridging requirements. Kingspan Group dominates metal panel segments with controlled distribution networks spanning industrial and cold-chain applications.
Wall cladding materials constitute protective and decorative exterior layers applied to building substrates, typically measured by wind-load resistance, water-vapor permeance, and fire-reaction classification to EN 13501-1. These systems shield structural elements from moisture intrusion, thermal cycling, and ultraviolet degradation while contributing to envelope energy performance. Vinyl cladding leads volume in North American residential markets due to cost-positioning and color retention warranties. Fiber cement under the material-type category commands premium positioning where fire-rated assemblies are mandated. Panelized installation methods are gaining specification share in commercial projects seeking accelerated envelope closure and reduced on-site labor exposure.
REACH restrictions on hazardous substance content in construction products constrain coating formulations and substrate treatments entering European markets. The EPA's Lead Renovation, Repair and Painting Rule shapes remediation protocols for existing cladding replacement across US residential stock. China's GB standards for building energy efficiency impose thermal performance minimums that favor insulated composite systems. Stakeholders must monitor regulatory divergence between carbon-accounting methodologies and embodied-carbon disclosure requirements as these frameworks mature across jurisdictions.
Market Dynamics
The EU Green Deal's embodied carbon thresholds are compressing specification windows for conventional cladding systems while accelerating substitution toward lower-carbon fiber cement and bio-based alternatives. Manufacturers must reformulate product lines to maintain commercial viability across European procurement channels.
Growth Catalysts
- Suburban residential construction:North American single-family housing starts in Texas, Florida, and Arizona are driving specification of fiber cement and engineered wood panels for durability and fire resistance.
- REACH compliance pathways:ECHA restrictions on hazardous substance content are forcing coating reformulation investments that favor established suppliers with technical service capabilities.
- Panelized installation methods:Commercial developers in Germany and the Netherlands are specifying prefabricated envelope systems to compress construction schedules and reduce on-site labor exposure.
Market Restraints
- Pulp and cement input volatility:Fiber cement production depends on cellulose fiber and Portland cement, both subject to energy-linked price swings and carbon border adjustment exposure.
- Specialized applicator concentration:Certified installation networks for high-performance systems concentrate in Germany, France, and the UK, limiting rollout speed in Southern and Eastern Europe.
- Vinyl substitution ceiling:Cost-positioned vinyl cladding dominates volume segments where fire ratings and thermal performance requirements remain unenforced.
Strategic Opportunities
- Polish and Romanian retrofit markets:EU Recovery and Resilience Facility disbursements are unlocking public building envelope upgrades where insulated metal composite systems hold technical advantages.
- Integrated insulation-cladding convergence:Thermal bridge elimination requirements are creating specification pull for factory-bonded systems combining mineral wool or PIR with weather-resistant facings.
- Digital specification platforms:Building product libraries like BIMobject and NBS Source are compressing distributor influence and enabling direct manufacturer-to-architect technical engagement.
Industry Challenges
- Fire classification certification timelines:EN 13501-1 testing protocols and notified body queue lengths extend product launch cycles by 8-14 months for novel material formulations.
- Installer skill fragmentation:Panelized and rainscreen systems demand specialized envelope contractor capabilities that remain scarce outside established Western European construction clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wall Cladding Materials Market |
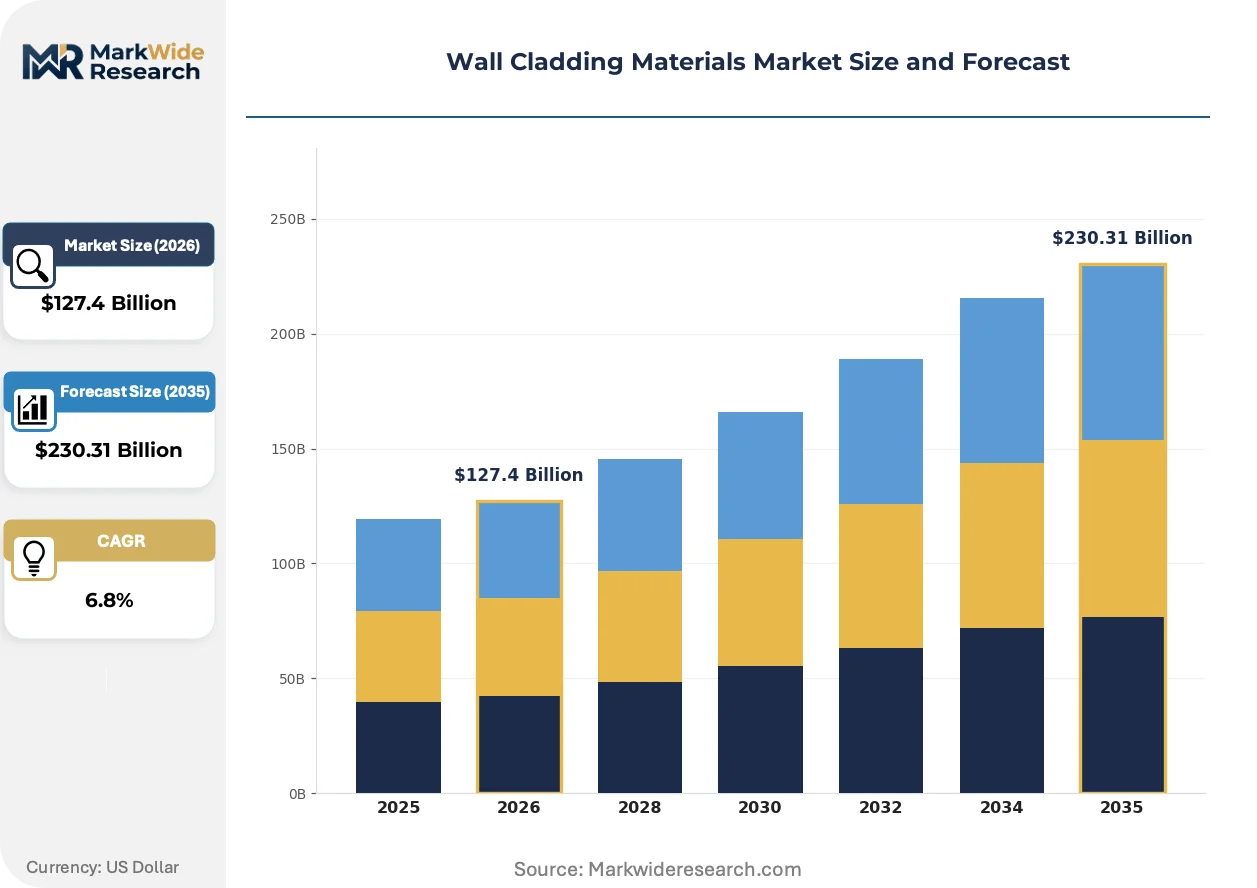
| Market Size in 2026 | $127.4 Billion |
| Market Size in 2035 | $230.31 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Brick, Stone, Wood, Vinyl Installation Method: Direct Attachment, Furring Strips, Clip System, Panelized End Use: Residential, Commercial, Industrial, Institutional Finish Type: Textured, Smooth, Painted, Laminated |
| Companies Covered | CertainTeed, Azek, James Hardie Industries, Tata Steel, UNIFLOOR, Saint-Gobain, Trex Company, Etex Group, Kingspan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wall Cladding Materials Market Evolving Landscape
Specification authority is migrating from general contractors to envelope consultants and sustainability officers, compressing traditional distribution influence. Three forces are restructuring competitive positioning across material categories and installation methods.
Prefabricated rainscreen subframe systems are overtaking conventional stick-built metal framing in commercial specifications above five stories. German and Dutch facade contractors are adopting unitized cassette systems that integrate cladding, insulation, and air barriers in factory conditions. This shift is compressing on-site labor requirements and compressing project risk profiles for developers facing skilled trades shortages.
REACH restrictions on chromium VI and formaldehyde content are eliminating coating chemistries that dominated European cladding markets through 2020. Manufacturers serving Germany, France, and Benelux markets are accelerating waterborne and UV-cured alternatives. The regulatory friction is most acute for small-batch custom color operations that lack capital for formulation redevelopment.
Architects and developers are unbundling cladding specification from general contractor procurement, establishing direct commercial relationships with system manufacturers. This pattern concentrates in UK and Scandinavian commercial projects where envelope performance guarantees carry contractual weight. Distributor margins are compressing as technical sales functions migrate in-house at James Hardie, Kingspan, and Saint-Gobain.
Wall Cladding Materials Market Segmentation
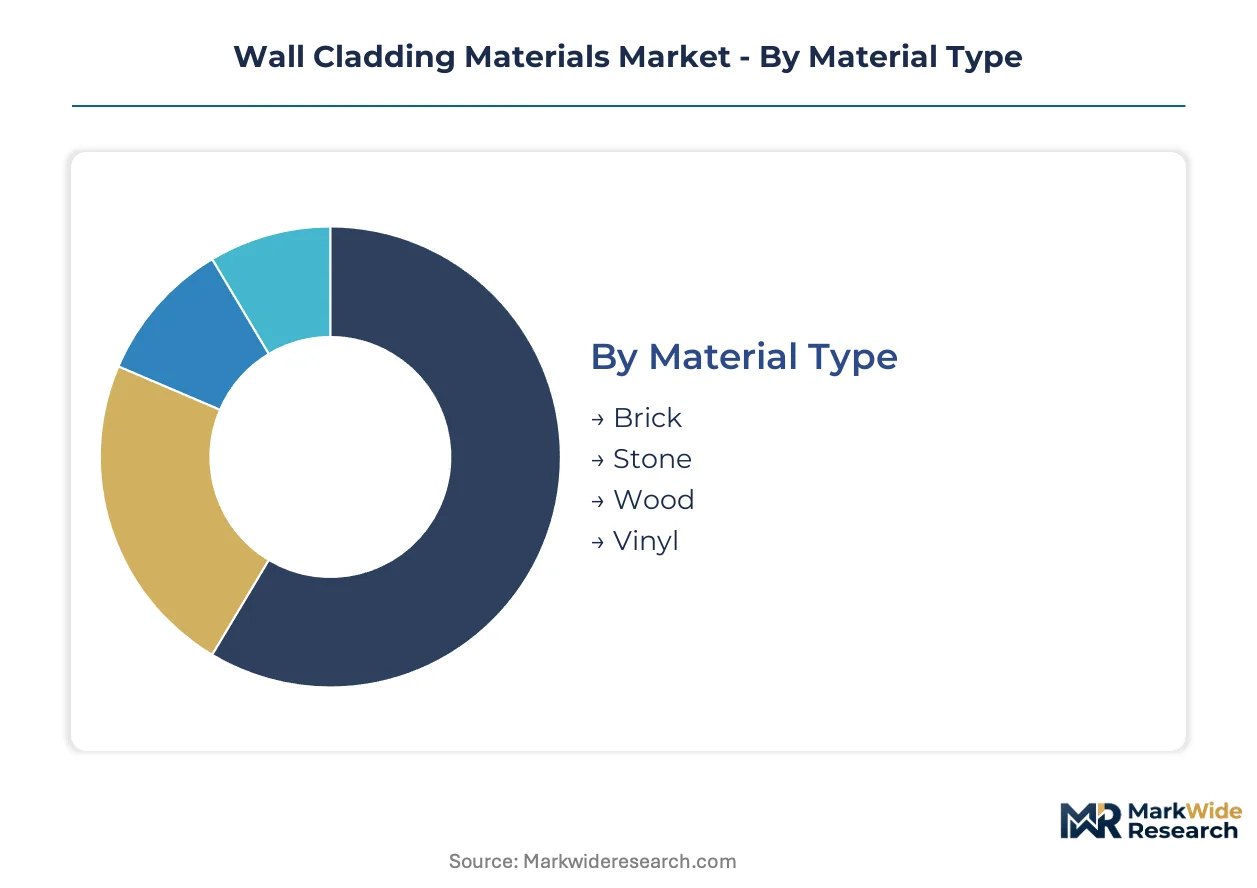
Cladding specification splits across material chemistry, structural attachment logic, and performance requirements. Buyers prioritize fire ratings, thermal bridging control, and installation speed when selecting across these dimensions. Each segmentation axis reveals distinct margin structures and competitive dynamics.
Material Type:
Cost-positioning and code compliance drive material selection, with fire-rated assemblies commanding premium specification in dense urban construction.
- Brick:Fired clay units deliver compressive strength and moisture resistance for load-bearing and veneer applications. Demand concentrates in German residential retrofits where heritage preservation codes and thermal bridge regulations favor masonry-veneer rainscreen systems.
- Stone:Natural granite, limestone, and slate provide durability and aesthetic permanence for institutional and high-end commercial facades. Specification clusters in UK and Scandinavian markets where envelope performance guarantees carry contractual weight and stone-anchored systems address stringent wind-load requirements.
- Wood:Engineered panels and treated lumber offer renewable carbon sequestration and design flexibility. Bio-based cladding gains traction in Austrian and Finnish projects pursuing carbon-negative envelope strategies.
- Vinyl:Polyvinyl chloride extrusions dominate North American residential volume through cost efficiency and color retention warranties. Cost-positioned specification persists where fire ratings remain unenforced by local codes.
Vinyl leads on scale; engineered wood leads on momentum.
Installation Method:
Labor availability and project schedule compression determine attachment system selection, with prefabrication gaining share in skilled-trades-constrained markets.
- Direct Attachment:Mechanical fastening directly to structural substrates minimizes material layers and system complexity. Application concentrates in US single-family residential construction where simplified installation reduces subcontractor coordination.
- Furring Strips:Pressure-treated or metal strapping creates drainage and ventilation cavities behind cladding faces. German facade contractors specify furring-based rainscreens to satisfy energy code thermal bridge elimination requirements.
- Clip System:Concealed aluminum or stainless steel brackets enable concealed fastening and thermal movement accommodation. High-rise commercial towers in London and Rotterdam adopt clip-anchored systems for wind-load distribution and maintenance access.
- Panelized:Factory-integrated cladding, insulation, and air barriers compress on-site labor exposure and construction schedules. Dutch and Belgian developers specify unitized cassettes to address envelope contractor scarcity and accelerate envelope closure.
Direct attachment leads on scale; panelized leads on momentum.
End Use:
Performance liability and procurement authority vary sharply across building types, with institutional buyers demanding extended warranties and certified installer networks.
- Residential:Single-family and multifamily housing prioritize cost efficiency, aesthetic variety, and moisture management. Suburban construction in Texas, Florida, and Arizona drives fiber cement and engineered wood specification for fire resistance and durability.
- Commercial:Office, retail, and hospitality facades balance brand expression with envelope performance guarantees. UK commercial developers establish direct manufacturer relationships to secure technical accountability.
- Industrial:Warehousing and manufacturing facilities demand weather resistance and minimal maintenance over extended service lives. Insulated metal composite systems serve Polish and Romanian logistics construction funded through EU Recovery and Resilience Facility disbursements.
- Institutional:Schools, hospitals, and government buildings impose fire classification, acoustic performance, and lifecycle cost scrutiny. French public procurement channels favor established suppliers with EN 13501-1 certification and technical service capabilities.
Residential leads on scale; institutional leads on momentum.
Finish Type:
Surface aesthetics and coating durability determine replacement cycles, with REACH restrictions eliminating legacy chemistries from European specification.
- Textured:Embossed or cast surfaces conceal substrate irregularities and provide shadow lines for visual depth. Fiber cement manufacturers leverage textured finishes to differentiate premium product tiers in North American distribution.
- Smooth:Planed or cast-flat surfaces enable contemporary aesthetic expression and simplified cleaning protocols. Scandinavian commercial projects specify smooth-faced panels to achieve minimalist design languages.
- Painted:Site-applied or factory-cured coatings deliver color customization and UV protection. Waterborne and UV-cured alternatives displace solvent-based systems under ECHA restrictions on hazardous substance content.
- Laminated:Film or foil surfacing bonds decorative layers to substrate cores for color consistency and scratch resistance. Laminated metal panels serve cold-chain and industrial applications requiring chemical resistance and rapid fabrication.
Painted leads on scale; laminated leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wall cladding manufacturing originated in European masonry traditions before industrial-scale fiber cement and metal panel production emerged in Germany and the United States during the early twentieth century. Contemporary demand patterns reflect this bifurcated heritage, with specification authority concentrated in mature construction markets where envelope performance codes have hardened.
United States
Suburban single-family construction in Texas, Florida, and Arizona drives fiber cement specification for fire resistance and hurricane durability. The EPA's Lead Renovation, Repair and Painting Rule shapes remediation protocols for existing cladding replacement across residential stock. Dallas-Fort Worth and Phoenix construction clusters concentrate demand for engineered wood and vinyl systems in volume housing developments.
Germany
Stringent building energy codes and thermal bridge elimination requirements pull premium cladding retrofits in multifamily and commercial envelopes. The EU Green Deal's embodied carbon thresholds compress specification windows for conventional systems while favoring lower-carbon alternatives. Bavarian and North Rhine-Westphalian facade contractors dominate certified installation networks for high-performance rainscreen assemblies.
United Kingdom
Post-Grenfell regulatory reforms mandate stricter fire classification for exterior wall systems in residential buildings above 18 meters. UK commercial developers establish direct manufacturer relationships to secure envelope performance guarantees with contractual weight. London and Southeast construction markets concentrate specification of unitized panelized systems for accelerated envelope closure.
China
GB standards for building energy efficiency impose thermal performance minimums that favor insulated composite systems in new commercial and residential construction. Provincial governments in Jiangsu and Zhejiang enforce green building assessment standards that elevate specification of factory-bonded insulation-cladding combinations. Yangtze River Delta manufacturing clusters supply metal composite and fiber cement panels across domestic and export markets.
Poland
EU Recovery and Resilience Facility disbursements unlock public building envelope upgrades where insulated metal composite systems hold technical advantages for thermal performance and installation speed. Polish logistics construction funded through EU programs concentrates demand for rapid-enclosure industrial facades. Warsaw and Krakow metropolitan areas anchor specification networks for panelized commercial systems.
Wall Cladding Materials Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material chemistry and certification complexity, with fire-rated and thermally integrated systems commanding specification premiums. The vendor base spans multinational building materials conglomerates, regional specialists in single material categories, and integrated envelope system providers. Three archetypes dominate: integrated insulation-cladding convergers, fiber cement technology leaders, and metal panel scale operators. Competitive moves concentrate on backward integration into mineral wool and PIR core production, plus geographic expansion of certified installer networks into Eastern European markets.
Within the integrated systems tier, Saint-Gobain and Kingspan Group exemplify the convergence archetype combining thermal insulation with weather-resistant facings. James Hardie Industries occupies a position representing fiber cement technology leadership in markets where fire-rated assemblies carry regulatory weight. Among metal panel specialists, Tata Steel anchors the scale-driven segment serving industrial and cold-chain applications through controlled distribution networks.
| Leading Market Players |
|---|
| CertainTeed |
| Azek |
| James Hardie Industries |
| Tata Steel |
| UNIFLOOR |
| Saint-Gobain |
| Trex Company |
| Etex Group |
| Kingspan Group |
| Others |
Value Network & Pricing Analysis
Commercial envelope contractors in Germany and the Netherlands anchor procurement volume for premium rainscreen systems, concentrating specification authority with buyers who negotiate project-based pricing tied to installation speed guarantees and thermal performance warranties. This buyer concentration rewards manufacturers with certified installer networks and compresses margins for commodity-grade suppliers lacking technical service capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates fire-rated fiber cement assemblies from vinyl cladding and basic metal panels. Price differentiation hinges on EN 13501-1 certification grade and factory-integrated insulation bonding. Cost compression in economy tiers is intensifying because pulp and cement input volatility erodes producer margins. Residential developers in North American volume housing remain most price-sensitive; institutional buyers in France and the UK exhibit lowest sensitivity due to lifecycle cost scrutiny and performance liability requirements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese mineral wool core production and German specialty coating formulation. Manufacturing draws from cellulose fiber suppliers in North America, Portland cement producers in Germany and Poland, and aluminum coil rollers in China and South Korea. Tariff exposure on Chinese aluminum and mineral wool inputs threatens cost stability for European panelized system assemblers. Distribution runs through facade contractor networks in Western Europe and building materials distributors in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in wall cladding materials rests on the shift toward factory-integrated insulation-cladding systems that capture premium specification while input cost volatility squeezes commodity-grade competitors. Panelized installation methods compress on-site labor exposure and accelerate project completion, rewarding suppliers with captive production of thermal cores and weather-resistant facings.
For Market Incumbents: Anticipate specification authority migration toward envelope consultants by building direct technical sales capabilities and BIM-compatible product libraries. Defensive consolidation moves should prioritize backward integration into mineral wool and PIR core production to secure thermal bridge elimination compliance, plus geographic expansion of certified installer networks into Polish and Romanian markets where EU Recovery and Resilience Facility disbursements unlock public building envelope upgrades.
For New Entrants and Emerging Players: Facade contractor partnerships in the Netherlands and Belgium offer the most penetrable channel for unitized cassette system introduction. White-space targets include Austrian and Finnish bio-based cladding projects pursuing carbon-negative envelope strategies, plus Polish logistics construction funded through EU programs. A go-to-market angle emphasizing rapid envelope closure and reduced skilled trades exposure differentiates against established stick-built metal framing suppliers.
For Investors and Strategic Acquirers: Building materials conglomerates with insulation-cladding convergence capabilities are the most active acquirer in this space, seeking targets with EN 13501-1 certification and Eastern European installer network presence. Long-term viability over a multi-year horizon favors integrated system providers over single-material commodity producers. The signal to watch is EU Green Deal embodied carbon threshold tightening, which would accelerate substitution toward lower-carbon fiber cement and bio-based alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Wool Core Production | Captive thermal insulation supply secures thermal bridge elimination compliance for German energy code retrofits. |
| Certified Installer Network Expansion | Geographic extension into Poland and Romania captures EU Recovery and Resilience Facility-funded public building upgrades. |
| Digital Specification Platform Integration | BIMobject and NBS Source presence compresses distributor influence and enables direct architect engagement. |
| Waterborne Coating Formulation Transition | REACH-compliant alternatives to chromium VI and formaldehyde-based systems maintain European market access. |
| Unitized Panelized System Development | Factory-integrated cladding-insulation-air barrier combinations address Dutch and Belgian skilled trades shortages. |
Research Methodology
Bottom-up residential and commercial construction modeling reconciled against top-down fiber cement and metal panel production tracking forms the analytical core. Primary interviews with facade contractors, envelope consultants, building materials procurement managers, and sustainability officers combined with secondary validation from ECHA regulatory filings, EU Recovery and Resilience Facility disbursement records, and national building energy code databases. Trade data from German and Chinese customs authorities, plus SEC 10-K disclosures from listed building materials conglomerates, provided supply-side triangulation.
Historical trendline analysis of cladding material specification patterns across material chemistry, installation method, and end-use segments informed projection frameworks. Segmentation dimensions modeled include material type, structural attachment logic, finish chemistry, and regional regulatory cluster. CAGRs were derived through regression analysis of construction output correlations and material substitution elasticity. Forecast inputs incorporated EU Green Deal embodied carbon threshold trajectories and REACH restriction implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment mechanisms and pulp-cement input price volatility. Forecasts reflect assumptions about regulatory enforcement consistency, certified installer network expansion rates, and panelized system adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Composite Coatings Market
Composite Materials
Graphite Carbon Raiser Market
Composite Materials
Composite Rollers Market
Composite Materials
Composite Drums Market
Composite Materials
Composite Metal Finishing Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Composite Cans Market
Composite Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market
Composite Materials
Global FRP Vessels Market
Composite Materials
Acrylic Laminates Market
Composite Materials
Composite Market
Composite Materials
Isostatic Graphite Market
Composite Materials
Low Temperature Sealing Glass Composite Powder Market
Composite Materials
Tow Prepreg Market
Composite Materials
Transportation Composites Market
Composite Materials
Composite Process Material Kits Market