
 Global Aluminum Extruded Products Market | 2026-2036
Global Aluminum Extruded Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aluminum Extruded Products Market Intelligence
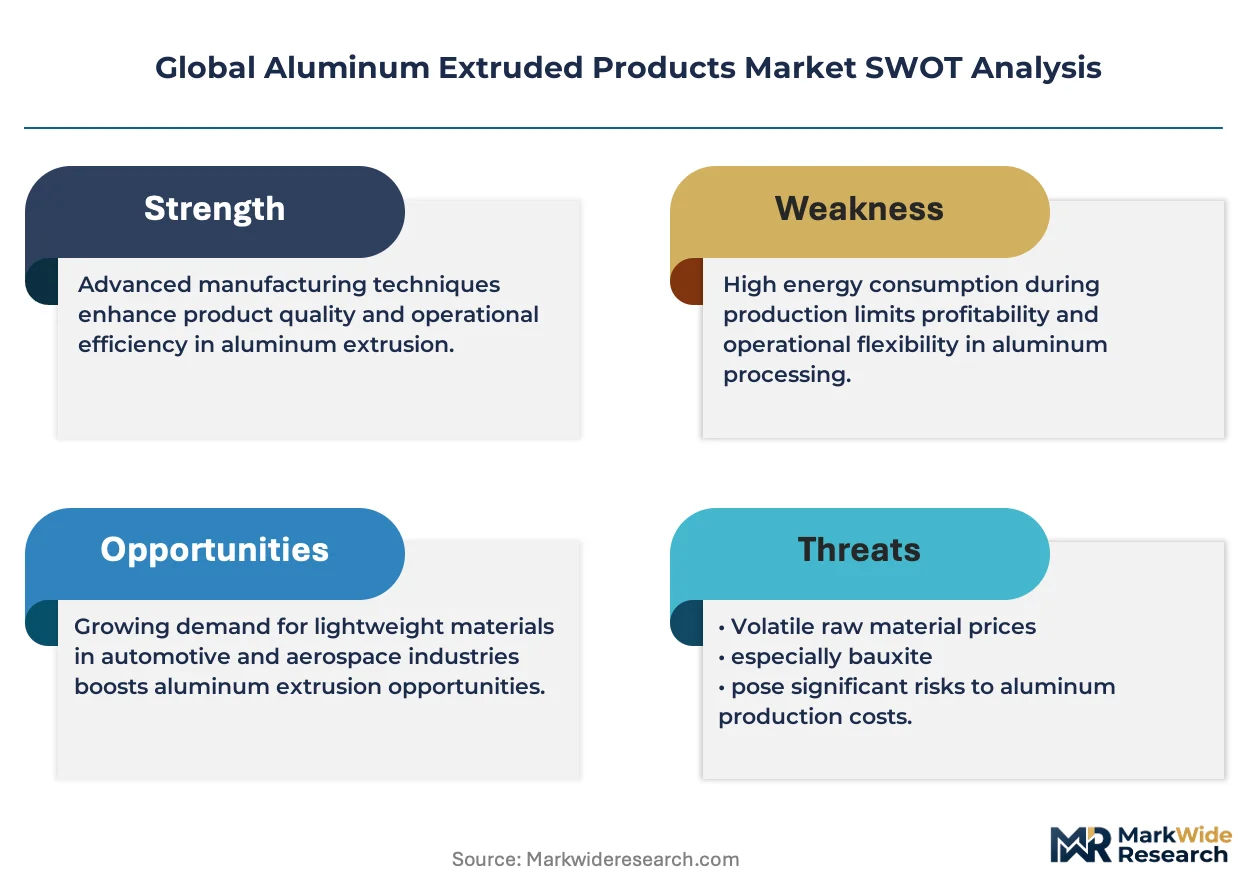
Custom design and engineering support services are pivoting the transaction from a simple material sale to a collaborative partnership. Norsk Hydro ASA leverages its significant investment in low-carbon aluminum production to attract sustainability-focused clients. Constellium N.V. specializes in high-strength alloys for the demanding aerospace sector. Meanwhile, China Zhongwang Holdings Limited dominates the Asian market through immense production scale.
Aluminum extruded products are shapes created by forcing heated aluminum alloy billets through a die of a specific cross-sectional profile. This process yields components with an excellent strength-to-weight ratio, crucial for structural applications. Profiles represent the largest product type segment due to their versatility in construction and industrial framing. Within end-use industries, automotive applications are showing rapid expansion, while construction remains the foundational volume driver.
Product quality and market access are governed by multiple standards, including the EU's CE marking for construction products and China's mandatory GB standards for material specifications. These regulations ensure structural integrity and safety across applications from buildings to transportation. Navigating the complex and often divergent regional standards for recycled content and carbon footprint reporting is a critical strategic challenge for suppliers.
Market Dynamics
The market's central dynamic is the collision between decarbonization mandates and material science. Regulatory pressure from frameworks like the EU Green Deal and the US Inflation Reduction Act is accelerating the substitution of steel with aluminum in automotive and industrial applications to reduce weight and emissions.
Growth Catalysts
- Electric Vehicle Transition:The automotive sector's pivot to electric vehicles, which require lightweight frames and battery enclosures to extend range, provides a primary demand driver for aluminum extrusions.
- Sustainable Construction:Green building codes and architectural trends favor aluminum profiles for their recyclability, durability, and design flexibility in energy-efficient curtain walls, windows, and solar panel mounting systems.
- Chinese Industrial Policy:China's national policies, including its dual carbon goals, are pushing its vast construction and transportation manufacturing industries towards greater adoption of less energy-intensive and lighter materials like aluminum.
Market Restraints
- Energy and Input Cost Volatility:The extrusion process is energy-intensive, and profitability is highly sensitive to fluctuations in electricity prices and the primary aluminum ingot price on the London Metal Exchange (LME).
- Substitution from Advanced Materials:In certain high-stress applications within aerospace and performance vehicles, advanced high-strength steels and carbon fiber composites present a persistent substitution threat to aluminum alloys.
- Geopolitical Supply Concentration:A significant portion of global primary aluminum smelting and extrusion capacity is located in China, creating potential supply chain vulnerabilities related to trade policy and regional disruptions.
Strategic Opportunities
- Renewable Energy Infrastructure:The global build-out of solar and wind energy presents a significant opportunity, as aluminum extrusions are critical components for solar panel frames and structural elements in wind turbines.
- Advanced Alloy Development:Investment in research and development for new high-strength, corrosion-resistant, and easily recyclable aluminum alloys can unlock new applications in marine, defense, and aerospace sectors.
- Circular Economy Models:Developing closed-loop recycling systems and increasing the use of post-consumer scrap can create a cost advantage and meet growing customer demand for products with a lower carbon footprint.
Industry Challenges
- Carbon Footprint Verification:A key operational challenge is navigating the complex and divergent regional standards for calculating, verifying, and reporting the carbon footprint of products, a process critical for market access in regions like the EU.
- Modernization of Assets:The high capital expenditure required to upgrade aging extrusion presses and integrate digital process controls limits the ability of smaller players to compete on efficiency and product complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aluminum Extruded Products Market |
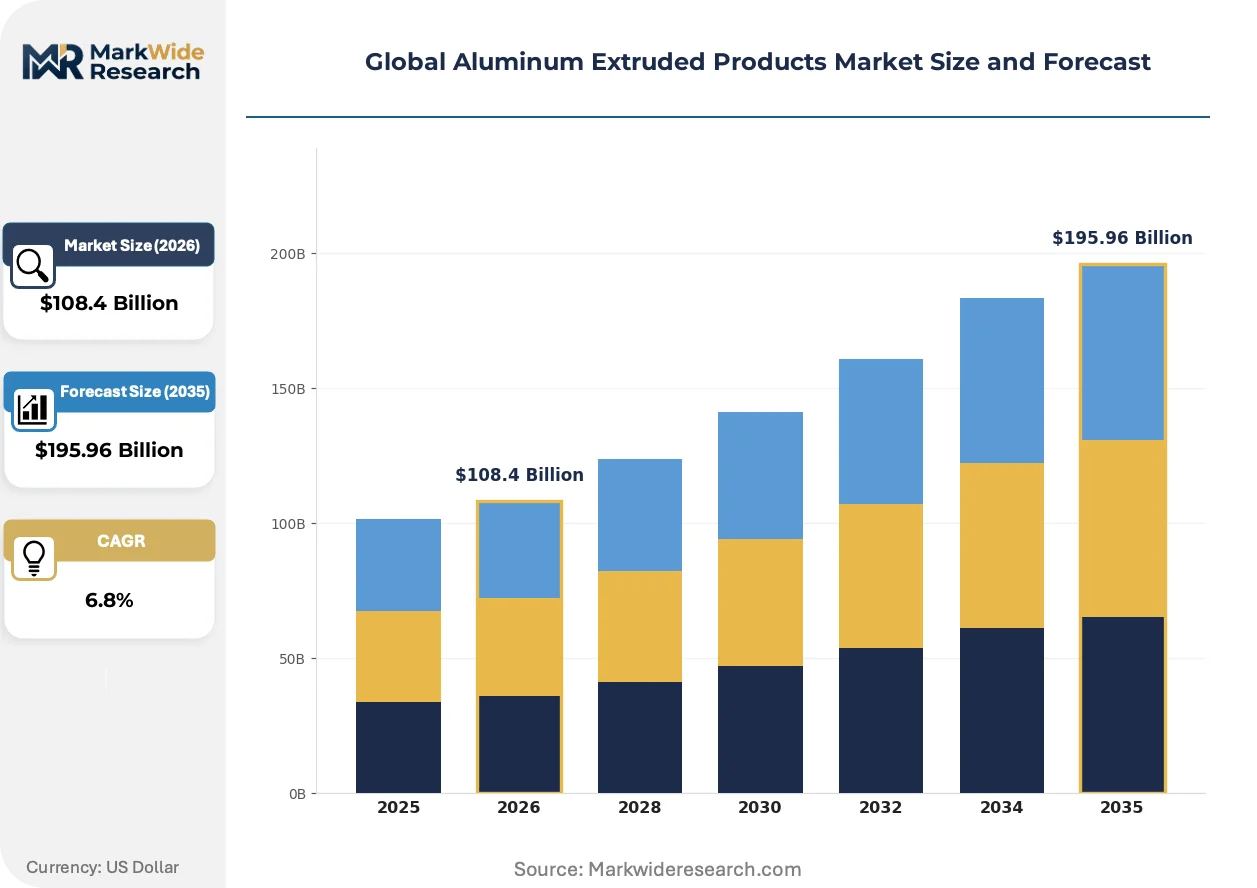
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $195.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Rods, Tubes, Profiles End Use Industry: Aerospace, Automotive, Construction, Electrical Grade: 6061, 6063, 6005, 7075 Form: Solid, Hollow, Anodized, Coated |
| Companies Covered | Norsk Hydro ASA, Hindalco Industries Ltd., Constellium N.V., Alcoa Corporation, Kaiser Aluminum, Arconic Corp., China Zhongwang Holdings Limited, Jindal Aluminum Limited, ALUPCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aluminum Extruded Products Market Strategic Shifts & Innovations
The industry's evolution is defined by the convergence of material science and sustainability imperatives. Innovations are focused on reducing the embodied carbon of products while simultaneously enhancing their performance characteristics to meet the demands of advanced manufacturing sectors.
Low-carbon primary aluminum, produced using renewable energy sources like hydropower, is a key product evolution. Automotive and construction specifiers are increasingly demanding this material to help meet their own corporate sustainability goals. This shift is rewriting the value proposition from a simple price-per-kilogram basis to a more complex calculation involving carbon content and lifecycle performance.
The European Union's Carbon Border Adjustment Mechanism (CBAM) is a pivotal regulatory development. This policy imposes a tariff on imported goods, including aluminum, based on their embedded carbon emissions, directly impacting trade flows. Producers using low-carbon energy sources gain a significant competitive advantage in the European market over those reliant on fossil fuels.
A fundamental change in purchasing behavior is the move toward requiring certified material traceability. This disrupts traditional procurement models by prioritizing suppliers who can provide verified Environmental Product Declarations (EPDs) and proof of recycled content. The trend is most visible in the building and construction industry, where it is driven by green building certification schemes.
Global Aluminum Extruded Products Market Segmentation
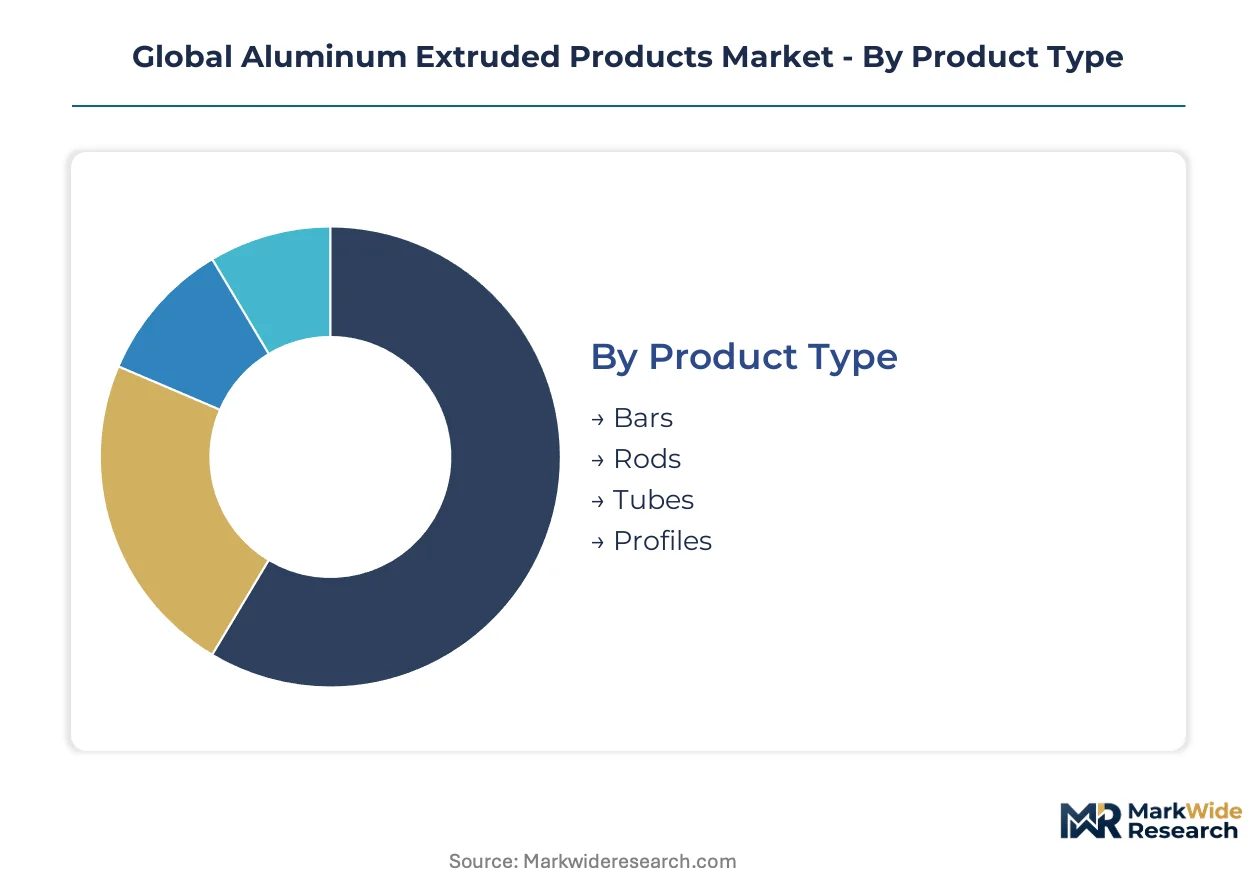
The Global Aluminum Extruded Products market is dissected into distinct segments, each driven by unique material specifications, processing requirements, and end-use applications. Understanding these segments is crucial for identifying areas of concentrated demand and specialized manufacturing capabilities across the value chain.
Product Type:
The production of various aluminum extruded product types often concentrates around specialized manufacturing capabilities, influencing regional supply dynamics.
- Profiles:These are custom-designed shapes with complex cross-sections, offering exceptional strength-to-weight ratios and design flexibility. Demand is concentrating in construction for architectural systems and in automotive for structural components in electric vehicles across Europe.
- Tubes:Characterized by their hollow cross-sections, these products offer precise internal and external dimensions, crucial for fluid transfer and lightweight structural applications. Demand is strong in the automotive sector for cooling systems and in construction for lightweight framing in China.
- Bars:Solid, rectilinear forms primarily used as raw material for machining, structural support, and general engineering purposes.
- Rods:Typically solid round or hexagonal shapes, these products find application in fasteners, electrical conductors, and various mechanical parts.
Profiles absorb the bulk of installed capacity due to their versatility; Tubes are expanding most quickly in automotive applications.
End Use Industry:
Each end-use industry segment exhibits distinct material requirements and demand drivers for aluminum extruded products.
- Automotive:This sector demands lightweight, high-strength alloys for vehicle frames, battery enclosures, and crash management systems, essential for improving fuel efficiency and extending EV range. Demand is concentrating in Germany and the United States, driven by stringent emissions regulations and EV production targets.
- Construction:This industry utilizes aluminum extrusions for windows, doors, curtain walls, and structural elements, valuing their durability, recyclability, and aesthetic appeal. Demand is significant in urban development projects across China and India, focusing on sustainable building practices.
- Aerospace:Requires specialized high-strength, fatigue-resistant aluminum alloys for aircraft fuselage components, wings, and internal structures.
- Electrical:Aluminum extrusions are used for busbars, heat sinks, and conduit, leveraging the material's excellent electrical conductivity and thermal dissipation properties.
Construction continues to represent the largest volume segment; Automotive applications are climbing the fastest.
Grade:
Specific aluminum grades are selected based on their distinct mechanical properties and suitability for various performance demands.
- 6061:This grade offers medium-to-high strength, good weldability, and excellent corrosion resistance, making it a versatile choice for structural components. Demand is concentrating in industrial machinery and transportation applications across the United States.
- 7075:Known for its very high strength-to-weight ratio, this grade is comparable to many steels and is critical for demanding structural applications. Demand is particularly high in aerospace and defense sectors in France and the UK.
- 6063:Features good surface finish, extrudability, and corrosion resistance, widely used for architectural extrusions, window frames, and decorative trim.
- 6005:Offers a balance of good strength, extrudability, and corrosion resistance, making it suitable for automotive and rail components.
The 6061 grade remains a foundational choice for general engineering; the 7075 grade exhibits the steepest expansion trajectory in specialized sectors.
Form:
The form of aluminum extruded products often dictates their final application and required post-processing.
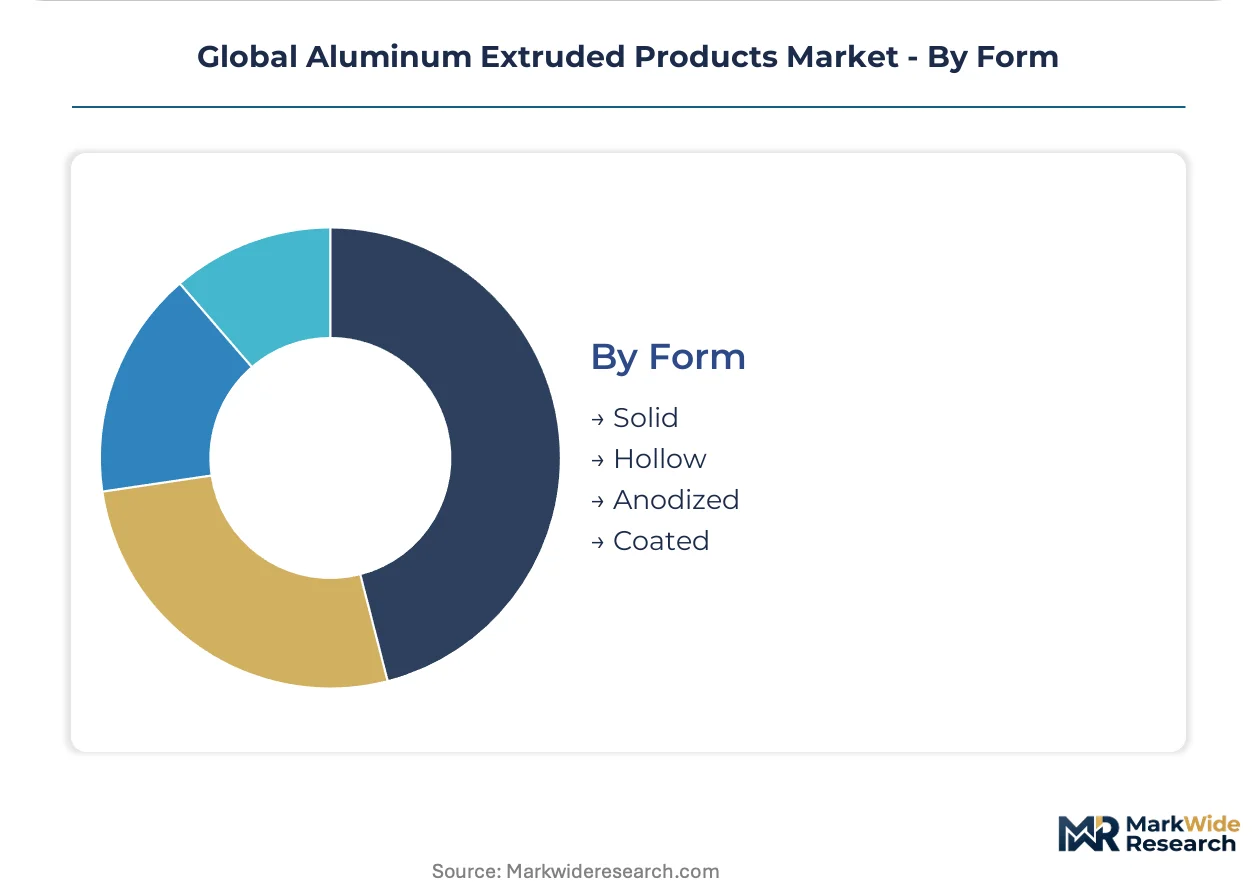
- Solid:These extrusions possess a uniform cross-section without internal voids, providing maximum material density and strength. Demand is concentrating in heavy industrial equipment and structural supports within manufacturing facilities in China.
- Anodized:This form undergoes an electrochemical process to create a durable, corrosion-resistant, and aesthetically pleasing oxide layer on the surface. Demand is significant in architectural facades and consumer electronics in Germany.
- Hollow:Characterized by an internal cavity, these forms are crucial for fluid transfer, lightweight structural elements, and energy absorption components.
- Coated:Involves applying a protective or decorative layer, such as paint or powder, to enhance durability, appearance, and specific functional properties.
Solid forms represent a consistent baseline for industrial use; Anodized products are gaining share fastest in premium architectural projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's expansive manufacturing base drives significant demand for aluminum extruded products. This urban center, along with other industrial zones, fuels construction and automotive sector growth. Global demand for these lightweight materials spans diverse geographies.
China
China's vast construction and transportation manufacturing industries drive substantial demand for aluminum extrusions. The national dual carbon goals push for lighter, more energy-efficient materials in these sectors. Major industrial hubs like the Yangtze River Delta concentrate production and consumption for building materials and EV components.
Germany
Germany's automotive sector, particularly EV production, requires high-strength aluminum extrusions for frames and battery enclosures. The EU Green Deal further accelerates material substitution in industrial applications. Stuttgart, a major automotive hub, sees concentrated development of advanced aluminum solutions for next-generation vehicles.
United States
The United States' industrial machinery and transportation sectors utilize robust aluminum extrusions for structural components. The US Inflation Reduction Act encourages domestic manufacturing and sustainable material adoption. Detroit's automotive cluster focuses on integrating lightweight aluminum into electric vehicle platforms.
France
French aerospace and defense sectors exhibit strong demand for high-strength aluminum alloys like 7075 for critical structural parts. European standards, including CE marking for construction products, ensure material quality and safety. Toulouse, a primary aerospace center, drives innovation in advanced alloy applications for aircraft manufacturing.
India
India's rapid urban development and infrastructure projects create substantial demand for aluminum profiles in sustainable building. National policies supporting smart cities and green construction promote durable, recyclable materials. Major metropolitan areas like Mumbai are experiencing high consumption for architectural systems and industrial framing.
Global Aluminum Extruded Products Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the aluminum extruded products market. The industry exhibits a tiered structure, from large integrated primary aluminum suppliers to specialized extruders focusing on complex profiles. Strategic archetypes include global diversified material suppliers, regional market leaders, and niche high-performance alloy developers. Companies frequently engage in capacity expansion and advanced alloy development to secure market position and address evolving client needs.
Among scale-driven manufacturers, Norway's Norsk Hydro ASA represents a player with significant investment in low-carbon aluminum production, attracting sustainability-focused clients. China Zhongwang Holdings Limited exemplifies immense production capabilities, dominating the Asian market through its vast operational scale. France-based Constellium N.V. occupies a position among specialists in high-strength alloys, particularly catering to demanding sectors like aerospace with advanced material solutions. These entities reflect the diverse operational models and strategic focuses within the global landscape, from sustainable sourcing to specialized performance.
| Leading Market Players |
|---|
| Norsk Hydro ASA |
| Hindalco Industries Ltd. |
| Constellium N.V. |
| Alcoa Corporation |
| Kaiser Aluminum |
| Arconic Corp. |
| China Zhongwang Holdings Limited |
| Jindal Aluminum Limited |
| ALUPCO |
Cost & Logistics Intelligence
The EU Green Deal's mandates for low-carbon materials are forcing aluminum extrusion suppliers to invest in sustainable production, influencing material costs and procurement decisions for end-use industries.
Pricing Analysis
Cost-down pressure on standard aluminum profiles accelerates because of immense production scale, particularly from China Zhongwang Holdings Limited. Pricing primarily follows a commodity spot model for basic products, but contract-based long-term offtake agreements secure supply for major automotive OEMs. Price differentiation stems from CE marking certification and the level of custom engineering support. Construction buyers exhibit the highest price sensitivity, while aerospace clients prioritize performance over cost.
Supply Chain Analysis
Elevated logistics and freight costs impact the delivered price of aluminum extrusions, especially for intercontinental shipments. Global supply concentrates significantly in China, alongside specialized production clusters in Germany and the United States. The industry relies on primary aluminum ingot and advanced alloy inputs, making it vulnerable to London Metal Exchange (LME) price volatility. Distribution runs through direct sales channels for large automotive and construction projects, while regional distributors serve smaller industrial fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a supply-constrained story, where specialized extrusion capacity for high-strength alloys creates bottlenecks, propping up pricing for demanding applications like aerospace.
For Market Incumbents: Deploy advanced alloy R&D to counter substitution from carbon fiber composites in performance vehicles. Norsk Hydro ASA should invest in low-carbon production capacity in Europe to meet EU Green Deal mandates. This strategy defends market share against emerging sustainable material trends and addresses carbon footprint reporting requirements.
For New Entrants and Emerging Players: Digital manufacturing and additive extrusion technologies offer a wedge into rapid prototyping for custom profiles in industrial machinery. Target the underpenetrated small-to-medium enterprise segment in India's construction sector with flexible, localized production. A go-to-market angle focusing on design flexibility and faster lead times can differentiate new players.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized, vertically integrated extruders given the accelerating demand for high-strength alloys in electric vehicles. Long-term viability favors firms with certified low-carbon production capabilities and robust recycling infrastructure. Acquisition targets should be mid-cap players possessing proprietary alloy formulations or strong regional market access in Germany. Watch for increasing regulatory enforcement of CBAM as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Low-Carbon Extrusion | Secures competitive advantage for sustainability-focused clients in Europe seeking certified materials. |
| Advanced Alloy Development for EVs | Unlocks new applications in lightweight vehicle frames and battery enclosures for automotive OEMs. |
| Closed-Loop Recycling System Implementation | Reduces raw material costs and meets growing customer demand for circular economy products. |
| Geographic Manufacturing Footprint Diversification | Mitigates geopolitical supply chain risks from concentrated production in specific regions. |
| Digital Process Control Integration | Improves operational efficiency and enables production of complex, custom profiles with precision. |
Research Approach
EU Green Deal policy documents, LME market reports, and national automotive industry association data formed the secondary backbone for this analysis. Primary interviews with extrusion plant managers, automotive procurement leads, and construction material specifiers validated market dynamics. This approach combined top-down market sizing with bottom-up validation to ensure data integrity.
A bottom-up approach aggregated demand across key end-use industries like automotive and construction, while a top-down validation assessed overall market potential throughout the forecast period. Segmentation dimensions included product type, end-use industry, and aluminum grade. Compound annual growth rates were derived from historical trends and projected technological shifts. Electric vehicle production targets and green building certifications served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant geopolitical trade disruptions or drastic LME price swings. This analysis reflects assumptions regarding regulatory stability and material science advancements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Copper and Copper Alloy Scrap and Recycling Market
Metals
Neodymium Market
Metals
Aluminum Scrap Recycling Market
Metals
Qatar Metalworking Market
Metals
Global Duplex Stainless Steel Market
Metals
Global Titanium Metal Market
Metals
Tinplate Market
Metals
Bismuth Market
Metals
Carbon Steel Market
Metals
Global Vanadium Market
Metals
Copper Clad Aluminum Wire Market
Metals
Prebaked Anodes for Aluminum Market
Metals
Ferro Vanadium Market
Metals
Global Oxygen-Free Copper Market
Metals
Copper Powder Market
Metals
Carbotanium Market