
 Acrylic Laminates Market | 2026-2036
Acrylic Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Laminates Market Outlook
ISO 4586 qualification for decorative high-pressure laminates is bifurcating the competitive landscape into certified mass producers and uncertified regional suppliers. Arpa Industriale S.p.A. leverages its Italian manufacturing base to dominate European specification channels for premium decorative sheets. Stylam Industries Limited anchors South Asian supply through integrated resin-to-laminate production in India. FunderMax GmbH differentiates via specialized exterior-grade acrylic surfaces for commercial facades.
Acrylic laminates are thermosetting composite surfaces formed by impregnating decorative paper with melamine and acrylic resins, then pressing onto substrates under heat and pressure exceeding 7 MPa, yielding scratch-resistant finishes for interior applications. Decorative sheets command the deepest specification margins in commercial projects, while high-pressure laminates sustain volume leadership across residential countertops and furniture. Solid surface acrylics are gaining fastest in healthcare and laboratory partitions where seamless hygiene standards apply.
REACH registration in Europe and evolving GB standards under China's SAMR framework constrain raw material sourcing and cross-border formulation compliance for acrylic resin suppliers. India's BIS certification for decorative laminates is tightening market access for uncertified imports while rewarding domestic manufacturers with PLI scheme incentives. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
ISO 4586 qualification requirements are bifurcating the acrylic laminates competitive landscape into certified mass producers and uncertified regional suppliers, reshaping procurement patterns across commercial interior fit-outs and modular furniture manufacturing.
Growth Catalysts
- Commercial Interior Fit-outs:Office renovation cycles and hospitality refurbishment projects in India and China are accelerating specification of decorative acrylic surfaces for wall cladding and reception areas.
- REACH Registration:European ECHA compliance mandates are forcing raw material transparency that rewards qualified suppliers with preferred vendor status in EU specification channels.
- Modular Furniture Manufacturing:India's PLI scheme incentives for domestic laminate production are concentrating new capacity in Panipat and Morbi industrial clusters.
Market Restraints
- Acrylic Resin Price Volatility:Petrochemical feedstock fluctuations and MMA monomer supply concentration in Northeast Asia create margin compression for decorative sheet producers.
- Technical Limitation:Thermosetting acrylic surfaces cannot be thermoformed post-curing, restricting application in complex curved furniture designs that solid surface competitors capture.
- Substitution Threat:Sintered stone and ultra-compact surfaces are displacing high-pressure laminates in premium countertop specifications above $80 per square meter.
Strategic Opportunities
- Healthcare Infrastructure:Seamless hygiene requirements in hospital and laboratory partitions are opening specification channels for solid surface acrylics in Germany and Japan.
- India BIS Certification:Tightening import standards under Bureau of Indian Standards IS 2046 are creating protected market space for domestic manufacturers with integrated resin-to-laminate operations.
- Digital Print Integration:UV-curable inkjet decoration convergence with high-pressure lamination is enabling mass customization for hospitality and retail interior projects.
Industry Challenges
- Skilled Press Operator Shortage:Multi-daylight hydraulic press calibration and resin impregnation line management require specialized technicians that Southeast Asian manufacturing clusters struggle to retain.
- ISO 4586 Qualification Timeline:Accelerated aging tests and fire resistance certification cycles extend new product introduction lead times by 14-18 months for European specification markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Laminates Market |
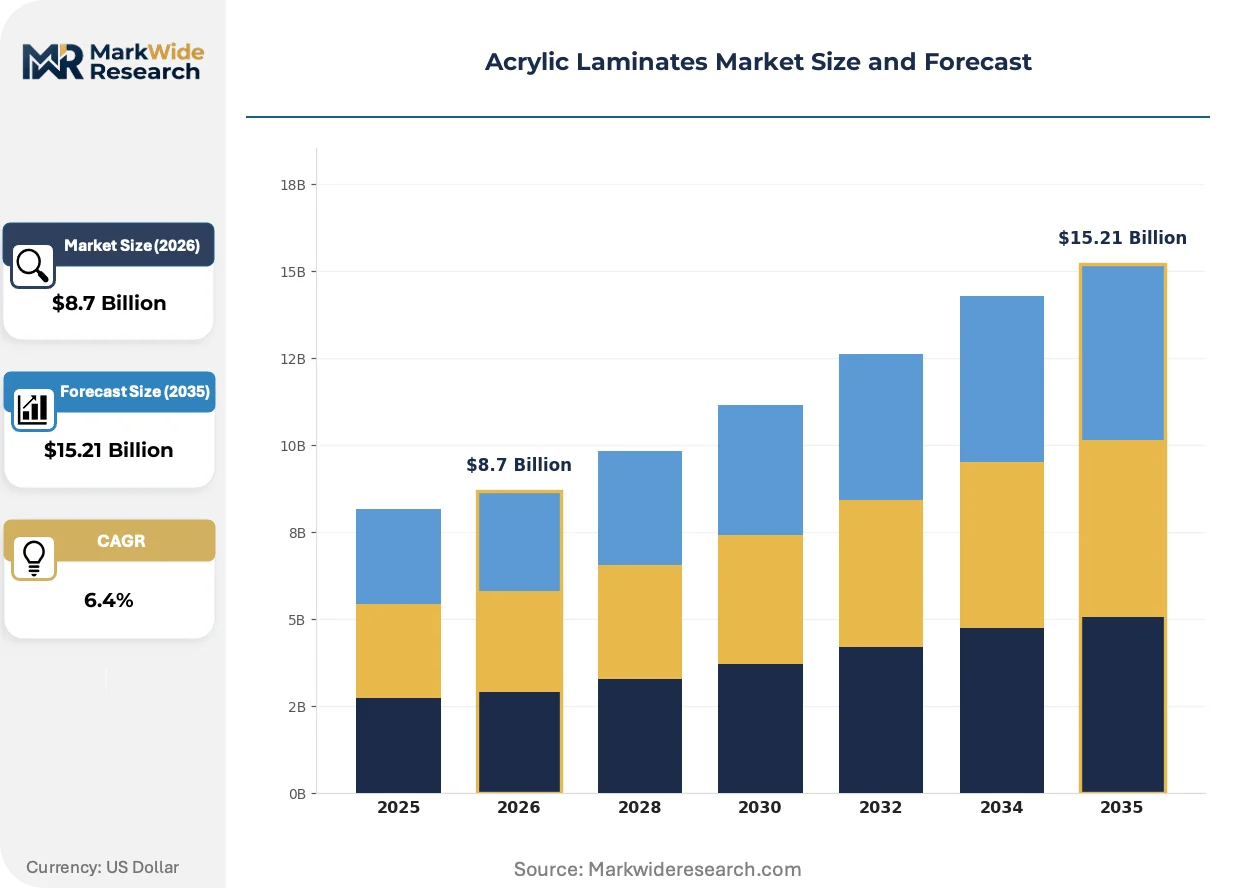
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Surface, Decorative Sheets, High-Pressure Laminates, Low-Pressure Laminates End Use: Residential, Commercial, Automotive, Industrial Application: Countertops, Wall Panels, Furniture, Partitions Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Arpa Industriale S.p.A., Stylam Industries Limited, Meraki PVC, FunderMax GmbH, Merino Laminates, Abet Laminati S.p.A., Panolam Industries International, Royal Crown Laminates, Greenlam Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Laminates Market Strategic Shifts
Surface engineering and regulatory compliance are converging to redefine competitive advantage in decorative laminates, with digital manufacturing and material transparency emerging as the dominant axes of differentiation.
Digital inkjet decoration is decomposing the traditional gravure-printed paper supply chain in decorative laminate production. Hospitality designers and retail fixture manufacturers are adopting UV-curable printed surfaces for short-run customization and rapid pattern iteration. This technology is decomposing minimum order quantity constraints that previously locked small and mid-sized interior projects out of premium decorative specifications.
China's SAMR framework is tightening GB standards for formaldehyde emission and surface wear resistance in decorative laminates used in public buildings. Domestic manufacturers in Guangdong and Zhejiang provinces are reformulating melamine-acrylic resin ratios to meet Grade E0 thresholds. Export-oriented suppliers are dual-certifying production lines to maintain access to both domestic construction projects and European specification channels.
Specification-driven procurement is consolidating buying power among large interior design firms and furniture OEMs, compressing distributor margins and accelerating direct manufacturer relationships. Tier-one commercial fit-out contractors in Mumbai and Bangalore are bypassing traditional stockist networks to source certified laminates directly from integrated producers. This pattern is most visible in India's western and southern states where modular office and co-working space construction is concentrating demand.
Acrylic Laminates Market Segmentation
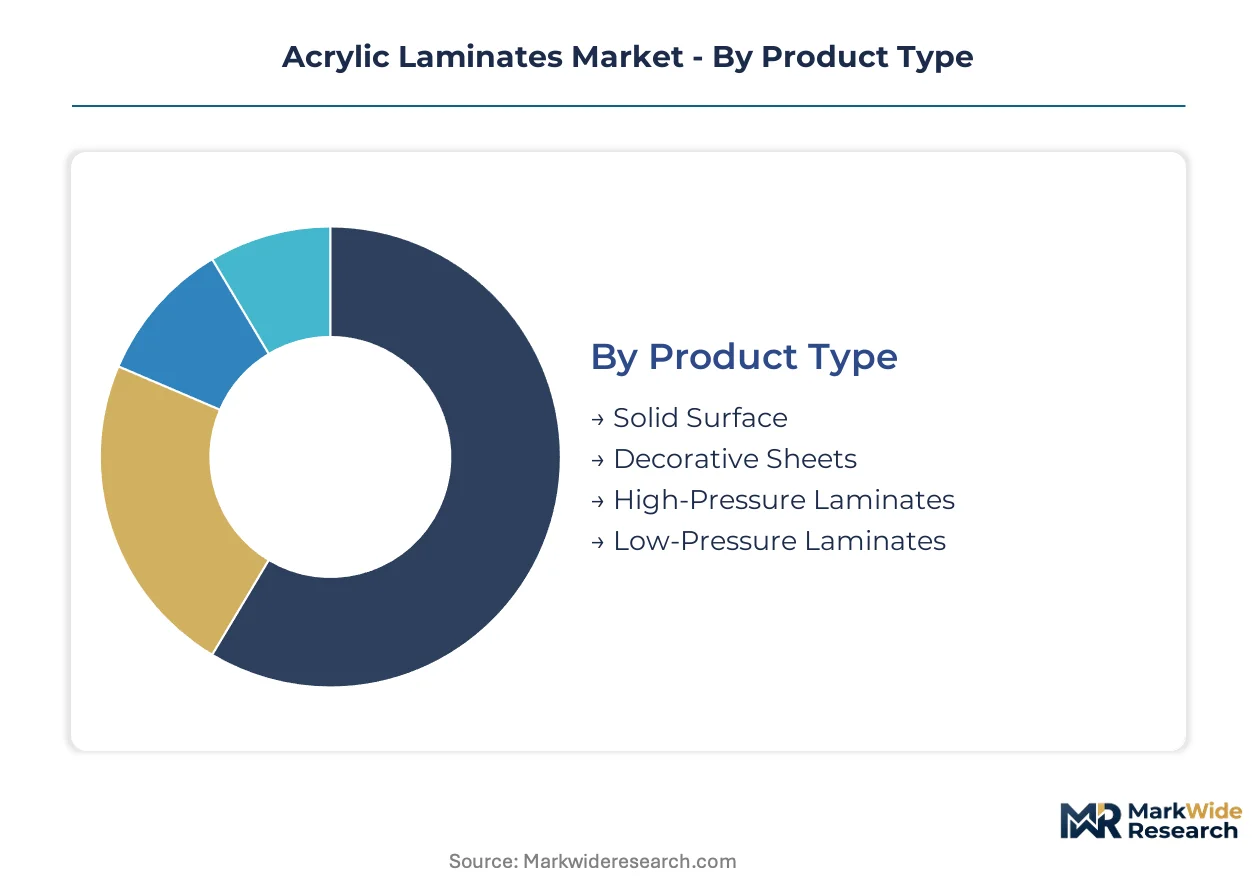
Acrylic laminates segment across product chemistry, end-use specification intensity, and channel access requirements. Each dimension carries distinct margin structures and certification barriers that reshape competitive positioning.
Product Type:
Margins concentrate in specialized surface chemistries where formulation control and press calibration create defendable specification positions.
- Decorative Sheets:Thermosetting surfaces formed by impregnating gravure-printed or inkjet-decorated paper with melamine-acrylic resin blends, then pressing under heat exceeding 150°C. Hospitality refurbishment in India and co-working fit-outs in China's tier-one cities are concentrating specification demand for premium patterned finishes.
- High-Pressure Laminates:Multi-layer composite surfaces bonded under pressures exceeding 7 MPa onto particleboard or MDF substrates, delivering scratch and heat resistance for residential countertops. India's modular furniture clusters in Panipat and Morbi are rotating volume toward certified domestic producers under BIS IS 2046 compliance mandates.
- Solid Surface:Cast acrylic-polymer matrices with homogeneous coloration enabling seamless joints and thermoforming for healthcare partitions.
- Low-Pressure Laminates:Decorative papers bonded with lower resin saturation for cost-sensitive furniture and cabinetry applications.
High-Pressure Laminates hold installed capacity. Solid Surface is rotating up the share rankings.
End Use:
Application environments dictate performance specifications, fire resistance requirements, and hygiene standards that stratify pricing power across customer categories.
- Commercial:Office fit-outs, hospitality refurbishment, and retail fixture installations requiring ISO 4586-certified surfaces with accelerated aging resistance. Mumbai and Bangalore contractors are bypassing stockists to source directly from integrated manufacturers, compressing traditional distributor margins.
- Residential:Kitchen countertops, bathroom vanities, and modular furniture surfaces where cost sensitivity dominates but BIS certification is tightening import access. India's urban residential construction expansion is concentrating demand in western and southern states.
- Automotive:Interior trim panels and decorative fascia components requiring UV stability and thermal cycling resistance.
- Industrial:Laboratory work surfaces and cleanroom partitions demanding chemical resistance and seamless hygiene properties.
Commercial commands specification premiums. Residential is expanding most quickly.
Application:
Installation geometry and wear exposure determine substrate compatibility, edge-banding requirements, and field service complexity.
- Countertops:Horizontal surfaces requiring heat resistance, moisture barrier integration, and impact durability for residential kitchens and commercial food service. Sintered stone competitors are displacing laminates above premium price thresholds in European and East Asian markets.
- Wall Panels:Vertical cladding applications in reception areas, elevator lobbies, and hospitality corridors where digital inkjet decoration enables rapid pattern customization for short-run projects.
- Furniture:Cabinet faces, shelving, and table surfaces where thermoforming limitations restrict complex curved designs.
- Partitions:Space division systems in healthcare and laboratory environments where seamless surfaces support hygiene protocols.
Countertops anchor volume throughput. Wall Panels are gaining share fastest.
Distribution Channel:
Channel selection reflects project scale, specification complexity, and certification documentation requirements that vary by customer type.
- Direct Sales:Manufacturer relationships with tier-one interior design firms and furniture OEMs for certified commercial projects requiring batch traceability and fire resistance documentation. India's western and southern state contractors are consolidating procurement through this channel.
- Specialty Stores:Stockist networks serving residential renovation and small commercial projects with immediate availability of standard patterns.
- Wholesale:Volume distribution to furniture manufacturers and construction material suppliers with inventory holding capabilities.
- Online Retail:Digital platforms enabling sample ordering and specification browsing for remote project planning.
Direct Sales captures margin concentration. Specialty Stores are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for domestic laminate production is redirecting investment toward integrated resin-to-laminate facilities. ECHA REACH compliance in Europe and SAMR GB standard revisions in China are fragmenting regulatory requirements across major demand centers.
India
Urban residential construction in Mumbai and Bangalore is absorbing certified decorative laminates for modular kitchens and bathroom vanities. BIS IS 2046 certification mandates are tightening import access and rewarding domestic manufacturers with production-linked incentives. Manufacturing gravity concentrates in Panipat and Morbi clusters where integrated press lines serve furniture OEMs directly.
China
Co-working space fit-outs in Shanghai and Shenzhen are specifying Grade E0 decorative surfaces for interior wall cladding. SAMR GB standards for formaldehyde emission are forcing reformulation of melamine-acrylic resin ratios in Guangdong and Zhejiang production bases. Export-oriented suppliers are dual-certifying lines to maintain European specification channel access.
Germany
Healthcare infrastructure refurbishment in Berlin and Munich is opening specification channels for solid surface acrylics in laboratory partitions. ECHA REACH registration mandates enforce raw material transparency that rewards qualified suppliers with preferred vendor status. Specification channels for premium decorative sheets concentrate in North Rhine-Westphalia industrial corridors.
United States
Commercial interior renovation cycles in New York and Los Angeles are accelerating demand for ISO 4586-certified surfaces in hospitality and corporate reception areas. EPA formaldehyde emission standards under TSCA Title VI constrain bonded wood product specifications that laminate substrates must meet. Distribution concentrates through direct manufacturer relationships with tier-one interior design firms.
Italy
Luxury hospitality refurbishment in Milan and Rome sustains premium specification margins for decorative high-pressure laminates with accelerated aging resistance. CE marking requirements under EU Construction Products Regulation enforce fire resistance documentation for commercial installation. Manufacturing competence clusters in Emilia-Romagna serve European specification channels.
Acrylic Laminates Market Competitive Environment
Player mix skews toward integrated resin-to-laminate producers with ISO 4586 certification and uncertified regional fabricators serving price-sensitive residential segments. The competitive landscape bifurcates around qualification barriers rather than scale concentration. Three archetypes dominate: European premium specification specialists, South Asian integrated volume producers, and Chinese export-oriented dual-certifiers. Capacity expansion and backward integration into resin production represent the dominant competitive moves as margin pressure from petrochemical feedstock volatility intensifies.
Among European specialists, Arpa Industriale S.p.A. and Abet Laminati S.p.A. exemplify the premium-tier archetype anchored in Italian manufacturing heritage. Stylam Industries Limited occupies a position within the South Asian integrated producer tier, representing the resin-to-laminate operational model that India's PLI scheme incentivizes. These three companies illustrate how geographic origin and certification status stratify competitive positioning across specification-driven versus volume-driven market segments.
| Leading Market Players |
|---|
| Arpa Industriale S.p.A. |
| Stylam Industries Limited |
| Meraki PVC |
| FunderMax GmbH |
| Merino Laminates |
| Abet Laminati S.p.A. |
| Panolam Industries International |
| Royal Crown Laminates |
| Greenlam Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Indian furniture OEMs and Panipat-based laminate producers lock in both methyl methacrylate supply access and eighteen-month price visibility, insulating integrated manufacturers from MMA monomer volatility that spot-market buyers absorb.
Pricing Analysis
Certification level creates the primary spread between ISO 4586-qualified decorative sheets and uncertified regional supply. Three-tier pricing structure across premium certified, standard domestic, and economy import levels stratifies the market, with BIS IS 2046 compliance commanding premiums in Indian specification channels. Pricing pressure stems from sintered stone substitution above premium thresholds in European countertop applications. Residential renovation contractors exhibit highest price sensitivity, while healthcare facility procurement teams prioritize seamless hygiene performance over unit cost.
Supply Chain Analysis
Strategic stockpiling of decorative paper and melamine resin dominates over just-in-time preferences, given multi-week press scheduling requirements and batch traceability mandates. Supply concentrates in India, China, and Italy, with acrylic resin feedstock drawing from Northeast Asian MMA monomer producers. Raw material dependencies center on petrochemical-derived methyl methacrylate, kraft paper substrates, and melamine-formaldehyde resins. Single-source vulnerability in MMA supply from Korean and Japanese chemical producers creates disruption risk. Distribution runs through direct manufacturer relationships with tier-one interior design firms, bypassing traditional stockist networks in Indian commercial fit-out markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment story. ISO 4586 and BIS certification requirements create switching costs that lock specification channels and defend incumbent positions against unqualified competitors.
For Market Incumbents: Fortify backward integration into captive resin production to offset MMA monomer price volatility from Korean and Japanese chemical suppliers. Expand press capacity in Morbi and Panipat clusters to capture PLI scheme incentives before qualification timelines extend. Sintered stone substitution in European premium countertops demands accelerated solid surface R&D investment.
For New Entrants and Emerging Players: Lead with digital inkjet decoration capabilities targeting short-run hospitality refurbishment projects in Mumbai and Bangalore, where gravure-printed minimum order quantities exclude smaller interior firms. India's western state modular kitchen segment offers lowest certification barriers for BIS IS 2046 entry. Direct contractor relationships bypass entrenched stockist networks.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated resin-to-laminate producers with existing ISO 4586 qualification and established specification channel access. Long-term viability hinges on regulatory compliance moats deepening rather than commodity scale advantages. Watch for ECHA REACH registration cost spikes that force consolidation among uncertified European regional suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive MMA supply insulates margins from Northeast Asian monomer price volatility. |
| ISO 4586 Certification Investment | Qualification unlocks European commercial specification channels and defends premium positioning. |
| Digital Inkjet Decoration Adoption | UV-curable printing enables short-run customization for hospitality refurbishment projects. |
| PLI Scheme Capacity Expansion | Domestic production incentives in Panipat and Morbi clusters tighten import competition. |
| Solid Surface Healthcare Positioning | Seamless hygiene specifications in German and Japanese laboratory partitions command margin premiums. |
Study Parameters
The analysis maps decorative sheets, high-pressure laminates, solid surface, and low-pressure laminates, each validated through procurement managers at furniture OEMs, press operators at integrated manufacturing facilities, specification architects at commercial interior firms, and resin procurement leads at chemical suppliers. Primary interview findings triangulate against customs trade data, BIS certification registries, ECHA REACH registration databases, and SEC filings from listed laminate producers. Bottom-up capacity estimates and top-down demand modeling cross-validate volume outputs.
Consistency checks against external benchmarks validate projection outputs across the analysis window. Segmentation dimensions include product chemistry tier, end-use specification intensity, application geometry, and distribution channel access requirements. CAGRs derive from installed capacity utilization trends, regulatory compliance cost trajectories, and substitution elasticity estimates between laminate and sintered stone surfaces. Forecast inputs incorporate PLI scheme incentive disbursement patterns and E0-grade formaldehyde emission standard adoption curves.
Forecasts assume regulatory continuity in ECHA REACH, BIS IS 2046, and SAMR GB standard regimes; material policy shifts would require re-modeling. Acrylic resin price volatility, certification timeline extensions, and sintered stone technology cost reduction represent primary forecast revision triggers. Revision becomes warranted when MMA monomer supply concentration or substitution rates cross thresholds that invalidate baseline margin assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
CFRTP Market
Composite Materials
Composites Testing Market
Composite Materials
Wind Turbine Composites Market
Composite Materials
Epoxy Composite Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Composites Distributor Market
Composite Materials
Wood Plastic Composite (WPC) Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
LAMEA Composite Process Material Kits Market
Composite Materials
Global Sports Composites Market
Composite Materials
Balsa Core Materials Market
Composite Materials
Structural Core Materials Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Pultrusion Market