
 Fiber Reinforced Polymer (FRP) Panels and Sheets Market | 2026-2036
Fiber Reinforced Polymer (FRP) Panels and Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Reinforced Polymer (FRP) Panels and Sheets Market Insights
Construction cladding among building contractors is consolidating as the dominant end-use vertical, displacing traditional metal and wood substrates in commercial facades and interior wall systems. Owens Corning Corporation leverages its glass fiber supply chain to anchor cost positions in sheet and panel formats. Röchling differentiates through engineered thermoplastic composites for corrosive industrial environments. Strongwell Corporation dominates pultruded profile production with continuous manufacturing scale across North American infrastructure projects.
Fiber Reinforced Polymer panels and sheets are composite structures comprising polymer matrices reinforced with glass, carbon, or aramid fibers, manufactured through pultrusion, resin transfer molding, or compression molding to achieve strength-to-weight ratios exceeding steel at one-fifth the density. Pultruded profiles command premium positioning in load-bearing applications where dimensional stability and corrosion resistance justify higher material costs. Sheet formats sustain volume leadership in cladding and electrical insulation where standardized dimensions and rapid installation drive procurement decisions. Calendered laminates occupy niche aerospace interiors where tight thickness tolerances and fire-smoke-toxicity certification create defensible margin pools.
REACH in Europe and the EU Green Deal's embodied carbon thresholds are forcing reformulation of resin systems toward bio-based and recycled content alternatives. OSHA and ICC fire-code enforcement in the United States shapes product testing protocols and limits market access for uncertified imports. Stakeholders must monitor evolving building code harmonization between ASTM International and EN standards to anticipate which manufacturing technologies will secure cross-border specification approval.
Market Dynamics
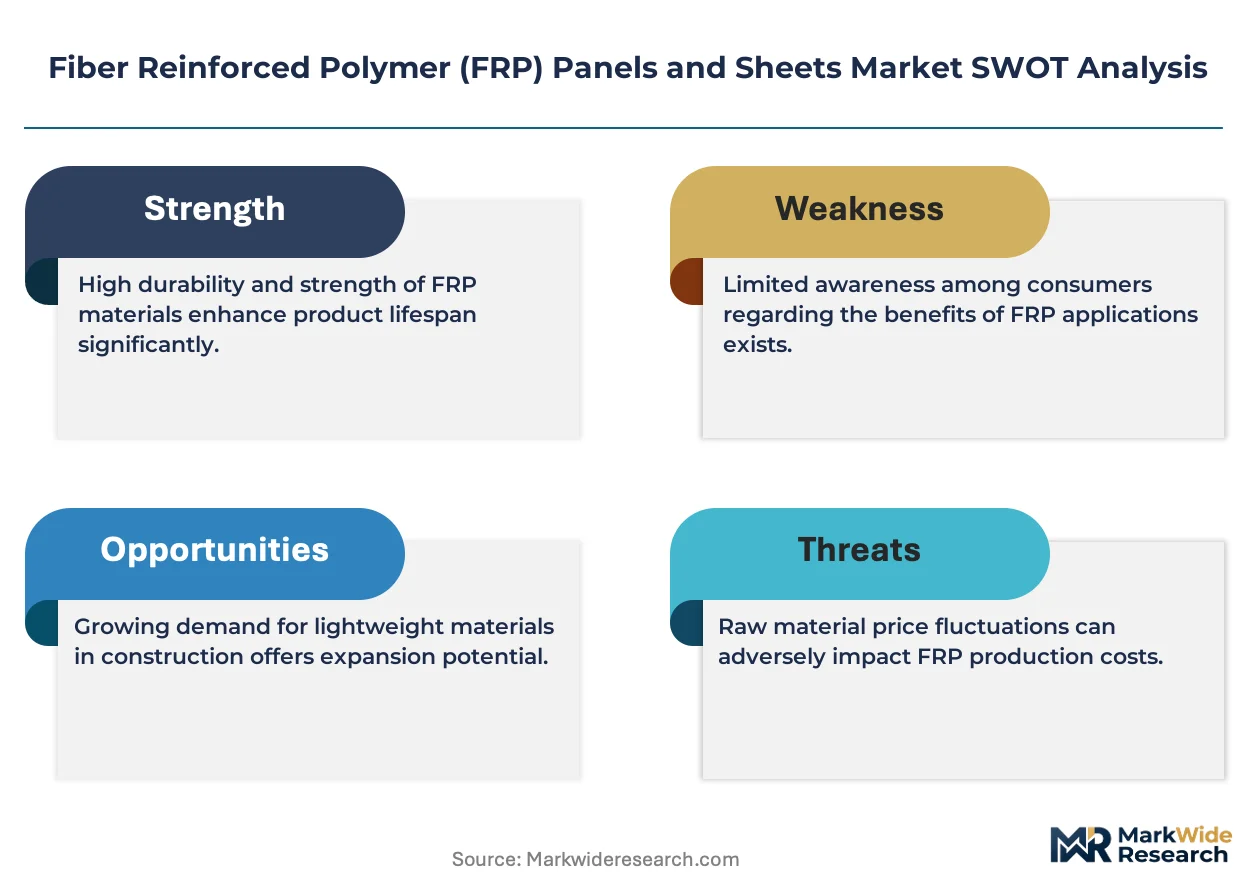
Construction cladding specification is consolidating around FRP substrates as building codes tighten fire-safety and embodied-carbon thresholds, forcing contractors to abandon legacy metal and wood facades.
Growth Catalysts
- REACH compliance deadlines:ECHA's 2025 registration review is accelerating resin reformulation toward bio-based epoxies and recycled fiber content, opening specification pathways for sustainable pultruded profiles.
- Infrastructure renewal pipelines:Germany's bridge rehabilitation programs and Netherlands' flood defense upgrades are absorbing premium-grade FRP sheet for corrosion-resistant structural rehabilitation.
- Pultrusion automation:Continuous processing advances are compressing cycle times for complex profiles, enabling cost parity with aluminum in mid-rise commercial framing.
Market Restraints
- Raw material concentration:Glass fiber roving supply concentrates among three Chinese producers, exposing converters to freight volatility and tariff uncertainty.
- Fire certification friction:ASTM E84 and EN 13501-1 testing divergence creates dual-certification burdens, delaying North Atlantic cross-border project approvals.
- Steel substitution resilience:Galvanized steel maintains cost advantage in non-corrosive interior applications, capping FRP penetration in budget-constrained municipal contracts.
Strategic Opportunities
- EU Green Deal procurement mandates:Public construction tenders above EUR 5 million now require Environmental Product Declarations, favoring domestic FRP producers with verified lifecycle data.
- Offshore wind nacelle interiors:Fire-smoke-toxicity certified FRP laminates are displacing thermoplastics in turbine housing panels, with North Sea installations driving volume.
- Digital specification platforms:Building information modeling libraries from Arkema and Sabic are embedding FRP material cards directly into architect workflows, compressing design-cycle conversion.
Industry Challenges
- Pultrusion die engineering scarcity:Tooling design for complex hollow profiles requires specialized polymer rheology expertise concentrated among retiring German and Austrian technicians.
- Resin inventory obsolescence:Reformulation cycles to meet evolving REACH SVHC restrictions are stranding legacy epoxy stocks and forcing working capital reallocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Reinforced Polymer (FRP) Panels and Sheets Market |
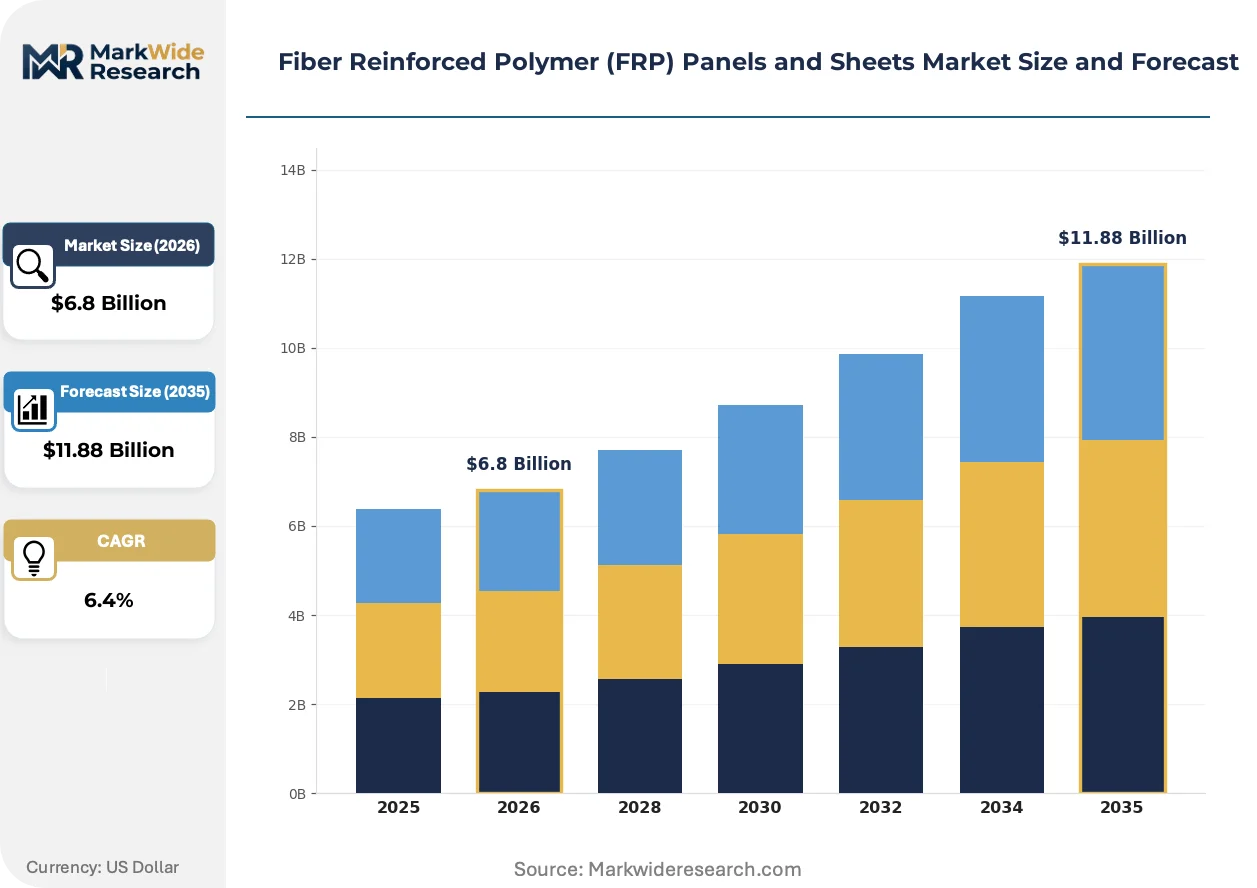
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Panel, Calendered Laminate, Pultruded Profile, Molded Composite Technology: Resin Transfer Molding, Vacuum Assisted Resin Infusion, Hand Lay-Up, Pultrusion, Compression Molding Application: Construction Cladding, Marine Components, Electrical Insulation, Aerospace Interiors, Wind Turbine Blades End User: Building Contractors, Shipbuilders, Electrical Manufacturers, Aircraft Assemblers, Renewable Energy Firms |
| Companies Covered | Crane Composites, Inc., Strongwell Corporation, Röchling, Hill & Smith Holdings PLC, LAMILUX Heinrich Strunz Holding GmbH & Co. KG, Owens Corning Corporation, Saint-Gobain, Kingspan, 3A Composites GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Reinforced Polymer (FRP) Panels and Sheets Market Trends and Innovations
Active material science breakthroughs and procurement digitization are compressing specification cycles while regulatory fragmentation forces parallel certification strategies across Atlantic markets.
Continuous basalt fiber pultrusion is electrifying structural reinforcement applications by delivering carbon-fiber-comparable tensile strength at 40% lower input cost. Bridge engineers in Scandinavia are specifying basalt-reinforced deck panels for salt-exposed coastal infrastructure. The technology is electrifying competitive positioning among mid-tier profile converters previously locked out of load-bearing specification.
OSHA's updated silica exposure limits are forcing composites fabricators toward closed-mold resin transfer molding and vacuum infusion processes. Workshop air monitoring requirements are accelerating capital expenditure in automated metering equipment. North American infrastructure contractors are responding by consolidating procurement around RTM-certified suppliers with documented exposure controls.
Specification authority is migrating from general contractors to architect-led design-build consortia, compressing traditional distributor influence. Digital material libraries and performance-based submittal templates are displacing physical sample-based selection in commercial facade projects. This pattern is most visible in German and Dutch healthcare and education construction, where integrated project delivery contracts dominate public procurement.
Fiber Reinforced Polymer (FRP) Panels and Sheets Market Segmentation
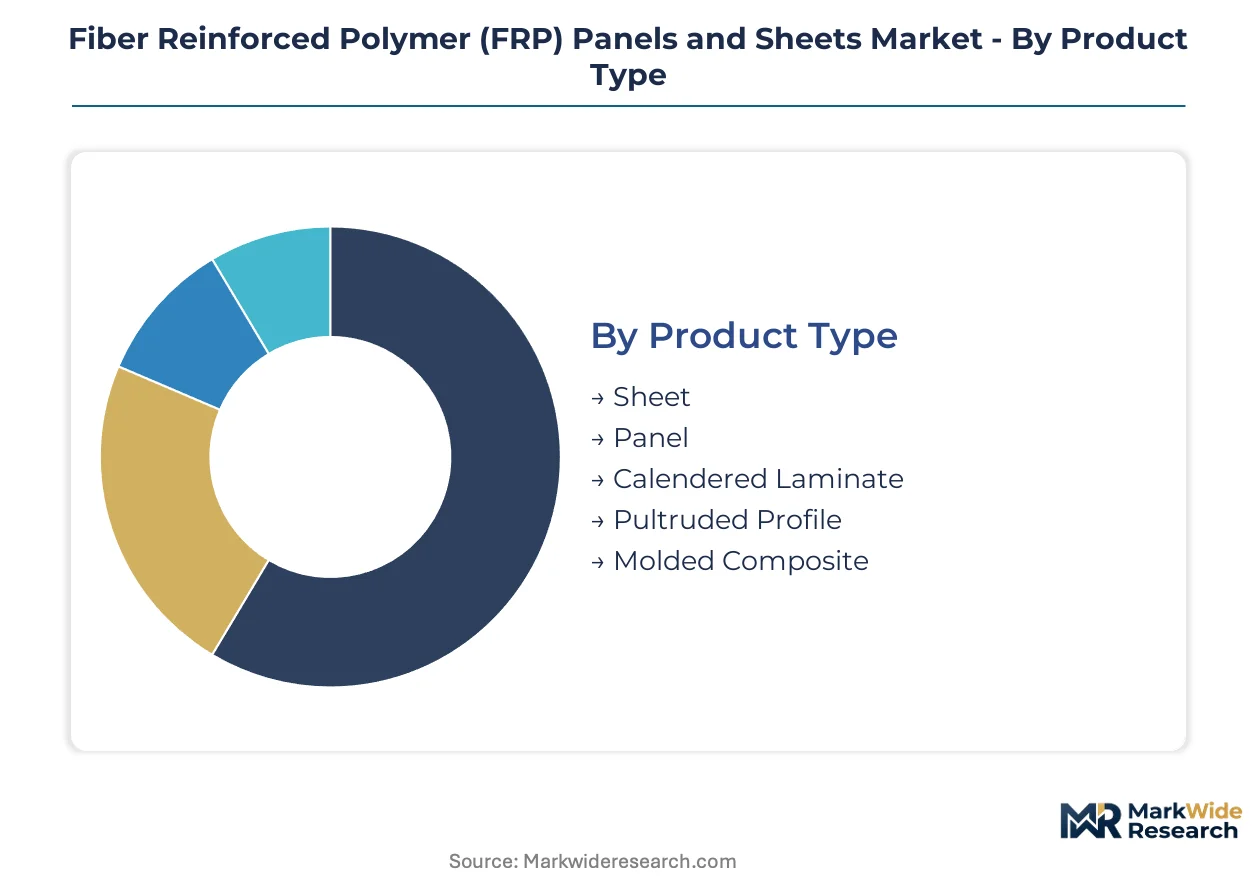
Segmentation in the Fiber Reinforced Polymer (FRP) Panels and Sheets Market reveals how specification authority migrates across value chain tiers. Product format dictates manufacturing capital intensity, while application verticals impose divergent certification burdens that reshape competitive access.
Product Type:
Upgrade cycles in commercial facade systems and infrastructure rehabilitation are displacing legacy substrates and reshaping volume distribution across FRP formats.
- Sheet:Flat glass-reinforced panels manufactured through continuous lamination deliver standardized dimensions for rapid cladding installation. Building contractors in Germany and the Netherlands specify sheet formats for healthcare and education construction where fire-smoke-toxicity certification compresses procurement timelines.
- Panel:Rigid sandwich constructions with foam or honeycomb cores achieve structural depth without weight penalty. Marine component fabricators favor paneled configurations for ship interior partitions where moisture resistance and acoustic dampening justify premium positioning.
- Calendered Laminate:Thin-gauge precision laminates serve aerospace interior applications with tight thickness tolerances.
- Pultruded Profile:Continuous fiber-reinforced structural shapes deliver load-bearing capacity for bridge rehabilitation and industrial framing.
- Molded Composite:Complex three-dimensional forms produced in matched-die tooling accommodate electrical insulation housings and wind turbine root fittings.
Volume placements concentrate in Sheet formats for standardized construction applications; the faster expansion belongs to Pultruded Profile as infrastructure renewal programs accelerate specification.
Technology:
Process selection hinges on production scale, geometric complexity, and regulatory exposure limits that favor closed-mold methods over open-air fabrication.
- Resin Transfer Molding:Closed-mold injection of catalyzed resin into fiber preforms yields consistent fiber-volume fractions with minimal emissions. OSHA silica enforcement in the United States is accelerating RTM adoption among North American infrastructure contractors seeking documented exposure controls.
- Vacuum Assisted Resin Infusion:Atmospheric pressure-driven resin distribution achieves large-area saturation without heavy tooling. Scandinavian bridge engineers specify VARI-produced basalt-reinforced deck panels for salt-exposed coastal infrastructure where carbon-fiber performance at reduced input cost drives selection.
- Hand Lay-Up:Manual fiber placement and roller consolidation persists in custom marine and architectural applications.
- Pultrusion:Continuous pulling of resin-impregnated fiber through heated dies enables high-volume structural profile production.
- Compression Molding:Matched-die pressure forming delivers net-shape electrical insulation components and aerospace fittings.
Capital deployment favors RTM and Pultrusion for scaled production; VARI gains share fastest in oversized structural applications where tooling cost avoidance matters.
Application:
End-use verticals impose distinct performance hierarchies that segment FRP procurement by certification burden and replacement-cycle urgency.
- Construction Cladding:Exterior facade and interior wall systems displace metal and wood substrates as REACH compliance and embodied-carbon thresholds tighten across European public procurement. EU Green Deal mandates above EUR 5 million now require Environmental Product Declarations, favoring domestic producers with verified lifecycle data.
- Marine Components:Hull structures, decks, and interior partitions exploit corrosion immunity in salt-water environments. Shipbuilders in Germany and the Netherlands specify FRP for vessel superstructures where weight reduction improves fuel efficiency and regulatory compliance.
- Electrical Insulation:Transformer housings and switchgear enclosures leverage dielectric properties and track resistance.
- Aerospace Interiors:Cabin panels and galleys require fire-smoke-toxicity certification under FAA and EASA protocols.
- Wind Turbine Blades:Root sections and nacelle housings absorb structural loads in renewable energy installations.
Construction Cladding commands the largest placement volume; Wind Turbine Blades expand most quickly as offshore installations multiply across the North Sea.
End User:
Customer-type segmentation tracks how specification authority concentrates among integrators with direct access to project financing and regulatory gatekeeping.
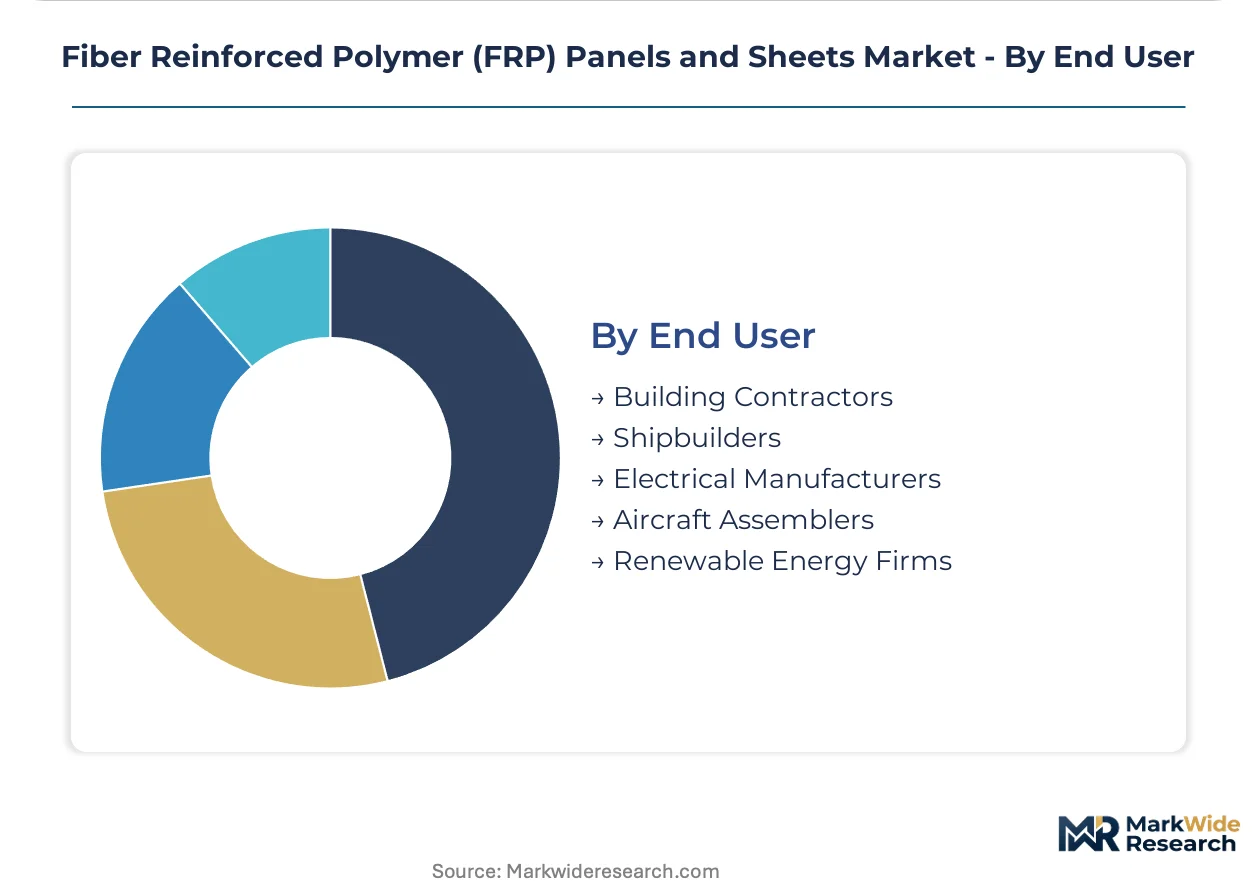
- Building Contractors:General and specialty contractors executing commercial facades and infrastructure rehabilitation drive sheet and panel procurement. German building consortia integrated with architect-led design-build contracts dominate public healthcare and education construction where FRP specification is consolidating.
- Shipbuilders:Naval and commercial vessel constructors specify marine-grade FRP for corrosion-critical zones. Scandinavian and Dutch shipyards lead composite adoption in passenger ferry and offshore support vessel segments.
- Electrical Manufacturers:Transformer and switchgear producers source molded insulation components for grid infrastructure.
- Aircraft Assemblers:Tier-1 aerospace suppliers procure certified laminates for cabin interior programs.
- Renewable Energy Firms:Wind farm developers and turbine OEMs acquire structural profiles and nacelle panels.
Building Contractors anchor volume demand through cladding specification; Renewable Energy Firms are climbing the fastest as offshore wind capacity targets escalate across European waters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial free zones in Jebel Ali and Ras Al Khaimah are drawing Gulf-based fabricators seeking tariff-advantaged resin import channels. These special-economic-zone incentives concentrate pultrusion capacity near major infrastructure corridors.
United States
Bridge rehabilitation programs across the Interstate Highway System absorb premium-grade pultruded profiles for corrosion-resistant deck replacement. OSHA's updated silica exposure limits are forcing composites fabricators toward closed-mold resin transfer molding processes with documented exposure controls. Infrastructure contractors in Texas and California are consolidating procurement around RTM-certified suppliers.
Germany
Automotive-adjacent industrial applications and infrastructure renewal programs absorb premium-grade pultruded profiles from Bavarian and North Rhine-Westphalian converters. REACH compliance deadlines from ECHA are accelerating resin reformulation toward bio-based epoxies among domestic compounders. The Ruhr industrial corridor hosts specialized die engineering expertise for complex hollow profile tooling.
Netherlands
Flood defense upgrades and coastal protection infrastructure specify basalt-reinforced FRP sheet for salt-exposed structural rehabilitation. EU Green Deal procurement mandates above EUR 5 million require Environmental Product Declarations, favoring domestic producers with verified lifecycle data. Rotterdam's port industrial zone concentrates marine-grade panel fabrication for North Sea vessel construction.
China
Glass fiber roving supply concentrates among domestic producers, exposing converters to freight volatility and tariff uncertainty. The country's national industrial standards regulator is tightening embodied-carbon thresholds for public construction materials. Yangtze River Delta manufacturing clusters supply standardized sheet formats for rapid cladding installation across Southeast Asian export markets.
United Arab Emirates
Healthcare and education construction projects specify fire-certified FRP cladding as building codes tighten safety thresholds. The country's national construction regulator mandates enhanced fire-smoke-toxicity testing for facade materials in high-occupancy structures. Dubai's design-build consortia are embedding digital material libraries into architect workflows for specification compression.
Fiber Reinforced Polymer (FRP) Panels and Sheets Market Competitive Landscape
Top-tier vendors anchor premium pultruded profile supply, while mid-scale converters compete on sheet format standardization and rapid-turn fabrication. The vendor base distributes across three strategic tiers: integrated fiber-to-fabric producers, specialized profile engineers, and regional sheet laminators. Two dominant competitive moves are reshaping positioning: backward integration into captive glass fiber supply, and technology licensing partnerships for automated pultrusion die engineering.
Among integrated fiber-to-fabric producers, Owens Corning Corporation and Saint-Gobain exemplify the archetype of upstream-controlled supply chains. Strongwell Corporation and Röchling occupy positions within the specialized engineering tier, differentiated by process expertise rather than commodity scale. These four named entities represent the competitive spectrum from raw material integration through application-specific fabrication, with each archetype defending margin pools through distinct capability barriers rather than price-based rivalry.
| Leading Market Players |
|---|
| Crane Composites, Inc. |
| Strongwell Corporation |
| Röchling |
| Hill & Smith Holdings PLC |
| LAMILUX Heinrich Strunz Holding GmbH & Co. KG |
| Owens Corning Corporation |
| Saint-Gobain |
| Kingspan |
| 3A Composites GmbH |
| Others |
Pricing and Supply Chain Analysis
Glass fiber roving price indices from Yangtze River Delta suppliers cascade through converter margins into three-tier pricing structure across premium, standard, and economy levels. REACH-driven resin reformulation costs and freight volatility from Chinese producers compress margin pools at mid-tier converters while rewarding backward-integrated compounders with captive fiber supply.
Pricing Analysis
Short lead-time premiums of thirty percent separate spot pultruded profile procurement from contract-of-take arrangements spanning bridge rehabilitation programs. Project-based pricing dominates infrastructure verticals where specification cycles exceed eighteen months, while sheet formats trade on commodity spot markets with volume-scale discounts tiered by healthcare and education contractors. Price differentiation hinges on fire-smoke-toxicity certification grade and geographic delivery cost from Bavarian versus Chinese manufacturing clusters. Cost compression in standard-grade sheet intensifies because Yangtze Delta exporters absorb tariff uncertainty to defend Southeast Asian market share. Municipal contractors exhibit highest price sensitivity; aerospace tier-one suppliers demonstrate least.
Supply Chain Analysis
Retiring German and Austrian pultrusion die engineers constrain tooling design capacity for complex hollow profiles among Bavarian and North Rhine-Westphalian converters. Raw material dependencies draw from Chinese glass fiber roving, Saudi petrochemical resin feedstock, and Belgian epoxy formulation expertise. Single-source vulnerability concentrates in three domestic Chinese fiber producers exposing converters to freight volatility and tariff uncertainty. Distribution runs through architect-led design-build consortia in German healthcare construction and consolidated RTM-certified supplier networks across Texas and California infrastructure corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous basalt fiber pultrusion technology is displacing legacy carbon-fiber reinforcement in Scandinavian bridge engineering, compressing specification cycles and reshaping competitive access for mid-tier profile converters.
For Market Incumbents: Anchor cost positions through in-house production of glass fiber roving and automated pultrusion die engineering partnerships. Defend against basalt-reinforced entrants by securing ECHA REACH pre-registration for bio-based epoxy formulations. Capacity addition in Ruhr industrial corridor preserves access to retiring German tooling expertise. For New Entrants and Emerging Players: Begin with basalt-reinforced deck panel specification in Netherlands flood defense and Scandinavian coastal infrastructure where carbon-fiber-comparable performance at reduced input cost opens procurement pathways. Target VARI-processed oversized structural applications where tooling cost avoidance accelerates adoption. Go-to-market through digital material library integration with Rotterdam and Hamburg architect workflows. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale VARI-specialized converters with North Sea offshore wind nacelle certifications in Netherlands and Germany. Five-to-ten year viability rests on Environmental Product Declaration verification capacity under EU Green Deal procurement mandates. Watch ECHA SVHC restriction announcements as inflection indicator for resin inventory obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Fiber Supply | Owens Corning and Saint-Gobain archetypes defend margin pools against Yangtze Delta freight volatility. |
| Automated Pultrusion Die Engineering Partnerships | Ruhr corridor expertise transfer preserves complex hollow profile capability as Austrian technicians retire. |
| Environmental Product Declaration Certification | EU Green Deal procurement mandates above EUR 5 million require verified lifecycle data from domestic producers. |
| Digital Material Library Integration | Arkema and Sabic embedding FRP cards into BIM workflows compresses German architect specification cycles. |
| Basalt Fiber Process Scale-Up | Scandinavian bridge engineers specify salt-exposed deck panels where carbon-fiber performance cost structure shifts. |
Research Methodology
Multi-period observation of ECHA REACH registration timelines, OSHA silica enforcement patterns, and EU Green Deal procurement award flows anchored the trend analysis, supplemented by interviews with pultrusion plant managers, architect specification leads, bridge rehabilitation contractors, resin procurement directors, and marine component fabricators. Secondary validation drew from customs trade data, SEC 10-K filings from listed fiber producers, German federal infrastructure award databases, and EN 13501-1 certification registries. Bottom-up volume modeling triangulated against top-down construction spend allocation across healthcare, education, and transportation verticals.
Segment-weighting across product format, manufacturing technology, application vertical, and end-user archetype shaped the analytical framework across the analysis window. CAGRs derived from elasticity-adjusted substitution rates of FRP for galvanized steel in corrosive environments and penetration curves for basalt-reinforced profiles in infrastructure rehabilitation. Industry-specific inputs included Yangtze Delta glass fiber capacity utilization rates and North Sea offshore wind nacelle installation pipelines.
Underlying measurement precision varies by segment; pultruded profile volumes in German bridge programs carry tighter precision than custom marine component fabrication. Forecasts reflect assumptions on REACH SVHC restriction timing and OSHA enforcement intensity. Material deviation in ECHA registration review outcomes or Yangtze Delta export tariff adjustments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Composite Process Material Kits Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
Molded Underfill Material Market
Composite Materials
Composite Market
Composite Materials
Lignin-Based Graphene Market
Composite Materials
Plastic Composites Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
Composite Coatings Market
Composite Materials
Case Material Market
Composite Materials
Polypropylene and Polypropylene Composites Market
Composite Materials
Global Honeycomb Core Materials Market
Composite Materials
Global FRP Sheets and Panels Market
Composite Materials
Carbon Fiber Prepreg Market
Composite Materials
Lightweight Materials Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Global Thermoplastic Composites Market