
 Lifestyle Diseases Apps Market | 2026-2036
Lifestyle Diseases Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Lifestyle Diseases Apps Market Intelligence
Silicon Valley's digital health engineering base is pivoting toward FDA-cleared software platforms for metabolic and cardiovascular conditions. Noom Inc. leverages behavioral psychology frameworks to sustain user retention in weight management programs. Fitbit Inc. anchors wearable data pipelines with integrated glucose and blood pressure trending. HealthifyMe competes through localized nutrition databases and multilingual coaching interfaces in South Asian markets.
Lifestyle diseases apps are software platforms designed to monitor, manage, and mitigate chronic conditions including obesity, type 2 diabetes, hypertension, and sleep disorders through real-time biometric tracking, personalized intervention protocols, and algorithmic risk scoring. These applications deploy machine learning models on cloud architectures to process continuous data streams from smartphones, connected glucometers, and wrist-worn photoplethysmography sensors, generating actionable health insights for users and care teams. Fitness tracker deployments dominate consumer-facing revenue pools, while AI-based platforms capture the fastest expansion as predictive analytics penetrate clinical workflows. Nutrition apps occupy a mature but defensible segment with high subscription renewal rates among bariatric and prediabetic populations.
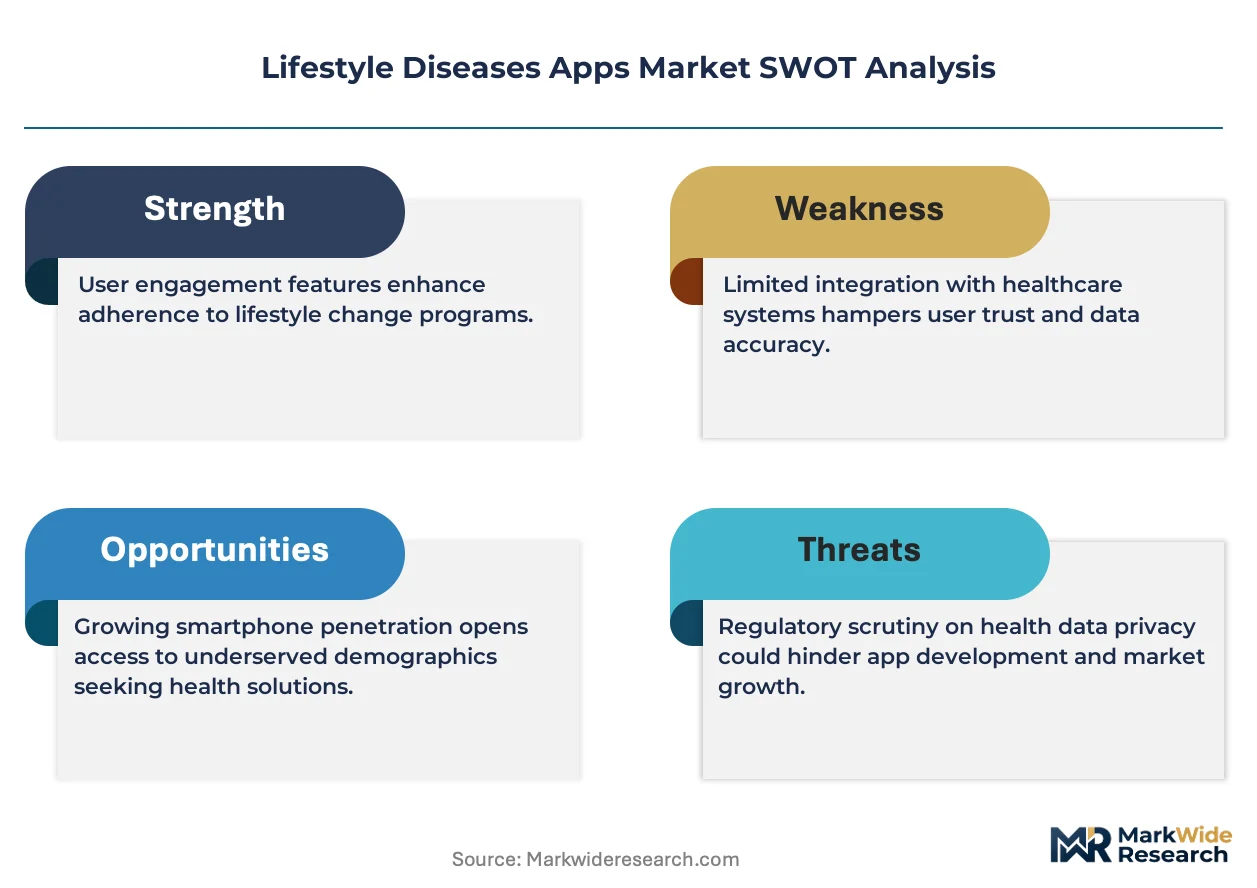
FDA's Software as a Medical Device framework and HIPAA privacy mandates shape product development timelines and liability exposure for developers targeting US healthcare integration. Europe's MDR and GDPR impose parallel conformity and data residency requirements that filter market entrants lacking regulatory operations in EU member states. Stakeholders must monitor evolving reimbursement codes from CMS and private payers that will determine whether clinical-grade apps transition from consumer purchases to covered benefits.
Market Dynamics
FDA's Software as a Medical Device framework is compressing product development timelines while elevating validation costs for developers targeting clinical integration. Healthcare systems now demand algorithmic transparency and prospective clinical evidence before reimbursing digital therapeutics for metabolic and cardiovascular conditions.
Growth Catalysts
- CMS Reimbursement Pathways:Medicare's expanding coverage codes for remote patient monitoring are pulling clinical-grade apps into covered benefit categories, accelerating provider adoption.
- Employer Wellness Mandates:Large self-insured employers in the United States are contracting directly with chronic disease management platforms to reduce medical loss ratios.
- Continuous Glucose Monitoring Integration:Bluetooth-enabled CGM devices are feeding real-time data streams into smartphone applications, enabling algorithmic insulin dosing recommendations.
Market Restraints
- FDA Validation Costs:Prospective clinical trials for Software as a Medical Device clearance require capital reserves that filter mid-stage developers from the US market.
- Data Localization Requirements:GDPR-mandated EU data residency is forcing parallel cloud infrastructure deployments, duplicating fixed costs for multi-territory operators.
- Clinical Workflow Friction:Electronic health record interoperability gaps are limiting automated care team alerts, reducing perceived value among physician adopters.
Strategic Opportunities
- India's Digital Health Stack:The country's national health identifier system and expanding 4G penetration are creating addressable infrastructure for localized diabetes prevention platforms.
- Hypertension in Sub-Saharan Africa:Underserved populations with rising cardiovascular burden represent white space for low-bandwidth, offline-first monitoring applications.
- AI-ECG Convergence:Machine learning models trained on photoplethysmography signals are enabling atrial fibrillation detection through consumer wearables, expanding addressable screening populations.
Industry Challenges
- Behavioral Science Talent Scarcity:Product teams lack sufficient expertise in habit formation psychology to sustain long-term user engagement beyond initial onboarding.
- Multi-Jurisdiction Compliance Burden:Simultaneous FDA, MDR, and PMDA submissions are stretching regulatory affairs capacity at growth-stage developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lifestyle Diseases Apps Market |
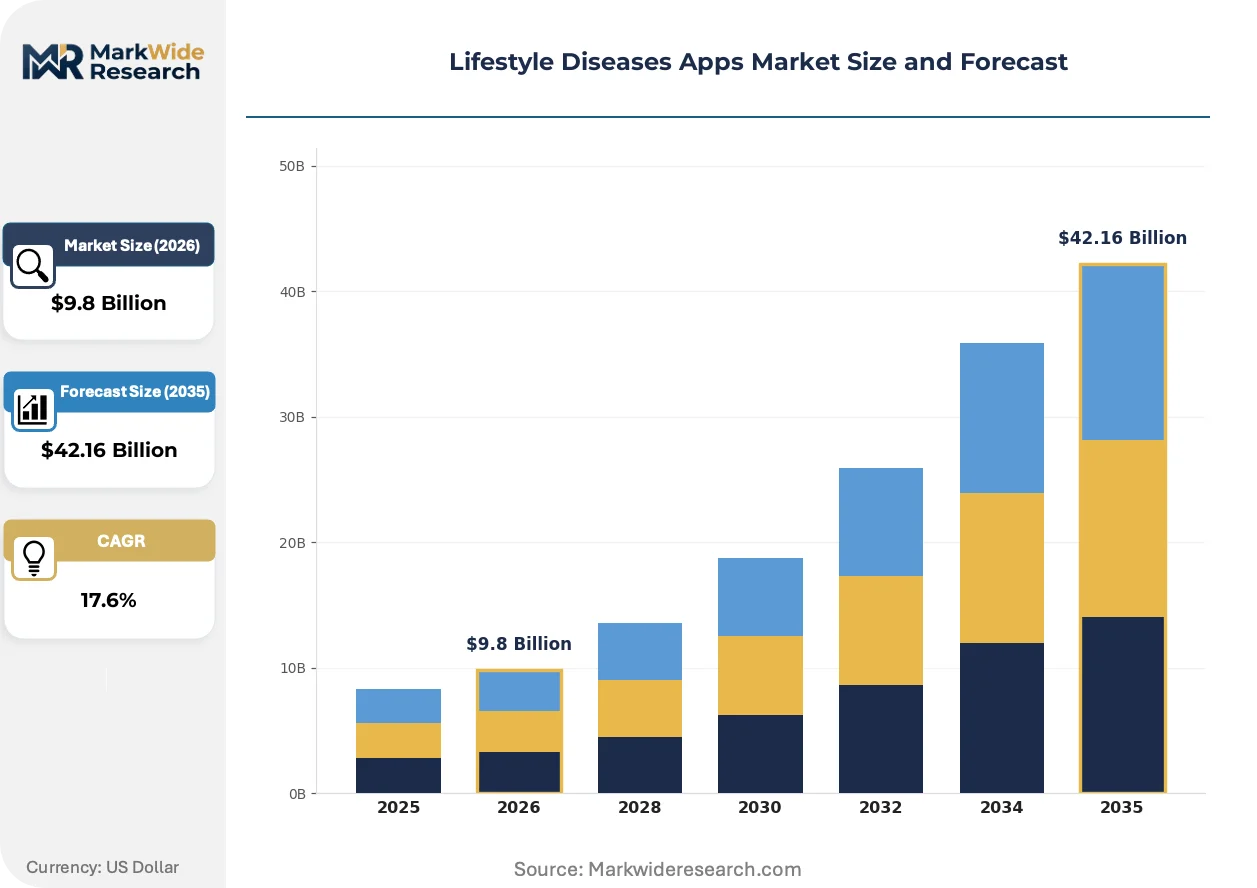
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $42.16 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Tracker, Nutrition App, Stress Management Tool, Sleep Monitor Technology: AI-Based, Cloud-Enabled, Mobile Application, Wearable Integration End User: Individuals, Healthcare Providers, Corporates, Wellness Coaches Distribution Channel: App Store, Direct Sales, Online Marketplace, Partnerships |
| Companies Covered | MyFitnessPal, Noom Inc., Fitbit Inc., Azumio Inc., Lifesum, Sleep Cycle, Headspace, HealthifyMe, Nudge Coach, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lifestyle Diseases Apps Market Strategic Shifts & Innovations
Machine learning architectures are migrating from cloud-only deployments to on-device inference, reshaping latency, privacy, and power consumption trade-offs across the ecosystem. Developers are racing to optimize model compression for smartphone neural processing units.
Edge AI is automating real-time glucose prediction and hypoglycemia alerting without continuous cloud connectivity. Type 1 diabetes patients in Germany and the United States are adopting these hybrid architectures fastest. The shift is compressing infrastructure costs for developers while hardening data sovereignty compliance.
Europe's MDR and GDPR are tightening in tandem, forcing developers to maintain parallel technical documentation and data residency architectures. Clinical evidence requirements for algorithm-based diagnostic outputs now match traditional medical device standards. Diabetes monitoring applications face the steepest compliance cost escalation.
Employer procurement departments are unbundling wellness program contracts, shifting from bundled annual subscriptions to per-employee-per-month pricing tied to biometric outcome verification. Human resources buyers in the United States are demanding HbA1c reduction guarantees before renewing contracts. This compression is pressuring vendor pricing power and forcing outcome measurement infrastructure investments.
Lifestyle Diseases Apps Market Segmentation
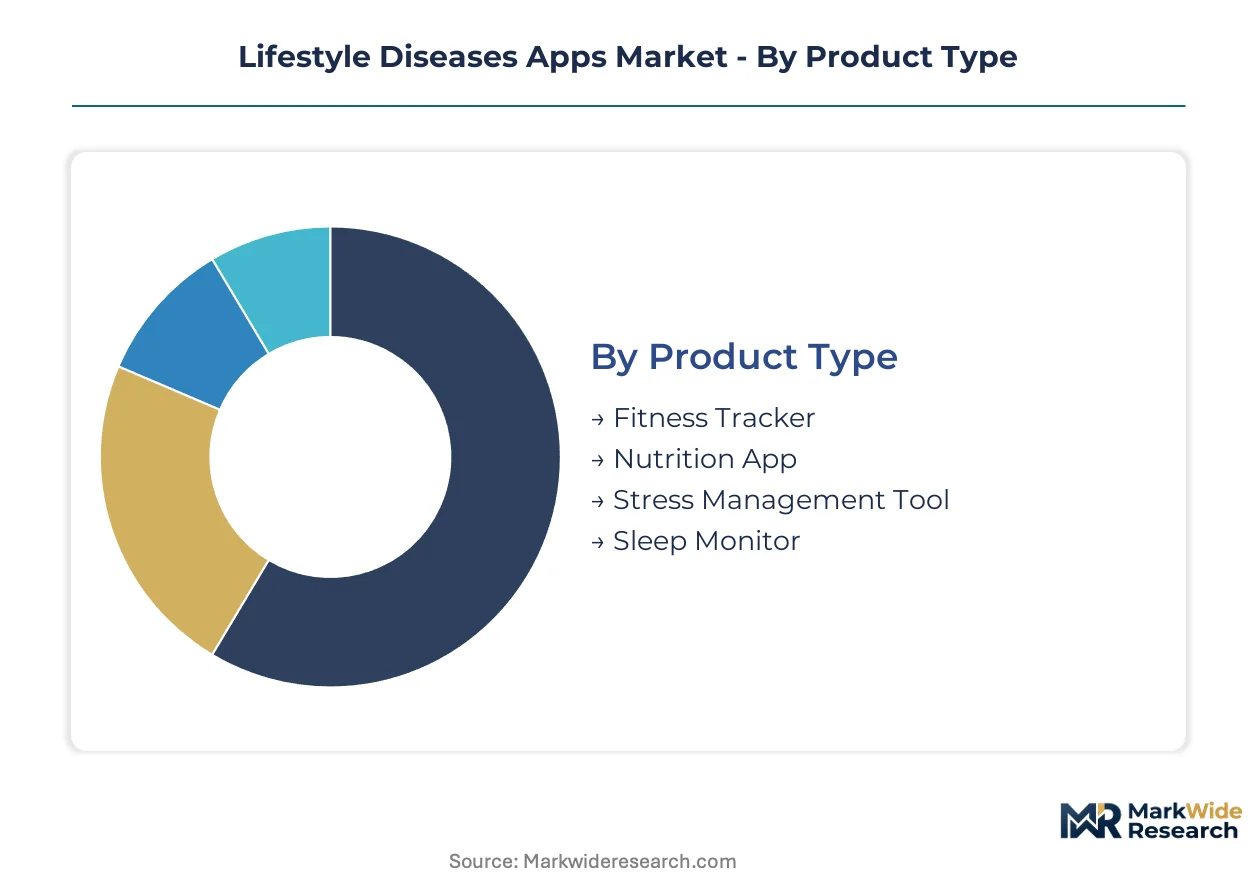
Lifestyle diseases apps serve heterogeneous user needs spanning preventive wellness, clinical chronic disease management, and employer-sponsored population health. Segmentation reveals divergent monetization models, regulatory pathways, and technology architectures across product categories and customer types.
Product Type:
Fitness trackers dominate consumer-facing revenue pools through hardware-software bundles, while AI-based platforms capture premium pricing in clinical workflows. Nutrition apps command the highest subscription renewal rates among prediabetic and bariatric populations.
- Fitness Tracker:Wearable devices with embedded accelerometers and photoplethysmography sensors stream continuous biometric data to companion smartphone applications. Demand concentrates among self-insured employers in the United States seeking medical loss ratio reductions through population health mandates. Insurance-linked incentive programs drive enterprise procurement volume.
- Nutrition App:Platforms delivering personalized meal planning, macro tracking, and behavioral coaching through localized food databases. HealthifyMe's multilingual interfaces for South Asian markets demonstrate addressable expansion beyond Western dietary frameworks. Subscription stickiness exceeds other categories due to ongoing coaching relationships.
- Stress Management Tool:Applications deploying guided meditation, biofeedback, and cognitive behavioral therapy protocols for anxiety and hypertension comorbidities.
- Sleep Monitor:Smartphone and wearable-based sleep stage detection with circadian rhythm optimization recommendations for obesity and metabolic syndrome patients.
Today's leader: Fitness Tracker. Tomorrow's challenger: Nutrition App.
Technology:
Cloud architectures currently support the majority of deployed instances, though edge AI migration is compressing latency and infrastructure costs for real-time glucose prediction. Wearable integration demands Bluetooth Low Energy optimization and FDA Software as a Medical Device validation for connected glucometers.
- AI-Based:Machine learning models process continuous data streams to generate algorithmic risk scores and personalized intervention protocols. Predictive analytics penetration into clinical workflows drives the steepest expansion trajectory across technology categories. Healthcare systems now require algorithmic transparency and prospective evidence before reimbursement authorization.
- Cloud-Enabled:Centralized server architectures hosting user data, analytics engines, and care team dashboards. GDPR-mandated EU data residency forces parallel infrastructure deployments, duplicating fixed costs for multi-territory operators.
- Mobile Application:Native smartphone software without continuous peripheral connectivity, serving price-sensitive individual consumers.
- Wearable Integration:Direct sensor data pipelines from wrist-worn devices enabling real-time biometric trending and automated care team alerts.
AI-Based platforms are gaining share fastest among clinical-grade deployments, while Cloud-Enabled architectures face margin pressure from data localization compliance.
End User:
Individual consumers generate the highest download volumes through app store distribution, though healthcare providers and corporates drive recurring revenue through outcome-based contracts. Wellness coaches represent an emerging channel for platform-assisted service delivery.
- Individuals:Direct-to-consumer purchasers managing personal fitness, nutrition, and chronic condition risk through self-directed engagement. United States employer wellness programs are absorbing individual procurement through subsidized benefit structures.
- Healthcare Providers:Hospital systems and physician practices integrating FDA-cleared apps into remote patient monitoring workflows. CMS reimbursement codes for chronic care management are accelerating clinical adoption.
- Corporates:Self-insured employers contracting directly with chronic disease management platforms to reduce medical expenditures.
- Wellness Coaches:Independent practitioners leveraging white-label platform infrastructure to scale client coaching relationships.
Healthcare Providers currently anchor premium pricing; Corporates represent the volume growth vector through per-employee-per-month contracting.
Distribution Channel:
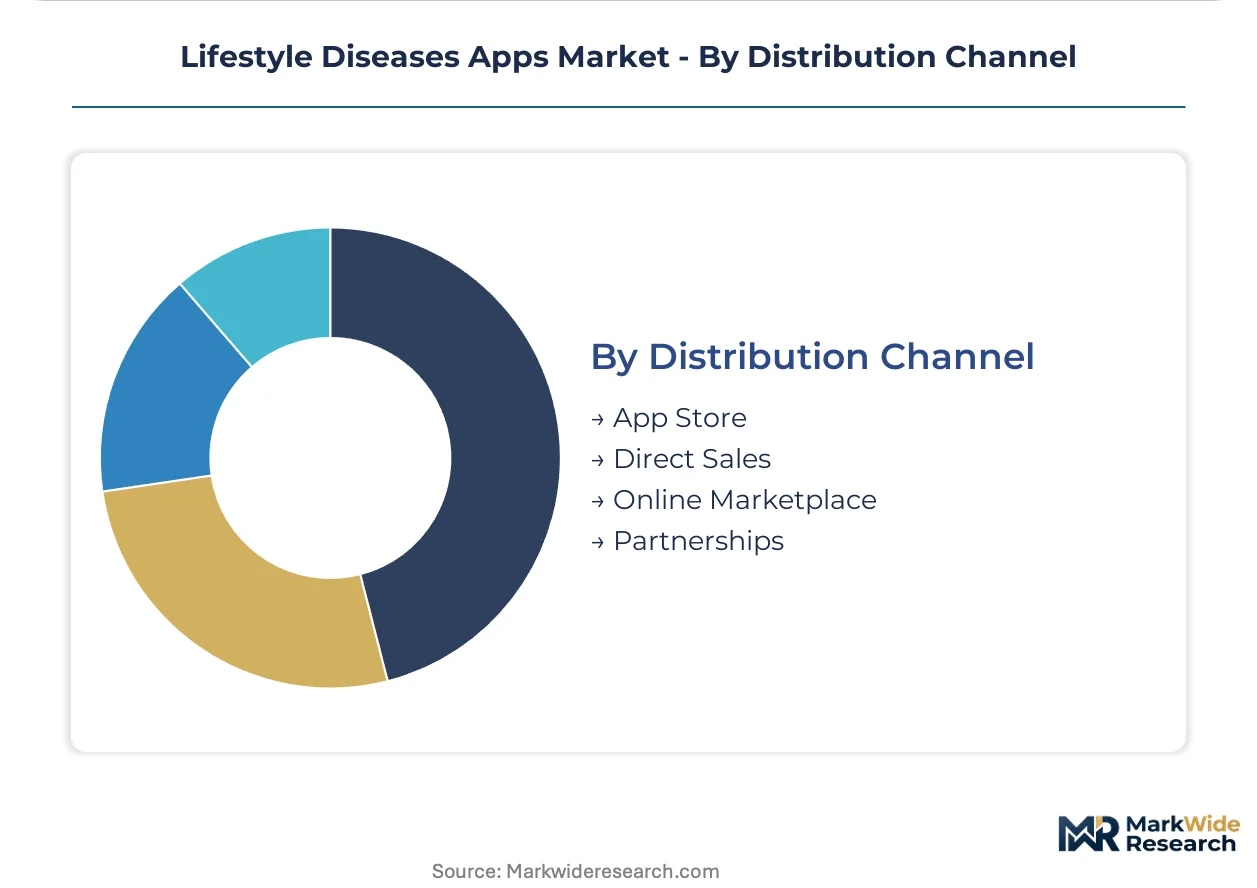
App stores dominate consumer acquisition with frictionless download economics, while direct sales and partnerships capture enterprise procurement with longer sales cycles and higher contract values. Online marketplaces aggregate niche wellness applications with limited clinical validation.
- App Store:Apple App Store and Google Play distribution with 15-30% platform fee structures. Consumer discovery algorithms favor high-retention fitness and nutrition applications with strong user review profiles.
- Direct Sales:Enterprise business development teams targeting human resources and benefits administrators at large self-insured employers. HbA1c reduction guarantees are becoming standard contract terms.
- Online Marketplace:Aggregator platforms bundling multiple wellness applications for small and medium enterprise procurement.
- Partnerships:Strategic alliances with health plans, pharmacy benefit managers, and medical device manufacturers for embedded distribution.
Direct Sales commands the highest contract values; Partnerships are expanding fastest through payer and device manufacturer integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where lifestyle diseases app developers concentrate engineering resources, with cost-of-compliance gaps pushing clinical validation work toward jurisdictions offering streamlined Software as a Medical Device pathways while commercial deployment targets high-reimbursement markets.
United States
Employer wellness mandates and CMS remote patient monitoring reimbursement codes are accelerating clinical-grade app procurement. FDA's Software as a Medical Device framework elevates validation costs but unlocks payer coverage. Silicon Valley engineering clusters dominate behavioral psychology platform development.
Germany
DiGAs (Digital Health Applications) fast-track reimbursement is pulling FDA-cleared platforms into statutory health insurance coverage. BfArM's evidence requirements demand prospective clinical trials for algorithmic interventions. Berlin healthtech incubators specialize in continuous glucose monitoring integration.
India
National health identifier system expansion and 4G penetration are enabling localized diabetes prevention platforms. CDSCO's Software as a Medical Device guidelines are formalizing, though less stringent than FDA pathways. Bangalore engineering centers dominate multilingual nutrition database development.
United Kingdom
NHS Digital's app assessment framework is filtering clinical-grade platforms into primary care workflows. MHRA's post-Brexit Software as a Medical Device regulations maintain EU MDR alignment. London fintech-healthtech convergence is producing employer wellness procurement platforms.
Japan
PMDA's SaMD classification system is creating a structured pathway for glucose prediction algorithms. METI's healthcare productivity initiatives are subsidizing chronic disease management platform adoption. Tokyo wearable device manufacturers anchor photoplethysmography sensor supply chains.
Lifestyle Diseases Apps Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue FDA-cleared clinical workflows and employer direct contracting. The market structure concentrates around three archetypes: behavioral psychology platforms, wearable-integrated data pipelines, and localized nutrition coaching services. Consolidation pressure is mounting as reimbursement codes favor validated clinical evidence over consumer download metrics. Dominant competitive moves include strategic partnerships with continuous glucose monitor manufacturers and outcome-based contracting with self-insured employers.
Among behavioral psychology specialists, Noom Inc. exemplifies the engagement-retention archetype through habit-formation frameworks. Fitbit Inc. anchors the wearable-integrated tier, leveraging hardware-software bundling for biometric data pipelines. HealthifyMe occupies a position within the localization-specialist segment, demonstrating addressable market expansion through multilingual coaching infrastructure. These three entities collectively represent the strategic positioning spectrum: psychology-driven retention, sensor-hardware convergence, and geographic adaptation.
| Leading Market Players |
|---|
| MyFitnessPal |
| Noom Inc. |
| Fitbit Inc. |
| Azumio Inc. |
| Lifesum |
| Sleep Cycle |
| Headspace |
| HealthifyMe |
| Nudge Coach |
| Others |
Cost & Logistics Intelligence
HIPAA privacy mandates and FDA Software as a Medical Device validation requirements gate qualified supply for clinical-grade platforms, restricting premium-tier pricing access to developers with capital reserves for prospective trials and compliant cloud infrastructure. This regulatory filtering concentrates pricing power among validated incumbents while compressing margins for consumer-facing entrants lacking reimbursement pathways.
Pricing Analysis
Direct-to-OEM discounts dominate enterprise procurement as self-insured employers negotiate per-employee-per-month contracts tied to biometric outcome verification. Pricing stratifies across FDA-cleared clinical tiers, outcome-guaranteed employer tiers, and direct-to-consumer subscription tiers, with brand premium and certification level as primary differentiation drivers. Cost compression in the consumer tier intensifies because app store discovery algorithms favor high-retention incumbents, forcing price erosion among undifferentiated nutrition and fitness applications. Individual consumers exhibit highest price sensitivity, while healthcare providers demonstrate lowest sensitivity due to CMS reimbursement coverage.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and India anchor hub-and-spoke patterns for cloud infrastructure and wearable device fulfillment. Engineering talent concentrates in Silicon Valley, Berlin healthtech incubators, and Bangalore development centers, while photoplethysmography sensor supply chains center on Tokyo wearable manufacturers. The ecosystem draws from Bluetooth Low Energy chipsets, continuous glucose monitoring hardware, and smartphone neural processing units as critical inputs. Single-source vulnerability in FDA-cleared glucose prediction algorithms creates supply chain risk, as prospective clinical evidence requirements filter qualified developers. Distribution runs through direct sales teams for enterprise contracts, app stores for consumer acquisition, and strategic partnerships with pharmacy benefit managers for embedded clinical deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in lifestyle diseases apps hinges on edge AI migration compressing cloud infrastructure costs while clinical validation unlocks premium reimbursement tiers previously inaccessible to consumer-grade platforms.
For Market Incumbents: Anticipate employer procurement unbundling by investing in outcome measurement infrastructure that supports HbA1c reduction guarantees in contract renewals. Consolidate position through backward integration into continuous glucose monitoring hardware partnerships, securing sensor data pipelines that emerging entrants cannot replicate. FDA validation costs represent the primary barrier; defend by accelerating Software as a Medical Device submissions ahead of tightening evidentiary standards. For New Entrants and Emerging Players: Enter via India's digital health stack, leveraging the national health identifier system and expanding 4G penetration to deploy localized diabetes prevention platforms before clinical-grade competitors establish presence. Target Sub-Saharan Africa's underserved hypertension populations with low-bandwidth, offline-first monitoring applications where incumbent infrastructure requirements create white space. Pursue wellness coach channel partnerships as the go-to-market angle, white-labeling platform infrastructure to independent practitioners scaling client relationships. For Investors and Strategic Acquirers: Roll-up economics work for behavioral psychology platforms because employer wellness mandates are consolidating procurement around engagement-retention capabilities that specialized developers have already validated. The five-to-ten year viability window favors acquisitions of FDA-cleared clinical workflows over consumer download metrics, as reimbursement codes progressively filter unvalidated applications. Watch CMS remote patient monitoring code expansion as the inflection signal determining whether clinical-grade apps transition from discretionary purchases to covered benefits.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Unlocks CMS reimbursement pathways for chronic care management platforms in US hospital systems. |
| Continuous Glucose Monitoring Integration | Establishes real-time data pipelines with Bluetooth-enabled devices for algorithmic insulin dosing. |
| Employer Direct Contracting | Bypasses payer intermediaries through per-employee-per-month pricing tied to biometric outcomes. |
| Edge AI Model Compression | Enables on-device glucose prediction without cloud connectivity, hardening GDPR compliance. |
| Multilingual Coaching Localization | Expands addressable markets through region-specific nutrition databases beyond Western dietary frameworks. |
Research Approach
Direct dialogue with digital health product managers, regulatory affairs specialists at FDA-cleared developers, hospital biomedical engineers, and employer benefits administrators grounded the qualitative foundation. Secondary validation drew from FDA 510(k) filings, CMS reimbursement code databases, DiGA approvals at BfArM, and App Store retention metrics. Bottom-up and top-down triangulation cross-checked platform revenue estimates against employer wellness program procurement disclosures and payer coverage policy documents.
Installed base projections and revenue forecasts emerged from modeling deployment models, end-user segments, and regional regulatory clusters across the analysis window. Segmentation dimensions included product type, technology architecture, and distribution channel, with AI-based platforms and wearable integration tracked separately. CAGRs were derived from fitting logistic adoption curves to historical clinical app penetration rates, incorporating continuous glucose monitoring device shipment data and employer wellness program contract values as industry-specific inputs.
Inputs from regulatory filings and enterprise procurement disclosures were available through the study window; gaps in private employer contract terms and unreported consumer subscription churn introduce uncertainty bands around revenue projections. Forecasts reflect documented assumptions regarding CMS reimbursement expansion and FDA validation timeline compression. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Global Plastic Surgery Software Market
Digital Health Solutions
Mhealth Apps Market
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
North America Mobile Health (Mhealth) Market
Digital Health Solutions
Digital Therapeutics Market
Digital Health Solutions
Global Metaverse in Healthcare Market
Digital Health Solutions
Vaccine Management Software Market
Digital Health Solutions
VR in Healthcare Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Digital Health Market